
 Global Secure Mobile Communications Software Market | 2026-2036
Global Secure Mobile Communications Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Secure Mobile Communications Software Market Foresight
Premium secure mobile communications software is decoupling from commodity endpoint protection as buyers demand sovereign-grade encryption with hardware-rooted trust anchors. Cisco Systems, Inc. leverages its Talos threat intelligence backbone to sustain enterprise-grade secure mobility deployments across federal accounts. BlackBerry Limited anchors its position through specialized kernel-hardened messaging platforms that dominate defense and intelligence channels. Thales Group competes on certified cryptographic modules that satisfy NATO and EU restricted-classification requirements.
Secure mobile communications software encompasses encrypted voice, data, and messaging applications engineered to operate on commercial off-the-shelf devices while maintaining classified-grade confidentiality through AES-256 or quantum-resistant algorithms and hardware security module integration. Its primary purpose is enabling authenticated, tamper-evident information exchange for personnel operating beyond traditional enterprise perimeter controls. Cloud-based deployment leads in new contract value as agencies prioritize elastic scale over fixed infrastructure, while end-to-end encryption captures the deepest margin pools due to certification complexity and sovereign data-residency requirements. Secure messaging for remote workforce use cases exhibits the steepest growth trajectory as hybrid work policies persist in financial and technology sectors.
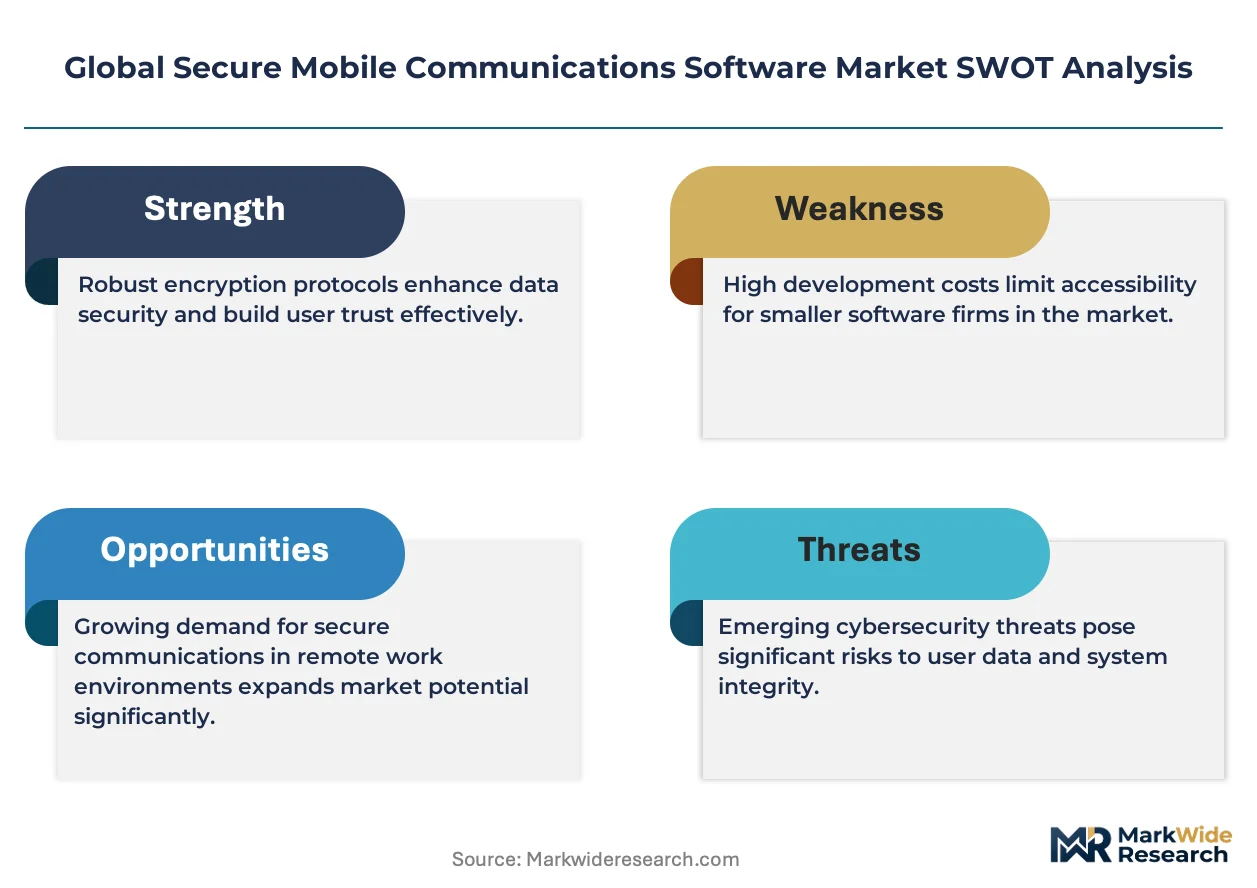
The EU AI Act and NIS2 Directive, alongside FDA cybersecurity guidance for connected medical devices and FCC Part 22/24 reliability mandates, collectively tighten product standards and procurement eligibility across jurisdictions. ETSI and ISO/IEC 27001 certification now functions as a de facto market-access filter for vendors serving European public-sector buyers. Stakeholders must monitor quantum-safe cryptography standardization timelines and corresponding procurement clause revisions to preserve competitive positioning as algorithm requirements shift.
Market Dynamics
Zero-trust architecture mandates from the EU NIS2 Directive and comparable frameworks are compelling enterprises to replace legacy VPN-dependent systems, creating a structural inflection point where sovereign-grade encryption becomes a procurement prerequisite rather than a premium option.
Growth Catalysts
- NATO defense procurement:Member states are accelerating encrypted mobile platform acquisitions for classified field communications, with Germany and Australia issuing multi-year framework agreements.
- EU NIS2 Directive:Critical infrastructure operators must deploy end-to-end encrypted channels by enforcement deadlines, forcing immediate enterprise software refresh cycles.
- Hardware-rooted trust anchors:Integration of secure enclaves and hardware security modules into commercial devices is lowering deployment barriers for agencies previously requiring specialized equipment.
Market Restraints
- Certification timeline compression:ETSI and ISO/IEC 27001 validation cycles extend 18-24 months, delaying product launches and freezing development roadmaps.
- Cryptographic talent scarcity:Quantum-safe algorithm expertise concentrates in national laboratories and select academic clusters, constraining vendor R&D bandwidth.
- Input cost volatility:Specialized hardware security module supply chains face allocation constraints from semiconductor foundry prioritization of consumer electronics.
Strategic Opportunities
- Connected medical devices:FDA cybersecurity guidance for hospital mobile workstations creates demand for HIPAA-compliant encrypted messaging platforms with audit trails.
- Financial sector hybrid work:Banks in Singapore and Switzerland are mandating sovereign-hosted secure communications for remote traders and relationship managers.
- Post-quantum migration services:Vendors offering algorithm transition consulting and crypto-agility tooling can capture multi-year implementation contracts as standards finalize.
Industry Challenges
- Legacy system integration:Enterprises operating decades-old SCADA and mainframe infrastructure face protocol incompatibility with modern encrypted mobile endpoints, requiring costly middleware development.
- Cross-border data residency:Conflicting sovereignty requirements between EU GDPR, China's data localization rules, and US CLOUD Act jurisdictions force vendors to maintain fragmented infrastructure architectures.
- Skill gap in quantum cryptography:The shortage of engineers trained in lattice-based and hash-based signature schemes delays product certification against NIST post-quantum standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Secure Mobile Communications Software Market |
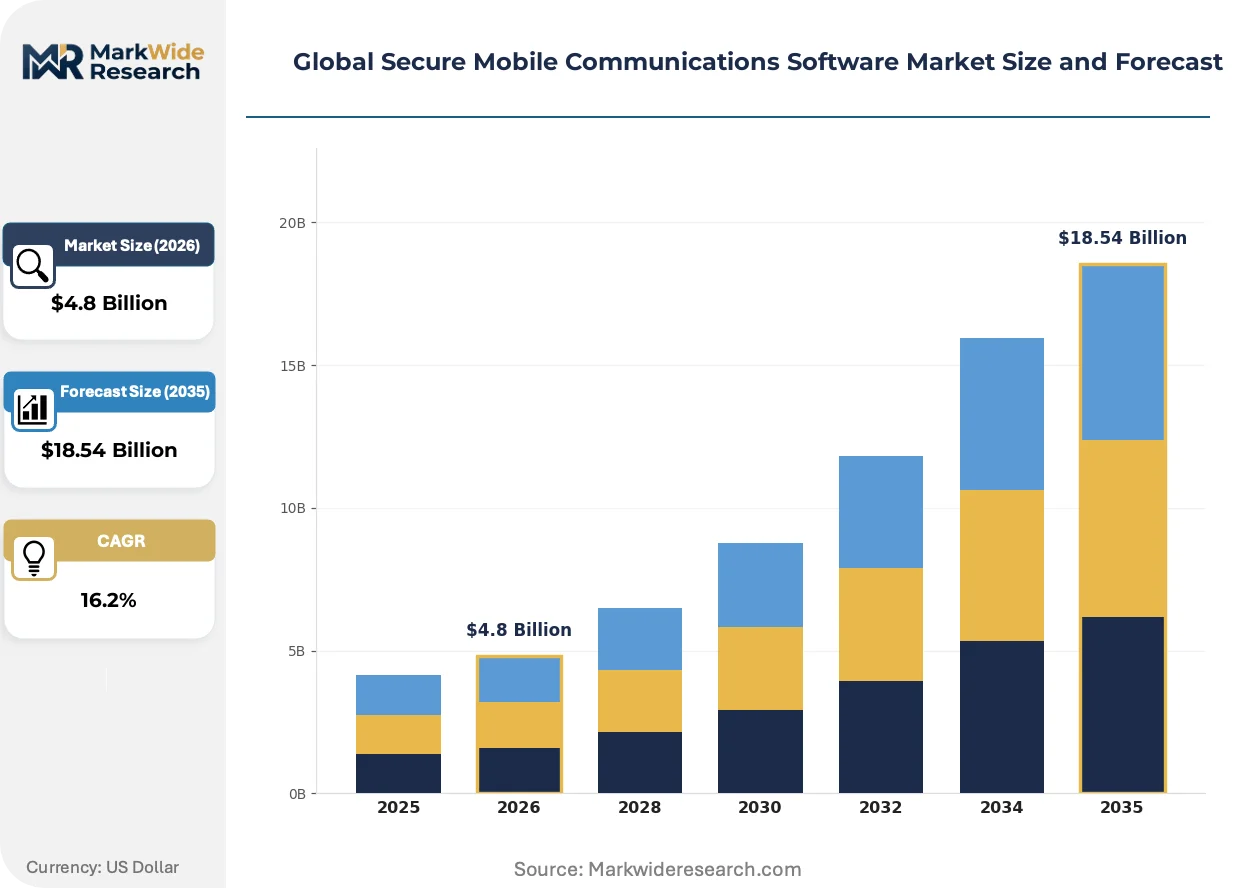
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: End-to-End Encryption, Multi-Factor Authentication, Secure Messaging, Access Control, Network Security Use Case: Remote Workforce, Government Communications, Financial Transactions, Military Operations, Emergency Services Customer Type: Large Enterprises, Small & Medium Businesses, Public Safety Agencies, Telecommunications Providers |
| Companies Covered | Cisco Systems, Inc., Microsoft Corporation, BlackBerry Limited, Symantec Corporation, McAfee Corp., IBM Corporation, Thales Group, Fortinet, Inc., MobileIron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Secure Mobile Communications Software Market Shifts & Advancements
Artificial intelligence is penetrating secure communications infrastructure, automating threat detection and response workflows while regulatory frameworks harden compliance requirements across multiple jurisdictions.
Machine learning-based anomaly detection is automating real-time identification of compromised endpoints and man-in-the-middle attempts within encrypted traffic streams. Defense agencies in the United States and Australia are deploying these systems at network edge nodes, reducing mean-time-to-detection from hours to seconds. This compression of incident response cycles is automating security operations center staffing models and reshaping vendor service offerings toward autonomous platform management.
The EU AI Act imposes conformity assessment obligations on AI-enabled security software, requiring documented risk management systems and human oversight protocols for automated decision-making components. Vendors must now maintain technical documentation and quality management systems previously associated with medical device manufacturers. European public-sector buyers are inserting AI Act compliance clauses into secure communications tenders, filtering out providers lacking certified governance frameworks.
Subscription-based consumption models are displacing perpetual license arrangements as agencies prioritize operational expenditure flexibility over capital commitments. Cloud-native secure communications platforms with usage-based metering are capturing preference among mid-sized financial services firms in Germany and the United Kingdom. This shift is compressing vendor revenue recognition timelines while accelerating customer acquisition through lower initial deployment thresholds.
Global Secure Mobile Communications Software Market Segmentation
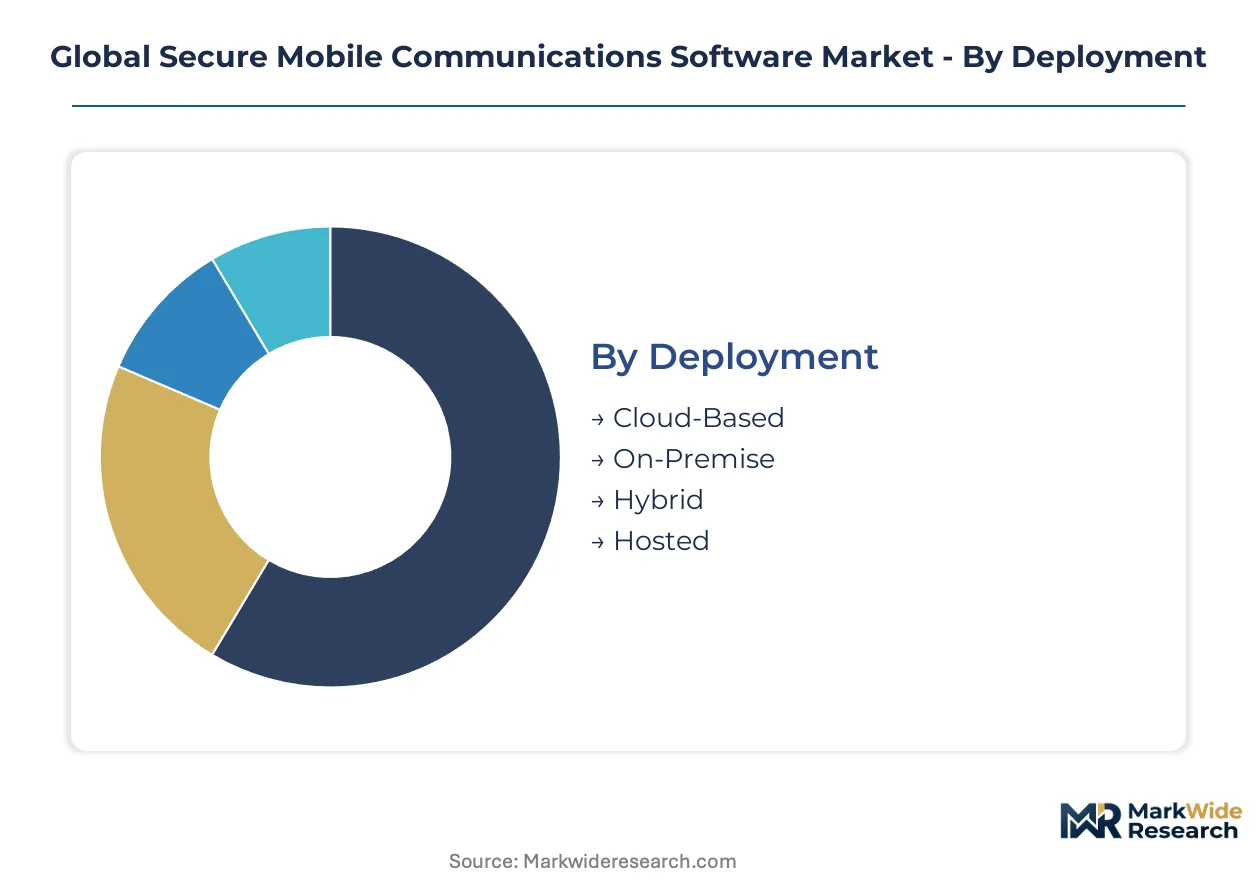
Segmentation in secure mobile communications software reveals divergent procurement logics across deployment architectures and customer risk profiles. Defense buyers prioritize sovereign data residency while financial institutions optimize for elastic scale, forcing vendors to maintain parallel certification tracks.
Deployment:
Cloud-based deployments command premium contract values through consumption-based metering, while on-premise installations retain footholds in classified environments with air-gapped requirements.
- Cloud-Based:Elastic infrastructure enables rapid provisioning for financial services firms in Singapore and Switzerland facing trader mobility mandates. AWS GovCloud and Azure Government enclaves satisfy FedRAMP and ITAR requirements for U.S. federal accounts. Sovereign-hosted instances in Germany and Australia address data residency constraints under GDPR and the Privacy Act.
- On-Premise:Dedicated hardware stacks serve NATO classified networks with physical tamper-evidence and electromagnetic shielding. German defense procurement specifications require on-premise cryptographic key generation within national borders. Fixed infrastructure locks capital into 5-7 year depreciation cycles, constraining agility.
- Hybrid:Split-traffic architectures route sensitive metadata on-premise while pushing encrypted payloads to cloud edge nodes. Australian critical infrastructure operators deploy hybrid models under the Security of Critical Infrastructure Act.
- Hosted:Managed service providers operate dedicated single-tenant instances with vendor-assumed compliance liability. Swiss banks favor hosted arrangements for relationship manager communications under FINMA outsourcing guidelines.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Type:
End-to-end encryption captures the deepest margin pools through certification complexity, while access control solutions face commoditization from identity platform bundling.
- End-to-End Encryption:AES-256 and emerging quantum-resistant algorithms protect voice, data, and messaging with keys generated in hardware security modules. ETSI and ISO/IEC 27001 certification cycles extend 18-24 months, creating vendor moats. EU NIS2 Directive enforcement deadlines accelerate enterprise refresh cycles.
- Secure Messaging:Kernel-hardened platforms with message expiration and screenshot prevention dominate defense and intelligence channels. Remote workforce policies in technology and financial sectors drive steepest expansion trajectory for this segment.
- Multi-Factor Authentication:Biometric and hardware token verification layers reduce credential compromise risk for mobile endpoints. FIDO2 standards adoption simplifies integration across device ecosystems.
- Access Control:Zero-trust policy engines dynamically authenticate users and devices beyond traditional perimeter models. Microsoft and Okta bundle comparable capabilities, pressuring standalone pricing.
- Network Security:Encrypted tunneling and micro-segmentation protect traffic traversing untrusted cellular and Wi-Fi infrastructure. 5G network slicing creates new attack surfaces requiring mobile-specific countermeasures.
End-to-End Encryption currently anchors vendor profitability. Secure Messaging is gaining share fastest as hybrid work persists.
Use Case:
Military operations demand specialized hardware-rooted trust anchors, while remote workforce applications scale across commodity devices with software-only protection.
- Military Operations:Battlefield communications require NSA Suite B or NATO RESTRICTED certification with anti-jam and low-probability-of-intercept waveforms. Specialized tactical radios integrate with commercial smartphones through hardened docking modules.
- Government Communications:Classified mobile platforms serve cabinet-level officials and diplomatic personnel with sovereign-controlled key escrow. Germany's BSI and Australia's ASD issue procurement frameworks with mandatory domestic hosting.
- Remote Workforce:Financial traders and technology executives require seamless encrypted collaboration across personal and corporate devices. HIPAA-compliant variants address hospital mobile workstations under FDA cybersecurity guidance.
- Financial Transactions:Real-time payment authorization and trading execution demand sub-100-millisecond latency with cryptographic non-repudiation. Singapore's MAS mandates encrypted channels for relationship manager communications.
- Emergency Services:First responders require priority network access with encrypted group communications during crisis events. FCC Part 22/24 reliability mandates govern U.S. public safety broadband deployments.
Remote Workforce dominates commercial procurement volume. Military Operations retains the highest contract values per seat.
Customer Type:
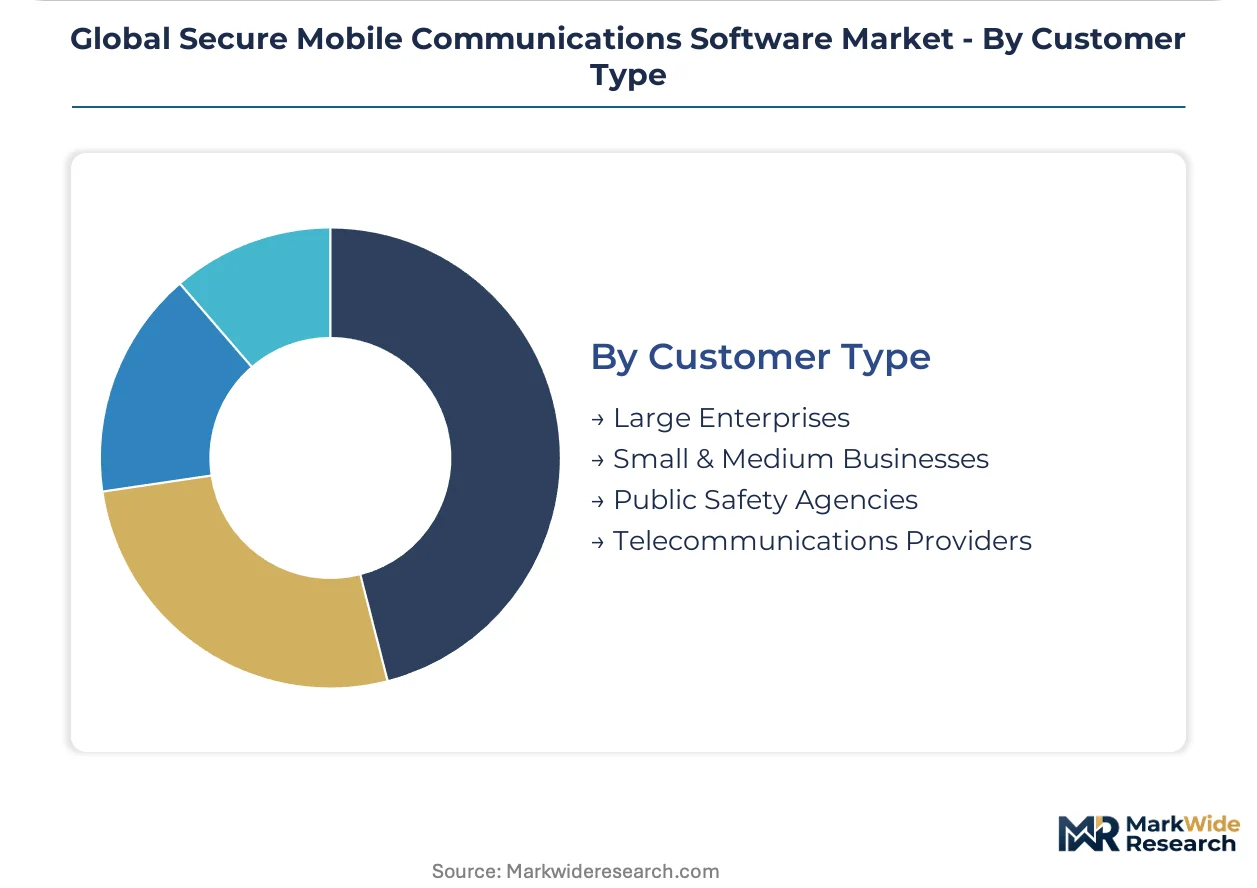
Large enterprises drive standardization through framework agreements, while public safety agencies fragment demand across municipal procurement jurisdictions.
- Large Enterprises:Global banks and technology firms consolidate secure communications under chief information security officer mandates with multi-year enterprise licensing. Centralized procurement extracts volume discounts while standardizing compliance posture.
- Public Safety Agencies:Police, fire, and emergency medical services require mission-critical reliability with offline functionality in degraded network conditions. U.S. FirstNet and European equivalents fund dedicated encrypted broadband networks.
- Telecommunications Providers:Mobile network operators embed secure communications as value-added services for enterprise subscribers, leveraging SIM-based authentication and network-layer encryption.
- Small & Medium Businesses:Cost-constrained organizations adopt consumer-grade encrypted messaging with limited administrative control, creating shadow IT risks and compliance gaps.
Large Enterprises anchor current revenue concentration. Public Safety Agencies represent the most durable long-term commitment profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryptographic engineering talent clusters in national laboratories and defense contractor facilities across Germany, the United States, Australia, Singapore, and Switzerland. These concentrations anchor sovereign-grade secure communications development.
United States
Defense agencies and intelligence services drive classified mobile platform procurement through NSA Suite B certification requirements. FCC Part 22/24 reliability mandates govern public safety broadband networks for first responders. The Washington-Baltimore corridor hosts concentrated federal contracting activity for encrypted battlefield communications.
Germany
BSI procurement frameworks mandate domestic cryptographic key generation for critical infrastructure operators under EU NIS2 Directive deadlines. Industrial conglomerates in Munich and Stuttgart deploy hardware-rooted trust anchors for manufacturing supply chain communications. Frankfurt financial institutions require sovereign-hosted encryption for trader mobility.
Australia
ASD issues multi-year framework agreements for encrypted mobile platforms serving defense and critical infrastructure sectors. The Security of Critical Infrastructure Act compels hybrid deployment architectures for energy and telecommunications operators. Sydney and Melbourne anchor enterprise adoption for remote workforce secure messaging.
Singapore
MAS mandates encrypted channels for relationship manager communications in private banking and wealth management. The city-state's data center concentration supports cloud-native secure communications for Southeast Asian financial institutions. Technology firms in one-north and Changi Business Park deploy zero-trust mobile access for distributed engineering teams.
Switzerland
FINMA outsourcing guidelines drive hosted secure communications arrangements for private banking relationship managers. The country's neutrality status attracts cryptographic R&D for diplomatic and international organization communications. Zurich and Geneva house concentrated demand for HIPAA-compliant encrypted messaging in pharmaceutical headquarters.
Global Secure Mobile Communications Software Market Competitive Landscape
Capital-heavy integrated platform vendors compete with asset-light specialized encryption developers across deployment and certification tracks. The vendor base stratifies between consolidated enterprise technology conglomerates and focused cryptographic specialists. Three archetypes dominate: federal-certified platform providers, kernel-hardened messaging specialists, and cloud-native zero-trust enablers. Competitive positioning depends on ETSI and ISO/IEC 27001 certification velocity alongside strategic partnerships with semiconductor manufacturers for hardware security module integration.
Within the federal-certified tier, Cisco Systems, Inc. and Thales Group occupy positions anchored by threat intelligence infrastructure and NATO cryptographic module certification respectively. BlackBerry Limited exemplifies the kernel-hardened messaging specialist archetype through defense and intelligence channel concentration. These three entities represent divergent strategic postures: platform breadth versus cryptographic depth versus specialized secure messaging focus.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Microsoft Corporation |
| BlackBerry Limited |
| Symantec Corporation |
| McAfee Corp. |
| IBM Corporation |
| Thales Group |
| Fortinet, Inc. |
| MobileIron |
| Others |
Supply & Pricing Matrix
EU NIS2 Directive enforcement deadlines for critical infrastructure operators gate both qualified supply and premium-tier pricing access, compressing vendor certification timelines while elevating sovereign-grade encryption to a non-negotiable procurement threshold. Hardware security module integration costs and ETSI validation cycles concentrate pricing power among established platform providers, forcing mid-tier competitors toward commoditized secure messaging segments.
Pricing Analysis
Subscription-based SaaS tiers dominate enterprise procurement, separating FedRAMP-authorized cloud deployments from on-premise classified installations. Certification grade—specifically ETSI and ISO/IEC 27001 validation status—drives the steepest price differentiation alongside hardware-rooted trust anchor integration. Cost compression in standard-tier secure messaging intensifies as Microsoft and Okta bundle comparable access control capabilities, eroding standalone vendor margins. Large enterprises with centralized CISO mandates exhibit lowest price sensitivity, while small and medium businesses default to consumer-grade alternatives with limited administrative oversight.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Singapore anchor hardware security module fulfillment for defense and financial sector deployments. Semiconductor fabrication for specialized cryptographic processors draws from Taiwan, South Korea, and domestic foundries with ITAR compliance. Single-source vulnerability concentrates in NATO-certified cryptographic module suppliers, constraining procurement flexibility for classified network operators. Distribution runs through defense contractor integration channels and hyperscaler marketplace enclaves, with sovereign-hosted instances requiring in-country hardware provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where NATO defense procurement and EU NIS2 mandates shift demand toward certified sovereign-grade platforms, marginalizing unvalidated competitors.
For Market Incumbents: Cement platform stickiness through exclusive hardware security module partnerships with semiconductor manufacturers, locking out emerging entrants from supply-constrained cryptographic components. Deepen certification velocity investment to compress ETSI validation cycles below 18-month thresholds, defending margin position against cloud-native challengers bundling zero-trust capabilities. For New Entrants and Emerging Players: Launch via managed service provider channels targeting HIPAA-compliant hospital mobile workstations, where FDA cybersecurity guidance creates immediate procurement windows absent incumbent saturation. White-space concentration in Swiss private banking and Singapore wealth management offers penetrable entry points through FINMA and MAS outsourcing frameworks. For Investors and Strategic Acquirers: Roll-up economics work for kernel-hardened messaging specialists because fragmented defense channel access and certification talent scarcity prevent organic scale. Target acquisition profiles center on vendors with existing NATO RESTRICTED or NSA Suite B validation, where regulatory moats sustain pricing power. The signal to watch is NIST post-quantum standard finalization, which will trigger algorithm migration service demand and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Certification | NIST standard adoption creates multi-year implementation contracts for crypto-agility tooling vendors. |
| Hardware Security Module Integration | Thales and Cisco leverage semiconductor partnerships to anchor sovereign-grade encryption supply chains. |
| Zero-Trust Platform Migration | EU NIS2 deadlines force enterprise VPN replacement cycles, favoring cloud-native secure communications providers. |
| Defense Channel Framework Agreements | Germany and Australia's multi-year procurement structures concentrate revenue among NATO-certified platform vendors. |
| AI-Enabled Threat Detection Deployment | Machine learning anomaly detection at network edge nodes automates SOC staffing for U.S. and Australian agencies. |
Research Methodology
Direct dialogue with CISOs at global financial institutions, defense procurement officers in NATO member states, platform engineers at hyperscaler enclaves, and integration specialists at managed service providers grounded qualitative assessment. Secondary validation drew from SEC filings of listed cybersecurity vendors, FedRAMP authorization databases, ETSI certification registries, and EU NIS2 implementation guidance documents. Bottom-up deployment modeling across cloud, on-premise, hybrid, and hosted architectures triangulated against top-down defense budget appropriation analysis.
Top-down macroeconomic drivers and bottom-up customer segmentation by deployment model, organization size, vertical risk profile, and regional regulatory cluster structured the analytical lens. CAGRs derived from elasticity-adjusted adoption curves across military operations, government communications, remote workforce, financial transactions, and emergency services use cases. Quantum-safe cryptography standardization timelines and corresponding procurement clause revisions served as scenario-weighting inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated NIST post-quantum migration mandates or semiconductor foundry allocation disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Secure Flash Drive Market
Security Software
Keystroke Dynamics Market
Security Software
Personal Data Recovery Software Market
Security Software
Consumer Endpoint Security Market
Security Software
Mobile Antivirus Software Market
Security Software
Global Data Classification Market
Security Software
Patch and Remediation Software Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Ultra-Secure Smartphone Market
Security Software
Internet Filter Software Market
Security Software
Global Data Loss Prevention Software Market
Security Software
Anomaly Detection Tools Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Global Network Security Software Market
Security Software
GDPR Software and Tools Market