
 Private Virtual Communications for Police Network Market | 2026-2036
Private Virtual Communications for Police Network Market Size, Share, and Industry Trends Forecast 2026-2036
Private Virtual Communications for Police Network Market Analytics
FCC FirstNet mandates is recalibrating the cost-of-entry calculus for vendors seeking public safety contracts, requiring end-to-end encryption and priority network access as baseline capabilities. Cisco Systems Inc dominates core routing infrastructure for police VPN backbones, leveraging decades of government security certifications. Microsoft Corporation anchors cloud-integrated command platforms, extending Teams and Azure Government into dispatch workflows. Checkpoint Software Inc specializes in threat prevention layers, differentiating through zero-trust architectures purpose-built for law enforcement data flows.
Private virtual communications for police networks encompass encrypted IP-based voice, video, and data transmission systems operating over dedicated or priority-access broadband infrastructure, typically requiring AES-256 encryption, sub-150ms latency thresholds, and 99.999% availability to support life-critical operations. Cloud-based deployment models are capturing the fastest expansion as agencies abandon capital-intensive on-premises radio towers for subscription-based secure connectivity. Secure Messaging and Incident Management technologies concentrate margin pools, reflecting the shift from voice-centric dispatch toward multimedia evidence documentation and real-time situational awareness. SWAT Teams and Dispatch Centers represent the highest-intensity user segments, driving demand for hardened devices and redundant failover pathways.
FCC FirstNet standards, NIST cybersecurity frameworks, and FBI CJIS security policies collectively shape product requirements, compliance costs, and vendor eligibility for US police network procurement. European equivalents including ENISA guidelines and national critical infrastructure protections impose parallel certification burdens on suppliers operating across jurisdictions. Stakeholders must monitor spectrum allocation decisions and interoperability mandates that will determine which platforms achieve de facto standard status in cross-agency emergency response scenarios.
Market Dynamics
The migration from legacy TETRA and P25 radio networks to LTE- and 5G-based private broadband is compressing procurement cycles and forcing vendors to recertify entire product portfolios under stricter encryption mandates.
Growth Catalysts
- FCC FirstNet mandates:The US public safety broadband authority requires priority network access and end-to-end encryption as baseline procurement criteria, eliminating vendors without hardened infrastructure.
- SWAT tactical requirements:Specialized units demand sub-150ms latency for real-time video streaming during hostage and active shooter scenarios, pulling investment toward edge-computing architectures.
- IP-based infrastructure replacement:Police agencies in Germany, the United Kingdom, and the United States are decommissioning analog radio towers in favor of encrypted packet-switched systems.
Market Restraints
- Semiconductor supply concentration:Specialized encryption chipsets for AES-256 hardware acceleration depend on foundry capacity concentrated in East Asia, creating vulnerability to export control disruptions.
- Interoperability certification costs:Multi-vendor testing against Project 25 and FirstNet standards adds 18-24 months to product launch timelines, freezing smaller suppliers out of federal contracts.
- Budget fragmentation across agencies:Municipal police departments in the United States operate under 18,000 separate procurement authorities, preventing volume consolidation and inflating per-unit costs.
Strategic Opportunities
- Cloud-native dispatch platforms:Subscription-based secure connectivity allows agencies to shift from capital-intensive radio tower ownership to operational expenditure models with automatic security patching.
- Multimedia evidence integration:Body-worn camera footage and drone video streams require encrypted storage and real-time transmission, opening adjacent revenue in evidence management software.
- EU critical infrastructure protections:ENISA guidelines and national security frameworks in Germany and France are mandating encrypted communications for counter-terrorism units, creating parallel certification pathways for vendors already hardened under US standards.
Industry Challenges
- Cybersecurity talent scarcity:Police IT departments lack personnel trained in zero-trust architecture deployment, forcing reliance on vendor-managed services and eroding operational autonomy.
- Legacy system integration:Analog radio networks must maintain parallel operations during IP transition periods, doubling maintenance overhead and complicating officer training programs.
- CJIS compliance timelines:FBI security policy audits for criminal justice information access create 12-18 month procurement delays that stall technology refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Virtual Communications for Police Network Market |
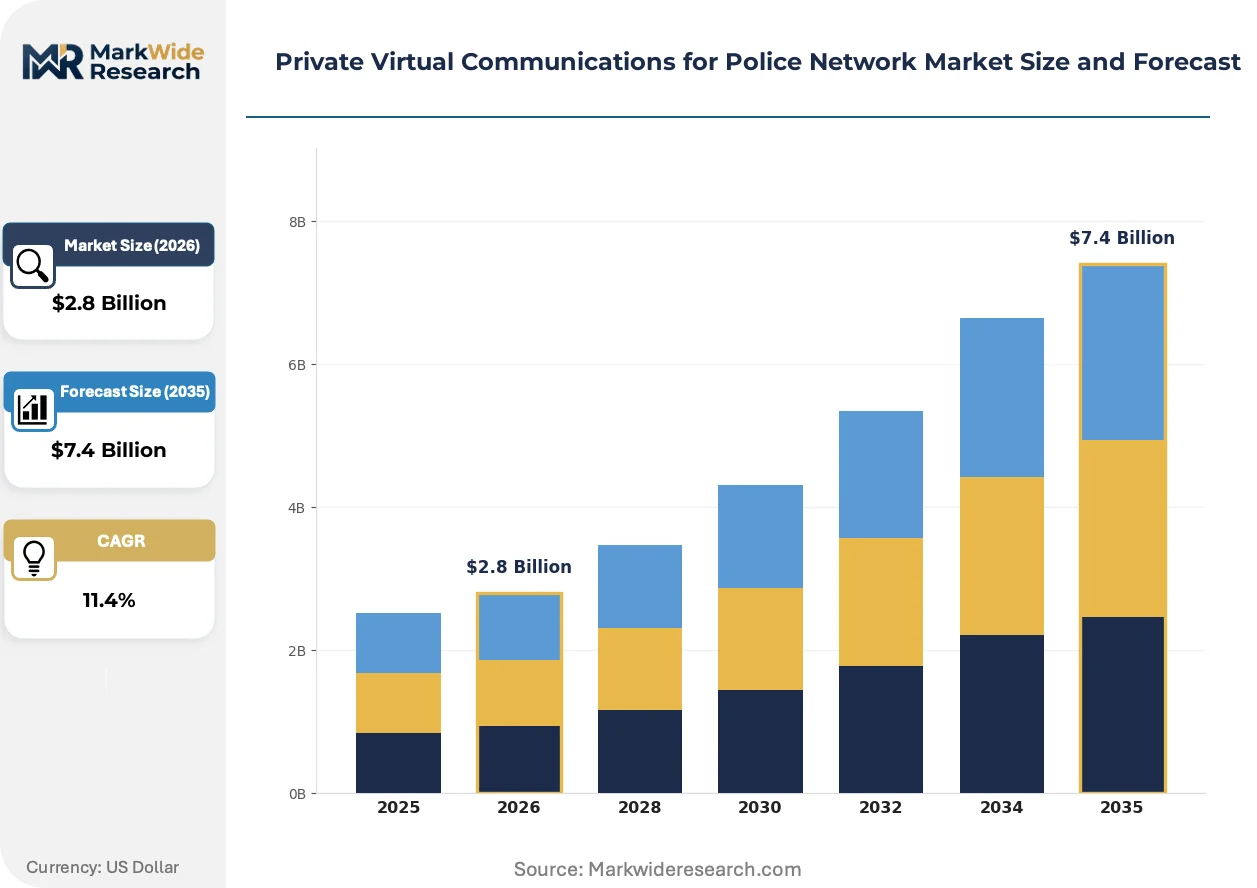
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Voice over IP, Secure Messaging, Video Conferencing, Incident Management Deployment Model: Cloud-based, On-premises, Hybrid, Dedicated Servers User Type: SWAT Teams, Patrol Officers, Dispatch Centers, Internal Affairs Communication Mode: Real-time, Asynchronous, Group Chat, One-to-One |
| Companies Covered | Cisco Systems Inc, Microsoft Corporation, Juniper Networks, IBM Corporation, Avast Software S R O, Checkpoint Software Inc, Netmotion Software Inc, Radio IP Software Inc, Axon Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Virtual Communications for Police Network Market Evolving Landscape
Encrypted edge computing and AI-assisted threat detection are converging to transform police communications from voice-centric dispatch into real-time situational awareness platforms. Vendors must now deliver integrated hardware-software stacks rather than discrete radio equipment.
Software-defined radio platforms with field-programmable gate arrays are rewriting how agencies deploy encryption. SWAT teams and mobile command units are adopting these reconfigurable systems to switch between frequency bands without hardware swaps. This flexibility is compressing equipment refresh cycles from ten-year radio replacement programs to three-year software licensing agreements.
EU AI Act risk classification rules are reshaping procurement criteria for automated threat detection systems. Law enforcement applications now face mandatory conformity assessments for biometric identification algorithms. German federal police and French Gendarmerie procurement offices are requiring algorithmic audit trails as standard contract terms, forcing vendors to reengineer black-box AI into interpretable decision systems.
Subscription-based secure connectivity is displacing capital-intensive infrastructure ownership. Police departments in Texas, California, and Florida are piloting network-as-a-service contracts that bundle encrypted broadband, device management, and CJIS-compliant cloud storage. This model shifts technical debt to vendors while accelerating access to 5G priority spectrum for smaller agencies without federal grant writing capacity.
Private Virtual Communications for Police Network Market Segmentation
Police agencies prioritize distinct capability bundles based on operational tempo, budget cycles, and CJIS compliance maturity. Segmentation reveals how procurement authority fragments across tactical units, IT departments, and municipal finance offices.
Technology:
Agency size and mission criticality determine encryption depth and latency tolerance across technology categories.
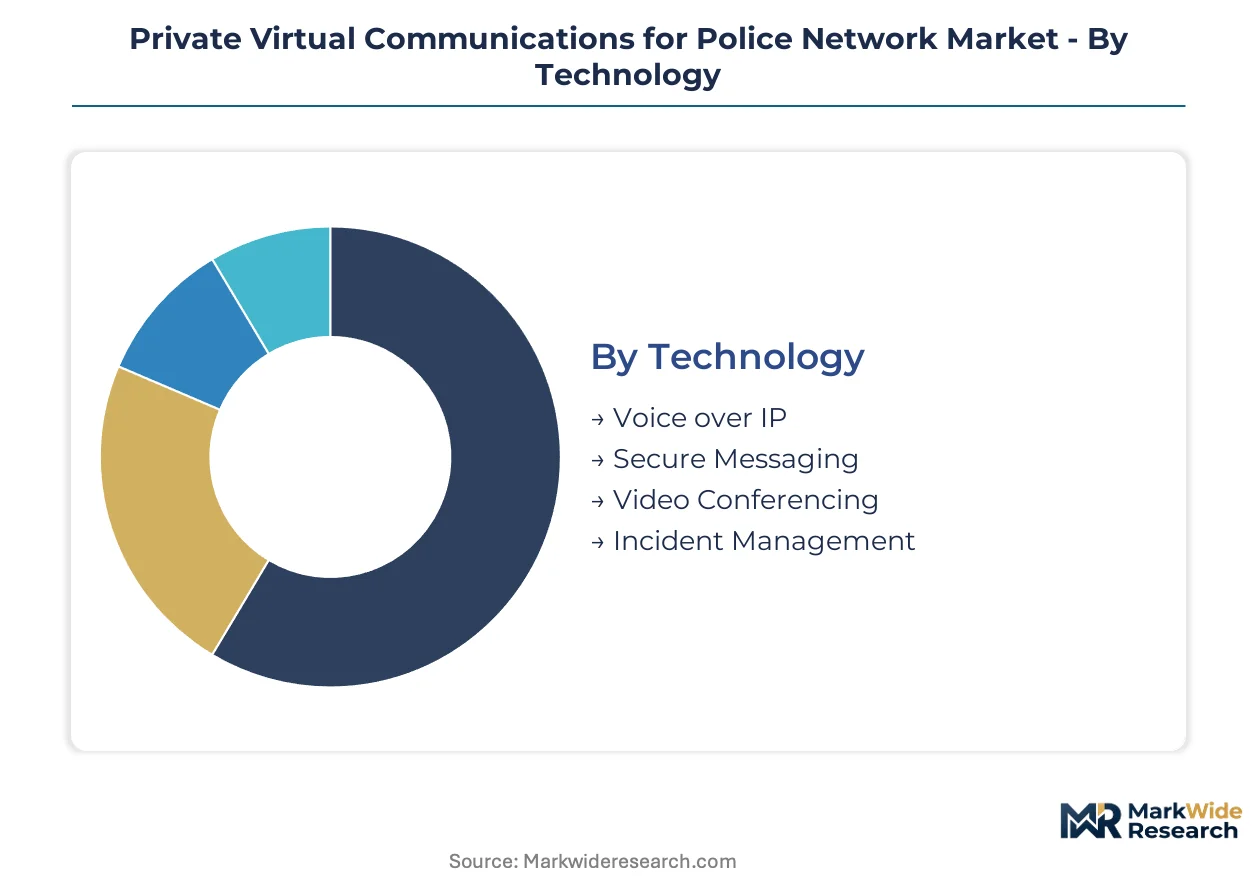
- Voice over IP:Packet-switched voice transmission over LTE and 5G priority spectrum replaces analog dispatch channels. Large metropolitan departments in the United States and Germany are retiring P25 infrastructure for VoIP backbones that integrate with computer-aided dispatch systems.
- Secure Messaging:AES-256 encrypted text and multimedia transmission with ephemeral key rotation. SWAT commanders in Texas and Florida demand this for hostage negotiation coordination where radio silence is mandatory.
- Video Conferencing:Multi-party encrypted video for inter-agency command coordination.
- Incident Management:Unified platforms combining dispatch, resource tracking, and evidence logging.
Voice over IP leads volumes today; Secure Messaging is gaining share fastest.
Deployment Model:
Capital availability and in-house cybersecurity expertise create sharp divides in infrastructure ownership preferences.
- Cloud-based:Subscription models with vendor-managed patching and CJIS-compliant data residency. Mid-sized agencies in California and the United Kingdom favor this to avoid radio tower maintenance and federal grant complexity.
- On-premises:Agency-owned hardware with dedicated encryption appliances. Large state police forces in Germany maintain on-premises cores for counter-terrorism units requiring air-gapped command networks.
- Hybrid:Mixed ownership with sensitive operations on local servers and routine traffic in cloud.
- Dedicated Servers:Single-tenant infrastructure for agencies with sovereign data requirements.
On-premises deployments anchor current installed base; Cloud-based models are expanding most quickly.
User Type:
Operational risk exposure and equipment portability needs differentiate procurement specifications across user categories.
- SWAT Teams:Hardened devices with sub-150ms latency, mesh networking failover, and biometric authentication. These units in Chicago and London drive premium pricing for edge-computing architectures that function in RF-denied environments.
- Dispatch Centers:Fixed-location command hubs requiring 99.999% availability and multi-agency interoperability. Consolidated regional dispatch authorities in Texas and Florida are modernizing with IP-based priority access under FirstNet mandates.
- Patrol Officers:Body-worn integration and vehicle-mounted terminals for routine patrol.
- Internal Affairs:Isolated communication channels with enhanced audit logging for investigation integrity.
Dispatch Centers dominate current procurement volumes; SWAT Teams command the steepest expansion trajectory.
Communication Mode:
Situational urgency and information sensitivity shape channel selection protocols.
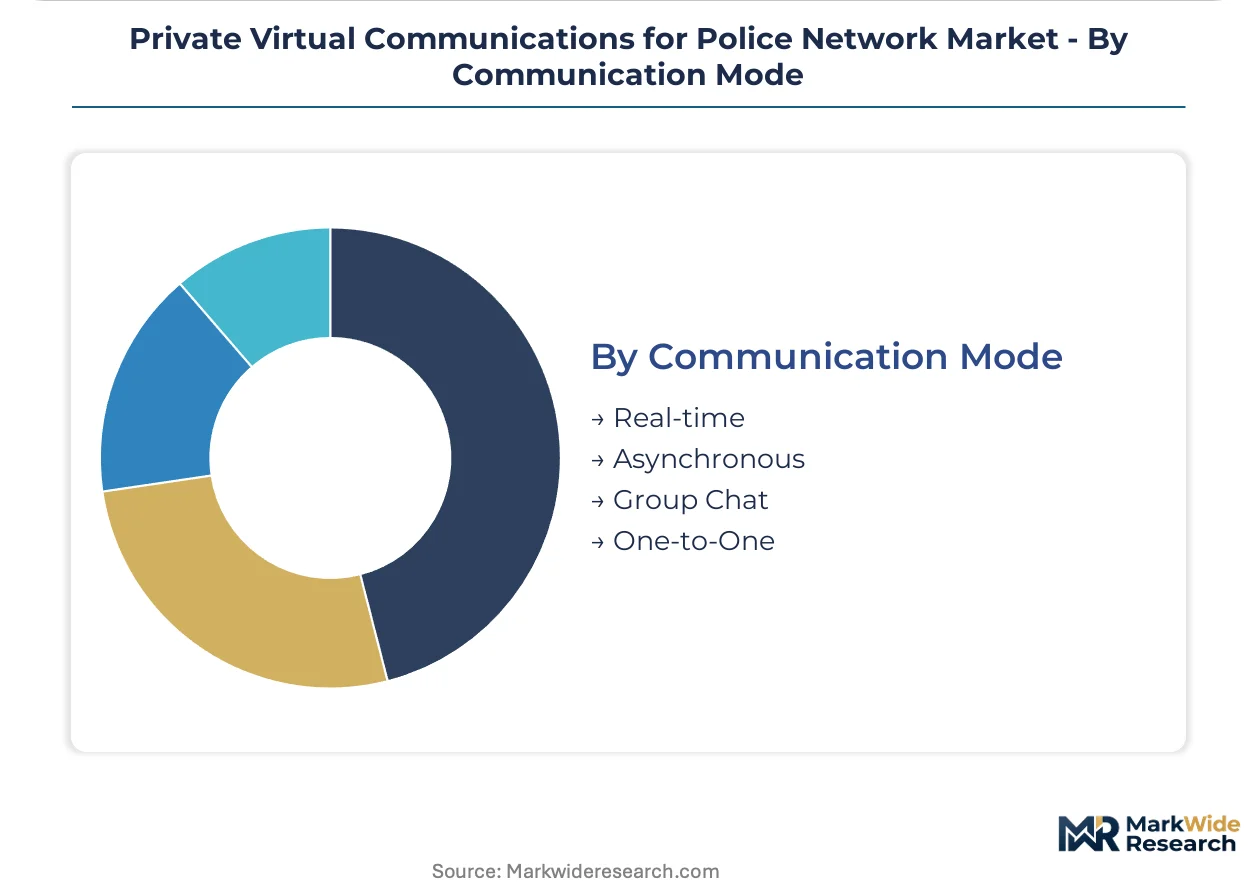
- Real-time:Sub-500ms transmission for active emergency response with guaranteed priority network access. Active shooter protocols in US school districts and UK counter-terrorism units mandate this for immediate officer coordination.
- Asynchronous:Store-and-forward messaging for non-urgent administrative traffic and evidence documentation. Rural sheriffs departments in Germany leverage this to extend coverage beyond cellular dead zones.
- Group Chat:Encrypted multi-party channels for shift coordination and incident command.
- One-to-One:Point-to-point channels for sensitive conversations requiring minimal metadata exposure.
Real-time channels capture the largest share; Asynchronous modes are climbing the fastest as evidence documentation requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cybersecurity talent clusters in Washington DC, London, and Berlin anchor procurement decision-making for encrypted police networks. FCC FirstNet mandates in the United States, ENISA guidelines across the European Union, and national critical infrastructure protections in Germany collectively reshape vendor certification requirements and deployment timelines.
United States
FirstNet priority access contracts and CJIS compliance audits drive procurement for 18,000 separate municipal police authorities. The FCC mandates end-to-end encryption and sub-150ms latency as baseline vendor qualifications. Chicago SWAT units and Texas regional dispatch centers are piloting cloud-native command platforms with integrated body-worn camera evidence streams.
Germany
Counter-terrorism units in Bavaria and North Rhine-Westphalia demand air-gapped command networks with sovereign data residency. ENISA critical infrastructure guidelines and BSI cybersecurity certifications impose parallel technical burdens on foreign suppliers. Berlin federal police are replacing legacy TETRA infrastructure with LTE-based encrypted packet systems.
United Kingdom
Metropolitan Police Service and regional counter-terrorism commands prioritize interoperability with European emergency response networks. Home Office procurement frameworks require vendors to demonstrate compliance with UK National Cyber Security Centre standards. London SWAT-equivalent units are deploying mesh-networking failover systems for RF-denied environments.
France
Gendarmerie Nationale procurement offices mandate algorithmic audit trails for AI-assisted threat detection under EU AI Act risk classifications. ANSSI cybersecurity certifications and national security frameworks restrict vendor eligibility to hardened European suppliers. Paris and Lyon counter-terrorism units are modernizing dispatch workflows with multimedia evidence integration.
Canada
Royal Canadian Mounted Police and municipal forces in Ontario and British Columbia align procurement with US FirstNet technical standards for cross-border interoperability. Public Safety Canada funding programs accelerate IP-based radio replacement in rural jurisdictions. Toronto and Vancouver police departments are piloting subscription-based secure connectivity models.
Private Virtual Communications for Police Network Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. Consolidation pressure intensifies as FCC FirstNet and ENISA certification requirements eliminate smaller suppliers lacking federal security clearances. Infrastructure incumbents anchor core routing and cloud backbones, cybersecurity specialists layer threat prevention architectures, and tactical equipment vendors integrate hardened devices with encrypted communications. Dominant competitive moves include strategic partnerships between network hardware suppliers and cloud platform providers, plus vertical integration into evidence management software adjacent to core communications.
Within the infrastructure tier, Cisco Systems Inc and Microsoft Corporation exemplify divergent strategic positioning. Cisco leverages decades of government security certifications to dominate core routing backbones for police VPN networks. Microsoft extends Azure Government and Teams platforms into dispatch workflows through cloud-integrated command systems. Checkpoint Software Inc occupies the cybersecurity specialist archetype, differentiating through zero-trust architectures purpose-built for law enforcement data flows.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Microsoft Corporation |
| Juniper Networks |
| IBM Corporation |
| Avast Software S R O |
| Checkpoint Software Inc |
| Netmotion Software Inc |
| Radio IP Software Inc |
| Axon Enterprise |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up cybersecurity specialists anchor supply-side discipline in encrypted police communications, compressing vendor margins through aggressive SaaS bundling while concentrating procurement leverage among agencies with federal grant access. This ownership pattern tightens pricing discipline at the high-performance tier where CJIS compliance and FirstNet certification create captive demand pools.
Pricing Analysis
Bundled subscription packages dominate municipal procurement, while unbundled per-device licensing persists in specialized SWAT equipment. Three-tier pricing structure across premium, standard, and economy levels separates agencies with dedicated cybersecurity staff from rural departments dependent on vendor-managed services. Price differentiation hinges on encryption certification depth and guaranteed latency SLAs. Cost compression in standard-tier VoIP backbones is intensifying because cloud-native entrants are undercutting legacy radio vendors on total cost of ownership. Municipal departments with constrained IT budgets exhibit highest price sensitivity; counter-terrorism units demonstrate least sensitivity due to sovereign funding guarantees.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Virginia coordinate hub-and-spoke fulfillment patterns for encrypted hardware, with secondary nodes in Germany and the United Kingdom serving European police agencies. Manufacturing concentrates in Taiwan, South Korea, and the United States for specialized encryption chipsets with AES-256 hardware acceleration. Component sourcing draws from Japanese precision foundries for field-programmable gate arrays, German automotive-grade sensor suppliers for biometric authentication modules, and Israeli cybersecurity firms for threat detection firmware. Single-source vulnerability in Taiwanese semiconductor fabrication creates exposure to export control disruptions. Distribution runs through certified value-added resellers with CJIS security clearance rather than open-channel electronics wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
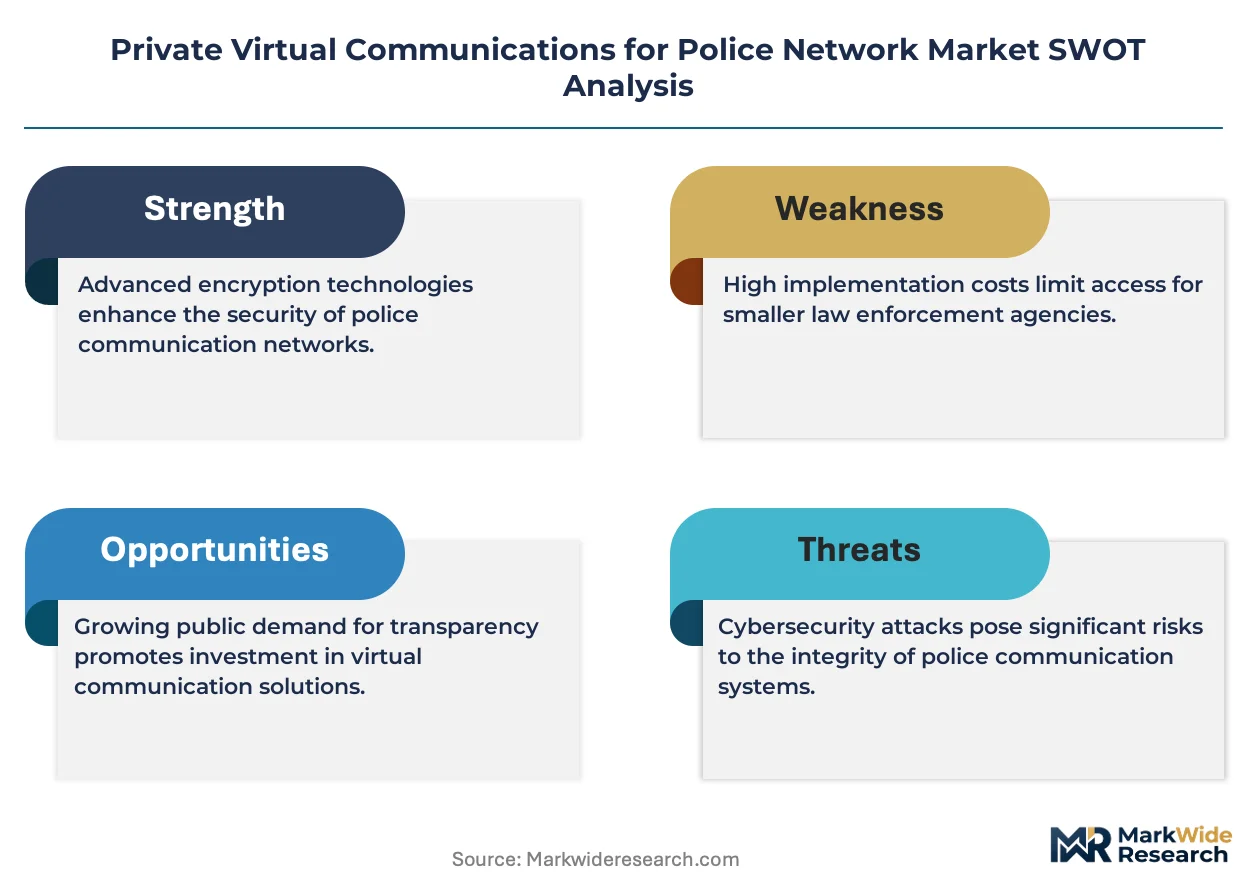
Encrypted police communications represent a late-cycle quality story where procurement committees now prioritize zero-trust architecture over lowest-cost radio replacement, reflecting the irreversibility of multimedia evidence integration into courtroom standards.
For Market Incumbents: Cement federal security clearance moats by accelerating CJIS compliance automation tools that freeze out uncertified rivals. Deepen backward integration into encryption chipset design to escape Taiwanese foundry bottlenecks. Counter emerging cloud-native dispatch platforms by embedding evidence management software directly into routing infrastructure, converting hardware sales into sticky subscription revenue.
For New Entrants and Emerging Players: Capture mid-sized municipal agencies in Florida, Texas, and California that lack federal grant writing capacity for FirstNet equipment. Target network-as-a-service white space where agencies seek to abandon radio tower ownership without building internal cybersecurity teams. Lead with CJIS-compliant cloud storage bundles that piggyback on existing Microsoft Azure Government deployments, avoiding head-to-head competition with Cisco's routing dominance.
For Investors and Strategic Acquirers: Valuations sit cheapest among European cybersecurity specialists with ENISA certifications that lack US market presence but possess replicable compliance frameworks. Five-to-ten-year viability favors vendors with dual US-EU certification pathways as cross-border interoperability mandates harden. Monitor FirstNet spectrum allocation decisions as the critical inflection signal determining which platforms achieve de facto standard status in multi-agency emergency response scenarios.
| Strategic Initiative | Industry Significance |
|---|---|
| FirstNet Certification Investment | Unlocks priority spectrum access for vendors seeking federal police contracts under FCC mandates. |
| Cloud-Native Dispatch Platform Launch | Shifts municipal agencies from capital-intensive radio towers to subscription-based secure connectivity models. |
| Zero-Trust Architecture Integration | Differentiates cybersecurity layers as FBI CJIS audits intensify compliance requirements. |
| Multimedia Evidence Management Expansion | Captures adjacent revenue from body-worn camera and drone video storage integration. |
| EU ENISA Certification Pathway | Opens parallel procurement channels in Germany and France under critical infrastructure protections. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, France, and Canada, with primary inputs from each jurisdiction's federal and municipal police procurement offices. The approach combines structured interviews with police IT directors, SWAT equipment coordinators, CJIS compliance officers, and regional dispatch authority managers with secondary validation against FCC FirstNet filings, ENISA critical infrastructure guidelines, FBI CJIS security policy updates, and vendor federal contract disclosures. Bottom-up equipment deployment estimates triangulate against top-down public safety broadband budget allocations.
Granularity-level modeling disaggregates the analysis window by technology type, deployment model, user category, and communication mode, with cross-cutting segmentation by agency size tier and CJIS compliance maturity. CAGRs derive from logistic adoption curves fitted to historical radio replacement cycles and projected IP infrastructure transition timelines. Industry-specific forecast inputs include FirstNet subscriber growth trajectories and TETRA decommissioning schedules across European police forces.
Semiconductor supply disruptions, spectrum reallocation decisions, and CJIS audit backlog delays are the dominant revision risks to baseline projections. Forecasts reflect documented assumptions regarding federal grant continuity and interoperability mandate enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Software-Defined Security Market
Security Software
Certificate Authority Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Secaas Market
Security Software
Single Sign-On Market
Security Software
Network Security Appliance Market
Security Software
Japan Mobile Biometrics Market
Security Software
Data Privacy Software Market
Security Software
Cloud Security Software Market
Security Software
Global Password Management Software Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Digital Risk Protection Software Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Employee Fraud Detection Market
Security Software
Phone Antivirus Software Market
Security Software
Endpoint Security Solutions Market