
 Japan Retail Cash Management Market | 2026-2036
Japan Retail Cash Management Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Retail Cash Management Market Insights
Bank-branch cash distribution to retail endpoints is narrowing as convenience store chains and supermarkets build direct relationships with equipment vendors. Glory Ltd. dominates the physical cash handling hardware segment through decades of specialized engineering. Fujitsu Frontech leverages its semiconductor heritage to embed advanced authentication sensors into retail terminals. Toshiba Tec Corporation sustains a formidable position in point-of-sale integration by controlling both hardware fabrication and software middleware layers.
Japan Retail Cash Management encompasses the hardware, software, and service infrastructure that automates cash acceptance, authentication, storage, and reconciliation across physical retail environments, typically operating at processing speeds exceeding 1,000 banknotes per minute with counterfeit detection accuracy above 99.9%. Its primary commercial purpose is to reduce labor hours tied to register reconciliation while minimizing cash shrinkage and accelerating deposit cycles. Point of Sale Systems command the largest installed base among product categories, though Currency Discriminators generate disproportionate margin pools due to their sensor density and replacement part economics. Cash Management Solutions within the service type dimension anchor recurring revenue streams, while Software Integration represents the fastest-growing segment as retailers seek API-connected treasury visibility.
METI's productivity standards and the F-Gas Regulation for cooling systems in cash vault infrastructure shape equipment design requirements, while JIS standards govern mechanical durability and electromagnetic compatibility for devices deployed in 24-hour retail settings. The Bank of Japan's ongoing pilot programs for central bank digital currency introduce contingency planning considerations for cash infrastructure stakeholders. Retailers and vendors must monitor whether METI expands automation subsidies beyond current manufacturing-focused schemes into frontline service operations.
Market Dynamics
METI's productivity mandates and the Bank of Japan's CBDC pilot programs are compressing investment timelines for cash infrastructure stakeholders. Equipment vendors now face simultaneous pressure to reduce labor dependency while maintaining contingency readiness for digital currency transitions.
Growth Catalysts
- Convenience store automation:Chains across Tokyo, Osaka, and Fukuoka are deploying intelligent cash handling to offset labor shortages. 24-hour operations require continuous uptime.
- F-Gas Regulation compliance:Cooling system upgrades in cash vault infrastructure are triggering replacement cycles. Equipment vendors integrate compliant thermal management to meet METI standards.
- Currency Discriminator sensor density:Advanced authentication modules at processing speeds above 1,000 banknotes per minute reduce shrinkage. Retailers prioritize counterfeit detection accuracy thresholds.
Market Restraints
- Semiconductor input volatility:Sensor fabrication depends on specialized foundry capacity concentrated in East Asian supply chains. Authentication module costs fluctuate with wafer availability.
- Vault cooling system complexity:F-Gas Regulation mandates for cash storage infrastructure extend procurement cycles. Compliance engineering adds non-recurring engineering costs.
- Central bank digital currency contingency:The Bank of Japan's pilot programs create planning uncertainty. Cash infrastructure stakeholders must maintain dual-track investment strategies.
Strategic Opportunities
- API-connected treasury visibility:Software Integration represents the fastest-growing segment as retailers demand real-time deposit reconciliation. Middleware vendors capture recurring revenue through SaaS models.
- Kanto region density:Dense urban retail networks in Tokyo require high-throughput cash processing infrastructure. Convenience store saturation creates installed base expansion potential.
- Point of Sale Systems integration:Hardware vendors controlling both fabrication and middleware layers can bundle authentication with transaction processing. Cross-selling compresses customer acquisition costs.
Industry Challenges
- Legacy register reconciliation skill gaps:Automated cash handling reduces frontline labor hours but requires field technicians for sensor calibration. Technical training pipelines lag deployment schedules.
- JIS electromagnetic compatibility certification:24-hour retail settings demand mechanical durability testing. Approval timelines extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Retail Cash Management Market |
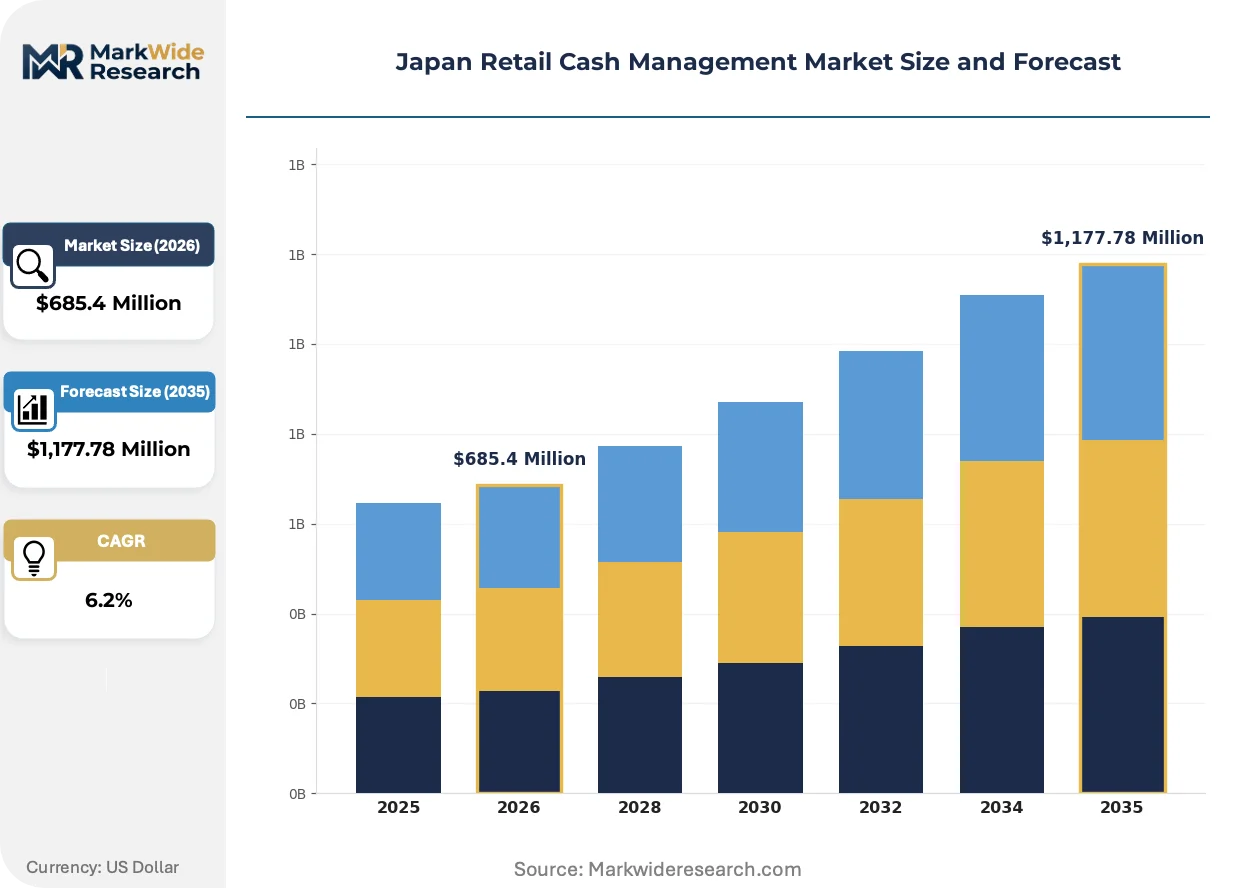
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cash Registers, Point of Sale Systems, Coin Counter Machines, Currency Discriminators End User: Supermarkets, Convenience Stores, Specialty Shops, E-commerce Platforms Service Type: Cash Management Solutions, Software Integration, Maintenance Services, Training Programs Distribution Channel: Direct Sales, Online Retailers, Resellers, Distributors |
| Companies Covered | Resona Bank, Glory Ltd., MUFG Bank, Fujitsu Frontech, Toshiba Tec Corporation, Mizuho Bank, Japan Post Bank, NTT Data Corporation, SMBC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Retail Cash Management Market Trends and Innovations
Intelligent cash systems are converging with enterprise treasury platforms, eroding the traditional boundary between store-level operations and corporate finance functions. This integration is compressing deposit cycles and shifting vendor value propositions toward data services.
Multi-spectral banknote authentication is migrating from ultraviolet-infrared dual detection toward machine-learning-enabled spectral analysis. Major convenience store chains in the Kanto region are piloting these modules at select Tokyo locations. The technology is compressing false-positive rates while extending sensor replacement intervals.
METI's F-Gas Regulation is mandating low-global-warming-potential refrigerants in cash vault cooling systems. Equipment manufacturers must redesign thermal management architectures to maintain JIS mechanical durability standards. Currency Discriminator vendors with integrated vault offerings face the steepest engineering adaptation requirements.
Retailers are unbundling after-sales service from hardware procurement, preferring outcome-based uptime guarantees over traditional maintenance contracts. Convenience store operators in Osaka and Fukuoka now specify availability metrics rather than spare parts coverage. This shift is compressing vendor margins while extending contract durations.
Japan Retail Cash Management Market Segmentation
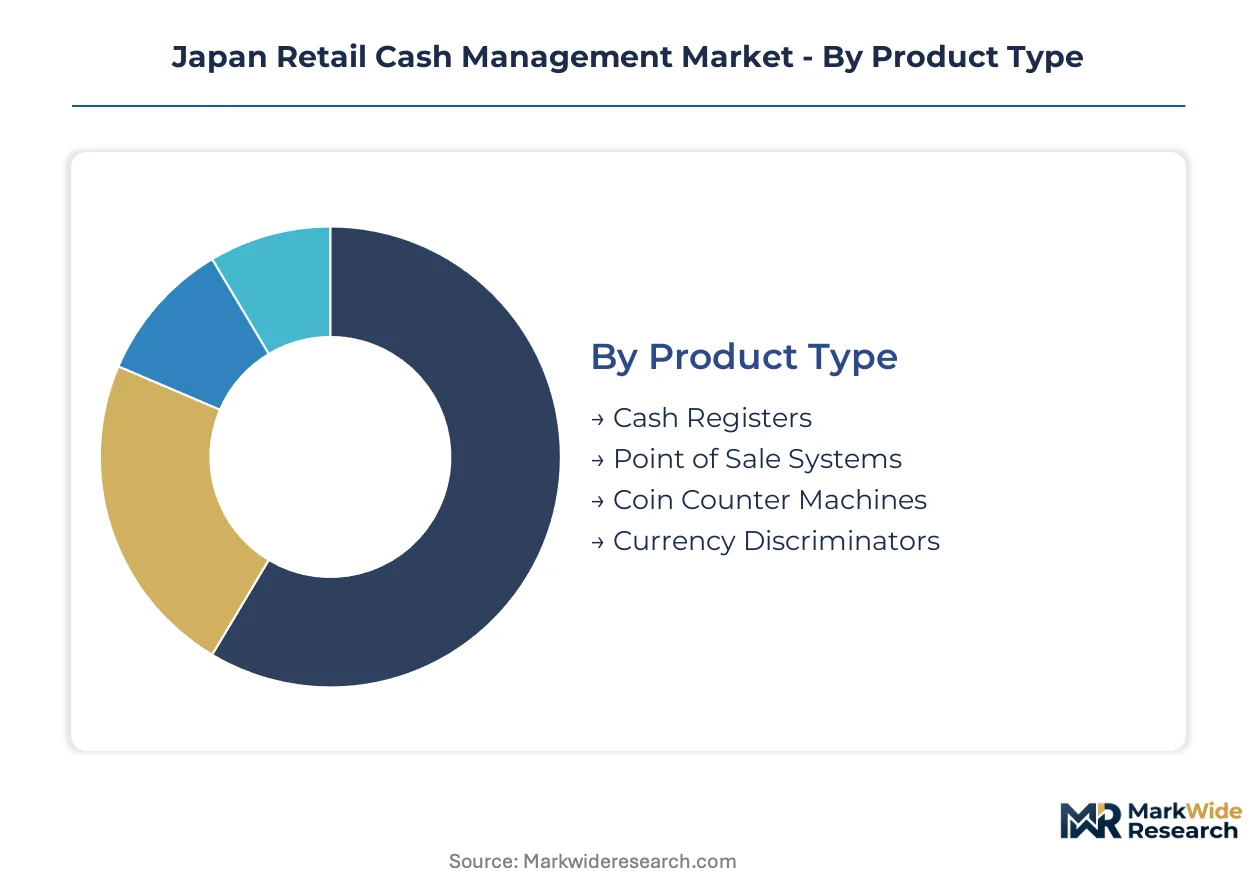
Segmentation in Japan's retail cash management market reflects divergent automation maturity across retail formats and diverging procurement preferences shaped by METI's labor-saving mandates. Equipment specifications, service bundling, and channel access vary substantially between high-volume convenience store operators and fragmented specialty retail.
Product Type:
Mature hardware categories anchor installed base economics while emerging sensor-intensive systems capture replacement cycles and margin expansion.
- Point of Sale Systems:Integrated terminals combining transaction processing with peripheral cash handling dominate deployment volumes across Tokyo and Osaka convenience store networks. Dense urban retail saturation in Kanto drives demand for compact, high-throughput units that reconcile sales data with cash vault deposits in real-time.
- Currency Discriminators:Multi-spectral authentication modules processing above 1,000 banknotes per minute command premium positioning due to sensor density and replacement part economics. Fukuoka-based retailers prioritize these units to minimize shrinkage in 24-hour operations where labor supervision is thin.
- Cash Registers:Entry-level mechanical units with basic till management persist in legacy specialty shops and smaller supermarket formats.
- Coin Counter Machines:Automated sorting and wrapping systems reduce manual reconciliation hours for high-coin-volume retail segments.
Point of Sale Systems retain volume leadership; Currency Discriminators hold the steepest expansion curve.
End User:
Procurement scale separates national chains with direct vendor relationships from fragmented operators dependent on distributor networks.
- Convenience Stores:24-hour operators across Tokyo, Osaka, and Fukuoka constitute the primary demand concentration for intelligent cash handling. METI's productivity standards and chronic labor shortages accelerate automation timelines for register reconciliation and overnight deposit preparation.
- Supermarkets:High-volume checkout environments require robust currency discriminators integrated with back-office cash vault infrastructure. F-Gas Regulation compliance for cooling systems extends procurement cycles and favors vendors with integrated thermal management engineering.
- Specialty Shops:Smaller format retailers prioritize compact, low-maintenance units with simplified training requirements.
- E-commerce Platforms:Physical pickup locations and cash-on-delivery operations create hybrid demand for portable cash management solutions.
Convenience Stores dominate procurement volumes; E-commerce Platforms are expanding most quickly as physical touchpoints proliferate.
Service Type:
Revenue model evolution shifts vendor relationships from transactional hardware sales toward recurring service architectures.
- Cash Management Solutions:Comprehensive service bundles encompassing hardware, cash-in-transit coordination, and reconciliation outsourcing anchor recurring revenue streams. Major convenience store chains in Kanto specify outcome-based uptime guarantees rather than traditional spare parts coverage.
- Software Integration:API-connected treasury visibility platforms represent the most rapidly climbing segment as retailers demand real-time deposit reconciliation across distributed store networks. Middleware vendors capture SaaS revenue by linking store-level cash data with corporate finance systems.
- Maintenance Services:Field technician deployment for sensor calibration and mechanical repair supports hardware lifecycle extension.
- Training Programs:Operator education for authentication module handling and vault protocol compliance addresses skill gaps from automated register reconciliation.
Cash Management Solutions sustain the largest revenue base; Software Integration gains share fastest through API monetization.
Distribution Channel:
Channel strategy bifurcates between direct engagement with scale operators and intermediary-dependent access to fragmented retail.
- Direct Sales:National convenience store chains and supermarket cooperatives negotiate directly with Glory Ltd., Fujitsu Frontech, and Toshiba Tec Corporation for customized hardware-software bundles. Direct relationships compress customer acquisition costs and enable co-development of METI-compliant thermal management systems.
- Distributors:Regional wholesalers maintain inventory proximity to specialty shops and smaller supermarket formats across secondary cities. Distributor networks extend vendor reach into Fukuoka and other western Japan markets where direct sales coverage is thin.
- Online Retailers:E-commerce procurement platforms serve smaller operators seeking standardized, low-configuration units with rapid delivery.
- Resellers:Value-added resellers bundle installation, training, and localized support for mid-tier retail segments.
Direct Sales commands the highest transaction values; Distributors provide the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokyo-Osaka Shinkansen corridor underwrites Japan's retail cash management density by connecting the Kanto and Kansai industrial zones where convenience store automation concentrates.
Kanto/Tokyo
Convenience store saturation across Greater Tokyo drives demand for high-throughput cash processing infrastructure. METI's productivity standards accelerate intelligent cash handling deployments in 24-hour operations. Dense urban retail networks in Shibuya, Shinjuku, and Yokohama require continuous uptime systems with API-connected treasury visibility.
Kansai/Osaka
Supermarket cooperatives and regional convenience chains prioritize F-Gas Regulation compliance in cash vault cooling systems. The Osaka-Kobe manufacturing belt supplies thermal management components to equipment vendors. Retailers in Kyoto and Osaka specify outcome-based uptime guarantees over traditional maintenance contracts.
Chubu/Nagoya
Automotive supply chain retail networks create hybrid demand for portable cash management at parts distribution centers. JIS electromagnetic compatibility certification requirements extend product launch timelines for vendors serving 24-hour highway service areas. Nagoya-based equipment distributors maintain inventory proximity to secondary city retail.
Kyushu/Fukuoka
Western Japan's convenience store expansion targets labor-saving automation to offset chronic staffing shortages. Fukuoka retailers prioritize currency discriminators with counterfeit detection accuracy above 99.9% for thinly supervised overnight operations. Regional wholesalers extend vendor reach where direct sales coverage remains limited.
Hokkaido
Tourism-dependent retail in Sapporo and Niseko drives seasonal cash volume spikes requiring flexible processing capacity. Cold climate durability testing under JIS mechanical standards shapes equipment specifications for outdoor-adjacent installations. Local distributors bundle installation and training for mid-tier retail segments.
Japan Retail Cash Management Market Competitive Landscape
On the supply side, the industry is bifurcated between specialized cash handling hardware fabricators and diversified electronics conglomerates with semiconductor heritage. Equipment vendors cluster around three strategic archetypes: dedicated physical cash engineering specialists, sensor-integrated terminal manufacturers, and point-of-sale integration platforms controlling middleware layers. Competitive positioning depends on backward integration into authentication sensor fabrication and forward integration into treasury software APIs.
Within the dedicated hardware tier, Glory Ltd. exemplifies decades-long specialization in physical cash handling engineering. Fujitsu Frontech occupies a position bridging semiconductor sensor heritage with retail terminal deployment. Toshiba Tec Corporation anchors the integrated platform segment through combined hardware fabrication and software middleware control. These three entities represent distinct strategic postures toward METI's labor-saving mandates and the Bank of Japan's digital currency contingency planning.
| Leading Market Players |
|---|
| Resona Bank |
| Glory Ltd. |
| MUFG Bank |
| Fujitsu Frontech |
| Toshiba Tec Corporation |
| Mizuho Bank |
| Japan Post Bank |
| NTT Data Corporation |
| SMBC |
| Others |
Pricing and Supply Chain Analysis
Specialized foundry undercapacity in East Asian semiconductor fabrication is compressing sensor module availability and forcing equipment vendors toward longer-term contract structures with tiered volume commitments. Glory Ltd., Fujitsu Frontech, and Toshiba Tec Corporation leverage scale procurement to secure wafer allocation, while smaller assemblers absorb spot-market volatility in authentication chip pricing.
Pricing Analysis
Volume-discount tiering separates national convenience store chains from fragmented specialty retail operators across three performance levels. Premium pricing attaches to Currency Discriminators with multi-spectral authentication above 1,000 banknotes per minute, while standard tiers cover integrated Point of Sale Systems with basic counterfeit detection. Cost compression in sensor-intensive modules is intensifying because semiconductor input volatility feeds through to authentication module bills of materials. Regional supermarket cooperatives in Kansai exhibit highest price sensitivity due to F-Gas Regulation compliance engineering overhead, whereas Tokyo-based convenience chains prioritize uptime guarantees over unit procurement cost.
Supply Chain Analysis
Contract-manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation for authentication sensor foundry capacity, with backend assembly concentrated in South Korea and coastal China. Optical sensor arrays, high-speed motors, and thermal management compressors constitute critical component dependencies. Single-source vulnerability in specialized banknote transport mechanisms creates procurement risk for 24-hour retail uptime specifications. Distribution runs through direct vendor relationships with national chains and regional wholesaler networks serving Fukuoka and secondary western Japan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan Retail Cash Management Market functions as a defensive-moat industry where regulatory entrenchment through METI certification requirements and JIS electromagnetic compatibility standards creates substantial incumbent protection against displacement.
For Market Incumbents: Build switching-cost moats by embedding API-connected treasury platforms deeper into corporate finance workflows, compressing deposit cycle visibility for retailers. Deepen backward integration into authentication sensor fabrication to offset semiconductor supply volatility threatening margin stability. Prioritize co-development partnerships with METI on expanded automation subsidy schemes beyond current manufacturing-focused programs. For New Entrants and Emerging Players: Pursue white-space expansion in Kyushu convenience store networks where direct sales coverage from Glory Ltd. and Fujitsu Frontech remains thin, and regional wholesalers dominate procurement access. Target outcome-based service contracts in Osaka supermarket cooperatives seeking uptime guarantees over traditional hardware ownership. Leverage SaaS-first treasury visibility platforms to bypass capital-intensive hardware fabrication barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Currency Discriminator manufacturing due to F-Gas Regulation thermal management engineering requirements and multi-spectral sensor density investments. Long-term viability favors vendors controlling both hardware fabrication and middleware API layers through integrated platform architectures. Acquisition screening should prioritize firms with captive sensor supply relationships and established METI compliance track records. Quarterly review of METI subsidy expansion announcements and Bank of Japan CBDC pilot program disclosures is advised to detect demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API-Connected Treasury Platform Launch | Middleware vendors capture recurring SaaS revenue from convenience store chains demanding real-time deposit reconciliation. |
| Multi-Spectral Authentication Module Development | Machine-learning-enabled spectral analysis compresses false-positive rates for Tokyo convenience store pilots. |
| F-Gas Regulation Thermal Management Redesign | Equipment vendors integrate low-global-warming-potential refrigerants to maintain JIS mechanical durability standards. |
| Outcome-Based Service Contract Expansion | Osaka and Fukuoka retailers now specify availability metrics over traditional spare parts coverage. |
| Backward Integration into Sensor Fabrication | Semiconductor heritage vendors secure wafer allocation against East Asian foundry capacity constraints. |
Research Methodology
Initial hypotheses were tested against primary input from cash management equipment procurement directors, convenience store operations executives, METI policy liaison officers, and bank treasury platform managers, and refined through secondary validation against Bank of Japan payment system reports, METI productivity standard filings, JIS certification databases, and customs import records for cash handling machinery. Bottom-up installed base modeling triangulated against top-down market sizing from equipment vendor revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type hardware tiers, service type revenue models, end-user retail format scale, and regional adoption intensity across Kanto, Kansai, and Kyushu clusters. CAGRs were derived from equipment replacement cycle analysis and automation penetration curve fitting, incorporating METI labor-saving mandate compliance timelines and F-Gas Regulation thermal management upgrade cycles as industry-specific forecast inputs.
Sensitivities concentrate around semiconductor foundry capacity allocation shifts, METI subsidy scheme expansion decisions, and Bank of Japan CBDC pilot program acceleration that could compress cash infrastructure investment timelines. Forecasts embed assumptions regarding convenience store automation penetration rates and authentication sensor cost trajectories. Quarterly review of METI policy bulletins, foundry utilization reports, and convenience store chain capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Estonia POS Terminal Market
Payments
France Virtual Cards Market
Payments
Blockchain Payments Software Market
Payments
Global Accounts Payable Software Market
Payments
Remote Mobile Payment Market
Payments
Global Payments Market
Payments
Malta POS Terminal Market
Payments
Sweden Mobile Payments Market
Payments
Biometric Payment Cards Market
Payments
Sweden POS Terminals Market
Payments
Latin America Subscription and Billing Management Market
Payments
United States Payment Gateways Market
Payments
Latin America Payment Gateway Market
Payments
Finland Payments Market
Payments
New Zealand Payments Market
Payments
Belgium POS Terminals Market