
 Mexico Real Time Payments Market | 2026-2036
Mexico Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Real Time Payments Market Foresight
Platform licensing revenue from API integration layers is tilting toward domestic payment processors and away from legacy card networks. BBVA México leverages its merchant-acquiring scale to embed real-time settlement into commercial banking workflows. Prosa anchors transaction switching infrastructure for regional banks seeking CoDi connectivity without proprietary buildouts. ACI Worldwide Inc competes on fraud-scoring modules that reduce chargeback exposure for high-velocity merchant payments.
Mexico real time payments denote funds transfer systems that clear and settle transactions within seconds through the SPEI-CoDi rail operated by Banco de México, requiring ISO 20022 message formatting and dual-factor authentication for amounts above threshold limits. These systems serve commercial and consumer purposes by eliminating interbank settlement risk and reducing cash-handling costs for retail and corporate treasuries. P2P transfers through mobile banking channels lead transaction volumes as smartphone penetration deepens among underbanked populations. Merchant payments via QR codes capture expanding margin pools as street vendors and micro-retailers adopt low-cost acceptance infrastructure. Cloud-based delivery models outpace on-premises deployments among fintech entrants seeking elastic capacity during payroll and tax-payment spikes.
Banco de México governs SPEI-CoDi interoperability standards and settlement finality rules that determine which institutions can originate real-time transactions. Mexico's central bank also enforces cybersecurity protocols aligned with CNBV guidelines for financial institution operational resilience. The Comisión Nacional para la Protección y Defensa de los Usuarios de Servicios Financieros (CONDUSEF) mandates fee transparency and dispute-resolution timelines that shape consumer-facing product design. Stakeholders must monitor whether Banco de México extends CoDi to cross-border corridors and how CNBV licensing requirements for payment aggregators evolve under open finance frameworks.
Market Dynamics
Banco de México's SPEI-CoDi rail expansion is compressing settlement windows for commercial banks and forcing merchant acquirers to reprice transaction economics around instant finality rather than overnight batch processing.
Growth Catalysts
- CoDi Interoperability Mandates:Banco de México's ISO 20022 formatting requirements are standardizing message protocols across regional banks, reducing integration friction for fintech entrants.
- QR Code Infrastructure:Street vendors and micro-retailers in urban corridors are adopting low-cost acceptance terminals, expanding addressable merchant pools beyond traditional POS networks.
- Smartphone Penetration Depth:Underbanked populations in Mexico City and Monterrey are accessing SPEI rails through mobile banking channels, driving P2P transaction volume expansion.
Market Restraints
- Dual-Factor Authentication Thresholds:Banco de México's transaction limits requiring biometric or token verification create friction for high-velocity micro-payments below regulatory floors.
- Cloud Concentration Risk:Elastic capacity provisioning for payroll and tax-payment spikes depends on hyperscaler infrastructure concentrated in limited domestic availability zones.
- Cash Handling Cost Stickiness:Informal sector merchants in peripheral states maintain parallel cash operations due to intermittent connectivity and consumer preference inertia.
Strategic Opportunities
- Cross-Border Corridor Extension:Banco de México's potential SPEI-CoDi linkage with US correspondent banking networks would unlock remittance settlement compression for migrant worker flows.
- Open Finance Aggregation:CNBV licensing evolution for payment aggregators under forthcoming frameworks will enable account-to-account payment initiation beyond traditional card rails.
- Embedded Treasury Workflows:Corporate ERP integration with real-time settlement APIs is digitizing cash concentration and disbursement scheduling for mid-market enterprises.
Industry Challenges
- ISO 20022 Talent Scarcity:Message mapping and schema implementation expertise for legacy core banking systems remains concentrated among specialized systems integrators.
- Fraud-Scoring Latency Requirements:Sub-second transaction authorization demands are forcing acquirers to rearchitect risk engines without degrading approval rates for thin-file merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Real Time Payments Market |
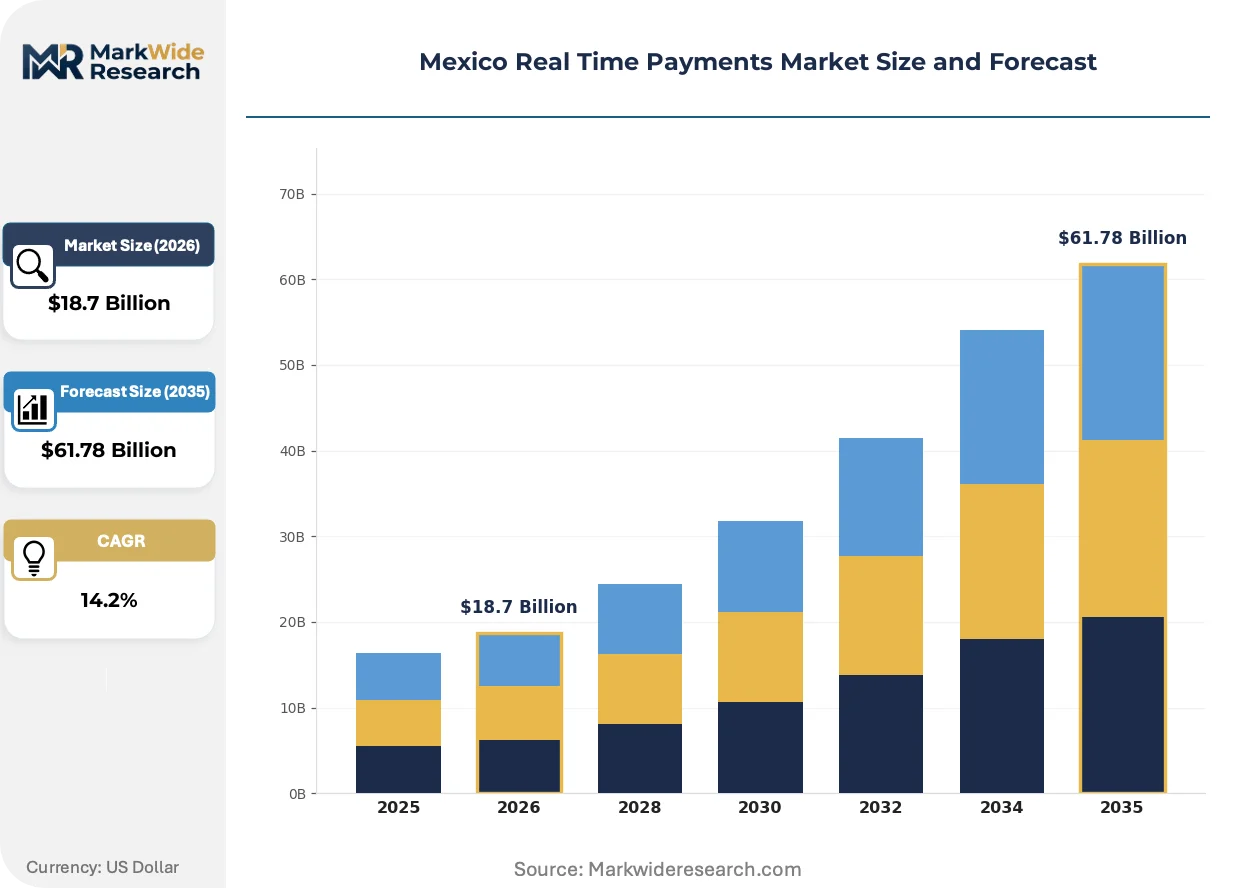
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: B2B Payments, P2P Transfers, Merchant Payments, Bill Payments Technology: Mobile Banking, Digital Wallets, QR Codes, API Integrations End User: Small Businesses, Large Enterprises, Retailers, Financial Institutions Delivery Model: Cloud-based, On-premises, Hybrid, Mobile-enabled |
| Companies Covered | Banco Azteca, Mastercard Inc, BBVA México, Fiserv Inc, ACI Worldwide Inc, Citibanamex, Visa Inc, Prosa, Banco Santander México, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Real Time Payments Market Shifts & Advancements
Merchant payment orchestration is shifting from card-present hardware toward software-defined acceptance stacks that embed real-time settlement into commercial banking workflows.
Cloud-native switching infrastructure is digitizing transaction routing decisions for regional banks seeking CoDi connectivity without proprietary data center investments. Mid-tier institutions in Guadalajara and Puebla are migrating switching workloads to elastic environments, compressing time-to-market for instant payment products from quarters to weeks.
Banco de México's cybersecurity protocols aligned with CNBV operational resilience guidelines are mandating penetration testing cycles and incident response drills for all SPEI-CoDi participants. Payment processors must demonstrate failover capabilities across geographically separated processing nodes, with compliance audits now occurring on 18-month rather than triennial cycles.
Micro-merchant onboarding patterns are fragmenting acquiring relationships as street vendors comparison-shop between digital wallet providers and bank-owned merchant apps. QR code interoperability demands are forcing acquirers to support multiple presentation formats, with Mexico City corridor merchants typically maintaining three to four active acceptance relationships to maximize consumer coverage.
Mexico Real Time Payments Market Segmentation
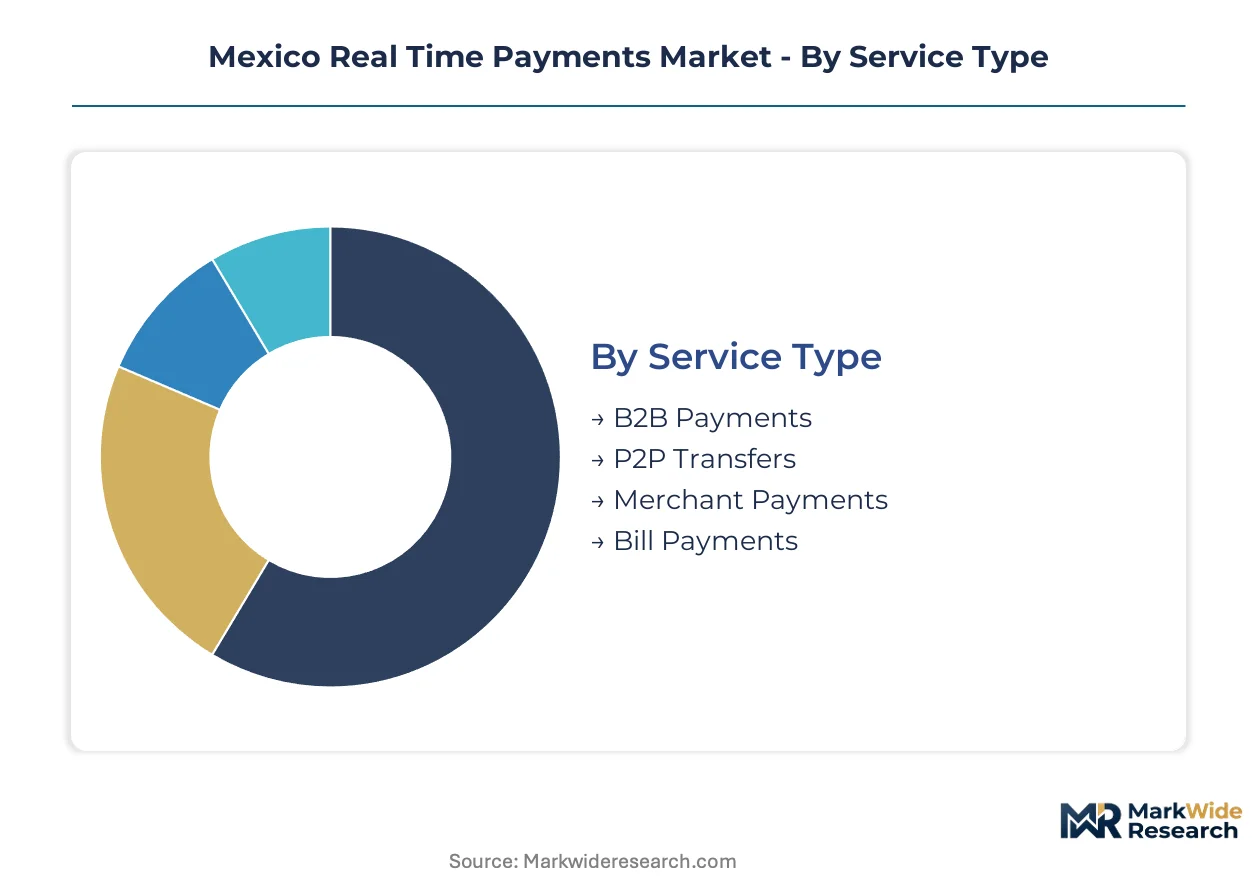
SPEI-CoDi infrastructure deployment varies sharply across transaction types and technical interfaces, creating divergent margin structures for payment processors. Understanding these divides reveals where Banco de México's standardization mandates compress differentiation versus where proprietary technology stacks retain pricing power.
Service Type:
Use-case spectrum spans high-value corporate treasury flows to sub-peso street vendor transactions, each imposing distinct latency and authentication requirements on the underlying rail.
- B2B Payments:ERP-integrated disbursements and supplier settlements leverage ISO 20022 structured remittance data for automated reconciliation. Large enterprises in Monterrey industrial corridors demand same-day payroll and tax payment finality, compressing working capital cycles.
- P2P Transfers:Mobile banking channels dominate volume as smartphone penetration deepens among underbanked populations in Mexico City peripheral zones. Banco de México's dual-factor authentication thresholds create friction for micro-transactions below regulatory floors.
- Merchant Payments:QR-enabled acceptance infrastructure expands addressable pools beyond traditional POS networks for street vendors.
- Bill Payments:Recurring utility and telecom settlements through SPEI rails reduce cash-handling costs for collection agents.
The dominant share belongs to P2P Transfers, while Merchant Payments is closing the gap fastest.
Technology:
Interface modality determines customer acquisition economics and fraud exposure profiles for financial institutions building on CoDi rails.
- Mobile Banking:Native applications from BBVA México and regional banks embed SPEI origination with biometric authentication layers. Underbanked populations in Guadalajara and Puebla access real-time rails without traditional branch relationships.
- Digital Wallets:Non-bank providers leverage CNBV licensing frameworks to offer stored-value accounts with instant settlement capabilities. Micro-merchant onboarding fragmentation forces acquirers to support multiple wallet interoperability standards.
- QR Codes:Low-cost presentation formats reduce hardware barriers for informal sector merchants in urban retail corridors.
- API Integrations:Platform licensing revenue tilts toward domestic processors embedding real-time settlement into commercial workflows.
Mobile Banking retains the largest transaction volume base, though API Integrations are climbing the fastest as corporate treasury digitization accelerates.
End User:
Organizational scale dictates integration complexity and support requirements for SPEI-CoDi connectivity.
- Small Businesses:Micro-retailers and street vendors adopt QR-enabled acceptance with minimal technical integration. Mexico City corridor merchants typically maintain three to four active acquiring relationships to maximize consumer coverage.
- Large Enterprises:Corporate treasuries demand ERP-embedded cash concentration and disbursement scheduling with real-time visibility. Mid-market enterprises in Monterrey industrial zones drive embedded treasury workflow adoption.
- Retailers:Multi-location chains require orchestration layers across payment acceptance and reconciliation systems.
- Financial Institutions:Regional banks in Guadalajara and Puebla migrate switching workloads to cloud-native infrastructure for elastic capacity.
Financial Institutions process the highest transaction values, yet Small Businesses are gaining share fastest as merchant acquiring competition intensifies.
Delivery Model:
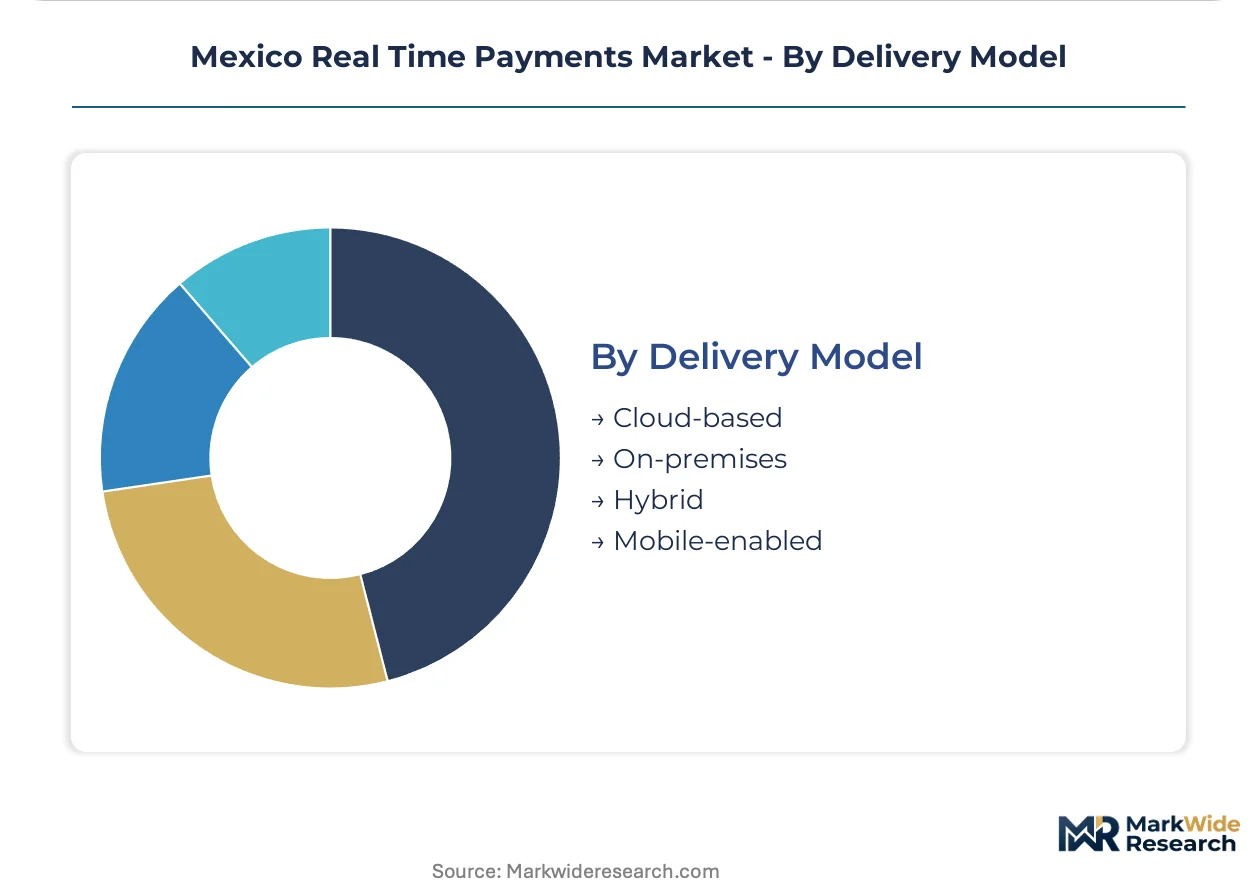
Infrastructure deployment choice reflects regulatory compliance burden versus operational flexibility trade-offs for market entrants.
- Cloud-based:Elastic capacity provisioning supports payroll and tax-payment spikes without proprietary data center investments. Fintech entrants outpace legacy institutions in time-to-market for instant payment products.
- On-premises:Legacy core banking systems retain switching infrastructure for institutions with concentrated transaction profiles. ISO 20022 message mapping expertise scarcity concentrates among specialized systems integrators.
- Hybrid:Regional banks balance sensitive data residency requirements with burst capacity needs during settlement windows.
- Mobile-enabled:Smartphone-native delivery reaches underbanked populations without traditional banking infrastructure access.
Cloud-based deployment holds the dominant position, while Hybrid models are expanding most quickly as CNBV operational resilience guidelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant acquirers in Mexico City command premium pricing for instant settlement services, while peripheral state banks compete aggressively on transaction fees to capture underbanked P2P volumes.
Mexico City Metro
Corporate treasuries and high-velocity retail chains drive demand for ERP-embedded real-time disbursements. Banco de México's SPEI-CoDi interoperability mandates enforce ISO 20022 formatting across all participants. The Polanco and Santa Fe financial corridors concentrate fintech development labs and merchant-acquiring headquarters.
Nuevo León
Industrial manufacturers in Monterrey prioritize same-day payroll finality and supplier settlement compression. CNBV operational resilience guidelines mandate penetration testing cycles for all payment processors. The Apodaca industrial park anchors cloud-native switching infrastructure deployments for regional bank consortia.
Jalisco
Guadalajara's technology sector generates API integration demand for platform licensing revenue streams. CONDUSEF fee transparency rules shape consumer-facing digital wallet product design. The Zapopan innovation district hosts domestic payment processors building CoDi connectivity without proprietary data center investments.
Bajío Region
Agribusiness supply chains in Guanajuato and Querétaro adopt QR-enabled merchant acceptance for seasonal harvest payments. Banco de México's dual-factor authentication thresholds create friction for micro-transactions below regulatory floors. León's leather goods corridor sees street vendors maintaining multiple acquiring relationships to maximize consumer coverage.
Northern Border States
Cross-border remittance corridors through Tijuana and Ciudad Juárez generate demand for potential SPEI-CoDi linkage with US correspondent banking networks. CNBV licensing requirements for payment aggregators evolve under forthcoming open finance frameworks. Maquiladora payroll operations drive elastic capacity provisioning during biweekly settlement windows.
Mexico Real Time Payments Market Competitive Landscape
Universal banks and specialized payment processors split the market between integrated commercial banking workflows and standalone transaction infrastructure. The competitive structure tilts toward domestic institutions with regulatory proximity to Banco de México standard-setting. Two archetypes dominate: merchant-acquiring scale players embedding real-time settlement into treasury products, and technology-focused switch operators enabling regional bank CoDi access. Consolidation pressures intensify through API platform licensing deals and cloud-native infrastructure partnerships.
Within the acquiring-scale tier, BBVA México and Citibanamex anchor positions through embedded commercial banking relationships, while Prosa exemplifies the infrastructure-specialist archetype by anchoring transaction switching for institutions avoiding proprietary buildouts. ACI Worldwide Inc occupies a position representing fraud-scoring module competition for high-velocity merchant authorization demands.
| Leading Market Players |
|---|
| Banco Azteca |
| Mastercard Inc |
| BBVA México |
| Fiserv Inc |
| ACI Worldwide Inc |
| Citibanamex |
| Visa Inc |
| Prosa |
| Banco Santander México |
| Others |
Supply & Pricing Matrix
Single-source dependency on Banco de México's SPEI-CoDi rail determines both pricing tier spreads and supply chain shape, as merchant acquirers must price around central bank-mandated settlement finality while regional banks compete for switching infrastructure access without proprietary alternatives.
Pricing Analysis
After-sales revenue from API integration layers and fraud-scoring modules drives lifetime value for payment processors serving merchant acquirers. Transaction-based pricing dominates, with per-unit fees compressing as volume scales and cloud-native entrants undercut legacy on-premises deployments. Price differentiation rests on settlement speed tiers and ISO 20022 compliance certification, with micro-merchants in Mexico City corridor zones exhibiting highest price sensitivity and large enterprises in Monterrey industrial zones least sensitive due to treasury workflow integration demands. Cost compression in the standard tier is intensifying because hyperscaler infrastructure enables elastic capacity provisioning without data center capital.
Supply Chain Analysis
Contract-manufacturing concentration for payment switching infrastructure sits with domestic processors Prosa and BBVA México's technology divisions, supplemented by specialized systems integrators holding ISO 20022 message mapping expertise. Geographic supply concentration centers on Mexico for core banking integration services, with fraud-scoring modules and cloud orchestration tools drawing from US hyperscaler availability zones and specialized software vendors. Raw material dependencies include proprietary switching hardware, biometric authentication tokens, and QR code presentation terminals. Single-source vulnerability to Banco de México's regulatory chokepoints over settlement finality rules creates systemic exposure. Distribution runs through direct API licensing to regional banks and indirect channel partnerships with merchant acquirers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
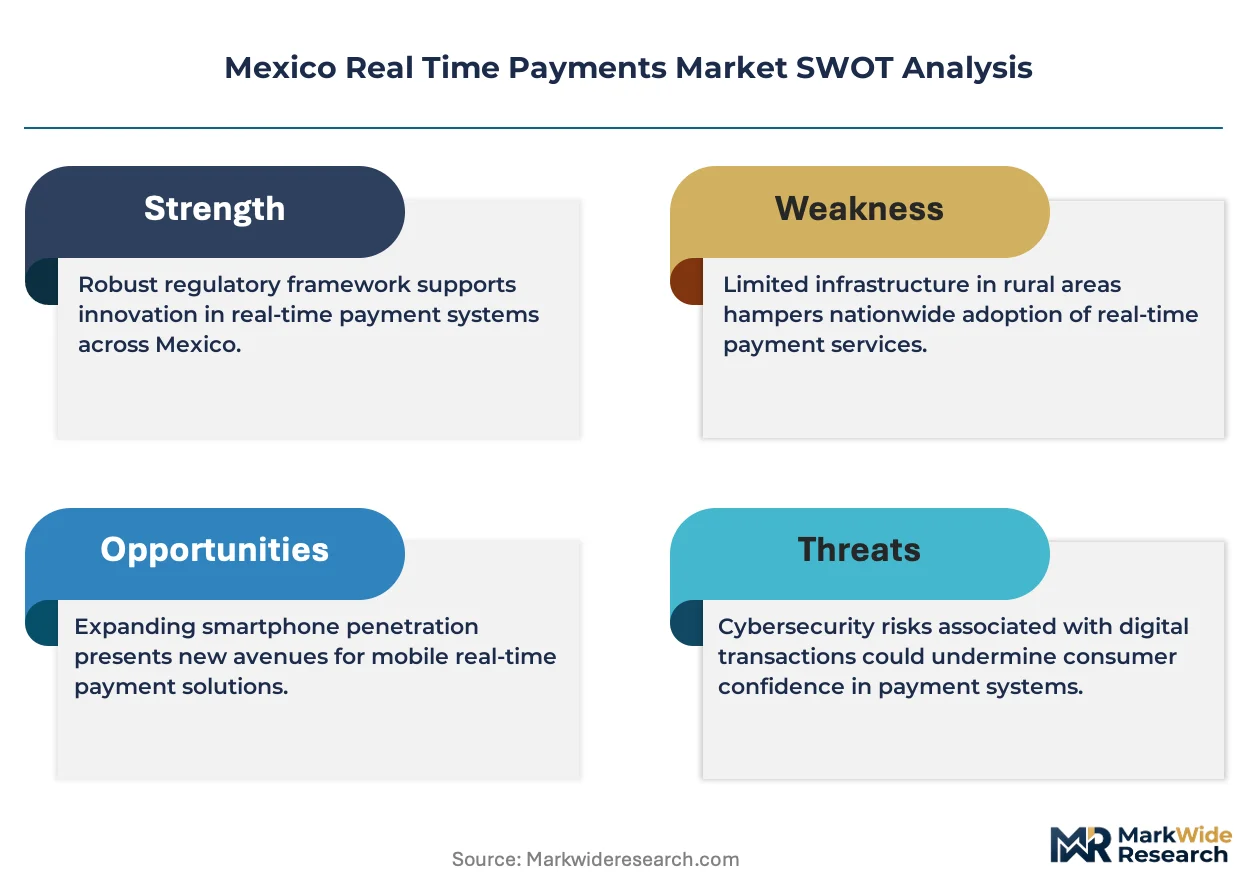
Incumbents face substitution defense against cash-handling inertia and informal sector parallel operations that threaten real-time payment volume capture.
For Market Incumbents: Pre-empt merchant defection to digital wallet aggregators by embedding real-time settlement deeper into commercial banking workflows, particularly for mid-market enterprises in Monterrey industrial zones. Consolidate switching infrastructure partnerships with regional banks in Guadalajara and Puebla to lock in CoDi connectivity volumes before cloud-native entrants capture share. Vertical integration into fraud-scoring module development reduces chargeback exposure and differentiates authorization latency performance.
For New Entrants and Emerging Players: Build out QR-enabled acceptance infrastructure for street vendors in Mexico City peripheral corridors and Bajío agribusiness supply chains, where merchant acquiring relationships remain fragmented and comparison-shopping behavior creates entry opportunity. Target the small business segment with simplified onboarding workflows that bypass legacy ISO 20022 integration complexity. A mobile-first go-to-market angle leveraging existing smartphone penetration among underbanked populations bypasses branch infrastructure requirements.
For Investors and Strategic Acquirers: Banco de México's potential cross-border corridor extension with US correspondent banking networks reshapes the acquisition landscape by unlocking remittance settlement compression economics. Long-term viability favors infrastructure-specialist archetypes with regulatory proximity to central bank standard-setting, particularly those anchoring transaction switching for regional bank consortia. Monitor CNBV licensing evolution for payment aggregators under open finance frameworks as the signal to watch for inflection in account-to-account payment initiation volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Switching Migration | Regional banks in Jalisco compress time-to-market from quarters to weeks through elastic infrastructure. |
| API Platform Licensing Expansion | Domestic processors embed real-time settlement into ERP-integrated corporate treasury workflows. |
| Fraud-Scoring Module Investment | Sub-second authorization demands force rearchitecture of risk engines without degrading approval rates. |
| QR Code Interoperability Buildout | Street vendors maintain multiple acceptance relationships to maximize consumer coverage in urban corridors. |
| Cross-Border Corridor Development | SPEI-CoDi linkage with US networks unlocks remittance settlement compression for migrant worker flows. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with payment technology executives, merchant acquiring operations leads, regional bank treasury managers, and Banco de México regulatory affairs specialists; and secondary validation through SPEI-CoDi transaction volume disclosures, CNBV operational resilience guidelines, CONDUSEF fee transparency rulings, and cloud infrastructure capex reports. Bottom-up segmentation modeling triangulated against top-down market sizing from central bank payment system statistics.
Forecast inputs considered transaction volume trajectories across P2P transfers, merchant payments, B2B disbursements, and bill payment categories, segmented by mobile banking, digital wallet, QR code, and API integration modalities. End-user splits across small businesses, large enterprises, retailers, and financial institutions were modeled across the projection horizon. CAGRs were derived from elasticity analysis of smartphone penetration curves and merchant adoption saturation patterns, with Banco de México's interoperability mandate timeline and CNBV licensing evolution serving as structural inputs.
Stress conditions across central bank policy shifts, hyperscaler infrastructure availability, and informal sector cash preference persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about CoDi rail expansion velocity and regulatory technology mandate enforcement. Quarterly review of merchant acquiring relationship fragmentation indices and cloud-native switching deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Canada POS Terminal Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
Europe Mobile Payment Market
Payments
Direct Carrier Billing Market
Payments
Latin America Mobile Payment Market
Payments
France Buy Now Pay Later Services Market
Payments
Global Telecom Billing Market
Payments
Global Smart Payment Systems Market
Payments
Spain Payment Gateway Market
Payments
Global Master Card Market
Payments
Convergent Billing Market
Payments
Vietnam Mobile Payments Market
Payments
Canada Mobile Payments Market
Payments
Mobile Money Market
Payments
Spain Payments Market
Payments
Italy Gift Cards Market