
 Africa Mobile Money Market | 2026-2036
Africa Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Mobile Money Market Intelligence
Multi-source platform partnerships is shifting how mobile money providers build agent networks across rural Africa. M-Pesa leverages its agent density in Kenya to sustain cross-border remittance corridors into Tanzania and Mozambique. MTN MoMo competes through interoperable wallets that span fourteen African markets. Orange Money anchors West African operations with regulatory licenses in Senegal, Mali, and Côte d'Ivoire.
Africa mobile money denotes digital financial services delivered through mobile devices, primarily using USSD sessions on basic feature phones or smartphone applications, enabling peer-to-peer transfers, merchant payments, and savings without traditional bank accounts. Wallet Services generate the highest transaction volumes, while Value-Added Services such as micro-insurance and credit scoring capture expanding margin pools. Consumer segments dominate user counts, but Small Enterprises represent the fastest-growing customer type as business-to-business payment digitization accelerates.
Kenya's Central Bank enforces tiered licensing under the National Payment System Act, while Ghana's Bank of Ghana applies capital adequacy rules through the Payment Systems and Services Act, and Nigeria's Central Bank mandates BVN-linked KYC for wallet holders. These frameworks shape product design by forcing providers to segment accounts by transaction limits and documentation depth. Stakeholders must monitor how interoperability mandates and open-banking directives alter competitive moats between telco-led and fintech-led platforms.
Market Dynamics
Interoperability mandates across East and West African monetary zones are compressing competitive moats between telco-led wallets and bank-led platforms, forcing providers to rebuild differentiation through agent network depth rather than captive user bases.
Growth Catalysts
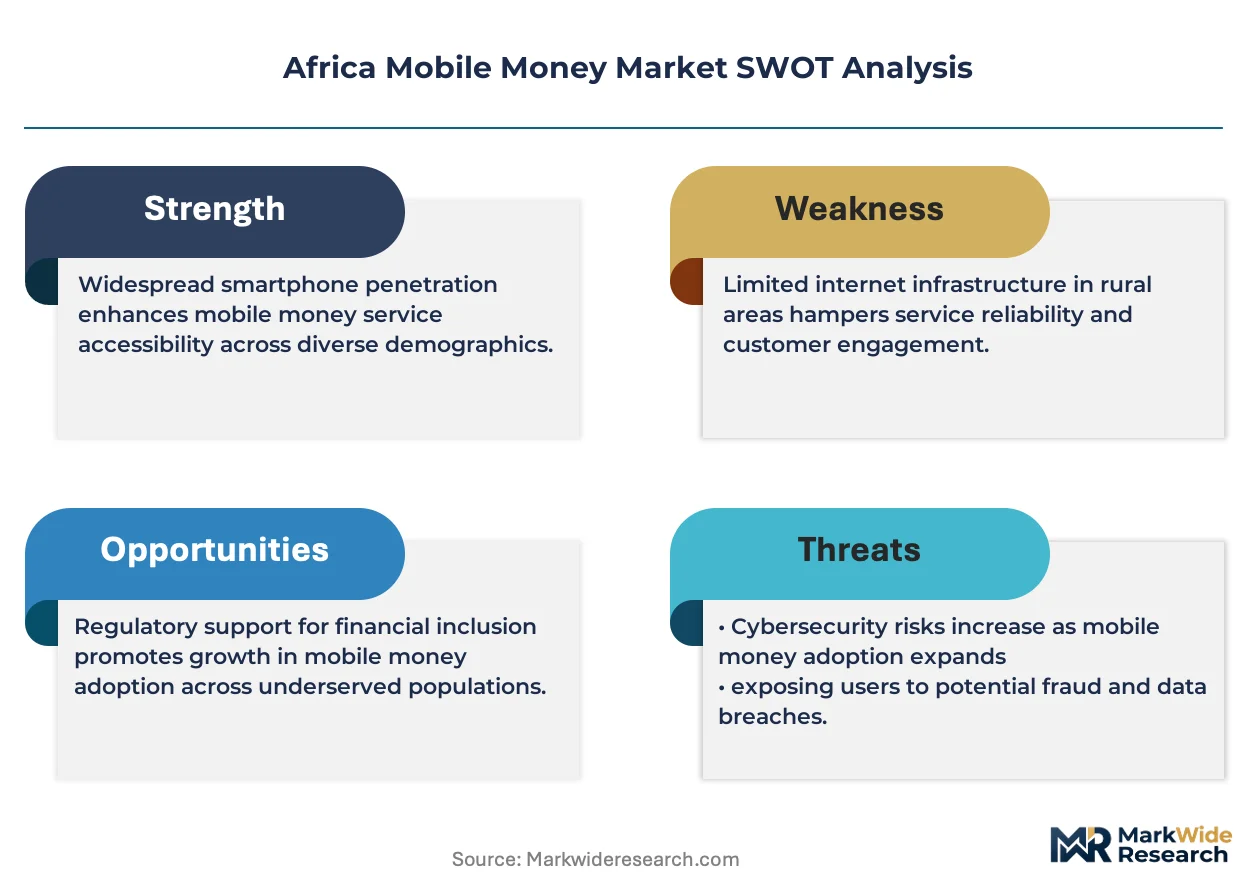
- Kenya's National Payment System Act:Tiered licensing frameworks legitimize non-bank wallet providers and expand permissible service categories for agent networks.
- Small enterprise B2B digitization:Supplier payment corridors in Kenya and Nigeria are converting cash-based business transactions into wallet-settled flows.
- Cross-border remittance corridors:Regional economic communities are harmonizing settlement rails between Tanzania, Uganda, and Mozambique.
Market Restraints
- Agent liquidity management costs:Float provisioning for rural agents consumes working capital and compresses unit economics in low-density territories.
- Ghana's capital adequacy rules:The Payment Systems and Services Act imposes reserve requirements that elevate barrier-to-entry for fintech entrants.
- Feature phone dependency:USSD session reliability varies across carrier networks, limiting service consistency in infrastructure-constrained zones.
Strategic Opportunities
- Nigeria's BVN-linked KYC infrastructure:Biometric verification networks enable tiered account opening without physical branch visits.
- Value-Added Services expansion:Micro-insurance and credit scoring attach to core wallet functions in Senegal and Côte d'Ivoire.
- Open banking API convergence:Account aggregation protocols are unifying telco and bank data layers for unified financial portraits.
Industry Challenges
- Interoperability protocol integration:Technical reconciliation between proprietary wallet switches and national payment switches demands specialized engineering capacity.
- Agent training and retention:High churn in rural agent networks disrupts cash-in/cash-out availability and erodes consumer trust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Mobile Money Market |
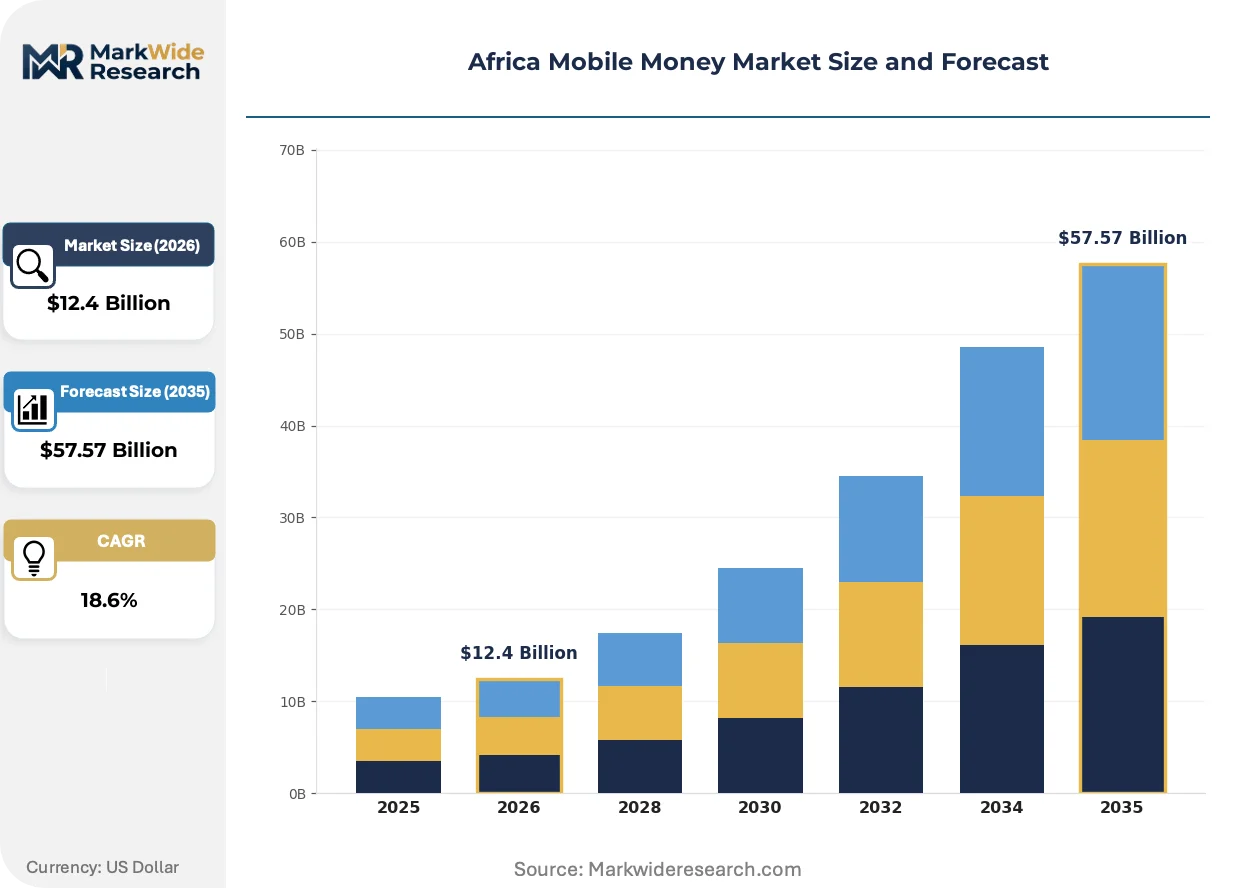
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $57.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wallet Services, Remittances, Bill Payments, Value-Added Services Customer Type: Consumers, Small Enterprises, Corporates, Government Agencies Technology: USSD, Smartphone Apps, SMS, NFC End User: Retail Customers, Merchants, Financial Institutions, NGOs |
| Companies Covered | Orange Money, OPay, M-Pesa, Viettel Money, Wave Money, Airtel Money, TeleBirr, Mukuru, MTN MoMo, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Mobile Money Market Strategic Shifts & Innovations
Platform architectures are pivoting from closed-loop systems toward open API ecosystems, enabling third-party fintechs to embed payment capabilities without building proprietary rails.
Super-app consolidation is unifying previously discrete financial services into single-interface platforms. Providers in Kenya and Nigeria are integrating savings, credit, and insurance modules atop core transfer functions. Small enterprises now execute supplier payments, payroll disbursements, and tax remittances through unified dashboards rather than fragmented point solutions.
Ghana's Payment Systems and Services Act is mandating interoperability between mobile money operators and traditional banks. The Bank of Ghana requires wallet-to-bank settlement within specified time windows. Tier-2 providers are responding by licensing direct connections to the national switch rather than routing through incumbent telco aggregators.
Merchant acquisition models are rotating from agent-assisted onboarding toward self-service digital enrollment. Restaurants and retail shops in Lagos and Nairobi are activating QR-code acceptance without field sales visits. This channel shift compresses onboarding costs and accelerates merchant density in urban corridors where smartphone penetration supports app-based setup workflows.
Africa Mobile Money Market Segmentation
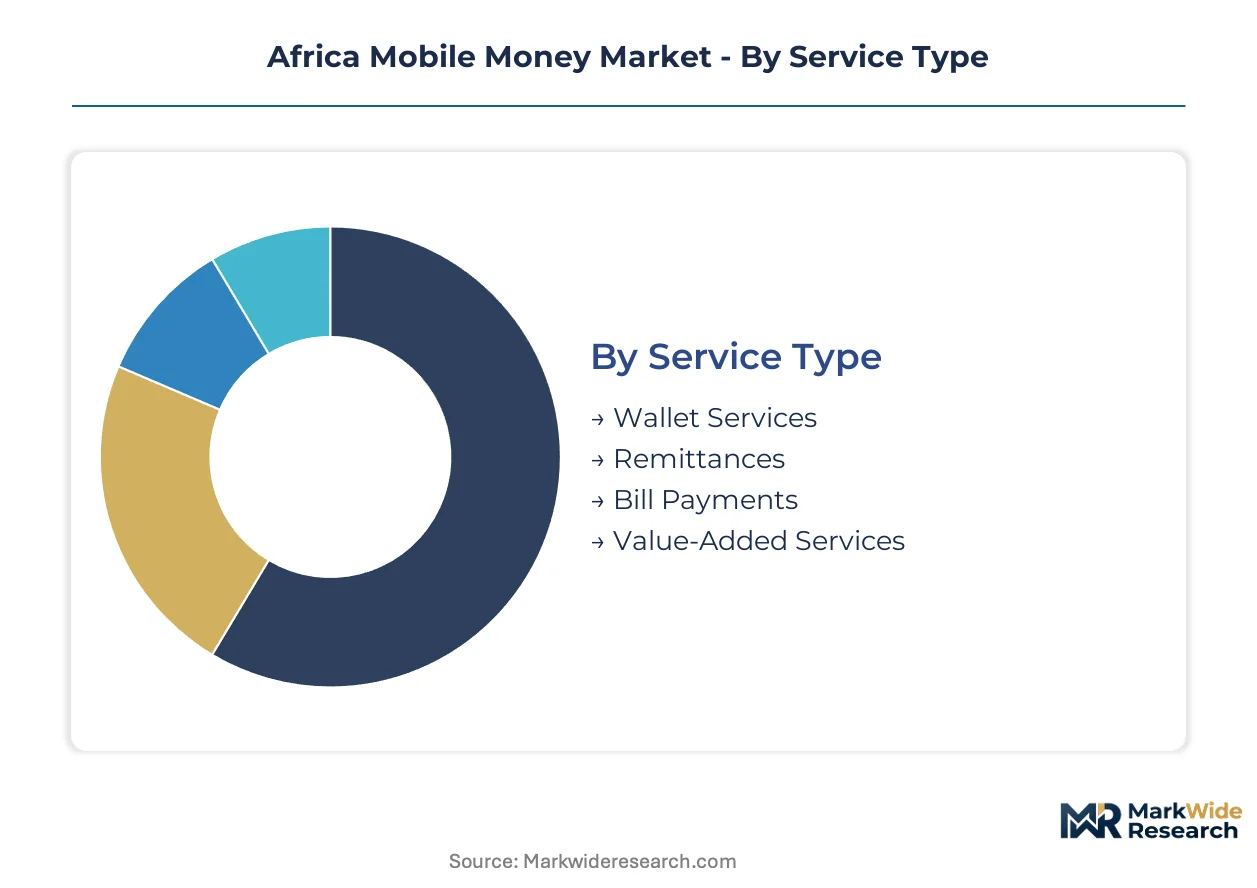
Segmentation reveals how mobile money providers allocate capital across divergent technical infrastructures and customer economics. Wallet services and consumer segments dominate transaction volumes, while enterprise digitization and value-added services reshape margin structures.
Service Type:
Providers upgrade service portfolios to capture recurring revenue beyond basic transfers, with replacement cycles accelerating as interoperability mandates commoditize core payments.
- Wallet Services:Peer-to-peer transfers and stored-value accounts function through USSD sessions on feature phones or smartphone interfaces. Demand concentrates in Kenya and Tanzania where agent network density enables reliable cash-in/cash-out access, though interoperability protocols are compressing per-transaction fees.
- Value-Added Services:Micro-insurance, credit scoring, and savings products attach to core wallet infrastructure with higher margin profiles than pure payments. Ghana's Payment Systems and Services Act licensing framework enables non-bank providers to offer these products directly, accelerating provider investment in data analytics capabilities.
- Remittances:Cross-border corridors link diaspora senders to recipients across East and West African monetary zones.
- Bill Payments:Utility and tax settlements convert recurring cash transactions to digital rails.
Wallet Services sits at the top of the volume ranking, with Value-Added Services climbing the fastest.
Customer Type:
Cost-to-serve economics vary dramatically across customer tiers, with small enterprises demanding complex workflow integration that justifies higher acquisition spend.
- Small Enterprises:Businesses in Kenya and Nigeria digitize supplier payments, payroll disbursements, and tax remittances through unified dashboards. These customers generate 3-5x higher revenue per user than consumers but require dedicated onboarding resources and API integration support.
- Consumers:Individual users execute peer-to-peer transfers, merchant payments, and airtime purchases primarily through USSD interfaces. Rural penetration in Mozambique and Uganda depends on agent liquidity management, while urban adoption shifts toward smartphone apps.
- Corporates:Large employers disburse salaries and manage treasury functions through bulk payment APIs.
- Government Agencies:Social benefit distribution and tax collection digitize last-mile fiscal operations.
Consumers anchor absolute transaction counts, though Small Enterprises expand most quickly as B2B payment digitization accelerates.
Technology:
Application requirements split across infrastructure maturity levels, with USSD dominance in rural zones and smartphone migration in urban corridors.
- USSD:Unstructured Supplementary Service Data sessions operate on basic feature phones without internet connectivity. Nigeria's BVN-linked KYC infrastructure enables tiered account opening through these channels, sustaining relevance despite smartphone growth.
- Smartphone Apps:iOS and Android interfaces support richer functionality including biometric authentication, QR-code merchant payments, and integrated financial dashboards. Lagos and Nairobi merchant acquisition increasingly relies on self-service digital enrollment rather than agent-assisted onboarding.
- SMS:Text-based alerts and confirmation messages provide asynchronous communication layers.
- NFC:Contactless proximity payments remain nascent, constrained by terminal deployment costs and feature phone prevalence.
USSD commands the widest installed base, while Smartphone Apps gain share fastest among merchant-facing use cases.
End User:
Margin concentration follows the divergence between retail transaction volume and institutional integration complexity.
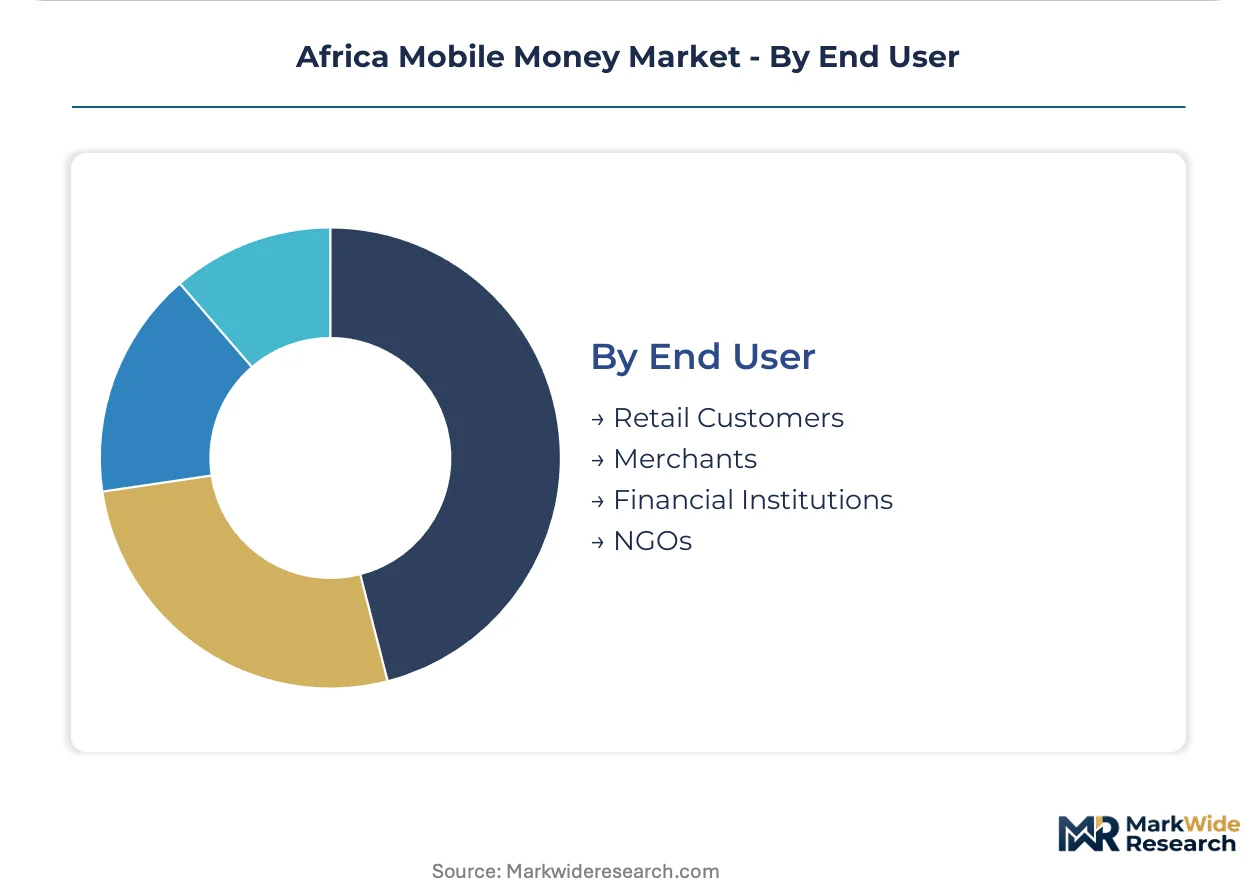
- Merchants:Retail shops, restaurants, and service providers accept wallet payments through QR codes or USSD verification. Urban corridors in Senegal and Côte d'Ivoire show accelerating density as self-service onboarding compresses acquisition costs.
- Retail Customers:Individual consumers execute daily purchases, transfers, and savings transactions. East Africa's interoperability frameworks enable seamless wallet-to-wallet transfers across provider boundaries, reducing switching costs.
- Financial Institutions:Banks and microfinance institutions leverage mobile rails for last-mile distribution and deposit mobilization.
- NGOs:Humanitarian organizations disburse cash transfers through agent networks in infrastructure-constrained territories.
Retail Customers generate the highest absolute flow volumes, with Merchants posting the steepest expansion trajectory as digitization penetrates informal commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting mobile money investment toward jurisdictions with tiered licensing frameworks that lower compliance costs for non-bank providers. Kenya's National Payment System Act and Ghana's Payment Systems and Services Act exemplify how progressive regulation attracts capital, while fragmented rules in larger markets create friction.
Kenya
Agent network density and interoperability maturity sustain transaction volume leadership. The Central Bank of Kenya enforces tiered licensing under the National Payment System Act, legitimizing non-bank wallet providers and expanding permissible service categories. Nairobi anchors cross-border remittance corridors into Tanzania and Uganda, with M-Pesa leveraging domestic agent density to capture regional flows.
Ghana
Capital adequacy rules under the Payment Systems and Services Act are elevating barriers for fintech entrants while enabling incumbent expansion. The Bank of Ghana mandates interoperability between mobile money operators and traditional banks, forcing wallet-to-bank settlement within specified windows. Accra concentrates provider headquarters and regulatory engagement, with Tier-2 operators licensing direct national switch connections.
Nigeria
Small enterprise B2B digitization is converting cash-based supplier payments into wallet-settled flows. The Central Bank of Nigeria mandates BVN-linked KYC for wallet holders, enabling tiered account opening without physical branch visits. Lagos merchant acquisition is shifting toward self-service digital enrollment, compressing onboarding costs for QR-code acceptance.
Senegal
Value-added services expansion is attaching micro-insurance and credit scoring to core wallet functions. The Central Bank of West African States harmonizes settlement rails across the monetary zone, enabling cross-border interoperability. Dakar serves as Orange Money's regional headquarters, coordinating West African operations across Mali and Côte d'Ivoire.
Uganda
Regional economic community harmonization is integrating settlement rails with Kenyan and Tanzanian corridors. The Bank of Uganda applies risk-based supervision to mobile money operators, balancing innovation with consumer protection. Kampala concentrates agent network development, with interoperability protocols reducing switching costs for cross-border recipients.
Africa Mobile Money Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue value-added service integration and open-banking convergence. Telco-led wallets dominate transaction volumes through captive subscriber bases and agent network depth, while fintech-led platforms compete on API flexibility and merchant-facing tools. Three archetypes define competitive positioning: vertically integrated telco operators, bank-affiliated digital wallets, and standalone fintech aggregators. Dominant competitive moves include strategic partnerships for interoperability access and portfolio diversification into credit and insurance products.
Within the telco-integrated tier, M-Pesa and MTN MoMo exemplify network-effects-driven positioning, while Orange Money anchors West African regulatory licensing. Airtel Money occupies a position spanning multiple markets with interoperable infrastructure. OPay represents the fintech-native archetype, leveraging Nigeria's BVN-linked KYC rails for rapid customer acquisition without legacy telco subscriber bases.
| Leading Market Players |
|---|
| Orange Money |
| OPay |
| M-Pesa |
| Viettel Money |
| Wave Money |
| Airtel Money |
| TeleBirr |
| Mukuru |
| MTN MoMo |
| Others |
Cost & Logistics Intelligence
Agent commission benchmarks across East Africa cascade through mobile money economics, compressing margins for rural float provisioning while elevating returns in urban merchant-acquisition corridors where density supports scale.
Pricing Analysis
Input-cost pass-through from agent liquidity provisioning shapes tiered pricing structures across wallet services. Per-transaction fees stratify by account tier and KYC depth, with Ghana's Payment Systems and Services Act mandating cost disclosures that sharpen price transparency. Pricing pressure intensifies as interoperability protocols commoditize core transfers, forcing providers to attach higher-margin value-added services. Small enterprises show lowest price sensitivity due to workflow integration benefits, while rural consumers face highest sensitivity to cash-in/cash-out spreads.
Supply Chain Analysis
Regional distribution centers in Nairobi, Lagos, and Accra anchor hub-and-spoke agent network deployment, with last-mile liquidity resting on rural agent float pools. Kenya, Nigeria, and Ghana concentrate provider headquarters and regulatory engagement, while component dependencies span USSD gateway providers, biometric verification vendors, and national switch operators. Supply chain risk centers on single-source agent management platform concentration. Distribution runs through telco-owned captive channels and licensed third-party aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with Ghana's Payment Systems and Services Act and Kenya's National Payment System Act progressively legitimizing non-bank wallet expansion into credit and insurance products.
For Market Incumbents: Anchor differentiation through agent network depth rather than proprietary rails, as interoperability mandates erode captive user advantages. Deepen data analytics capabilities to attach micro-insurance and credit scoring products before fintech entrants capture margin pools. Defend against bank-led platform convergence by licensing direct national switch connections that bypass telco aggregation layers. For New Entrants and Emerging Players: Nigeria's BVN-linked KYC infrastructure opens a window for rapid customer acquisition without legacy branch networks. Target small enterprise B2B payment digitization in Lagos and Nairobi corridors where workflow integration justifies premium pricing. Pursue white-label API partnerships with merchant-facing platforms seeking embedded finance capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with fintech-native platforms possessing regulatory licenses in multiple monetary zones. Long-term viability favors providers bridging telco distribution with bank-grade compliance infrastructure. Watch interoperability mandate timing across West African economic communities as inflection signal for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Value-Added Service Licensing | Ghana's Payment Systems and Services Act enables direct micro-insurance provision, expanding margin pools beyond core transfers. |
| Agent Network Density Expansion | Rural float provisioning in Mozambique and Uganda captures unbanked populations before interoperability erodes localization advantages. |
| Cross-Border Corridor Integration | East African Community harmonization links Kenyan, Tanzanian, and Ugandan settlement rails for regional remittance scale. |
| Open Banking API Development | Account aggregation protocols unify telco and bank data layers for unified financial portraits in Nigerian and Ghanaian markets. |
| Merchant Self-Service Onboarding | QR-code activation without field sales visits compresses acquisition costs in Lagos and Nairobi urban corridors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mobile money platform executives, central bank regulatory leads, agent network operators, and small enterprise finance officers with secondary validation. Regulatory filings from the Bank of Ghana, Central Bank of Kenya, and Central Bank of Nigeria anchored policy trajectory assessment alongside industry association reports and telecommunications operator disclosures. Bottom-up transaction volume modeling triangulated against top-down macroeconomic indicators.
Comparable-period anchoring linked historical wallet adoption curves to forward projection parameters across the analysis window. Segmentation dimensions spanned service type, customer tier, technology interface, and end-user application, with CAGRs derived from regression analysis of penetration rates and revenue-per-user trajectories. Agent network density metrics and interoperability protocol implementation timelines fed directly into geographic growth assumptions.
Revisions become necessary when central banks alter licensing frameworks, interoperability mandates accelerate, or agent liquidity crises disrupt cash-in/cash-out availability. Forecasts reflect documented assumptions around regulatory stability and infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Vietnam Mobile Payments Market
Payments
Italy POS Terminals Market
Payments
United States Payments Market
Payments
Czech Republic POS Terminals Market
Payments
Sweden Mobile Payments Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Global Smart Payment Systems Market
Payments
Mexico Payments Market
Payments
Indonesia Prepaid Cards Market
Payments
Greece POS Terminals Market
Payments
Telecom Cloud Billing Market
Payments
Denmark POS Terminals Market
Payments
Portugal POS Terminals Market
Payments
Subscription Billing Management Market
Payments
India Real Time Payments Market
Payments
Italy Payments Market