
 Medical Payment Fraud Detection Market | 2026-2036
Medical Payment Fraud Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Payment Fraud Detection Market Outlook
Legacy rules-based detection is rebalancing toward neural network architectures that slash false-positive rates in claims adjudication. LexisNexis Risk Solutions leverages its identity graph databases to cross-reference provider credentials against sanction lists in milliseconds. IBM anchors its position through Watson Health infrastructure that integrates with existing electronic data interchange pipelines. FICO competes by applying its proprietary Falcon fraud scoring engines originally developed for banking to medical claims patterns.
Medical payment fraud detection encompasses algorithmic systems that analyze billing codes, provider histories, and patient records to identify anomalous reimbursement requests before funds disburse. These platforms process structured and unstructured data through supervised learning models trained on labeled fraud cases, with throughput requirements exceeding ten thousand claims per hour for large payers. Fraud analytics solutions currently command the deepest margin pools as insurers prioritize retrospective and prospective claim review automation. Cloud-based deployments are expanding fastest among mid-tier regional payers seeking elastic compute for seasonal enrollment spikes. Machine learning segments attract disproportionate R&D allocation as vendors race to reduce the eighteen-month model retraining cycles that plague first-generation implementations.
FDA oversight of clinical decision support intersects with CMS program integrity rules to mandate audit trails for algorithmic claim denials. The HIPAA Security Rule and state-level insurance fraud statutes create layered compliance obligations that shape procurement specifications for detection platforms. Stakeholders must weigh vendor explainability capabilities against the opacity of ensemble models that regulators increasingly scrutinize for disparate impact in coverage determinations.
Market Dynamics
Real-time claim validation mandates from CMS are compressing adjudication windows from weeks to milliseconds, forcing payers to retire batch-processed fraud screening for streaming analytics architectures that score claims at ingestion.
Growth Catalysts
- CMS Interoperability Mandates:The 2021 CMS Final Rule on program integrity requires automated prior authorization and real-time claim validation, compelling carriers to upgrade legacy detection infrastructure.
- Graph Neural Networks:Advanced architectures now map provider-patient-billing relationships across billions of nodes, surfacing collusion patterns invisible to rules-based systems.
- Recovery Audit Contractor Expansion:RAC program intensity in the United States creates direct financial pressure for prospective detection rather than retrospective clawback.
Market Restraints
- Model Retraining Cycles:Eighteen-month refresh intervals for supervised learning models leave detection systems vulnerable to evolving fraud schemes during gap periods.
- Cloud Concentration Risk:Elastic compute for seasonal enrollment spikes depends heavily on three hyperscale providers, creating single-point-of-failure exposure during Q4 enrollment surges.
- Explainability Trade-offs:Ensemble methods with highest accuracy resist interpretability demands from state insurance commissioners auditing algorithmic claim denials.
Strategic Opportunities
- Medicaid Expansion States:Newly eligible populations in states adopting expansion create demand for fraud detection calibrated to managed care organization billing patterns.
- Pharmacy Benefit Integration:Convergence of medical and pharmacy claims data enables cross-domain anomaly detection for compound medication fraud.
- Value-Based Contracting:CMS ACO REACH and similar models reward detection systems that identify upcoding before capitation payments lock in inflated baselines.
Industry Challenges
- Legacy EDI Pipeline Integration:X12 837 claim formats and proprietary payer data models require expensive middleware development to feed modern detection engines.
- Clinical NLP Talent Scarcity:Shortage of engineers trained on both medical ontologies (SNOMED CT, ICD-10) and transformer architectures slows deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Payment Fraud Detection Market |
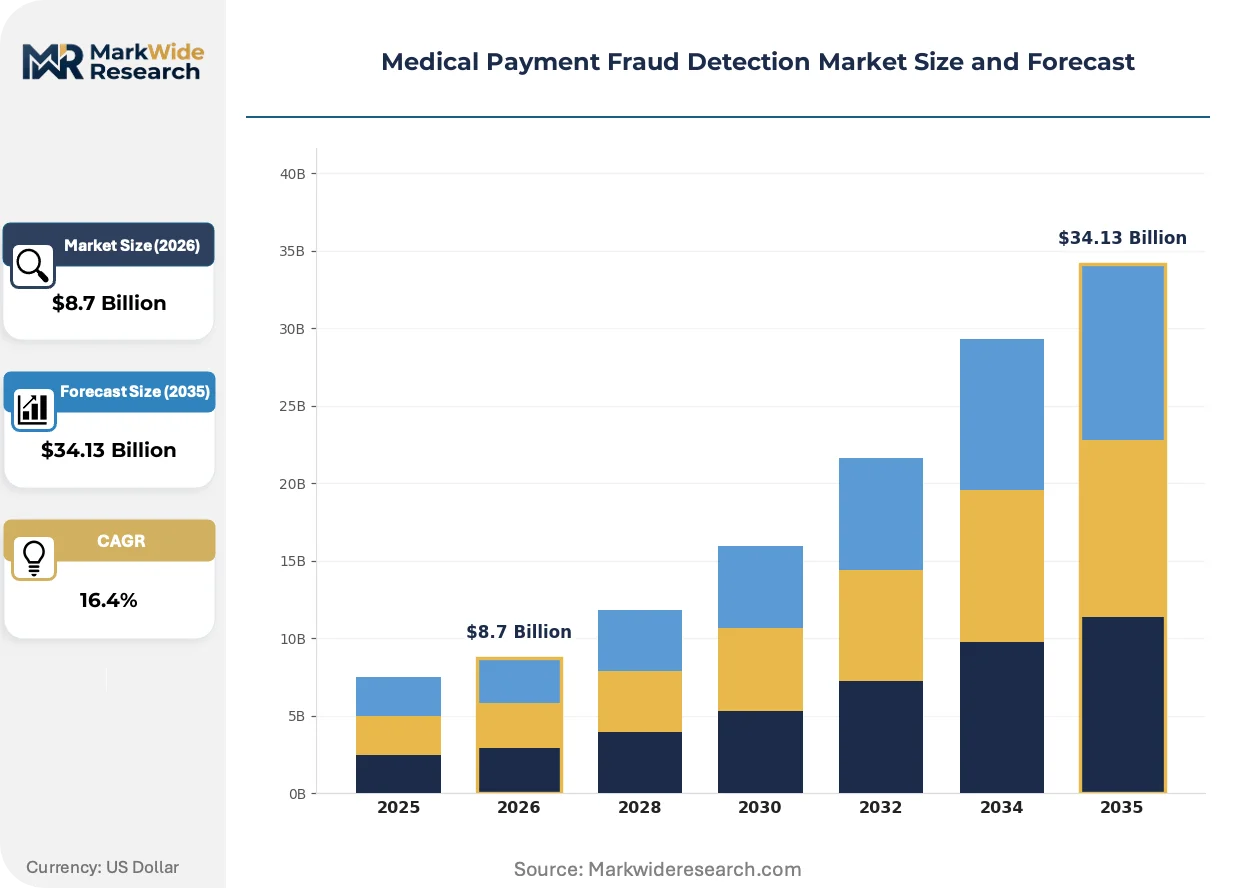
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Fraud Analytics, Claim Review, Predictive Modeling, Identity Verification Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Healthcare Providers, Insurance Companies, Regulatory Bodies, Payment Processors Technology: Machine Learning, Artificial Intelligence, Data Mining, Rule-Based Systems |
| Companies Covered | Alivia Analytics, LexisNexis Risk Solutions, NICE Actimize, OptumInsight, IBM, FICO, ClarisHealth, OSP, Accertify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Payment Fraud Detection Market Strategic Shifts
Neural architectures are displacing deterministic rules engines across the fraud detection stack, with vendor R&D concentrating on throughput optimization and explainability tooling that satisfies state audit requirements.
Transformer-based models for clinical narrative analysis are electrifying detection accuracy by extracting intent signals from unstructured physician notes that structured billing codes obscure. Medicare Advantage plans with highest claim volumes are deploying these systems first, compressing the advantage window for regional payers still dependent on keyword matching. The technology is electrifying competitive positioning by enabling same-day fraud identification that supports pre-payment denial workflows.
The EU AI Act's risk classification for health insurance decision systems is mandating conformity assessments for any algorithmic claim adjudication affecting coverage determinations. Vendors must now document training data provenance and model performance across demographic subgroups before European deployment. German statutory health insurers and French mutuelles are responding by demanding built-in bias detection dashboards as standard procurement requirements.
Consolidation of fraud detection procurement under enterprise analytics contracts is displacing point-solution purchasing that dominated prior authorization and payment integrity silos. Large national carriers are unbundling retrospective review vendors and consolidating spend with platforms offering prospective detection across the entire claims lifecycle. This pattern is most visible among Blues plans restructuring payment integrity operations under unified data science centers.
Medical Payment Fraud Detection Market Segmentation
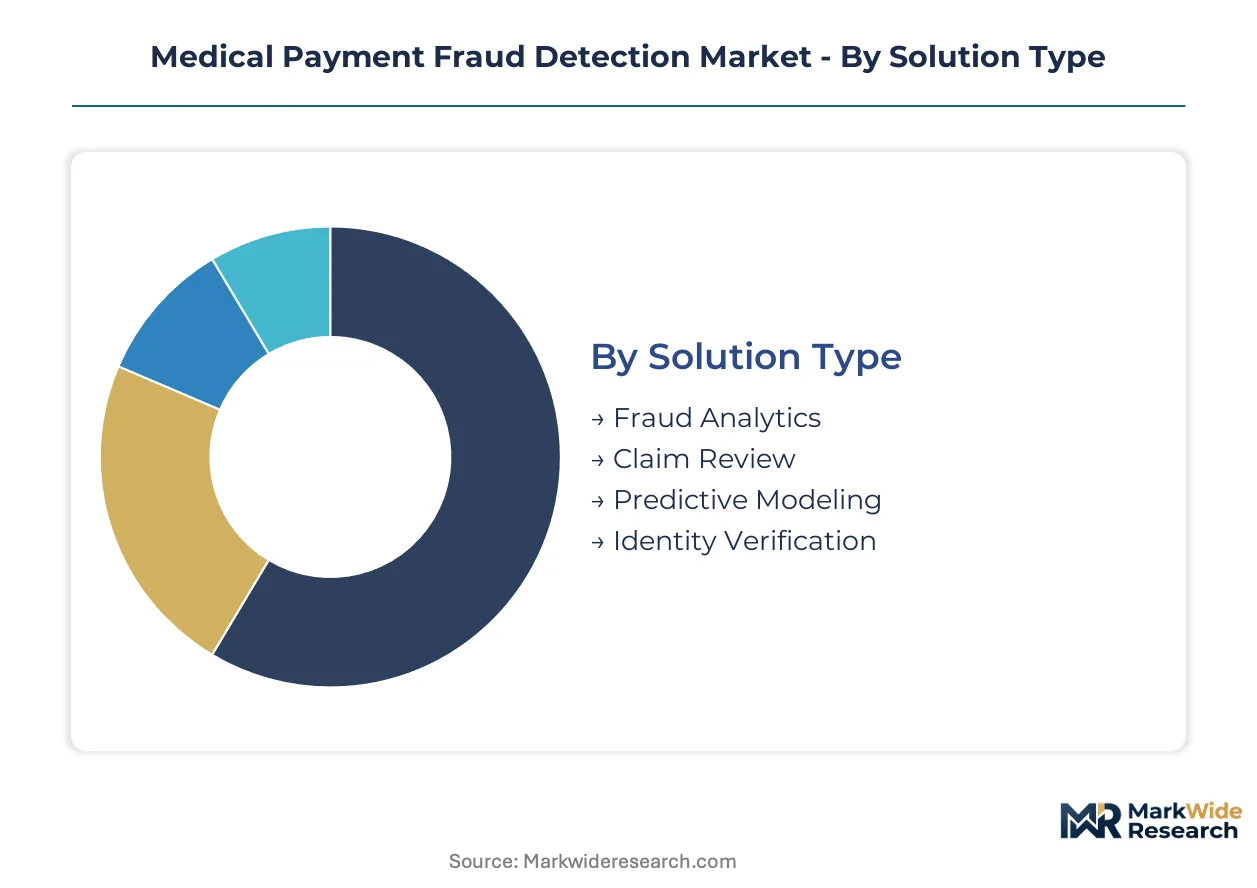
Segmentation in medical payment fraud detection reveals divergent technology appetites across payer tiers. Solution architecture choices directly determine whether carriers achieve sub-second claim scoring or remain trapped in batch-processed workflows. Deployment preferences split sharply between national insurers demanding elastic scale and regional plans prioritizing data sovereignty.
Solution Type:
Volume concentration sits with retrospective detection tools, while premium margins flow to prospective platforms that intercept fraudulent claims before payment.
- Fraud Analytics:Platforms aggregate historical claims data, provider networks, and sanction databases to surface statistical anomalies through supervised learning pipelines. Medicare Advantage carriers in Florida and Texas deploy these systems to identify upcoding clusters before capitation baselines lock.
- Claim Review:Manual and semi-automated adjudication workflows subject flagged claims to clinical coder examination. Demand concentrates among Medicaid managed care organizations in expansion states facing intensified Recovery Audit Contractor scrutiny.
- Predictive Modeling:Neural architectures forecast fraud probability scores at claim ingestion using real-time feature engineering.
- Identity Verification:Biometric and document verification systems validate patient and provider credentials against government databases.
Today's leader: Fraud Analytics. Tomorrow's challenger: Predictive Modeling.
Deployment Model:
Customer type dictates infrastructure choice — national carriers pursue elasticity while mid-tier plans lock in fixed-cost predictability.
- Cloud-Based:Hyperscale compute enables seasonal enrollment surge capacity without capital expenditure. Blues plans restructuring payment integrity operations favor these deployments for unified data science center consolidation.
- On-Premises:Dedicated hardware installations satisfy HIPAA Security Rule audit requirements for claims data never leaving carrier-controlled facilities. State insurance commissioners in jurisdictions with strict data residency mandates drive procurement here.
- Hybrid:Sensitive patient records remain on-premises while compute-intensive model training leverages cloud burst capacity.
- SaaS:Subscription pricing lowers barrier to entry for regional payers lacking internal data science teams.
Cloud deployments capture the steepest expansion trajectory as CMS interoperability mandates compress implementation timelines.
End User:
Application context separates high-volume transactional screening from specialized investigative workflows.
- Healthcare Providers:Hospitals and physician groups deploy detection tools to preempt audit exposure and protect revenue cycle integrity. Large health systems in California and New York implement these platforms to defend against RAC clawback demands.
- Insurance Companies:Carriers represent the dominant procurement segment, integrating detection engines directly into claims adjudication pipelines. Prior authorization reform pressures drive replacement of legacy rules engines with neural architectures.
- Regulatory Bodies:State Medicaid fraud control units and federal program integrity contractors utilize detection platforms for targeted investigations.
- Payment Processors:Clearinghouses and financial intermediaries embed fraud screening to satisfy contractual liability provisions with payer clients.
Insurance companies anchor current procurement volume. Regulatory bodies present the fastest-growing demand profile as CMS expands program integrity funding.
Technology:
Maturity curves diverge sharply — established methods defend installed base while emerging architectures capture greenfield deployments.
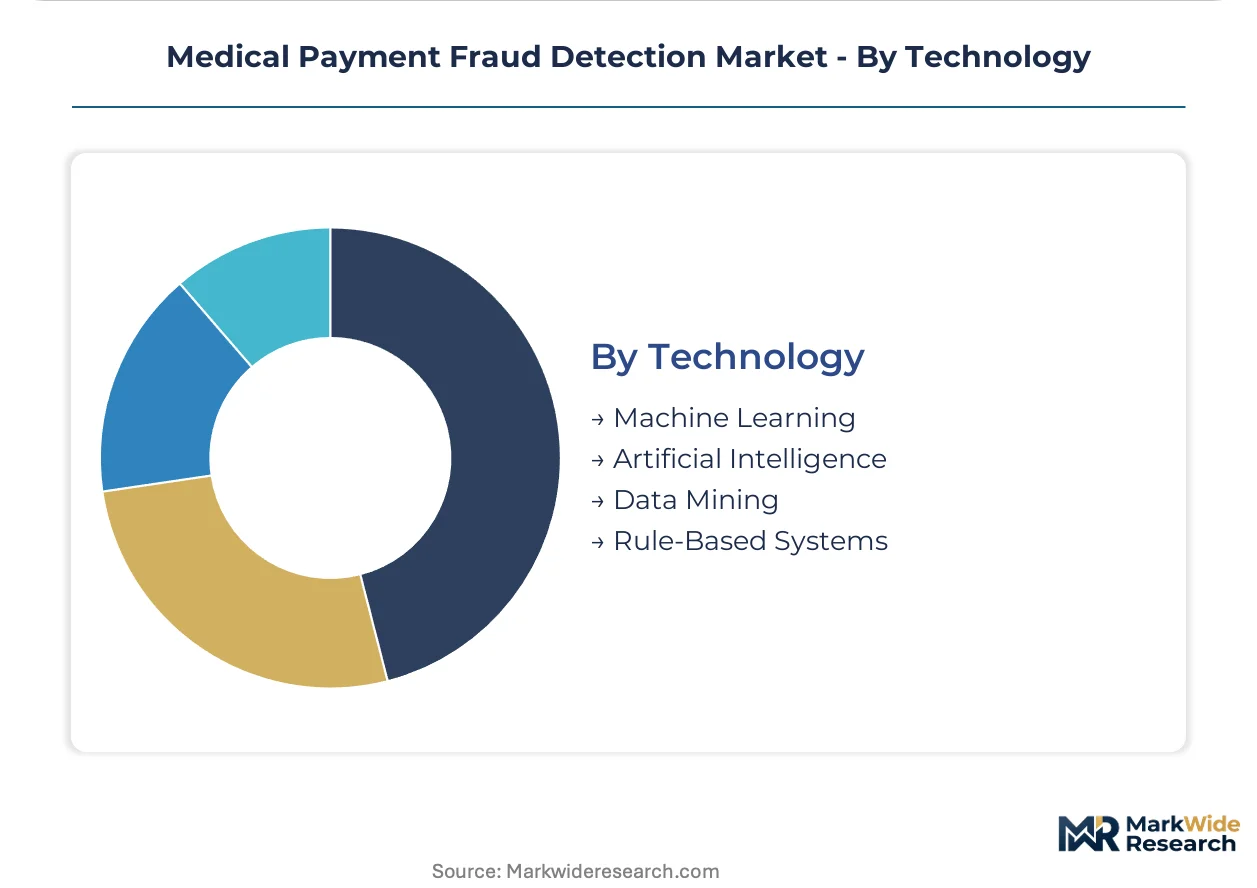
- Machine Learning:Ensemble methods and gradient-boosted trees process structured claims data at throughput exceeding ten thousand claims hourly. Graph neural networks mapping provider-patient-billing relationships now displace first-generation implementations at national carriers.
- Artificial Intelligence:Transformer-based clinical NLP extracts intent signals from unstructured physician notes that structured billing codes obscure. Medicare Advantage plans with highest claim volumes deploy these systems to compress fraud identification from weeks to same-day resolution.
- Data Mining:Pattern recognition across historical claims repositories identifies statistical outliers for investigator prioritization.
- Rule-Based Systems:Deterministic if-then logic engines maintain relevance for regulatory audit trails requiring explicit decision pathways.
Machine learning dominates current revenue. Artificial intelligence commands the premium expansion trajectory as explainability tooling matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States healthcare fraud detection cluster anchors procurement volume, driven by Recovery Audit Contractor programs and CMS interoperability mandates that compress claim validation windows from weeks to milliseconds.
United States
Medicare Advantage carriers in Florida and Texas deploy graph neural networks to identify upcoding clusters before capitation baselines lock. The CMS Final Rule on program integrity mandates real-time claim validation protocols for all federal programs. Greater Boston health systems implement detection platforms to defend against RAC clawback demands while maintaining revenue cycle integrity.
Germany
German statutory health insurers demand built-in bias detection dashboards as standard procurement requirements under evolving EU AI Act conformity assessments. The EU AI Act's risk classification for health insurance decision systems mandates documentation of training data provenance across demographic subgroups. Frankfurt-based mutuelles are consolidating fraud detection procurement under enterprise analytics contracts that span the entire claims lifecycle.
United Kingdom
NHS Digital procurement frameworks prioritize explainability tooling that satisfies state audit requirements for algorithmic claim denials. The UK Information Commissioner's Office scrutinizes ensemble models for disparate impact in coverage determinations. London-based payment integrity contractors integrate detection engines directly into NHS claims adjudication pipelines to intercept fraudulent reimbursement requests.
France
French mutuelles respond to EU AI Act mandates by demanding conformity assessments for any algorithmic claim adjudication affecting coverage determinations. ANSM and CNIL guidance shapes procurement specifications for detection platforms handling sensitive patient records. Paris-region insurers are deploying transformer-based clinical NLP systems to extract intent signals from unstructured physician notes that structured billing codes obscure.
India
Indian health insurance carriers face escalating pressure from the Insurance Regulatory and Development Authority of India to automate fraud detection across expanding coverage pools. The Digital India initiative accelerates cloud-based deployments among mid-tier regional payers seeking elastic compute for seasonal enrollment spikes. Maharashtra-based insurers implement hybrid architectures that keep sensitive patient records on-premises while leveraging cloud burst capacity for model training.
Medical Payment Fraud Detection Market Competitive Environment
Global majors compete with regional champions across technology licensing and data asset depth, creating a tiered structure where scale-driven platforms battle specialized fraud analytics boutiques. The vendor base organizes around three strategic archetypes: identity graph specialists leveraging cross-industry data assets, healthcare-native platforms with embedded clinical ontologies, and financial services incumbents repurposing banking fraud engines for medical claims. Consolidation of fraud detection procurement under enterprise analytics contracts is displacing point-solution purchasing, while M&A activity concentrates around clinical NLP capabilities and cloud-native architectures.
Within the identity-centric tier, LexisNexis Risk Solutions and IBM exemplify archetypes built on cross-referencing provider credentials against sanction databases in milliseconds. FICO occupies a position representing financial services incumbents applying proprietary fraud scoring engines originally developed for banking to medical claims patterns. These three anchors demonstrate how competitive positioning depends on data asset breadth, throughput architecture, and explainability tooling maturity.
| Leading Market Players |
|---|
| Alivia Analytics |
| LexisNexis Risk Solutions |
| NICE Actimize |
| OptumInsight |
| IBM |
| FICO |
| ClarisHealth |
| OSP |
| Accertify |
| Others |
Value Chain & Pricing Dynamics
Large national insurance carriers concentrating procurement under enterprise analytics contracts dictate subscription-based SaaS pricing tiers that scale with claim volume throughput and model complexity. This buyer concentration enables vendors to command premium pricing for real-time scoring architectures while mid-tier regional payers negotiate standardized per-seat licensing for retrospective detection tools.
Pricing Analysis
Cloud infrastructure costs and specialized clinical NLP engineering talent feed directly into vendor pricing structures, with hyperscale compute surcharges passed through as seasonal elasticity premiums. Pricing stratifies across enterprise, professional, and essential tiers differentiated by throughput ceiling, explainability dashboard depth, and dedicated model retraining frequency. Cost compression in the essential tier intensifies as open-source machine learning frameworks commoditize baseline fraud scoring. Medicaid managed care organizations exhibit highest price sensitivity due to fixed administrative cost ratios, while Medicare Advantage carriers prioritize sub-second latency over license cost.
Supply Chain Analysis
Model retraining cycles and algorithmic audit requirements create reverse-logistics flows where deprecated detection engines return to vendors for architecture upgrades or regulatory recertification. Core development concentrates in the United States, India, and Israel, with clinical ontology engineering anchored in Boston and Tel Aviv health tech clusters. GPU semiconductor supply draws from Taiwan and South Korea fabrication facilities, creating single-source vulnerability during Q4 enrollment surge demand. Distribution runs through direct enterprise sales teams supplemented by systems integrators serving Blues plans and regional payer networks.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical payment fraud detection rests on compressing eighteen-month model retraining cycles through automated MLOps pipelines, while premium-tier demand shifts toward transformer-based clinical NLP with embedded explainability tooling.
For Market Incumbents: Anchor market position through exclusive data licensing agreements with CMS and state Medicaid agencies that lock competitor access to labeled fraud case repositories. Defend against cloud-native entrants by embedding detection engines directly into existing EDI pipeline infrastructure, raising switching costs for national carriers. Prioritize R&D allocation toward graph neural network architectures that surface collusion patterns invisible to rules-based substitutes. For New Entrants and Emerging Players: Cloud marketplace distribution routes offer lowest-friction customer acquisition for mid-tier regional payers lacking internal data science teams. White-space opportunity concentrates in Medicaid expansion states requiring fraud detection calibrated to managed care organization billing patterns. Target pharmacy benefit integration as the most penetrable cross-domain application, positioning compound medication fraud detection as the initial wedge offering. For Investors and Strategic Acquirers: Enterprise analytics platforms with healthcare vertical focus represent the most active acquirer category in this space, consolidating point-solution vendors into unified payment integrity suites. Long-term viability favors targets with proprietary clinical NLP capabilities and pre-negotiated cloud burst capacity agreements. Monitor CMS program integrity funding allocations and prior authorization reform implementation velocity as inflection indicators for detection platform procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Scoring Architecture Deployment | Sub-second claim validation satisfies CMS interoperability mandates for Medicare Advantage carriers. |
| Clinical NLP Capability Acquisition | Transformer-based narrative analysis extracts intent signals from unstructured physician notes that billing codes obscure. |
| Graph Neural Network R&D Investment | Provider-patient-billing relationship mapping surfaces collusion patterns invisible to first-generation implementations. |
| Explainability Dashboard Development | Built-in bias detection satisfies EU AI Act conformity assessments and state insurance commissioner audit requirements. |
| Hybrid Cloud Infrastructure Partnership | Elastic compute burst capacity addresses seasonal enrollment spikes without capital expenditure commitment. |
Study Parameters
Bottom-up payer procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with health insurance carrier CIOs, payment integrity directors, clinical data scientists, and CMS program integrity contractors combine with secondary validation from hospital procurement databases, GPO contracts, and CMS Medicare cost reports. SEC filings of publicly traded analytics vendors, hyperscaler healthcare vertical revenue disclosures, and state Medicaid fraud control unit budget appropriations provide triangulation anchors.
Historical trendline analysis of fraud detection platform deployments across Medicare Advantage, Medicaid managed care, and commercial payer segments establishes baseline adoption curves. Modeled dimensions span solution type, deployment architecture, end-user category, and technology maturity tier, with additional segmentation by regional regulatory cluster reflecting EU AI Act, HIPAA Security Rule, and CMS interoperability mandate compliance requirements. CAGRs derive from weighted average of vendor guidance, carrier procurement pipeline visibility, and elasticity-adjusted cloud infrastructure spend patterns.
The model assumes a particular technology adoption path; alternative pathways for transformer-based clinical NLP or quantum-resistant encryption would alter the outlook. Forecasts reflect assumptions regarding CMS prior authorization reform implementation velocity and EU AI Act enforcement consistency. Practitioners should monitor Recovery Audit Contractor program expansion announcements and state Medicaid fraud control unit staffing levels for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Sweden POS Terminals Market
Payments
Global Payment Processor Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Malaysia Payments Market
Payments
North America POS Terminal Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
United States Clearing Houses and Settlements Market
Payments
Telecom Cloud Billing Market
Payments
Japan POS Terminals Market
Payments
Mexico Digital Wallet Market
Payments
UK Virtual Cards Market
Payments
Germany Mobile Payments Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
E-Wallet Market
Payments
United Kingdom Mobile Payments Market