
 UAE Card Payments Market | 2026-2036
UAE Card Payments Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Card Payments Market Insights
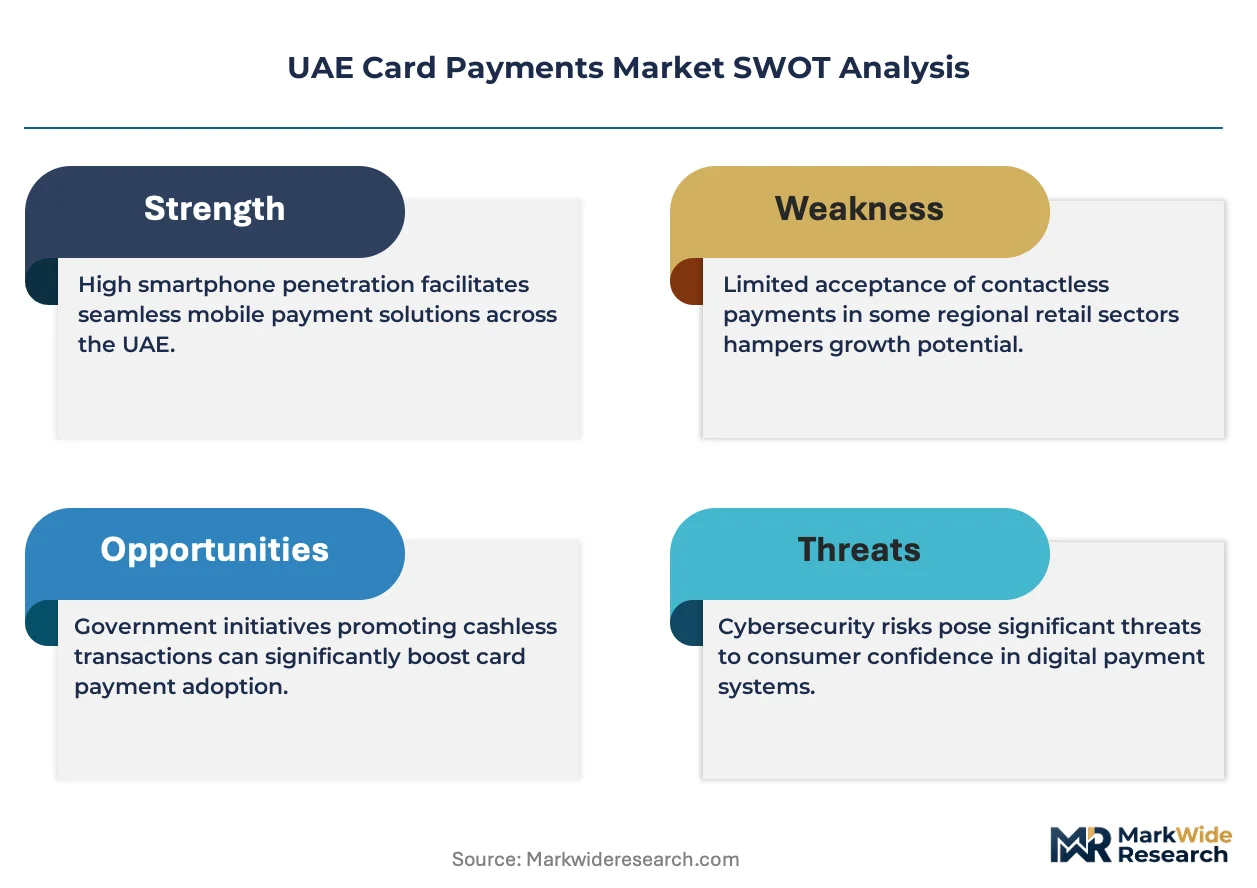
Software-defined loyalty and subscription bundling is expanding as a distinct revenue layer atop physical card issuance. Emirates NBD leverages its ecosystem of lifestyle partnerships to sustain premium cardholder retention. First Abu Dhabi Bank PJSC anchors corporate card portfolios through treasury-linked working capital tools. Mashreq Bank differentiates via digital-first onboarding that compresses time-to-activation for SME segments.
Card payments encompass electronically initiated fund transfers between cardholders and merchants through authorization, clearing, and settlement protocols operating on EMV chip standards and tokenized credential frameworks. The primary commercial purpose is to displace cash handling costs while capturing transaction data for risk scoring and customer analytics. Credit cards command the dominant share of issuer interchange revenue pools, while contactless cards are gaining fastest among transit and quick-service retail acceptance channels. Prepaid instruments occupy a niche serving unbanked labor populations and corporate expense control programs.
The UAE Central Bank governs licensing and capital adequacy for payment service providers, while SAMA-aligned cybersecurity standards shape infrastructure investment thresholds. Visa and Mastercard network rules further constrain product design through compliance mandates on dispute resolution and fraud liability allocation. Stakeholders must monitor how open banking APIs and real-time payment rails redefine the boundary between card-based and account-to-account transaction flows.
Market Dynamics
The UAE Central Bank's real-time payment interoperability mandate is compressing settlement windows and forcing card issuers to integrate account-to-account rails alongside traditional card networks.
Growth Catalysts
- Real-time payment interoperability:The UAE Central Bank's mandate for instant settlement infrastructure compels issuers to upgrade authorization systems. This regulatory pressure accelerates contactless terminal deployment across retail and hospitality sectors.
- Tourism transaction density:Dubai and Sharjah hospitality operators process visitor payment volumes that justify premium card tier investments. Issuers capture interchange revenue from high-value cross-border spending patterns.
- EMV tokenization standards:Network compliance requirements for credential vaulting reduce fraud liability exposure. Merchants adopt tap-to-pay terminals to minimize chargeback costs and checkout friction.
Market Restraints
- Network concentration risk:Visa and Mastercard routing rules dominate UAE issuer product design. Alternative scheme penetration remains structurally limited by merchant acceptance infrastructure.
- Cybersecurity capex intensity:SAMA-aligned infrastructure investment thresholds require continuous fraud detection system upgrades. Smaller issuers face disproportionate compliance cost burdens relative to transaction scale.
- Account-to-account substitution:Real-time payment rails displace low-value card transactions for peer-to-peer and bill payment use cases. Issuers must defend interchange revenue at the point of sale.
Strategic Opportunities
- SME digital onboarding white space:Compressed time-to-activation workflows capture merchant acquiring share from traditional branch-dependent competitors. Digital-first platforms reduce customer acquisition costs in Abu Dhabi and northern emirates.
- Subscription bundling convergence:Lifestyle partnership ecosystems integrate loyalty currencies across travel, dining, and entertainment verticals. Premium cardholders exhibit higher retention rates when reward redemption spans multiple merchant categories.
- Open banking API integration:Account aggregation services enable personalized financial management tools atop card transaction data. Issuers differentiate through data-driven spending insights rather than commodity payment rails.
Industry Challenges
- Legacy core banking integration:Real-time payment connectivity requires middleware development between card management systems and instant settlement infrastructure. Project timelines extend due to vendor dependency and testing protocols.
- Specialized fraud analytics talent scarcity:Machine learning model development for transaction scoring demands data science capabilities concentrated among global technology vendors. Local issuers compete for limited UAE-based expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Card Payments Market |
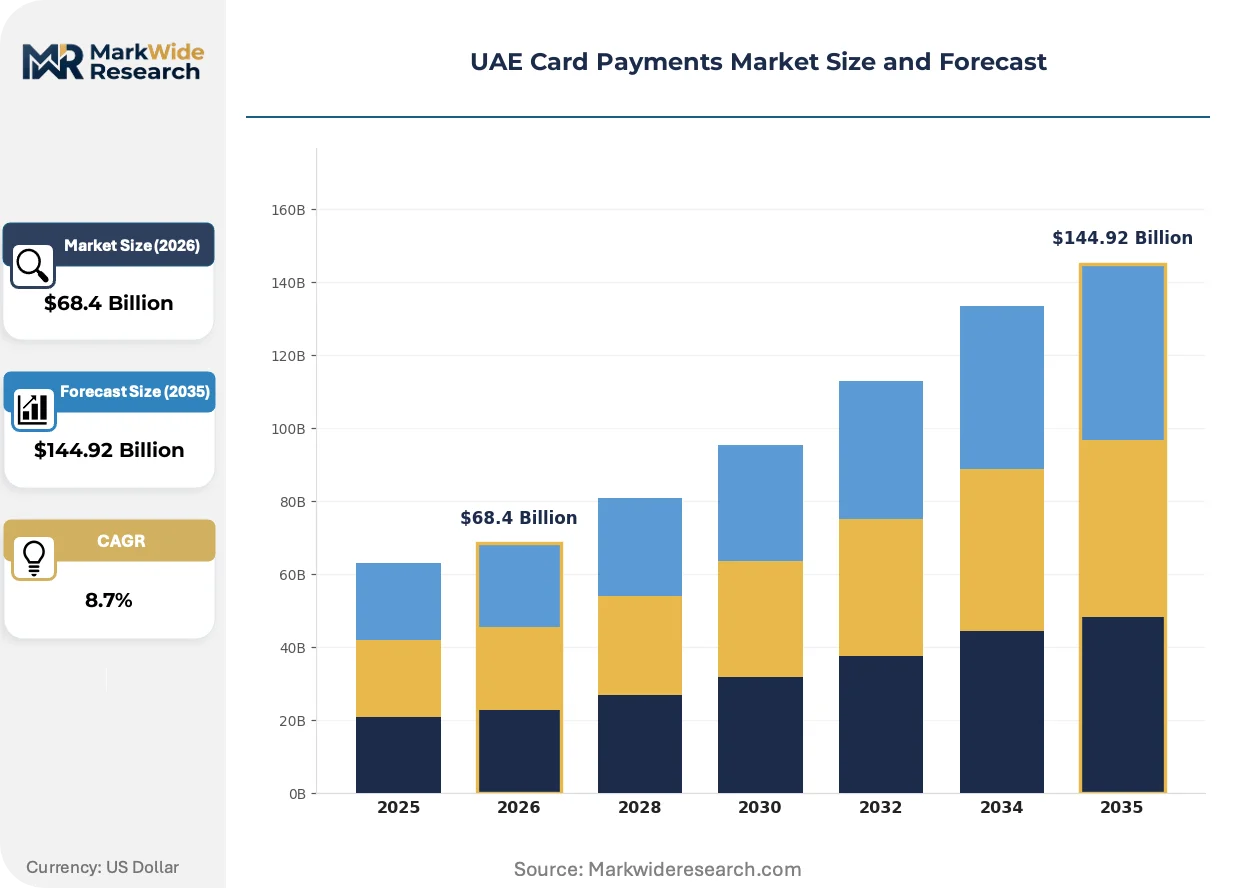
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Cards, Debit Cards, Prepaid Cards, Contactless Cards End User: Consumers, Businesses, Government, Non-Profit Organizations Transaction Value: Low Value, Medium Value, High Value, Premium Transactions Acceptance Channel: In-Store, Online, Mobile, ATMs |
| Companies Covered | Emirates NBD, Abu Dhabi Commercial Bank, National Bank of Ras Al-Khaimah, Road & Transport Authority, Mashreq Bank, CitiBank UAE, First Abu Dhabi Bank PJSC, Union National Bank, HSBC Bank Middle East, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Card Payments Market Trends and Innovations
Software-defined card programs are unifying issuance, loyalty, and merchant acquiring into single-platform architectures. This convergence compresses vendor stacks and enables subscription-based revenue models detached from physical plastic economics.
Biometric authentication at the point of sale is unifying identity verification with payment authorization. Dubai International Airport and major mall operators deploy facial recognition-linked wallets for visitor transactions. This technology is compressing checkout steps from three taps to passive authentication, reducing abandonment in high-throughput retail environments.
The UAE Central Bank's open finance framework is mandating standardized API access for customer-permissioned data sharing. Issuers must expose transaction histories to licensed third-party providers. Corporate treasury segments face the most significant operational adaptation as working capital tools integrate external account data for cash positioning.
Visitor spending patterns are rotating demand toward multi-currency digital wallets with dynamic conversion. Hospitality merchants in Dubai and Abu Dhabi configure terminals to accept wallet-based credentials from source markets including China, India, and Russia. This channel shift displaces traditional magnetic stripe acceptance and reduces foreign exchange margin capture by acquirers.
UAE Card Payments Market Segmentation
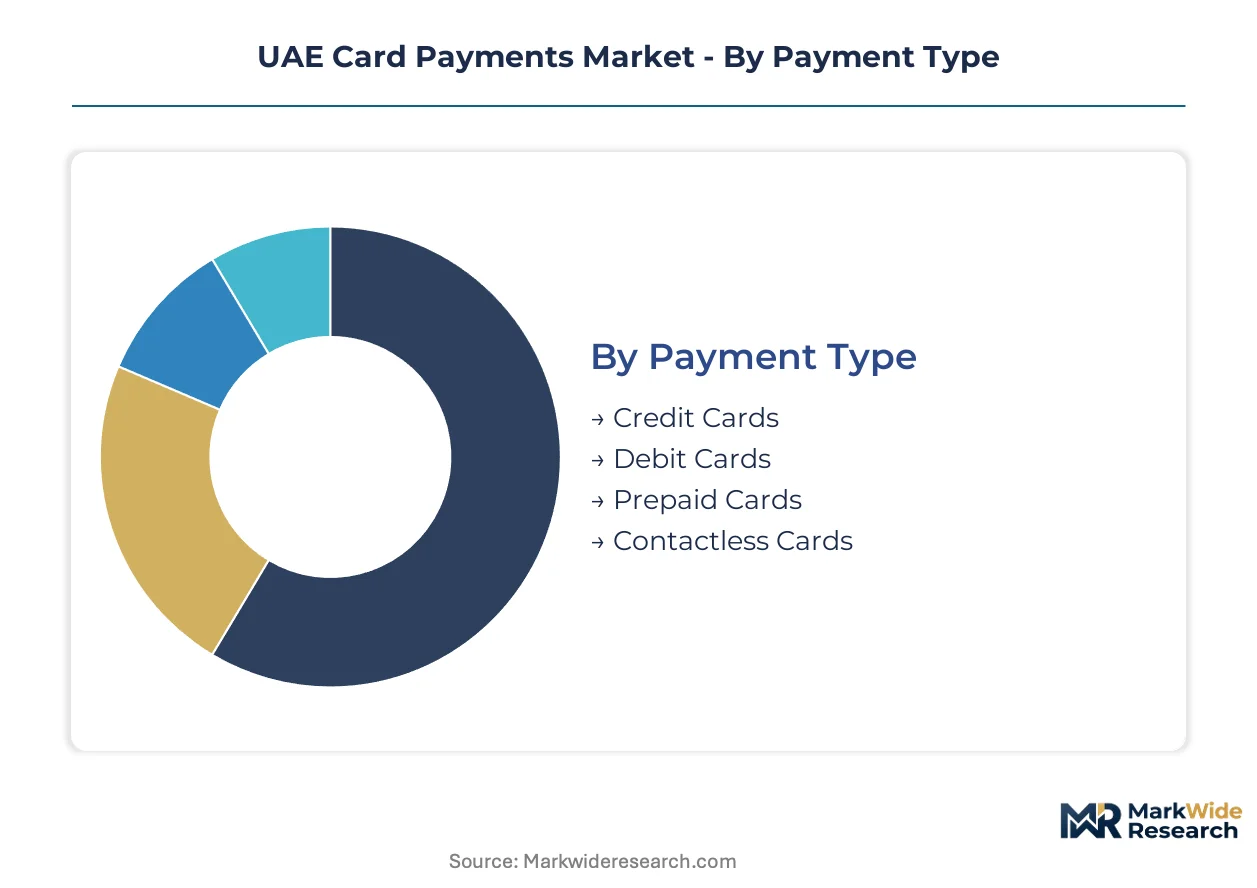
Payment type and transaction value splits determine issuer revenue architecture and infrastructure investment priorities across the Emirates. End-user concentration shapes product design, while acceptance channel preferences dictate terminal deployment strategies for merchant acquirers.
Payment Type:
Credit instruments dominate interchange revenue pools, while prepaid and contactless variants capture distinct customer acquisition and retention economics.
- Credit Cards:Revolving credit facilities with tiered interest structures and reward programs anchor issuer profitability through interchange fees and interest income. Dubai and Abu Dhabi hospitality merchants drive premium tier issuance for visitor cross-border spending.
- Debit Cards:Direct account-linked instruments with real-time authorization against demand deposits serve everyday transaction needs. Sharjah retail corridors and northern emirates branches concentrate mass-market debit deployment for domestic purchasing.
- Prepaid Cards:Stored-value instruments with fixed loading limits serve unbanked labor populations and corporate expense control programs.
- Contactless Cards:Near-field communication-enabled credentials with tap-to-pay functionality accelerate transit and quick-service retail throughput.
Mature deployment sits with credit and debit products. Newer deployment is concentrated in contactless-enabled form factors.
End User:
Consumer volume sustains retail economics, while commercial and institutional segments demand specialized authorization workflows and reporting integration.
- Consumers:Individual cardholders with personal credit or debit facilities represent the foundational transaction base. Dubai mall operators and hospitality venues configure acceptance infrastructure for visitor spending patterns.
- Businesses:Corporate card programs with centralized expense management and treasury integration support working capital optimization. Abu Dhabi government-linked entities and free zone companies drive commercial portfolio growth.
- Government:Public sector procurement cards with pre-approved vendor networks and audit trail requirements enforce expenditure control.
- Non-Profit Organizations:Restricted-purpose instruments with donor-imposed spending limits and transparent fund flow documentation serve charitable disbursement needs.
Consumer segments generate transaction density. Commercial deployment is climbing the fastest among free zone enterprises.
Transaction Value:
Value band stratification determines authorization risk scoring, interchange rate tiers, and fraud detection sensitivity thresholds.
- Low Value:Transactions below defined thresholds with simplified authentication protocols accelerate checkout throughput. Quick-service retail and transit operators in Dubai Metro and Sharjah bus networks optimize for micro-payment velocity.
- Medium Value:Mid-range purchases with standard EMV chip authentication and dynamic currency conversion support everyday commerce. Abu Dhabi retail clusters and northern emirates supermarkets concentrate medium-value terminal deployment.
- High Value:Elevated transaction amounts with stepped-up verification requirements and manual review triggers protect against authorized push fraud. Luxury retail in Dubai Mall and hospitality venues drive high-value authorization infrastructure.
- Premium Transactions:Ultra-high-value purchases with concierge verification, dedicated relationship management, and bespoke reward redemption anchor ultra-affluent cardholder retention.
Medium-value bands sustain merchant acquirer economics. Premium transaction deployment is expanding most quickly among private banking segments.
Acceptance Channel:
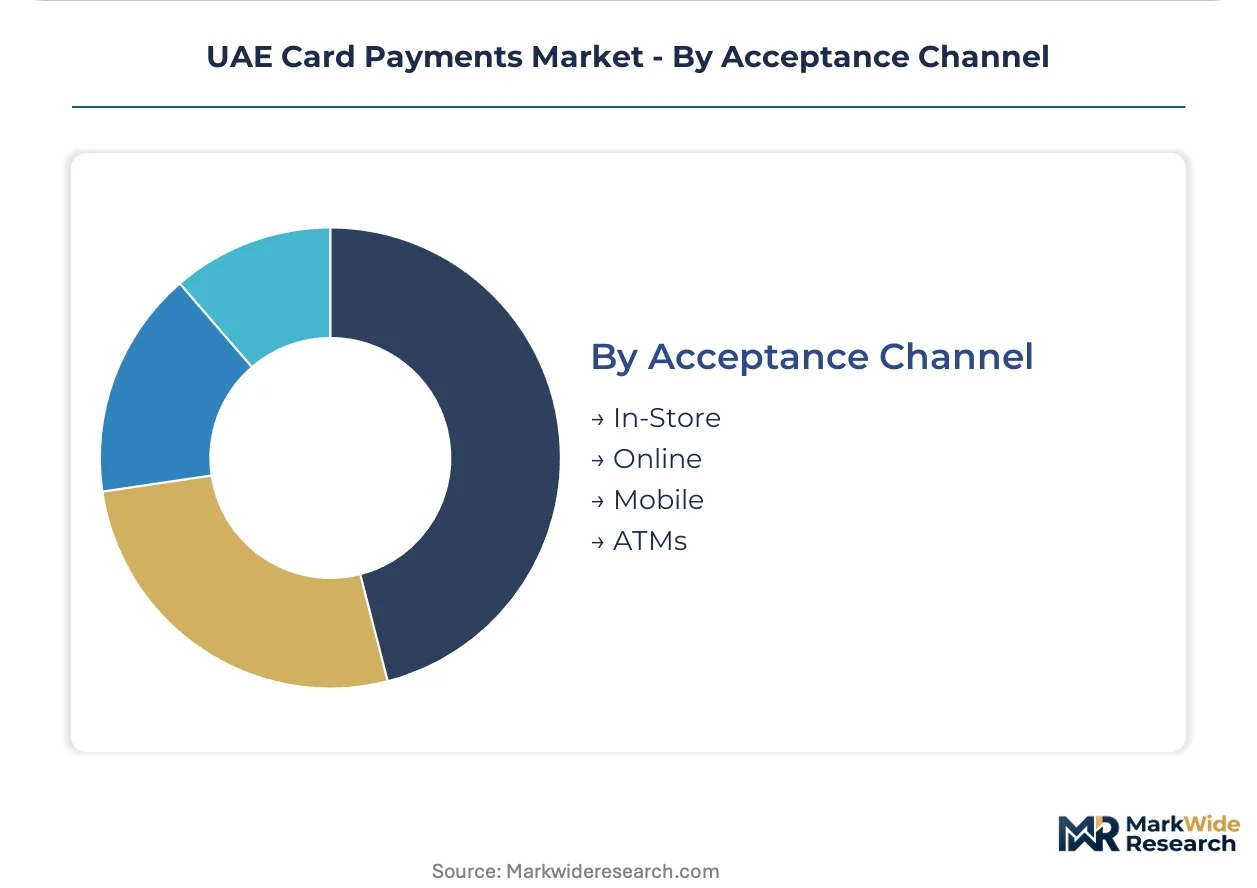
Channel mix shapes terminal hardware requirements, fraud liability allocation, and settlement timing expectations for merchant contracts.
- In-Store:Physical point-of-sale terminals with EMV chip and contactless acceptance handle face-to-face commerce. Dubai and Abu Dhabi retail corridors concentrate in-store infrastructure investment for visitor and resident purchasing.
- Online:E-commerce gateways with 3-D Secure authentication and tokenized credential vaulting support remote card-not-present transactions. UAE Central Bank cybersecurity mandates drive online fraud system upgrades.
- Mobile:Smartphone-based wallets with biometric authentication and host card emulation enable software-defined payment initiation. Hospitality and tourism operators prioritize mobile acceptance for Chinese and Indian visitor wallet compatibility.
- ATMs:Automated teller machines with cash dispensing, balance inquiry, and fund transfer functions serve self-service banking needs.
In-store and ATM channels represent mature infrastructure. Mobile acceptance deployment is gaining share fastest among hospitality merchants targeting visitor wallet preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors the Emirates' card payment infrastructure through its hospitality and retail corridors. The emirate's merchant acquiring density concentrates in mall operators and tourism venues. Abu Dhabi follows with corporate treasury demand from government-linked entities and free zone enterprises.
Dubai
Visitor transaction volumes from Chinese and Indian tourists drive premium card tier issuance among hospitality merchants. The UAE Central Bank's real-time payment interoperability mandate compresses settlement windows for Dubai Mall operators and airport retailers. Dubai International Airport deploys biometric-linked wallets for passenger payment authentication.
Abu Dhabi
Corporate card portfolios expand through treasury-linked working capital tools serving free zone companies. MOHAP-aligned cybersecurity standards shape infrastructure investment for government procurement card programs. Al Maryah Island financial district concentrates commercial banking relationships and premium cardholder acquisition.
Sharjah
Mass-market debit deployment targets resident purchasing in retail corridors and transit networks. The emirate's bus operators optimize contactless terminal deployment for micro-payment velocity. Sharjah's northern positioning captures spillover tourism traffic from Dubai with wallet-compatible acceptance infrastructure.
Northern Emirates
SME digital onboarding white space exists among branch-dependent merchant populations in Ajman, Fujairah, and Ras Al-Khaimah. Compressed time-to-activation workflows reduce customer acquisition costs for acquirers expanding beyond Dubai-Abu Dhabi corridors. Ras Al-Khaimah's developing tourism infrastructure drives incremental terminal deployment for hospitality operators.
UAE Card Payments Market Competitive Landscape
Capital-heavy full-service banks compete with digital-first specialists across the UAE card payments ecosystem. The market structure concentrates around tier-one lenders with treasury integration capabilities and niche digital challengers with compressed onboarding workflows. Three archetypes dominate: ecosystem-anchored universal banks with lifestyle partnership networks, corporate-focused institutions with working capital tool integration, and digital-native platforms targeting SME acquisition efficiency. Competitive moves center on strategic partnerships with hospitality merchants and technology licensing for biometric authentication deployment.
Within the universal bank tier, Emirates NBD and First Abu Dhabi Bank PJSC exemplify ecosystem-anchored positioning through loyalty currency integration and treasury-linked corporate offerings. Among digital-first specialists, Mashreq Bank occupies a position representing compressed time-to-activation workflows for SME segments. These three institutions anchor the competitive structure across retail and commercial card issuance archetypes.
| Leading Market Players |
|---|
| Emirates NBD |
| Abu Dhabi Commercial Bank |
| National Bank of Ras Al-Khaimah |
| Road & Transport Authority |
| Mashreq Bank |
| CitiBank UAE |
| First Abu Dhabi Bank PJSC |
| Union National Bank |
| HSBC Bank Middle East |
| Others |
Pricing and Supply Chain Analysis
Premium-standard divergence in card issuance economics manifests through interchange rate stratification and plastic personalization cost structures. UAE issuers source EMV chip modules from concentrated Asian foundries while maintaining domestic vaulting operations for credential tokenization. Pricing power concentrates with network-branded premium tiers that command elevated merchant discount rates.
Pricing Analysis
Margin tightening in mass-market debit reflects real-time payment rail substitution for low-value transactions. Three-tier pricing structure across premium, standard, and economy levels anchors issuer revenue architecture, with differentiation driven by reward redemption velocity and concierge service bundling. Cost compression accelerates in prepaid segments as unbanked labor market saturation limits pricing flexibility. Corporate treasury clients exhibit lowest price sensitivity due to working capital tool integration.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for EMV chip fabrication, while China dominates plastic substrate and magnetic stripe component manufacturing. Card personalization equipment draws from German and Japanese precision engineering suppliers. Tariff exposure on semiconductor inputs presents structural risk given limited alternative foundry capacity. Distribution runs through regional card bureau operators in Dubai and Riyadh before final issuer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE card payments sector occupies a technology-transition phase as biometric authentication and software-defined issuance displace legacy EMV plastic economics. Account-to-account real-time rails are compressing traditional interchange revenue pools.
For Market Incumbents: Anticipate margin compression in low-value debit by accelerating middleware development for instant payment interoperability. Defend premium credit portfolios through lifestyle partnership ecosystem expansion. Vertical integration into token vaulting infrastructure reduces third-party credential dependency.
For New Entrants and Emerging Players: Capture SME digital onboarding white space in northern emirates with compressed time-to-activation workflows. Target hospitality merchant acquiring in Ras Al-Khaimah's developing tourism corridor. Go-to-market leverage rests on API-first platform architecture with minimal branch infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with digital-native card platforms given open banking API integration mandates. Long-term viability favors issuers with treasury-linked corporate relationships and biometric authentication licensing. Watch visitor transaction recovery velocity at Dubai International Airport as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Deployment | Dubai International Airport facial recognition wallets compress checkout friction for visitor volumes. |
| Open Banking API Integration | UAE Central Bank mandates enable personalized financial management tools atop transaction data. |
| SME Digital Onboarding Platform | Compressed time-to-activation workflows reduce acquisition costs in northern emirates merchant segments. |
| Lifestyle Partnership Ecosystem Expansion | Emirates NBD's loyalty currency integration sustains premium cardholder retention across travel and dining. |
| Real-Time Payment Rail Connectivity | Middleware development between card systems and instant settlement infrastructure defends interchange revenue. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with card product executives, merchant acquiring heads, UAE Central Bank regulatory officers, and hospitality payment operations directors combined with UAE Central Bank circulars, Visa network rule disclosures, SAMA cybersecurity standards, and EMVCo specification documents. Bottom-up transaction volume modeling and top-down banking sector revenue triangulation validated segmentation splits.
Reconciliation of issuer-reported portfolio data, merchant acquirer terminal deployment statistics, and tourism authority visitor spending estimates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include payment instrument type, end-user category, transaction value band, and acceptance channel. CAGRs derived from historical trajectory analysis and regulatory mandate implementation timelines. Forecast inputs incorporated real-time payment interoperability deployment schedules and biometric authentication adoption curves.
The model holds under stable regulatory enforcement and visitor traffic recovery; deviation in cybersecurity breach frequency or account-to-account substitution velocity would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Gift Card and Incentive Card Market
Payments
China Real Time Payments Market
Payments
Norway Mobile Payments Market
Payments
Germany Real Time Payments Market
Payments
Proximity Mobile Payment Market
Payments
Canada Real Time Payments Market
Payments
India POS Terminals Market
Payments
Saudi Arabia Payments Market
Payments
Estonia POS Terminal Market
Payments
NFC Payments Market
Payments
B2B Payments Market
Payments
Money Transfer Agencies Market
Payments
Argentina Mobile Wallet Market
Payments
Global Accounts Payable Automation Market
Payments
Digital Transfer Services Market
Payments
Remote Mobile Payment Market