
 Deep Learning Chip Market | 2026-2036
Deep Learning Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Deep Learning Chip Market Analysis
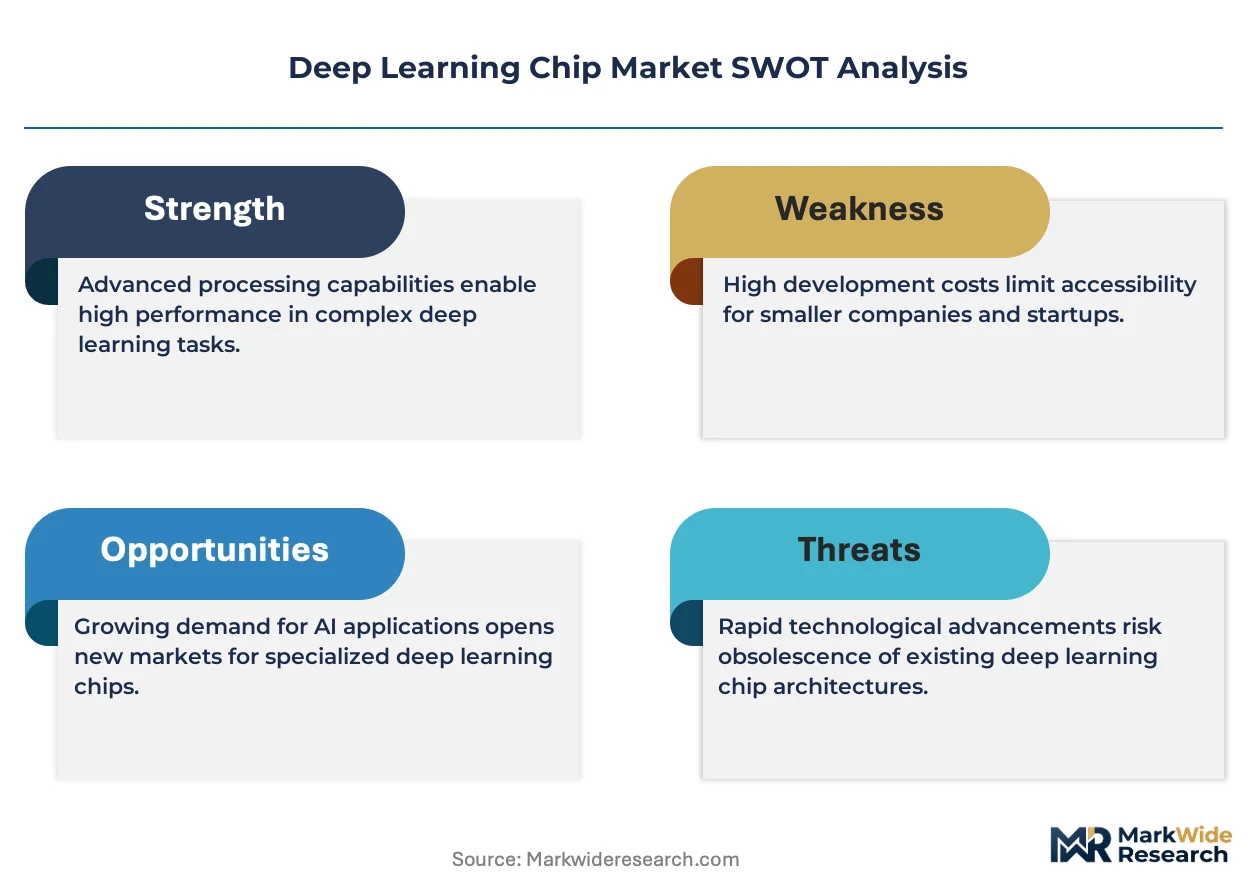
Subscription-based access to cloud-hosted AI training clusters is rebalancing how deep learning compute gets monetized. NVIDIA Corporation leverages its CUDA software ecosystem to lock in enterprise workflows across hyperscaler and research markets. Advanced Micro Devices sustains competitive pressure through open-source ROCm tooling and aggressive pricing on Instinct accelerators. Intel Corporation anchors its position with Gaudi processors aimed at cost-sensitive inference deployments in enterprise data centers.
Deep learning chips are specialized silicon processors engineered to execute matrix multiplication and tensor operations at throughputs measured in teraflops or petaflops, with architectures optimized for parallel computation rather than sequential general-purpose processing. Their primary commercial purpose is accelerating the training and inference of neural networks that power computer vision, language models, and autonomous decision systems. GPUs continue to dominate training workloads due to mature software stacks and broad developer familiarity, while ASICs such as TPUs capture margin pools in hyperscale inference where workload specificity justifies custom silicon investment. FPGAs occupy a narrower niche in low-latency edge applications within telecommunications and industrial automation where reprogrammability offsets volume constraints.
FDA scrutiny of AI-enabled medical devices shapes healthcare demand for traceable, auditable chip architectures that support deterministic inference. The EU AI Act and REACH compliance requirements are forcing European deployments toward chips with documented supply chains and energy efficiency certifications. China's MIIT dual carbon goals and GB standards are redirecting domestic procurement toward domestically fabricated accelerators. Stakeholders must monitor how export control regimes and subsidy competition between Washington, Brussels, and Beijing reshape foundry access and software portability across national boundaries.
Market Dynamics
Cloud service providers are consolidating procurement power as AI training workloads migrate from enterprise data centers to hyperscale infrastructure, compressing pricing power for hardware vendors while amplifying demand for software-integrated silicon ecosystems.
Growth Catalysts
- EU AI Act compliance mandates:High-risk AI system certification requirements are forcing enterprises to upgrade to traceable, auditable chip architectures with deterministic inference capabilities.
- Edge AI deployment in autonomous vehicles:NHTSA safety standards and OEM demand for real-time perception are accelerating low-latency inference chip adoption across automotive supply chains.
- TSMC advanced node concentration:Taiwan's dominance in 3nm and below fabrication is concentrating cutting-edge supply, creating captive demand pools for foundry partners with guaranteed capacity allocation.
Market Restraints
- CoWoS advanced packaging bottleneck:TSMC's chip-on-wafer-on-substrate capacity constraints are throttling output for high-bandwidth memory integration, extending lead times for training accelerators.
- EUV lithography equipment dependency:ASML's monopoly on extreme ultraviolet scanners limits foundry expansion outside existing customer relationships, freezing new market entrants from advanced node access.
- High-bandwidth memory supply concentration:SK Hynix, Samsung, and Micron control HBM3E output, creating single-source vulnerability for AI accelerator bill-of-materials.
Strategic Opportunities
- India's semiconductor PLI scheme:Domestic fabrication incentives and design-linked subsidy programs are attracting fabless chip architects to establish R&D centers in Bengaluru and Hyderabad.
- Photonic interconnect convergence:Co-packaged optics with silicon photonics is enabling terabit-scale chip-to-chip communication, reducing power consumption in hyperscale training clusters.
- Healthcare AI device certification pathways:FDA's pre-certification program for software-as-a-medical-device is creating streamlined demand for inference chips with embedded audit trails in diagnostic imaging.
Industry Challenges
- Neuromorphic architecture talent scarcity:Spiking demand for analog compute designers and spiking neural network specialists is outpacing university pipeline output across all major hiring geographies.
- Multi-die integration complexity:Chiplet-based designs require new EDA tools, thermal management solutions, and interconnect standards that strain legacy verification workflows and extend time-to-tapeout.
- Cross-border IP licensing friction:Export control classifications for advanced AI accelerators are fragmenting software portability and creating compliance overhead for multinational deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep Learning Chip Market |
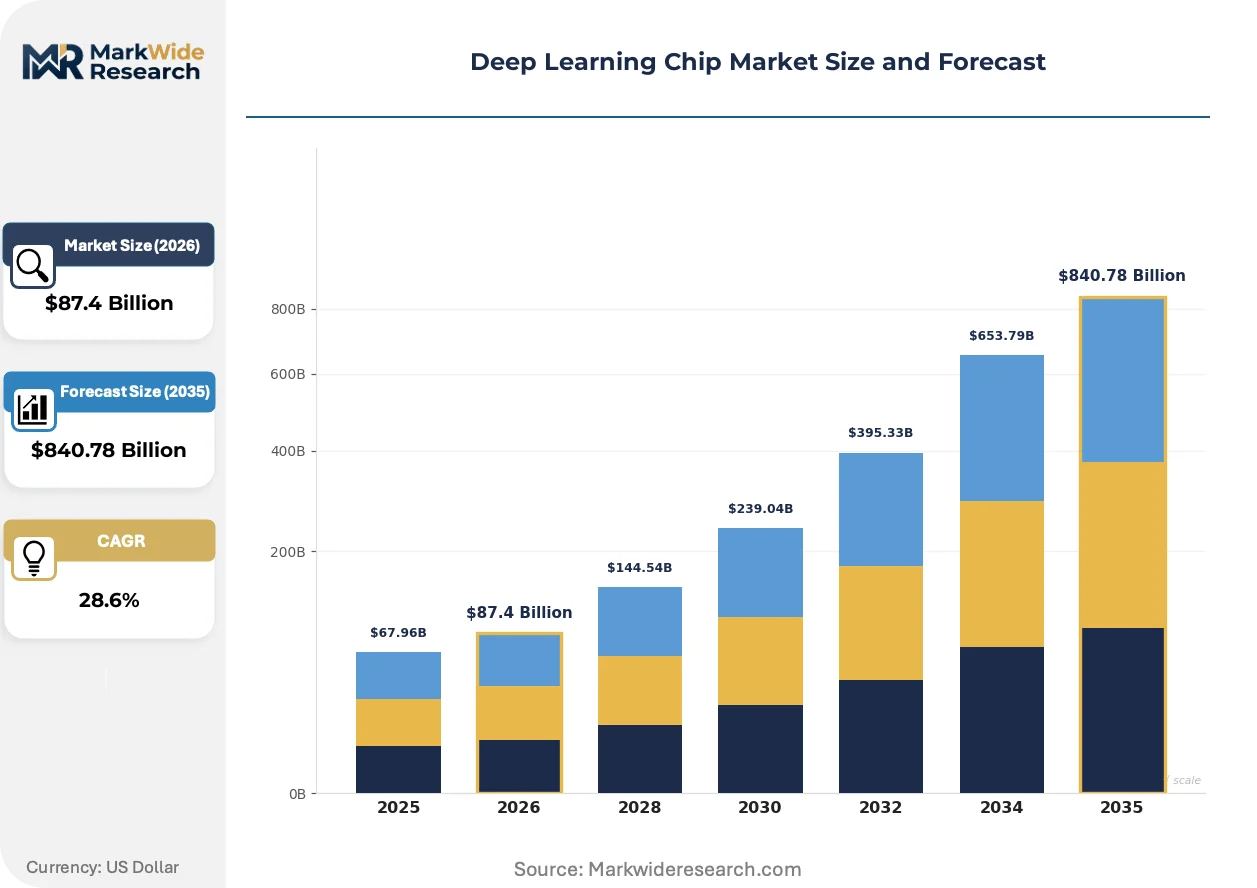
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $840.78 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPUs, TPUs, ASICs, FPGAs Application: Computer Vision, Natural Language Processing, Speech Recognition, Robotics End User: Healthcare, Automotive, Telecommunications, Industrial Technology: Neural Networks, Reinforcement Learning, Generative Models, Transfer Learning |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Intel Corporation, Google, Samsung Electronics, Qualcomm, Amazon, Xilinx, Baidu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep Learning Chip Market Emerging Trajectories
Silicon architectures are fragmenting across competing optimization targets—training throughput, inference latency, and energy efficiency—forcing buyers to segment workloads across heterogeneous compute fabrics rather than defaulting to general-purpose accelerators.
Chiplet-based modular designs are overtaking monolithic die strategies in high-performance AI accelerators. AMD and Intel have adopted multi-tile packaging for their latest data center GPUs, while hyperscalers like Google and Amazon are customizing chiplet configurations for TPU and Trainium roadmaps. This disaggregation is overtaking traditional foundry economics by yielding higher manufacturing yields on smaller dies while enabling rapid mixing of process nodes across logic, memory, and I/O functions.
REACH substance restrictions and EU AI Act conformity requirements are tightening material disclosure and energy efficiency documentation for chips deployed in European jurisdictions. The European Chemicals Agency is expanding SVHC candidate lists to include semiconductor process chemicals, forcing foundries to requalify cleaning and etching chemistries. Medical device and automotive OEMs are responding by mandating full supply chain transparency from accelerator vendors as a procurement precondition.
Subscription-based access to cloud-hosted training clusters is fragmenting enterprise capital deployment patterns. Research institutions and mid-sized enterprises are abandoning on-premise GPU purchases in favor of reserved instance contracts with AWS, Azure, and GCP, compressing hardware refresh cycles and shifting margin capture toward software orchestration layers. This transition is most visible in North American and Western European academic markets, where federal research funding agencies now prioritize operational expenditure grants over capital equipment allocations.
Deep Learning Chip Market Segmentation
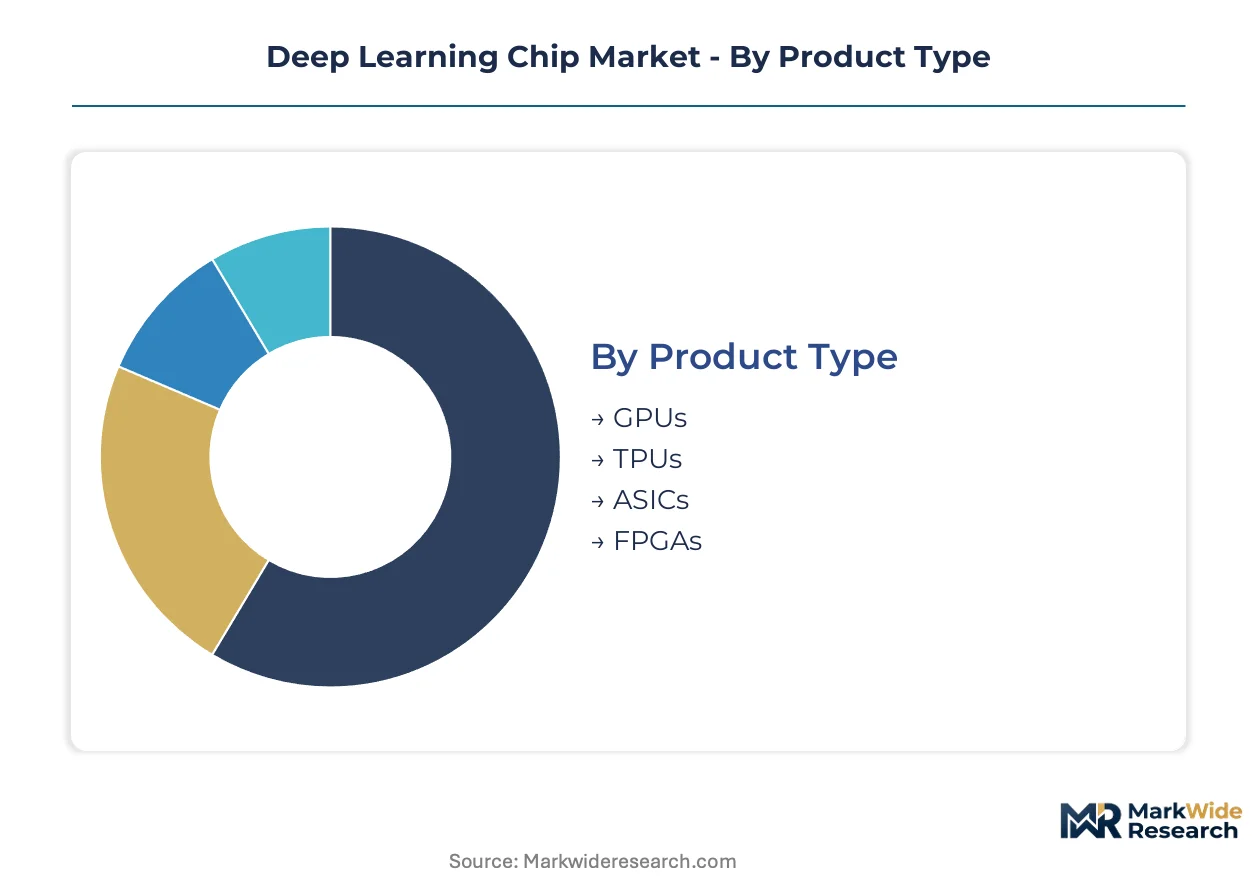
Deep learning chip procurement splits sharply across workload characteristics, with buyers selecting architectures based on whether training throughput or inference latency dominates their neural network deployment. Segmentation reveals how software ecosystem lock-in and foundry capacity allocation reshape competitive dynamics across each product category.
Product Type:
Buyers prioritize software maturity and memory bandwidth when selecting accelerator silicon for their AI infrastructure roadmaps.
- GPUs:Parallel processing engines with CUDA and ROCm software stacks dominate training clusters due to broad framework compatibility and mature developer tooling. Cloud service providers in the United States and Taiwan concentrate procurement here for large language model training, though CoWoS packaging constraints extend delivery timelines.
- TPUs:Google's tensor processing units deliver matrix multiplication efficiency through systolic array architectures optimized for TensorFlow workloads. Hyperscalers with captive silicon programs in Mountain View and Seattle deploy these for inference at scale where workload predictability justifies custom silicon investment.
- ASICs:Application-specific designs from Broadcom and Marvell target narrow inference tasks with superior watt-per-operation metrics.
- FPGAs:Reprogrammable logic from Xilinx and Intel adapts to evolving neural network topologies in low-volume edge deployments.
Volume sits with GPUs; growth tilts toward ASICs as hyperscalers internalize accelerator design.
Application:
Neural network task complexity determines whether buyers favor training-optimized or inference-optimized silicon architectures.
- Computer Vision:Convolutional and vision transformer workloads process image classification, object detection, and video analysis at scale. Automotive OEMs in Germany and Japan drive demand for deterministic inference chips that meet KBA and METI safety certification requirements.
- Natural Language Processing:Transformer architectures powering large language models consume the highest memory bandwidth and compute density in data center deployments. OpenAI, Anthropic, and research institutions in California and Massachusetts reserve cloud training clusters for foundation model development.
- Speech Recognition:Recurrent and attention-based models enable real-time audio transcription and voice assistant interfaces.
- Robotics:Sensor fusion and motion planning algorithms require low-latency edge inference in manufacturing and logistics environments.
Revenue concentrates in natural language processing; computer vision climbs fastest on automotive safety mandates.
End User:
Regulatory compliance requirements and latency tolerance shape sector-specific procurement patterns for accelerator silicon.
- Healthcare:FDA pre-certification pathways for AI-enabled diagnostic devices demand inference chips with embedded audit trails and deterministic execution. Medical device manufacturers in Minnesota and Massachusetts prioritize traceable supply chains for imaging and pathology applications.
- Automotive:NHTSA functional safety standards and OEM liability frameworks require fault-tolerant architectures for autonomous perception systems. Tier-1 suppliers in Stuttgart and Nagoya source low-latency accelerators for lidar and camera fusion pipelines.
- Telecommunications:5G baseband processing and network function virtualization drive edge AI deployment in base stations.
- Industrial:Predictive maintenance and quality inspection systems integrate vision accelerators into factory automation networks.
Procurement scale favors automotive; healthcare posts the steepest expansion trajectory on regulatory compliance upgrades.
Technology:
Algorithmic approach determines memory access patterns and parallelization strategies that silicon architects must optimize.
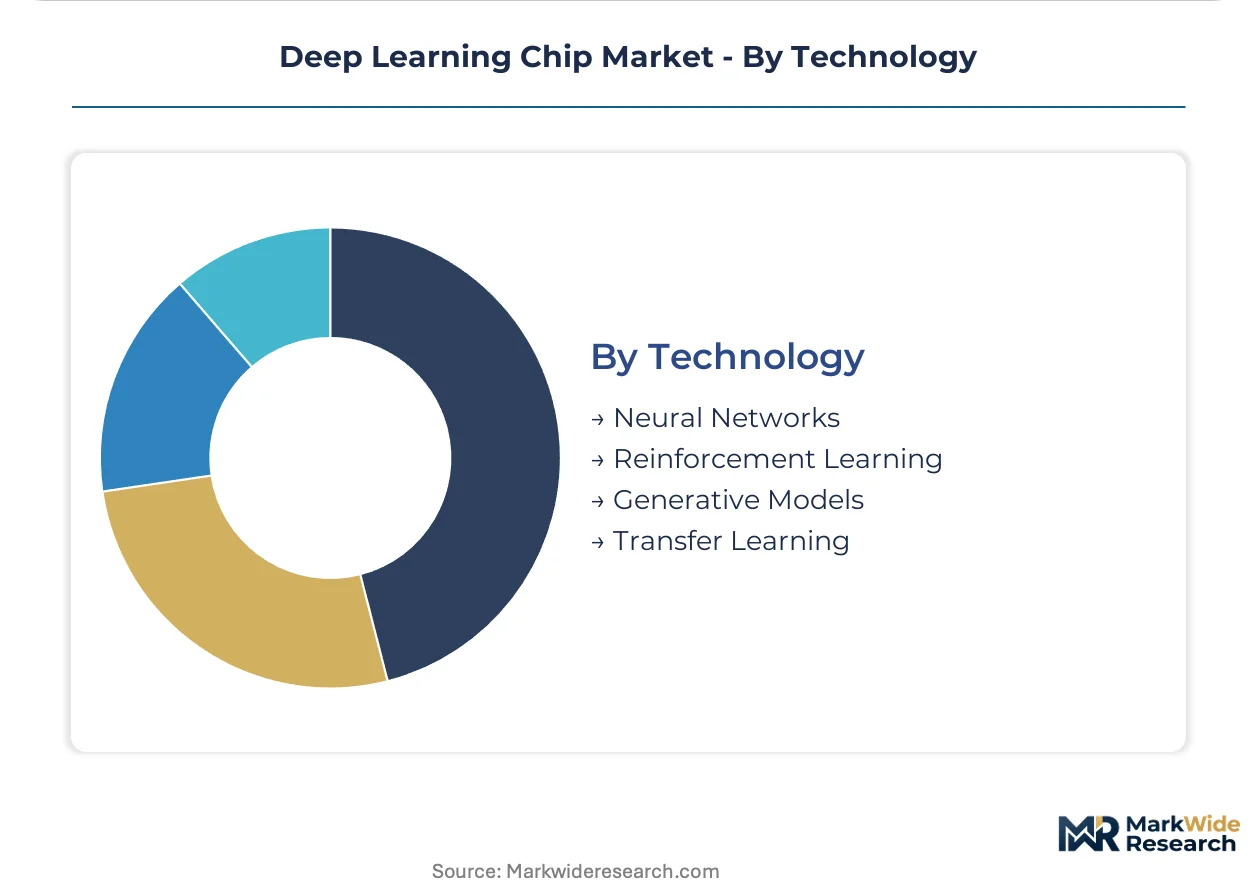
- Neural Networks:Feedforward, convolutional, and recurrent architectures constitute the foundational workload for general-purpose accelerators. Research universities across Massachusetts, California, and Ontario consume cloud GPU hours for architecture search and hyperparameter optimization.
- Reinforcement Learning:Policy gradient and Q-learning methods require simulation-environment coupling that stresses interconnect bandwidth. Robotics labs in Pittsburgh and Tokyo deploy specialized edge clusters for real-world policy deployment.
- Generative Models:Diffusion and autoregressive architectures demand the highest compute intensity for training and sampling operations.
- Transfer Learning:Fine-tuning pre-trained foundation models enables efficient specialization with reduced data requirements.
Training hours accumulate in neural networks; generative models capture the fastest-growing share of accelerator capex.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Taiwan while consumption fragments across data center clusters in the United States, China, Germany, and Japan. Advanced node fabrication capacity determines regional supply security, with each major economy pursuing domestic design capabilities to offset foundry dependency.
United States
Hyperscalers in California and Washington state drive demand for training accelerators through cloud-hosted AI clusters. FDA pre-certification pathways for medical devices create specialized procurement criteria for healthcare inference deployments. Research institutions in Massachusetts and the San Francisco Bay Area consume reserved GPU instances for foundation model development.
China
MIIT dual carbon goals and GB standards redirect domestic procurement toward locally fabricated accelerators for surveillance and industrial AI. Export control classifications fragment software portability for advanced training chips. Design houses in Beijing and Shanghai accelerate R&D on domestically produced alternatives to restricted foreign silicon.
Germany
Automotive OEMs in Stuttgart source low-latency inference chips for autonomous perception systems under KBA safety mandates. EU AI Act conformity requirements force documentation of supply chains and energy efficiency for high-risk AI deployments. Industrial automation clusters in Bavaria integrate vision accelerators into predictive maintenance networks.
Japan
METI industrial policy supports domestic semiconductor design for robotics and edge AI applications. Tier-1 suppliers in Nagoya procure fault-tolerant architectures for lidar and camera fusion pipelines. Research consortia in Tokyo and Osaka develop neuromorphic alternatives to conventional digital accelerators.
India
PLI scheme incentives attract fabless chip architects to establish design centers in Bengaluru and Hyderabad. CDSCO regulatory pathways for AI-enabled diagnostics create demand for traceable inference silicon in medical device manufacturing. Cloud service providers in Mumbai and Delhi expand reserved instance offerings to research institutions and enterprises.
Deep Learning Chip Market Vendor Landscape
Capital-heavy producers compete with asset-light designers for margin capture in the deep learning chip market. Foundry operators with guaranteed CoWoS capacity allocation command premium pricing from accelerator vendors desperate for advanced packaging slots. Three strategic archetypes dominate: integrated device manufacturers with captive fabrication, fabless designers dependent on foundry partnerships, and hyperscalers with custom silicon programs. Competitive moves concentrate on securing multi-year foundry capacity agreements and acquiring EDA tooling startups to accelerate chiplet-based design workflows.
Within the integrated device manufacturer tier, Intel Corporation anchors positions in cost-sensitive enterprise data centers through Gaudi processor deployments. NVIDIA Corporation exemplifies the fabless ecosystem play, leveraging CUDA software lock-in across hyperscaler and research markets. Advanced Micro Devices occupies a competitive position through open-source ROCm tooling and aggressive Instinct accelerator pricing, pressuring incumbent margins in cloud training clusters.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Samsung Electronics |
| Qualcomm |
| Amazon |
| Xilinx |
| Baidu |
| Others |
Supply Flow & Price Mechanics
Polysilicon spot price volatility cascades through foundry cost structures into three-tier pricing stratification across premium, standard, and economy accelerator tiers, with CoWoS packaging premiums widening spreads between leading-edge and trailing-node offerings.
Pricing Analysis
Margin tightening in mid-range inference accelerators reflects hyperscaler procurement consolidation and ROCm-compatible pricing pressure from AMD. Three-tier pricing structure across premium, standard, and economy levels segments on CUDA ecosystem maturity and HBM3E memory bandwidth. Cost-down pressure on economy-tier ASICs accelerates because Chinese domestic alternatives undercut Western silicon on foundry labor arbitrage. Research institutions exhibit highest price sensitivity; automotive Tier-1s tolerate premium positioning for KBA-certified deterministic inference chips.
Supply Chain Analysis
Air freight rates for lithography equipment from the Netherlands to Taiwan feed into foundry capital recovery charges passed to fabless designers. Supply concentrates in Taiwan, South Korea, and the United States for advanced node fabrication, with EUV scanner maintenance dependencies anchoring output in existing customer relationships. Raw material inputs draw from high-purity silicon wafers, photoresist chemistries, and rare earth elements for magnetic components. Single-source vulnerability sits with ASML's extreme ultraviolet monopoly. Distribution runs through direct foundry allocation agreements rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around foundry capacity holders as CoWoS packaging constraints force acquisition or exit for accelerator designers lacking guaranteed TSMC allocation.
For Market Incumbents: Cement multi-year CoWoS capacity reservations through equity partnerships with TSMC or Samsung Foundry. Acquire EDA tooling startups specializing in chiplet thermal verification to compress time-to-tapeout against emerging entrants. Defensive priority rests on backward integration into advanced packaging to offset SK Hynix HBM3E supply concentration. For New Entrants and Emerging Players: The premium-to-economy price gap in healthcare inference chips creates entry opportunity for CDSCO-compliant traceable architectures. Target Bengaluru and Hyderabad design centers under India's PLI scheme for cost-engineered alternatives to CUDA-locked training accelerators. Go-to-market angle: deterministic audit-trail silicon for FDA pre-certification pathways in Minnesota medical device clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless designers with taped-out 5nm inference accelerators and stranded CoWoS allocation in Taiwan. Long-term viability hinges on software portability across ROCm, oneAPI, and emerging open standards. Watch for MIIT domestic procurement mandates as inflection signal for Western accelerator demand destruction in China.| Strategic Initiative | Industry Significance |
|---|---|
| CoWoS Capacity Reservation | Secures TSMC packaging slots essential for HBM3E integration in training accelerators. |
| Chiplet EDA Acquisition | Accelerates multi-die verification workflows for AMD and Intel competitive positioning. |
| EU AI Act Certification | Unlocks German automotive and healthcare procurement under KBA and ECHA compliance mandates. |
| ROCm Ecosystem Expansion | Reduces CUDA dependency for hyperscaler training clusters seeking vendor diversification. |
| India PLI Design Center | Captures fabless subsidy incentives and CDSCO-aligned medical device silicon demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with semiconductor procurement executives at hyperscalers, foundry capacity planners, EDA tooling product managers, and automotive Tier-1 supplier engineers validated demand assumptions. SEC 10-K disclosures from NVIDIA, AMD, and Intel, combined with MIIT GB standard publications and ECHA SVHC candidate list updates, supplied financial and regulatory calibration points. Bottom-up wafer starts and top-down cloud capex trajectories were reconciled through iterative triangulation.
Data-stream reconciliation across foundry utilization rates, hyperscaler accelerator deployment disclosures, and customs import records shaped the projection framework. Segmentation dimensions modeled include product architecture, application workload, end-user regulatory cluster, and technology approach across the analysis window. CAGRs derived from curve-fitting historical foundry revenue per wafer against cloud infrastructure spending elasticity. EU AI Act compliance timelines and NHTSA autonomous vehicle safety mandates served as policy-inflection inputs.
Underlying measurement precision varies by segment; automotive and healthcare procurement data carry tighter precision than emerging robotics edge deployments. Forecasts reflect assumptions about CoWoS capacity expansion, export control stability, and open-source software portability that semiconductor stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Thailand Data Center Processor Market
Chipset and Processors
Edge AI Processor Market
Chipset and Processors
Global Microprocessor and GPU Market
Chipset and Processors
8-Bit MCU Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Integrated Graphics Chipset Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Protein Chip Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
United Arab Emirates Data Center Processor Market