
 Automotive Gateway Chips Market | 2026-2036
Automotive Gateway Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gateway Chips Market Analytics
Silicon carbide substrate migration is decoupling thermal management costs from traditional silicon-based gateway designs. NXP Semiconductors leverages its S32G vehicle network processor family to anchor high-throughput Ethernet gateway slots across premium OEM programs. Infineon Technologies sustains its position through AURIX TC4x microcontrollers that integrate lockstep cores for ASIL-D functional safety. Texas Instruments competes with Jacinto 7 SoCs that consolidate cockpit and gateway workloads onto unified compute platforms.
Automotive gateway chips are mixed-signal integrated circuits that route, filter, and secure data traffic between vehicle domains using multi-protocol transceivers operating up to multi-gigabit Ethernet speeds alongside legacy CAN-FD and LIN interfaces. Their primary purpose is to enforce deterministic latency boundaries while isolating critical powertrain and chassis networks from infotainment and telematics payloads. Ethernet-based gateway silicon leads in revenue contribution as zonal architectures displace flat network topologies, though CAN transceiver integration retains volume dominance in cost-optimized vehicle classes. SoC solutions represent the fastest-expanding product category, absorbing adjacent switch and security accelerator functions that previously required discrete components.
UN ECE R155 and R156 regulations, enforced by Germany's KBA and Japan's MLIT through type-approval frameworks, mandate cybersecurity management systems and software update capabilities that directly dictate gateway chip security IP requirements. The EU Cyber Resilience Act extends these obligations to aftermarket gateway modules, compelling Tier-1 suppliers to certify entire supply chains. China's MIIT publishes GB standards for connected vehicle security that SAMR enforces through mandatory testing, creating divergent certification paths for chips serving export versus domestic Chinese programs. Stakeholders must monitor whether regional cybersecurity mandates fragment gateway platform designs or drive consolidation around programmable security subsystems that adapt to jurisdiction-specific rules.
Market Dynamics
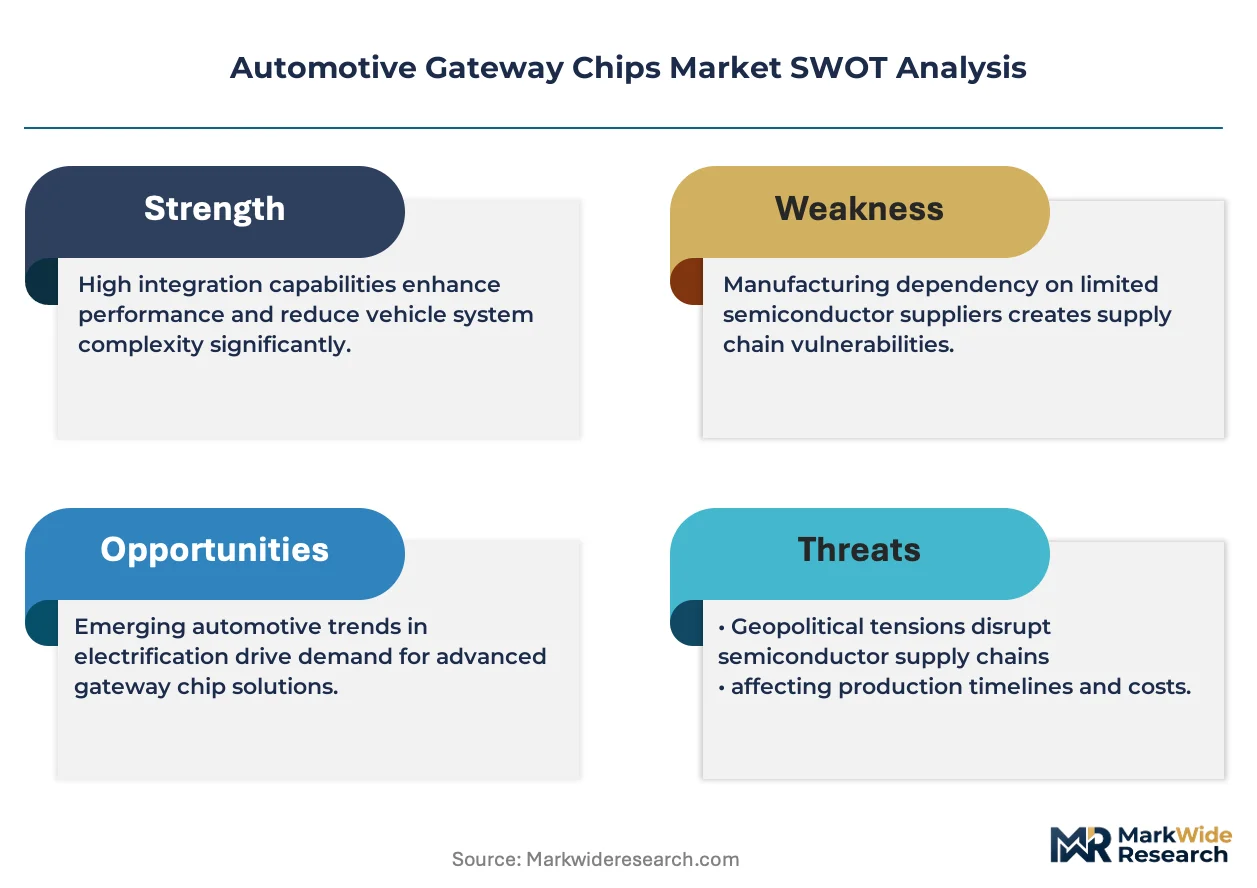
Centralized E/E architecture migration is compressing discrete gateway functions into consolidated domain controllers, forcing chipmakers to absorb switch, security, and real-time processing capabilities onto single silicon dies while maintaining ASIL-D safety integrity.
Growth Catalysts
- UN ECE R155 cybersecurity mandates:Germany's KBA and Japan's MLIT enforce type-approval frameworks requiring hardware-rooted trust architectures, compelling gateway silicon upgrades across vehicle programs.
- Zonal computing loads:BMW, Mercedes-Benz, and Volkswagen are consolidating gateway functions into domain controllers, creating demand for multi-gigabit Ethernet-capable processors.
- Silicon carbide substrate migration:Thermal management costs are decoupling from traditional silicon-based designs, enabling higher integration density in power-constrained automotive environments.
Market Restraints
- Advanced node wafer costs:16nm and 7nm automotive-qualified foundry capacity commands premium pricing, squeezing margins on gateway SoCs serving mass-market vehicle classes.
- Functional safety certification timelines:ASIL-D qualification cycles extend 18-24 months, delaying revenue recognition for new gateway processor tape-outs.
- Legacy CAN-FD protocol persistence:Cost-optimized vehicle segments in emerging markets resist full Ethernet migration, fragmenting silicon SKU requirements.
Strategic Opportunities
- Software-defined vehicle architectures:Over-the-air update capabilities mandated by EU Cyber Resilience Act create attach opportunities for secure element integration within gateway chips.
- Edge AI inference offloading:Sensor fusion workloads are migrating from centralized compute to zonal gateways, opening vector processing unit integration vectors.
- China's GB standards compliance:MIIT-connected vehicle security regulations enforced by SAMR through mandatory testing create localized certification paths for export-oriented chipmakers.
Industry Challenges
- Multi-protocol verification complexity:Simultaneous CAN-FD, LIN, and multi-gigabit Ethernet validation requires specialized automotive test equipment and extended emulation cycles.
- Cybersecurity IP integration:Hardware security module design talent concentrates among limited semiconductor vendors, creating recruitment bottlenecks for gateway chip development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gateway Chips Market |
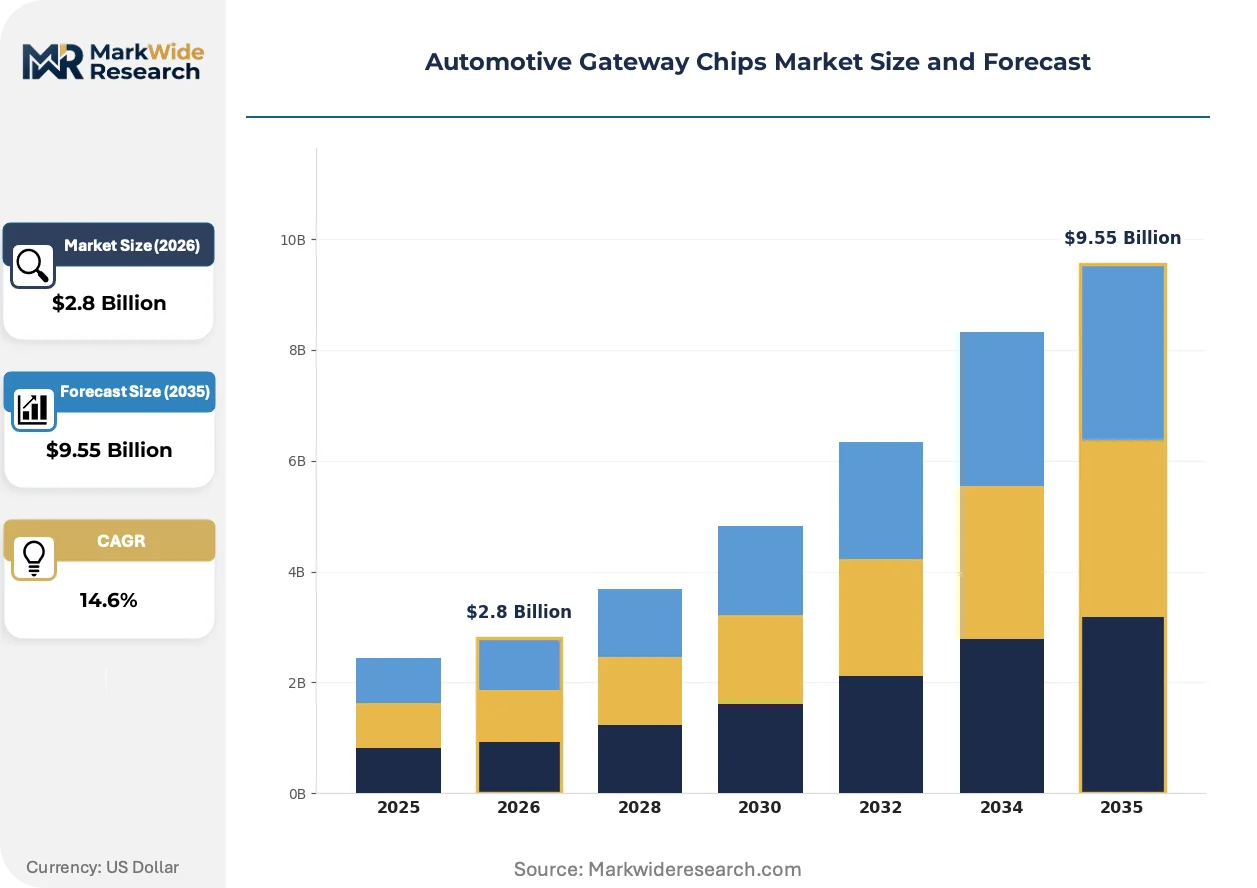
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontroller, SoC, ASIC, FPGA Technology: Ethernet, CAN, LIN, FlexRay End User: OEMs, Aftermarket Providers, Fleet Operators, Tier-1 Suppliers Installation: Integrated, Standalone, Plug-and-Play, Field Upgradeable |
| Companies Covered | STMicroelectronics, Robert Bosch GmbH, NXP Semiconductors, Analog Devices, ON Semiconductor, Infineon Technologies, Texas Instruments, Microchip Technology, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gateway Chips Market Evolving Landscape
Gateway silicon evolution is compressing discrete networking, security, and real-time control functions into unified compute platforms, with regulatory mandates and procurement model shifts accelerating architectural consolidation across OEM supply chains.
Multi-core lockstep processor architectures are absorbing discrete safety microcontroller and Ethernet switch functions that previously required separate components. Premium OEM programs in Germany are adopting these integrated SoCs at accelerated cadences to reduce board space and harness wiring complexity. This consolidation is absorbing adjacent semiconductor revenue pools and compressing Tier-1 supplier bill-of-materials flexibility.
The EU Cyber Resilience Act extends cybersecurity obligations to aftermarket gateway modules, compelling entire supply chain certification. Germany's KBA enforces these requirements through type-approval frameworks that dictate hardware-rooted trust IP specifications. Gateway chip vendors serving European OEM programs are responding by embedding programmable security subsystems capable of jurisdiction-specific rule adaptation.
Long-term supply agreements are replacing spot purchasing for automotive-qualified silicon as OEMs secure capacity at advanced nodes. Tier-1 gateway module suppliers in Stuttgart and Ingolstadt are locking in multi-year foundry allocations to de-risk program launches. This shift is most visible in Germany, where BMW, Mercedes-Benz, and Volkswagen have consolidated procurement functions to negotiate directly with semiconductor vendors.
Automotive Gateway Chips Market Segmentation
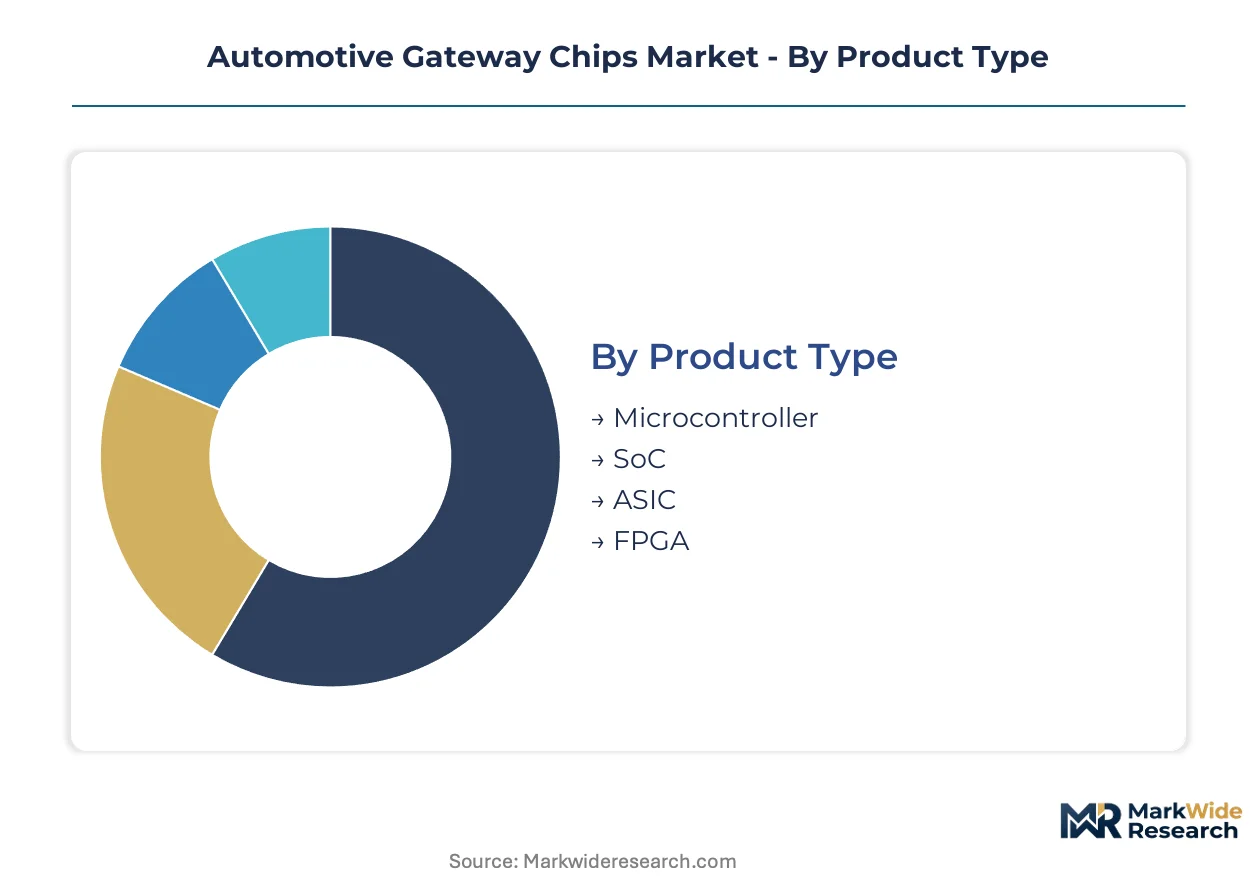
Gateway chip procurement splits along fault-tolerance requirements, protocol migration timelines, and integration depth. OEMs select silicon categories based on zonal architecture maturity, while aftermarket channels prioritize field-upgradeable form factors to extend vehicle service lives.
Product Type:
Silicon complexity dictates unit economics and safety certification burden, with buyers trading integration density against qualification timelines.
- Microcontroller:Lockstep core architectures execute deterministic routing with ASIL-D safety integrity. BMW, Mercedes-Benz, and Volkswagen specify AURIX-class devices for chassis-critical domains where latency bounds are non-negotiable.
- SoC:Unified compute platforms absorb Ethernet switching, hardware security modules, and real-time processing onto single dies. These command premium pricing in Germany's domain controller consolidation wave, climbing the fastest as zonal architectures displace distributed gateways.
- ASIC:Custom silicon minimizes die area for high-volume vehicle programs with frozen network specifications. NXP and Infineon tape these for committed OEM annual volume commitments exceeding 500,000 units.
- FPGA:Reconfigurable logic enables protocol adaptation during development cycles before ASIC hardening. Tier-1 suppliers in Stuttgart deploy these for pre-production gateway validation against evolving UN R155 security requirements.
Microcontrollers lead on scale; SoCs lead on momentum.
Technology:
Physical layer selection tracks E/E architecture generation, with legacy buses persisting in cost-optimized segments while multi-gigabit Ethernet captures new platform development.
- Ethernet:Multi-gigabit speeds enable sensor fusion and over-the-air payload aggregation across zonal domains. Germany's KBA type-approval frameworks for UN ECE R155 mandate the bandwidth headroom these links provide for encrypted update tunnels.
- CAN:Controller Area Network dominates powertrain and body electronics with deterministic arbitration. CAN-FD variants retain volume dominance in emerging-market vehicle classes where full Ethernet migration is cost-prohibitive.
- LIN:Low-cost single-wire protocol serves door modules, seat controls, and lighting subnetworks. Japanese OEMs specify these for economy vehicle interior domains where data rates remain below 20 kbps.
- FlexRay:Time-triggered deterministic busing supports brake-by-wire and steer-by-wire chassis networks. BMW retains this for legacy platform extensions despite Ethernet's broader displacement.
Ethernet commands development investment; CAN retains shipment volume.
End User:
Procurement authority concentration varies by vehicle lifecycle stage, with OEMs dictating silicon specifications and aftermarket channels seeking backward-compatible retrofit paths.
- OEMs:Vehicle manufacturers specify gateway silicon during platform architecture definition, locking in multi-year supply agreements. Direct negotiations with NXP, Infineon, and Texas Instruments now bypass traditional Tier-1 distribution in Germany.
- Tier-1 Suppliers:Continental, Bosch, and ZF integrate chips into gateway modules for OEM program allocation. These suppliers bear ASIL-D certification costs and inventory risk under Stuttgart and Ingolstadt procurement terms.
- Aftermarket Providers:Independent module vendors address vehicle cybersecurity retrofit mandates under EU Cyber Resilience Act extended obligations. Germany's KBA enforces supply chain certification for these channels.
- Fleet Operators:Commercial vehicle aggregators specify telematics-heavy gateway configurations for asset tracking and predictive maintenance. These buyers prioritize field-upgradeable security patches over initial silicon cost.
OEMs anchor specification authority; aftermarket channels expand fastest on regulatory retrofit demand.
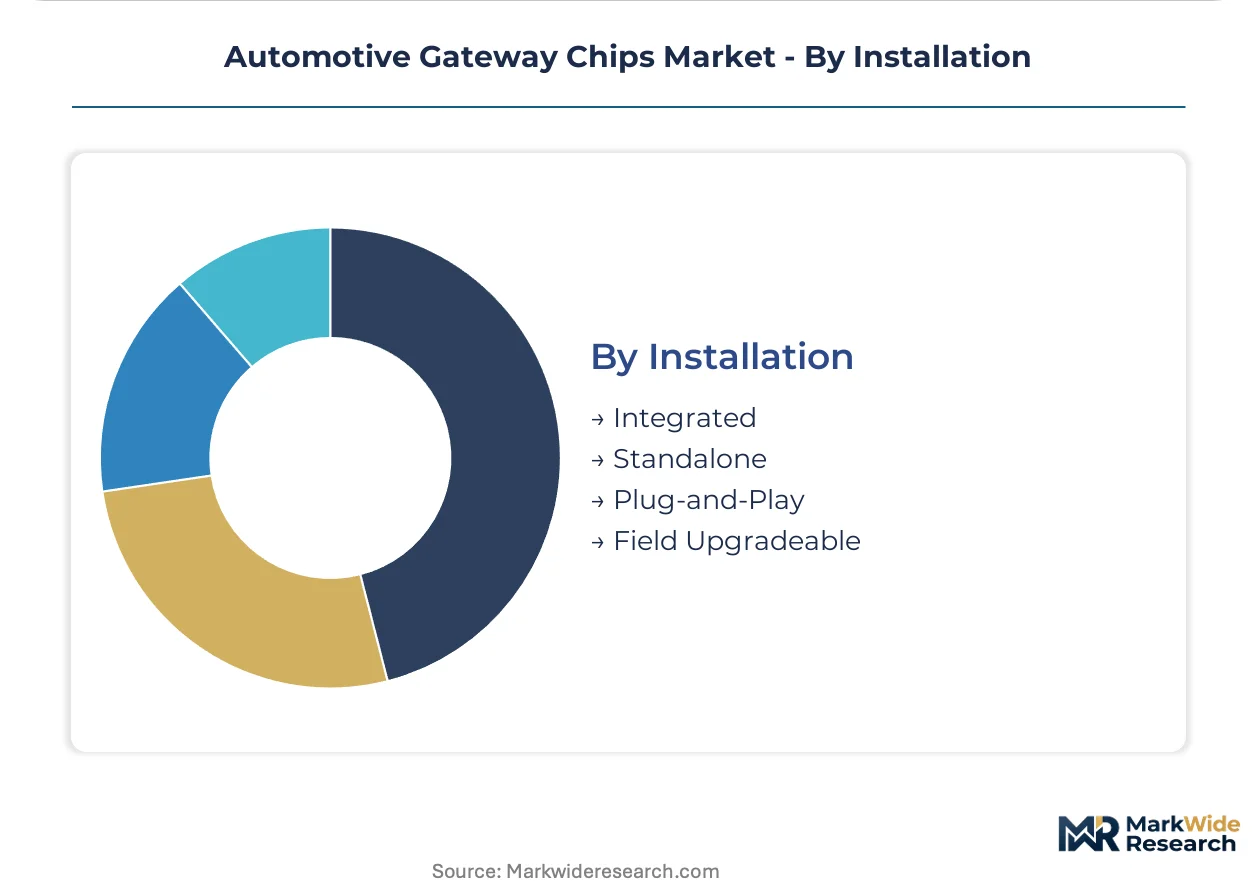
Installation:
Physical integration depth determines thermal design constraints and service accessibility tradeoffs across vehicle production and post-sale phases.
- Integrated:Silicon mounts directly onto domain controller PCBs with shared thermal management and power delivery. Mercedes-Benz specifies these for EQS and S-Class centralized compute clusters.
- Standalone:Discrete gateway modules maintain separate housing and connector schemes for service replacement. Volkswagen retains these for MQB platform derivatives where zonal migration remains partial.
- Plug-and-Play:Standardized form factors enable rapid swap without calibration or software reflash. Japanese aftermarket channels favor these for minimized service bay occupancy.
- Field Upgradeable:Firmware-over-the-air capable designs satisfy UN ECE R156 software update mandates without hardware replacement. EU Cyber Resilience Act enforcement is expanding this segment's attach rate.
Integrated configurations dominate new platform design; field upgradeable variants gain share on regulatory compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive corridor between Stuttgart and Ingolstadt anchors gateway chip procurement through consolidated OEM-direct negotiations with semiconductor vendors. Regulatory enforcement by Germany's KBA under UN ECE R155 cybersecurity mandates compresses supplier qualification timelines across European programs. Zonal architecture migration at BMW, Mercedes-Benz, and Volkswagen concentrates demand for multi-gigabit Ethernet-capable silicon in Bavaria and Baden-Württemberg production clusters.
United States
Detroit's automaker engineering centers specify gateway silicon for pickup truck and full-size SUV platforms with legacy CAN-FD persistence. NHTSA cybersecurity guidance aligns with UN ECE R155 principles, compelling hardware-rooted trust architectures for vehicles exported to European markets. Michigan and Ohio-based Tier-1 suppliers integrate chips from NXP Semiconductors and Texas Instruments into domain controller modules for Ford and General Motors programs.
China
Domestic EV manufacturers in Shenzhen and Shanghai accelerate zonal architecture adoption faster than legacy joint ventures. MIIT's GB standards for connected vehicle security, enforced by SAMR through mandatory testing, create divergent certification paths for chips serving export versus domestic programs. Yangtze River Delta semiconductor packaging facilities handle backend processing for gateway chips designed by international vendors seeking China market access.
Japan
MLIT enforces UN ECE R155 type-approval frameworks with stricter interpretation timelines than European counterparts. Toyota and Honda engineering centers in Aichi Prefecture specify gateway silicon with extended temperature ranges for hybrid powertrain integration. Renesas Electronics anchors domestic supply relationships through lockstep core microcontrollers serving brake-by-wire chassis networks.
South Korea
Hyundai Motor Group's Namyang R&D campus consolidates gateway function specification for Genesis premium platforms and Kia volume programs. MFDS-aligned automotive cybersecurity guidelines influence chip procurement criteria alongside export-market UN regulations. Samsung Electronics foundry capacity at Pyeongtaek supplies advanced node wafer starts for international gateway SoC vendors seeking capacity diversification.
Automotive Gateway Chips Market Competitive Landscape
Global majors compete with regional champions across automotive-qualified silicon supply, creating a tiered structure where European and American vendors hold premium OEM sockets while Asian suppliers capture cost-optimized volume segments. Market concentration reflects ASIL-D certification barriers that extend 18-24 months for new processor tape-outs, entrenching incumbents with existing qualification portfolios. Two strategic archetypes dominate: integrated device manufacturers with captive foundry relationships, and fabless specialists leveraging Taiwan Semiconductor Manufacturing capacity. Competitive dynamics center on multi-year supply agreement negotiations and security IP licensing rather than price competition.
Within the integrated device manufacturer tier, Infineon Technologies and NXP Semiconductors exemplify European-based vendors with deep automotive certification heritage and direct OEM procurement relationships. Texas Instruments represents American fabless-specialist positioning through Jacinto SoC consolidation of cockpit and gateway workloads. These three anchors demonstrate how geographic origin and manufacturing model selection map to distinct customer access patterns across German, American, and Asian OEM supply chains.
| Leading Market Players |
|---|
| STMicroelectronics |
| Robert Bosch GmbH |
| NXP Semiconductors |
| Analog Devices |
| ON Semiconductor |
| Infineon Technologies |
| Texas Instruments |
| Microchip Technology |
| Renesas Electronics |
| Others |
Value Network & Pricing Analysis
Advanced node wafer costs at 16nm and 7nm automotive-qualified foundries cascade through gateway chip pricing tiers, with Germany's OEM-direct procurement compressing margins on mass-market silicon while premium domain controller sockets absorb pass-through premiums.
Pricing Analysis
Input-cost pass-through from foundry capacity premiums shapes a three-tier pricing structure across premium, standard, and economy levels. ASIL-D certification grade and volume scale drive price differentiation, with chassis-critical lockstep microcontrollers commanding premiums over infotainment-optimized variants. Pricing pressure stems from advanced node capacity constraints at Taiwan Semiconductor Manufacturing and Samsung Pyeongtaek. Mass-market vehicle classes exhibit highest price sensitivity, while German premium OEMs prioritize supply security over unit cost.
Supply Chain Analysis
China's GB standards for connected vehicle security, enforced by SAMR through mandatory testing, are reshaping sourcing patterns for chips serving domestic versus export programs. Gateway silicon supply concentrates in Taiwan, South Korea, and Germany, drawing from silicon carbide substrates, automotive-grade packaging materials, and multi-protocol IP cores. Single-source vulnerability around advanced node foundry capacity creates structural risk. Distribution runs through Tier-1 module suppliers in Stuttgart and Ingolstadt before OEM final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive gateway chips market functions as a regulatory compounder, with UN ECE R155 cybersecurity mandates creating irreversible silicon upgrade cycles across vehicle programs.
For Market Incumbents: Deploy long-term supply agreements as the primary lever to lock in multi-year foundry allocations before capacity tightens further. Secure ASIL-D certification pipelines for next-generation lockstep architectures to defend against fabless entrants with shorter qualification timelines. Consolidate security IP portfolios through selective licensing to raise barriers for challengers lacking hardware-rooted trust expertise. For New Entrants and Emerging Players: Aftermarket retrofit channels offer the most penetrable entry vector, with EU Cyber Resilience Act extended obligations creating certified module demand outside OEM procurement cycles. Target fleet operator telematics configurations where field-upgradeable security patches outweigh initial silicon cost considerations. Pursue joint development agreements with Yangtze River Delta packaging facilities to bypass captive foundry relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where ASIL-D certification portfolios concentrate among European and American vendors with decade-long OEM relationships. Five-to-ten year viability favors integrated device manufacturers with captive backend capacity and direct KBA type-approval track records. Watch for inflection when China's MIIT accelerates GB standard harmonization with UN ECE frameworks, compressing divergent certification paths.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Foundry Allocation Lock-in | BMW, Mercedes-Benz, and Volkswagen direct negotiations secure capacity at advanced nodes ahead of competitors. |
| Hardware Security Module Integration | Programmable subsystems adapt to jurisdiction-specific KBA, MLIT, and SAMR certification requirements. |
| Zonal Architecture Platform Standardization | Domain controller consolidation absorbs discrete gateway, switch, and accelerator functions onto unified silicon. |
| Silicon Carbide Substrate Migration | Thermal management decoupling enables higher integration density in power-constrained automotive environments. |
| Aftermarket Cybersecurity Retrofit Certification | EU Cyber Resilience Act supply chain obligations extend addressable market beyond OEM new vehicle programs. |
Research Methodology
Multiple input streams — primary interviews with Tier-1 supplier procurement, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and SEC semiconductor filings; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from segmented growth rate reconciliation. Forecast inputs included zonal architecture migration timelines, UN ECE R155 implementation schedules, and foundry capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cybersecurity regulation fragmentation, advanced node yield improvements, and silicon carbide substrate cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
South Korea Edge AI Processor Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Global Multimedia Chipsets Market
Chipset and Processors
Display Driver Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Automotive Microcontrollers (MCU) Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Thailand Data Center Processor Market