
 United States Large Kitchen Appliances Market | 2026-2036
United States Large Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Large Kitchen Appliances Market Analytics
Multi-source component procurement is pivoting toward captive motor and compressor production as supply chain volatility reshapes cost structures. Whirlpool Corporation leverages its Benton Harbor manufacturing footprint to sustain domestic compressor assembly capacity. GE Appliances anchors its Louisville operations with in-house stainless steel fabrication and induction coil winding. Samsung Electronics competes through vertical control over semiconductor-driven inverter modules for its Chef Collection refrigeration line.
United States large kitchen appliances encompass electrically or gas-powered fixed equipment for food preservation, thermal processing, and ware cleaning, typically rated between 120V and 240V with cabinet dimensions exceeding 24 inches in width. These units employ hermetic compressor systems, cavity insulation rated to R-30 equivalent, and electronic control boards with Wi-Fi protocol stacks for remote diagnostics and energy management. Refrigerators dominate value contribution due to extended replacement cycles and premiumization toward French-door configurations with dual evaporators. Smart appliances within the installation-type dimension are capturing margin pools through subscription-enabled predictive maintenance and utility demand-response integration. The commercial end-user segment sustains above-average durability specifications and 208V three-phase electrical requirements that limit supplier participation.
The Department of Energy minimum efficiency standards and ENERGY STAR certification thresholds determine market access for refrigeration and dishwasher product lines, while the EPA SNAP program phases down hydrofluorocarbon refrigerants with compliance deadlines compressing R&D timelines. The Consumer Product Safety Commission maintains active recall jurisdiction over gas cooking products with simmer burner malfunction risks, creating liability exposure that shapes warranty reserve calculations. State regulators in California enforce Title 24 building efficiency codes that effectively mandate electric-ready appliance rough-ins for new residential construction. Stakeholders must monitor emerging federal standby power regulations and state-level gas appliance prohibition preemption battles that could bifurcate product portfolios between all-electric and dual-fuel configurations.
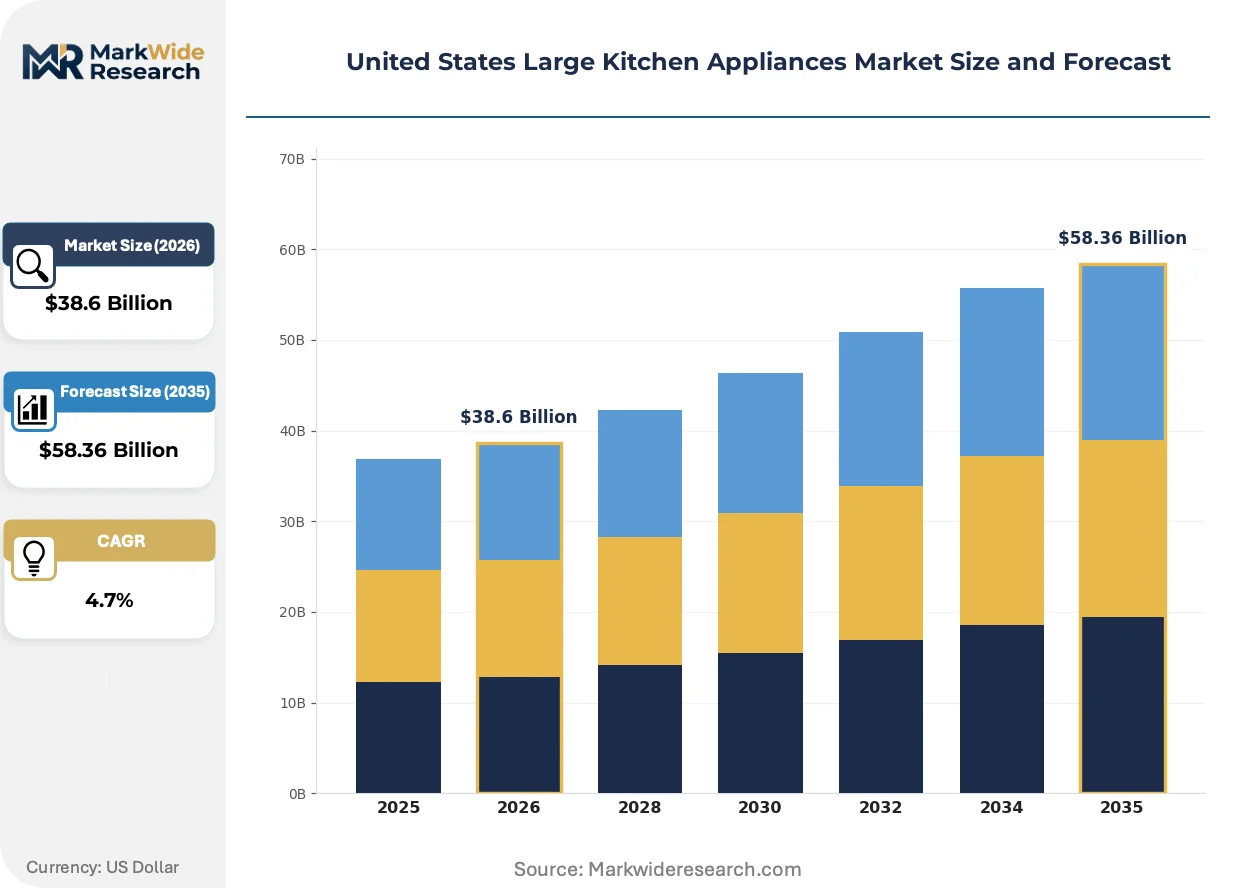
Market Dynamics
Electrification mandates in California and New York are forcing manufacturers to bifurcate product portfolios between gas and all-electric configurations, while Sun Belt residential construction sustains replacement cycle compression for built-in refrigeration and smart cooking suites.
Growth Catalysts
- California Title 24 building codes:Electric-ready appliance rough-in mandates for new residential construction are accelerating induction range and heat-pump dryer penetration in the nation's largest housing market.
- Smart utility demand-response programs:Wi-Fi-enabled appliances with automated load-shifting capabilities are capturing utility-sponsored rebates and subscription revenue pools from Texas to Florida.
- Dual-evaporator French-door refrigeration:Premium configurations with independent climate zones are extending replacement cycles while commanding margin premiums in renovation-heavy Georgia and Texas metro corridors.
Market Restraints
- Hermetic compressor supply concentration:Domestic captive production capacity at Benton Harbor and Louisville anchors supply, but semiconductor-driven inverter module shortages constrain Chef Collection-tier output.
- EPA SNAP refrigerant phase-down timelines:Hydrofluorocarbon compliance deadlines are compressing R&D budgets and forcing premature platform redesigns ahead of natural replacement cycles.
- Stainless steel input volatility:In-house fabrication at GE Appliances' Louisville campus mitigates spot price exposure, but mid-tier competitors remain exposed to commodity swings.
Strategic Opportunities
- Heat-pump dryer technology convergence:Integration with heat-pump HVAC systems creates whole-home electrification bundles for California and New York retrofits.
- Predictive maintenance subscriptions:Remote diagnostic protocol stacks enable recurring revenue streams from high-end built-in refrigeration installed in Sun Belt custom homes.
- Texas-Florida-Georgia permit concentration:Elevated new housing starts in these three states create concentrated demand pockets for smart cooking suite pre-installation partnerships with residential builders.
Industry Challenges
- Induction coil winding skill scarcity:In-house capability at Louisville operations contrasts with industry-wide technician shortages for precision electromagnetic component assembly.
- DOE efficiency certification timelines:Minimum standard updates and ENERGY STAR threshold revisions demand parallel testing protocols that strain validation laboratory capacity.
- Gas-electric portfolio complexity:Maintaining dual supply chains for dual-fuel and all-electric configurations duplicates tooling and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Large Kitchen Appliances Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.36 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Washers Distribution Channel: Online, Specialty Stores, Retail Chains, Direct Sales Installation Type: Built-in, Freestanding, Smart Appliances, Compact End User: Residential, Commercial, Institutional, Hospitality |
| Companies Covered | Whirlpool Corporation, GE Appliances, LG Electronics, Samsung Electronics, Bosch Home Appliances, Haier U.S. Appliance Solutions, Electrolux Major Appliances, Panasonic, Miele, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Large Kitchen Appliances Market Evolving Landscape
Semiconductor-driven control systems and refrigerant chemistry transitions are compressing product development cycles while reshaping competitive differentiation around energy management software rather than mechanical reliability alone.
Inverter-driven compressor technology is consolidating variable-speed refrigeration control across premium French-door and built-in product lines. Residential builders in Sun Belt states specify these units for energy code compliance and utility rebate capture. The technology is consolidating supplier margins into semiconductor and firmware competency layers, displacing pure mechanical component vendors.
EPA SNAP hydrofluorocarbon phase-down regulations are mandating refrigerant chemistry transitions with compliance deadlines through 2025-2027. Appliance manufacturers must validate alternative low-global-warming-potential formulations without compromising hermetic system reliability. The regulation most affects built-in refrigeration with extended warranty exposure, pushing suppliers toward accelerated life testing protocols.
Builder-direct procurement models are bypassing traditional retail channels for new construction specifications in Texas, Florida, and Georgia. National residential builders consolidate appliance selections into master purchasing agreements with installation and warranty integration. This channel compression is most visible in Sun Belt metro corridors where permit velocity supports dedicated builder program infrastructure.
United States Large Kitchen Appliances Market Segmentation
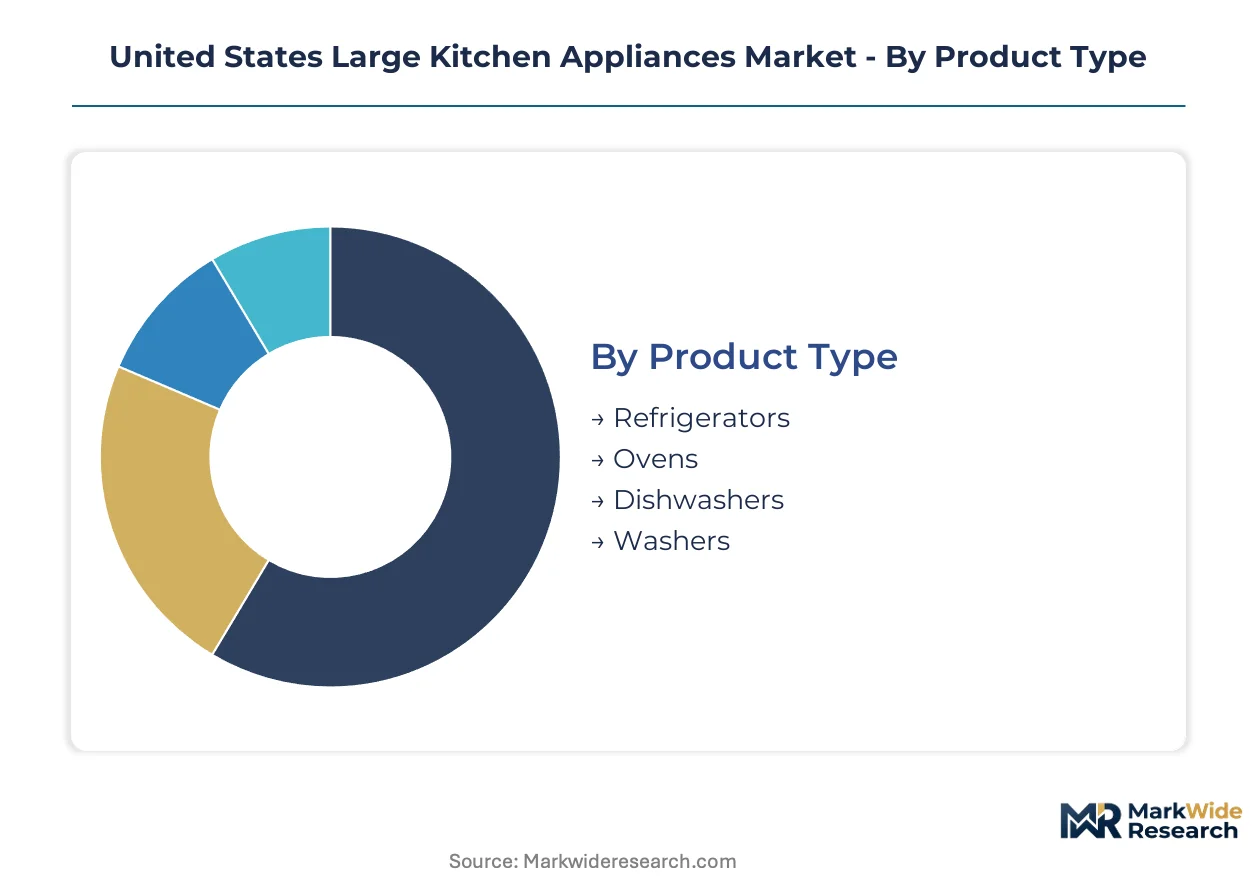
Large kitchen appliances in the United States span divergent certification pathways, with DOE efficiency standards and ENERGY STAR thresholds applying unevenly across product categories. Segmentation reveals how regulatory burden concentrates in refrigeration while commercial end-uses trigger separate durability specifications and electrical codes.
Product Type:
DOE minimum efficiency standards and EPA SNAP refrigerant regulations impose the heaviest compliance burden on refrigeration platforms, while cooking and cleaning appliances navigate CPSC safety jurisdiction and state electrification mandates.
- Refrigerators:French-door configurations with dual evaporators carry R-30 equivalent cavity insulation and hermetic compressor systems. Sun Belt residential builders in Texas and Florida specify these for extended replacement cycles and utility rebate capture in new construction corridors.
- Ovens:Induction ranges and gas cooking suites face bifurcated regulatory pressure from California Title 24 electric-ready mandates and CPSC simmer burner recall jurisdiction. Georgia metro renovation spending sustains demand for smart cooking suites with Wi-Fi protocol stacks.
- Dishwashers:ENERGY STAR certification thresholds determine market access for water-efficient thermal processing units.
- Washers:Heat-pump dryer technology convergence creates whole-home electrification bundles for California and New York retrofits.
Refrigerators sit at the top of the volume ranking, with heat-pump-enabled washers climbing the fastest.
Distribution Channel:
Channel economics vary sharply by customer acquisition cost and installation service requirements, with builder-direct models compressing traditional retail margins in high-permit Sun Belt metros.
- Online:E-commerce platforms capture subscription-enabled predictive maintenance revenue through remote diagnostic protocol stacks. Texas and Florida utility demand-response program integration drives digital procurement for Wi-Fi-enabled inventory.
- Specialty Stores:Independent dealers anchor replacement cycle demand for built-in refrigeration with extended warranty service infrastructure. California electrification retrofits concentrate in regional appliance centers with induction coil winding technical support.
- Retail Chains:Big-box footprint dominates freestanding product volume through promotional financing and mass-market SKUs.
- Direct Sales:National residential builders in Georgia consolidate master purchasing agreements for new construction pre-installation partnerships.
Retail chains maintain the widest volume footprint, with direct sales expanding most quickly through builder program consolidation.
Installation Type:
Physical integration depth determines electrical rough-in specifications, warranty exposure duration, and semiconductor-driven control system complexity across residential and commercial deployments.
- Built-in:Cabinet-integrated refrigeration and cooking suites require 240V dedicated circuits and custom panel-ready configurations. Sun Belt custom home specifications in Texas drive margin premiums for predictive maintenance subscriptions on extended-warranty platforms.
- Freestanding:Standardized dimensions and plug-and-play connectivity support rapid replacement cycles in rental housing and budget renovation segments. Florida permit velocity sustains volume throughput for 24-inch width baseline configurations.
- Smart Appliances:Wi-Fi protocol stacks with automated load-shifting capabilities capture utility-sponsored rebates from Texas to California.
- Compact:Sub-24-inch width units serve urban infill and accessory dwelling unit construction in New York and California regulatory environments.
Freestanding units dominate absolute shipment volume, with smart appliances gaining share fastest through rebate program expansion.
End User:
Durability specifications and electrical infrastructure requirements fragment supplier participation, with commercial and institutional segments demanding 208V three-phase power and accelerated service response.
- Residential:Single-family and multifamily housing drives replacement cycle timing through kitchen renovation spending and new construction permit velocity. Georgia, Texas, and Florida metro corridors concentrate demand for French-door refrigeration and smart cooking suites.
- Commercial:Restaurants and foodservice operations require above-average durability specifications and 208V three-phase electrical infrastructure that limits qualified supplier participation. California Title 24 compliance adds electric-ready rough-in mandates for new construction.
- Institutional:Schools and healthcare facilities specify ware cleaning and thermal processing equipment under federal procurement guidelines.
- Hospitality:Hotel and extended-stay properties balance guest experience aesthetics with operational energy management through ENERGY STAR-certified platforms.
Residential end-uses command the largest volume position, with commercial applications showing the steepest expansion trajectory amid electrification retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Florida-Georgia corridor anchors domestic demand for large kitchen appliances through elevated housing permit velocity and kitchen renovation spending. Residential builders in Sun Belt metro areas specify built-in refrigeration and smart cooking suites for new construction. State-level electrification mandates in California and New York reshape product specifications toward heat-pump dryers and induction ranges.
Texas
Houston and Dallas-Fort Worth residential builders compress replacement cycles for French-door refrigeration with dual-evaporator configurations. The state lacks electrification mandates, preserving dual-fuel cooking suite demand. Whirlpool Corporation's Benton Harbor supply chain serves Texas builder-direct procurement through master purchasing agreements.
Florida
Miami and Orlando permit velocity sustains volume throughput for freestanding 24-inch baseline configurations. Florida Power & Light demand-response programs drive Wi-Fi-enabled appliance penetration. Samsung Electronics anchors distribution through utility-sponsored rebate capture in the Southeast's largest housing market.
California
Los Angeles and Bay Area retrofits accelerate induction range penetration under Title 24 electric-ready rough-in mandates. The California Energy Commission enforces building efficiency codes that effectively prohibit gas appliance rough-ins in new residential construction. Heat-pump dryer technology converges with HVAC electrification bundles in Sacramento and San Diego metro corridors.
New York
New York City and Long Island kitchen renovation spending concentrates demand for compact and built-in configurations. The state's electrification mandates align with California timelines, forcing portfolio bifurcation for suppliers. GE Appliances' Louisville induction coil winding capability serves Northeast retrofit demand through regional appliance centers.
Georgia
Atlanta residential construction sustains smart cooking suite pre-installation partnerships with national builders. The state offers no electrification mandates, preserving gas cooking demand alongside electric-ready specifications. Builder-direct procurement models bypass traditional retail channels for new construction in the Atlanta-Sandy Springs-Roswell metro area.
United States Large Kitchen Appliances Market Competitive Landscape
Global majors compete with regional champions across manufacturing footprint and supply chain control dimensions. The vendor base consolidates around captive compressor production and in-house stainless steel fabrication capabilities. Three archetypes dominate: vertically integrated domestic manufacturers, Asian electronics conglomerates with semiconductor-driven control systems, and European premium specialists. Competitive moves center on backward integration into motor and compressor production and strategic partnerships with Sun Belt residential builders.
Within the domestic integrated tier, Whirlpool Corporation and GE Appliances exemplify captive manufacturing strategies. Whirlpool leverages Benton Harbor operations for compressor assembly capacity. GE Appliances anchors Louisville with in-house stainless steel fabrication and induction coil winding. Among Asian electronics conglomerates, Samsung Electronics occupies a position emphasizing vertical control over semiconductor-driven inverter modules.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| GE Appliances |
| LG Electronics |
| Samsung Electronics |
| Bosch Home Appliances |
| Haier U.S. Appliance Solutions |
| Electrolux Major Appliances |
| Panasonic |
| Miele |
| Others |
Value Network & Pricing Analysis
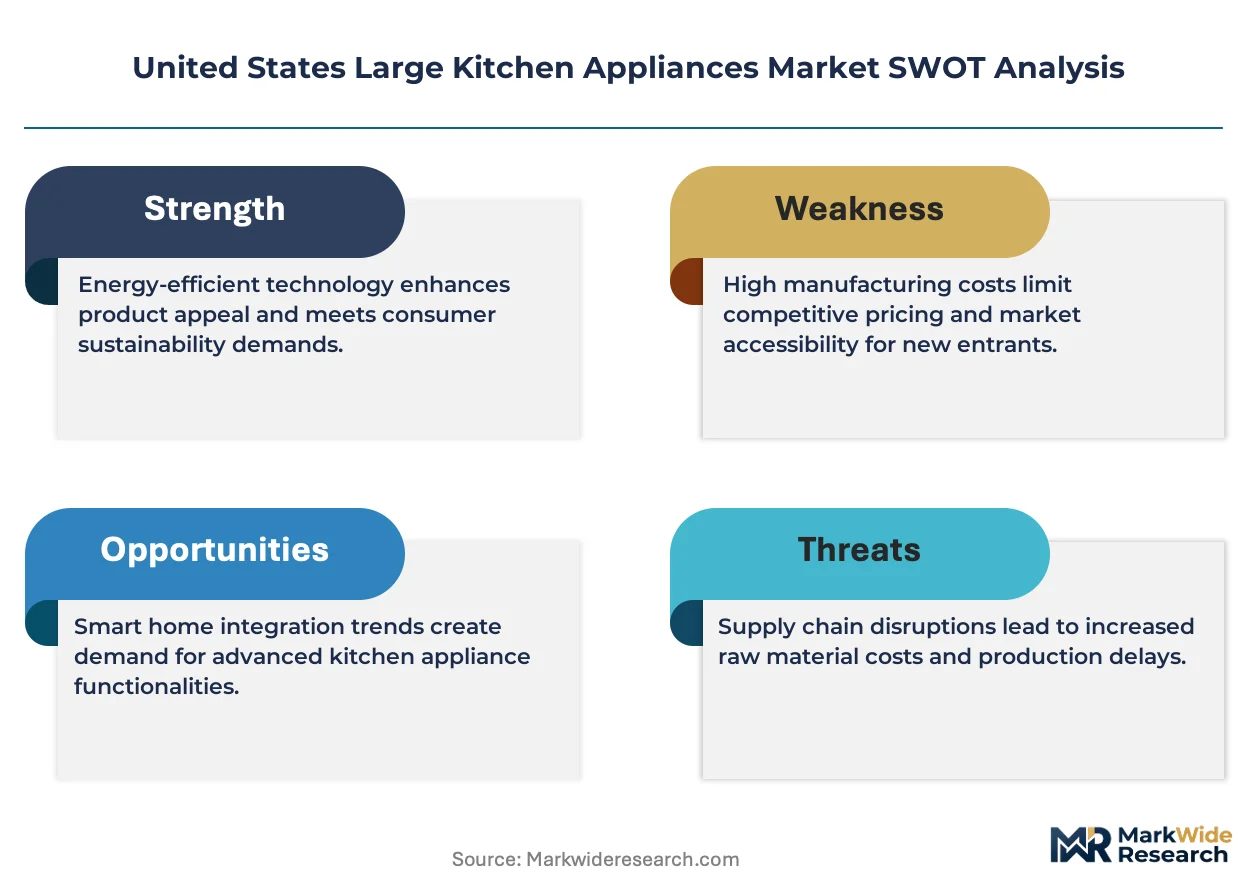
EPA SNAP hydrofluorocarbon phase-down mandates gate qualified supply for hermetic refrigeration systems and reserve premium-tier pricing access to manufacturers with captive compressor production and accelerated life testing infrastructure. This environmental compliance burden stratifies the vendor base between integrated domestic producers and import-dependent competitors exposed to R&D timeline compression and premature platform redesign costs.
Pricing Analysis
Stainless steel spot price pass-through from commodity markets shapes three-tier pricing structure across premium, standard, and economy levels. ENERGY STAR certification thresholds and DOE efficiency standards drive price differentiation between compliant and non-compliant product lines, with California Title 24 electric-ready specifications commanding installation service premiums. Cost compression in mid-tier freestanding configurations is intensifying because semiconductor-driven inverter module shortages constrain output. Residential builders in Texas and Florida exhibit lowest price sensitivity for built-in refrigeration with predictive maintenance subscriptions, while rental housing operators in budget renovation segments remain most price-sensitive.
Supply Chain Analysis
Direct-to-builder channels handle Sun Belt residential construction demand through master purchasing agreements with installation and warranty integration. Domestic captive production at Benton Harbor and Louisville anchors supply, yet semiconductor fabrication in Taiwan, South Korea, and Japan feeds inverter module dependencies for Chef Collection-tier refrigeration. Hermetic compressor systems draw from specialized motor winding operations concentrated in Mexico and China, exposing suppliers to tariff exposure on electromagnetic component imports. Distribution runs through big-box retail chains for freestanding volume, specialty dealers for replacement cycle service, and builder-direct procurement for new construction pre-installation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States large kitchen appliances market functions as a stable compounder, with residential construction permit velocity in Sun Belt states driving replacement cycle compression that sustains steady demand growth across economic cycles.
For Market Incumbents: Deploy captive compressor production capacity as a defensive moat against semiconductor-driven inverter module shortages that constrain premium-tier output. Deepen backward integration into induction coil winding and stainless steel fabrication to mitigate commodity price volatility exposure. Consolidate builder-direct procurement relationships in Texas, Florida, and Georgia to defend against Asian electronics conglomerates capturing utility rebate program share through Wi-Fi-enabled inventory. For New Entrants and Emerging Players: Capture white-space in heat-pump dryer technology convergence for California and New York whole-home electrification retrofits where incumbent portfolios remain gas-weighted. Target compact sub-24-inch configurations for urban infill and accessory dwelling unit construction in New York and California regulatory environments. Pursue go-to-market partnerships with regional appliance centers offering induction coil winding technical support rather than competing through mass retail channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier competitors exposed to stainless steel input volatility and lacking in-house fabrication capabilities. The five-to-ten year viability window favors manufacturers with vertical control over semiconductor-driven control systems and hermetic compressor assembly. Monitor EPA SNAP refrigerant phase-down compliance timelines as the inflection signal for R&D budget strain and premature platform redesign costs that will accelerate vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Compressor Production Expansion | Benton Harbor and Louisville operations anchor domestic hermetic system supply against import dependency. |
| Heat-Pump Dryer Technology Convergence | Integration with HVAC electrification bundles captures California and New York retrofit mandates. |
| Predictive Maintenance Subscription Launch | Remote diagnostic protocol stacks enable recurring revenue from Sun Belt built-in refrigeration installations. |
| Builder-Direct Procurement Consolidation | Master purchasing agreements with national residential builders bypass traditional retail margin compression. |
| Induction Coil Winding Capability Investment | In-house electromagnetic component assembly mitigates technician scarcity and supports electrification demand. |
Research Methodology
Multiple input streams — primary interviews with appliance manufacturing executives, residential builder procurement directors, and utility demand-response program managers, alongside secondary validation through DOE certification databases, EPA SNAP regulatory filings, and housing permit velocity data from the Census Bureau — were reconciled through bottom-up shipment modeling and top-down market sizing triangulation.
Historical shipment trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across product type, distribution channel, installation type, and end user segmentation dimensions throughout the forecast period. CAGRs were derived from regression analysis of replacement cycle timing, new construction permit correlations, and electrification mandate implementation schedules, with specific weighting applied to semiconductor supply constraints and refrigerant chemistry transition timelines.
Regulatory enforcement variance, commodity price volatility, and supply chain disruption severity are the dominant revision risks that could materially alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Commercial Tabletop Kitchen Products Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Induction Hobs Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
Global Baking Tools Market