
 Europe Small Kitchen Appliances Market | 2026-2036
Europe Small Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Kitchen Appliances Market Foresight
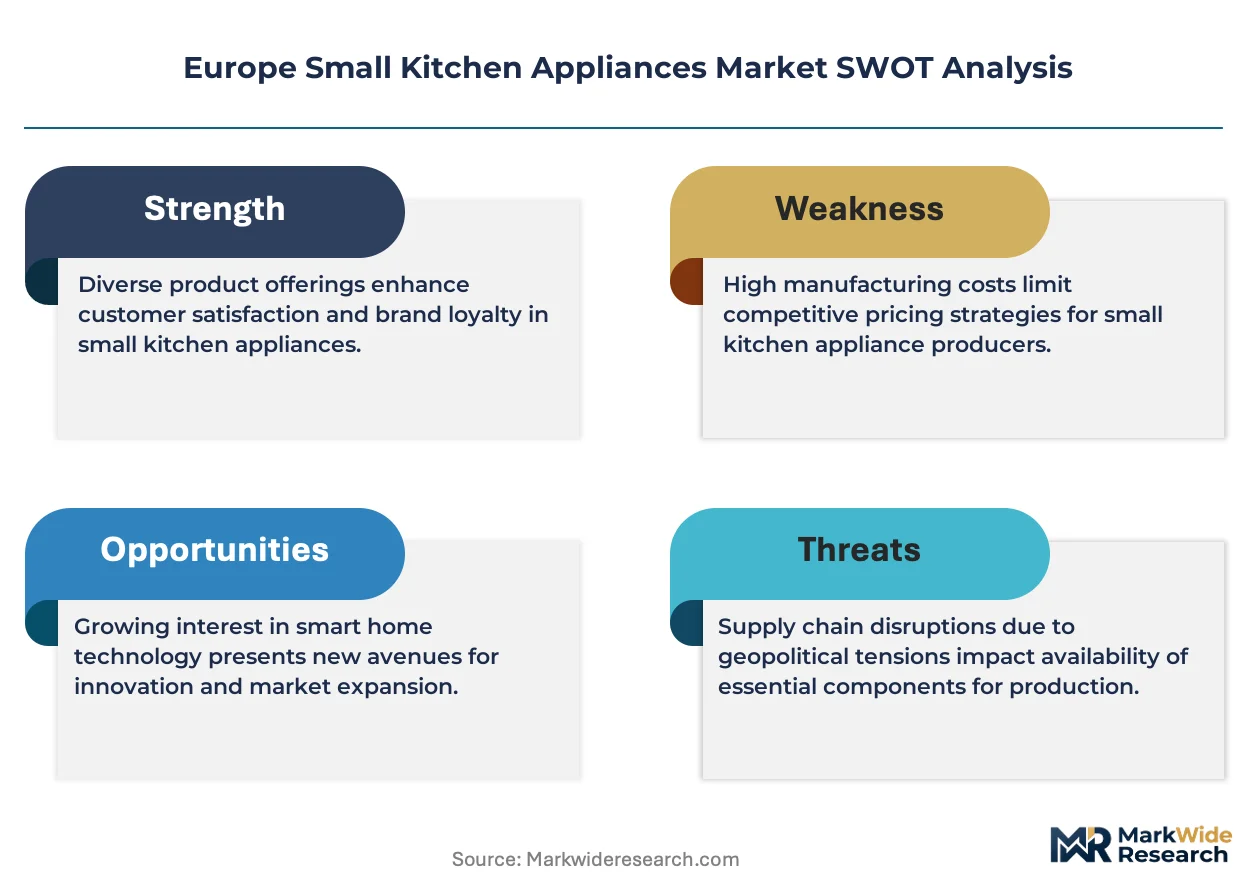
Specialty kitchen retail across Europe is tilting toward direct-to-consumer platforms and curated showroom experiences. Robert Bosch GmbH leverages its German engineering heritage to sustain premium positioning in built-in coffee systems. Groupe SEB anchors volume through broad brand portfolio coverage spanning mass-market to professional tiers. De'Longhi S.p.A. specializes in espresso machine craftsmanship that commands loyalty among Mediterranean consumer bases.
Small kitchen appliances encompass electrically powered countertop devices operating at 220-240V with rated capacities typically below 2,500 watts, designed for food preparation, beverage production, or cooking assistance in domestic and light-commercial settings. Coffee Makers lead value generation due to ritual-driven replacement cycles and pod-system lock-in effects, while Smart Appliances represent the fastest-expanding technology dimension as Wi-Fi connectivity and app-based recipe integration become standard expectations rather than premium differentiators. Multi-Functional units capture margin pools by collapsing multiple single-purpose devices into space-efficient formats suited to European urban kitchens.
CE marking under EU safety directives, REACH chemical compliance for plastic and coating components, and the EU Ecodesign Directive together elevate baseline manufacturing costs while blocking non-compliant imports from third-country suppliers. The EU Green Deal's extended producer responsibility requirements are reshaping end-of-life collection and recyclability obligations across the value chain. Stakeholders must monitor whether pending right-to-repair legislation alters warranty structures and spare-part availability timelines.
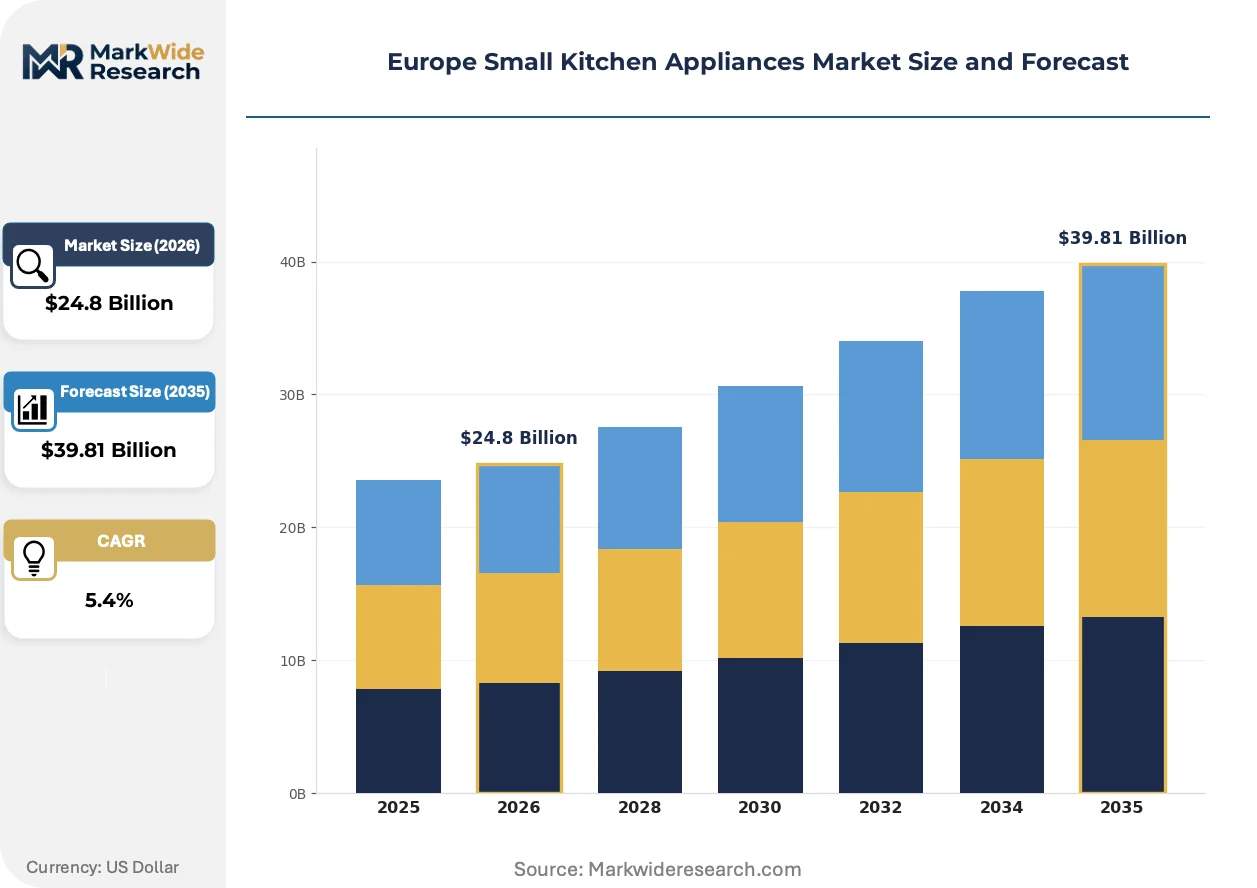
Market Dynamics
The EU Ecodesign Directive and REACH compliance mandates are compressing margins while forcing component redesigns across European small kitchen appliance supply chains. Manufacturers must absorb elevated testing costs and material substitution expenses to maintain market access.
Growth Catalysts
- Urban Compact Living:French and German metropolitan households prioritize space-efficient multifunctional appliances. Kitchen footprint constraints drive electric tool adoption over manual alternatives.
- REACH Chemical Compliance:Restrictions on hazardous substances in plastics and coatings accelerate material innovation. Suppliers investing early in compliant chemistries capture preferential sourcing relationships.
- Wi-Fi Connectivity Integration:Smart appliance functionality shifts from premium tier to baseline expectation. App-based recipe synchronization and remote operation become standard specification requirements.
Market Restraints
- CE Marking Certification Burden:Third-country suppliers face extended timeline and cost barriers for EU safety directive compliance. Non-European manufacturers struggle with documentation and testing facility access.
- Pod-System Lock-in Effects:Proprietary coffee capsule ecosystems create switching costs that limit competitive entry. Established brands maintain installed base advantages through format exclusivity.
- Extended Producer Responsibility:EU Green Deal end-of-life collection obligations impose reverse logistics infrastructure investments. Smaller manufacturers lack capital for compliant recycling network development.
Strategic Opportunities
- Right-to-Repair Legislation:Pending warranty and spare-part availability mandates create aftermarket service revenue streams. Manufacturers can monetize repair ecosystems and component subscription models.
- Mediterranean Espresso Loyalty:Italian and Spanish consumer bases demonstrate brand attachment to craftsmanship positioning. Premium manual-machine segments resist commoditization pressure.
- Direct-to-Consumer Platforms:Specialty kitchen retail channels fragment toward curated showroom and digital-native experiences. Brands bypass wholesale margin compression through owned-channel development.
Industry Challenges
- Embedded Systems Engineering Talent:Connected appliance development requires scarce firmware and IoT security expertise. European manufacturers compete with automotive and industrial sectors for equivalent skill profiles.
- Legacy Supply Chain Reconfiguration:Decades-old component sourcing relationships resist rapid sustainability pivot. Existing supplier contracts lock in non-recyclable material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Kitchen Appliances Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toasters, Blenders, Coffee Makers, Food Processors End User: Residential, Commercial, Professional Chefs, Catering Services Technology: Smart Appliances, Manual Appliances, Energy Efficient, Multi-Functional Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Miele and Cie. KG, Robert Bosch GmbH, BSH Hausgerate GmbH, Smeg, De'Longhi S.p.A., Electrolux Group, Whirlpool Corp., AGA Rangemaster Ltd., Groupe SEB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Kitchen Appliances Market Shifts & Advancements
Digital recipe ecosystems and energy efficiency mandates are converging to redefine product value propositions in European small kitchen appliances. Manufacturers now compete on software integration and carbon footprint credentials rather than standalone mechanical performance.
Smart control interfaces are virtualizing traditional appliance operation. Cloud-connected cooking programs enable remote monitoring and automated parameter adjustment. German and French early adopters integrate these systems into smart home ecosystems at accelerating rates. This capability is virtualizing the boundary between hardware manufacturer and food service platform.
The EU Ecodesign Directive tightens standby power and material efficiency requirements through 2027 implementation timelines. Manufacturers must redesign heating elements and motor assemblies to meet descending consumption thresholds. Coffee maker and food processor segments face the most aggressive phase-out schedules for non-compliant inventory.
Subscription-based consumable replenishment is displacing traditional retail purchasing for pod-system owners. Italian and Spanish households increasingly automate capsule delivery through manufacturer-direct programs. This behavioral shift concentrates lifetime value capture with original equipment suppliers and weakens third-party compatible capsule penetration.
Europe Small Kitchen Appliances Market Segmentation
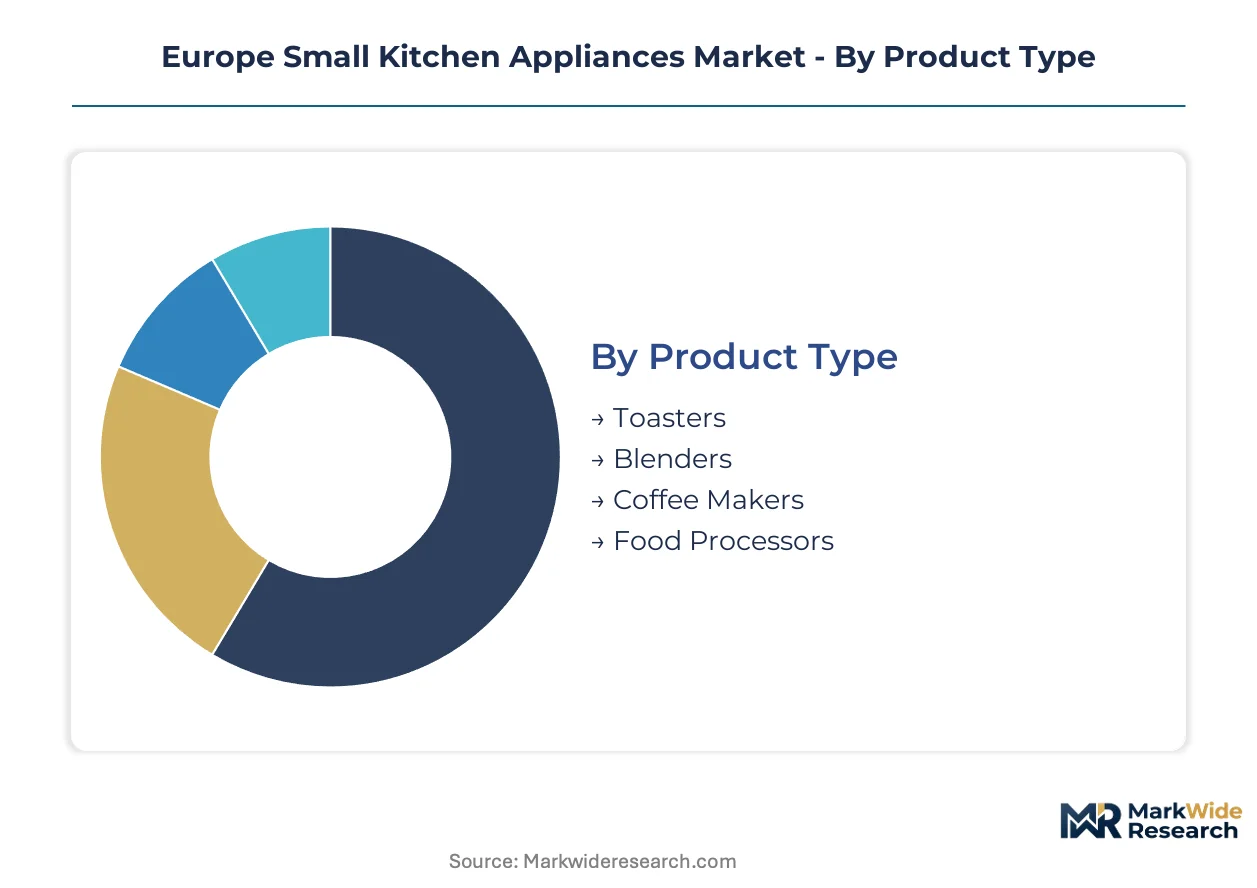
European small kitchen appliance purchasing splits along four distinct axes that reshape go-to-market economics. Product type determines replacement cadence and margin structure. Technology tier separates premium positioning from commodity exposure. Distribution channel selection dictates customer acquisition cost and brand control intensity.
Product Type:
Mature segments dominate installed base while emerging formats capture renovation-driven replacement cycles.
- Coffee Makers:Electric brewing systems operating at 220-240V with integrated heating elements and pump mechanisms. German and French metropolitan households drive premium espresso machine demand through ritual-driven morning consumption habits. Pod-system lock-in effects sustain recurring revenue streams for incumbent suppliers.
- Food Processors:Motor-driven countertop units with interchangeable blade assemblies for slicing, grating, and emulsification. Compact urban kitchens in Paris and Milan prioritize multi-bowl configurations that collapse multiple manual tools into single footprint appliances. Motor durability and safety interlock reliability determine replacement timing.
- Toasters:Resistive heating element appliances with browning control circuits. Breakfast preparation frequency in Northern European markets sustains steady replacement demand for entry-level and mid-tier units.
- Blenders:High-speed blade systems for liquid and semi-solid food preparation. Smoothie consumption trends in Spanish and Portuguese markets drive personal-format unit adoption.
Coffee Makers handle the majority of throughput; Food Processors are expanding most quickly on share.
End User:
Volume concentration sits with domestic purchasers while margin accretion flows toward commercial specifications.
- Residential:Individual household procurement for daily food preparation and beverage production. French and German urban apartments prioritize compact multifunctional units that maximize utility per square meter of counter space. CE marking compliance and energy labeling transparency influence purchase decisions.
- Commercial:Small business deployment in cafés, bakeries, and casual dining establishments. Italian espresso bar operators demand commercial-grade brewing systems with rapid recovery boilers and volumetric dosing. Durability specifications and service network proximity override upfront cost considerations.
- Professional Chefs:High-intensity usage in restaurant kitchens and culinary training facilities. Precision temperature control and continuous-duty motor ratings differentiate specification requirements from residential equivalents.
- Catering Services:Mobile and event-based food service operations requiring transportable equipment with rapid setup capabilities. Portability and power flexibility constraints shape product selection.
Residential captures the volume base; Commercial yields the steepest margin expansion.
Technology:
Connectivity integration is climbing the fastest while efficiency mandates force baseline redesign across all tiers.
- Smart Appliances:Wi-Fi-enabled devices with cloud-connected recipe synchronization and remote parameter control. German early adopters integrate these systems into broader smart home ecosystems at accelerating rates. Firmware update capability and data security architecture become competitive differentiators.
- Multi-Functional:Collapsed-format appliances combining multiple preparation modes into single footprint units. Space-constrained urban kitchens in Amsterdam and Brussels drive demand for units replacing three or more single-purpose devices. Component modularity and cleaning accessibility determine user satisfaction.
- Energy Efficient:EU Ecodesign Directive-compliant designs with reduced standby consumption and optimized heating element performance. REACH-compliant material specifications add compliance cost layer.
- Manual Appliances:Non-electric tools for food preparation without power dependency. Premium craftsmanship positioning in Mediterranean markets resists full electrification.
Multi-Functional carries the replacement momentum; Smart Appliances are gaining share fastest on technology upgrade cycles.
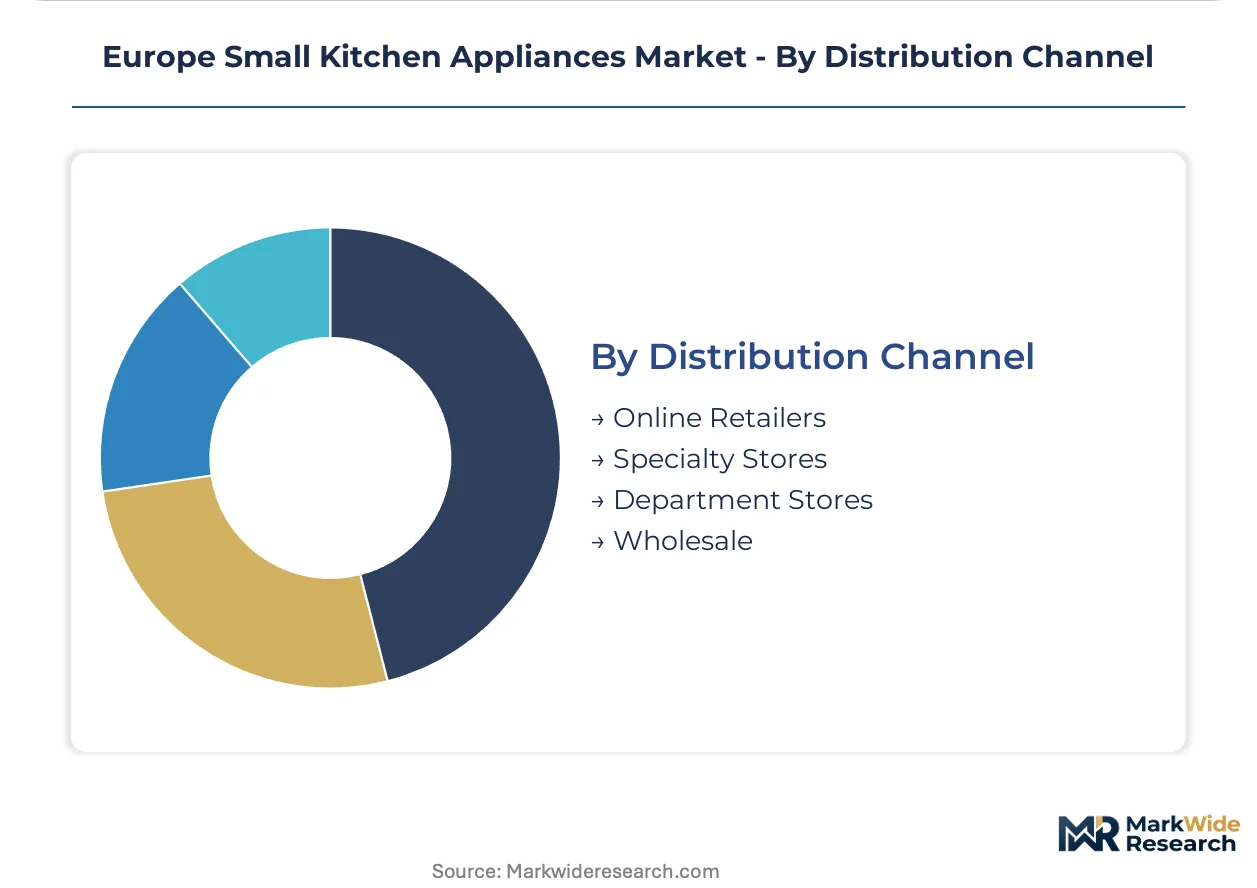
Distribution Channel:
Channel fragmentation accelerates as direct relationships disintermediate traditional wholesale structures.
- Online Retailers:Digital-native platforms with algorithmic recommendation engines and subscription-based consumable bundling. Italian and Spanish pod-system owners increasingly automate capsule replenishment through manufacturer-direct portals. Customer data ownership shifts margin capture toward original equipment suppliers.
- Specialty Stores:Curated showroom experiences with hands-on demonstration capability and staff technical expertise. German engineering-focused brands leverage these venues to sustain premium positioning against mass-market alternatives.
- Department Stores:Multi-category retail environments with seasonal promotional calendars and gift-oriented merchandising. Holiday purchasing concentration in French and UK markets sustains this channel's relevance for entry-tier gifting.
- Wholesale:Business-to-business procurement networks serving commercial and catering end users. Volume pricing structures and extended payment terms accommodate capital-constrained small business customers.
Online Retailers absorb the volume migration; Specialty Stores defend the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metropolitan households command premium pricing for built-in coffee systems, while Polish and Romanian markets absorb entry-tier volume through price-sensitive retail channels. This asymmetry concentrates margin capture in Western European engineering clusters while Eastern European expansion drives unit growth.
Germany
Urban households in Berlin and Munich prioritize multifunctional appliances that maximize utility per square meter of counter space. The EU Ecodesign Directive forces standby power reductions across heating-element product lines. Baden-Württemberg engineering clusters anchor precision manufacturing for premium espresso machine components.
France
Parisian apartment dwellers drive demand for collapsed-format devices replacing multiple single-purpose tools. REACH chemical compliance mandates accelerate material substitutions in plastic housing production. The Île-de-France region concentrates specialty kitchen retail showroom development for hands-on demonstration experiences.
Italy
Mediterranean espresso consumption rituals sustain loyalty to craftsmanship-positioned manual machine segments. Pending right-to-repair legislation alters warranty structures for commercial-grade brewing systems. Milan and Turin industrial districts specialize in high-pressure pump mechanism fabrication for professional-tier equipment.
United Kingdom
London metropolitan kitchens favor smart appliance integration with broader home automation ecosystems. CE marking certification requirements block non-compliant third-country imports from penetrating British market channels post-regulatory divergence. The Southeast England corridor hosts direct-to-consumer platform development for subscription-based consumable replenishment.
Spain
Barcelona and Madrid households demonstrate accelerating adoption of Wi-Fi-connected recipe synchronization features. Extended producer responsibility obligations under the EU Green Deal impose reverse logistics investments for end-of-life collection networks. Catalan manufacturing zones produce compact personal-format blenders for Iberian smoothie consumption trends.
Europe Small Kitchen Appliances Market Competitive Landscape
Engineering-heritage conglomerates and broad-portfolio holding groups split the market into distinct competitive spheres. Consolidation pressure intensifies as compliance costs under REACH and the EU Ecodesign Directive disadvantage capital-constrained mid-tier participants. Two strategic archetypes dominate: precision-engineering specialists leveraging German manufacturing credibility, and multi-brand portfolio operators capturing volume across price tiers. Dominant competitive moves include direct-to-consumer platform development and subscription-based consumable lock-in strategies.
Within the engineering-specialist tier, Robert Bosch GmbH and Miele and Cie. KG exemplify precision-manufacturing positioning rooted in German industrial heritage. Groupe SEB occupies a position as the archetypal multi-brand portfolio operator, spanning mass-market accessibility through professional-tier specifications. De'Longhi S.p.A. represents Mediterranean craftsmanship specialization, anchoring espresso machine loyalty among ritual-driven consumer bases. These three entities collectively illustrate the competitive segmentation between engineering credibility, portfolio breadth, and regional craftsmanship positioning.
| Leading Market Players |
|---|
| Miele and Cie. KG |
| Robert Bosch GmbH |
| BSH Hausgerate GmbH |
| Smeg |
| De'Longhi S.p.A. |
| Electrolux Group |
| Whirlpool Corp. |
| AGA Rangemaster Ltd. |
| Groupe SEB |
| Others |
Supply & Pricing Matrix
Undercapacity in precision motor manufacturing across Baden-Württemberg and Lombardy clusters is forcing appliance OEMs into longer lead-time commitments and prepayment structures, compressing working capital flexibility while elevating configured-to-order premiums for high-specification espresso and food processing units.
Pricing Analysis
The customization-premium spread between standard countertop appliances and configured-to-order built-in systems widens to reflect engineering labor and component specificity. Pricing stratifies across premium craftsmanship-positioned, standard multifunctional, and economy entry-tier levels, with CE marking tier and motor durability rating as primary differentiation drivers. Cost compression in economy tiers is intensifying because Chinese suppliers are absorbing REACH compliance overhead to maintain volume access. Residential apartment purchasers in Paris and Berlin show highest price sensitivity, while Italian commercial espresso operators demonstrate lowest sensitivity due to recovery boiler reliability requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Tier 1 injection molders serving the housing segment, with supply-chain finance facilities bridging cash-flow gaps for mid-tier component suppliers. Manufacturing concentrates in Germany, Italy, and Poland, with precision pump mechanisms sourced from Milan-Turin industrial districts and motor assemblies from Baden-Württemberg. Raw material dependencies center on REACH-compliant engineering plastics, copper motor windings, and stainless steel heating elements. Single-source vulnerability sits with high-pressure pump suppliers for professional espresso systems. Distribution runs through direct-to-consumer platforms, specialty kitchen retail, and wholesale networks serving commercial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European small kitchen appliances sit in early-cycle expansion as Wi-Fi connectivity integration shifts from premium tier to baseline expectation, accelerating replacement cycles across German and French metropolitan households.
For Market Incumbents: Insulate installed base advantages by deepening captive supply of precision pump mechanisms through backward integration into Milan-Turin supplier networks. Accelerate firmware update infrastructure investment to defend against software-native entrants targeting smart home ecosystem integration. Lock in component subscription revenue through automated consumable replenishment platforms before right-to-repair mandates alter warranty economics.
For New Entrants and Emerging Players: Polish and Romanian secondary cities present underpenetration for entry-tier multifunctional appliances as urban renovation cycles accelerate. Target commercial catering segments in Iberia with portable, rapid-setup equipment formats underserved by incumbent focus on fixed-installation systems. Enter through wholesale distribution partnerships offering extended payment terms to capital-constrained small business operators.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pod-system operators with manufacturer-direct replenishment platforms, positioning these archetypes for premium valuation multiples. Long-term viability favors portfolio breadth across mass-market through professional tiers rather than single-segment concentration. Monitor right-to-repair legislative passage as inflection signal for aftermarket service revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Bypasses wholesale margin compression while capturing customer data ownership from Italian and Spanish pod-system households. |
| Smart Home Ecosystem Integration | Positions appliances as nodes within German and UK home automation architectures, virtualizing hardware boundaries. |
| REACH-Compliant Material Transition | Secures preferential sourcing relationships with EU-based injection molders ahead of Ecodesign Directive phase-out schedules. |
| Aftermarket Service Network Buildout | Monetizes pending right-to-repair mandates through component subscription and repair ecosystem revenue streams. |
| Multi-Functional Product Line Extension | Captures Paris and Amsterdam kitchen footprint constraints through collapsed-format appliances replacing multiple single-purpose devices. |
Research Methodology
The analysis maps coffee maker, food processor, toaster, and blender sub-sectors, each validated through category buyers at specialty retailers, procurement leads at mass-market distributors, R&D directors at appliance manufacturers, and regulatory affairs specialists at industry associations. Primary interview findings triangulate against EU Ecodesign Directive implementation documents, REACH chemical restriction updates, customs import records for small appliance categories, and SEC filings from publicly traded holding companies. Bottom-up unit shipment estimates from distribution channel partners reconcile with top-down consumer expenditure data from national statistical offices.
The forecast framework holds EU regulatory timelines and Wi-Fi adoption curves as fixed boundary conditions while varying replacement cycle assumptions and smart home penetration rates across the projection horizon. Segmentation dimensions include product type, technology tier, end-user category, and distribution channel, with regional regulatory cluster as an additional modeled dimension. CAGRs derive from fitted adoption curves applied to replacement-driven demand pools. Industry-specific inputs incorporate Ecodesign Directive standby power phase-out schedules and pod-system installed base conversion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese suppliers absorbing compliance costs or software-native entrants bypassing hardware manufacturing would shift outcomes. Macroeconomic deviation in European consumer confidence, regulatory acceleration of right-to-repair mandates, or technological breakthrough in solid-state heating elements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
Built-In Coffee Machine Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
US Induction Cookware Market