
 Colombia Kitchen Appliances Market | 2026-2036
Colombia Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Kitchen Appliances Market Outlook
Colombia's energy efficiency labeling mandate is restructuring the cost-of-entry calculus for appliance manufacturers serving the domestic market. Industrias HACEB SA leverages its Bogotá manufacturing base to control distribution across Andean corridors. Mabe de Colombia SA anchors the mid-range refrigerator segment through captive production of compressor systems. Whirlpool Colombia competes on brand recognition while navigating import tariff schedules on finished goods.
Colombia kitchen appliances comprise electrically or gas-powered equipment designed for food preservation, preparation, and cooking, typically operating at 110V/60Hz with energy consumption ratings measured in kilowatt-hours annually. These products serve residential and commercial end users requiring thermal control, mechanical refrigeration cycles, or electromagnetic induction heating for daily food service operations. Refrigerators command the largest installed base among product types due to universal household penetration requirements across climate zones. Smart appliances represent the fastest-growing technology segment as connectivity modules integrate with residential energy management platforms. The residential end-user category sustains the deepest volume pool, though hospitality procurement generates higher per-unit margins through specification-grade equipment demands.
Colombia's Superintendencia de Industria y Comercio enforces consumer protection standards while the Instituto Colombiano de Normas Técnicas y Certificación (ICONTEC) administers product safety certifications including electrical and gas appliance compliance. The Unidad de Planeación Minero Energética mandates energy labeling that directly shapes manufacturer design priorities and consumer purchasing comparisons at retail. Stakeholders must monitor regulatory alignment between national efficiency targets and import duty structures that favor local assembly operations over fully finished imports.
Market Dynamics
Colombia's mandatory energy labeling regime under the Unidad de Planeación Minero Energética is restructuring manufacturer design priorities and retail assortment strategies across the Andean corridor. Local assembly operations now command tariff advantages over finished imports, reshaping competitive entry economics.
Growth Catalysts
- Energy Efficiency Mandates:The Unidad de Planeación Minero Energética labeling requirements accelerate consumer upgrade cycles toward certified efficient equipment in Bogotá and Medellín metropolitan zones.
- Urban Middle-Class Expansion:Residential households across Colombia's Andean region are replacing legacy cooking equipment with induction and gas-efficient alternatives.
- Local Assembly Incentives:Import duty structures favor domestic production operations, reducing landed cost disadvantages for regionally manufactured refrigeration and cooking systems.
Market Restraints
- Copper and Steel Input Volatility:Compressor manufacturing and chassis fabrication face raw material price swings that compress margin predictability for domestic producers.
- Import Dependency for Electronic Components:Control modules and inverter drives concentrate sourcing from Asian suppliers, exposing assemblers to currency fluctuation and logistics disruption.
- 110V/60Hz Technical Isolation:Colombia's electrical standard limits cross-border product portability with neighboring 220V markets, fragmenting production scale economies.
Strategic Opportunities
- Smart Appliance Connectivity:Integration with residential energy management platforms creates premium positioning for WiFi-enabled refrigeration and cooking equipment in upper-middle segments.
- Pacific Coast Urbanization:Cali and Buenaventura corridor development expands addressable household formation beyond traditional Andean demand concentration.
- Commercial Kitchen Specification:Hospitality procurement for hotels and restaurant chains generates higher per-unit margins through durable, high-duty-cycle equipment requirements.
Industry Challenges
- ICONTEC Certification Timelines:Electrical and gas safety approvals create product launch delays that mismatch seasonal retail planning cycles.
- Technician Training Gaps:Inverter compressor diagnostics and smart module servicing require specialized skills scarce in secondary city service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Kitchen Appliances Market |
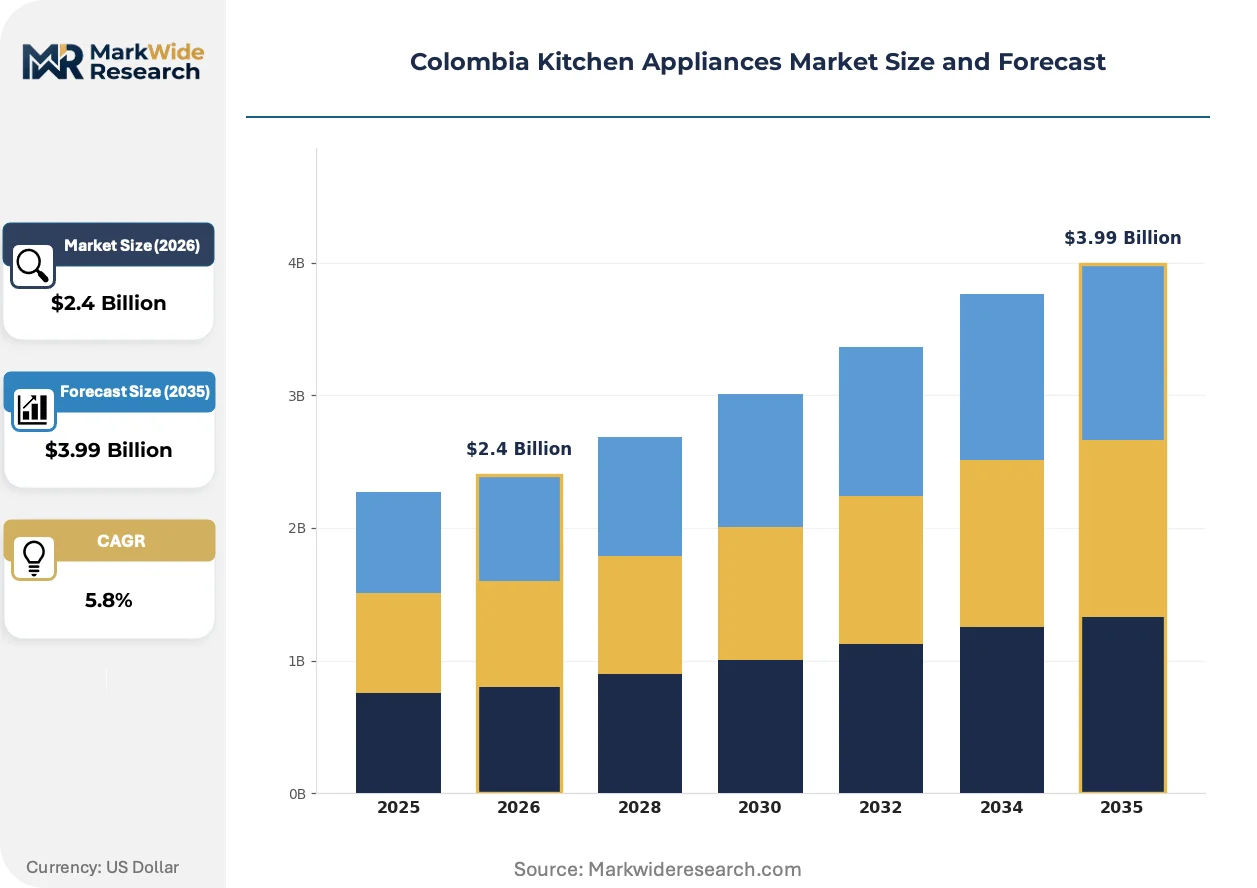
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Cooktops, Microwaves Technology: Smart Appliances, Energy-Efficient, Conventional, Induction End User: Residential, Commercial, Hospitality, Institutional Distribution Channel: Retail Stores, E-Commerce, Direct Sales, Wholesalers |
| Companies Covered | Whirlpool Colombia, Industrias HACEB SA, GE Appliances, LG Electronics, Samsung Electronics, Panasonic Corporation, Mabe de Colombia SA, KitchenAid, Electrolux Colombia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Kitchen Appliances Market Strategic Shifts
Connectivity modules and energy management integration are redefining product architecture in Colombia's appliance sector. Manufacturers now compete on software-enabled efficiency optimization rather than hardware specifications alone.
Inverter compressor technology is consolidating market share across mid-range and premium refrigeration segments. Residential buyers in Bogotá and Medellín prioritize variable-speed cooling systems that reduce kilowatt-hour consumption. This shift is compressing demand for conventional fixed-speed compressor platforms and forcing component suppliers to retool production lines.
The Unidad de Planeación Minero Energética labeling mandate tightens efficiency thresholds annually, accelerating product obsolescence cycles. Manufacturers must redesign thermal systems and insulation specifications to maintain retail placement. Refrigeration categories face the steepest compliance gradients, driving consolidation toward suppliers with captive compressor and insulation capabilities.
Urban households are compressing replacement cycles for cooking equipment from decade-long intervals to five-to-seven year horizons. Retail channels in Medellín and Cali report accelerated trade-ins of conventional gas ranges for induction and hybrid systems. This behavioral pivot concentrates in new construction and renovation segments where electrical infrastructure upgrades accompany appliance procurement.
Colombia Kitchen Appliances Market Segmentation
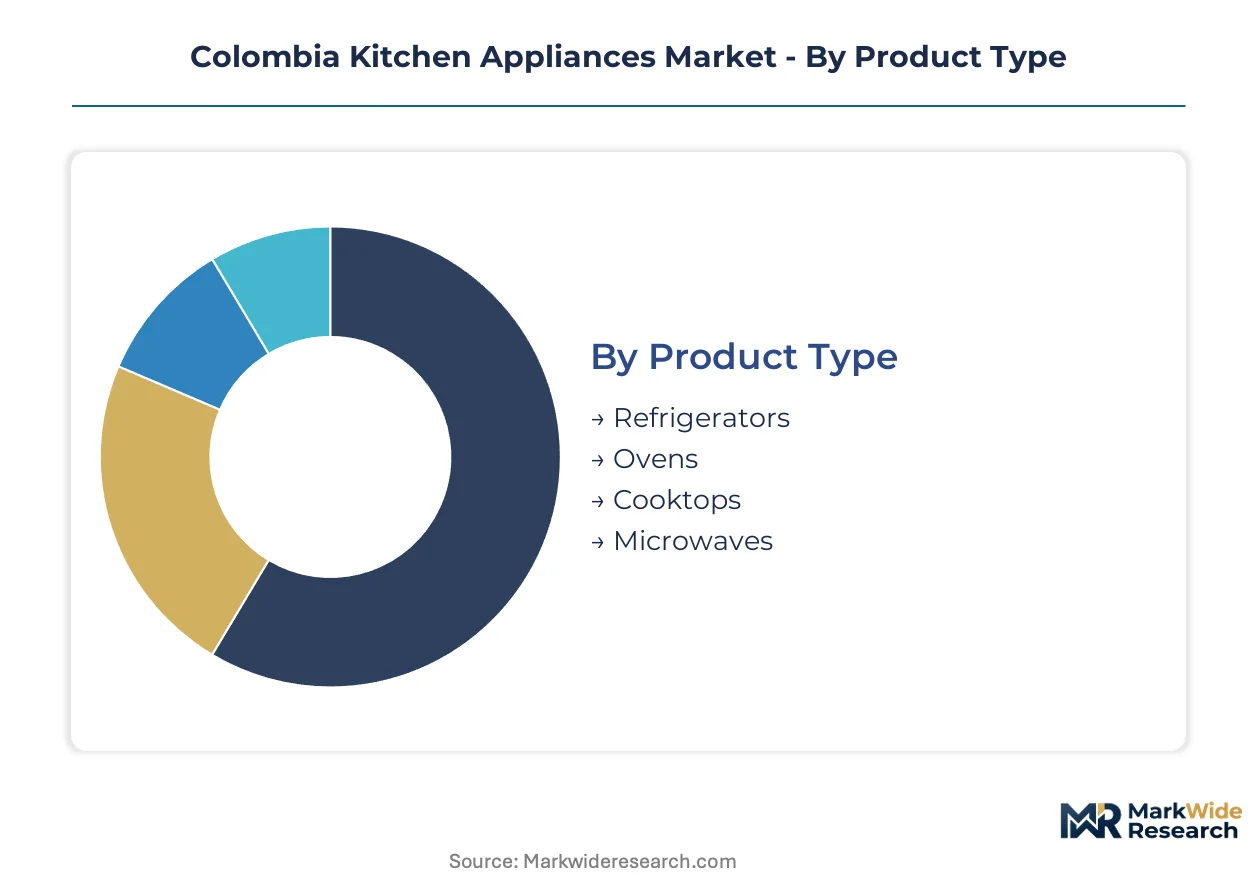
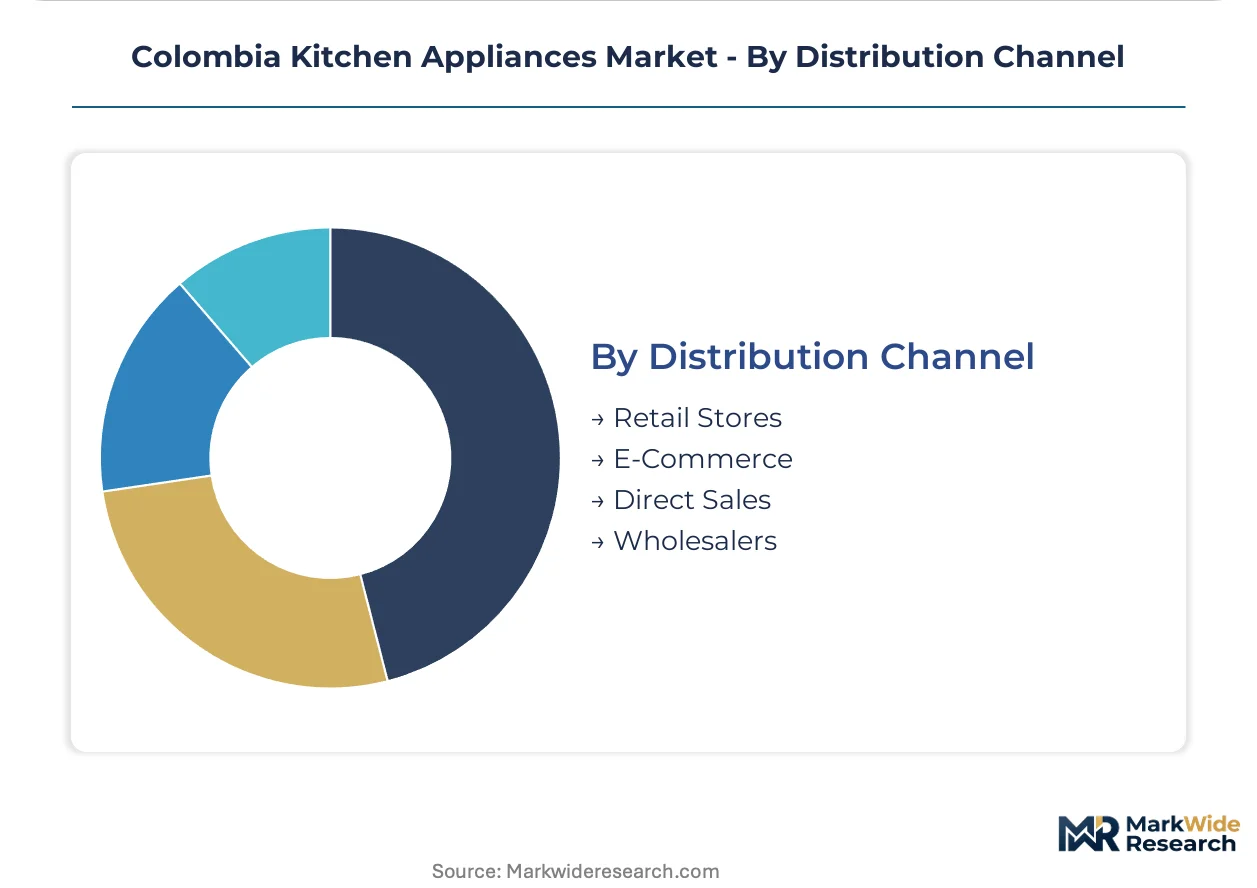
Colombia's kitchen appliance segmentation reflects the interplay between energy regulations, urban infrastructure, and channel evolution. Manufacturers calibrate product portfolios across four intersecting dimensions to capture value in Bogotá and Medellín's upgrade cycles.
Product Type:
Refrigeration and cooking platforms anchor the technical specification hierarchy, with efficiency mandates driving differential design investments across categories.
- Refrigerators:Compression-based thermal systems with variable-speed inverter drives dominate volume. Demand concentrates in Bogotá middle-class households replacing fixed-speed units under UPME labeling pressure.
- Ovens:Convection and gas-thermal configurations serve residential baking demand. Medellín's renovation segment drives replacement of legacy units with convection alternatives.
- Cooktops:Gas burner and induction coil platforms for surface cooking. Cali's new construction corridor absorbs hybrid gas-induction specifications.
- Microwaves:Magnetron-based rapid heating units for defrosting and reheating. Secondary city retail channels move entry-level countertop configurations.
Mature deployment sits with refrigerators. Newer deployment is concentrated in induction-enabled cooktops.
Technology:
Energy performance certification and connectivity modules now separate price tiers, with regulatory pressure accelerating migration from legacy platforms.
- Smart Appliances:WiFi-enabled units with energy management platform integration. Upper-middle households in Bogotá's northern districts adopt connected refrigeration for demand-response utility programs.
- Energy-Efficient:UPME-certified equipment meeting escalating kWh/year thresholds. Retail assortment in Medellín now requires certification for premium placement.
- Conventional:Fixed-speed compressors and standard insulation without connectivity modules. Price-sensitive segments in secondary Andean cities sustain residual demand.
- Induction:Electromagnetic coil cooking with rapid thermal response and efficiency gains. Pacific coast urbanization in Cali accelerates electrical infrastructure upgrades enabling adoption.
Conventional platforms retain installed base dominance. Induction and smart configurations are climbing the fastest as replacement cycles compress.
End User:
Volume concentration and margin structure diverge sharply between residential mass markets and specification-driven commercial procurement.
- Residential:Household units for daily food preservation and preparation. Andean urban middle-class replacement cycles drive the deepest volume pool across Bogotá and Medellín metropolitan zones.
- Commercial:Restaurants and food service operations requiring high-duty-cycle durability. Per-unit margins exceed residential tiers through specification-grade compressor and chassis requirements.
- Hospitality:Hotel kitchen and in-room appliance procurement. Cartagena and Bogotá tourism investment generates project-based volume with extended warranty demands.
- Institutional:School, hospital, and government cafeteria equipment. ICONTEC safety certification timelines create procurement planning constraints for public sector buyers.
Residential segments command volume leadership. Hospitality procurement delivers the steepest expansion trajectory in margin contribution.
Distribution Channel:
Channel economics reflect tariff structures favoring local assembly and the service infrastructure requirements of post-sale support.
- Retail Stores:Branded showroom and electronics chain presence with immediate delivery. Homecenter and Alkosto networks in Bogotá control refrigerator and cooking equipment visibility.
- E-Commerce:Platform-based sales with logistics-dependent fulfillment. MercadoLibre and Falabella digital channels gain microwave and small appliance share in urban zones.
- Direct Sales:Manufacturer-controlled account management for project and hospitality procurement. Mabe and HACEB deploy dedicated teams for commercial kitchen specification.
- Wholesalers:Independent distributors serving secondary city retailers and contractors. Pereira and Manizales corridors depend on regional wholesaler inventory for appliance access.
Retail store networks dominate refrigerator transactions. E-commerce is gaining share fastest in compact appliance categories with lower service dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's Free Trade Zones anchor appliance manufacturing concentration, with Bogotá's Zona Franca drawing assembly operations seeking tariff advantages under UPME energy regulations.
Andean Region
Bogotá and Medellín middle-class households drive replacement demand for UPME-certified refrigeration systems. The Unidad de Planeación Minero Energética tightens efficiency thresholds annually, forcing redesign cycles. Zipaquirá and Sabaneta industrial parks host compressor fabrication facilities serving domestic assembly operations.
Caribbean Coast
Cartagena hospitality procurement generates specification-grade kitchen equipment demand from tourism investment. The Superintendencia de Industria y Comercio enforces consumer protection standards for imported goods. Barranquilla's port infrastructure handles component shipments for regional distribution.
Pacific Region
Cali's new construction corridor absorbs induction cooktop specifications as electrical infrastructure upgrades accelerate. ICONTEC certification timelines shape product launch planning for Pacific coast retailers. Buenaventura port development expands logistics capacity for Asian component imports.
Orinoquía
Villavicencio and Yopal secondary cities depend on wholesaler networks for appliance access. Rural electrification programs expand addressable households beyond traditional urban concentrations. Regional distributors maintain inventory for construction and renovation segments.
Amazonía
Leticia and Puerto Inírida represent frontier markets with limited retail infrastructure. Off-grid energy solutions create niche demand for low-consumption refrigeration. River transport logistics constrain product assortment to compact, high-efficiency configurations.
Colombia Kitchen Appliances Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Colombia's appliance sector. The vendor base clusters around three strategic archetypes: multinational brand licensors leveraging import channels, domestic assemblers exploiting tariff-protected local production, and regional distributors controlling secondary city access. Consolidation pressure intensifies as UPME labeling mandates raise compliance costs. Dominant competitive moves include captive compressor manufacturing and direct retail channel expansion.
Among domestic assemblers, Industrias HACEB SA and Mabe de Colombia SA exemplify the tariff-advantaged local production archetype, occupying positions anchored to Bogotá manufacturing infrastructure. Whirlpool Colombia represents the multinational brand licensing model, sitting within import-dependent competitive positioning. These three companies illustrate the structural divide between local assembly economics and finished goods import strategies.
| Leading Market Players |
|---|
| Whirlpool Colombia |
| Industrias HACEB SA |
| GE Appliances |
| LG Electronics |
| Samsung Electronics |
| Panasonic Corporation |
| Mabe de Colombia SA |
| KitchenAid |
| Electrolux Colombia |
| Others |
Value Chain & Pricing Dynamics
Copper and steel price indices cascade through compressor manufacturing and chassis fabrication into three-tier pricing structures across premium, standard, and economy appliance tiers. UPME certification compliance costs concentrate in premium segments where inverter technology and smart modules justify margin recovery, while tariff-protected local assembly operations in Bogotá's Zona Franca compress landed costs against import-dependent competitors.
Pricing Analysis
Short lead-time premiums command pricing power for UPME-certified refrigeration systems in Bogotá's renovation corridors, while spot inventory liquidation discounts clear conventional fixed-speed units from secondary city wholesalers. Certification-grade price differentiation separates inverter-enabled premium tiers from economy fixed-speed platforms, with cost compression in the mid-range intensifying as Asian component sourcing exposes assemblers to peso-dollar volatility. Residential buyers in Medellín's middle-class segments demonstrate highest price sensitivity, whereas hospitality procurement in Cartagena absorbs specification-grade premiums for extended warranty coverage.
Supply Chain Analysis
Regional distribution centers in Bogotá and Barranquilla operate hub-and-spoke patterns feeding Andean retail networks and Caribbean hospitality corridors. Manufacturing concentration centers on China, South Korea, and Mexico for control modules, inverter drives, and compressor subassemblies. Colombian assembly operations draw from copper coil stock, steel sheet, and refrigerant chemical imports, with single-source vulnerability in Asian semiconductor sourcing for smart appliance connectivity. Logistics chokepoints at Buenaventura port constrain Pacific region fulfillment timelines. Distribution runs through captive manufacturer-direct channels for commercial specification, retail chain partnerships for residential volume, and independent wholesalers for secondary city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UPME energy labeling mandates in Colombia construct a cost-of-compliance moat that rewards captive manufacturing infrastructure and accelerates consolidation among tariff-advantaged domestic assemblers.
For Market Incumbents: To counter margin erosion from copper and steel input volatility, deepen backward integration into compressor fabrication at Zipaquirá industrial parks and secure long-term refrigerant chemical offtake agreements. Channel control through direct retail presence in Homecenter and Alkosto networks defends position against import-dependent brand licensors. For New Entrants and Emerging Players: UPME labeling thresholds in Colombia open a window for smart appliance connectivity specialists targeting Bogotá's northern district demand-response utility programs. Pacific coast urbanization in Cali presents the most penetrable geography for induction-enabled cooktop introduction alongside electrical infrastructure upgrades. A project-based go-to-market angle through hospitality procurement channels captures higher-margin specification-grade volume. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic assemblers with captive Bogotá manufacturing infrastructure and established ICONTEC certification pathways. Long-term viability across the next decade hinges on inverter compressor technology migration and smart module integration capabilities. The signal to monitor is UPME threshold acceleration forcing redesign cycles that strand conventional fixed-speed inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Compressor Manufacturing | Backward integration at Sabaneta facilities secures margin control against copper price swings. |
| Smart Appliance Platform Launch | WiFi-enabled refrigeration integrates with UPME demand-response programs in Bogotá metropolitan zones. |
| Distribution Channel Expansion | Direct retail presence in Alkosto and Homecenter networks controls visibility for replacement cycles. |
| Energy Certification Investment | UPME label maintenance preserves premium placement as efficiency thresholds tighten annually. |
| Hospitality Specification Partnership | Cartagena and Bogotá hotel procurement generates project-based volume with extended warranty terms. |
Study Parameters
Independent corroboration across compressor manufacturing executives, retail category managers at electronics chains, ICONTEC certification specialists, and hospitality procurement directors underwrites the qualitative findings. Secondary validation draws from UPME energy consumption databases, Superintendencia de Industria y Comercio enforcement records, customs import manifests for Asian component shipments, and trade association assembly volume reports. Bottom-up channel volume estimates triangulate against top-down household penetration models.
Comparable-period anchoring to historical replacement cycle data and UPME regulatory phase-in timelines structures the projection horizon. Segmentation dimensions span product type, technology tier, end-user category, and distribution channel, with inverter adoption rates and smart connectivity penetration as industry-specific forecast inputs. CAGRs derive from installed base turnover velocity and urban household formation patterns across the analysis window.
The model assumes a particular technology adoption path for inverter compressor migration; alternative pathways for fixed-speed platform persistence in price-sensitive segments would alter the outlook. Forecasts reflect documented assumptions regarding UPME threshold escalation and tariff structure stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Europe Built-In Coffee Machine Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Outdoor Cooking Equipment Market