
 Electric Pizza Oven Market | 2026-2036
Electric Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Pizza Oven Market Foresight
NSF/ANSI Standard 4 certification for commercial cooking equipment is collapsing the vendor pool as smaller fabricators struggle to fund third-party fire suppression and electrical safety testing. Middleby Corporation leverages its conveyor oven platform to dominate high-volume quick-service installations across North America. Blodgett sustains its position in deck oven segments through specialized refractory engineering and direct factory service networks. Unox competes on programmable humidity control systems that reduce bake-time variance in European artisan operations.
An electric pizza oven is a thermostatically controlled cooking appliance that uses resistive heating elements or infrared emitters to achieve deck temperatures between 450°F and 900°F for commercial dough baking. The primary purpose is to deliver consistent thermal profiles that replicate or exceed wood-fired results without combustion byproducts or ventilation complexity. Conveyor ovens lead in throughput-driven installations where ticket-time compression justifies premium capital outlay, while infrared technology segments are gaining fastest in compact urban kitchens where heat-up speed and energy density outweigh floor-space economics. Countertop configurations remain mature with thin margin pools, though wood-fired electric hybrids are carving niche positions in experience-focused dining concepts.
The U.S. Department of Energy sets minimum efficiency standards for commercial kitchen equipment, while the EU Ecodesign Directive and CE marking requirements govern European market access and drive R&D spending toward reduced standby power consumption. The U.S. FDA's Food Code provisions on equipment cleanability further shape stainless-steel surface specifications and access-panel geometry. Stakeholders must monitor how impending amendments to DOE test procedures treat hybrid heating technologies, as reclassification risks could strand development investments or unlock subsidy eligibility for electrification retrofits.
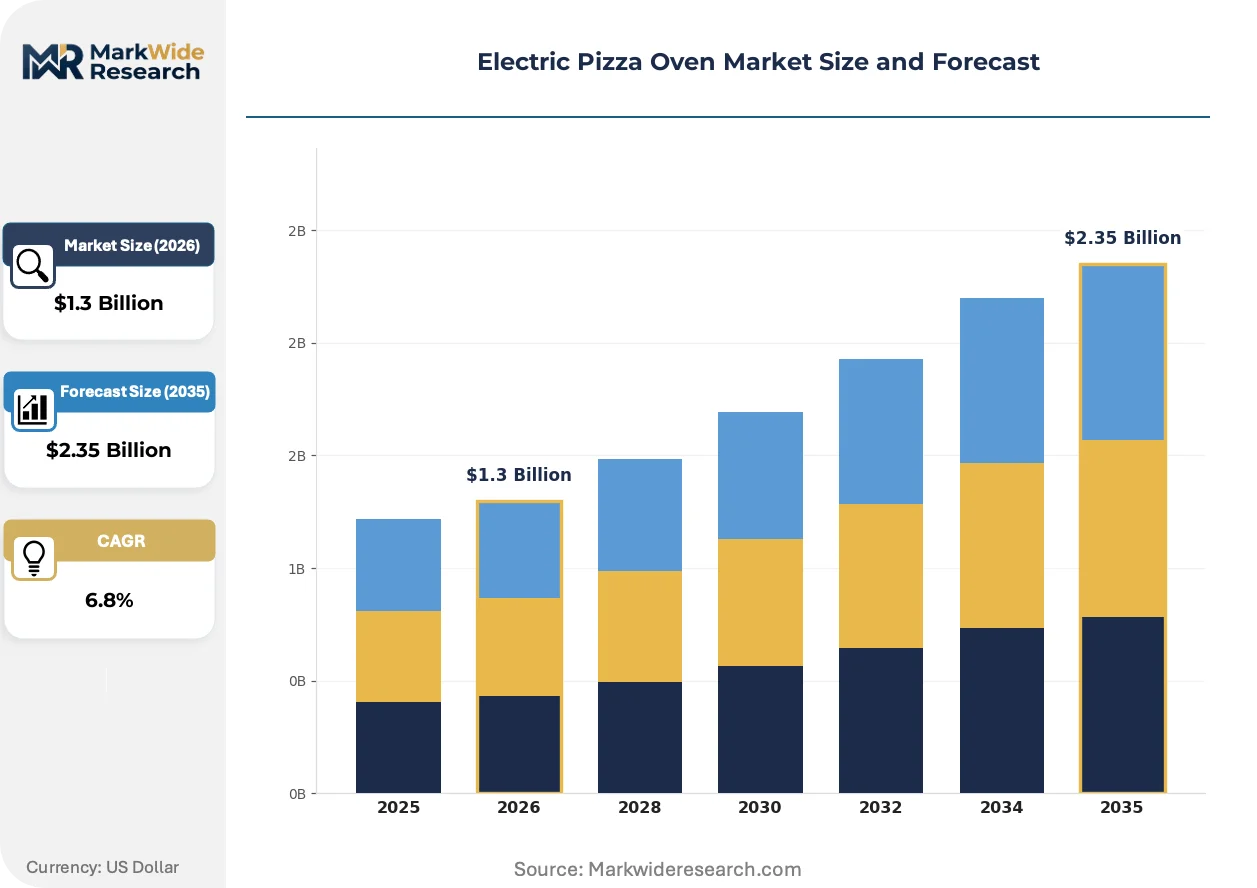
Market Dynamics
Electrification mandates across commercial kitchen infrastructure are compressing replacement cycles and forcing capital redeployment toward resistive and infrared heating platforms.
Growth Catalysts
- EU Ecodesign Directive:Phase-out schedules for gas-powered commercial cooking equipment are accelerating procurement timelines for electric alternatives in European foodservice operations.
- Quick-service restaurant expansion:Pizza-focused menu extensions by major chains are driving bulk equipment orders with standardized thermal specifications.
- Infrared emitter advances:Ceramic and quartz heating elements now achieve 900°F deck temperatures with faster heat-up cycles than traditional resistive coils.
Market Restraints
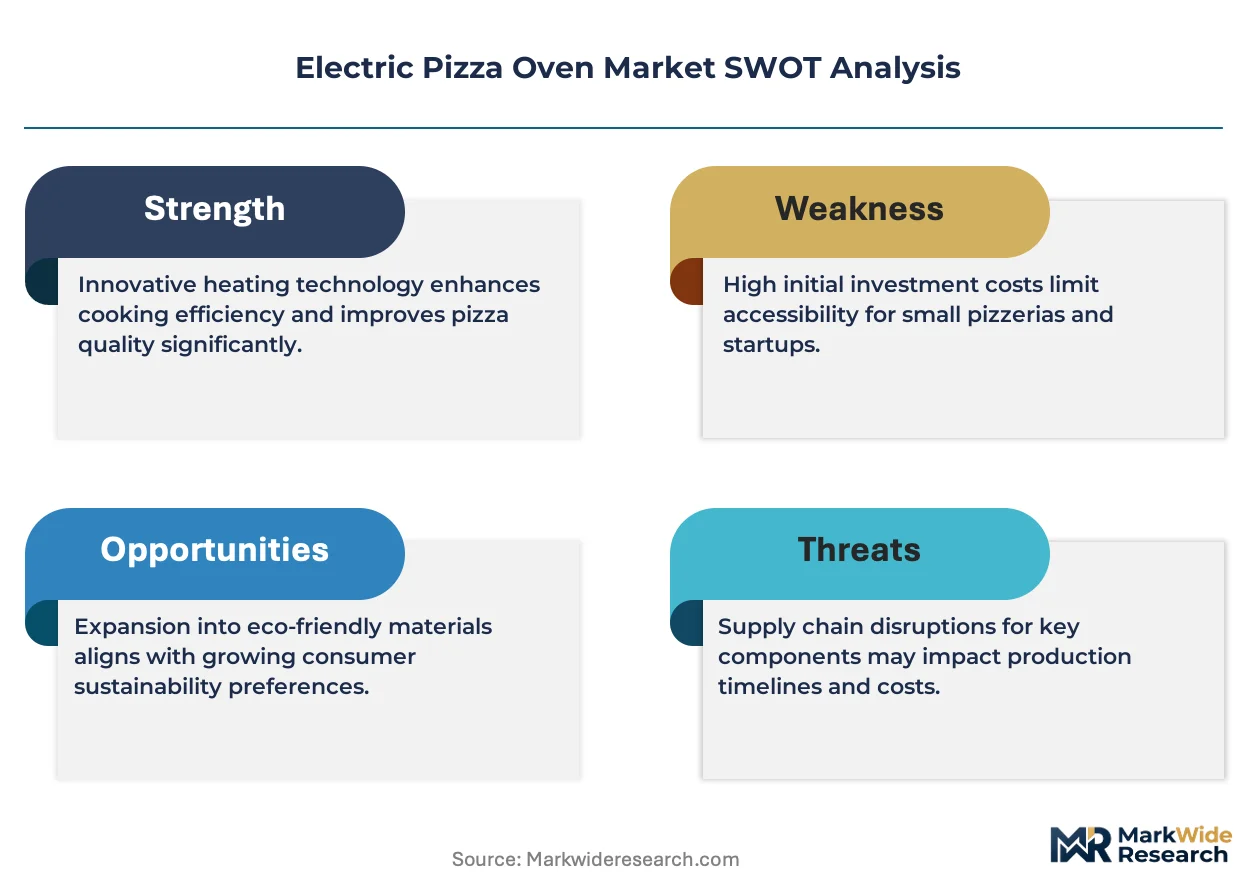
- Copper and nickel price volatility:Resistive heating element manufacturing faces input cost pressure from commodity metal markets.
- Italian equipment concentration:Artisan oven fabrication clusters around Naples and Milan create geographic supply risk.
- Ventilation retrofit requirements:Existing kitchen infrastructure often requires ductwork modifications to accommodate high-temperature electric units.
Strategic Opportunities
- U.S. electrification subsidies:Inflation Reduction Act provisions for commercial building decarbonization may unlock retrofit financing for independent pizzerias.
- Ghost kitchen proliferation:Delivery-only operations prioritize compact countertop configurations with rapid heat-up characteristics.
- Wood-fired electric hybrids:Dual-mode systems combining infrared precision with aromatic wood compartments address experience-dining concepts.
Industry Challenges
- NSF/ANSI Standard 4 certification timelines:Third-party fire suppression and electrical safety testing extends product launch cycles for smaller fabricators.
- Refractory engineering talent scarcity:Specialized thermal mass design expertise concentrates among legacy European manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Pizza Oven Market |
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Ovens, Commercial Ovens, Conveyor Ovens, Wood-Fired Electric Ovens End User: Restaurants, Pizzerias, Catering Services, Home Users Technology: Infrared, Convection, Radiant Heat, Dual Heat Installation: Built-in, Freestanding, Portable, Custom Installations |
| Companies Covered | Baker's Pride, Blodgett, Middleby Corporation, TurboChef, Unox, Wood Stone Corporation, Lincoln, Southbend, Wisco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Pizza Oven Market Shifts & Advancements
Equipment intelligence and thermal precision are converging to redefine operational expectations across independent and chain installations alike.
Programmable humidity control systems are supplanting fixed-deck configurations in European artisan pizzerias. Unox and comparable manufacturers embed sensors that modulate steam injection during bake cycles. Operators now replicate Neapolitan crust texture without wood-fired inconsistency.
DOE test procedure amendments for commercial cooking equipment are reshaping R&D investment allocation. Hybrid heating technologies face potential reclassification risks that could strand development expenditures or unlock subsidy eligibility. Manufacturers are preemptively redesigning control architectures to satisfy both resistive and infrared measurement protocols.
Direct factory service networks are displacing third-party equipment maintenance arrangements in high-volume installations. Middleby Corporation and Blodgett now embed diagnostic telemetry that predicts element degradation before failure. North American quick-service chains increasingly specify OEM service contracts as procurement preconditions.
Electric Pizza Oven Market Segmentation
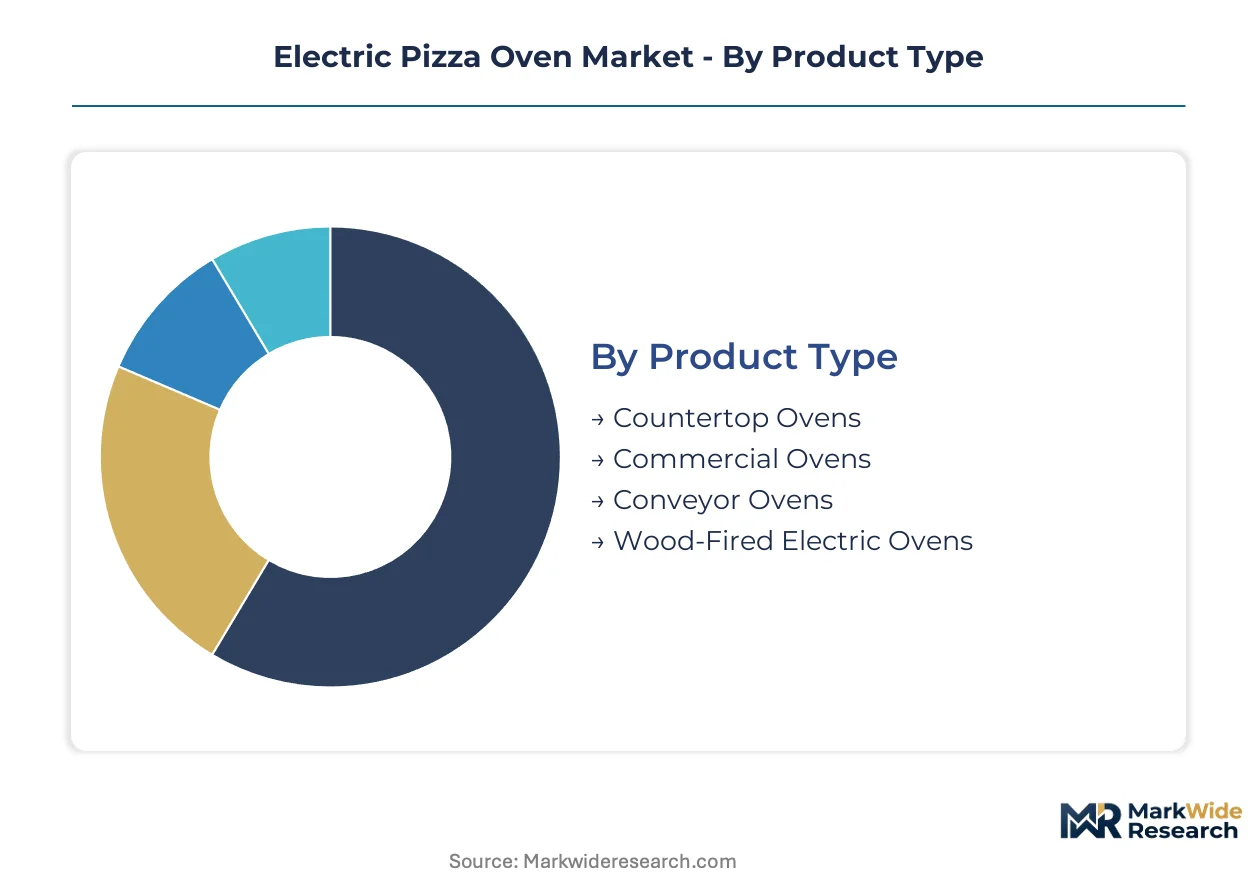
Channel mix across electric pizza oven procurement varies sharply by operational scale. High-volume quick-service chains favor conveyor configurations through direct OEM contracts, while independent operators source countertop units through foodservice distributors. Equipment intelligence and thermal precision now segment buyer priorities more than price alone.
Product Type:
Channel flow differs markedly: conveyor ovens move through direct manufacturer relationships with chain accounts, countertop units through broadline distributors, and wood-fired hybrids through specialty dealers serving experience-dining concepts.
- Conveyor Ovens:Continuous-belt thermal systems achieve 600-800°F deck temperatures with ticket-time compression below 5 minutes. Quick-service chains in the United States specify these for throughput-driven installations where labor efficiency justifies premium capital outlay. NSF/ANSI Standard 4 certification requirements favor established fabricators with fire suppression testing capabilities.
- Countertop Ovens:Compact thermostatically controlled units with resistive heating elements occupy 24-36 inches of line space. Ghost kitchen proliferation in urban United States markets drives demand for rapid heat-up configurations with minimal ventilation retrofit requirements. Margin pools remain thin due to commoditized component sourcing.
- Commercial Ovens:Floor-standing deck configurations with refractory thermal mass target independent pizzerias seeking wood-fired replication without combustion complexity.
- Wood-Fired Electric Ovens:Dual-mode systems combine infrared precision with aromatic wood compartments for experience-focused dining concepts in Italy and the United States.
By volume, conveyor ovens lead through chain procurement consolidation. By growth pace, wood-fired electric hybrids are expanding most quickly as experience-dining concepts proliferate.
End User:
Cost tier segmentation separates capital-intensive chain deployments from independent operator equipment refresh cycles, with catering services occupying a volatile middle ground sensitive to event-volume fluctuations.
- Restaurants:Full-service operators integrate pizza ovens into menu diversification strategies, prioritizing programmable humidity control for crust consistency. United States casual-dining chains specify OEM service contracts as procurement preconditions, embedding diagnostic telemetry for predictive maintenance.
- Pizzerias:Independent operators and artisan chains in Italy concentrate demand around Naples and Milan manufacturing clusters, favoring refractory engineering expertise for thermal mass optimization. EU Ecodesign Directive compliance accelerates electric conversion from gas-powered legacy equipment.
- Catering Services:Mobile and event-driven operators prioritize portable configurations with rapid setup characteristics.
- Home Users:Residential countertop units with 450-550°F temperature ceilings serve enthusiast segments through e-commerce channels.
Restaurants command the largest capital deployment per installation. Pizzerias show the steepest expansion trajectory as electrification mandates compress replacement cycles across European markets.
Technology:
Application requirements dictate thermal delivery mechanism: infrared for speed-sensitive urban kitchens, convection for uniform baking across varied product loads, radiant heat for traditional crust development.
- Infrared:Ceramic and quartz emitter arrays achieve 900°F deck temperatures with heat-up cycles under 15 minutes. Compact urban kitchens in the United States and Italy prioritize this technology where energy density outweighs floor-space economics. DOE test procedure amendments create reclassification risk for hybrid control architectures.
- Radiant Heat:Resistive coil systems with slower thermal response maintain lower capital cost positions for price-sensitive independent operators.
- Convection:Forced-air circulation ensures temperature uniformity across multi-product baking loads in high-volume operations.
- Dual Heat:Combined infrared and convection modes address operators requiring both speed and consistency flexibility.
Infrared configurations dominate new capital allocation. Dual heat systems are climbing the fastest as manufacturers preempt regulatory reclassification through control architecture redesign.
Installation:
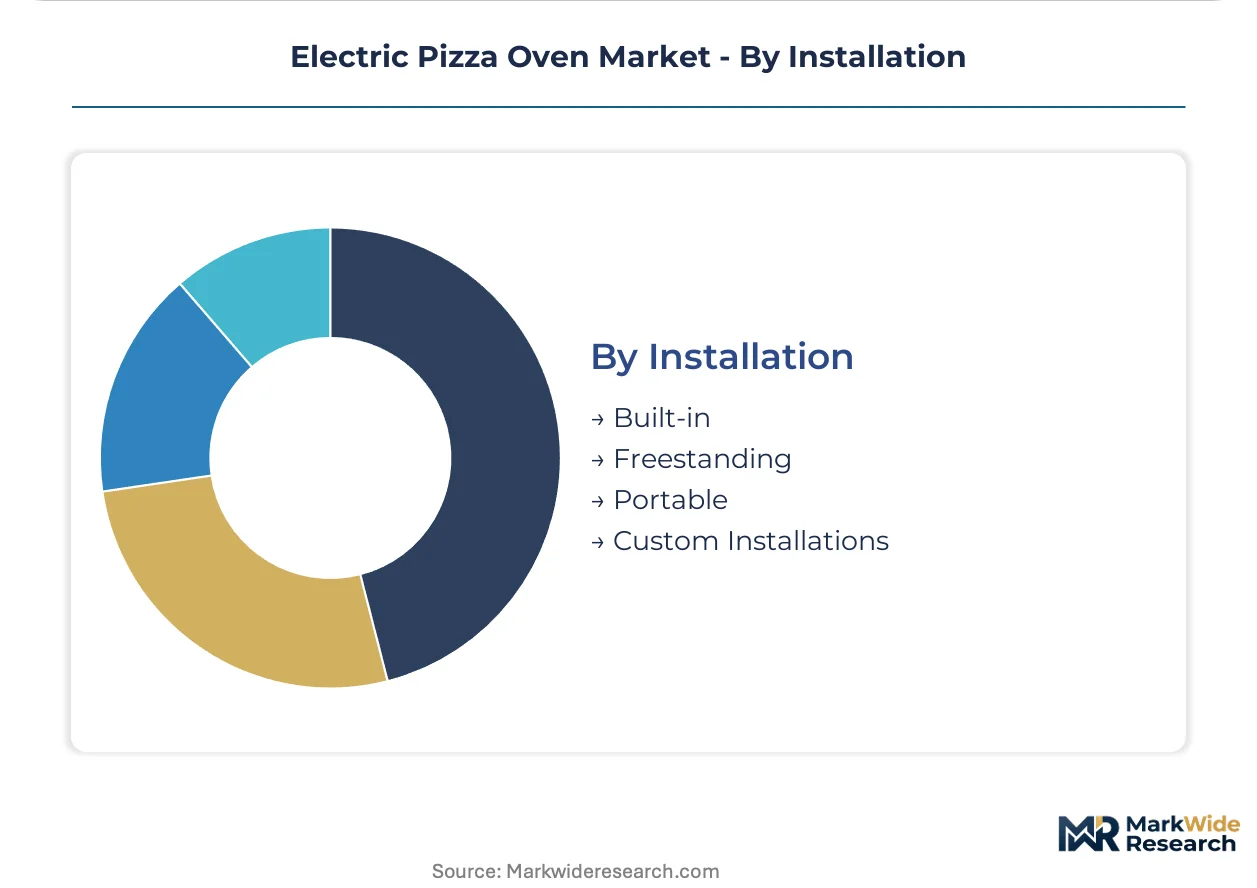
Volume concentration tracks operational permanence: built-in installations anchor flagship locations, freestanding units enable format flexibility, portable configurations serve emerging ghost kitchen and catering segments.
- Freestanding:Self-contained floor units with integrated ventilation and electrical connections minimize infrastructure modification for independent pizzerias. United States foodservice distributors stock these for rapid deployment in secondary markets.
- Built-in:Custom-integrated systems with specified ductwork and electrical rough-in anchor flagship locations for major chains.
- Portable:Compact wheeled configurations with quick-connect utilities target catering operators and temporary foodservice installations.
- Custom Installations:Specified thermal envelopes and aesthetic cladding serve experience-dining concepts with architect-driven requirements.
Freestanding units lead by installation count across independent operator bases. Portable configurations are gaining share fastest as delivery-only kitchen formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and artisan pizzerias drive equipment procurement across distinct national markets, with electrification mandates compressing replacement cycles in mature economies and infrastructure investment expanding access in emerging ones.
United States
Major quick-service chains dominate conveyor oven procurement through direct OEM contracts, prioritizing ticket-time compression above capital cost. The Department of Energy's efficiency standards and Inflation Reduction Act electrification subsidies accelerate gas-to-electric conversions. Equipment intelligence clusters around Chicago and Dallas foodservice manufacturing corridors.
Italy
Artisan pizzerias concentrate demand around Naples and Milan manufacturing clusters, seeking refractory engineering expertise for thermal mass optimization. The EU Ecodesign Directive phase-out schedules force accelerated procurement timelines for electric alternatives. Wood-fired electric hybrid development centers on Bologna and Florence experience-dining concepts.
Germany
Commercial kitchen operators face stringent CE marking and EU Ecodesign compliance requirements that favor established fabricators with certification capabilities. Energy-efficiency mandates under the EU Green Deal drive R&D spending toward reduced standby power consumption. Industrial equipment fabrication concentrates in North Rhine-Westphalia and Bavaria.
China
Foodservice expansion in tier-one cities creates demand for compact infrared configurations suited to urban kitchen footprints. The country's national quality standards and dual carbon goals shape equipment import requirements and local manufacturing incentives. Production clusters concentrate in Guangdong and Zhejiang provinces.
United Kingdom
Ghost kitchen proliferation in London and Manchester drives countertop unit demand with rapid heat-up specifications. Post-Brexit regulatory alignment with EU Ecodesign principles maintains equipment certification continuity. Distribution networks center on Birmingham and London foodservice hubs.
Electric Pizza Oven Market Competitive Landscape
Player mix skews toward diversified commercial kitchen equipment manufacturers with established certification infrastructure and specialized thermal engineering boutiques. Market structure consolidates around conveyor oven platforms for high-volume installations while fragmenting across artisan deck oven segments. Two strategic archetypes dominate: integrated foodservice conglomerates leveraging factory service networks, and regional specialists commanding refractory design expertise. Competitive moves center on predictive maintenance telemetry integration and geographic expansion through distributor partnerships.
Among North American-based fabricators, Middleby Corporation and Blodgett exemplify scale-driven consolidation archetypes, with the former representing conveyor platform dominance and the latter occupying deck oven specialization. Italian manufacturer Unox anchors the European programmable humidity control segment. These three companies collectively illustrate how certification capabilities and direct service infrastructure separate viable competitors from marginal fabricators facing NSF/ANSI Standard 4 compliance barriers.
| Leading Market Players |
|---|
| Baker's Pride |
| Blodgett |
| Middleby Corporation |
| TurboChef |
| Unox |
| Wood Stone Corporation |
| Lincoln |
| Southbend |
| Wisco |
| Others |
Supply & Pricing Matrix
Long-term OEM service contracts with take-or-pay provisions lock in supply access for North American quick-service chains while insulating manufacturers from spot-price volatility in copper and nickel markets. These arrangements bundle predictive maintenance telemetry with equipment procurement, converting capital expenditure into operational cost visibility across multi-unit rollouts.
Pricing Analysis
Cost-plus contracts indexed to LME copper and nickel benchmarks dominate conveyor oven procurement, with price adjustments triggered quarterly. Three-tier pricing structure across NSF-certified premium, CE-marked standard, and uncertified economy levels separates buyers by compliance requirements and service bundling. Pricing pressure stems from commodity metal volatility squeezing resistive heating element margins. Independent pizzerias exhibit highest price sensitivity due to capital constraints, while major chains prioritize throughput metrics over unit cost.
Supply Chain Analysis
Italy and China anchor electric pizza oven fabrication, with Naples and Milan clusters supplying refractory-engineered deck units and Guangdong province producing compact infrared assemblies. Manufacturing draws from nickel-chromium alloy feedstock, ceramic emitter substrates, and programmable control modules. Single-source vulnerability concentrates in Italian refractory engineering talent for thermal mass optimization. Distribution runs through foodservice equipment distributors in secondary markets and direct OEM contracts for chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric pizza oven market functions as a defensive-moat industry where NSF/ANSI Standard 4 certification requirements create regulatory entrenchment that marginalizes unqualified fabricators. Switching costs for installed base maintenance lock in recurring revenue streams for established service networks.
For Market Incumbents: Shield market position through backward integration into nickel-chromium alloy supply and predictive maintenance telemetry deployment. Certification investment barriers block emerging Asian fabricators from North American chain procurement. Channel control via exclusive distributor agreements in secondary markets reinforces installed base capture. For New Entrants and Emerging Players: Lead with portable infrared configurations targeting ghost kitchen proliferation in urban United States markets. Wood-fired electric hybrid segments show lowest incumbent saturation and highest experience-dining concept penetration. Direct-to-operator digital sales channels bypass established distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with dormant certification capabilities and regional service infrastructure. Long-term viability hinges on electrification mandate acceleration compressing replacement cycles across European and North American foodservice operations. Watch DOE test procedure amendments for hybrid heating reclassification as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | NSF/ANSI Standard 4 compliance unlocks North American quick-service chain procurement channels. |
| Predictive Maintenance Integration | Diagnostic telemetry embedded by Middleby and Blodgett converts equipment sales into recurring service revenue. |
| Backward Integration | In-house resistive heating element production insulates margins from LME copper and nickel volatility. |
| Geographic Manufacturing Expansion | North American production footprints reduce delivery costs and tariff exposure for United States chain accounts. |
| Hybrid Technology Development | Dual-mode infrared and wood-fired systems capture experience-dining premium in Italy and United States urban markets. |
Research Methodology
Initial hypotheses were tested against primary input from foodservice equipment procurement directors, commercial kitchen design consultants, OEM aftermarket service heads, and independent pizzeria operators and refined through secondary validation against SEC 10-K filings, EU Ecodesign Directive implementation reports, DOE commercial equipment standards documentation, and foodservice distributor inventory data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, technology platform, end-user segment, installation configuration, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated electrification mandate phase-out schedules, quick-service chain capex disclosure patterns, and refractory engineering labor availability indices.
Forecasts assume regulatory continuity in EU Ecodesign Directive implementation and DOE efficiency standard enforcement; material policy shifts would require re-modeling. Specific risks include commodity metal price spikes, ventilation retrofit cost inflation, and hybrid heating technology reclassification. Recalibration cycles align with material shifts in electrification subsidy availability and chain expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Ceramic Coated Cookware Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
US Range Cooker Market
Kitchen Appliances
Europe Household Refrigerator Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Household Cooking Appliance Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
France Cookware Market
Kitchen Appliances
Portable Sandwich Maker Market