
 Minoxidil API Market | 2026-2036
Minoxidil API Market Size, Share, and Industry Trends Forecast 2026-2036
Minoxidil API Market Insights
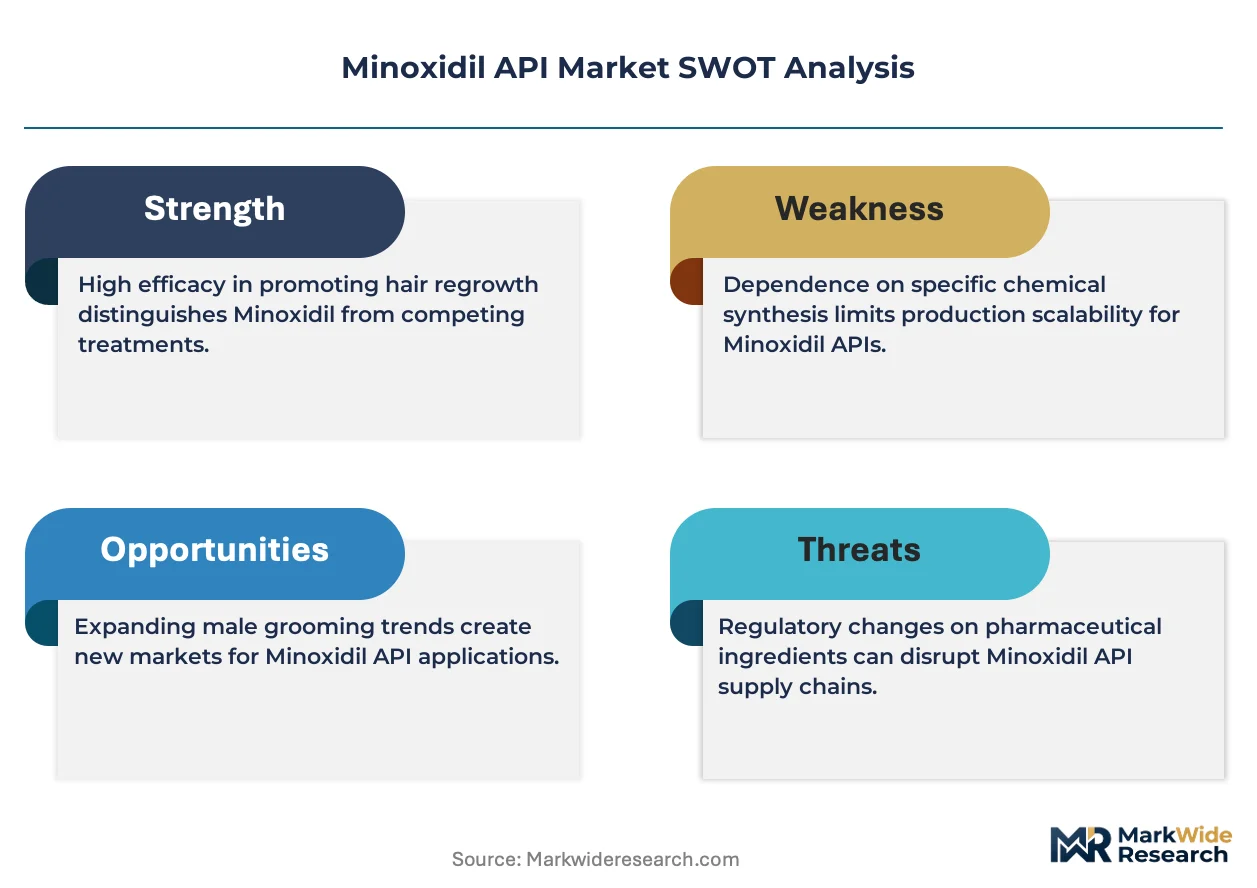
Specialty dermatology clinics is redrawing procurement patterns for minoxidil API, displacing traditional hospital-centric purchasing as direct-to-consumer hair restoration services proliferate. Pfizer Inc. leverages its legacy cardiovascular expertise to anchor supply relationships with hypertension-focused generic formulators. Teva Pharmaceutical Industries Ltd. competes through vertical integration across oral and topical dosage development. Sun Pharmaceutical Industries Ltd. sustains cost leadership via high-volume API production from Indian manufacturing complexes.
Minoxidil API denotes the active pharmaceutical ingredient 2,4-diamino-6-piperidinopyrimidine-3-oxide, synthesized through guanidine condensation routes and specified at minimum 99.0% assay purity for pharmaceutical-grade applications. The compound functions primarily as a potassium channel opener, repurposed from antihypertensive therapy to androgenetic alopecia treatment through vasodilation of dermal papilla microcirculation. Topical solution formulations occupy mature volume positions, while foam delivery systems command premium positioning due to enhanced propellant-free application and reduced irritancy profiles. Alopecia treatment applications concentrate demand from branded and generic dermatology portfolios, whereas blood pressure regulation segments retain steady hospital procurement despite declining first-line prescribing.
FDA current Good Manufacturing Practice enforcement and EMA Active Substance Master File requirements shape import inspection intensity for Asian API suppliers. India's CDSCO manufacturing license protocols and China's NMPA environmental compliance standards for piperidine derivative synthesis impose capacity constraints on intermediate producers. Stakeholders must monitor evolving bioequivalence study design changes for topical generic approvals and assess captive synthesis versus merchant API sourcing for foam formulation pipelines.
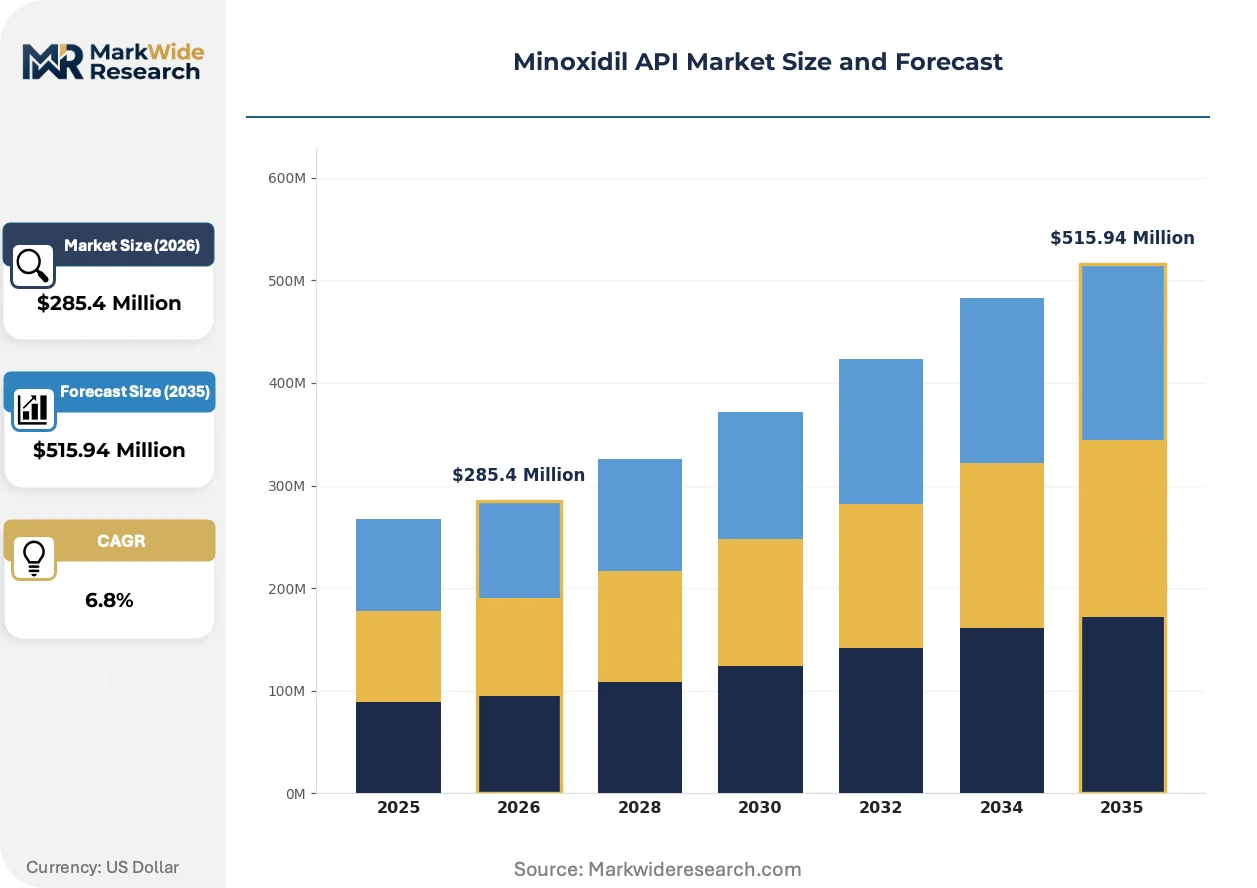
Market Dynamics
FDA bioequivalence enforcement for topical generics is compressing merchant API margins while forcing formulators toward captive synthesis or premium-certified suppliers. This regulatory pressure intersects with dermatology clinic procurement centralization to reshape supplier-buyer power dynamics.
Growth Catalysts
- EMA Active Substance Master File harmonization:Streamlined cross-border API registration accelerates European market entry for compliant Indian and Chinese manufacturers.
- Foam delivery system adoption:Propellant-free formulations command formulation partnerships with specialty dermatology chains seeking differentiated patient compliance profiles.
- India:CDSCO manufacturing license protocols and export-oriented infrastructure position domestic API producers as regulated-market suppliers.
Market Restraints
- Piperidine derivative synthesis:Environmental compliance costs for NMPA-mandated wastewater treatment constrain intermediate capacity expansion in China's Jiangsu and Zhejiang chemical clusters.
- Merchant API concentration:Reliance on third-party 2,4-diamino-6-piperidinopyrimidine-3-oxide suppliers exposes formulators to lot-to-lot purity variability and inspection-triggered supply interruptions.
- Oral minoxidil resurgence:Low-dose systemic prescribing for alopecia competes with topical API demand in hypertension-focused hospital procurement channels.
Strategic Opportunities
- United States compounding pharmacy channel:503A and 503B outsourcing facilities seek customized minoxidil concentrations bypassing branded topical economics.
- China domestic dermatology demand:NMPA-approved hair restoration clinics proliferate in tier-1 cities, creating localized API consumption nodes.
- Green chemistry incentives:REACH-registered biocatalytic reduction routes for pyrimidine oxide intermediates qualify for EU Green Deal sustainable manufacturing tax credits.
Industry Challenges
- Analytical method transfer:FDA import alert remediation requires dedicated stability-indicating HPLC validation teams that mid-size API houses struggle to retain.
- Multi-site inspection coordination:Simultaneous FDA and EMA pre-approval inspections demand redundant quality unit staffing across manufacturing and laboratory facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minoxidil API Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solution, Foam, Tablets, Injectable End User: Pharmacies, Hospitals, Online Retail, Clinics Application: Alopecia Treatment, Blood Pressure Regulation, Hair Restoration, Dermatological Disorders Distribution Channel: Direct Sales, Wholesale, E-commerce, Retail Pharmacies |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., Cipla Ltd., Aurobindo Pharma Limited, Lupin Limited, Xian Aland Biotech Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minoxidil API Market Trends and Innovations
Continuous processing technologies and regulatory data integrity mandates are converging to redefine minoxidil API manufacturing economics. These shifts favor capitalized players capable of integrated quality systems and real-time release testing.
Continuous flow reactors for guanidine condensation are supplanting batch vessel operations in advanced intermediate production. Sun Pharmaceutical and select CDMOs have commissioned microreactor trains that reduce solvent volumes and thermal degradation risk. This technology is supplanting traditional batch economics by enabling on-demand API output aligned to just-in-time foam formulation campaigns.
REACH registration requirements for piperidine derivatives now mandate complete substance identity profiles including nanoform fraction analysis. ECHA enforcement has triggered reformulation of intermediate supply contracts to exclude unregistered byproduct streams. European generic topical marketers are responding by consolidating API sourcing to REACH-authorized suppliers with full substance dataset documentation.
Dermatology clinic chains now specify lot-level CoA transparency and direct supplier auditing rights in API procurement agreements. This specification displaces traditional distributor-mediated purchasing with direct manufacturer relationships backed by quality agreements. The United States and South Korea exhibit the most pronounced contract restructuring, with clinic networks leveraging volume commitments for supply security guarantees.
Minoxidil API Market Segmentation
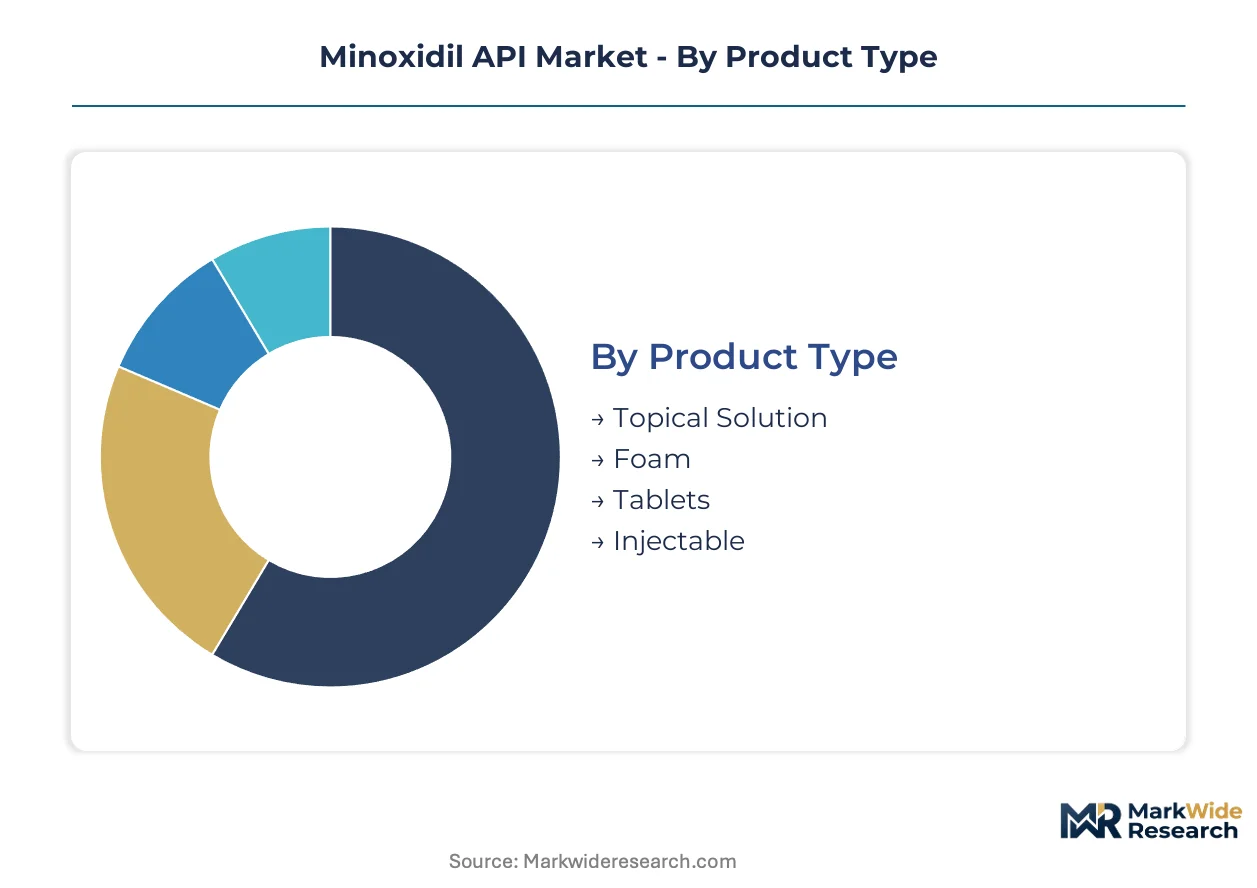
Segmentation in minoxidil API procurement reflects divergent purity standards across regulated markets versus compounding channels. Formulators targeting FDA-approved topical generics demand pharmaceutical-grade specifications that diverge sharply from merchant API grades serving institutional buyers.
Product Type:
Domestic consumption concentrates in tablet and solution formats for established cardiovascular therapy, while export-led demand drives foam and specialty formulation APIs.
- Topical Solution:Mature ethanol-propylene glycol carrier systems dominate hospital and retail pharmacy dispensing. Indian contract manufacturers supply regulated markets under FDA bioequivalence protocols, though propellant-based irritancy profiles limit clinic chain adoption.
- Foam:Propellant-free emulsion technology commands premium positioning through enhanced patient compliance. South Korean and United States dermatology clinic networks specify foam-grade APIs with documented lot-to-lot viscosity consistency for direct-purchase agreements.
- Tablets:Oral antihypertensive formulations retain steady procurement from hospital formularies.
- Injectable:Parenteral-grade specifications serve acute hypertension management in emergency settings.
Topical solution commands the established base. The steepest expansion runs through foam.
End User:
Procurement authority is fragmenting as direct-to-consumer channels displace traditional wholesale purchasing.
- Pharmacies:Community and chain dispensaries anchor volume for generic topical solutions under established reimbursement codes.
- Hospitals:Institutional formularies sustain oral minoxidil procurement for resistant hypertension protocols.
- Online Retail:Direct-to-consumer platforms bypass distributor markups for unbranded topical kits.
- Clinics:Specialty dermatology networks in the United States and South Korea negotiate direct API supply agreements with audit rights and CoA transparency requirements.
Hospitals retain the volume anchor. Clinics are climbing the fastest as procurement centralization accelerates.
Application:
Repurposing from cardiovascular to dermatological indications has inverted demand concentration across therapeutic categories.
- Alopecia Treatment:Androgenetic alopecia applications concentrate demand from branded and generic dermatology portfolios. Foam-grade APIs with specified particle size distribution attract premium pricing from United States compounding pharmacies seeking 503B outsourcing facility compliance.
- Blood Pressure Regulation:Resistant hypertension segments retain steady hospital procurement despite declining first-line prescribing. Indian API producers supply this segment through cost-optimized tablet-grade specifications under CDSCO manufacturing license protocols.
- Hair Restoration:Cosmetic procedure integration drives clinic-direct procurement patterns.
- Dermatological Disorders:Off-label scarring alopecia applications generate niche formulation demand.
Blood pressure regulation anchors the historical base. Hair restoration is gaining share fastest through aesthetic clinic proliferation.
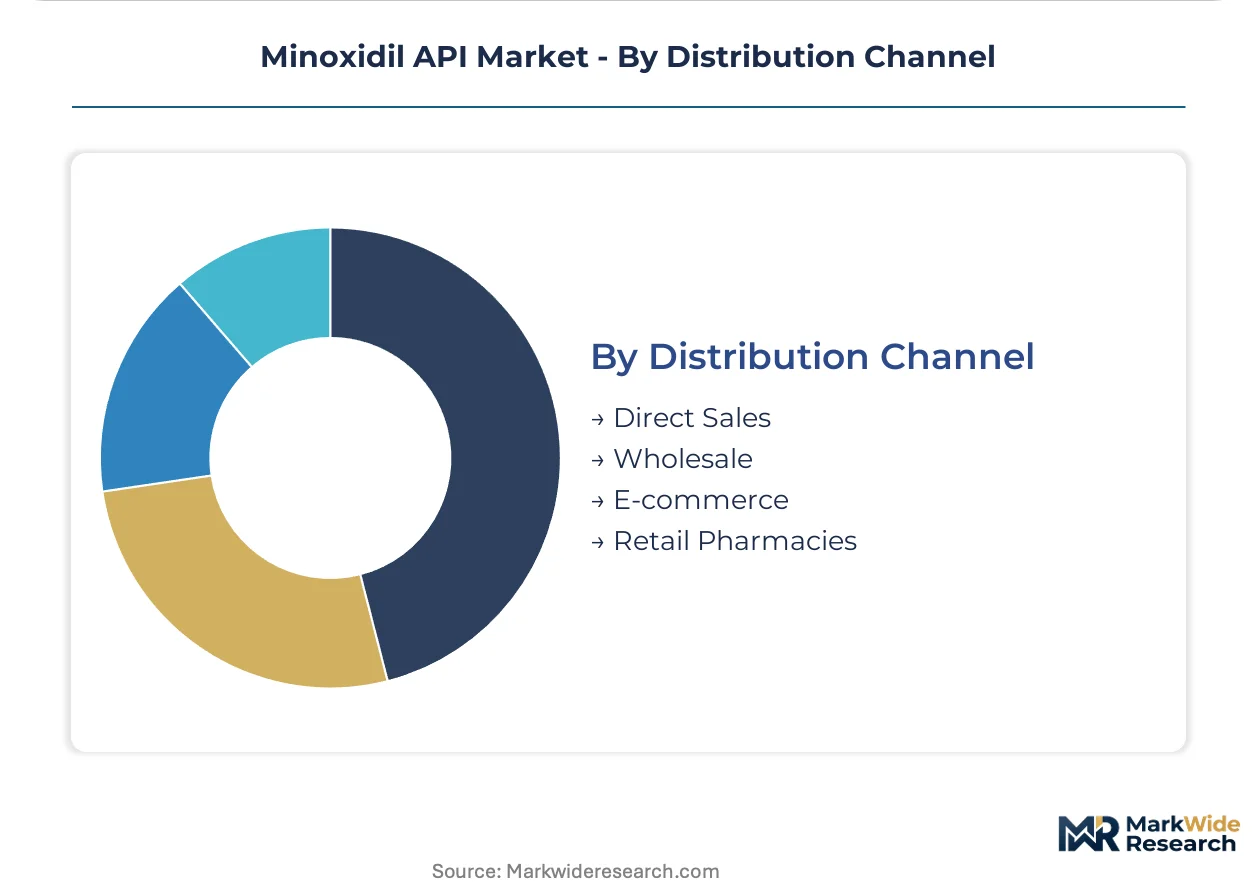
Distribution Channel:
Channel strategy diverges between regulated-market compliance requirements and emerging direct-access models.
- Direct Sales:Manufacturer-to-formulator relationships dominate FDA-regulated topical generic supply. EMA Active Substance Master File holders in India and China bypass distributor intermediaries to secure quality agreement terms with European generic marketers.
- Wholesale:Traditional pharmaceutical distributors retain relevance for oral tablet formulations in hospital procurement channels.
- E-commerce:B2B platforms facilitate merchant API spot purchasing for mid-size formulators lacking captive synthesis.
- Retail Pharmacies:Final-mile dispensing concentrates consumer-facing topical product access.
Wholesale channels command the established infrastructure. Direct sales are expanding most quickly as quality agreement standardization progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturers export bulk minoxidil to United States and European generic formulators under FDA bioequivalence protocols, while Chinese intermediate producers supply piperidine derivatives to regulated markets facing tightening environmental compliance.
United States
Dermatology clinic chains in California and Texas negotiate direct API supply agreements with audit rights and certificate-of-analysis transparency requirements. FDA enforcement of topical generic bioequivalence standards compresses merchant supplier margins while favoring captive synthesis or premium-certified sources. Houston and Miami serve as distribution hubs for compounded minoxidil formulations targeting 503A and 503B outsourcing facilities.
India
Contract manufacturers in Maharashtra and Gujarat supply pharmaceutical-grade minoxidil to regulated markets under CDSCO manufacturing license protocols. CDSCO export-oriented infrastructure positions domestic producers as preferred suppliers for European generic marketers seeking EMA Active Substance Master File holders. Hyderabad and Ahmedabad chemical clusters concentrate guanidine condensation capacity for intermediate and API production.
China
Jiangsu and Zhejiang chemical clusters face NMPA-mandated wastewater treatment costs that constrain piperidine derivative intermediate expansion. NMPA environmental compliance standards for pyrimidine oxide synthesis impose capacity limitations on legacy batch operations. Shanghai and Hangzhou serve as coordination centers for REACH-registered biocatalytic reduction routes qualifying for EU Green Deal manufacturing incentives.
Germany
EMA regulatory harmonization streamlines cross-border API registration for compliant Asian suppliers entering European generic topical markets. ECHA enforcement of REACH registration requirements for piperidine derivatives mandates complete substance identity profiles including nanoform fraction analysis. Frankfurt and Munich host quality agreement negotiations between generic marketers and Indian API houses seeking European market access.
South Korea
Specialty dermatology networks in Seoul and Busan specify foam-grade APIs with documented lot-to-lot viscosity consistency for direct-purchase agreements. MFDS oversight of hair restoration clinic proliferation in tier-1 cities creates localized API consumption nodes. Incheon chemical processing zones intermediate between Chinese intermediate suppliers and domestic foam formulation facilities.
Minoxidil API Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification depth, with public pharmaceutical companies leveraging capital markets for capacity expansion while private API houses compete on cost structure and geographic proximity to intermediate sources. Market structure tilts toward consolidation among FDA-inspected facilities capable of supporting topical generic approvals, with tiering between EMA-registered suppliers and merchant API traders serving compounding channels. Three archetypes dominate: vertically integrated pharmaceutical conglomerates with captive synthesis, high-volume Indian and Chinese API specialists, and regional CDMOs offering formulation partnerships. Competitive moves center on backward integration into piperidine intermediate production and strategic partnerships with dermatology clinic chains for direct supply agreements.
Among publicly traded pharmaceutical conglomerates, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. exemplify the vertically integrated archetype with legacy cardiovascular expertise anchoring supply relationships across therapeutic categories. Sun Pharmaceutical Industries Ltd. occupies a position within the high-volume API specialist tier, with Indian manufacturing infrastructure supporting cost-optimized production for regulated markets. These three companies represent the competitive spectrum from branded originator heritage to generic API scale economics.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Cipla Ltd. |
| Aurobindo Pharma Limited |
| Lupin Limited |
| Xian Aland Biotech Co Ltd |
| Others |
Pricing and Supply Chain Analysis
FDA bioequivalence enforcement for topical generics gates both supplier qualification and price differentiation simultaneously, compressing merchant API margins while elevating certified sources to premium positioning. This regulatory filter creates a bifurcated market where EMA-registered suppliers command formulation partnerships with dermatology clinic chains, while uncertified merchant traders serve price-sensitive compounding channels.
Pricing Analysis
Batch-processed API pricing faces compression from continuous-flow manufacturing investments, while foam-grade specifications sustain premiums through documented lot-to-lot viscosity consistency. Pricing stratifies across REACH-authorized, FDA-inspected, and merchant-grade tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in standard topical solution grades is intensifying because Indian and Chinese producers compete on scale economics. Compounding pharmacies exhibit highest price sensitivity; dermatology clinic networks prioritize supply security over unit cost.
Supply Chain Analysis
Piperidine derivative intermediate supply from China's Jiangsu and Zhejiang chemical clusters underwrites global minoxidil API output, with guanidine condensation capacity concentrated in Indian manufacturing complexes. The chain draws from piperidine feedstocks, pyrimidine oxide intermediates, and propellant-free foam formulation chemicals. Single-source vulnerability runs through NMPA-mandated environmental compliance shutdowns at legacy batch operations. Distribution runs through direct manufacturer-to-formulator agreements for regulated markets, with wholesale channels retaining oral tablet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Minoxidil API procurement is shifting toward platform-economics logic as dermatology clinic chains consolidate purchasing through direct supplier relationships with embedded quality agreements and audit rights, displacing traditional distributor-mediated spot purchasing.
For Market Incumbents: Fortify captive synthesis capabilities or premium-certified supply positions as FDA import alert remediation demands dedicated stability-indicating HPLC validation teams that mid-size API houses struggle to retain. Backward integration into piperidine intermediate production in Indian chemical clusters secures margin control against NMPA environmental compliance disruptions. Channel control through exclusive formulation partnerships with United States and South Korean clinic networks defends positioning against merchant API price erosion.
For New Entrants and Emerging Players: CDSCO manufacturing license fast-track positions domestic Indian producers as regulated-market suppliers to European generic marketers seeking EMA Active Substance Master File holders. Compounding pharmacy 503B outsourcing facilities represent the most penetrable white-space target, with customized concentration formulations bypassing branded topical economics. Green chemistry credentials through REACH-registered biocatalytic reduction routes qualify for EU Green Deal sustainable manufacturing tax credits as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: EMA Active Substance Master File harmonization reshapes the acquisition landscape toward REACH-authorized suppliers with full substance dataset documentation and redundant quality unit staffing across manufacturing and laboratory facilities. Mid-cap Indian API houses with FDA-inspected facilities and foam formulation partnerships offer strongest long-term viability through the projection horizon. Watch FDA bioequivalence study design changes for topical generic approvals as the signal indicating accelerated consolidation among compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piperidine Intermediates | NMPA environmental compliance costs in China constrain legacy suppliers, rewarding upstream control. |
| Continuous Flow Reactor Commissioning | Microreactor trains reduce solvent volumes and enable just-in-time API output aligned to foam campaigns. |
| EMA Active Substance Master File Registration | Streamlined cross-border API registration accelerates European market entry for compliant manufacturers. |
| Dermatology Clinic Direct Supply Agreements | Quality agreements with audit rights and CoA transparency displace distributor-mediated purchasing. |
| REACH-Registered Biocatalytic Reduction Routes | EU Green Deal sustainable manufacturing tax credits reward green chemistry process investments. |
Research Methodology
Initial hypotheses were tested against primary input from API manufacturing executives, regulatory affairs leads at Indian and Chinese producers, dermatology clinic procurement directors, and generic topical formulators, and refined through secondary validation against FDA filings, EMA Active Substance Master File databases, CDSCO manufacturing license records, and customs trade data. Bottom-up volume estimates from guanidine condensation capacity and top-down market sizing from formulation demand were triangulated to converge on consistent outputs.
Variance decomposition across product type, end user procurement authority, application therapeutic category, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate reconciliation against macro pharmaceutical API demand indicators. Forecast inputs incorporated foam delivery system adoption curves, oral minoxidil resurgence patterns, and environmental compliance cost trajectories for piperidine derivative synthesis.
Underlying assumptions cover sustained FDA bioequivalence enforcement intensity and EMA regulatory harmonization progress, with deviation risk concentrated in NMPA environmental policy shifts and oral minoxidil off-label prescribing expansion. Practitioners should keep alternative scenarios live as topical generic approval timelines and clinic chain consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Cosmetic Dropper Market