
 Personal Care Chemicals Market | 2026-2036
Personal Care Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Chemicals Market Outlook
The EU Green Deal is hardening ingredient disclosure requirements across European supply chains. BASF SE leverages its integrated biotech platforms to secure renewable emollient supply. Croda International Plc anchors its position through specialty lipid chemistry for skin barrier repair. Dow Inc. competes on surfactant scale, serving multinational brand owners with consistent bulk volumes.
Personal care chemicals comprise functional ingredients engineered at defined molecular weights, HLB values, and purity grades to deliver cleansing, conditioning, preservation, or sensory modification in consumer products. These compounds undergo esterification, ethoxylation, or fermentation-based synthesis to meet cosmetic-grade specifications for dermal compatibility and microbial stability. Emollients command margin concentration due to their technical complexity and brand-owner reliance on skin-feel differentiation. Surfactants retain volume leadership across shampoo and body wash applications, while serum formulations within the skincare application vector attract fastest-growing demand from aging-population markets seeking concentrated active delivery.
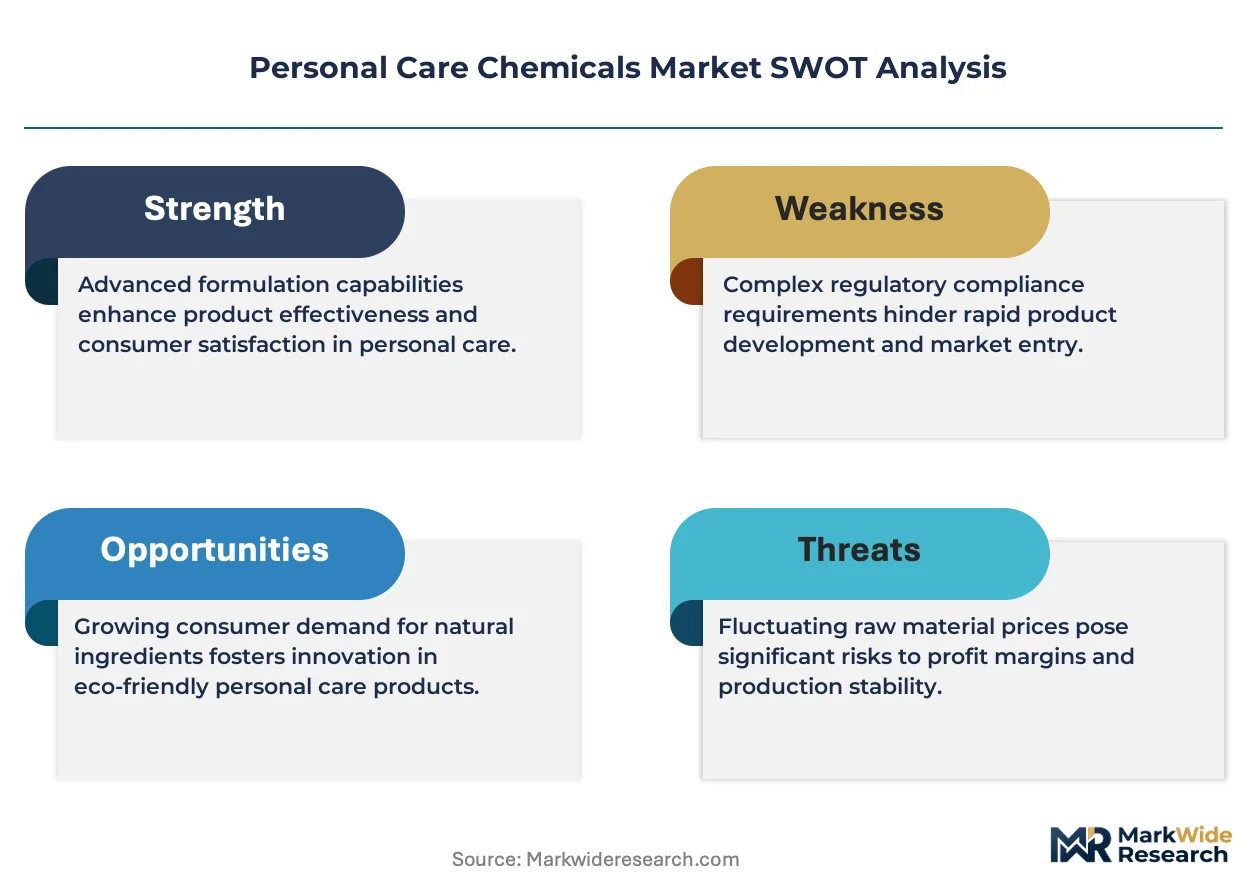
REACH registration in Europe, FDA cosmetic ingredient oversight in the United States, and China's GB standards for cosmetic raw materials collectively elevate compliance costs while screening out unqualified suppliers. ECHA's expanding SVHC candidate list pushes formulators toward green chemistry certifications ahead of mandatory restrictions. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that limits geographic market access.
Market Dynamics
Formulators face escalating pressure from ECHA's expanding SVHC candidate list, forcing simultaneous reformulation of emollients, surfactants, and preservatives while maintaining skin-feel performance and microbial stability.
Growth Catalysts
- EU Green Deal ingredient disclosure mandates:Brand owners accelerate procurement of bio-based emollients to preempt compliance deadlines and secure shelf access in European retail channels.
- China's domestic premium brand scaling:Local skincare manufacturers expand captive formulation facilities, driving concentrated demand for cosmetic-grade surfactants and active delivery systems.
- Fermentation-based synthesis maturation:Industrial biotechnology platforms achieve parity with petrochemical routes for medium-chain fatty acid esters, unlocking renewable feedstock qualification at scale.
Market Restraints
- Palm oil and coconut oil price volatility:Oleochemical feedstock fluctuations compress margin predictability for surfactant manufacturers serving mass-market personal care brands.
- Specialty lipid supplier concentration in Germany and Netherlands:Limited qualified sources for skin barrier repair lipids create procurement bottlenecks during ECHA evaluation periods.
- Preservative efficacy gaps in natural alternatives:Formulators struggle to match paraben performance with phenoxyethanol-free systems, constraining clean-label claims in water-based products.
Strategic Opportunities
- India's underpenetrated men's grooming segment:Urban male consumers adopt multi-step skincare routines, opening formulation partnerships for domestic contract manufacturers.
- Microbiome-friendly certification tailwind:Brands leverage prebiotic surfactant positioning to differentiate in prestige channels ahead of standardized testing protocols.
- Direct-to-consumer sampling integration:Subscription box channels demand miniaturized, stable emulsion formats, rewarding suppliers with rapid compounding turnaround capabilities.
Industry Challenges
- Cosmetic toxicologist talent scarcity:Formulation teams lack sufficient REACH dossier preparation expertise, delaying new ingredient registrations and market entry timelines.
- Legacy preservative system integration complexity:Reformulating established rinse-off products with alternative antimicrobial technologies requires extensive stability retesting without guaranteed performance equivalence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Chemicals Market |
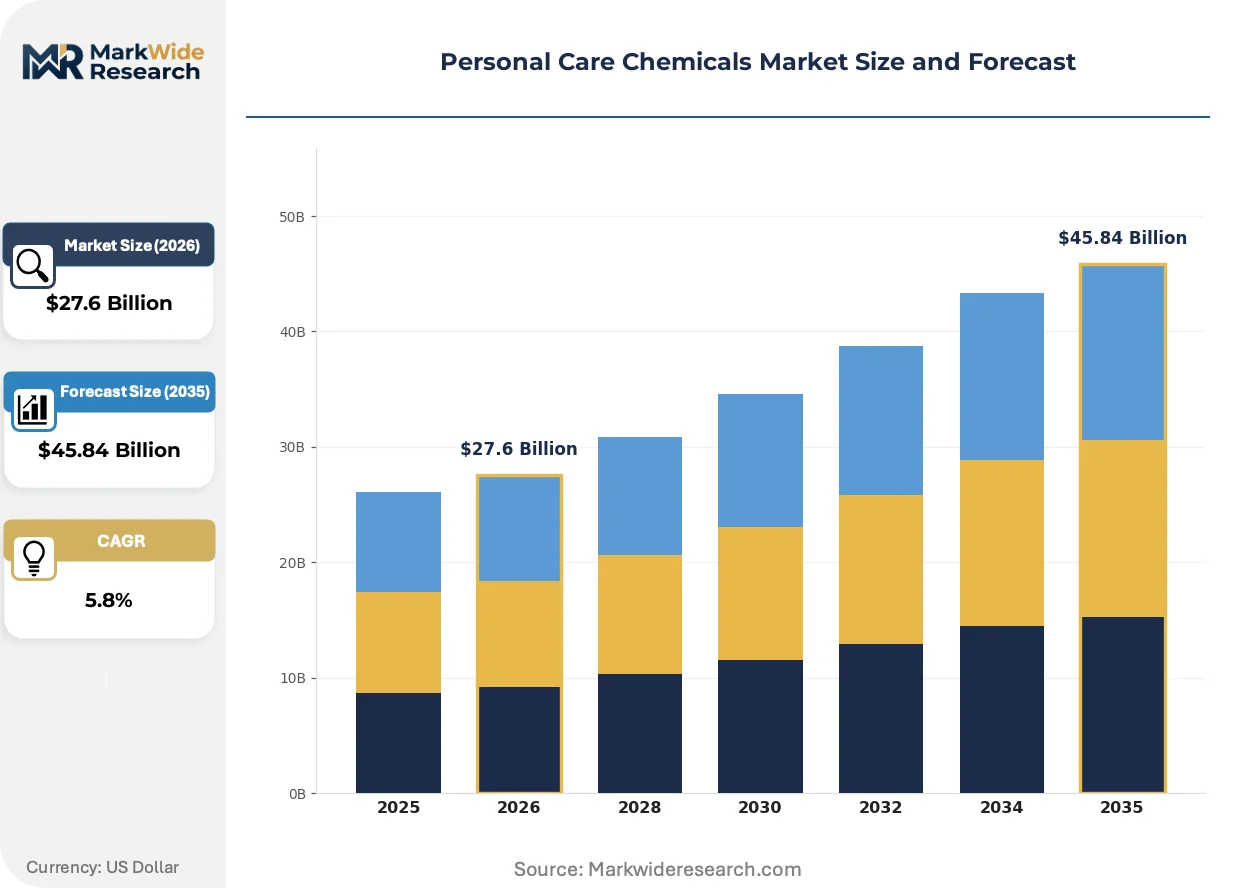
| Market Size in 2026 | $27.6 Billion |
| Market Size in 2035 | $45.84 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Emollients, Preservatives, Conditioners Application: Skincare, Haircare, Oral Care, Makeup Formulation: Lotion, Cream, Gel, Serum End User: Individual Consumers, Salons, Dermatologists, Manufacturers |
| Companies Covered | Dow Inc., Clariant AG, BASF SE, Syensqo SA/NV, Lonza Group AG, Croda International Plc, Ashland Global Holdings Inc., The Lubrizol Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Chemicals Market Strategic Shifts
Active ingredient delivery architectures and regulatory chemistry are converging to redefine competitive positioning in personal care formulation supply.
Encapsulation technology is modularizing active release profiles in serum and eye cream formats. Prestige skincare brands adopt lipid nanoparticle and cyclodextrin complex systems to protect retinoids and vitamin C from oxidation. This modularization enables formulators to decouple active stability from base emulsion chemistry, compressing development cycles for seasonal product lines.
REACH registration timelines are hardening entry barriers for novel cosmetic ingredients. ECHA's cumulative data requirements for skin sensitization and aquatic toxicity endpoints extend dossier preparation to 18-24 months. Small and mid-sized suppliers respond by prioritizing existing INCI-named materials over innovative chemistries, consolidating formulation option sets for brand owners.
Clean beauty certification is fragmenting procurement criteria across retail channels. Sephora's Clean at Sephora, Ulta's Conscious Beauty, and retailer-specific restricted substance lists force suppliers to maintain parallel documentation systems. Contract manufacturers in New Jersey and California invest in multi-standard auditing capabilities to serve divergent brand requirements without dedicated production lines.
Personal Care Chemicals Market Segmentation
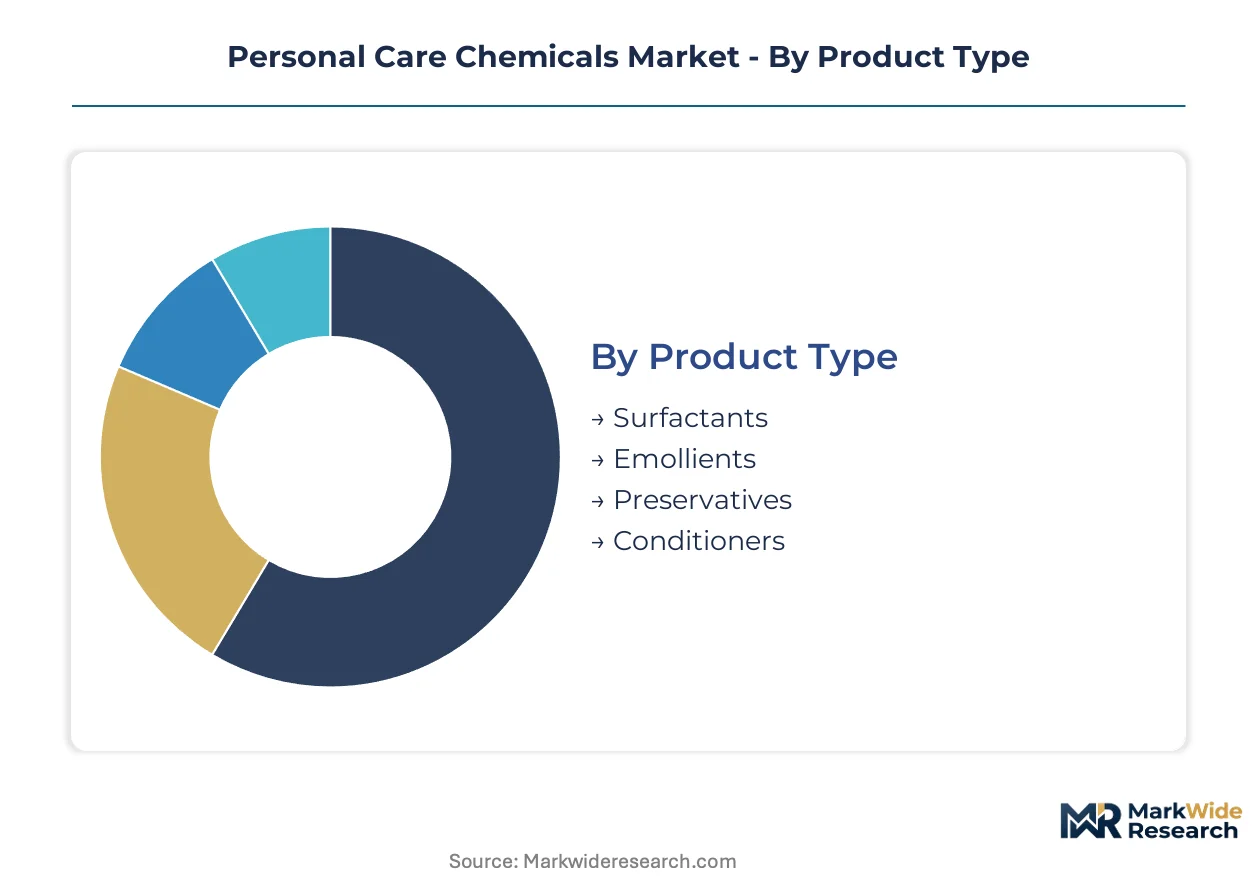
Personal care chemical suppliers configure production assets around distinct specification tiers that govern raw material selection, synthesis pathways, and certification requirements. Segmentation clarity determines which formulation capabilities warrant capital investment versus toll manufacturing arrangements.
Product Type:
Reformulation cycles accelerate as brand owners replace legacy chemistries with bio-qualified alternatives ahead of regulatory deadlines.
- Surfactants:Anionic, cationic, and amphoteric surface-active agents engineered at defined HLB values for cleansing efficacy. Mass-market shampoo manufacturers in China scale procurement of sulfate-free variants to serve domestic premium brand requirements while maintaining foam performance.
- Emollients:Esterified lipids and hydrocarbon oils delivering skin-feel modification at specified molecular weights. Specialty skincare houses in France and Germany concentrate demand for skin barrier repair lipids that meet ECHA's evolving SVHC screening protocols.
- Preservatives:Antimicrobial systems ensuring microbial stability across water-based formulations.
- Conditioners:Cationic polymers and quaternary compounds depositing on keratin surfaces for detangling.
Volume placements concentrate in surfactants; the faster expansion belongs to emollients.
Application:
End-use concentration patterns reflect demographic aging and male grooming adoption curves across metropolitan markets.
- Skincare:Serum, moisturizer, and cleanser formulations demanding cosmetic-grade purity with dermal compatibility testing. Aging-population markets in Japan and South Korea drive concentrated active delivery system procurement for retinoid and vitamin C stabilization.
- Haircare:Shampoo, conditioner, and treatment products requiring rinse-off surfactant systems.
- Oral Care:Toothpaste and mouthwash formulations with flavor stability and foaming requirements.
- Makeup:Pigment dispersion and long-wear film-forming technologies.
Haircare commands the largest absolute volume; skincare gains share fastest on per-unit value expansion.
Formulation:
Packaging format decisions determine emulsion stability specifications and preservative load requirements.
- Lotion:Oil-in-water emulsions at lower viscosity for pump dispensing.
- Cream:Higher internal phase emulsions delivering occlusion for dry skin conditions.
- Gel:Hydrocolloid-thickened systems with clarity requirements.
- Serum:Low-viscosity concentrated active vehicles with minimal emulsifier content. Prestige channels in urban China and the United States prioritize serum formats for multi-step routine positioning and higher per-ounce pricing.
Cream formulations retain the widest manufacturing base; serum production capacity is scaling fastest.
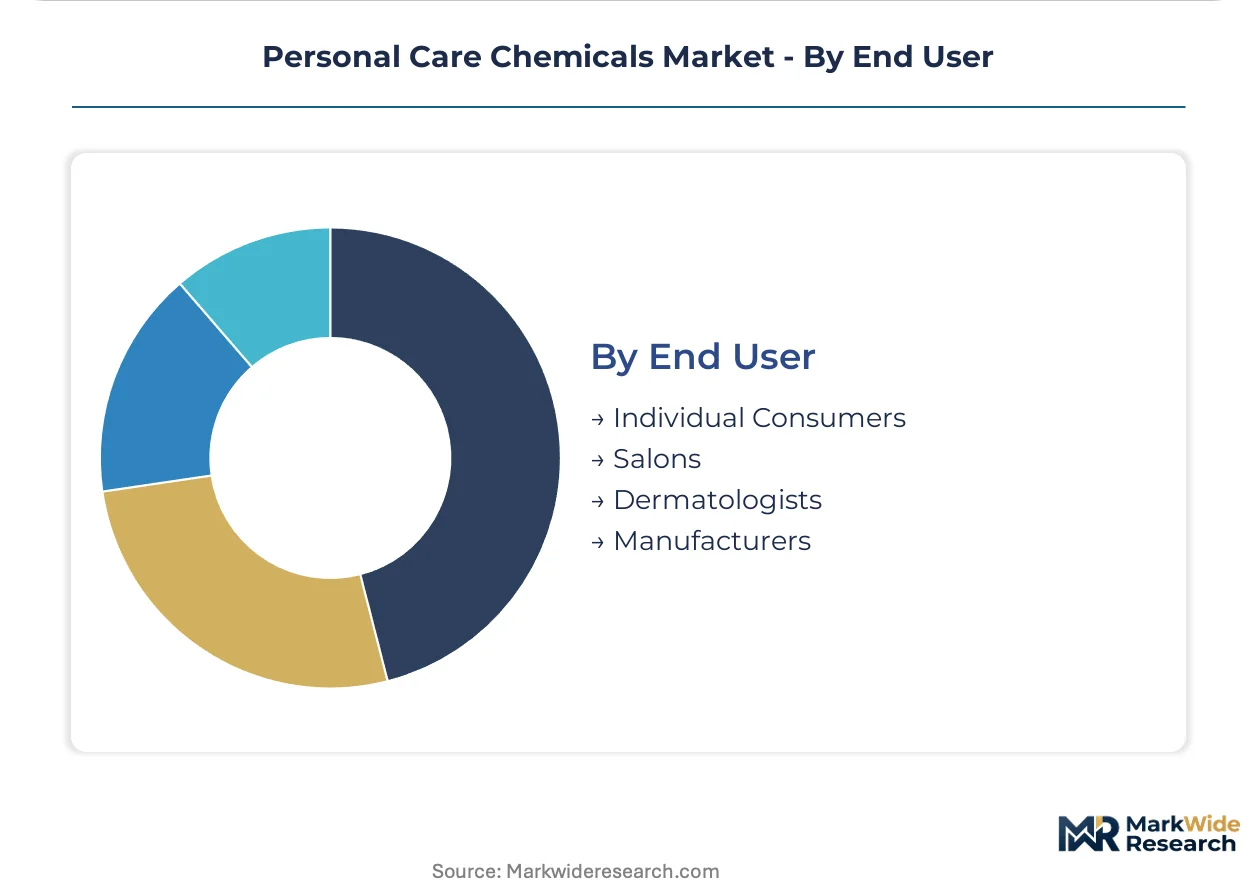
End User:
Channel structure determines batch size economics, documentation depth, and technical service intensity.
- Individual Consumers:Retail-packaged finished goods with mass-market formulation standards.
- Salons:Professional back-bar sizes with concentrated active claims.
- Dermatologists:Clinic-dispensed products requiring clinical testing documentation.
- Manufacturers:Contract and captive formulation facilities purchasing cosmetic-grade raw materials in bulk. Domestic skincare manufacturers in China expand captive blending operations, driving concentrated surfactant and emollient procurement at technical-grade specifications.
Manufacturers absorb the largest chemical volumes; dermatologist channel requirements are expanding most quickly on clinical positioning premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of personal care chemicals clusters in Germany and the Netherlands, while consumption accelerates fastest in China and India. This geographic split forces suppliers to maintain dual supply chain configurations—European manufacturing assets for REACH compliance and Asian distribution hubs for brand-owner proximity.
China
Domestic skincare brands scale captive formulation facilities in Shanghai and Guangzhou, driving concentrated procurement of cosmetic-grade surfactants. GB standards for cosmetic raw materials tighten purity specifications for imported emollients. The Yangtze River Delta hosts expanding fermentation-based synthesis capacity for medium-chain fatty acid esters.
Germany
Specialty lipid manufacturers in North Rhine-Westphalia supply skin barrier repair chemistries to prestige European skincare houses. ECHA's expanding SVHC candidate list forces simultaneous reformulation of legacy emollients and preservatives. BASF SE leverages integrated biotech platforms in Ludwigshafen to secure renewable feedstock qualification at scale.
United States
Contract manufacturers in New Jersey and California invest in multi-standard auditing capabilities to serve divergent clean beauty certifications. FDA cosmetic ingredient oversight elevates documentation depth for preservative efficacy claims. Greater Boston anchors clinical testing infrastructure serving dermatologist-dispensed product channels.
India
Urban male consumers in Mumbai and Bangalore adopt multi-step grooming routines, opening formulation partnerships for domestic contract manufacturers. BIS standards for cosmetic raw materials create compliance entry barriers for unqualified surfactant suppliers. Maharashtra scales technical-grade chemical blending operations to serve regional skincare brand expansion.
France
Prestige skincare houses in Paris concentrate demand for encapsulation technologies protecting retinoid stability. ANSM enforces ingredient disclosure requirements that exceed baseline EU mandates. Île-de-France hosts specialized lipid chemistry R&D serving barrier repair positioning in premium channels.
Personal Care Chemicals Market Competitive Environment
The competitive structure tilts toward integrated multinational chemical conglomerates with fermentation and oleochemical platforms. Tier-one suppliers combine REACH dossier expertise with bulk surfactant scale, while mid-cap specialists anchor positions through skin-feel differentiation and certification depth. Strategic moves concentrate on backward integration into renewable feedstocks and multi-standard auditing capabilities for clean beauty retail access.
Within the integrated conglomerate tier, BASF SE and Croda International Plc exemplify divergent positioning archetypes—BASF representing scale-driven biotech platform leverage, Croda occupying specialty lipid chemistry depth. Dow Inc. sits within the surfactant volume leadership segment, serving multinational brand owners with consistent bulk supply. Among European-based specialists, Evonik Industries AG anchors the active delivery systems vector through encapsulation technology positioning.
| Leading Market Players |
|---|
| Dow Inc. |
| Clariant AG |
| BASF SE |
| Syensqo SA/NV |
| Lonza Group AG |
| Croda International Plc |
| Ashland Global Holdings Inc. |
| The Lubrizol Corporation |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal ingredient disclosure mandates are forcing brand owners to accelerate procurement of bio-based emollients, compelling suppliers to reconfigure oleochemical feedstock sourcing and compress margin structures for REACH-compliant chemistries.
Pricing Analysis
Outcome-based pricing anchors emollient valuations to skin-feel performance metrics in prestige skincare formulations. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered specialty lipids from technical-grade surfactants and commodity bulk cleansers. Pricing pressure stems from palm oil and coconut oil volatility eroding surfactant margin predictability. Mass-market shampoo manufacturers exhibit highest price sensitivity, while prestige skincare houses absorb premiums for barrier repair lipid certification.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore manage hub-and-spoke patterns for oleochemical feedstocks and finished emollients. Manufacturing concentrates in Germany, the Netherlands, and China, with fermentation-based synthesis capacity scaling in the Yangtze River Delta. Raw material dependencies center on palm oil derivatives, coconut fatty acids, and renewable sugar feedstocks. Single-source vulnerability from specialty lipid supplier concentration in North Rhine-Westphalia creates procurement bottlenecks during ECHA evaluation windows. Distribution runs through contract manufacturers in New Jersey and California serving divergent clean beauty certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-based synthesis platforms are displacing petrochemical routes for medium-chain fatty acid esters, restructuring competitive economics for renewable emollient supply.
For Market Incumbents: Acquire fermentation-based biotech platforms to secure renewable feedstock qualification ahead of REACH registration deadlines. BASF SE's integrated Ludwigshafen operations demonstrate how backward integration into sugar-derived feedstocks defends margin position against oleochemical volatility. Prioritize multi-standard auditing capabilities for Sephora's Clean at Sephora and Ulta's Conscious Beauty divergent requirements. For New Entrants and Emerging Players: Launch via direct-to-consumer sampling integration channels targeting subscription box miniaturized emulsion formats. India's underpenetrated men's grooming segment in Mumbai and Bangalore offers concentrated white-space for multi-step skincare routine partnerships. Position through prebiotic surfactant microbiome-friendly certification ahead of standardized testing protocol finalization. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with REACH dossier expertise and skin-feel differentiation IP. Long-term viability hinges on fermentation platform scale and captive renewable feedstock supply. Watch for ECHA SVHC candidate list expansion velocity as signal for reformulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | BASF SE's sugar-based platform secures supply independence from palm oil volatility. |
| Multi-Standard Auditing Investment | New Jersey contract manufacturers serve Sephora and Ulta divergent clean beauty requirements. |
| Encapsulation Technology Licensing | Evonik Industries AG's lipid nanoparticle systems protect retinoid stability in prestige serums. |
| Fermentation Capacity Scale-Up | Yangtze River Delta facilities achieve parity with petrochemical routes for fatty acid esters. |
| REACH Dossier Expertise Acquisition | Croda International Plc anchors positioning through specialty lipid registration depth. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cosmetic formulators, procurement leads at domestic Chinese skincare brands, ECHA regulatory consultants, and contract manufacturing executives in New Jersey and California combined with secondary validation from Cefic chemical industry reports, FDA cosmetic ingredient guidance documents, and China customs import records. Bottom-up volume triangulation across surfactant, emollient, and preservative product tiers reconciled with top-down market sizing.
Granularity-level modeling operated at product type, application, formulation format, and end-user channel dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by per-unit value expansion in serum and encapsulation technology vectors. Forecast inputs incorporated ECHA SVHC candidate list expansion timelines, China GB standards tightening schedules, and fermentation platform capacity buildout curves.
ECHA regulatory acceleration, palm oil price volatility spikes, and clean beauty certification fragmentation are the dominant revision risks to projection assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Anti-Aging Products Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market