
 Cosmetic Dropper Market | 2026-2036
Cosmetic Dropper Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Dropper Market Outlook
Glass-to-plastic hybrid formulation technology is fragmenting traditional material sourcing strategies across cosmetic dropper supply chains. Albéa leverages its integrated European manufacturing footprint to sustain cost advantages in molded glass assemblies. Quadpack anchors its position through dedicated R&D centers in Barcelona specializing in sustainable resin formulations. Virospack competes by controlling decoration and finishing capabilities that differentiate premium serum presentations.
A cosmetic dropper is a precision dispensing closure consisting of a bulb, cap, and calibrated tube—typically borosilicate glass or pharmaceutical-grade polyethylene—designed to deliver controlled volumes of liquid personal care formulations. The mechanism relies on vacuum displacement through bulb compression, with tip orifice diameters ranging from 0.5mm to 2.0mm to accommodate viscosity variations across serums and essential oils. Glass droppers dominate premium skincare applications where chemical inertness and UV protection preserve active ingredient stability, while plastic droppers are gaining structural share in travel-size and disposable segments where weight reduction and breakage resistance outweigh optical clarity requirements. Child-resistant droppers represent a concentrated margin pool as regulatory mandates expand beyond pharmaceuticals into cosmeceutical categories.
REACH compliance through ECHA governs substance restrictions in rubber bulb compounds and colored glass coatings, directly shaping material substitution timelines for European manufacturers. The EU Green Deal's packaging waste directives are forcing reformulation of multi-component assemblies to improve recyclability, while FDA cosmetic labeling requirements for US-bound exports demand precise volume graduation markings on dropper tubes. Stakeholders must monitor how forthcoming extended producer responsibility frameworks recalibrate cost structures across single-use versus reusable dropper formats.
Market Dynamics
EU F-Gas Regulation and REACH substance restrictions are forcing rapid material substitution across cosmetic dropper supply chains, compressing lead times for compliant rubber bulb and glass coating formulations while premium skincare brands accelerate precision dosing adoption.
Growth Catalysts
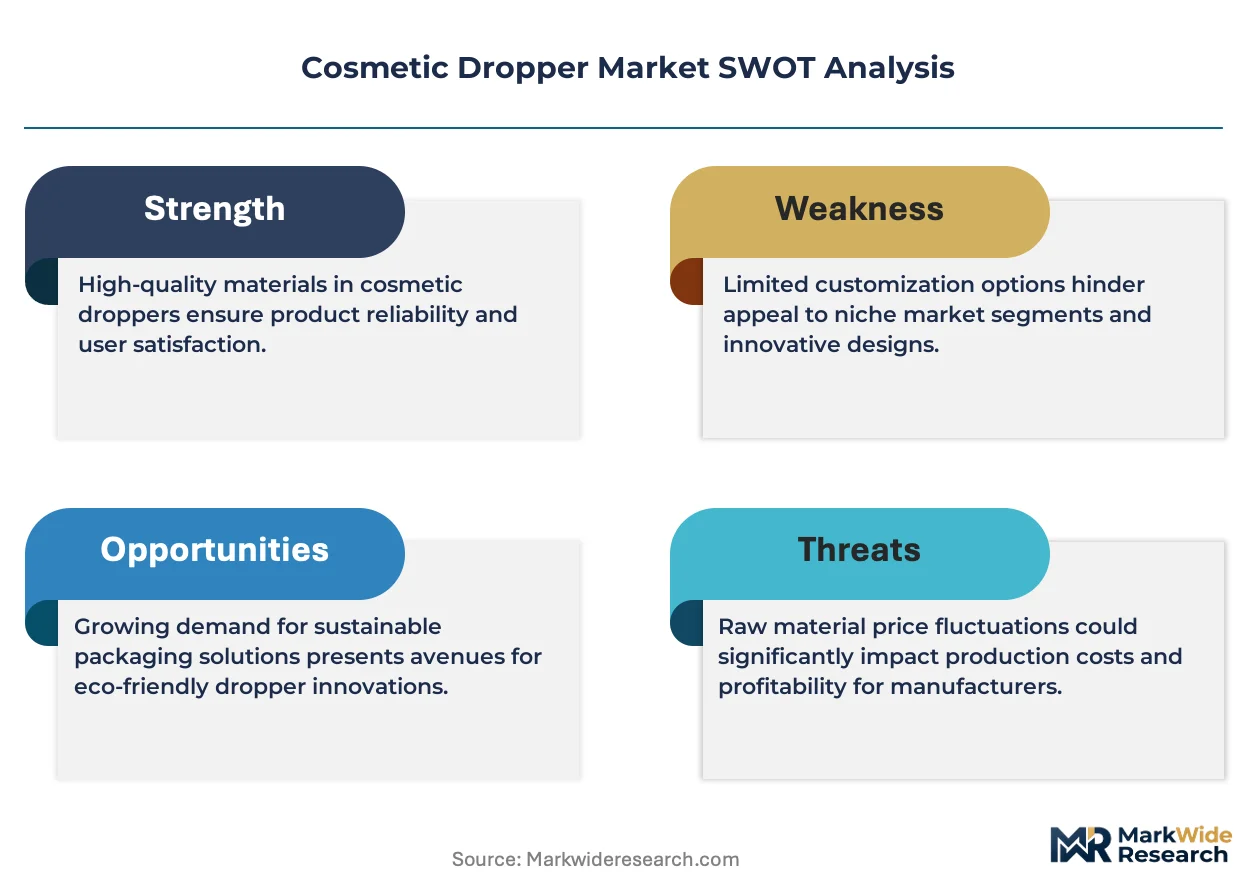
- REACH chemical compliance mandates:ECHA substance restrictions on phthalates and heavy metals in rubber compounds are accelerating certified material adoption, pulling demand toward pre-qualified European suppliers with validated testing protocols.
- Serum formulation complexity:High-actives skincare brands require calibrated dropper orifices below 1.0mm for peptide and retinol concentrates, expanding specification depth across premium packaging procurement.
- Hamburg-Rhine-Ruhr manufacturing concentration:German cosmetic production clusters around these hubs are consolidating specialized dropper sourcing, creating captive demand for regional molders with decoration capabilities.
Market Restraints
- Borosilicate glass supply concentration:Three European specialty glassmakers control pharmaceutical-grade tubing supply, exposing brands to allocation risk during energy price spikes.
- Multi-component recyclability barriers:Glass-bulb-cap assemblies with incompatible materials face EU Green Deal packaging waste penalties, forcing costly redesign cycles.
- Pharmaceutical-grade polymer cost volatility:Medical polyethylene and polypropylene resin indices track crude oil and natural gas feedstocks, compressing margin stability for plastic dropper specialists.
Strategic Opportunities
- Child-resistant mandate expansion:EU safety standards are extending beyond pharmaceuticals into cosmeceutical categories, opening certified closure development contracts for compliant suppliers.
- Travel-size segment penetration:Plastic dropper demand in sub-15ml formats for airline retail and subscription sampling is outpacing glass adoption, rewarding lightweight material innovation.
- UV-actives protection convergence:Integration of amber and cobalt glass with oxygen-scavenging bulb compounds is creating premium positioning for oxidation-sensitive vitamin C and ferulic acid formulations.
Industry Challenges
- Decoration chemistry compliance:REACH restrictions on solvent-based inks and metallic coatings for glass are forcing water-based alternative validation, extending color-matching timelines for brand launches.
- Volume graduation precision:FDA cosmetic labeling requirements for US-bound exports demand calibrated tube markings within 5% tolerance, requiring capital investment in laser etching or pad printing automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Dropper Market |
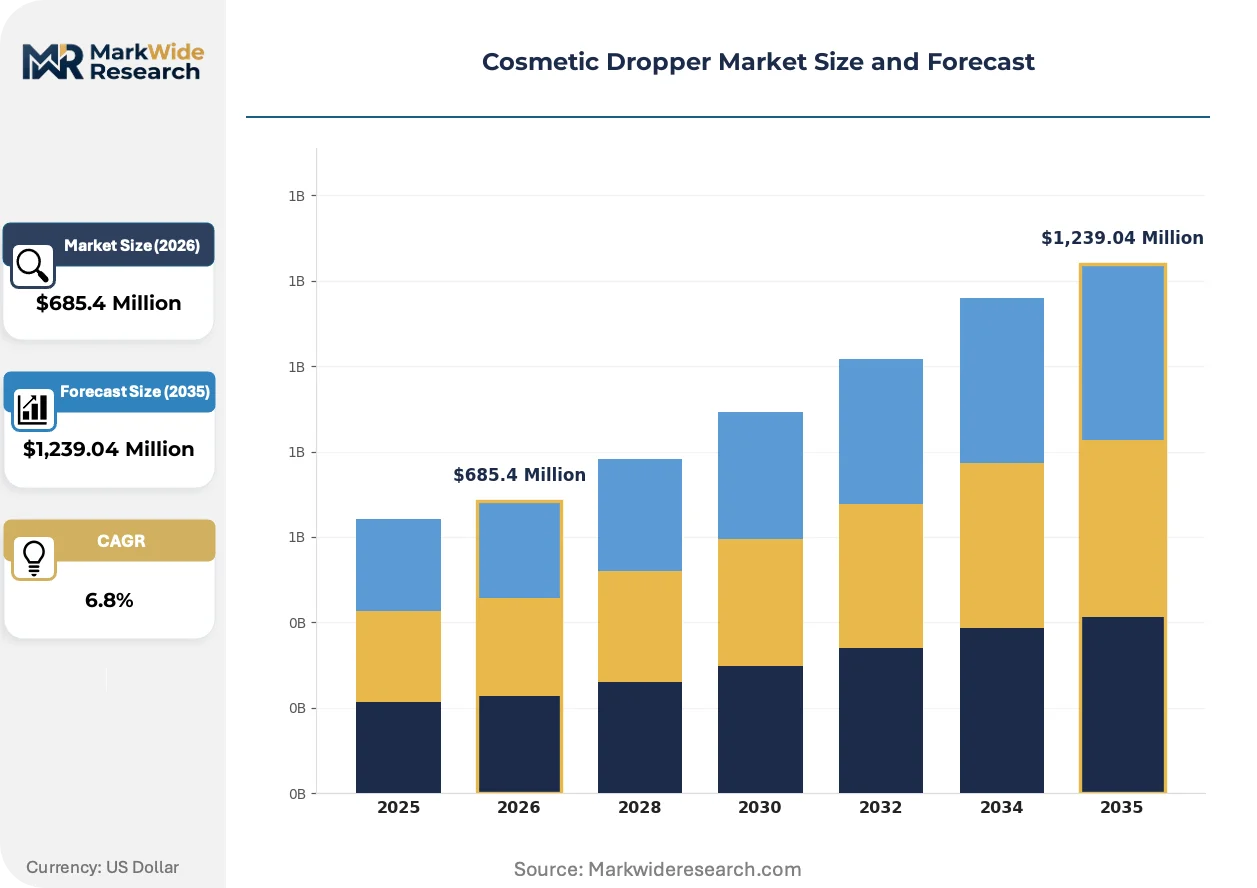
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
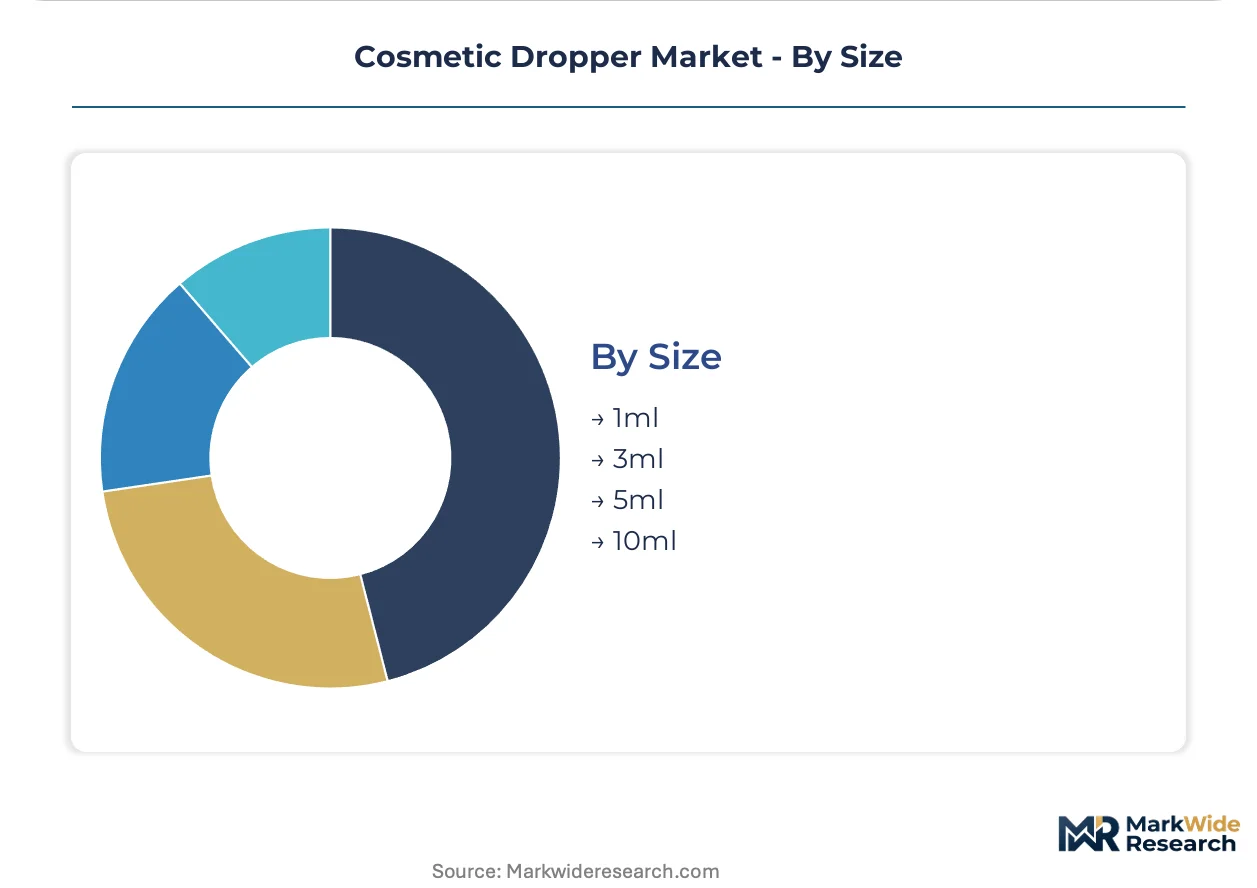
| Segmentation | Product Type: Glass Droppers, Plastic Droppers, Child-Resistant Droppers, Reusable Droppers End User: Skincare Brands, Cosmetic Manufacturers, Retail Outlets, E-commerce Platforms Application: Serums, Essential Oils, Herbal Extracts, Makeup Products Size: 1ml, 3ml, 5ml, 10ml |
| Companies Covered | Albéa, Quadpack, Virospack, Coverpla, Silgan Holdings, Aptar Beauty, Gerresheimer, Raepak, Lumson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Dropper Market Strategic Shifts
Material hybridization and regulatory tightening are compressing traditional sourcing models while precision dosing requirements fragment specification standards across cosmetic dropper categories.
Glass-to-plastic hybrid formulation technology combines pharmaceutical-grade polyethylene tubes with borosilicate glass reservoirs, preserving chemical inertness for actives while reducing breakage risk. Mid-market skincare brands in Germany and France are adopting these assemblies for e-commerce channels where shipping damage claims erode margin. The convergence is rendering obsolete single-material dropper specifications that cannot balance protection with weight reduction.
ECHA's 2023 expansion of REACH candidate list substances to include additional rubber accelerators and plasticizers is forcing bulb compound reformulation across European manufacturing. Suppliers with in-house polymer laboratories are compressing certification timelines, while smaller molders face 12-18 month validation gaps. Child-resistant droppers for cosmeceutical applications face the steepest compliance burden, as dual safety and chemical standards converge.
Direct-to-brand procurement platforms are disintermediating traditional packaging distributors for dropper volumes above 500,000 units annually. Beauty conglomerates in the Netherlands and Sweden are consolidating supplier bases through digital tendering, compressing price discovery cycles from quarters to weeks. This channel shift is most visible among clean beauty brands prioritizing transparent supply chain documentation for ESG reporting under EU CSRD requirements.
Cosmetic Dropper Market Segmentation
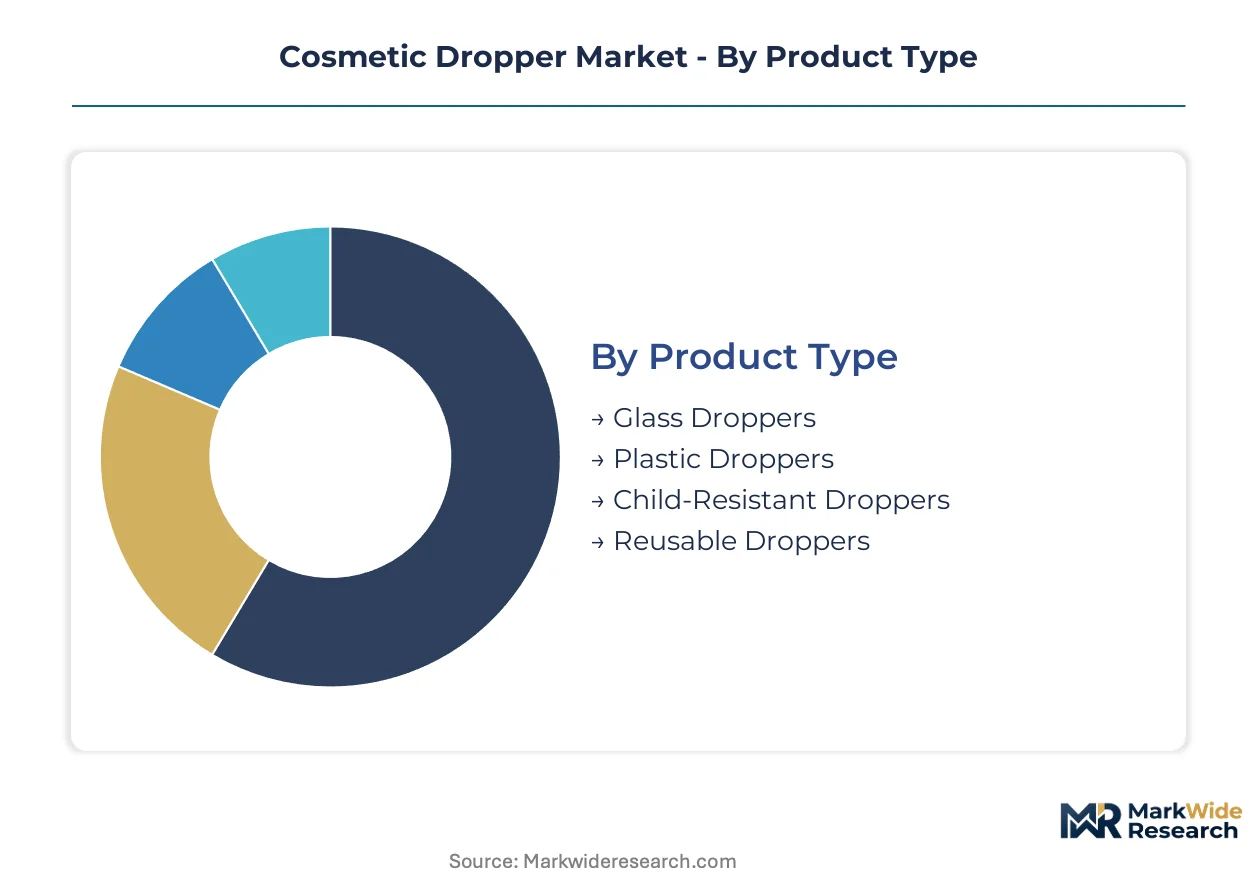
Precision dosing requirements fragment cosmetic dropper procurement across material grades, safety certifications, and volume calibrations. Specification depth varies sharply between pharmaceutical-grade skincare actives and mass-market color cosmetics, forcing suppliers to maintain parallel production capabilities.
Product Type:
After-sales service intensity escalates with product complexity—glass droppers demand breakage replacement programs while child-resistant formats require regulatory recertification support.
- Glass Droppers:Borosilicate or soda-lime glass tubes paired with natural rubber or nitrile bulbs deliver chemical inertness for oxidation-sensitive formulations. Hamburg-based premium skincare manufacturers specify amber and cobalt variants for UV-blocking of vitamin C and retinol serums, with REACH-compliant bulb compounds now mandatory under ECHA's expanded substance restrictions.
- Plastic Droppers:Pharmaceutical-grade polyethylene and polypropylene assemblies reduce shipping weight and eliminate breakage claims in e-commerce channels. Travel-size subscription boxes and airline retail in Germany favor sub-5ml formats where optical clarity requirements are secondary to durability.
- Child-Resistant Droppers:Dual-mechanism closures combining push-and-turn caps with calibrated tubes face expanding EU safety mandates beyond pharmaceuticals into cosmeceuticals.
- Reusable Droppers:Refillable glass-reservoir designs with replaceable bulb components target clean beauty brands prioritizing packaging waste reduction under EU Green Deal directives.
Glass droppers hold the largest share; momentum sits with child-resistant formats as regulatory scope widens.
End User:
Procurement scale and specification authority concentrate differently across contract manufacturers versus brand-direct channels.
- Skincare Brands:Direct formulation knowledge drives precise orifice diameter and graduation marking requirements for high-actives serums. German peptide and retinol specialists demand sub-1.0mm tip tolerances with laser-etched volume indicators.
- Cosmetic Manufacturers:Contract packagers serving multiple brand houses prioritize modular dropper platforms compatible with diverse bottle neck finishes and decoration chemistries.
- Retail Outlets:Private-label fragrance and essential oil programs favor standardized 5ml-10ml formats with solvent-based pad printing for rapid logo application.
- E-commerce Platforms:Direct-to-consumer sampling programs and subscription boxes favor lightweight plastic droppers with breakage-resistant construction for last-mile durability.
Skincare brands command specification authority; e-commerce platforms are expanding most quickly as channel share shifts.
Application:
Viscosity range and oxidation sensitivity determine material selection and protective features across formulation categories.
- Serums:High-actives skincare concentrates with low viscosity require precision orifice control and oxygen-scavenging bulb compounds. Vitamin C and ferulic acid formulations in Germany and France drive demand for amber glass with nitrogen-flushed assembly environments.
- Essential Oils:Volatile aromatic compounds necessitate chemical-resistant bulb materials and tight-sealing cap interfaces to prevent evaporation and degradation.
- Herbal Extracts:Plant-based tinctures with variable particulate content require wider tip diameters and graduated dosing for consumer-controlled dispensing.
- Makeup Products:Liquid foundations and color correctors with higher viscosity and pigment loading favor larger orifice droppers or pump alternatives.
Serums dominate value contribution; essential oils show steepest expansion trajectory as wellness positioning spreads.
Size:
Volume calibration precision tightens at smaller formats where dosing accuracy directly impacts consumer safety and brand liability.
- 1ml:Micro-sampling formats for clinical trial distribution and luxury trial programs require ultra-precise graduation markings within tight FDA cosmetic labeling tolerances.
- 3ml:Travel-size and subscription sampling segments favor this format for TSA compliance and single-treatment dosing of premium actives.
- 5ml:Standard trial size balancing portability with sufficient volume for efficacy demonstration across multi-day regimens.
- 10ml:Full-treatment miniatures for airline retail and gift-with-purchase programs where breakage risk must be minimized.
5ml holds the largest share; 3ml formats are gaining share fastest as sampling economics tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cosmetic dropper manufacturers export precision-dosing assemblies to premium skincare brands across France, the United Kingdom, and the Netherlands, with Hamburg-Rhine-Ruhr production clusters commanding specialized procurement relationships.
Germany
Hamburg's premium cosmetic manufacturing hub and the Rhine-Ruhr packaging belt drive concentrated demand for REACH-compliant glass droppers with calibrated sub-1.0mm orifices. ECHA's expanded substance restrictions on rubber accelerators force bulb compound reformulation among local molders. Bavaria-based clean beauty brands are consolidating supplier bases through digital tendering platforms.
France
Parisian luxury skincare houses and Provence essential oil distillers require amber glass droppers with oxygen-scavenging bulb compounds for oxidation-sensitive formulations. ANSM guidance on cosmeceutical safety standards is extending child-resistant mandate scope beyond pharmaceuticals. The Île-de-France region hosts specialized decoration facilities serving premium serum presentations.
United States
FDA cosmetic labeling requirements for volume graduation markings within 5% tolerance are reshaping procurement specifications for US-bound European exports. Direct-to-consumer sampling programs in California and New York favor lightweight plastic droppers for last-mile durability. Midwest contract manufacturers are consolidating modular dropper platforms compatible with diverse bottle neck finishes.
United Kingdom
London-based clean beauty startups and Manchester contract packagers prioritize transparent supply chain documentation for EU CSRD-aligned ESG reporting. The UK REACH framework maintains substance restrictions parallel to ECHA standards post-Brexit. Southeast England logistics corridors facilitate just-in-time dropper deliveries to European distribution hubs.
Italy
Lombardy fragrance houses and Emilia-Romagna cosmetic manufacturers specify solvent-based pad printing for rapid logo application on standardized 5ml-10ml formats. Italian packaging distributors face disintermediation pressure from direct-to-brand procurement platforms above 500,000-unit annual volumes. Milan's design studios influence premium dropper aesthetics for global luxury brands.
Cosmetic Dropper Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base organizes around three strategic archetypes: integrated European manufacturers with captive glass molding, decoration-focused specialists controlling finishing capabilities, and scale-driven polymer processors serving high-volume plastic formats. Dominant competitive moves include backward integration into pharmaceutical-grade resin formulation and geographic expansion through dedicated R&D center establishment.
Among France-based packaging conglomerates, Albéa occupies a position representing integrated manufacturing footprint advantages. Quadpack exemplifies the R&D-led archetype through its Barcelona-based sustainable resin specialization. Virospack anchors the decoration-specialist tier with controlled finishing capabilities for premium serum presentations. These three entities collectively illustrate how European suppliers are responding to REACH compliance compression and EU Green Deal recyclability mandates through differentiated capability investments.
| Leading Market Players |
|---|
| Albéa |
| Quadpack |
| Virospack |
| Coverpla |
| Silgan Holdings |
| Aptar Beauty |
| Gerresheimer |
| Raepak |
| Lumson |
| Others |
Value Chain & Pricing Dynamics
Rhine-Ruhr logistics corridors connecting German glass molders to Hamburg cosmetic manufacturers impose freight cost premiums that compound with borosilicate supply concentration, pushing price differentiation toward REACH certification tiers and forcing mid-market buyers toward plastic hybrid alternatives.
Pricing Analysis
Current-generation glass-to-plastic hybrid assemblies command 15-25% premiums over prior-generation all-glass formats, while next-generation oxygen-scavenging bulb compounds with nitrogen-flushed assembly environments sit at the apex. Three-tier pricing structure across premium amber-cobalt glass, standard soda-lime variants, and economy polyethylene formats tracks REACH compliance depth and orifice calibration precision. Cost compression in standard tiers is intensifying because pharmaceutical-grade polymer resin indices tie to volatile natural gas feedstocks. Contract manufacturers serving multiple brand houses exhibit highest price sensitivity; peptide-specialist skincare brands with direct formulation knowledge show lowest.
Supply Chain Analysis
EU F-Gas Regulation export-control restrictions on fluorinated greenhouse gases limit flows of specialized glass-coating technologies to non-compliant overseas facilities, reshaping regional sourcing patterns. Supply concentrates in Germany, France, and Italy, with Hamburg-Rhine-Ruhr production clusters anchoring pharmaceutical-grade glass tubing and Lombardy molders controlling decoration chemistry. Raw material dependencies rest on borosilicate glass from three European specialty makers, natural rubber bulb compounds subject to ECHA accelerator restrictions, and pharmaceutical-grade polyethylene resins. Single-source vulnerability in borosilicate tubing exposes brands to allocation risk during energy price spikes. Distribution runs through direct-to-brand procurement platforms disintermediating traditional packaging distributors above 500,000-unit annual volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as premium skincare brands restock precision-dosing inventory following post-pandemic destocking cycles and EU regulatory clarity stabilizes material substitution timelines.
For Market Incumbents: Insulate margin position through backward integration into pharmaceutical-grade resin formulation and captive bulb compound laboratories that compress REACH certification timelines. ECHA's 2023 rubber accelerator restrictions threaten smaller molders with 12-18 month validation gaps; incumbents with in-house polymer capabilities can capture distressed demand. Capacity concentration in Hamburg-Rhine-Ruhr clusters reinforces regional procurement relationships against digital platform disintermediation. For New Entrants and Emerging Players: Pursue white-space opportunities in child-resistant cosmeceutical droppers where EU safety mandate expansion outpaces certified supplier capacity. The 3ml travel-size segment for subscription sampling shows fastest penetration with lowest incumbent saturation. Go-to-market through direct-to-brand digital tendering platforms serving Netherlands and Sweden clean beauty brands prioritizing transparent supply chain documentation for CSRD-aligned ESG reporting. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underperforming dropper divisions lacking REACH-compliant material portfolios. Long-term viability centers on suppliers controlling decoration chemistry and oxygen-scavenging bulb formulation as premium serum complexity escalates. Watch ECHA substance list expansion velocity as inflection indicator for material substitution capex cycles and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | In-house pharmaceutical-grade polyethylene development compresses REACH certification timelines against ECHA restrictions. |
| Child-Resistant Certification Investment | Dual-mechanism closure capabilities capture EU safety mandate expansion beyond pharmaceuticals into cosmeceuticals. |
| Digital Procurement Platform Partnership | Direct-to-brand channel access serves Netherlands and Sweden clean beauty ESG documentation requirements. |
| Decoration Chemistry Capability Acquisition | Water-based ink and laser etching expertise addresses REACH solvent-based coating restrictions for premium presentations. |
| Regional Production Cluster Expansion | Hamburg-Rhine-Ruhr proximity reinforces specialized procurement relationships with German peptide serum manufacturers. |
Study Parameters
Desk research of ECHA substance restriction databases, EU packaging waste directive filings, and pharmaceutical-grade glass trade flows preceded structured interviews with procurement directors at German skincare brands, technical R&D leads at European packaging molders, and regulatory affairs specialists navigating REACH compliance. Primary fieldwork with Hamburg-Rhine-Ruhr manufacturing clusters and Barcelona sustainable resin laboratories combined with secondary validation from customs records and industry association reports. Bottom-up volume modeling across material grades and orifice specifications triangulated with top-down premium skincare production estimates.
Assumptions held fixed include ECHA regulatory enforcement intensity, EU Green Deal packaging waste penalty structures, and pharmaceutical-grade resin feedstock cost pass-through mechanisms; variables tested included child-resistant mandate expansion velocity and direct-to-brand procurement platform adoption rates. The analytical framework modeled segmentation across glass-plastic-hybrid material tiers, calibrated orifice diameter bands, end-user specification authority levels, and regional manufacturing cluster proximity. CAGRs derived from installed base replacement cycles and premium serum formulation complexity trajectories. Forecast inputs incorporated oxidation-sensitive actives growth and airline retail travel-size demand elasticity.
Macroeconomic conditions sit as an overlay; deviation in natural gas feedstock pricing, freight corridor cost structures, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and brand inventory restocking patterns. Material shifts in ECHA candidate list expansion scope or F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market