
 Global Hyaluronic Acid Based Dermal Fillers Market | 2026-2036
Global Hyaluronic Acid Based Dermal Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hyaluronic Acid Based Dermal Fillers Market Foresight
Project finance and leasing arrangements for aesthetic clinic equipment is tilting competitive dynamics toward asset-light expansion models. AbbVie Inc. leverages its Allergan heritage to dominate branded filler portfolios across North America and Europe. Galderma S.A. anchors its position through dermatology-centric channel control and physician education investments. Hugel Inc. competes aggressively on manufacturing scale from its South Korean production base.
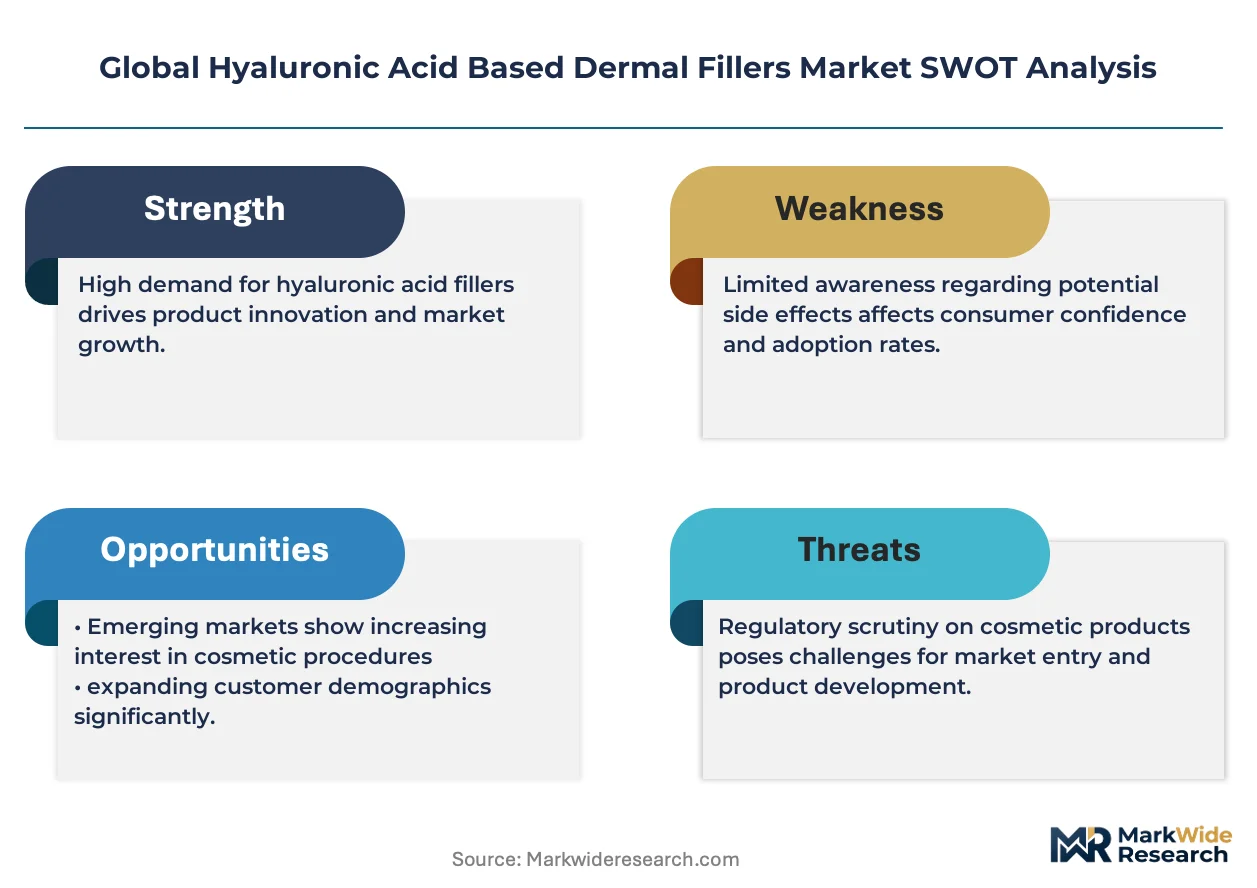
Hyaluronic acid based dermal fillers constitute injectable, biodegradable gels formulated with cross-linked sodium hyaluronate at concentrations ranging from 20 to 25 mg/mL, designed to restore facial volume and correct contour deficiencies through tissue integration and water retention. The monophasic segment sustains premium positioning due to smoother extrusion properties and reduced post-injection swelling, while biphasic formulations occupy the high-volume mainstream through established clinical familiarity and cost accessibility. Dermatology clinics and aesthetic centers concentrate margin capture through direct-to-practitioner distribution, whereas online pharmacies represent the fastest-growing channel as telehealth consultations normalize prescription workflows.
FDA 510(k) clearance requirements and the EU Medical Device Regulation impose biocompatibility and stability testing burdens that filter out undercapitalized entrants. The EU AI Act and ISO 13485 quality management standards further shape product development timelines and post-market surveillance obligations. Stakeholders must monitor evolving reimbursement classifications for aesthetic versus reconstructive indications, as payer decisions will determine addressable patient populations across key markets.
Market Dynamics
Cross-linked sodium hyaluronate concentration wars and the EU Medical Device Regulation's biocompatibility testing burdens are compressing development timelines while filtering undercapitalized entrants from commercialization pipelines.
Growth Catalysts
- Telehealth normalization:Online pharmacies accelerate prescription workflows for aesthetic consultations, bypassing traditional clinic gatekeepers in the United States and Brazil.
- MFDS regulatory efficiency:South Korea's streamlined premarket pathways enable faster product iterations for monophasic gel formulations targeting Asian facial anatomy preferences.
- Asset-light clinic expansion:Project finance and leasing arrangements for injection equipment reduce capital barriers for independent aesthetic centers.
Market Restraints
- Fermentation-grade hyaluronate input volatility:Pharmaceutical-grade raw material costs fluctuate with bioreactor capacity constraints in Chinese manufacturing hubs.
- EU MDR compliance burden:Stability testing and post-market surveillance obligations extend certification timelines by 18-24 months for non-European manufacturers.
- Calcium hydroxylapatite substitution:Longer-lasting synthetic alternatives capture volume in deep-tissue volumizing applications.
Strategic Opportunities
- Male aesthetic underpenetration:Jawline contouring and tear-trough correction protocols for male patients remain underserved across German and Australian markets.
- Combination therapy protocols:Adjunctive use with energy-based devices creates bundled service revenue streams in premium Dubai and London clinics.
- Reconstructive indication expansion:HIV-associated lipoatrophy and post-oncology facial restoration qualify for partial reimbursement in select Swiss and Canadian jurisdictions.
Industry Challenges
- Vascular occlusion management training:Hyaluronidase administration competency gaps persist among newly certified injectors in high-volume Brazilian medical spas.
- ISO 13485 quality system implementation:Small-scale manufacturers struggle with document control and risk management file maintenance for MDR technical documentation.
- Cold chain integrity:Temperature excursions during cross-border distribution compromise gel rheological properties in emerging market logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hyaluronic Acid Based Dermal Fillers Market |
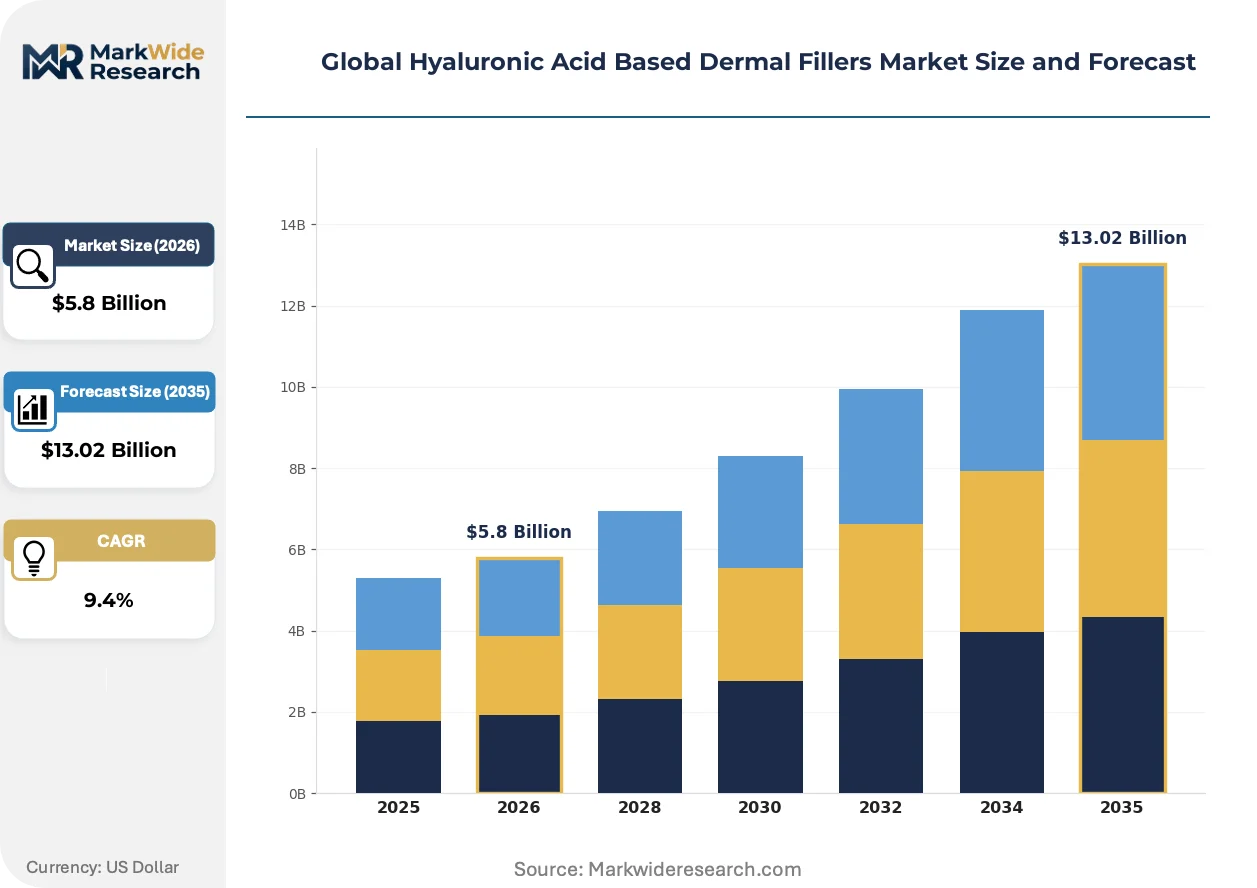
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monophasic, Biphasic, Cohesive Polydensified Matrix, Hybrid Fillers Application: Wrinkle Reduction, Lip Augmentation, Cheek Enhancement, Scar Treatment, Nasolabial Fold Correction End User: Dermatology Clinics, Aesthetic Centers, Plastic Surgery Clinics, Medical Spas Distribution Channel: Hospital Pharmacies, Specialty Stores, Online Pharmacies, Direct Sales |
| Companies Covered | Teoxane SA, Sinclair Pharma plc., AbbVie Inc., BioPlus Co. Ltd., Hugel Inc., Galderma S.A., LG Chem Ltd., Prollenium Medical Technologies Inc., Merz Pharma GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hyaluronic Acid Based Dermal Fillers Market Shifts & Advancements
Digital injection guidance systems and predictive rheology modeling are compressing the gap between formulation science and individualized treatment outcomes across premium clinic networks.
Artificial intelligence-powered facial mapping software is virtualizing the consultation-to-treatment pathway. Aesthetic practitioners in Seoul and Los Angeles deploy 3D simulation platforms to preview volumetric outcomes before needle insertion. This technology is virtualizing traditional informed consent processes while reducing revision rates and liability exposure.
The EU AI Act's risk classification framework for medical device software imposes conformity assessment obligations on algorithmic treatment planning tools. Manufacturers integrating machine learning into injection guidance systems must now maintain technical documentation and post-market monitoring equivalent to Class IIa devices. German notified bodies report 40% backlog increases for software-as-medical-device certifications.
Direct-to-practitioner distribution models disintermediate traditional pharmaceutical wholesalers. Galderma and AbbVie deploy proprietary e-commerce portals with real-time inventory visibility and physician education modules. This channel compression concentrates margin capture with manufacturers while reducing price transparency for independent clinic buyers in the United States and United Kingdom.
Global Hyaluronic Acid Based Dermal Fillers Market Segmentation
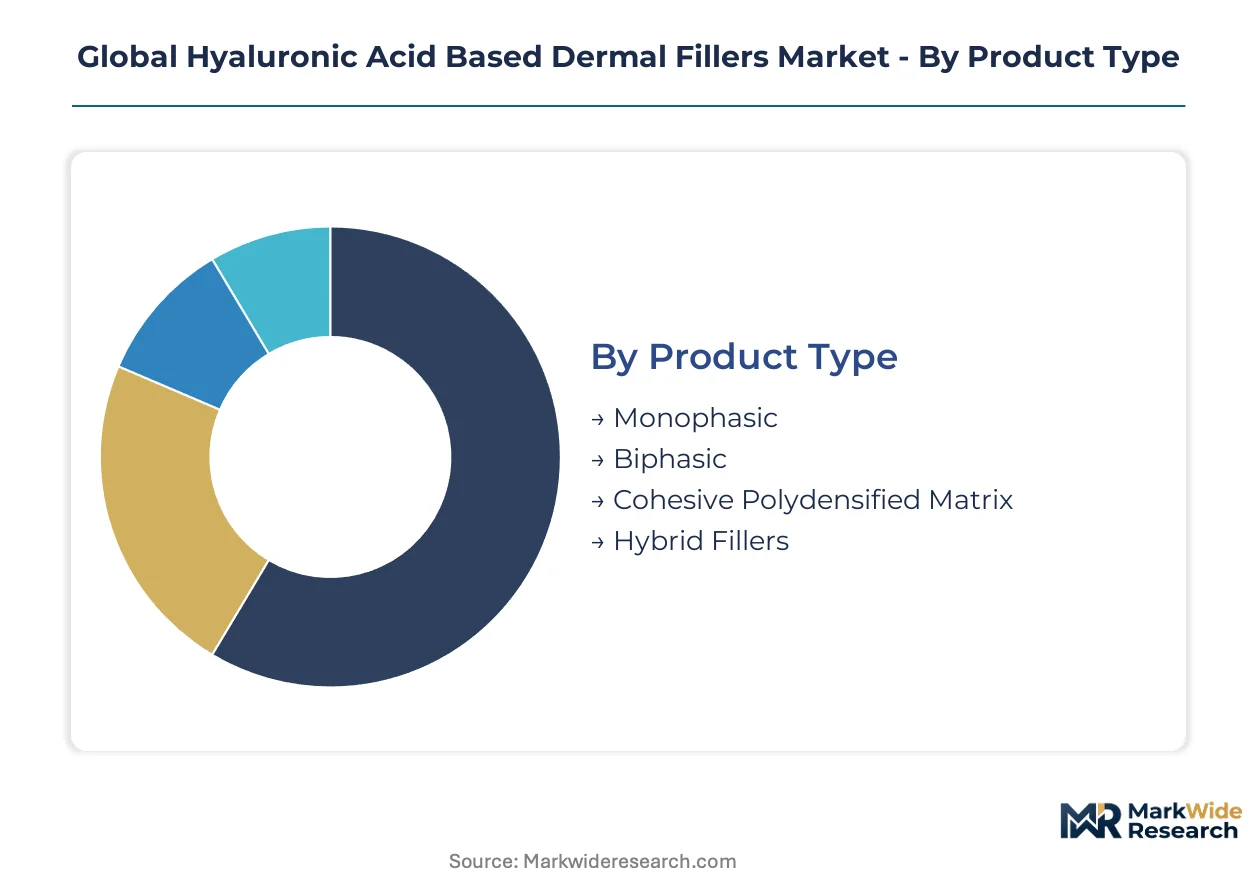
Segmentation in hyaluronic acid based dermal fillers reveals how formulation science, injection site anatomy, and channel economics partition commercial opportunity across distinct competitive arenas. Each category carries different margin profiles, regulatory burdens, and practitioner training requirements that shape vendor strategy.
Product Type:
After-sales-service intensity varies sharply by product type — monophasic formulations demand minimal post-injection support while hybrid fillers require intensive practitioner onboarding and complication management protocols.
- Monophasic:Single-phase cross-linked sodium hyaluronate gels deliver uniform particle distribution and smoother extrusion through fine-gauge needles. Demand concentrates in Seoul and Los Angeles aesthetic centers where practitioners prioritize reduced post-injection swelling and downtime for time-pressed patients. The EU MDR's biocompatibility documentation requirements favor established manufacturers with technical file depth.
- Biphasic:Suspensions of cross-linked gel particles in non-cross-linked hyaluronate carrier phase occupy mainstream clinical practice through established handling familiarity and cost accessibility. German dermatology clinics and Brazilian medical spas drive volume through standardized injection protocols and predictable volumetric outcomes.
- Cohesive Polydensified Matrix:Density-gradient formulations optimize tissue integration for superficial dermal placement. Swiss aesthetic centers specify these for tear-trough and perioral applications requiring natural expression preservation.
- Hybrid Fillers:Dual-technology combinations incorporating both hyaluronic acid and calcium hydroxylapatite or poly-L-lactic acid components. Dubai premium clinics adopt these for patients seeking extended duration without surgical intervention.
By volume, Biphasic leads. By growth pace, Monophasic is ahead.
Application:
Application segmentation tracks how facial anatomy zones dictate formulation rheology requirements and practitioner specialization depth.
- Wrinkle Reduction:Superficial and mid-dermal injection protocols targeting glabellar lines, forehead creases, and periorbital rhytides. South Korean MFDS-cleared products dominate this category through Asian facial structure optimization.
- Lip Augmentation:Vermilion border definition and volume restoration procedures requiring highly cohesive gels with minimal tissue displacement. Brazilian medical spas generate disproportionate procedure volume through cultural emphasis on facial proportion aesthetics.
- Cheek Enhancement:Deep dermal and supraperiosteal placement for malar volume restoration. FDA 510(k) clearance pathways in the United States prioritize safety data for this high-risk vascular territory.
- Scar Treatment:Subcision-adjunctive filler placement for acne and traumatic scar revision. Australian dermatology clinics report expanding patient eligibility through TGA reimbursement pathway developments for reconstructive indications.
- Nasolabial Fold Correction:Mid-face volumizing to soften melolabial crease depth. United Kingdom aesthetic centers standardize combination protocols with energy-based devices in this application.
Cheek Enhancement commands premium pricing. Lip Augmentation is expanding most quickly.
End User:
End-user segmentation exposes how facility type determines procurement authority, patient volume, and service bundling economics.
- Dermatology Clinics:Physician-directed practices with diagnostic capability and complication management infrastructure. Swiss and Canadian jurisdictions qualify reconstructive procedures for partial reimbursement through these channels.
- Aesthetic Centers:Standalone facilities focusing exclusively on non-surgical cosmetic procedures. Asset-light expansion models through equipment leasing accelerate footprint growth in the United States and Brazil.
- Plastic Surgery Clinics:Surgical practices integrating injectables as pre-operative planning tools and post-surgical maintenance. London and Dubai locations bundle fillers with rhinoplasty and facelift procedures.
- Medical Spas:Hybrid clinical-spa environments with nurse injector staffing models. Hyaluronidase administration training gaps create liability exposure in high-volume Brazilian operations.
Dermatology Clinics capture margin leadership. Medical Spas are climbing the fastest.
Distribution Channel:
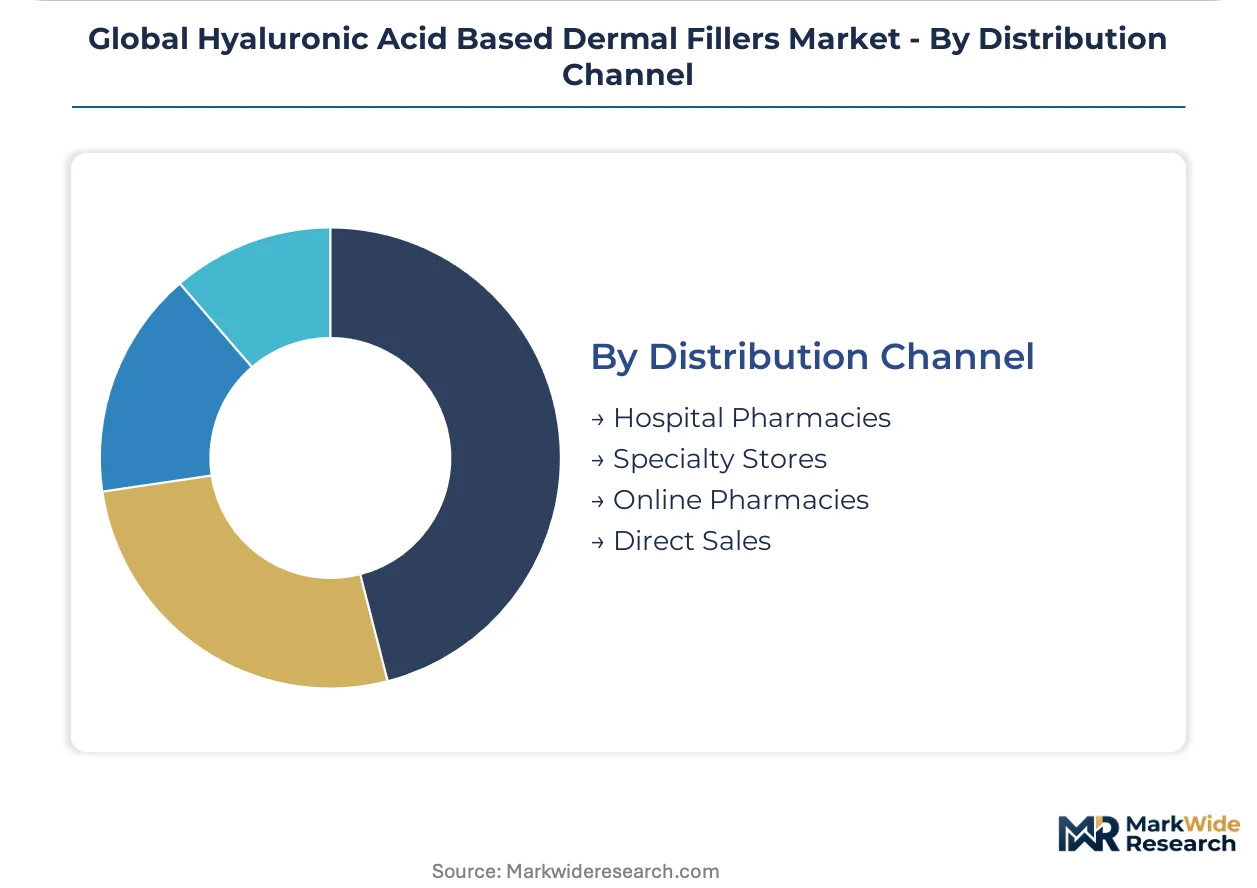
Channel segmentation tracks how procurement pathway choice affects price transparency, inventory velocity, and manufacturer margin retention.
- Hospital Pharmacies:Institutional procurement for reconstructive indications and academic medical center practices. Swissmedic and Health Canada oversight shapes cold chain and documentation requirements.
- Specialty Stores:Medical supply distributors serving independent practitioners with consolidated aesthetic product portfolios. United Kingdom buying groups negotiate aggregate pricing across dermatology networks.
- Online Pharmacies:Telehealth-integrated prescription fulfillment bypassing traditional clinic gatekeepers. FDA and ANVISA enforcement attention focuses on counterfeit product infiltration in United States and Brazilian digital channels.
- Direct Sales:Manufacturer-to-practitioner portals with real-time inventory and embedded education modules. Galderma and AbbVie deploy proprietary platforms to concentrate margin capture in North American and European markets.
Direct Sales leads by value concentration. Online Pharmacies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent urban consumers in Seoul, Los Angeles, and São Paulo drive procedure volume, while regulatory divergence between FDA, EU MDR, and MFDS pathways fragments certification timelines. Medical spa density and telehealth penetration now determine addressable market expansion more than traditional dermatology infrastructure.
United States
Direct-to-practitioner e-commerce portals concentrate manufacturer margins while bypassing wholesale intermediaries. FDA 510(k) clearance pathways prioritize safety documentation for cheek enhancement applications in high-risk vascular territories. Los Angeles aesthetic centers deploy 3D facial simulation platforms to virtualize informed consent and reduce revision liability.
South Korea
MFDS regulatory efficiency accelerates monophasic gel iterations optimized for Asian facial anatomy preferences. Seoul's Gangnam district hosts the highest medical spa density globally, with nurse injector staffing models driving procedure accessibility. Hugel Inc. leverages domestic manufacturing scale to supply price-competitive formulations across Asia-Pacific markets.
Brazil
Cultural emphasis on facial proportion aesthetics generates disproportionate lip augmentation volume through medical spa channels. ANVISA enforcement attention targets counterfeit product infiltration in digital distribution channels. São Paulo's independent aesthetic centers adopt equipment leasing arrangements to reduce capital barriers for expansion.
Germany
Biphasic formulation demand concentrates in dermatology clinics with established handling familiarity and cost accessibility protocols. EU MDR biocompatibility documentation requirements extend certification timelines by 18-24 months for non-European manufacturers. Berlin and Munich buying groups negotiate aggregate pricing across independent practitioner networks.
Switzerland
Reconstructive indication qualification for HIV-associated lipoatroxy and post-oncology facial restoration enables partial reimbursement through dermatology clinic channels. Swissmedic oversight shapes cold chain integrity requirements for cross-border distribution. Zurich aesthetic centers specify cohesive polydensified matrix formulations for tear-trough applications requiring natural expression preservation.
Global Hyaluronic Acid Based Dermal Fillers Market Competitive Landscape
Channel-controlling players compete with product-specialist players through divergent margin capture strategies. The vendor base clusters around three strategic archetypes: multinational pharmaceutical conglomerates with dermatology heritage, Korean manufacturing scale specialists, and European premium-formulation boutiques. Consolidation pressure intensifies as EU MDR compliance burdens filter undercapitalized entrants from commercialization pipelines. Dominant competitive moves include direct-to-practitioner portal deployment and physician education module integration.
Within the multinational tier, AbbVie Inc. and Galderma S.A. exemplify channel-control strategies through proprietary e-commerce platforms with real-time inventory visibility. Hugel Inc. represents the Korean manufacturing scale archetype, competing on production efficiency from its domestic base. Merz Pharma GmbH & Co. KGaA occupies the European premium-formulation position, while Teoxane SA and Sinclair Pharma plc. exemplify specialized aesthetic portfolios. LG Chem Ltd. and BioPlus Co. Ltd. sit within the Asian chemical conglomerate diversification pattern, leveraging upstream hyaluronate production capabilities.
| Leading Market Players |
|---|
| Teoxane SA |
| Sinclair Pharma plc. |
| AbbVie Inc. |
| BioPlus Co. Ltd. |
| Hugel Inc. |
| Galderma S.A. |
| LG Chem Ltd. |
| Prollenium Medical Technologies Inc. |
| Merz Pharma GmbH & Co. KGaA |
| Others |
Supply & Pricing Matrix
Shandong province's fermentation-grade hyaluronate manufacturing clusters anchor global raw material availability, with bioreactor capacity utilization swings transmitting directly into formulation cost structures and manufacturer margin compression cycles.
Pricing Analysis
Cost-plus contracts with pharmaceutical-grade sodium hyaluronate indexation to Chinese bioreactor output dominate procurement between raw material suppliers and finished-gel manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates monophasic gels with EU MDR technical file depth from biphasic mainstream formulations and unbranded alternatives. Pricing pressure stems from MFDS-registered Korean entrants competing on manufacturing scale in Asian markets. Independent aesthetic centers in Brazil and the United States exhibit highest price sensitivity, while Swiss dermatology clinics purchasing cohesive polydensified matrix formulations for tear-trough applications demonstrate lowest elasticity.
Supply Chain Analysis
Upstream feedstock concentration rests on Shandong province bioreactor complexes, South Korean MFDS-registered fermentation facilities, and select European pharmaceutical-grade extraction operations. Finished-gel production draws from cross-linked sodium hyaluronate, phosphate-buffered saline, and lidocaine hydrochloride as core inputs. Single-source vulnerability concentrates in Chinese pharmaceutical-grade hyaluronate output, where environmental compliance enforcement intermittently constrains batch release volumes. Distribution runs through direct-to-practitioner e-commerce portals with real-time inventory visibility, bypassing traditional pharmaceutical wholesalers in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated aesthetic center chains and buying groups across German and United Kingdom markets, fragmenting procurement authority among independent practitioners and compressing manufacturer margin retention.
For Market Incumbents: Build regulatory moat through EU MDR technical file depth and ISO 13485 quality system certification to filter undercapitalized entrants. Deepen physician education module integration within proprietary e-commerce portals to lock in channel control. Defend against Korean manufacturing scale specialists by accelerating monophasic gel iterations through MFDS-registered production partnerships. Prioritize cold chain integrity investments to protect gel rheological properties in cross-border distribution networks. For New Entrants and Emerging Players: Build out male aesthetic protocols for jawline contouring and tear-trough correction across German and Australian markets, where cultural stigma has suppressed procedure penetration. Target medical spa channels in São Paulo through equipment leasing arrangements that reduce capital barriers for independent aesthetic center expansion. Pursue ANVISA-registered digital pharmacy partnerships with embedded telehealth consultation workflows to bypass traditional clinic gatekeepers in Brazilian distribution. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR compliance burdens and biocompatibility testing costs are filtering undercapitalized manufacturers from commercialization pipelines, concentrating viable assets among channel-controlling multinationals and Korean scale specialists. Acquisition target archetype: European premium-formulation boutiques with cohesive polydensified matrix IP and Swissmedic technical file depth. Signal to watch: MFDS approval velocity for monophasic gels targeting Asian facial anatomy preferences as indicator of Korean manufacturing scale specialist momentum.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Expansion | Biocompatibility documentation depth filters undercapitalized competitors from European commercialization pipelines. |
| Direct-to-Practitioner Portal Deployment | Proprietary e-commerce platforms with real-time inventory concentrate manufacturer margin capture in North America. |
| Monophasic Gel Formulation Iteration | MFDS regulatory efficiency enables faster product cycles optimized for Asian facial anatomy preferences. |
| Physician Education Module Integration | Embedded training protocols lock in practitioner loyalty and reduce hyaluronidase administration competency gaps. |
| Cold Chain Infrastructure Investment | Temperature-controlled distribution protects gel rheological properties in emerging market logistics networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with aesthetic practitioners, dermatology clinic procurement managers, medical spa operators, and regulatory affairs specialists at notified bodies; and secondary validation through FDA 510(k) clearance databases, EU MDR technical documentation filings, MFDS registration records, and customs trade data on pharmaceutical-grade sodium hyaluronate flows. Bottom-up procedure volume estimates by application and end-user channel were triangulated against top-down manufacturer shipment data across the analysis window.
Forecast inputs incorporated formulation type segmentation, injection site anatomy requirements, distribution channel economics, and regional regulatory pathway divergence. CAGRs were derived from modeled patient population expansion, procedure frequency trends, and average selling price trajectories by product tier across the projection horizon. Industry-specific inputs included bioreactor capacity utilization rates in Chinese manufacturing hubs and telehealth consultation normalization velocities in United States and Brazilian markets.
Stress conditions across raw material cost volatility, EU MDR certification timeline extensions, and telehealth regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on patient demographic expansion and reimbursement classification evolution for reconstructive indications. Cross-checking against hospital procurement database benchmarks and GPO contract pricing disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market