
 Global Argireline Market | 2026-2036
Global Argireline Market Size, Share, and Industry Trends Forecast 2026-2036
Global Argireline Market Foresight
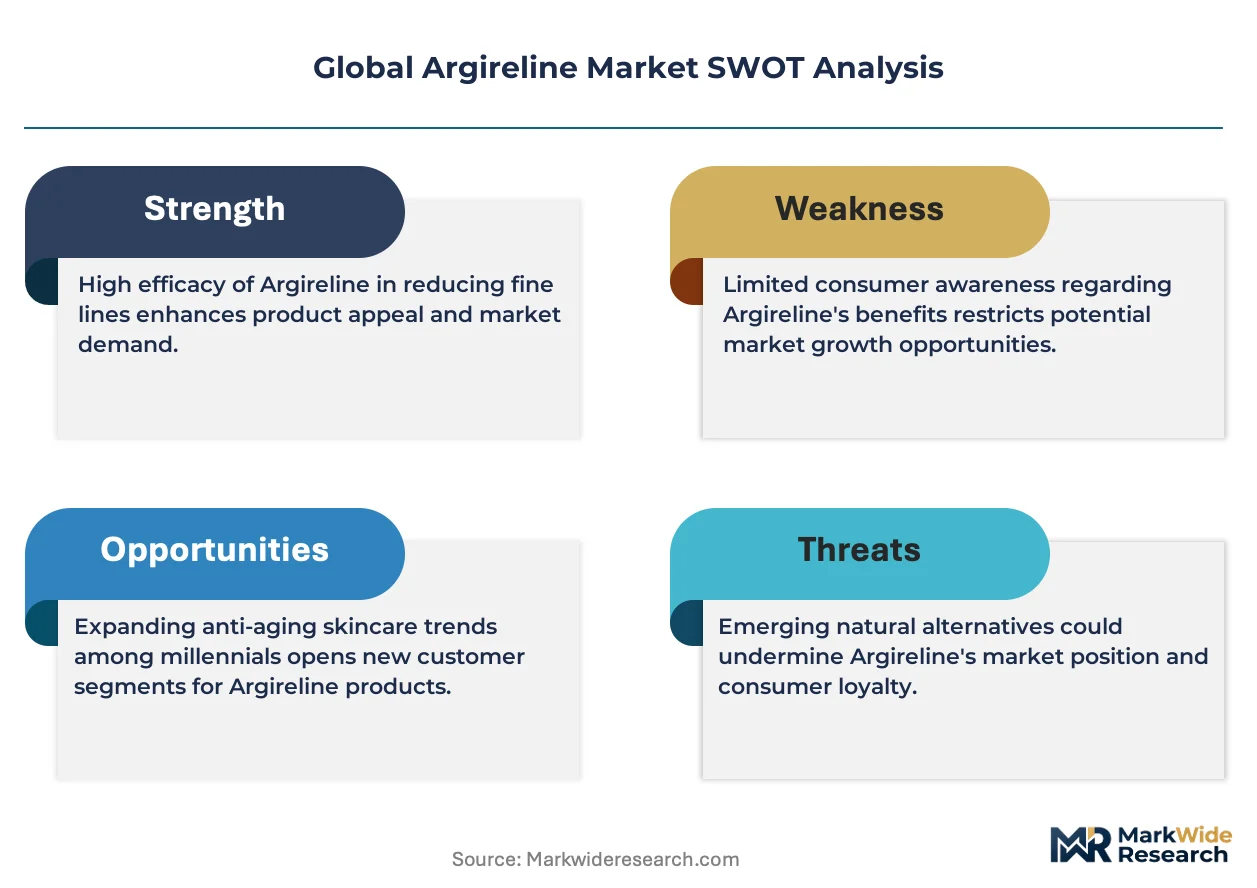
Cosmetic manufacturers are bifurcating from dermatology clinics as the fastest-growing buyer archetype for Argireline raw material procurement. Shenzhen JYMed Technology leverages its peptide synthesis infrastructure to dominate supply contracts with Asian personal care brands. Sederma anchors European demand through its heritage in active cosmetic ingredients and sustained R&D partnerships with luxury formulators. DSM competes on bioengineered peptide platforms, extending its reach into fermented production methods that appeal to clean-beauty-positioned clients.
Argireline is a synthetic hexapeptide (acetyl hexapeptide-3/8) that modulates SNAP-25 complex formation to attenuate neurotransmitter release, thereby reducing expression-line muscle contraction intensity without paralysis. The peptide is manufactured through solid-phase peptide synthesis with purity grades typically exceeding 95% for cosmetic-grade applications, serving primarily as a topical alternative to botulinum toxin in anti-aging formulations. Powder formulations occupy the highest margin tier due to stability advantages and downstream formulation flexibility for cosmetic manufacturers. Bioengineered and fermented production methods are gaining fastest among formulation types as brands respond to consumer preference shifts toward biotech-derived actives with traceable supply chains.
The EU Cosmetics Regulation (EC) No 1223/2009 and REACH compliance requirements administered by ECHA shape ingredient safety dossier standards for Argireline suppliers seeking European market access. China's NMPA and SAMR enforce cosmetics registration and new ingredient notification rules that determine entry timelines for imported peptide actives. India's CDSCO and BIS standards for cosmetic raw materials create additional compliance layers for suppliers targeting that market. Stakeholders must monitor divergence between regional safety assessment protocols and emerging biotechnology disclosure requirements as peptide sourcing decisions carry increasing regulatory weight.
Market Dynamics
Peptide synthesis infrastructure concentration in East Asia is redistributing procurement leverage toward contract manufacturers, while EU Cosmetics Regulation (EC) No 1223/2009 amendments on ingredient safety dossiers force European formulators to validate supply chain traceability.
Growth Catalysts
- Medical aesthetics protocol shift:Dermatology clinics in South Korea are expanding peptide-based treatment menus as patient preferences move from injectables to topical alternatives.
- REACH compliance maturation:ECHA-administered dossier standards for cosmetic-grade peptides are filtering out sub-scale suppliers, consolidating volume with certified producers.
- Fermentation biotechnology:Bioengineered production methods are displacing traditional solid-phase synthesis for brands targeting clean-beauty-positioned consumer segments.
Market Restraints
- Raw material input volatility:Amino acid precursor costs fluctuate with agricultural commodity cycles, compressing margins for non-integrated peptide manufacturers.
- Supply geographic concentration:Bulk Argireline output clusters in China's Guangdong and Jiangsu provinces, exposing buyers to single-country logistics disruption risk.
- Botulinum toxin substitution threat:Established neurotoxin brands maintain physician loyalty through rebate structures that peptide topicals cannot replicate in clinical settings.
Strategic Opportunities
- Indian market entry timing:CDSCO cosmetic raw material standards are stabilizing, creating first-mover advantage for dossier-ready suppliers before domestic peptide capacity matures.
- Men's grooming application expansion:Male-targeted anti-aging formulations remain underpenetrated versus female-skewed product lines across North American and European retail.
- SAMR notification pathway clarity:China's 2021 cosmetics registration reform is accelerating new ingredient approval timelines for peptide actives with complete toxicology packages.
Industry Challenges
- Peptide chemist talent scarcity:Solid-phase synthesis expertise pools concentrate at legacy pharmaceutical CMOs, forcing cosmetic ingredient suppliers to compete for experienced analytical scientists.
- Multi-jurisdiction dossier harmonization:Divergent safety assessment protocols between ECHA, NMPA, and FDA create redundant toxicology study requirements that extend commercialization timelines.
- Stability validation capex burden:Powder formulation shelf-life testing under ICH guidelines demands climate-controlled stability chambers that mid-scale manufacturers struggle to fund.
Report Scope
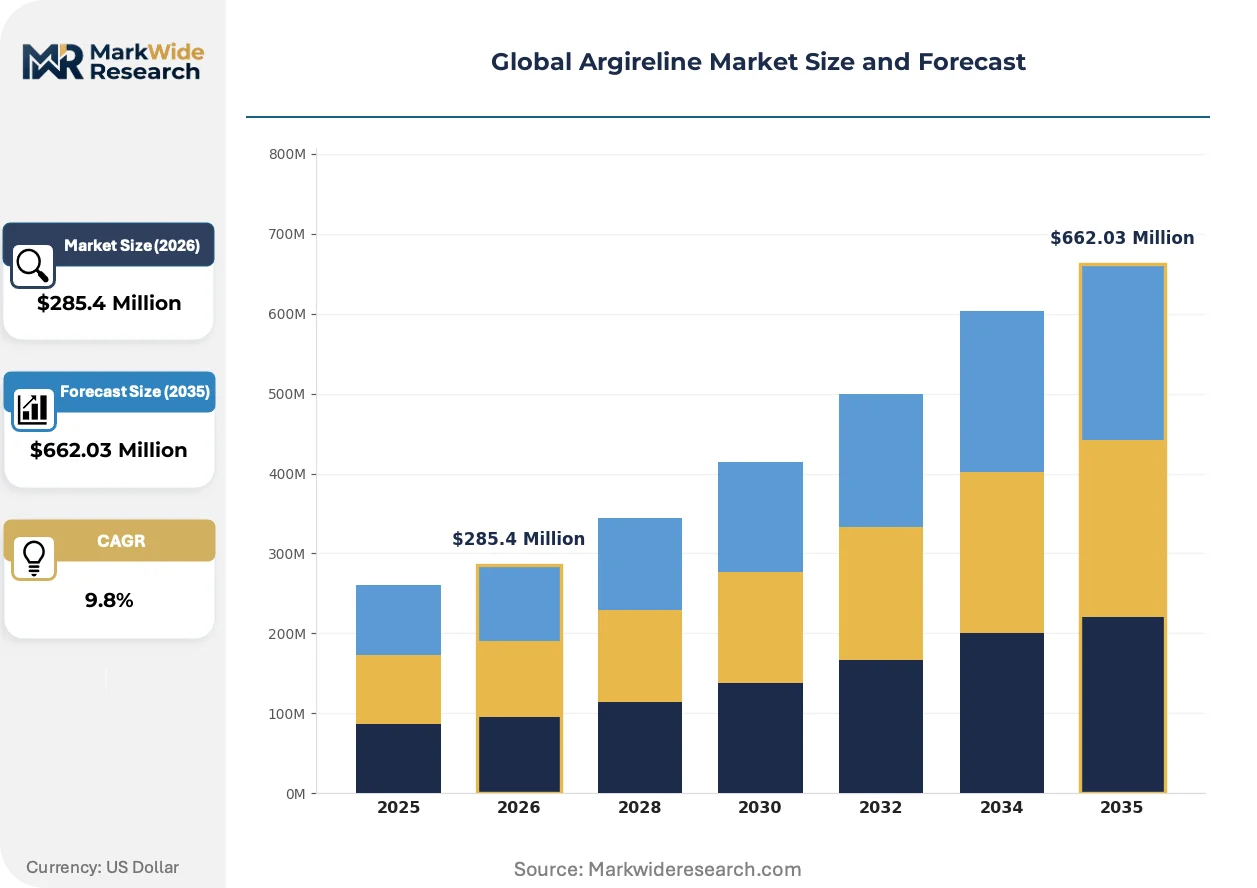
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Argireline Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $662.03 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Solution, Gel, Capsule, Liquid Application: Anti-Aging, Wrinkle Reduction, Moisturizing, Skin Brightening, Hair Care End User: Cosmetic Manufacturers, Dermatology Clinics, Spa Centers, Personal Care Brands Formulation Type: Organic, Synthetic, Bioengineered, Fermented |
| Companies Covered | Shenzhen JYMed Technology, Sederma, Lipotec, DSM, Evonik Industries, Shanghai Soho-Yiming Pharmaceuticals, Lubrizol, BASF, Zhejiang Peptites Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Argireline Market Shifts & Advancements
Biotechnology-derived actives are compressing traditional chemical synthesis pathways, while regulatory disclosure mandates and direct-to-consumer channel expansion reshape how peptide ingredients reach end-formulators.
Microfluidic peptide synthesis platforms are miniaturizing production footprints for cosmetic-grade hexapeptides. Korean and Chinese contract manufacturers are adopting these systems to serve mid-tier personal care brands with lower minimum order quantities. This distributed manufacturing model is compressing lead times from synthesis to formulation delivery.
REACH substance evaluation under ECHA's 2023-2025 rolling action plan is intensifying scrutiny of synthetic peptide environmental fate data. European formulators must now submit extended safety dossiers covering aquatic toxicity endpoints. Luxury skincare houses with established regulatory affairs teams are absorbing these costs faster than indie beauty brands.
Direct ingredient sourcing from peptide manufacturers is displacing traditional distributor intermediaries among scaled cosmetic formulators. Large personal care conglomerates in Germany and France are building preferred supplier agreements that bypass regional chemical traders. This channel consolidation is most visible in the premium anti-aging segment where supply chain transparency commands marketing value.
Global Argireline Market Segmentation
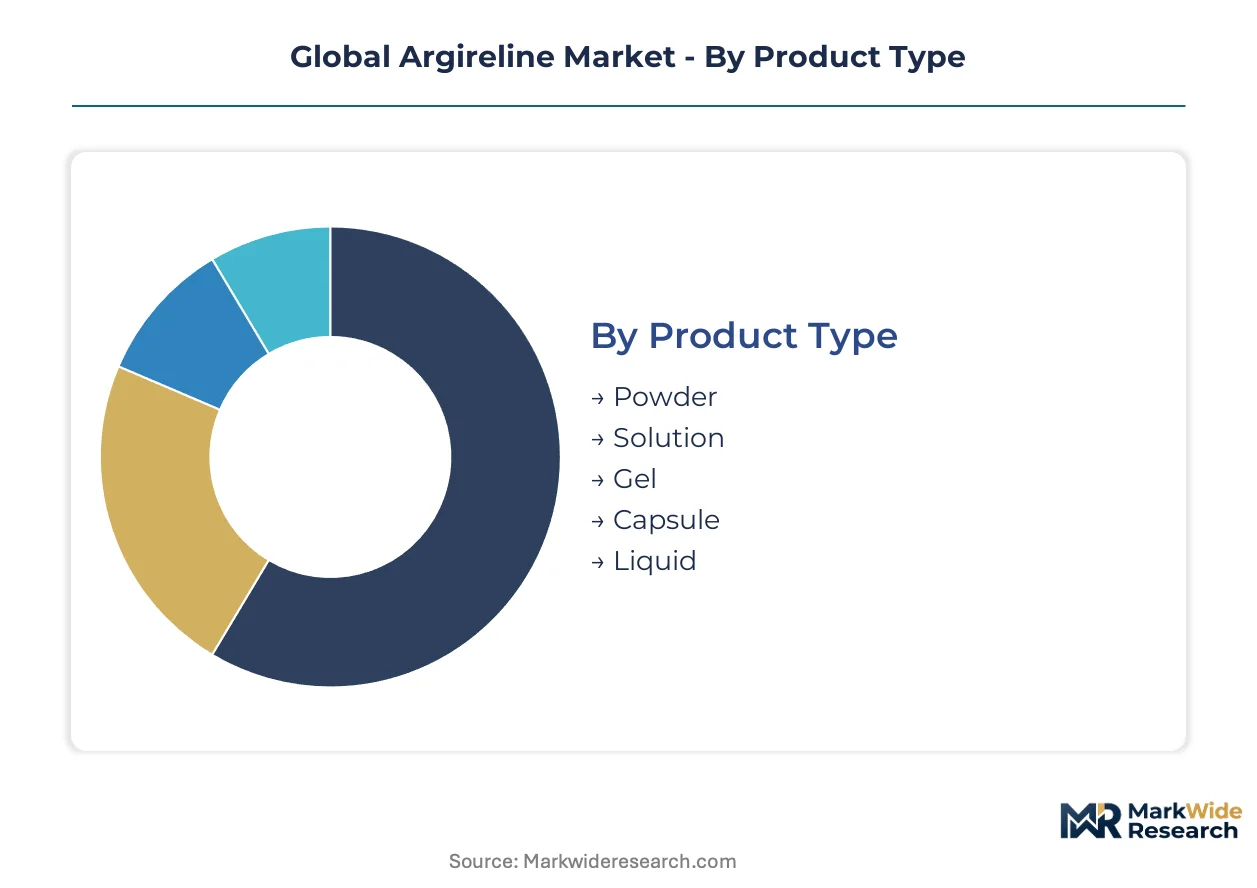
Argireline procurement patterns diverge sharply across formulation physics and end-use certification requirements. Cosmetic manufacturers prioritize stability and regulatory dossier completeness over unit cost, while dermatology clinics demand clinical-grade purity thresholds that filter supplier pools.
Product Type:
REACH dossier requirements under ECHA differentiate powder formulations from liquid alternatives through stability data obligations and shelf-life validation protocols.
- Powder:Lyophilized peptide achieves superior thermal stability across ICH climate zones, supporting multi-year supply agreements with German and French luxury formulators facing extended safety documentation deadlines. Cosmetic manufacturers in Seoul and Shanghai specify powder grades exceeding 98% purity to satisfy dual-registration pathways for EU and China market entry.
- Solution:Aqueous preparations require cold-chain logistics and buffered pH maintenance, limiting sourcing radius to regional contract manufacturers. Demand concentrates in Japanese medical aesthetics chains where on-site compounding protocols favor ready-to-dilute formats over powder reconstitution.
- Gel:Viscous semisolid matrices suit direct-to-consumer topical delivery systems.
- Capsule:Encapsulated formats target ingestible nutricosmetic applications with distinct regulatory filing requirements.
- Liquid:Fluid formulations serve high-throughput manufacturing lines requiring pump-compatible viscosity profiles.
Established volume favors powder; emerging adoption favors solution formats in clinic-direct channels.
Application:
Margin structures across application segments reflect formulation complexity and clinical claim substantiation burden rather than raw material input costs alone.
- Anti-Aging:Peptide modulation of SNAP-25 complex formation supports topical neurotransmitter inhibition claims requiring toxicology packages under FDA and NMPA notification rules. South Korean medical aesthetics chains integrate Argireline into premium protocol bundles alongside laser resurfacing treatments.
- Wrinkle Reduction:Expression-line targeting commands price premiums over general anti-aging positioning due to measurable efficacy endpoints and before-after documentation standards. European luxury houses anchor positioning through Sederma partnership heritage and sustained R&D investment.
- Moisturizing:Humectant synergy applications represent volume-driven commodity positioning.
- Skin Brightening:Combination with niacinamide or vitamin C derivatives requires stability compatibility testing.
- Hair Care:Scalp application protocols remain underdeveloped versus facial skincare formulations.
Clinical claim density favors wrinkle reduction; mass-market penetration favors moisturizing positioning.
End User:
Procurement scale and technical specification authority separate cosmetic manufacturers from service-based buyers in clinic and spa channels.
- Cosmetic Manufacturers:Scaled personal care conglomerates in Germany, France, and South Korea negotiate preferred supplier agreements bypassing distributor intermediaries. Shenzhen JYMed Technology anchors Asian supply through peptide synthesis infrastructure serving K-beauty brand integration at scale.
- Dermatology Clinics:Medical aesthetics protocols in Seoul and Busan are expanding peptide-based treatment menus as patient preferences shift from injectable neurotoxins to topical alternatives. Clinic procurement requires GMP certification and batch-specific CoA documentation.
- Spa Centers:Service providers lack technical specification authority, purchasing through formulated finished goods rather than raw peptide inputs.
- Personal Care Brands:Indie beauty labels face REACH compliance cost barriers that luxury houses absorb through established regulatory affairs teams.
Volume concentration favors cosmetic manufacturers; margin expansion favors dermatology clinic direct sales.
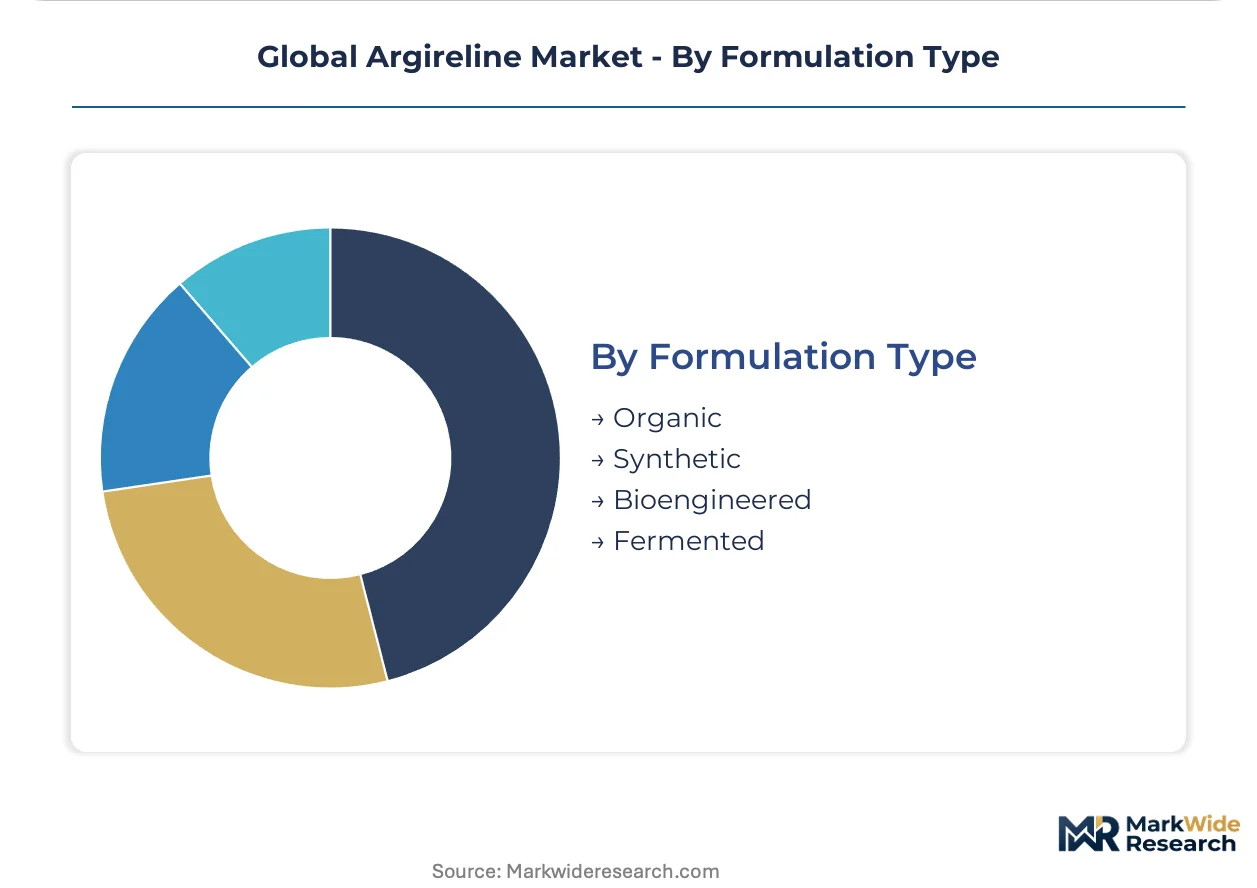
Formulation Type:
Production method selection determines supply chain traceability credentials and clean-beauty market access eligibility.
- Synthetic:Solid-phase peptide synthesis dominates current output through established Fmoc chemistry protocols and 95%+ purity achievement at commercial scale. China's Guangdong and Jiangsu province clusters supply bulk volumes under cost-optimized manufacturing economics.
- Bioengineered:Fermented production methods are gaining share fastest among brands responding to consumer preference shifts toward biotechnology-derived actives with traceable supply chains. DSM competes through bioengineered peptide platforms extending into fermented methods.
- Organic:Plant-derived precursor claims require agricultural input certification and GMO-free documentation.
- Fermented:Microbial production systems appeal to clean-beauty-positioned segments seeking reduced petrochemical dependency.
Cost efficiency favors synthetic; positioning differentiation favors bioengineered and fermented alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex anchors peptide raw material throughput for cosmetic-grade hexapeptide distribution, consolidating East Asian supply chain leverage before finished actives reach European and North American formulation facilities.
China
Guangdong and Jiangsu province clusters generate bulk Argireline output through solid-phase synthesis infrastructure serving K-beauty and domestic cosmetic brands. SAMR cosmetics registration reforms under the 2021 regulatory framework compress new ingredient approval timelines for peptide actives with complete toxicology dossiers. Shenzhen's peptide synthesis corridor houses contract manufacturers supplying preferred supplier agreements with scaled personal care conglomerates.
South Korea
Seoul Capital Area medical aesthetics chains are expanding peptide-based treatment menus as patient preferences shift from injectable neurotoxins to topical alternatives. MFDS cosmetic ingredient standards enforce batch-specific CoA documentation requirements for clinic-direct procurement channels. Busan-Ulsan manufacturing zones concentrate downstream formulation capacity for premium anti-aging skincare exports.
Germany
Luxury skincare houses in the Rhine-Ruhr and Bavarian industrial zones absorb REACH compliance costs through established regulatory affairs teams faster than indie beauty competitors. ECHA-administered dossier standards for synthetic peptides filter sub-scale suppliers, consolidating volume with certified producers. Frankfurt's chemical trading infrastructure supports direct ingredient sourcing agreements that bypass traditional distributor intermediaries.
United States
Mass-market cosmetic manufacturers in New Jersey and California formulation corridors seek peptide actives with FDA-compliant toxicology packages for wrinkle-reduction claims. FTC substantiation requirements for anti-aging efficacy endpoints drive demand for clinical-grade purity thresholds. Greater Boston biotech clusters incubate microfluidic peptide synthesis platforms serving mid-tier personal care brands with lower minimum order quantities.
India
CDSCO cosmetic raw material standards are stabilizing, creating first-mover advantage for dossier-ready suppliers before domestic peptide capacity matures in Maharashtra and Gujarat pharmaceutical zones. BIS certification requirements for imported active ingredients extend commercialization timelines for unprepared entrants. Mumbai-Pune industrial corridors concentrate contract formulation capacity for regional personal care brand launches.
Global Argireline Market Competitive Landscape
Listed leaders compete with private specialists across synthesis scale and regulatory dossier depth. The vendor base stratifies between integrated peptide manufacturers with captive amino acid supply and specialized cosmetic ingredient houses competing on formulation flexibility. Three archetypes dominate: pharmaceutical-grade CMOs repurposing infrastructure for cosmetic actives, dedicated peptide synthesis specialists, and diversified chemical conglomerates extending into bioengineered platforms. Capacity expansion and preferred supplier agreement formation constitute the dominant competitive moves.
Within the synthesis-specialist tier, Shenzhen JYMed Technology occupies a position exemplifying East Asian infrastructure concentration, while Sederma anchors European demand through heritage positioning in active cosmetic ingredients. DSM sits within the diversified chemical conglomerate archetype, representing bioengineered peptide platform capabilities. These three companies illustrate the geographic and strategic bifurcation shaping procurement leverage across the value chain.
| Leading Market Players |
|---|
| Shenzhen JYMed Technology |
| Sederma |
| Lipotec |
| DSM |
| Evonik Industries |
| Shanghai Soho-Yiming Pharmaceuticals |
| Lubrizol |
| BASF |
| Zhejiang Peptites Biotech |
| Others |
Supply & Pricing Matrix
REACH substance evaluation under ECHA's rolling action plan gates both supplier qualification and price differentiation simultaneously, forcing European formulators to absorb extended safety dossier costs that filter sub-scale competitors from premium tier access while concentrating procurement leverage with certified producers.
Pricing Analysis
Volume-discount tiering structures dominate Argireline procurement, with three-tier pricing separating GMP-certified clinical grades from standard cosmetic grades and economy bulk powder alternatives. Price differentiation hinges on purity certification thresholds and REACH dossier completeness, with German luxury formulators least sensitive due to established regulatory affairs teams absorbing compliance overhead. Pricing pressure stems from amino acid precursor cost volatility compressing margins for non-integrated manufacturers, while mid-tier Korean cosmetic brands exhibit highest price sensitivity as they balance K-beauty positioning against raw material input swings.
Supply Chain Analysis
Inventory lead times stretch across 8-12 weeks for powder formulations requiring ICH stability validation, compressing to 3-4 weeks for aqueous solutions sourced from regional contract manufacturers. Supply concentrates in China's Guangdong and Jiangsu provinces, with secondary capacity clusters in South Korea's Busan-Ulsan corridor and emerging fermentation platforms in the Netherlands. Raw material dependencies center on Fmoc-protected amino acids, specialized resins, and analytical reference standards. Single-country concentration risk exposes buyers to logistics disruption from port congestion or export licensing shifts. Distribution runs through direct preferred supplier agreements that displace traditional chemical distributor intermediaries among scaled cosmetic conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argireline procurement is shifting toward platform-economics dynamics as direct manufacturer relationships and interoperable regulatory dossiers replace fragmented distributor networks, with peptide synthesis infrastructure becoming the controlling node in value capture.
For Market Incumbents: Fortify supply chain control through backward integration into amino acid precursor production or captive fermentation capacity in the Netherlands, defending against bioengineered peptide platforms displacing traditional solid-phase synthesis. Prioritize REACH dossier depth to filter sub-scale competitors from European premium tier access. For New Entrants and Emerging Players: Differentiate on fermented production methods with traceable supply chains targeting clean-beauty-positioned indie brands in North America, where regulatory affairs cost barriers have slowed established European houses. Target India's CDSCO-ready segment before domestic peptide capacity matures in Maharashtra pharmaceutical zones. For Investors and Strategic Acquirers: ECHA's 2023-2025 rolling action plan on synthetic peptide environmental fate data reshapes the acquisition landscape toward dossier-complete specialists with climate-controlled stability infrastructure. Long-term viability favors integrated manufacturers with captive synthesis and regulatory affairs depth. Watch for SAMR notification pathway acceleration as the signal for China market entry timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Precursors | Captive supply of Fmoc-protected inputs insulates margin compression from agricultural commodity cycles. |
| Fermentation Platform Scale-Up | Bioengineered methods unlock clean-beauty positioning for DSM and competing biotechnology specialists. |
| REACH Dossier Harmonization Investment | Extended aquatic toxicity data satisfies ECHA standards that filter sub-scale European competitors. |
| Direct Preferred Supplier Agreements | Bypassing distributor intermediaries concentrates procurement leverage with Shenzhen JYMed and Sederma. |
| Microfluidic Synthesis Miniaturization | Korean contract manufacturers adopt distributed production to serve mid-tier brands with lower MOQs. |
Research Methodology
Cross-validation between primary interviews with peptide synthesis chemists, cosmetic formulators, and regulatory affairs directors and secondary validation through ECHA substance evaluation databases, SAMR cosmetics registration filings, and customs trade data anchors the qualitative findings. Bottom-up triangulation across solid-phase synthesis capacity estimates and top-down reconciliation with personal care active ingredient spending patterns ensures dimensional consistency. The analysis draws from structured conversations with procurement leads at German luxury skincare houses, MFDS compliance officers in Seoul, and CDSCO registration consultants in Mumbai.
Sensitivity analysis across purity grade tiers, formulation physics, and regional regulatory clusters shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application claim density, end-user procurement authority, and production method provenance. CAGRs derive from regression against peptide active ingredient penetration curves in medical aesthetics protocols and clean-beauty brand launches. Industry-specific forecast inputs incorporate amino acid precursor cost indices and REACH compliance cost absorption rates by manufacturer scale tier.
Decision-makers should treat outputs as directional under assumptions of stable SAMR notification timelines and continued ECHA dossier stringency; material deviation in regulatory processing speed or synthetic peptide environmental scrutiny would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market