
 US Minoxidil Market | 2026-2036
US Minoxidil Market Size, Share, and Industry Trends Forecast 2026-2036
US Minoxidil Market Analysis
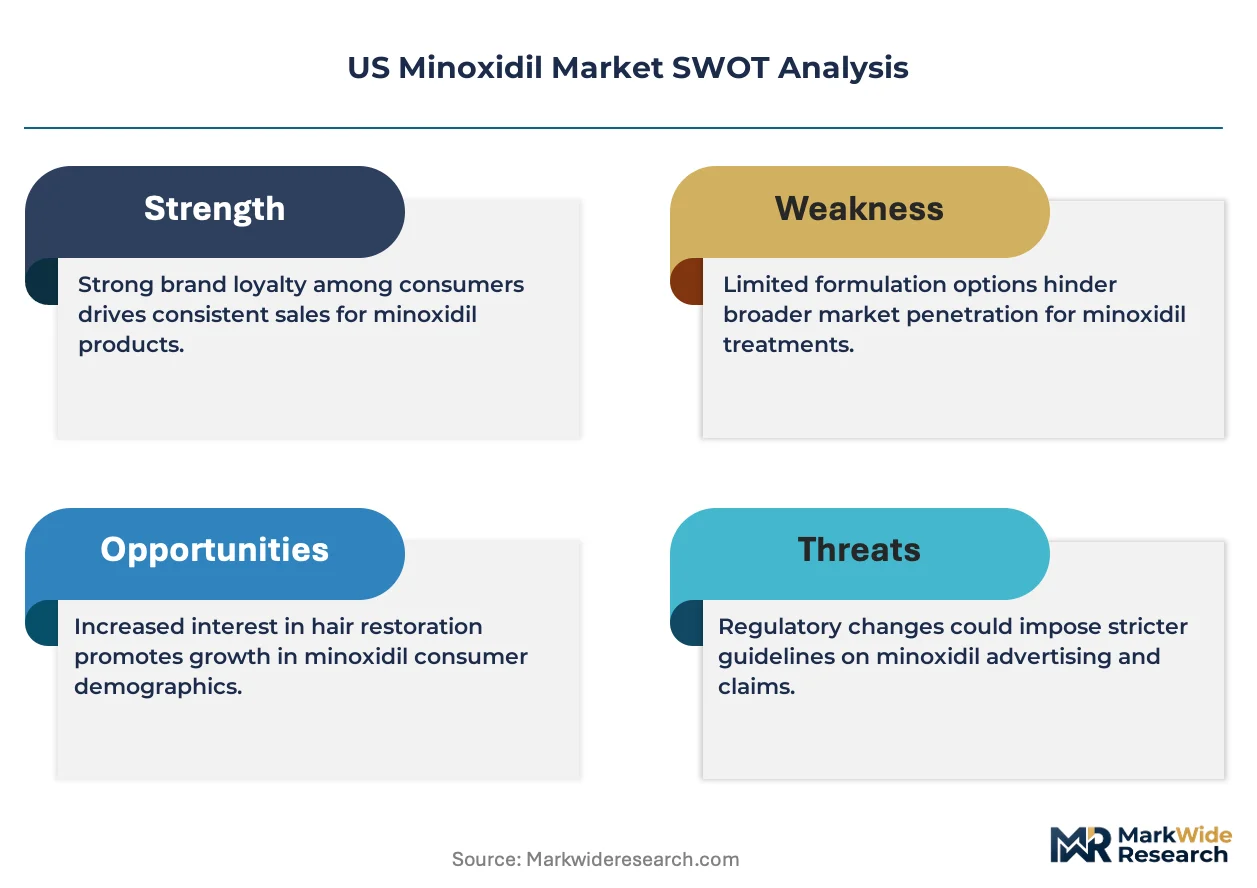
Capital-intensity divergence between mass-market private-label operators and specialized compounding pharmacies is unwinding competitive stability in the US minoxidil landscape. Perrigo Company PLC leverages its vertically integrated manufacturing footprint to sustain private-label dominance across pharmacy and supermarket channels. Johnson and Johnson Consumer Inc anchors premium positioning through brand equity built on decades of clinical marketing. Minoxidilmax specializes in higher-concentration formulations that occupy a niche between OTC accessibility and physician-directed therapy.
Minoxidil, a piperidinopyrimidine derivative and ATP-sensitive potassium channel opener, functions as a vasodilator that prolongs the anagen phase of hair follicles through enhanced microcirculation and upregulated vascular endothelial growth factor expression. The US market produces this active pharmaceutical ingredient through synthetic organic chemistry routes involving 2,4-diamino-6-chloropyrimidine intermediates, with final formulations standardized at 2% and 5% concentrations for topical delivery. Foam formulations lead volume due to reduced propylene glycol content and improved cosmetic acceptability, while spray delivery systems represent the fastest-growing format as direct-to-consumer brands optimize application convenience for subscription models. Dermatologist-directed applications command margin concentration through compounded higher-strength solutions and combination therapies with finasteride or retinoids.
FDA OTC monograph regulation governs concentration ceilings and labeling claims, while USP-NF standards enforce dissolution and purity specifications that shape manufacturing compliance costs. State pharmacy boards in California, Florida, and Texas impose additional compounding oversight that fragments market access for customized formulations. Stakeholders must monitor evolving FDA enforcement discretion on telehealth-prescribed compounded minoxidil combinations, as regulatory clarity will determine whether hybrid medical-aesthetic positioning expands addressable demand or contracts to traditional OTC boundaries.
Market Dynamics
Telehealth dermatology platforms are compressing the path from diagnosis to treatment, converting prescription-grade minoxidil into subscription replenishment models that bypass traditional pharmacy channels and reshape margin capture across the value chain.
Growth Catalysts
- FDA OTC Monograph Expansion:The FDA's ongoing updates to topical hair growth monographs enable new formulation formats and concentration presentations, broadening accessible entry points for first-time users.
- Direct-to-Consumer Marketing Normalization:Social media platforms and influencer-driven education reduce stigma around male pattern baldness, expanding addressable demand among men aged 25-40.
- California and New York Telehealth Density:These states host the highest concentration of dermatology-focused telehealth platforms, driving subscription-based replenishment velocity and patient retention rates.
Market Restraints
- Propylene Glycol Sensitivity Limitations:Traditional solution formulations containing this penetration enhancer trigger dermatological adverse reactions in 15-20% of users, restricting compliance and repeat purchase rates.
- State Pharmacy Board Fragmentation:California, Florida, and Texas impose divergent compounding oversight requirements, creating compliance complexity for customized minoxidil combination therapies.
- Finasteride Combination Substitution:Oral 5-alpha-reductase inhibitors prescribed through telehealth platforms compete for the same patient cohort seeking pharmaceutical hair loss intervention.
Strategic Opportunities
- Southeast and Midwest Geographic White Space:States outside California and New York show lower telehealth dermatology penetration, representing expansion opportunity for platform-based subscription models.
- Retinoid and Caffeine Combination Formulations:Compounding pharmacies can develop proprietary adjuvant blends that differentiate from standardized OTC monograph products.
- Foam-to-Spray Format Migration:Spray delivery systems reduce application time and improve cosmetic acceptability, enabling premium positioning within direct-to-consumer subscription tiers.
Industry Challenges
- USP-NF Dissolution Testing Capacity:Analytical chemistry talent shortages in quality control laboratories delay batch release timelines for new formulation launches.
- Telehealth Prescribing Compliance Ambiguity:Evolving FDA enforcement discretion on compounded minoxidil combinations creates regulatory uncertainty for hybrid medical-aesthetic positioning strategies.
- Active Pharmaceutical Ingredient Sourcing Concentration:Domestic reliance on 2,4-diamino-6-chloropyrimidine intermediate suppliers creates vulnerability to synthetic chemistry production disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Minoxidil Market |
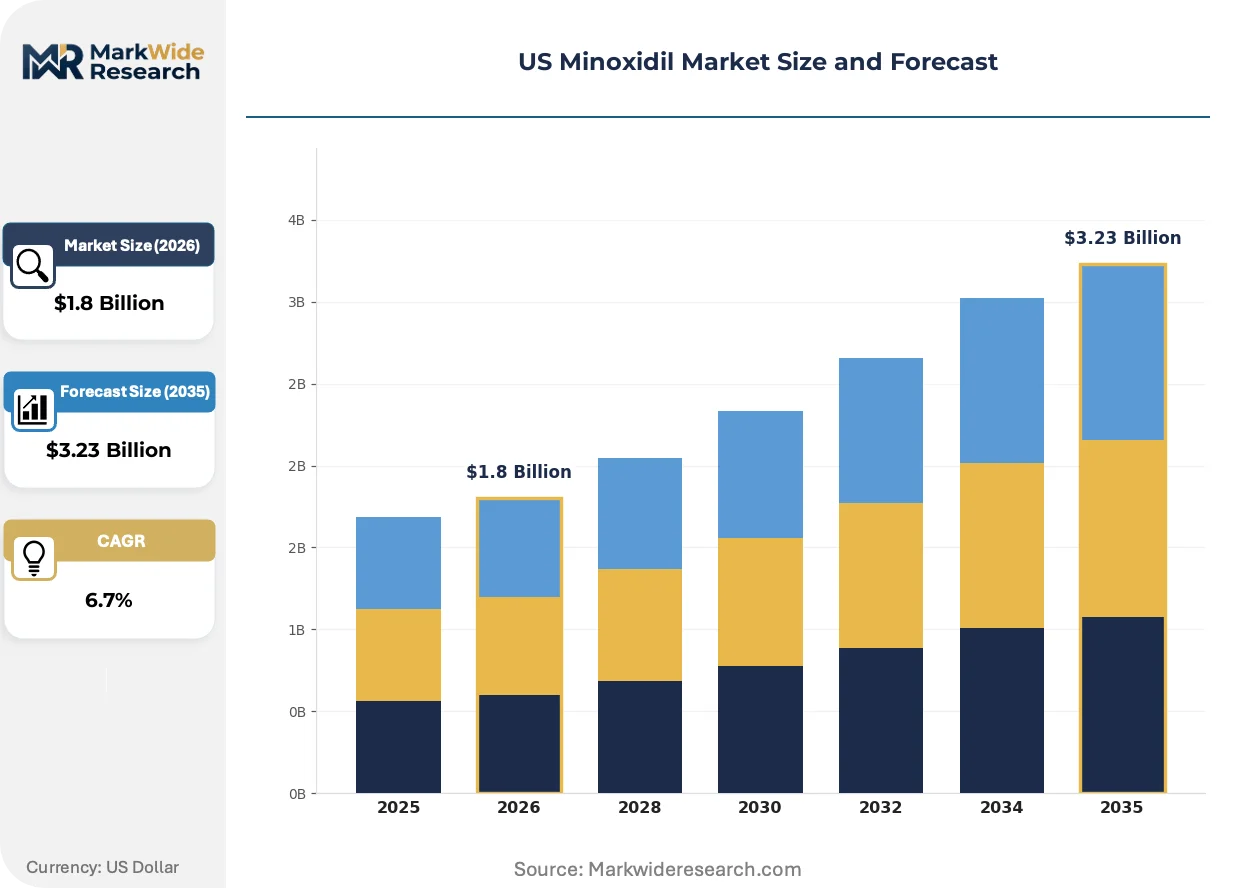
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Foam, Spray, Gel Application: Hair Loss Treatment, Hair Regrowth, Scalp Care, Dermatological Applications End User: Men, Women, Dermatologists, Retail Consumers Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Costco Wholesale Corporation, Pure Source, Perrigo Company PLC, Minoxidilmax, Par Pharmaceuticals, Johnson and Johnson Consumer Inc, LGM Pharma, Pfizer, Walmart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Minoxidil Market Emerging Trajectories
Formulation science and distribution architecture are converging to transform minoxidil from a pharmacy-shelf commodity into a personalized, digitally-delivered therapeutic regimen with embedded compliance monitoring.
Nanostructured lipid carrier systems are miniaturizing active pharmaceutical ingredient delivery to hair follicle bulge regions, improving bioavailability beyond traditional propylene glycol-based penetration. Specialized compounding pharmacies in Texas and Florida are adopting these lipid nanoparticle platforms for higher-concentration custom formulations. This technology is miniaturizing the effective dose required for clinical response, enabling reduced application frequency and improved user adherence metrics.
FDA enforcement discretion letters regarding telehealth-prescribed compounded drug combinations are reshaping permissible marketing claims for minoxidil-finasteride blends. Compounders must navigate between OTC monograph boundaries and prescription drug advertising regulations. Dermatology platforms operating across state lines face particular scrutiny, with California and New York boards issuing divergent guidance on acceptable promotional language.
Subscription auto-replenishment models are displacing episodic pharmacy purchasing, locking patients into 90-day supply cycles with embedded progress tracking apps. Direct-to-consumer brands optimize this channel through spray format bundles that reduce shipping costs per dose. This behavioral shift concentrates most visibly in urban coastal markets where same-day delivery infrastructure supports just-in-time inventory management.
US Minoxidil Market Segmentation
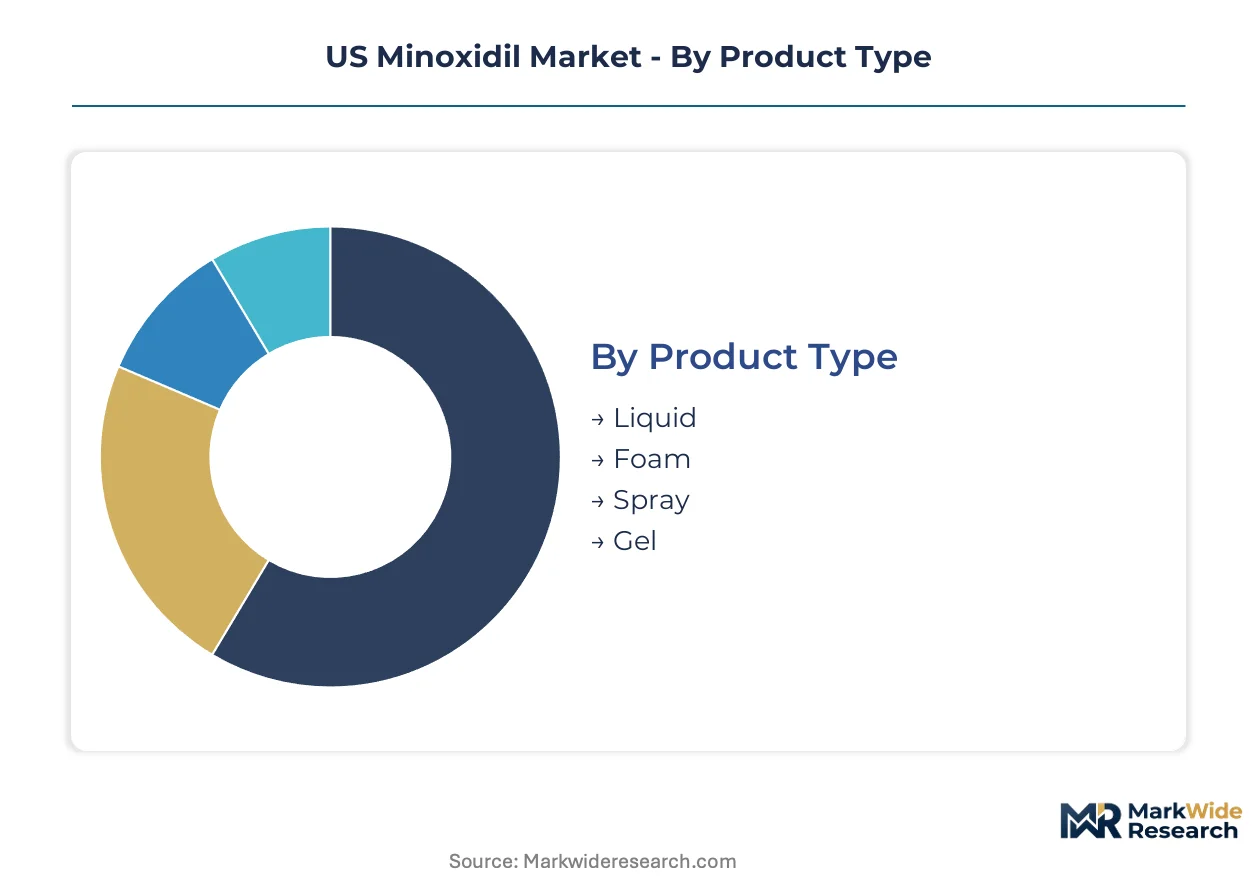
Minoxidil segmentation reflects divergent consumer tolerance profiles, prescriber control preferences, and channel economics that determine formulation viability and margin capture. Product format selection directly correlates with compliance duration and subscription renewal rates across direct-to-consumer platforms.
Product Type:
Liquid and foam formulations face intensifying substitution pressure from spray delivery systems that reduce application friction and improve cosmetic acceptability in subscription models.
- Foam:Propylene glycol-free aqueous formulations reduce dermatological adverse reactions in sensitive users. Demand concentrates in California and New York where telehealth platforms prioritize patient retention through tolerability-optimized regimens.
- Spray:Metered-dose aerosol systems enable rapid scalp coverage with reduced residue. Direct-to-consumer brands in subscription tiers favor this format for shipping efficiency and application convenience among men aged 25-40.
- Liquid:Traditional propylene glycol-based solutions retain pharmacy shelf presence through lower unit economics.
- Gel:Viscous formulations target localized application needs with reduced drip incidence.
Foam anchors the volume base while spray gains share at the steepest rate.
Application:
Margin concentration varies sharply across clinical endpoints, with hair regrowth claims commanding premium positioning against maintenance-oriented scalp care applications.
- Hair Loss Treatment:Preventive applications targeting androgenetic alopecia progression dominate pharmacy and supermarket channels. FDA OTC monograph labeling governs permissible efficacy claims and concentration ceilings.
- Hair Regrowth:Reactive therapeutic positioning requires more intensive patient education and compliance monitoring. Dermatologist-directed applications in Texas and Florida compounding pharmacies concentrate here.
- Scalp Care:Adjunctive moisturizing and barrier repair formulations extend product ecosystem value.
- Dermatological Applications:Off-label and compounded indications occupy regulatory gray zones under evolving FDA enforcement discretion.
Hair loss treatment retains the installed base while hair regrowth applications expand most quickly through telehealth conversion.
End User:
Prescriber gatekeeping intensity creates tiered access economics, with dermatologist-mediated channels capturing higher margins than self-directed retail purchase.
- Men:Direct-to-consumer marketing normalizes treatment-seeking behavior among younger demographics. Social media influencer partnerships reduce stigma and expand addressable demand in coastal urban markets.
- Dermatologists:Physician-directed prescribing enables compounded higher-concentration formulations and combination therapies. State pharmacy board oversight in California, Florida, and Texas fragments compliance requirements.
- Women:Lower baseline prevalence of androgenetic alopecia limits segment scale despite comparable treatment efficacy.
- Retail Consumers:Unassisted OTC selection drives volume through pharmacy and supermarket channels.
Men constitute the volume anchor while dermatologist-directed applications achieve the steepest margin expansion.
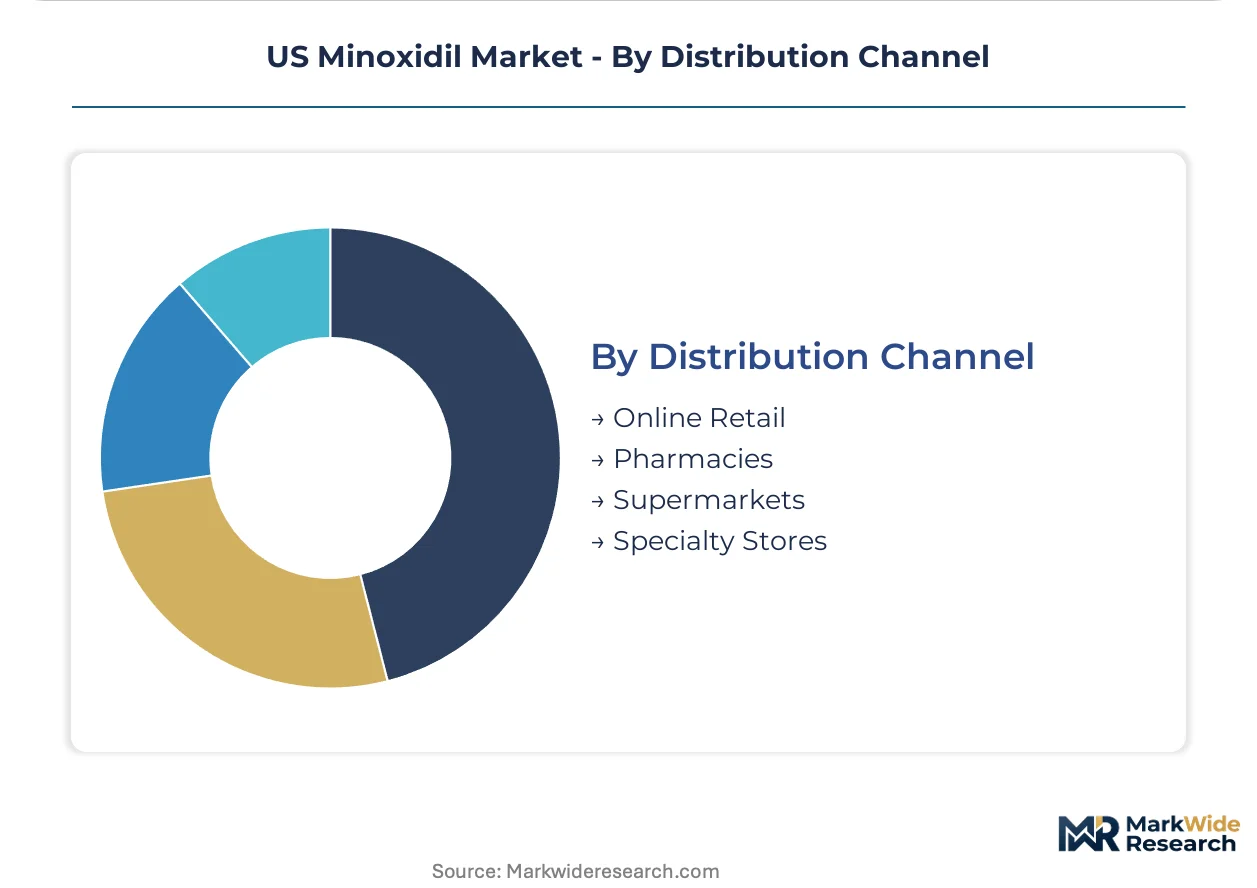
Distribution Channel:
Channel selection determines replenishment predictability and customer lifetime value, with subscription models displacing episodic purchase patterns.
- Online Retail:Direct-to-consumer platforms embed auto-replenishment with progress tracking applications. Same-day delivery infrastructure in California and New York supports just-in-time inventory management.
- Pharmacies:Brick-and-mortar locations retain private-label dominance through Perrigo's vertically integrated manufacturing footprint.
- Supermarkets:Mass-market placement captures impulse and convenience-driven purchase.
- Specialty Stores:Aesthetic and wellness retail environments support premium positioning.
Pharmacies anchor current volume while online retail climbs the fastest through subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and New York where telehealth dermatology platforms command premium subscription rates, while Texas and Florida compete on compounded formulation accessibility and lower compliance costs.
California
Telehealth dermatology density and same-day delivery infrastructure drive the highest subscription renewal rates nationwide. The California State Board of Pharmacy imposes stringent compounding oversight that fragments access for customized minoxidil combinations. Los Angeles and San Francisco anchor demand concentration where influencer-driven marketing normalizes treatment-seeking among men aged 25-40.
New York
Urban coastal demographics and dense dermatology platform penetration sustain premium pricing for foam and spray formulations. New York State Education Department's Office of the Professions regulates telehealth prescribing with particular scrutiny on cross-state promotional claims. The New York City metro area concentrates subscription velocity through embedded progress-tracking applications.
Texas
Compounding pharmacy proliferation and lower state compliance costs attract higher-concentration formulation specialists. The Texas State Board of Pharmacy maintains distinct oversight requirements that enable customized minoxidil-retinoid blends. Houston and Dallas-Fort Worth clusters support hybrid medical-aesthetic positioning with reduced regulatory friction.
Florida
Retiree demographics and aesthetic medicine density sustain demand for hair regrowth applications beyond preventive maintenance. The Florida Board of Pharmacy enforces compounding standards that diverge from California and New York precedents. Miami and Tampa Bay metropolitan areas concentrate telehealth platform expansion targeting snowbird populations.
Illinois
Midwest distribution hub positioning and lower telehealth penetration create geographic white space for subscription model expansion. The Illinois Department of Financial and Professional Regulation governs pharmacy practice with moderate compounding oversight. Chicago anchors regional demand while secondary cities remain underpenetrated relative to coastal benchmarks.
US Minoxidil Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the US minoxidil landscape. Vertically integrated private-label manufacturers sustain mass-market dominance through pharmacy and supermarket channels, while specialized compounders capture margin in higher-concentration niches. Three archetypes define competitive positioning: mass-market private-label operators, premium brand equity holders, and compounding pharmacy specialists. Capacity consolidation and subscription platform partnerships represent the dominant competitive moves reshaping channel economics.
Among mass-market private-label operators, Perrigo Company PLC anchors cost-competitive positioning through vertically integrated manufacturing. Johnson and Johnson Consumer Inc exemplifies premium-tier brand equity built on decades of clinical marketing heritage. Minoxidilmax occupies the specialized compounder archetype, focusing on higher-concentration formulations that bridge OTC accessibility and physician-directed therapy.
| Leading Market Players |
|---|
| Costco Wholesale Corporation |
| Pure Source |
| Perrigo Company PLC |
| Minoxidilmax |
| Par Pharmaceuticals |
| Johnson and Johnson Consumer Inc |
| LGM Pharma |
| Pfizer |
| Walmart |
| Others |
Supply Flow & Price Mechanics
Manufacturing scale economies in 2,4-diamino-6-chloropyrimidine synthesis anchor supply concentration among vertically integrated API producers, compressing unit costs for standardized 2% and 5% formulations while elevating price floors for customized compounded alternatives. Perrigo's captive production of propylene glycol-free foam bases enables cost leadership in pharmacy channels, whereas California compounding pharmacies absorb premium overhead from state-mandated quality control protocols.
Pricing Analysis
The customization-premium spread separates mass-market OTC monograph products from physician-directed compounded formulations. Three-tier pricing structure across premium, standard, and economy levels tracks concentration grade and prescriber involvement, with telehealth subscription tiers commanding premium positioning through embedded compliance monitoring. Cost compression in standard liquid solutions intensifies as private-label operators exploit backward integration into API sourcing. Retail consumers exhibit highest price sensitivity, while dermatologist-mediated patients accept premium markups for tolerability-optimized regimens.
Supply Chain Analysis
Inventory lead times for 2,4-diamino-6-chloropyrimidine intermediates stretch across domestic synthetic chemistry facilities and imported raw material streams. Active pharmaceutical ingredient production concentrates in the United States, India, and China, with final formulation filling distributed across regional contract manufacturers. Propylene glycol, ethanol, and aerosol propellants constitute critical input dependencies. Single-source vulnerability in domestic intermediate suppliers elevates disruption risk. Distribution runs through pharmacy wholesale networks, direct-to-consumer fulfillment centers, and telehealth platform-integrated compounding pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemistry talent scarcity in USP-NF dissolution testing constrains batch release velocity for new formulation launches, creating competitive moats for laboratories with certified quality control infrastructure.
For Market Incumbents: Shield pharmacy channel dominance by deepening backward integration into foam base manufacturing and securing exclusive distribution agreements with telehealth platforms in California and New York. Counter spray-format substitution pressure through rapid portfolio extension into metered-dose aerosol systems. Certification investment in lipid nanoparticle compounding capabilities defends margin position against Texas and Florida specialists. For New Entrants and Emerging Players: Anchor in the Southeast and Midwest geographic white space where telehealth dermatology penetration lags coastal benchmarks. Target Illinois and secondary Midwestern cities with subscription auto-replenishment models supported by regional fulfillment infrastructure. Differentiate through retinoid-caffeine adjuvant blends that occupy regulatory space between OTC monograph boundaries and prescription drug requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compounders with validated lipid carrier platforms over commodity foam manufacturers facing price erosion. Five-to-ten year viability hinges on FDA enforcement clarity for telehealth-prescribed combination therapies. Monitor California State Board of Pharmacy guidance evolution as the decisive inflection signal for hybrid medical-aesthetic market expansion or contraction to traditional OTC boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Telehealth platforms in California capture recurring revenue through embedded progress-tracking applications. |
| Lipid Nanoparticle Formulation Development | Texas compounding pharmacies differentiate through enhanced follicular bioavailability and reduced application frequency. |
| FDA OTC Monograph Expansion Pursuit | New concentration presentations broaden accessible entry points for first-time users beyond standard offerings. |
| Spray Format Manufacturing Scale-Up | Metered-dose aerosol systems reduce shipping costs per dose and improve cosmetic acceptability in subscription tiers. |
| Telehealth Platform Partnership | Cross-state dermatology networks bypass traditional pharmacy channels and reshape margin capture economics. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dermatology platform executives, compounding pharmacy operators, and FDA regulatory affairs specialists, and secondary validation through FDA OTC monograph filings, USP-NF dissolution standards documentation, and state pharmacy board compliance records. Bottom-up demand modeling triangulated against top-down market sizing from customs data and channel shipment audits. Conversations with telehealth subscription managers and quality control laboratory directors supplied operational detail on batch release timelines and patient retention mechanics.
Across the analysis window, the forecast framework applied segment-level growth rate derivation by product format, application endpoint, prescriber control intensity, and geographic telehealth density. CAGRs emerged from trend extrapolation moderated by regulatory scenario weighting. Modeled inputs included FDA enforcement discretion probability distributions, state pharmacy board compliance cost differentials, and direct-to-consumer marketing spend elasticity coefficients for men aged 25-40.
Decision-makers should treat outputs as directional under sustained telehealth platform expansion and stable OTC monograph boundaries; material deviation in FDA compounded drug enforcement or propylene glycol supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Minoxidil API Market
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market