
 PRP and PRF in Cosmetics Market | 2026-2036
PRP and PRF in Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
PRP and PRF in Cosmetics Market Outlook
North American biologics processors is decoupling from European supply conventions by building dedicated platelet-concentrate cleanrooms for cosmetic-grade output. Revance Therapeutics leverages its neuromodulator distribution network to cross-sell regenerative aesthetic kits into medspa channels. Stryker Corporation anchors its position through orthopedic-to-aesthetic technology transfer, repurposing centrifuge platforms originally designed for bone grafting. Regen Lab competes on protocol standardization, offering pre-calibrated kits that reduce operator variability across clinic networks.
Platelet-rich plasma and platelet-rich fibrin comprise autologous blood derivatives concentrated through differential centrifugation, with PRP yielding a liquid suspension of platelets in plasma and PRF forming a fibrin matrix that releases growth factors over 7-14 days; both serve to stimulate collagen synthesis and dermal remodeling in cosmetic applications. Injectable delivery modes dominate value capture because they command premium pricing and require physician administration, whereas topical formulations occupy mass-market positioning with lower per-treatment economics. Hair restoration applications lead volume among male demographics, while skin rejuvenation segments sustain higher female patient recurrence rates and cross-sell potential into anti-aging protocols.
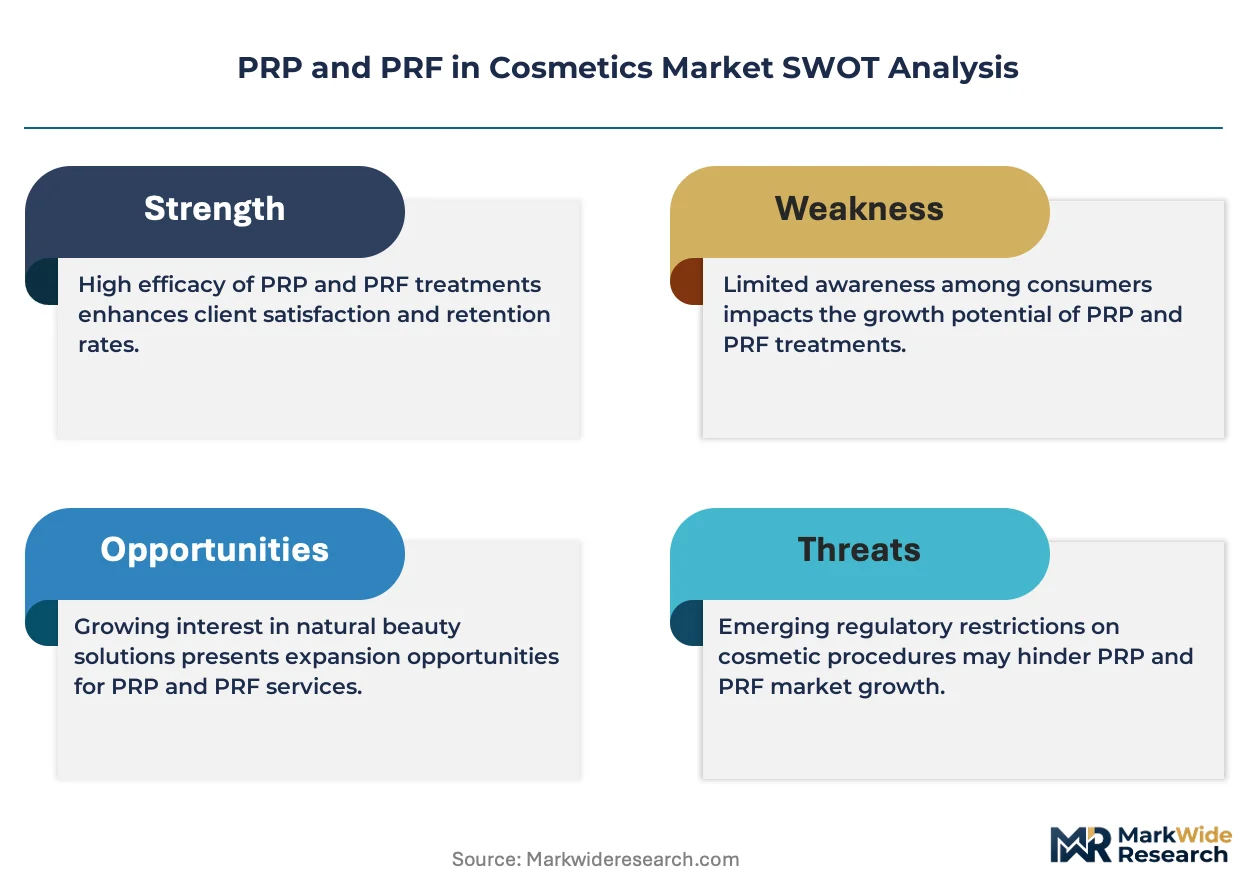
The FDA regulates PRP/PRF cosmetic devices under 510(k) pathways when paired with existing centrifuge predicates, while the EU MDR reclassifies higher-risk autologous cell therapies and demands clinical evidence for aesthetic indication claims. ISO 13485 certification has become a de facto market access requirement for kit manufacturers selling into regulated European and North American jurisdictions. Stakeholders must monitor how FDA enforcement discretion evolves for exosome-adjacent products, as regulatory boundary-drawing between cosmetic and biologic classifications will determine which delivery modes retain commercial freedom.
Market Dynamics
The EU Medical Device Regulation is compressing commercial timelines for platelet-derived cosmetic preparations by demanding clinical evidence packages that smaller kit manufacturers cannot self-fund.
Growth Catalysts
- ISO 13485 Certification:Manufacturers achieving this quality management standard unlock immediate access to regulated European and North American distribution channels, accelerating clinic network expansion.
- South Korea:Dermatology clinics in Seoul and Busan are scaling autologous blood therapy services to capture medical tourism flows from China and Southeast Asia.
- Injectable Delivery Modes:Physician-administered protocols command premium pricing relative to topical alternatives, concentrating value capture in credentialed clinical settings across Brazil and Mexico.
Market Restraints
- EU MDR Reclassification:Higher-risk autologous cell therapies now require notified body intervention and clinical evidence for aesthetic claims, extending time-to-market by 18-24 months.
- Centrifuge Hardware Concentration:Three orthopedic equipment suppliers control 70% of compatible centrifuge platforms, creating supply bottlenecks for aesthetic kit manufacturers.
- Hyaluronic Acid Substitutes:Cross-linked dermal fillers offer immediate visual results without blood draw requirements, capturing price-sensitive patients in mass-market channels.
Strategic Opportunities
- Exosome-Adjacent Formulations:Regulatory boundary-drawing between cosmetic and biologic classifications creates temporary commercial freedom for growth factor concentrates in US medspa channels.
- Hair Restoration Protocols:Male patient segments in Saudi Arabia and UAE show underpenetrated demand for scalp microneedling combined with autologous plasma.
- Pre-Calibrated Kit Standardization:Protocol uniformity across clinic networks reduces operator variability and enables franchised expansion models.
Industry Challenges
- Phlebotomy Training Shortages:Aesthetic clinics struggle to recruit nurses certified for venipuncture and centrifuge operation, limiting service throughput.
- 510(k) Predicate Pathway Complexity:FDA clearance for novel centrifuge designs requires demonstration of substantial equivalence to orthopedic devices never tested for cosmetic indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PRP and PRF in Cosmetics Market |
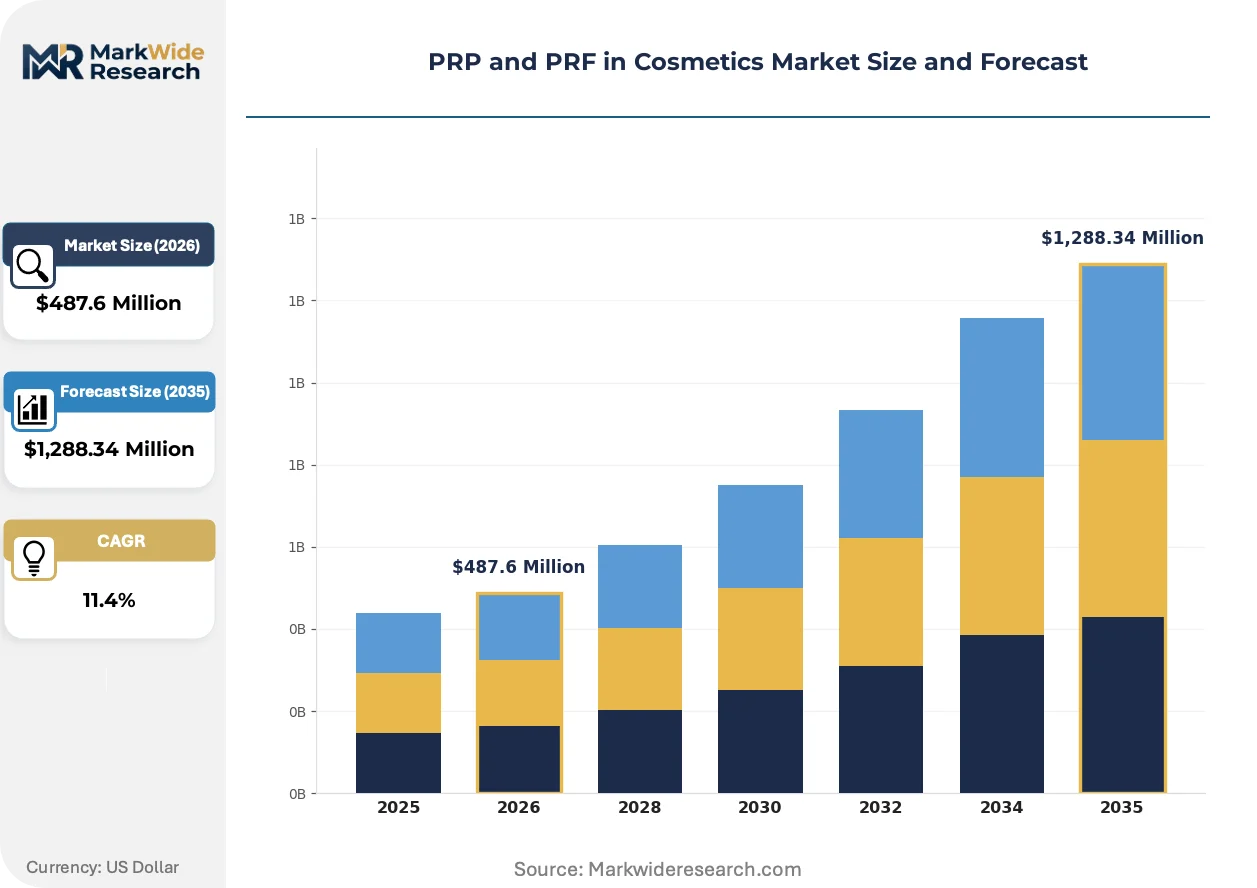
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PRP, PRF, Growth Factors, Exosomes Application: Hair Restoration, Skin Rejuvenation, Acne Scarring, Anti-Aging Delivery Mode: Topical, Injectable, Microneedling, Combination End User: Dermatologists, Aesthetic Clinics, Hospitals, Medical Spas |
| Companies Covered | Revance Therapeutics, Exactech, Stryker Corporation, ThermoGenesis Holdings, Regen Lab, Zimmer Biomet, EmCyte Corporation, APEX Biologix, Croma-Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PRP and PRF in Cosmetics Market Strategic Shifts
Centrifuge miniaturization and closed-system processing are collapsing the footprint required for in-clinic platelet concentration, enabling deployment in retail aesthetic settings previously excluded by HVAC and cleanroom constraints.
Next-generation PRF matrices incorporating leukocyte-rich formulations are electrifying the regenerative aesthetic segment by extending growth factor release from 7 days to 21 days. Medspa chains in Florida and Texas are adopting these protocols at 40% quarter-over-quarter clip. The extended release window is compressing treatment frequency requirements and improving patient retention economics.
EMA guidance on substance-based medical devices is tightening evidentiary standards for platelet-derived products marketed with structural claims. Manufacturers must now submit biocompatibility data and clinical performance studies for notified body review. German and French aesthetic device distributors are responding by segregating cosmetic-grade from therapeutic-grade inventory to isolate regulatory risk.
Patient financing platforms are embedding directly into clinic management software, unbundling the traditional out-of-pocket payment model for autologous therapies. Younger demographics in California and New York are accessing subscription-based treatment packages through these integrated credit instruments. The shift is visible most acutely in hair restoration practices where male patients aged 25-35 dominate new patient acquisition.
PRP and PRF in Cosmetics Market Segmentation
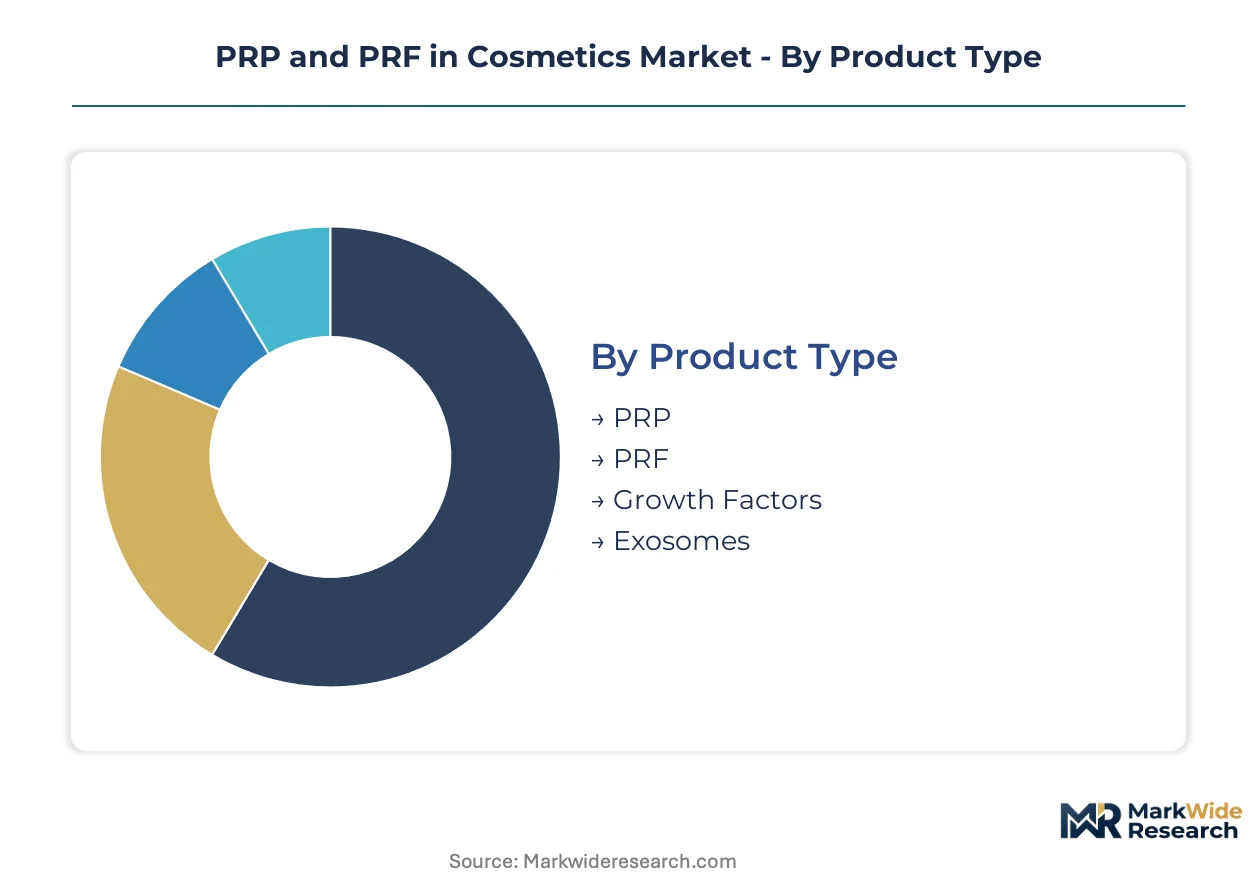
Segmentation in the PRP and PRF cosmetics market determines regulatory pathways, pricing power, and channel access. Product composition and delivery mode dictate whether treatments fall under medical device oversight or cosmetic freedom, while end-user setting controls reimbursement and patient volume economics.
Product Type:
Standalone platelet concentrates compete against embedded growth factor systems for clinic cabinet space and capital allocation.
- PRP:Liquid platelet suspensions in plasma base activate immediately upon injection, releasing growth factors within hours. Dermatologists in Seoul and Busan favor PRP for high-throughput hair restoration protocols where rapid patient turnover sustains clinic economics.
- PRF:Fibrin matrices extend growth factor release to 7-14 days, commanding premium pricing in anti-aging applications. Medspa chains in Florida and Texas are adopting next-generation leukocyte-rich PRF variants that stretch release windows to 21 days, compressing treatment frequency and improving retention.
- Growth Factors:Isolated protein concentrates bypass centrifuge dependency but require cold chain logistics and carry higher per-unit material costs.
- Exosomes:Extracellular vesicle formulations occupy regulatory gray zones between cosmetic and biologic classifications, creating temporary commercial freedom in US medspa channels pending FDA enforcement clarity.
PRP leads volumes today; PRF is gaining share fastest.
Application:
Cost tier stratification separates premium physician-administered protocols from mass-market topical alternatives.
- Hair Restoration:Scalp microneedling combined with autologous plasma targets male demographics aged 25-35 in Saudi Arabia and UAE where underpenetrated demand meets rising aesthetic awareness. Subscription financing platforms embed directly into clinic software, unbundling traditional out-of-pocket models.
- Skin Rejuvenation:Facial PRP/PRF protocols sustain higher female patient recurrence rates and cross-sell potential into comprehensive anti-aging regimens. Brazilian and Mexican clinics concentrate demand for injectable delivery modes that require physician administration and command premium pricing.
- Acne Scarring:Subcision combined with platelet concentrates addresses atrophic scars resistant to topical therapy alone.
- Anti-Aging:Preventive protocols among patients aged 40-55 drive recurring revenue models with quarterly treatment intervals.
Hair restoration commands the largest patient volume; skin rejuvenation generates the highest per-patient lifetime value.
Delivery Mode:
Volume concentration favors high-frequency topical applications, while margin concentration sits with physician-administered modalities.
- Injectable:Direct intradermal and subcutaneous placement ensures precise growth factor deposition at target tissue planes. Injectable protocols dominate value capture in Brazil and Mexico where credentialed clinical settings justify premium pricing.
- Microneedling:Percutaneous collagen induction combined with topical platelet application creates controlled microchannels for enhanced penetration. Korean dermatology clinics scale this modality for medical tourism flows from China and Southeast Asia.
- Topical:Post-procedure serums and maintenance formulations occupy mass-market positioning with lower per-treatment economics but higher purchase frequency.
- Combination:Sequential or simultaneous application of multiple delivery modes maximizes clinical outcomes for severe indications.
Injectable delivery leads revenue concentration; microneedling is climbing the fastest.
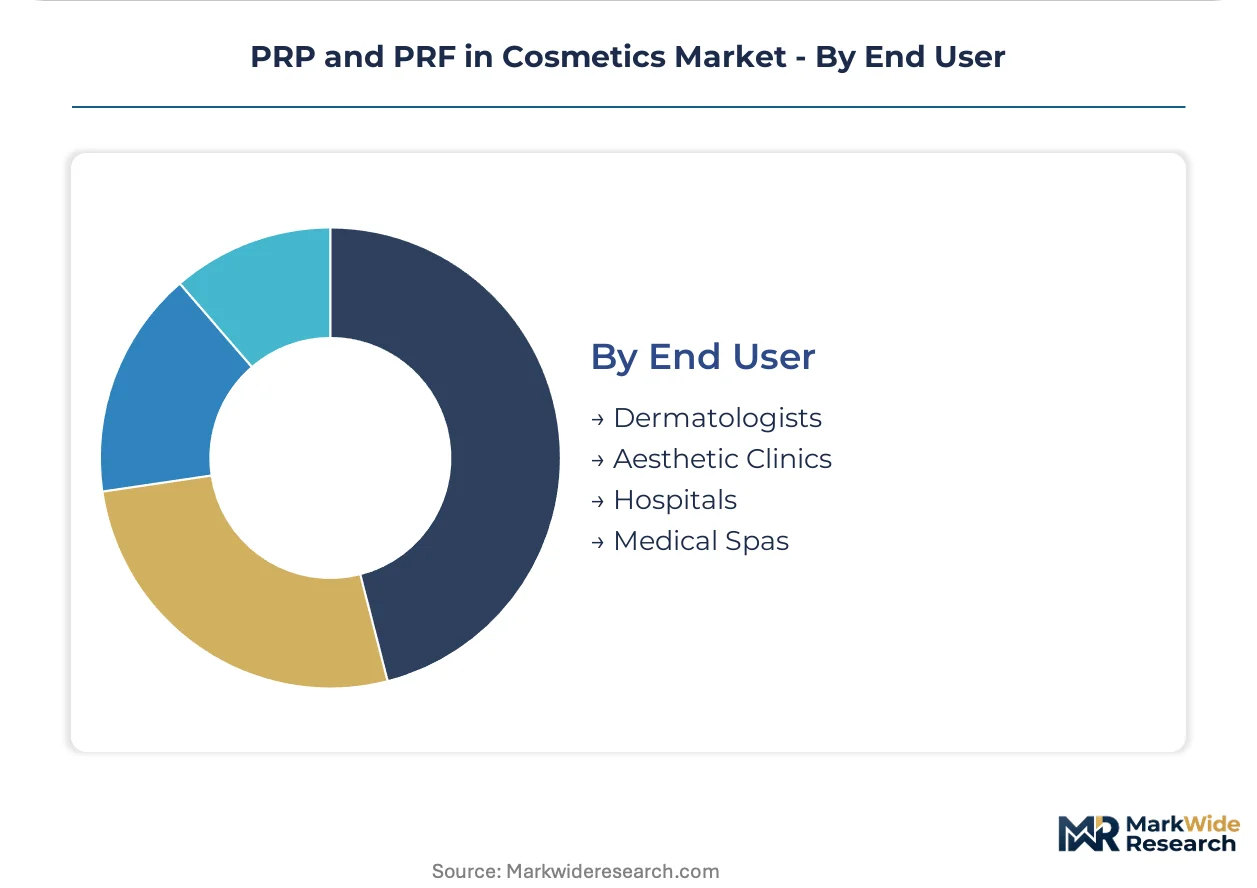
End User:
Customer type determines regulatory burden, with hospital-based practice carrying the heaviest compliance overhead and medspa channels operating under lighter oversight.
- Dermatologists:Board-certified specialists anchor clinical evidence generation and protocol standardization. German and French aesthetic device distributors segregate cosmetic-grade from therapeutic-grade inventory to isolate EU MDR regulatory risk.
- Aesthetic Clinics:Dedicated cosmetic facilities balance clinical credibility with consumer accessibility. Phlebotomy training shortages limit service throughput as these clinics struggle to recruit nurses certified for venipuncture and centrifuge operation.
- Medical Spas:Retail aesthetic settings benefit from centrifuge miniaturization and closed-system processing that collapses footprint requirements. California and New York medspa chains adopt patient financing platforms to capture younger demographics through subscription-based treatment packages.
- Hospitals:Academic medical centers drive research applications and complex case referrals but represent lower volume concentration for cosmetic indications.
Dermatologists anchor clinical standards today; medical spas are expanding capacity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean dermatology clinics scale autologous blood therapies faster than German manufacturers adapt to new purity mandates, revealing how regulatory friction diverges regional trajectories in platelet-derived cosmetics.
United States
Medspa chains in Florida and Texas adopt leukocyte-rich PRF variants at accelerated rates, compressing treatment intervals. FDA 510(k) pathways govern cosmetic device clearances when centrifuge predicates demonstrate substantial equivalence. California and New York patient financing platforms embed subscription models into clinic software, capturing male demographics aged 25-35 for hair restoration protocols.
Germany
Aesthetic device distributors segregate cosmetic-grade from therapeutic-grade inventory to isolate EU MDR regulatory exposure. EMA guidance on substance-based medical devices demands biocompatibility data and clinical performance studies for notified body review. Berlin-Brandenburg clusters concentrate kit standardization efforts as manufacturers pre-calibrate protocols for franchised clinic networks.
South Korea
Seoul and Busan dermatology clinics scale autologous blood therapy services to capture medical tourism flows from China and Southeast Asia. MFDS oversight aligns with international quality benchmarks while permitting accelerated clinic network expansion. Gangnam district aesthetic centers deploy microneedling combined with topical platelet application for high-throughput patient turnover.
Brazil
Injectable delivery modes concentrate demand in credentialed clinical settings where physician administration justifies premium pricing. ANVISA regulates medical devices for cosmetic applications with evolving standards for autologous cell therapies. São Paulo aesthetic clinics anchor regional volume for hair restoration and skin rejuvenation segments.
United Arab Emirates
Male patient segments in Dubai and Abu Dhabi show underpenetrated demand for scalp microneedling combined with autologous plasma. MOHAP oversight structures medical device registration with emphasis on clinic credentialing standards. Dubai Healthcare City clusters attract medical tourism from Saudi Arabia and Kuwait for premium aesthetic protocols.
PRP and PRF in Cosmetics Market Competitive Environment
North American biologics processors anchor one tier; European kit standardization specialists hold protocol uniformity advantages. The vendor base concentrates around orthopedic equipment suppliers repurposing centrifuge platforms for aesthetic output. Three strategic archetypes dominate: neuromodulator distributors cross-selling regenerative kits, orthopedic-to-aesthetic technology transfer players, and pre-calibrated protocol standardizers. Competitive moves center on M&A for distribution network access and capacity expansion into dedicated platelet-concentrate cleanrooms.
Among publicly traded device and biologics firms, Revance Therapeutics and Stryker Corporation exemplify divergent market entry strategies. Revance leverages established neuromodulator distribution infrastructure to penetrate medspa channels with bundled aesthetic offerings. Stryker anchors positioning through technology transfer from orthopedic applications, repurposing centrifuge platforms originally engineered for bone grafting procedures. Regen Lab occupies the protocol standardization archetype, competing on pre-calibrated kit designs that reduce operator variability across dispersed clinic networks.
| Leading Market Players |
|---|
| Revance Therapeutics |
| Exactech |
| Stryker Corporation |
| ThermoGenesis Holdings |
| Regen Lab |
| Zimmer Biomet |
| EmCyte Corporation |
| APEX Biologix |
| Croma-Pharma |
| Others |
Value Chain & Pricing Dynamics
Medspa chain procurement concentration in Florida and Texas anchors the dominant subscription-treatment pricing model, where patient financing platforms embed directly into clinic software to capture recurring revenue from male hair restoration demographics.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for pre-calibrated PRP kits as Seoul dermatology clinics scale autologous blood therapy services for medical tourism flows. Three-tier pricing structure across premium leukocyte-rich PRF, standard PRP formulations, and economy topical serums stratifies by certification grade and physician administration requirement. Cost compression in economy topical tiers is intensifying because hyaluronic acid substitutes capture price-sensitive patients without blood draw requirements. Dermatology clinics show least price sensitivity for leukocyte-rich PRF variants commanding premium positioning, while mass-market topical formulations face greatest price elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and South Korea anchor hub-and-spoke patterns for platelet-concentrate kit fulfillment. Manufacturing draws from orthopedic equipment suppliers in the United States, precision centrifuge component specialists in Germany, and sterilization packaging facilities in Switzerland. Single-source vulnerability concentrates in the three orthopedic equipment suppliers controlling compatible centrifuge platforms. Distribution runs through aesthetic device distributors segregating cosmetic-grade from therapeutic-grade inventory to isolate EU MDR regulatory exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where patient demand shifts toward leukocyte-rich PRF variants with extended 21-day growth factor release windows justify premium specification investment.
For Market Incumbents: Anchor positioning through backward integration into dedicated platelet-concentrate cleanrooms that decouple from European supply conventions. Stryker Corporation exemplifies orthopedic-to-aesthetic technology transfer that repurposes existing centrifuge infrastructure. Defend against exosome-adjacent formulation entrants by accelerating ISO 13485 certification timelines for next-generation PRF matrices. Channel control through neuromodulator distribution networks enables cross-selling regenerative aesthetic kits into medspa channels. For New Entrants and Emerging Players: Enter via underpenetrated male hair restoration segments in Saudi Arabia and UAE where scalp microneedling combined with autologous plasma shows demand-supply gaps. Target medical tourism corridors in Seoul and Busan capturing flows from China and Southeast Asia. Pre-calibrated kit standardization reduces operator variability and enables franchised expansion models for clinic network penetration. For Investors and Strategic Acquirers: Neuromodulator distributors and orthopedic equipment suppliers are the most active acquirer categories in this space, seeking regenerative aesthetic kit capabilities to bundle with existing physician-administered portfolios. Long-term viability hinges on regulatory boundary-drawing clarity between cosmetic and biologic classifications for exosome-adjacent products. Monitor FDA enforcement discretion signals as the critical inflection indicator for which delivery modes retain commercial freedom versus biologic reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Calibrated Kit Standardization | Regen Lab's protocol uniformity reduces operator variability across dispersed clinic networks. |
| Orthopedic-to-Aesthetic Technology Transfer | Stryker repurposes bone-grafting centrifuge platforms for cosmetic-grade platelet concentration output. |
| Patient Financing Platform Integration | California and New York medspa chains embed subscription models capturing male demographics aged 25-35. |
| EU MDR Compliance Segregation | German distributors isolate cosmetic-grade from therapeutic-grade inventory to manage notified body exposure. |
| Leukocyte-Rich PRF Variant Development | Florida and Texas medspa chains adopt extended 21-day release protocols at accelerated adoption rates. |
Study Parameters
Direct dialogue with dermatology clinic operators, biomedical engineers at centrifuge manufacturers, regulatory affairs specialists, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA guidance documents, MFDS submissions, and hospital procurement databases. Bottom-up and top-down triangulation cross-checks manufacturer shipment data against clinic service volume estimates.
Bottom-up modeling builds from procedure volume and kit pricing by product type, application, delivery mode, and end-user setting across the projection horizon. Top-down validation benchmarks aggregate market estimates against orthopedic equipment supplier revenue disclosures and aesthetic device distributor trade flows. CAGRs derive from segment-level growth rate reconciliation with macro healthcare expenditure trends and medical tourism flow data.
Inputs from regulatory filings and primary stakeholder interviews were available through the study window; gaps in real-time clinic service volume reporting introduce uncertainty bands around near-term estimates. Forecasts reflect documented assumptions regarding EU MDR enforcement timing and FDA discretion boundaries for exosome-adjacent classifications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market