
 Cosmetic Cetearyl Alcohol Ingredients Market | 2026-2036
Cosmetic Cetearyl Alcohol Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Cetearyl Alcohol Ingredients Market Insights
Petrochemical-derived fatty alcohols is decoupling from premium cosmetic formulations as plant-based cetearyl alcohol gains cost parity at scale. BASF leverages integrated oleochemical supply chains to secure feedstock consistency across European and Asian production hubs. Croda anchors its positioning through specialty-grade cetearyl alcohol variants tailored for sensitive-skin segments. Kao Corporation dominates Asia-Pacific demand through captive consumption in its personal care brand portfolio and third-party supply contracts.
Cetearyl alcohol, a blend of cetyl and stearyl fatty alcohols typically comprising 30-70% cetyl and 70-30% stearyl composition, functions primarily as an oil-in-water emulsifier and viscosity builder in topical formulations manufactured via catalytic hydrogenation of vegetable or petrochemical wax esters. Emulsifiers command the largest share of product-type value pools due to their non-substitutable role in cream and lotion stability, while skin conditioning agents represent the fastest-growing category as consumers prioritize multifunctional ingredients that combine texture and barrier benefits. Application demand skews heavily toward moisturizers and hair care, where cetearyl alcohol's sensory profile and compatibility with cationic conditioning polymers create formulation lock-in effects that resist cheaper alternatives.
REACH registration requirements in Europe mandate full toxicological dossiers for cetearyl alcohol imports, while the FDA maintains GRAS oversight for cosmetic use in the United States and China's NMPA enforces new cosmetic ingredient registration rules that lengthen market entry timelines. These frameworks elevate compliance costs for smaller suppliers and create regulatory moats for established players with dedicated toxicology and registration teams. Stakeholders must monitor evolving biobased certification standards and regional divergences in preservative system approvals that could force reformulation cycles across export portfolios.
Market Dynamics
Clean-label procurement mandates from premium skincare brands are restructuring cetearyl alcohol supply chains, forcing feedstock traceability investments and accelerating the displacement of petrochemical-derived fatty alcohols by certified plant-based alternatives at cost parity.
Growth Catalysts
- REACH compliance:Full toxicological dossier requirements in Europe create regulatory moats that favor established suppliers with dedicated registration teams and certified supply chains.
- K-beauty manufacturing corridor:South Korea's contract manufacturing expansion drives concentrated demand for emulsifier-grade cetearyl alcohol in sheet mask and essence formulations.
- Green chemistry standards:Emerging biobased certification frameworks in Asia are redirecting procurement toward oleochemical feedstocks with verified carbon accounting.
Market Restraints
- Feedstock concentration risk:Palm oil and coconut oil supply volatility in Southeast Asia creates input cost instability for plant-based production routes.
- NMPA registration timelines:China's new cosmetic ingredient rules extend market entry cycles by 12-18 months for unregistered suppliers.
- Technical substitution ceiling:Cetearyl alcohol's formulation lock-in with cationic conditioning polymers limits displacement risk but also caps premium pricing power.
Strategic Opportunities
- Sensitive-skin segments:Specialty-grade variants with ultra-low impurity profiles command price premiums in dermatological and pediatric formulations.
- Hair care application expansion:Leave-in conditioners and scalp treatments represent underpenetrated categories where emulsifier demand is accelerating.
- CSRD alignment:EU corporate sustainability reporting requirements are creating procurement mandates for Scope 3 traceable feedstocks.
Industry Challenges
- Toxicology dossier compilation:REACH-compliant safety data generation requires specialized regulatory affairs capabilities scarce among mid-tier suppliers.
- Multi-regional certification synchronization:Divergent preservative system approvals between FDA, ECHA, and NMPA force parallel formulation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Cetearyl Alcohol Ingredients Market |
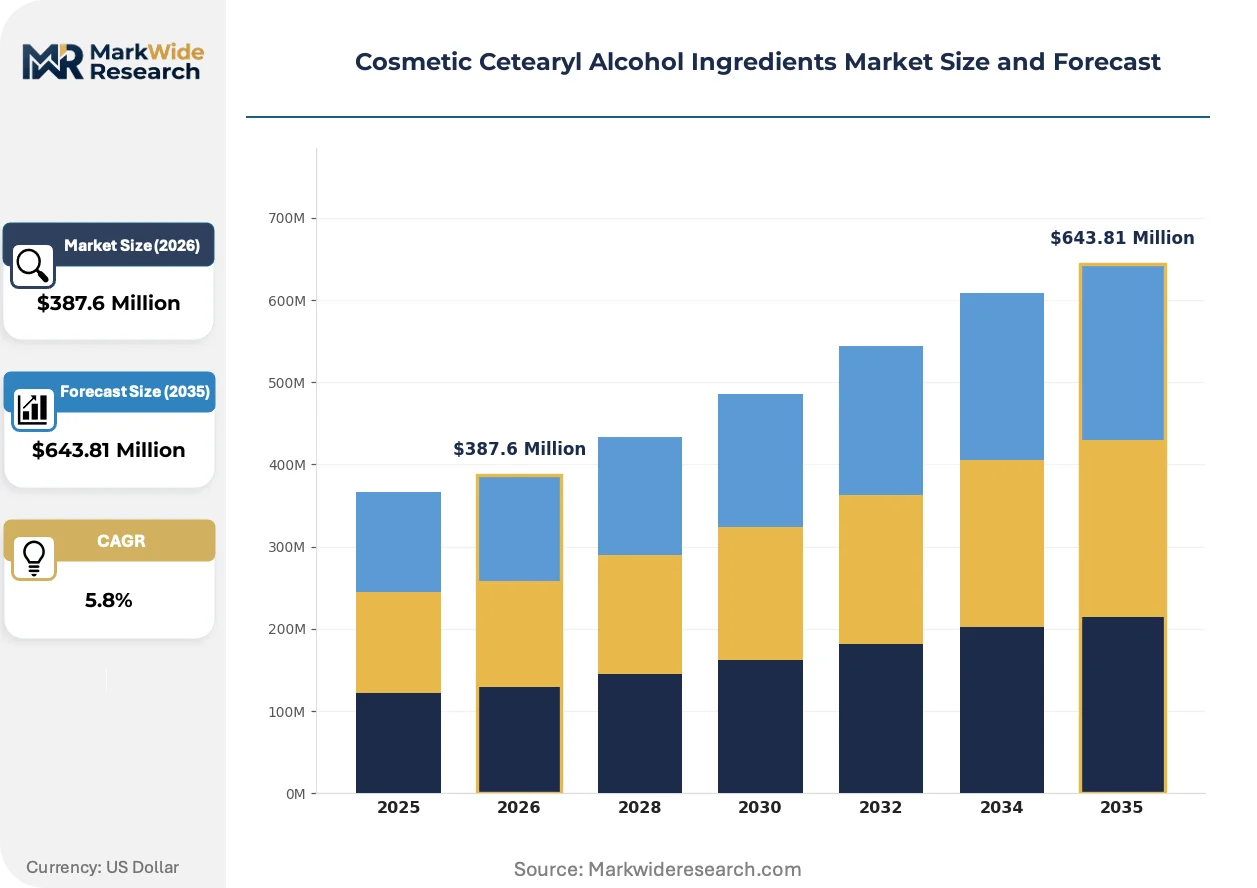
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Thickening Agents, Stabilizers, Skin Conditioning Agents Application: Moisturizers, Hair Care, Makeup, Cleansers Form: Liquid, Cream, Gel, Powder End User: Cosmetic Manufacturers, Personal Care Brands, Contract Manufacturers, Retailers |
| Companies Covered | BASF, P&G Chemicals, Kao Corporation, Croda, VVF LLC, KLK OLEO, Lubrizol, HallStar Company, SEPPIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Cetearyl Alcohol Ingredients Market Trends and Innovations
Formulation science and procurement protocols are converging to reward feedstock transparency, compressing the competitive advantage of opaque supply chains while elevating certified oleochemical pathways.
Enzymatic interesterification of vegetable wax esters is expanding into commercial-scale production of high-purity cetearyl alcohol with tailored cetyl-to-stearyl ratios. Specialty chemical producers in Germany and the Netherlands are adopting these biocatalytic routes to meet brand-specific sensory requirements. The technology is expanding into premium segments previously dominated by petrochemical-derived consistency.
REACH registration dossier requirements now mandate full substance identity and impurity profiling for cetearyl alcohol imports into the European Economic Area. This regulatory burden elevates compliance costs for smaller traders while consolidating procurement relationships around integrated oleochemical producers with in-house toxicology teams. Sensitive-skin and baby care segments are responding fastest by specifying registered-grade material exclusively.
Direct contracting between personal care brands and oleochemical processors is displacing traditional distributor intermediaries in volume procurement. K-beauty contract manufacturers and China's export-oriented personal care clusters are consolidating purchase volumes through annual framework agreements with named suppliers. This pattern is most visible in South Korea's Incheon-Free Economic Zone and China's Guangdong personal care manufacturing belt.
Cosmetic Cetearyl Alcohol Ingredients Market Segmentation
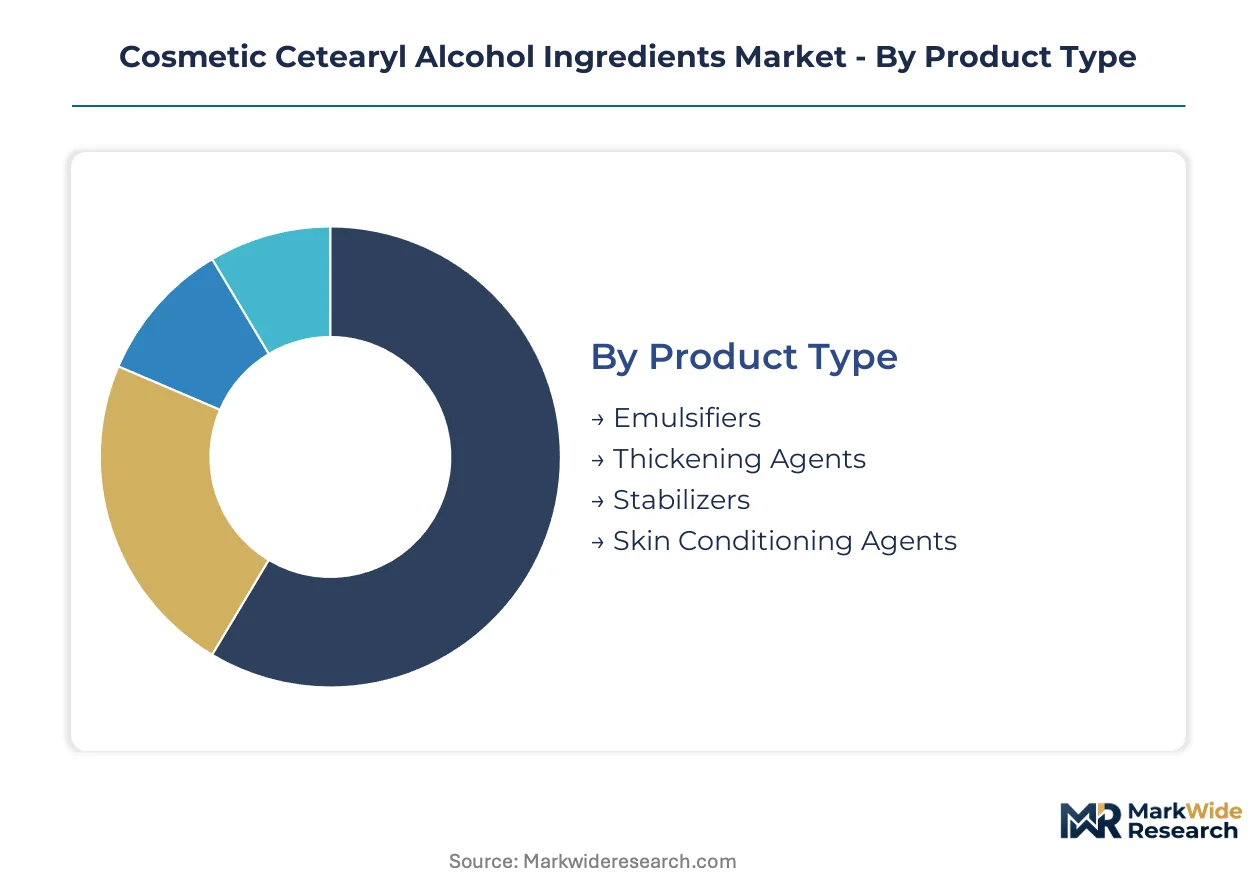
Cetearyl alcohol procurement varies sharply across functional roles and formulation formats, with regulatory burden intensity dictating supplier qualification tiers. Brand clean-label mandates and REACH dossier requirements are compressing the viable supplier base for high-exposure applications.
Product Type:
REACH registration mandates full toxicological dossiers for emulsifier and skin-conditioning grades, while thickening and stabilizer variants face lighter documentation thresholds in European imports.
- Emulsifiers:Oil-in-water systems require 30-70% cetyl-to-stearyl ratios for optimal HLB balance. Demand concentrates in South Korea's sheet mask manufacturing corridor, where formulation stability under high-humidity storage creates non-substitutable procurement lock-in.
- Skin Conditioning Agents:Multifunctional grades combine barrier repair with texture modification, typically specifying ultra-low impurity profiles. Pediatric and dermatological brands in Germany and France are driving fastest expansion through sensitive-skin positioning.
- Thickening Agents:Viscosity-building grades prioritize batch-to-batch consistency over sensory refinement.
- Stabilizers:Crystallization control variants serve anhydrous and w/o emulsion formats with narrower specification windows.
Emulsifiers sit at the top of the volume ranking, with skin conditioning agents climbing the fastest.
Application:
Moisturizer and hair care procurement absorbs the bulk of high-purity grades, while makeup and cleanser segments tolerate broader specification ranges.
- Moisturizers:Facial and body cream formulations exploit cetearyl alcohol's occlusive film-forming alongside emulsification. China's Guangdong export manufacturing belt concentrates demand for mass-market day creams, with premium night cream grades sourcing from Netherlands-based oleochemical processors.
- Hair Care:Rinse-off conditioners and leave-in treatments leverage compatibility with cationic polymers for deposition control. South Korean contract manufacturers are expanding procurement for scalp treatment essences, a category gaining share in K-beauty export portfolios.
- Makeup:Color cosmetic applications prioritize sensory elegance over functional loading.
- Cleansers:Mild surfactant systems incorporate cetearyl alcohol for refatting balance.
Moisturizers command the largest procurement volumes, though hair care is expanding most quickly through leave-in format proliferation.
Form:
Liquid and cream delivery systems dominate premium positioning, while gel and powder formats serve cost-optimized or anhydrous niches.
- Liquid:Pre-dispersed aqueous solutions simplify cold-process manufacturing for mid-tier cosmetic manufacturers. German specialty chemical suppliers are scaling enzymatic interesterification output to serve this format's consistency requirements.
- Cream:Semi-solid bulk deliveries target high-volume contract manufacturers with heated mixing capabilities. South Korea's Incheon-Free Economic Zone concentrates demand through integrated formulation-to-filling operations.
- Gel:Low-viscosity variants suit sprayable and pump-dispense applications.
- Powder:Anhydrous grades serve solid shampoo and travel-format formulations with extended shelf-life requirements.
Cream formulations lead volume procurement, with liquid formats gaining share fastest through process efficiency mandates.
End User:
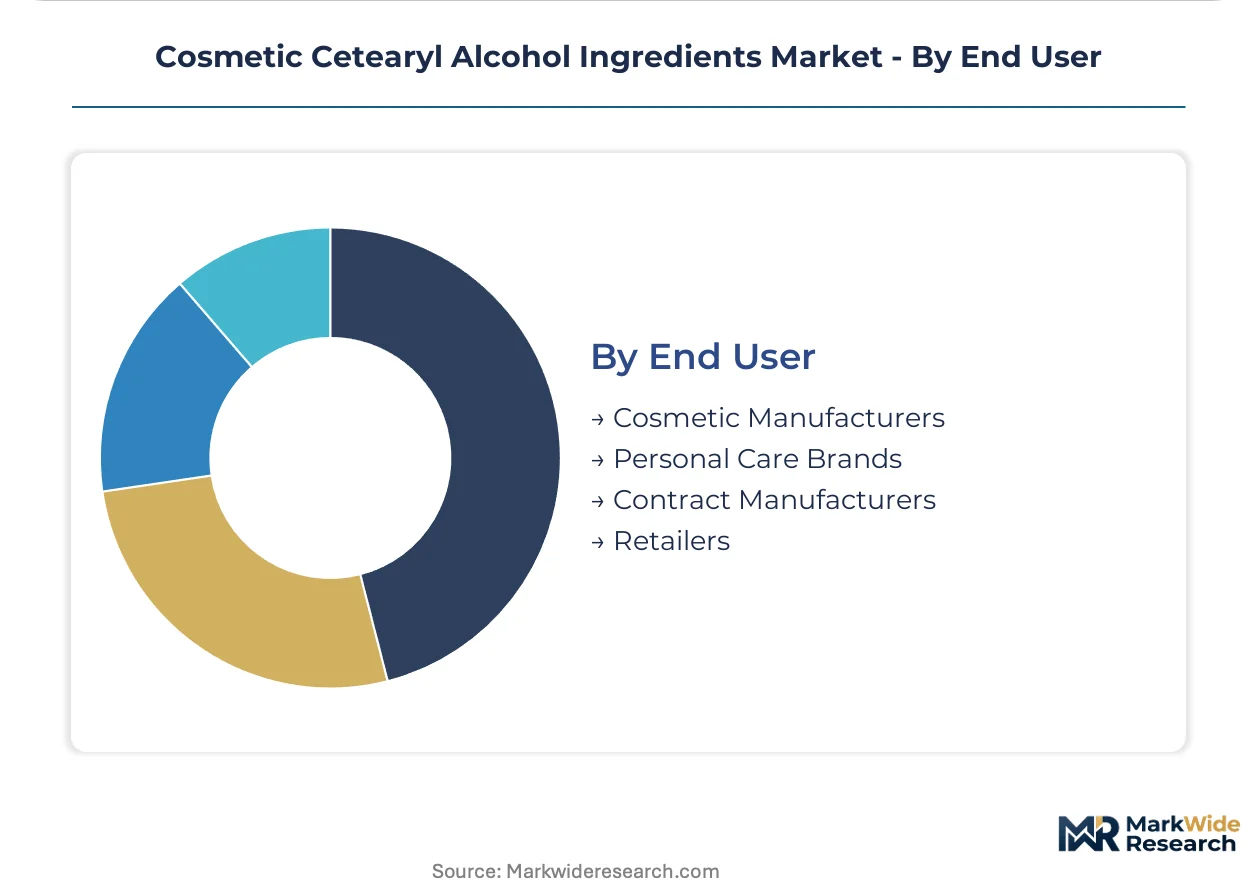
Direct contracting patterns diverge sharply between captive-brand manufacturers and third-party suppliers, with contract manufacturers consolidating purchase volumes through annual framework agreements.
- Cosmetic Manufacturers:Integrated brand owners with in-house formulation capabilities specify registered-grade material exclusively. Kao Corporation's captive consumption across Japanese and Asian production hubs exemplifies this procurement mode.
- Contract Manufacturers:Third-party formulators serving multiple brand clients aggregate demand through named-supplier agreements. South Korean and Chinese clusters are displacing distributor intermediaries fastest through direct oleochemical processor relationships.
- Personal Care Brands:Non-integrated marketers rely on toll manufacturing with ingredient specification control.
- Retailers:Private-label programs source through contracted formulators with limited direct procurement involvement.
Contract manufacturers sit at the top of the volume ranking, with cosmetic manufacturers climbing the fastest through backward integration into formulation capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's K-beauty manufacturing corridor anchors procurement concentration for emulsifier-grade cetearyl alcohol, with China's Guangdong export zones and Germany's integrated oleochemical hubs following as secondary demand centers. REACH registration requirements in Europe and NMPA rules in China are restructuring supplier qualification tiers across all major markets.
South Korea
Sheet mask and essence formulations drive concentrated demand for high-purity emulsifier grades in the Incheon-Free Economic Zone. MFDS cosmetic ingredient oversight mandates full safety documentation for imported fatty alcohols. Contract manufacturers in Seoul Capital Area are displacing distributor intermediaries through direct annual framework agreements with named oleochemical suppliers.
China
Guangdong's personal care export manufacturing belt absorbs bulk volumes for mass-market moisturizer formulations. NMPA registration timelines extend market entry cycles by 12-18 months for unregistered cetearyl alcohol suppliers. Yangtze River Delta processors are consolidating procurement through backward integration into oleochemical feedstock relationships.
Germany
Dermatological and pediatric brands in Bavaria and North Rhine-Westphalia specify REACH-registered material with ultra-low impurity profiles. ECHA dossier requirements for full toxicological data create regulatory moats favoring established suppliers with dedicated registration teams. Enzymatic interesterification capacity is scaling in the Netherlands-Germany border region to serve premium sensory requirements.
United States
Clean-label procurement mandates from premium skincare brands headquartered in California and New York Metro are accelerating plant-based feedstock adoption. FDA GRAS oversight maintains consistent cosmetic use approval without REACH-equivalent dossier burdens. Southeast contract manufacturing clusters are specifying certified oleochemical pathways to satisfy brand Scope 3 traceability requirements.
Japan
Kao Corporation's captive consumption across domestic production hubs exemplifies integrated brand-owner procurement modes. METI guidelines on biobased chemical certification are redirecting procurement toward feedstocks with verified carbon accounting. Osaka-Kobe industrial corridors concentrate toll manufacturing relationships for non-integrated personal care marketers.
Cosmetic Cetearyl Alcohol Ingredients Market Competitive Landscape
Global majors compete with regional champions across integrated oleochemical supply chains, with REACH registration capabilities and feedstock traceability systems serving as primary differentiation vectors. The supplier base organizes into three tiers: integrated petrochemical-oleochemical conglomerates with multi-regional production footprints, specialty chemical houses focused on high-purity cosmetic grades, and regional oleochemical processors serving captive or contract manufacturing demand. Dominant competitive moves include backward integration into palm and coconut oil supply chains, plus enzymatic biocatalytic technology licensing for tailored cetyl-to-stearyl ratio production.
Within the integrated conglomerate tier, BASF anchors positioning through European and Asian production hub coordination, while Kao Corporation exemplifies captive-demand absorption through personal care brand portfolio integration. Among specialty-grade suppliers, Croda occupies a position representing ultra-low impurity profile capabilities for sensitive-skin segments.
| Leading Market Players |
|---|
| BASF |
| P&G Chemicals |
| Kao Corporation |
| Croda |
| VVF LLC |
| KLK OLEO |
| Lubrizol |
| HallStar Company |
| SEPPIC |
| Others |
Pricing and Supply Chain Analysis
REACH-registered versus unregistered grade divergence splits procurement economics between premium dermatological supply and commodity cosmetic sourcing. Certification ladders in Europe and China force parallel inventory strategies, with registered material commanding sustained premiums while spot-market petrochemical alternatives face margin compression from feedstock volatility and extended NMPA approval cycles.
Pricing Analysis
Input-cost pass-through from palm and coconut oil feedstocks anchors pricing volatility for plant-based production routes. Three-tier pricing structure across premium, standard, and economy levels reflects REACH dossier completion status, ultra-low impurity specifications, and volume commitment scale. Pricing pressure stems from Southeast Asian feedstock concentration risk and Chinese contract manufacturers consolidating purchase volumes through annual framework agreements. Mass-market moisturizers exhibit highest price sensitivity, while pediatric and dermatological brands absorb premiums for certified supply chain documentation.
Supply Chain Analysis
Certification and qualification gating through REACH, NMPA, and MFDS frameworks concentrates viable supplier relationships around integrated oleochemical producers with dedicated toxicology teams. Manufacturing capacity clusters in Germany, the Netherlands, and South Korea's Incheon-Free Economic Zone, with raw material dependency on Malaysian and Indonesian palm oil plus Philippine coconut oil. Single-source vulnerability runs through Southeast Asian feedstock processing before catalytic hydrogenation. Distribution runs through direct annual framework agreements between oleochemical processors and K-beauty contract manufacturers, displacing traditional distributor intermediaries fastest in China's Guangdong belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label emulsifier demand functions as a stable compounder, with formulation lock-in effects from cationic polymer compatibility resisting technical substitution and sustaining procurement continuity across economic cycles.
For Market Incumbents: Anticipate enzymatic biocatalytic technology licensing as the primary defensive lever against specialty-grade entrants targeting sensitive-skin segments. Deepen backward integration into named-supplier palm and coconut oil relationships to secure feedstock consistency amid Southeast Asian supply volatility. Prioritize CSRD-aligned Scope 3 traceability investments to defend position against emerging green chemistry procurement mandates from EU personal care brands.
For New Entrants and Emerging Players: Capture white-space opportunity in scalp treatment essences and leave-in conditioner formats where South Korean contract manufacturers are expanding procurement fastest. Target hair care application expansion as the most penetrable category, with enzymatic interesterification capabilities enabling tailored cetyl-to-stearyl ratios for brand-specific sensory requirements. Pursue direct contracting relationships with China's Yangtze River Delta processors as the primary go-to-market angle, bypassing distributor intermediaries entirely.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration capabilities and feedstock traceability systems serve as primary differentiation vectors, squeezing mid-tier suppliers without dedicated toxicology teams. Long-term viability favors integrated oleochemical conglomerates with multi-regional production footprints and specialty chemical houses with ultra-low impurity profile capabilities. Monitor NMPA registration timeline compression as the critical inflection signal for Chinese market entry accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm and Coconut Oil Supply Chains | Secures feedstock consistency for BASF and KLK OLEO across European and Asian production hubs amid Southeast Asian volatility. |
| Enzymatic Biocatalytic Technology Licensing | Enables Croda and specialty German producers to manufacture tailored cetyl-to-stearyl ratios for premium sensory requirements. |
| REACH Dossier Completion and Maintenance | Creates regulatory moats favoring established suppliers with dedicated registration teams over smaller traders. |
| Direct Annual Framework Agreements with Contract Manufacturers | Consolidates procurement volumes for South Korean and Chinese clusters while displacing distributor intermediaries. |
| CSRD-Aligned Scope 3 Traceability Investment | Satisfies EU corporate sustainability reporting mandates for feedstock carbon accounting in premium brand procurement. |
Research Methodology
Multiple input streams — primary interviews with cosmetic formulators, oleochemical procurement leads, and regulatory affairs directors; secondary validation through ECHA registration databases, NMPA filing records, and customs trade data; plus SEC 10-K disclosures from integrated chemical conglomerates — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across product type, application format, and regional production hub segmentation generated value and volume outputs over the projection horizon. CAGRs were derived from growth driver elasticity modeling against feedstock price indices and regulatory timeline assumptions. Industry-specific forecast inputs included K-beauty manufacturing corridor expansion rates and enzymatic interesterification capacity buildout trajectories.
Underlying measurement precision varies by segment; emulsifier and skin conditioning agent categories carry tighter precision than thickening and stabilizer variants due to registration documentation density. Forecasts reflect assumptions about NMPA timeline normalization and REACH dossier maintenance continuity. A model refresh is warranted upon material change in Southeast Asian feedstock supply disruption frequency or MFDS cosmetic ingredient oversight expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Compound Camphor Ointment Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market