
 Cosmetic & Toiletry Chemicals Market | 2026-2036
Cosmetic & Toiletry Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic & Toiletry Chemicals Market Analytics
Multi-source procurement for active ingredients is shifting toward vertically integrated supply agreements as brands seek traceability. BASF SE leverages its backward integration into petrochemical feedstocks to control surfactant cost structures. Croda International Plc differentiates through lipid chemistry leadership in emollient technology. Evonik Industries AG anchors its position via specialty silicone alternatives for clean-label hair care.
Cosmetic and toiletry chemicals comprise functionally active and inactive substances formulated at specified concentrations to deliver stability, sensory performance, or biological efficacy in finished consumer products. These chemicals typically undergo esterification, ethoxylation, or fermentation-derived synthesis to achieve defined HLB values, rheological profiles, or antimicrobial spectra for topical application. Surfactants occupy the largest volume position due to universal cleansing application across skin care and hair care segments, while preservative systems command disproportionate margin contribution from tightening microbial safety standards. Emollients represent the fastest-expanding category as lipid-based barrier repair claims proliferate in premium skin care and makeup formulations.
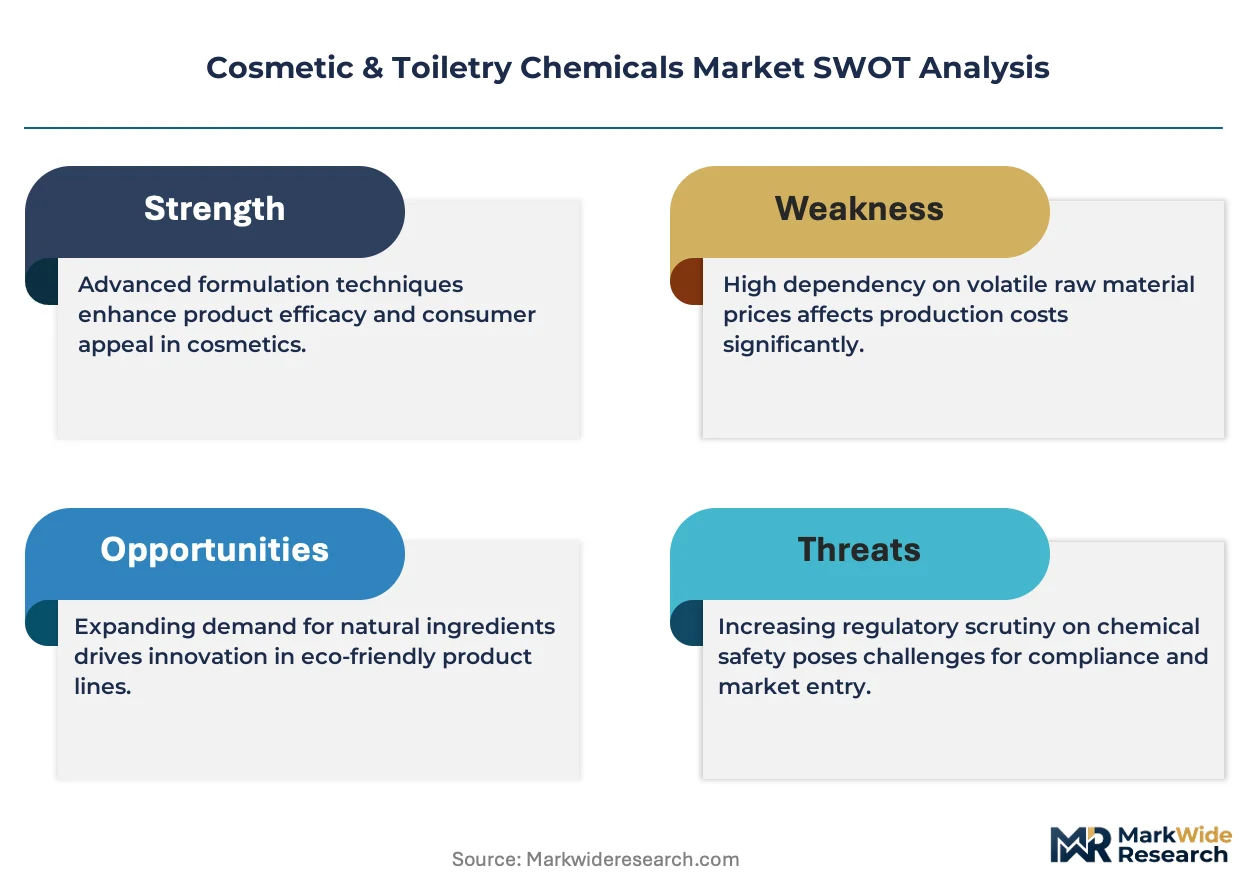
REACH registration requirements in Europe, FDA cosmetic ingredient oversight in the United States, and China's GB standards administered by SAMR collectively elevate compliance costs for synthetic preservative and surfactant suppliers. ECHA's evolving restrictions on CMR-classified substances are accelerating reformulation cycles toward bio-derived alternatives, particularly in preservative and emollient categories. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border formulation supply chains.
Market Dynamics
Clean beauty certification requirements are compressing formulation cycles as brands race to replace synthetic preservatives and petrochemical surfactants before ECHA restriction deadlines take effect.
Growth Catalysts
- ECHA CMR restrictions:European bans on carcinogenic, mutagenic, and reprotoxic substances are forcing rapid adoption of bio-based preservation systems across skin care and hair care lines.
- China domestic formulation expansion:Captive laboratories in Shanghai and Guangzhou are absorbing regional specialty ingredient demand previously served by European imports.
- Biotechnology fermentation:Microbial synthesis of ceramides and squalane is displacing shark-derived and olive-sourced alternatives in premium emollient formulations.
Market Restraints
- Palm oil price volatility:Surfactant cost structures remain exposed to Malaysian and Indonesian feedstock fluctuations and EU Deforestation Regulation traceability mandates.
- Specialty chemical supply concentration:German and Swiss lipid chemistry specialists control critical emollient precursor pathways, creating single-source vulnerability for mid-tier formulators.
- Natural preservation efficacy gaps:Bio-derived antimicrobial systems demonstrate shorter shelf-life performance versus synthetic parabens, limiting clean-label claims in mass-market distribution.
Strategic Opportunities
- India personal care manufacturing:PLI scheme incentives and BIS standardization are attracting contract formulation investment for domestic and export skin care production.
- Silicone-free hair care:Evolving EU environmental classification of cyclic silicones is creating white space for plant-derived conditioning polymers in European salon and retail channels.
- Solid format cosmetics:Waterless shampoo bars and concentrated cleansing balms are opening preservative-free positioning in sustainable beauty segments across North American and European direct-to-consumer platforms.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise bridging cosmetic science and green chemistry principles remains concentrated among senior practitioners at established European suppliers.
- REACH registration timelines:New bio-based surfactant introductions face 18-36 month dossier preparation and consortium negotiation periods before market authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic & Toiletry Chemicals Market |
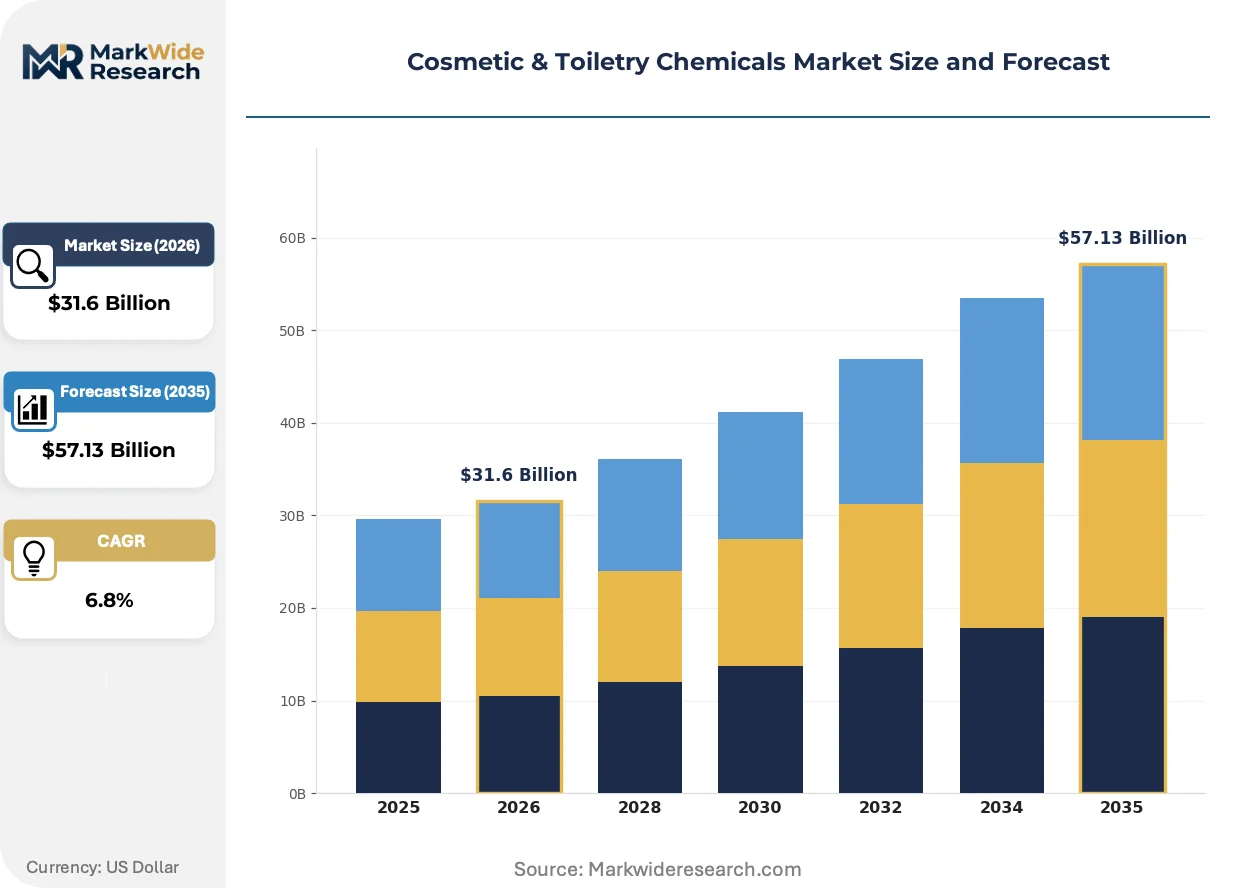
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $57.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Emollients, Humectants, Preservatives Application: Skin Care, Hair Care, Oral Care, Makeup End User: Manufacturers, Retailers, Distributors, E-commerce Formulation Type: Liquid, Cream, Gel, Powder |
| Companies Covered | BASF SE, Evonik Industries AG, Croda International Plc, Ashland Inc., Dow Chemical Company, Clariant AG, Symrise AG, DSM-Firmenich, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic & Toiletry Chemicals Market Evolving Landscape
Biotechnology-derived actives and waterless product formats are converging to redefine efficacy claims and supply chain water intensity across skin and hair care categories.
Biosynthetic squalane produced via engineered yeast fermentation is absorbing volume share from traditional olive and amaranth extraction routes. Premium skin care brands in France and South Korea are adopting this pathway to secure supply independence from agricultural harvest variability. The technology is absorbing margin pressure from volatile botanical feedstock markets while enabling carbon footprint reduction claims.
REACH authorization requirements for existing synthetic preservatives are tightening substance evaluation thresholds through ECHA's 2024-2027 work program. Downstream formulators face reformulation mandates for methylisothiazolinone and formaldehyde-releasing systems in rinse-off applications. Hair care and wet wipe segments are responding fastest, with preservative-free and organic acid-buffered alternatives entering professional and baby care lines.
Direct-to-consumer sampling programs are compressing traditional distributor relationships in color cosmetics and skin care actives. Indie brands in California and Seoul are sourcing single-ingredient concentrates via platform-enabled supplier marketplaces, bypassing conventional regional distribution layers. This pattern is most visible in retinol, vitamin C, and peptide additive categories where technical specifications are standardized and batch certification is digitized.
Cosmetic & Toiletry Chemicals Market Segmentation
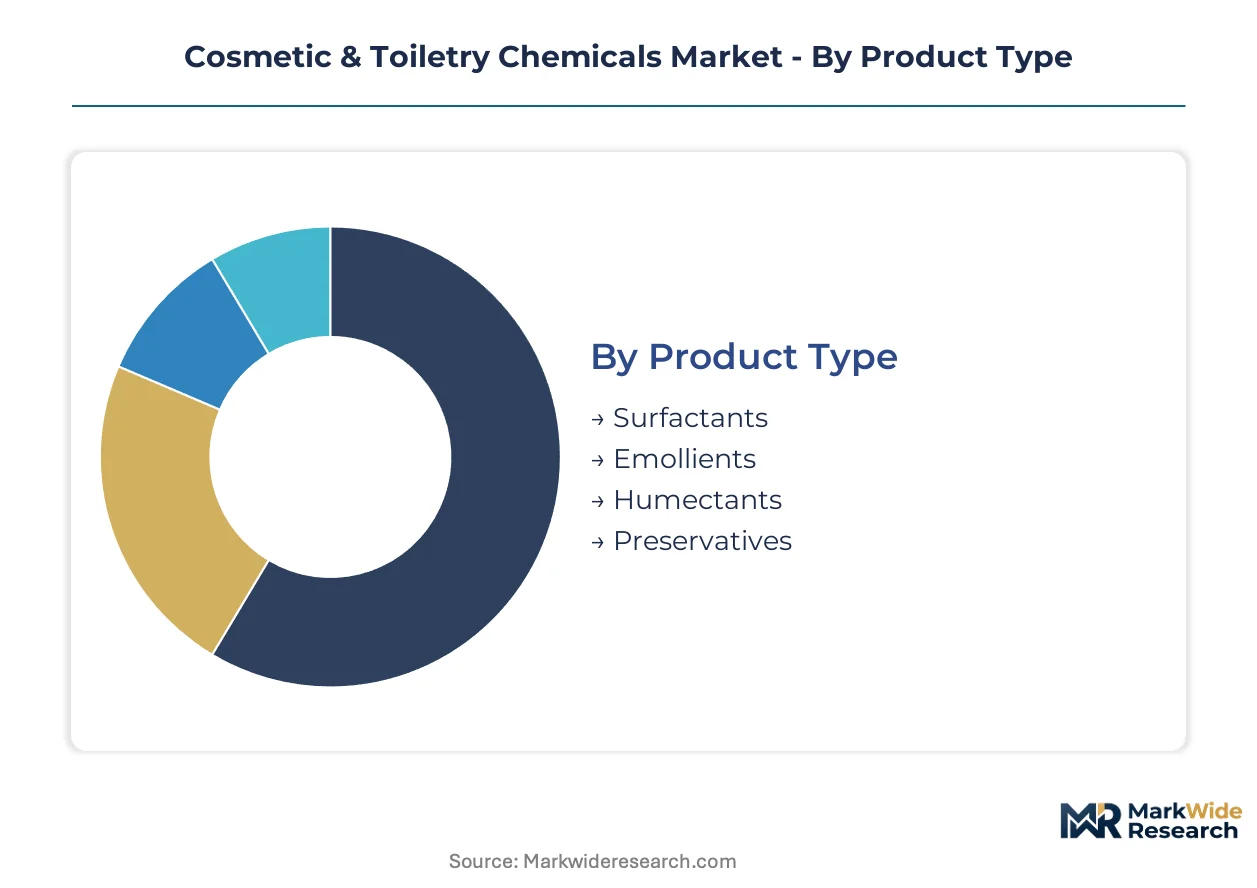
Cosmetic and toiletry chemicals fragment across four distinct axes, each revealing divergent margin structures and supply chain requirements. Product type segmentation exposes the tension between high-volume surfactant commodities and premium-priced specialty emollients. Application and end-user dimensions further stratify procurement patterns between mass-market manufacturers and clean-beauty indie brands.
Product Type:
Surfactants dominate tonnage while emollients capture disproportionate value, creating a bifurcated supply landscape between commodity scale and specialty margin.
- Surfactants:Anionic, cationic, nonionic, and amphoteric surface-active agents reduce interfacial tension for cleansing and foaming functions. Demand concentrates in China and India where domestic manufacturers are absorbing regional volume previously imported from European suppliers, though palm oil feedstock volatility continues compressing margins for sulfate-based systems.
- Emollients:Lipid-based barrier repair ingredients including esters, fatty alcohols, and hydrocarbon oils deliver skin conditioning and sensory modification. Premium skin care brands in France and South Korea are driving fastest expansion here as ceramide and squalane claims proliferate in anti-aging and microbiome-friendly formulations.
- Humectants:Hygroscopic molecules such as glycerin, sorbitol, and sodium PCA attract and retain moisture in aqueous formulations.
- Preservatives:Antimicrobial systems including organic acids, phenoxyethanol, and bio-derived alternatives ensure microbiological stability against ECHA and FDA safety thresholds.
Today's leader: Surfactants. Tomorrow's challenger: Emollients.
Application:
Skin care commands formulation complexity while hair care offers volume scale, with oral care and makeup occupying distinct regulatory and technical niches.
- Skin Care:Facial moisturizers, serums, cleansers, and sun care products demand the broadest ingredient palette across actives and functional additives. Clean beauty certification requirements in California and EU markets are accelerating preservative-free and waterless format adoption, compressing traditional formulation cycles.
- Hair Care:Shampoos, conditioners, styling products, and treatments rely heavily on surfactant-silicone-polymer systems. Silicone-free positioning is gaining fastest traction in German and French salon channels as cyclic silicone environmental classifications tighten under REACH.
- Oral Care:Toothpastes, mouthwashes, and whitening systems require specialized flavor masking and abrasive compatibility.
- Makeup:Color cosmetics, foundations, and lip products prioritize pigment dispersion, wear longevity, and sensory elegance.
Skin care absorbs the most R&D investment. Hair care offers the clearest substitution opportunity for petrochemical-derived conditioning agents.
End User:
Procurement authority splits between integrated manufacturers controlling formulation IP and platform-enabled distributors fragmenting traditional supply relationships.
- Manufacturers:Brand-owning companies with captive laboratories specify ingredient grades and purity standards directly.
- Retailers:Private label and store-brand operators sourcing finished formulations or semi-finished bases.
- Distributors:Regional chemical traders managing inventory, documentation, and technical service for mid-tier formulators.
- E-commerce:Direct-to-consumer platforms and indie brand marketplaces enabling single-ingredient concentrate sourcing, bypassing conventional distribution layers in California and Seoul.
Manufacturers retain pricing power. E-commerce is eroding distributor relevance fastest in standardized actives.
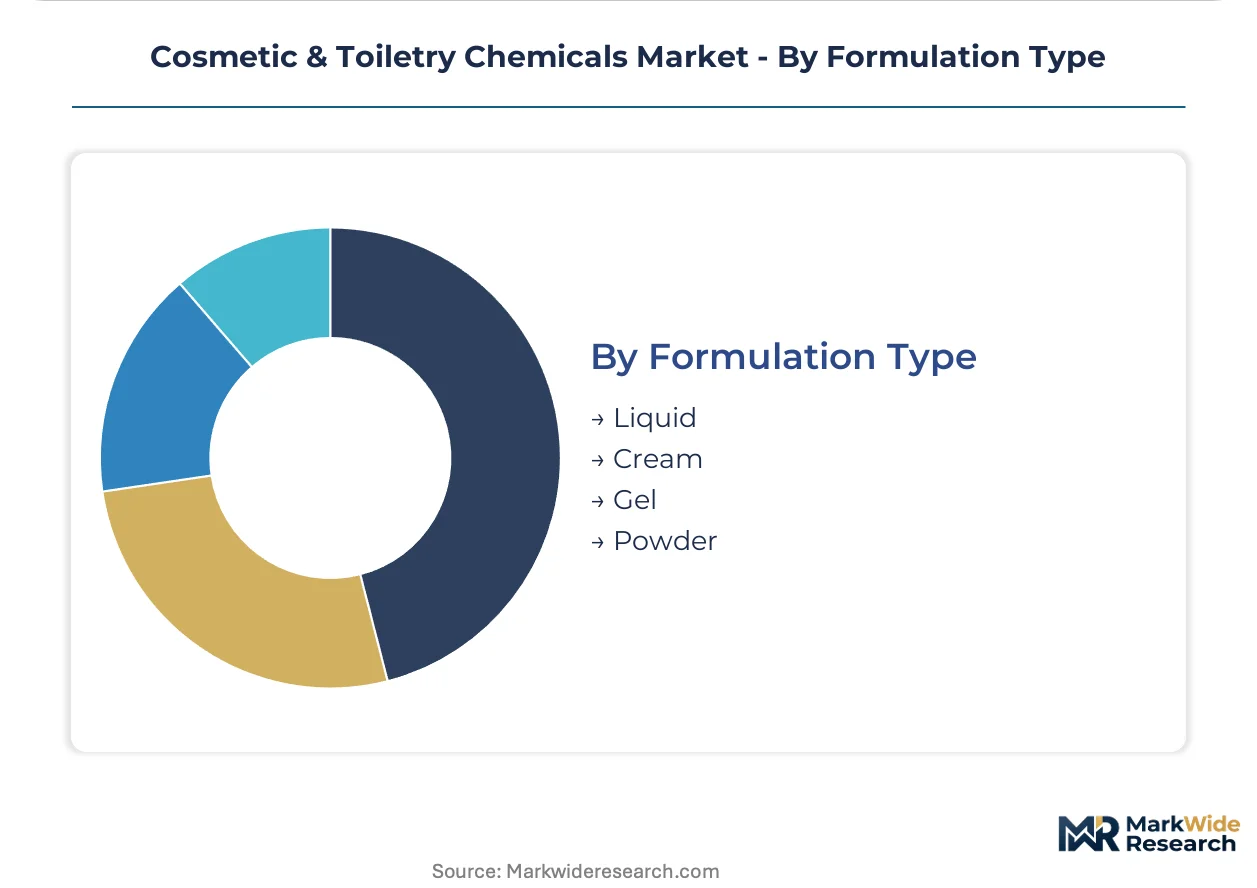
Formulation Type:
Physical state determines preservation burden, water intensity, and packaging requirements across the sustainability spectrum.
- Liquid:Aqueous solutions and fluid emulsions requiring robust preservation systems and stability against freeze-thaw cycles.
- Cream:Semi-solid oil-in-water or water-in-oil emulsions with higher emollient loading and richer sensory profiles.
- Gel:Cross-linked polymer networks delivering clarity, spreadability, and suspension capacity for actives.
- Powder:Anhydrous particulate systems enabling preservative-free claims and concentrated transportation economics, expanding fastest in solid shampoo bars and cleansing balms across North American direct-to-consumer channels.
Liquid maintains volume dominance. Powder formats are climbing the fastest as waterless beauty gains regulatory and consumer favor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Guangzhou absorb the fastest capacity expansion as domestic Chinese manufacturers build captive formulation laboratories. Specialty ingredient procurement is fragmenting across regional clusters. Regulatory divergence between ECHA, FDA, and SAMR is forcing parallel compliance investments.
China
Domestic cosmetic manufacturers in Shanghai and Guangzhou are expanding captive formulation laboratories that previously relied on European imports. SAMR's GB standards for cosmetic ingredient safety are tightening documentation requirements for bio-based surfactants. The Yangtze River Delta cluster is absorbing regional specialty emollient demand as local biotechnology fermentation scales up ceramide production.
Germany
BASF SE's backward integration into petrochemical feedstocks anchors surfactant cost control for European skin care and hair care formulators. ECHA's evolving REACH restrictions on CMR-classified substances are accelerating R&D redirection toward natural preservation systems. The Rhine-Ruhr industrial corridor concentrates lipid chemistry expertise that supplies premium emollient precursors to French and South Korean brands.
United States
Indie brands in California are sourcing single-ingredient concentrates via platform-enabled supplier marketplaces, bypassing conventional distribution layers. FDA cosmetic ingredient oversight is elevating compliance costs for synthetic preservative suppliers serving mass-market personal care. The Los Angeles-Orange County metro anchors clean beauty certification demand that compresses formulation cycles for preservative-free positioning.
France
Premium skin care brands in Paris and Lyon are adopting biosynthetic squalane from engineered yeast fermentation to secure supply independence from agricultural harvest variability. EU Green Deal compliance requirements are redirecting investment toward bio-based surfactants in rinse-off applications. The Île-de-France region concentrates formulation chemist expertise bridging cosmetic science and green chemistry principles.
India
PLI scheme incentives and BIS standardization are attracting contract formulation investment for domestic and export skin care production. The country's national pharmaceutical regulator is aligning cosmetic ingredient safety frameworks with emerging ASEAN harmonization. Maharashtra's Mumbai-Pune industrial corridor is absorbing multinational specialty chemical sourcing previously routed through Singapore distributors.
Cosmetic & Toiletry Chemicals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-derived alternatives and waterless format specialization. The supplier base stratifies between petrochemical-anchored commodity surfactant producers and fermentation-based specialty emollient innovators. Three archetypes dominate: backward-integrated chemical conglomerates controlling feedstock economics, lipid chemistry specialists commanding premium barrier-repair ingredients, and platform-enabled ingredient marketplaces disintermediating traditional distribution. Competitive moves concentrate on M&A for biotechnology capabilities and strategic partnerships for clean beauty certification compliance.
Within the integrated chemical tier, BASF SE represents the archetype of feedstock-controlled surfactant supply. Evonik Industries AG and Croda International Plc exemplify specialty positioning through silicone alternatives and lipid chemistry leadership respectively. These three anchors illustrate the divergence between commodity scale and premium formulation value capture.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Croda International Plc |
| Ashland Inc. |
| Dow Chemical Company |
| Clariant AG |
| Symrise AG |
| DSM-Firmenich |
| Solvay SA |
| Others |
Value Network & Pricing Analysis
Formulation chemist concentration in the Rhine-Ruhr corridor feeds directly into pricing-tier spreads, with European labor premiums widening the gap between premium bio-based emollients and commodity surfactants sourced from lower-cost Asian manufacturing clusters.
Pricing Analysis
Input-cost pass-through from palm oil and petrochemical feedstocks governs contract structures across surfactant categories. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based grades from conventional sulfate systems. Cost compression in mass-market anionic surfactants is intensifying because Malaysian and Indonesian feedstock volatility compresses processor margins. Indie clean-beauty brands in California and Seoul show least price sensitivity for fermentation-derived ceramides, while private-label manufacturers in India absorb maximum pressure on preservative costs.
Supply Chain Analysis
Certification and qualification gating through REACH dossier preparation and SAMR GB standard documentation filters supplier participation. Manufacturing concentrates in Germany, China, and Switzerland, with lipid chemistry specialists in the Rhine-Ruhr corridor and biotechnology fermentation scaling in Shanghai's Yangtze River Delta. Critical dependencies include Malaysian palm oil derivatives, engineered yeast strains for squalane, and olive-derived phytosterols. Single-source vulnerability runs through German emollient precursor pathways. Distribution runs through regional chemical traders managing inventory and technical documentation for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European regulatory compliance costs and Asian manufacturing scale, with ECHA restriction timelines accelerating reformulation expenditure in France and Germany while Chinese captive laboratories capture regional volume at lower cost bases.
For Market Incumbents: Anticipate biotechnology-derived preservative systems displacing synthetic paraben volumes by securing fermentation capacity partnerships before ECHA authorization deadlines tighten. BASF SE and Croda International Plc should deepen backward integration into bio-based feedstocks to defend margin position against emerging yeast-fermentation specialists. Certification investment in EU Green Deal compliance represents the critical lever for maintaining pricing power in French and German premium channels.
For New Entrants and Emerging Players: Enter via silicone-free hair care conditioning polymers in European salon channels, where cyclic silicone environmental classifications under REACH have opened immediate white space. Target solid-format waterless cosmetics in North American direct-to-consumer platforms, where preservative-free positioning commands retail premium. Platform-enabled supplier marketplaces in California offer the most penetrable go-to-market angle for single-ingredient concentrate distribution.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fermentation-based emollient producers lacking brand relationships but holding scalable biotechnology IP. Long-term viability across the analysis window favors suppliers with captive yeast-strain libraries and documented REACH dossiers. Watch for ECHA substance evaluation threshold announcements as the signal indicating accelerated M&A windows for natural preservation system specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures margin control against palm oil volatility for German surfactant producers. |
| Fermentation Capacity Expansion | Enables squalane supply independence from olive harvest variability for French skin care brands. |
| REACH Dossier Consortium Participation | Accelerates market authorization timelines for bio-based preservative introductions. |
| Platform-Enabled Distribution Partnership | Disintermediates traditional chemical traders for California indie brand sourcing. |
| Solid Format Product Line Extension | Captures preservative-free positioning in North American sustainable beauty segments. |
Research Methodology
Bottom-up skin care and hair care formulation modeling reconciled against top-down surfactant and emollient production tracking forms the analytical core. Primary interviews with cosmetic formulation chemists, procurement leads at brand-owning manufacturers, biotechnology R&D directors, and regional chemical distribution managers combined with secondary validation from ECHA substance registrations, SAMR GB standard filings, customs trade data, and SEC disclosures from publicly traded suppliers. Triangulation between demand-side specification trends and supply-side capacity announcements anchors volume estimates.
Input-output matrix framing connects feedstock availability through processing capacity to finished ingredient pricing tiers across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user procurement authority, and formulation physical state, with regional regulatory clusters treated as distinct supply-demand nodes. CAGRs derive from segment-level volume buildups validated against aggregate chemical industry growth patterns, with biotechnology fermentation scale-up curves and ECHA restriction implementation timelines as industry-specific forecast inputs.
Inputs from ECHA registration databases and SAMR cosmetic ingredient filings were available through the study window; gaps in private-label manufacturer procurement data introduce uncertainty bands around mass-market surfactant volume estimates. Forecasts reflect documented assumptions regarding ECHA work program implementation pace and Chinese domestic laboratory expansion rates. A model refresh is warranted upon material change in REACH authorization timelines or Malaysian palm oil export policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Lanolin Nipple Cream Market
Cosmetic Chemicals
Europe Hyaluronic Acid-Based Dermal Fillers Market
Cosmetic Chemicals
Emollients Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Cosmetics and Personal Care Ingredients Market
Cosmetic Chemicals
Hair Gloss Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market