
 Cosmetic Isoparaffins Market | 2026-2036
Cosmetic Isoparaffins Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Isoparaffins Market Insights
EU REACH is decoupling cosmetic isoparaffin demand from conventional mineral oil sourcing by mandating tighter polycyclic aromatic hydrocarbon limits. ExxonMobil Chemical Company leverages its integrated refining footprint to supply pharmaceutical-grade isoparaffin streams. Croda International Plc anchors its position through bio-based alkane alternatives that compete on carbon intensity metrics. Lanxess AG specializes in high-purity C13-C14 isoparaffins for sensitive-skin applications.
Cosmetic isoparaffins are branched-chain saturated hydrocarbons with carbon ranges typically spanning C10 to C16, manufactured via catalytic reforming or Fischer-Tropsch synthesis to achieve ultra-low aromatic content below 10 ppm. These solvents function primarily as non-volatile carriers, spreadability enhancers, and moisture barriers in leave-on cosmetic products. Light isoparaffins dominate current volume due to their compatibility with volatile silicone replacements in skin care, while medium isoparaffins represent the fastest-growing category as hair care brands reformulate away from cyclic silicones. Ultra-light isoparaffins command premium positioning in fragrance applications where rapid evaporation profiles are essential.
EMA cosmetic ingredient guidelines, EPA TSCA Section 5 premanufacture notifications, and China's GB standards for cosmetic raw materials collectively shape purity benchmarks and market access conditions for isoparaffin suppliers. ECHA substance evaluation protocols now require extended toxicity datasets for C15+ isoparaffin fractions used in leave-on products. Stakeholders must monitor evolving biobased alkane certifications and regional carbon border adjustments that will redefine feedstock competitiveness.
Market Dynamics
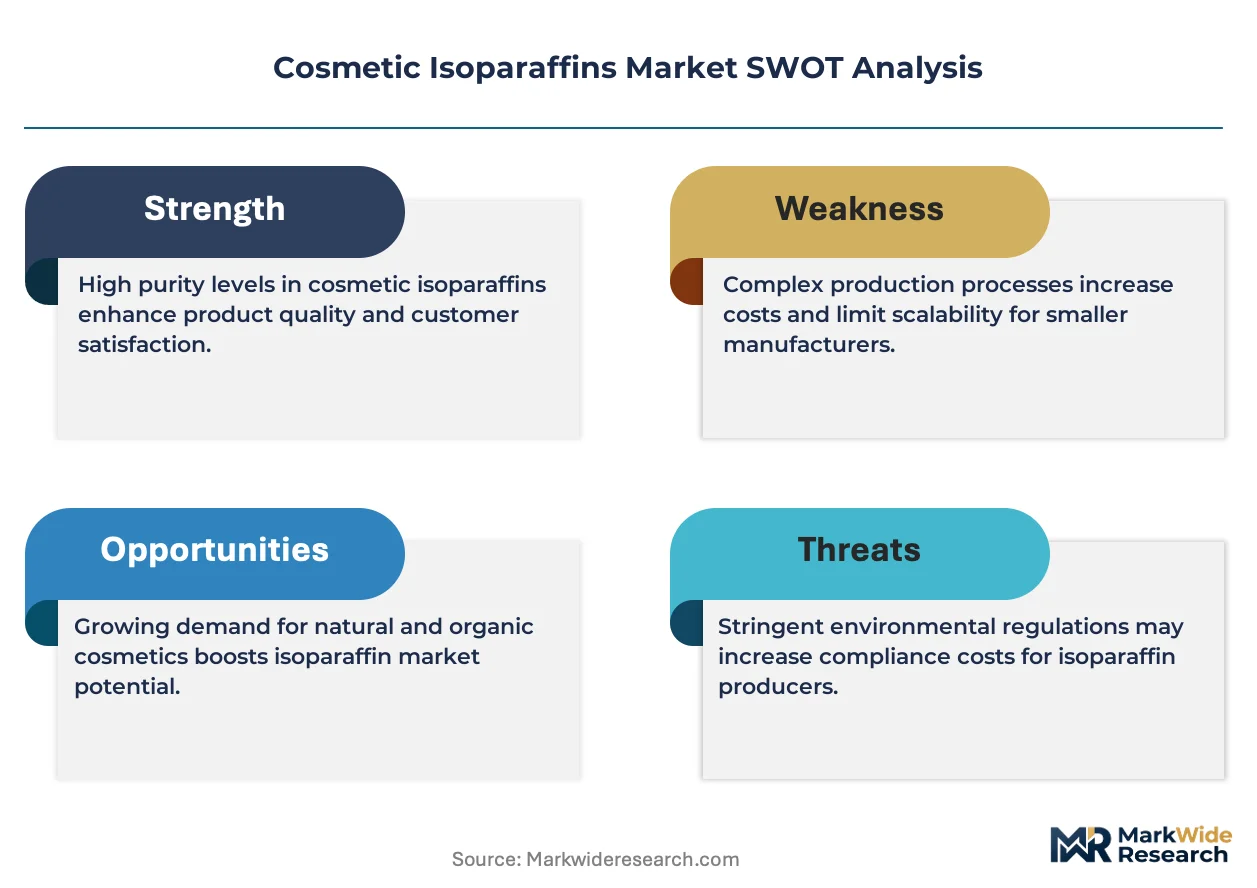
EU REACH polycyclic aromatic hydrocarbon limits are forcing cosmetic formulators to abandon conventional mineral oil sourcing and migrate toward catalytically refined isoparaffin streams with sub-10 ppm aromatic content.
Growth Catalysts
- REACH compliance mandates:European cosmetic manufacturers face binding purity specifications that favor isoparaffin solvents over traditional hydrocarbon carriers.
- Silicone substitution wave:Personal care brands are accelerating reformulation programs to replace cyclic silicones with medium isoparaffins in hair conditioning products.
- Seoul manufacturing concentration:South Korea's K-beauty production cluster generates concentrated procurement demand for ultra-low aromatic solvents.
Market Restraints
- Feedstock volatility:Naphtha cracking economics and natural gas liquid pricing directly compress isoparaffin margin structures.
- Supplier concentration:Pharmaceutical-grade isoparaffin capacity concentrates among integrated refiners with catalytic reforming assets.
- Bio-based substitution threat:Croda International's alkane alternatives compete on lifecycle carbon metrics in premium cosmetic segments.
Strategic Opportunities
- Fragrance evaporation profiles:Ultra-light isoparaffins command premium positioning in fine fragrance applications requiring rapid dry-down characteristics.
- Sensitive-skin specialization:High-purity C13-C14 fractions open formulation opportunities in dermatologically tested product lines.
- China GB standard alignment:Harmonizing purity benchmarks with China's cosmetic raw material regulations unlocks manufacturing access for multinational brands.
Industry Challenges
- Extended toxicity datasets:ECHA substance evaluation protocols now demand comprehensive safety data for C15+ fractions in leave-on applications.
- Legacy formulation integration:Reformulating established cosmetic SKUs around isoparaffin carriers requires stability testing timelines that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Isoparaffins Market |
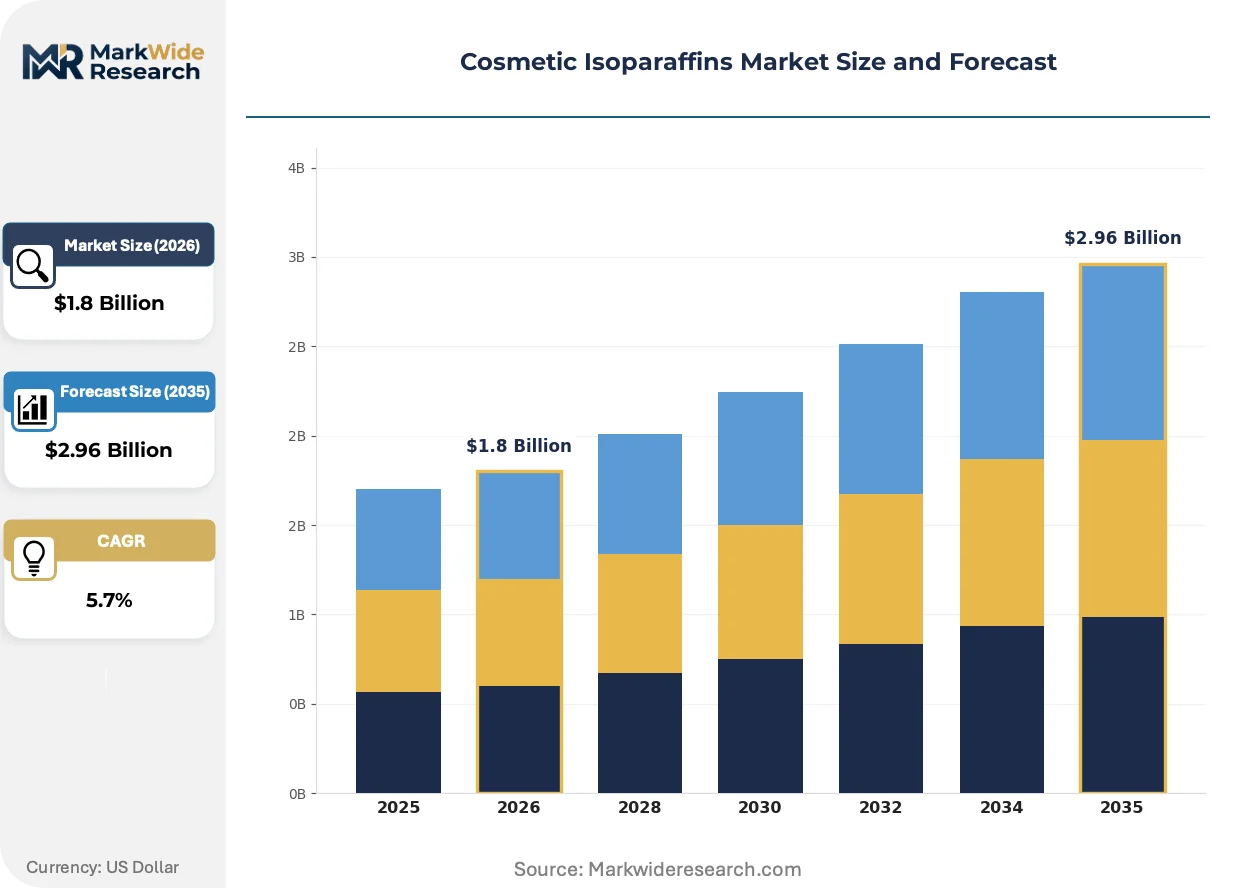
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Isoparaffins, Medium Isoparaffins, Heavy Isoparaffins, Ultra-Light Isoparaffins Application: Makeup, Skin Care, Hair Care, Fragrance Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Customer Type: Individual Consumers, Professional Salons, Cosmetic Manufacturers, Retailers |
| Companies Covered | Lanxess AG, The Innovation Company, Croda International Plc, Nihon Koken Kogyo Co., Ltd., Rita Corporation, INEOS Group Limited, Presperse Corporation, ExxonMobil Chemical Company, Elementis PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Isoparaffins Market Trends and Innovations
Fischer-Tropsch synthesis routes are gaining industrial traction as brands pursue carbon intensity reduction without sacrificing solvent performance. Three intersecting developments are reshaping competitive positioning.
Biocatalytic upgrading of sugar-derived feedstocks is integrating into commercial isoparaffin production, enabling cosmetic brands to meet Scope 3 reduction targets. K-beauty manufacturers in South Korea are adopting these bio-based streams fastest, compressing the premium positioning window for fossil-derived alternatives. The technology is integrating carbon accounting directly into procurement specifications.
REACH authorization requirements for mineral oil derivatives are tightening impurity thresholds across the European Economic Area. Cosmetic ingredient suppliers must now certify polycyclic aromatic hydrocarbon content below detectable limits. Leave-on skin care products face the most stringent enforcement, driving technical service investments in analytical verification.
Direct sourcing contracts between fragrance houses and isoparaffin refiners are displacing traditional distributor intermediaries. Specialty chemical procurement teams at L'Oréal and Estée Lauder are negotiating volume commitments with integrated producers. This pattern is most visible in Paris and New York, where global formulation centers sit adjacent to trading desks.
Cosmetic Isoparaffins Market Segmentation
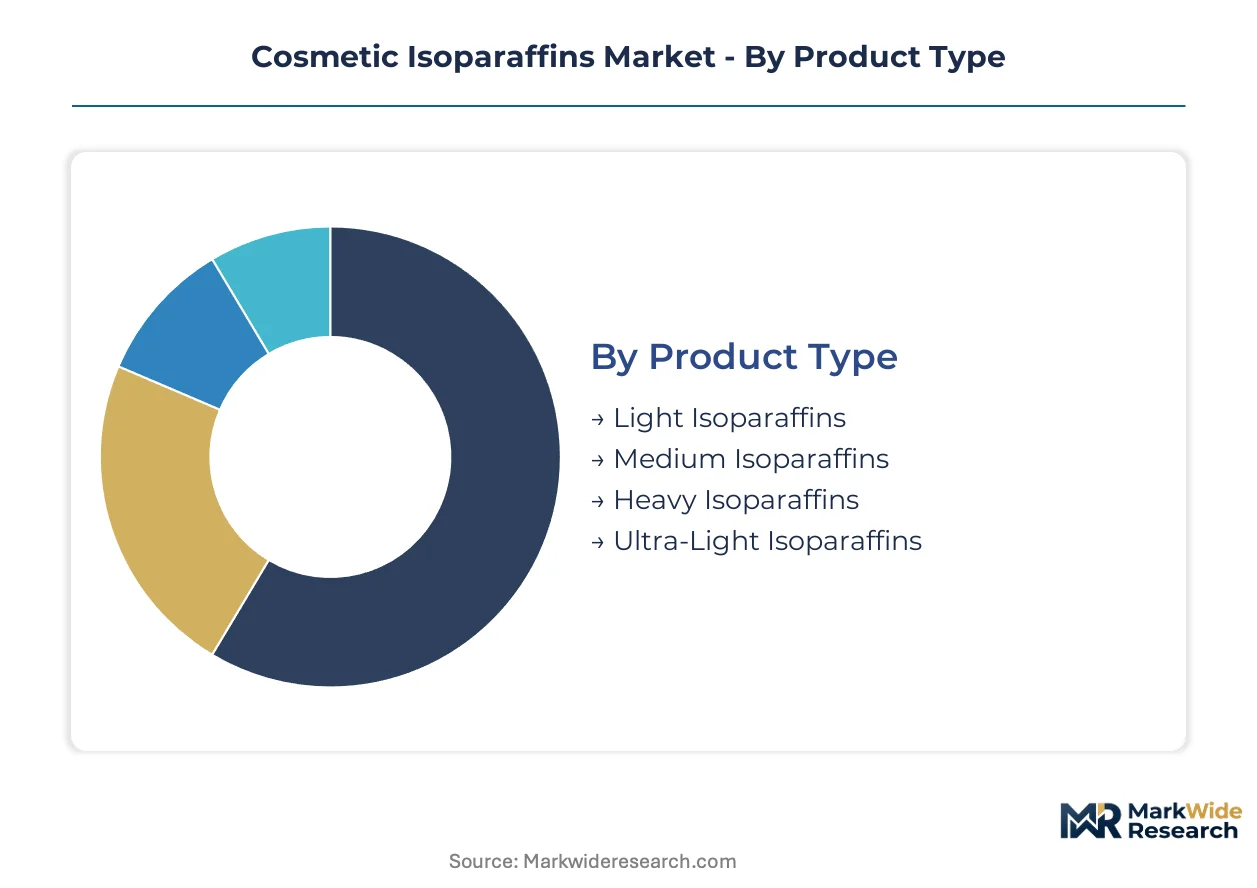
Isoparaffin segmentation reveals how carbon chain length dictates functional role and regulatory exposure across cosmetic formulations. Manufacturers configure product portfolios around evaporation profiles, skin contact duration, and substitution economics for cyclic silicones.
Product Type:
Light isoparaffins function as standalone volatile carriers in quick-dry applications, while heavy fractions embed as persistent moisture barriers in leave-on systems.
- Light Isoparaffins:C10-C12 branched alkanes deliver rapid evaporation with minimal residue, making them compatible with volatile silicone replacements in Korean skin care manufacturing. Seoul-based K-beauty formulators concentrate procurement here due to compatibility with waterless serum textures.
- Medium Isoparaffins:C13-C14 fractions balance spreadability with moderate persistence, anchoring hair conditioner reformulations as brands abandon cyclic silicones under EU REACH pressure. German cosmetic chemists specify these grades for detangling formulations requiring thermal stability.
- Heavy Isoparaffins:C15-C16 saturated hydrocarbons serve as occlusive film-formers in overnight skin treatments.
- Ultra-Light Isoparaffins:C8-C9 isoparaffins enable rapid dry-down in fine fragrance applications.
Volume placements concentrate in Light Isoparaffins; the faster expansion belongs to Medium Isoparaffins.
Application:
End-use segmentation tracks where isoparaffins substitute incumbent technologies versus entrench in legacy formulations.
- Makeup:Long-wear foundation and lipstick formulations employ isoparaffins as transfer-resistant film formers. Paris-based luxury houses specify pharmaceutical-grade C12-C14 streams for 12-hour wear claims.
- Skin Care:Waterless cleansers and barrier creams integrate light fractions to replace cyclopentasiloxane. Chinese domestic brands under GB standard compliance drive volume in this segment.
- Hair Care:Conditioner and serum applications are climbing the fastest as cyclic silicone phase-outs accelerate.
- Fragrance:Fine fragrance houses specify ultra-light grades for rapid top-note diffusion without ethanol dominance.
Skin Care captures current volume leadership; Hair Care posts the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects where formulation expertise concentrates versus where finished goods reach end consumers.
- Online Retail:E-commerce platforms aggregate direct-to-consumer cosmetic sales, with Alibaba and Amazon hosting isoparaffin-containing product listings from mid-tier brands.
- Specialty Stores:Sephora and Ulta Beauty locations stock premium isoparaffin-based formulations, offering tactile sampling that validates spreadability claims.
- Supermarkets:Mass-market skin care lines with isoparaffin carriers reach price-sensitive consumers through Target and Carrefour shelf placement.
- Direct Sales:Amway and Mary Kay representatives distribute professional-grade isoparaffin hair treatments through consultant networks.
Specialty Stores dominate premium placement; Online Retail gains share fastest in post-pandemic purchasing habits.
Customer Type:
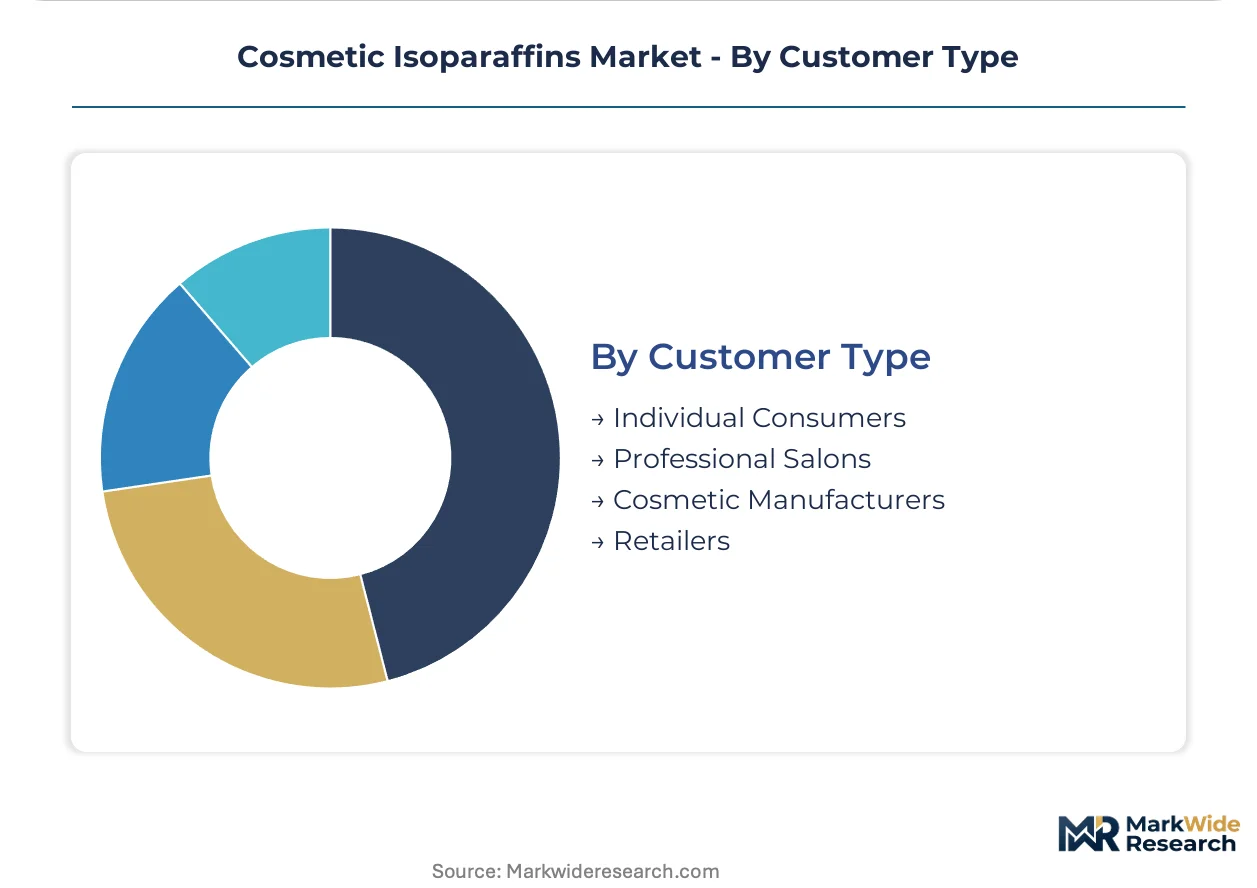
Buyer segmentation distinguishes between formulation-scale procurement and finished goods consumption.
- Individual Consumers:End users purchase isoparaffin-containing products based on texture preference and silicone-free labeling, with limited awareness of specific hydrocarbon chemistry.
- Professional Salons:Hairdressing establishments in Seoul and New York specify bulk isoparaffin conditioning treatments for in-salon application.
- Cosmetic Manufacturers:L'Oréal, Estée Lauder, and Amorepacific negotiate direct supply contracts with ExxonMobil and Idemitsu for pharmaceutical-grade isoparaffin streams.
- Retailers:Private label buyers at CVS and Boots formulate house-brand isoparaffin products through toll manufacturing arrangements.
Cosmetic Manufacturers control upstream volume commitments; Professional Salons expand fastest as salon-exclusive lines proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors procurement intensity for cosmetic isoparaffins, with the capital region's K-beauty manufacturing cluster generating concentrated demand for ultra-low aromatic solvents. Formulation centers in Paris and New York negotiate direct supply contracts with integrated refiners. Regulatory divergence across jurisdictions fragments purity certification requirements.
South Korea
Amorepacific and LG Household & Health Care drive isoparaffin procurement for waterless serum textures and long-wear makeup. MFDS cosmetic ingredient guidelines mandate sub-10 ppm aromatic content for leave-on products. The Seoul Capital Area concentrates over 70 percent of national cosmetic manufacturing output.
United States
Estée Lauder and L'Oréal USA specify pharmaceutical-grade C12-C14 streams for 12-hour wear claims in prestige makeup. EPA TSCA Section 5 premanufacture notifications govern new isoparaffin introductions. New Jersey's chemical corridor hosts formulation R&D centers that source directly from Gulf Coast refiners.
Germany
Henkel and Beiersdorf accelerate reformulation programs substituting medium isoparaffins for cyclic silicones in hair conditioning. ECHA substance evaluation protocols demand extended toxicity datasets for C15+ fractions. The Cologne-Düsseldorf industrial zone anchors European cosmetic chemistry development.
China
Domestic brands under GB standard compliance drive volume in waterless cleanser and barrier cream segments. NMPA cosmetic raw material regulations tighten impurity thresholds for hydrocarbon solvents. The Yangtze River Delta manufacturing belt around Shanghai hosts toll production for multinational private labels.
France
LVMH and L'Oréal Luxury Division procure ultra-light isoparaffins for fine fragrance rapid dry-down formulations. ANSM enforces REACH-aligned polycyclic aromatic hydrocarbon limits through cosmetic product safety reporting. The Paris metropolitan area concentrates global fragrance house formulation expertise.
Cosmetic Isoparaffins Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity certification tiers, with pharmaceutical-grade supply commanding substantial price premiums over technical-grade alternatives. The vendor base stratifies between integrated refiners with catalytic reforming assets and specialty chemical houses focusing on bio-based alkane alternatives. Two archetypes dominate: upstream-integrated energy majors leveraging feedstock control, and downstream-specialized ingredient suppliers competing on carbon intensity metrics. Capacity expansion and direct sourcing contract negotiation constitute the primary competitive moves reshaping channel relationships.
Within the integrated refiner archetype, ExxonMobil Chemical Company and INEOS Group Limited occupy positions anchored by captive naphtha cracking and Fischer-Tropsch synthesis capabilities. Croda International Plc exemplifies the bio-based alternative tier, competing on lifecycle carbon metrics rather than feedstock scale. Lanxess AG represents the high-purity specialization segment, with C13-C14 fractions targeting sensitive-skin dermatological applications. These three anchors illustrate how competitive positioning fragments across upstream control, sustainability certification, and formulation-specific technical service.
| Leading Market Players |
|---|
| Lanxess AG |
| The Innovation Company |
| Croda International Plc |
| Nihon Koken Kogyo Co., Ltd. |
| Rita Corporation |
| INEOS Group Limited |
| Presperse Corporation |
| ExxonMobil Chemical Company |
| Elementis PLC |
| Others |
Pricing and Supply Chain Analysis
EU REACH sub-10 ppm aromatic mandates are compressing acceptable supplier pools and forcing cosmetic formulators toward pharmaceutical-grade isoparaffin streams that command substantial premiums over technical-grade alternatives. This specification squeeze concentrates procurement power among integrated refiners with catalytic reforming assets while fragmenting price discovery across certification tiers.
Pricing Analysis
Pharmaceutical-grade purity certification anchors value-based pricing, with C13-C14 fractions for sensitive-skin applications and ultra-light C8-C9 grades for fragrance dry-down profiles commanding the widest spreads over standard cosmetic grades. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-certified streams from industrial cosmetic grades and bulk technical alternatives. Cost compression in standard cosmetic grades is intensifying because Korean and Chinese manufacturers are consolidating volume commitments around direct refinery contracts. Private label retailers at CVS and Boots exhibit the highest price sensitivity, while L'Oréal and Estée Lauder procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
China's GB standard alignment requirements and South Korea's MFDS cosmetic ingredient guidelines are reshaping sourcing patterns toward domestic toll manufacturers with verified analytical capabilities. Supply concentrates in the United States, Germany, and South Korea, where integrated refiners with Fischer-Tropsch synthesis or catalytic reforming assets anchor production. Feedstock economics draw from naphtha cracking margins and natural gas liquid pricing, with catalytic reformer yields and hydrogen consumption anchoring variable cost structures. Single-source vulnerability runs through pharmaceutical-grade capacity concentration among ExxonMobil, INEOS, and Idemitsu. Distribution runs through direct supply contracts between fragrance houses and refiners, displacing traditional chemical distributor intermediaries in Paris and New York formulation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade isoparaffin capacity scarcity among integrated refiners is propping pricing power and extending contract duration premiums. This supply-constrained structure favors incumbents with captive feedstock and certification infrastructure.
For Market Incumbents: Deepen backward integration into naphtha cracking and catalytic reforming assets to secure feedstock cost control against volatile natural gas liquid pricing. Expand high-purity C13-C14 fractionation capacity in the Cologne-Düsseldorf industrial zone to capture German hair care reformulation demand as cyclic silicone phase-outs accelerate. Defend margin position by locking multi-year direct supply contracts with Seoul-based K-beauty manufacturers before bio-based alkane alternatives achieve cost parity. For New Entrants and Emerging Players: E-commerce direct procurement platforms offer the most penetrable route for mid-tier isoparaffin grades serving Chinese domestic brands under GB standard compliance. Target waterless cleanser and barrier cream segments where formulation complexity remains lower than long-wear makeup or fine fragrance applications. Pursue toll manufacturing partnerships with Yangtze River Delta producers to bypass capital-intensive refinery infrastructure while building analytical verification capabilities. For Investors and Strategic Acquirers: The window for entry favors bio-based alkane specialists with sugar-derived feedstock technology and Scope 3 carbon accounting integration. Long-term viability hinges on certification infrastructure that bridges fossil and renewable feedstock streams without reformulation disruption for cosmetic manufacturers. Watch ECHA substance evaluation outcomes for C15+ fractions in leave-on products as the critical regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalytic Reforming | Captive naphtha processing secures pharmaceutical-grade yield control against feedstock volatility. |
| Bio-Based Alkane Certification Investment | Croda's sugar-derived routes demonstrate carbon intensity metrics that command premium positioning. |
| Direct Supply Contract Negotiation | L'Oréal and Estée Lauder procurement teams are consolidating volume commitments with integrated producers. |
| High-Purity C13-C14 Fractionation Expansion | German hair care reformulation under EU REACH creates specialized demand for sensitive-skin grades. |
| Analytical Verification Infrastructure Buildout | ANSM and ECHA enforcement of polycyclic aromatic hydrocarbon limits requires certified testing capabilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among cosmetic formulation chemists, refinery technical service directors, procurement leads at K-beauty manufacturers, fragrance house supply chain managers, and regulatory affairs specialists at ingredient suppliers. Secondary sources included ECHA substance evaluation protocols, EPA TSCA Section 5 premanufacture notifications, MFDS cosmetic ingredient guidelines, and China GB standards for cosmetic raw materials. Bottom-up volume modeling triangulated against top-down value estimates derived from refinery capacity disclosures and direct sourcing contract values.
Data-stream reconciliation across production volume, trade flows, and end-use consumption patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled included carbon chain length tier, application category, purity certification level, and regional manufacturing cluster. CAGRs were derived from trend extrapolation of reformulation timelines, regulatory phase-in schedules, and silicone substitution elasticities. Industry-specific forecast inputs incorporated K-beauty export growth trajectories and EU REACH authorization timelines for mineral oil derivatives.
The model holds under stable regulatory enforcement intensity and continued silicone substitution momentum; deviation in bio-based alkane cost reduction speed or ECHA toxicity dataset requirements for C15+ fractions would shift volume projections. Forecasts reflect documented assumptions regarding reformulation cycle duration and certification investment lag times. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
North America Cosmeceuticals Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Anti-Wrinkle Products Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
Methylisothiazolinone Market
Cosmetic Chemicals
Organic Cosmetic Ingredients Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market