
 Anti-Aging Products Market | 2026-2036
Anti-Aging Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Products Market Intelligence
Clinical-grade peptide concentration is redrawing competitive boundaries in anti-aging formulations. L'Oréal S.A. leverages its dermatological research network to anchor premium positioning in European pharmacies. Estée Lauder Companies Inc. sustains brand equity through controlled distribution in travel retail channels. Shiseido Company, Limited competes on fermentation-derived ingredient narratives tied to Japanese manufacturing heritage.
Anti-aging products comprise topical and injectable formulations designed to reduce visible signs of skin aging through collagen stimulation, cellular renewal, or barrier repair, typically incorporating active concentrations between 0.3% and 2% retinol or equivalent peptide complexes for epidermal penetration. Serums command the highest margin pools due to concentrated actives and premium positioning, while skincare application dominates volume as consumers integrate retinol and hyaluronic acid regimens into daily routines. Peptide ingredient research is accelerating fastest among biotechnology suppliers seeking alternatives to retinol tolerability concerns.
FDA oversees cosmeceutical claim substantiation in the United States, while the EU Cosmetics Regulation mandates safety assessments through ECHA-notified bodies before CE-marked market entry. South Korea's MFDS fast-tracks functional cosmetics approval, creating regulatory arbitrage for brands testing novel delivery systems. Stakeholders must monitor evolving ingredient ban lists and substantiation requirements across jurisdictions to preserve formulation pipelines and market access.
Market Dynamics
Peptide-based formulation science is compressing product development cycles across the anti-aging sector, forcing incumbents to rebuild R&D pipelines around biotech-derived actives rather than traditional retinol matrices.
Growth Catalysts
- MFDS fast-track pathways:South Korea's functional cosmetics approval system accelerates novel delivery system commercialization, attracting brands seeking regulatory arbitrage for liposome-encapsulated peptide launches.
- Dermatology clinic expansion:Professional treatment menus now incorporate clinical-grade peptide protocols, creating institutional demand pull for concentrated active formulations previously confined to prescription channels.
- Fermentation biotechnology:Japanese manufacturing heritage in microbial cultivation yields proprietary postbiotic extracts, differentiating supply chains through ingredient origin narratives rather than synthetic chemistry.
Market Restraints
- Retinol supply concentration:Three specialty chemical producers control pharmaceutical-grade retinol precursor supply, exposing formulators to input cost volatility and allocation constraints during harvest cycles.
- ECHA disclosure mandates:REACH ingredient registry requirements impose documentation burdens on peptide suppliers, extending safety assessment timelines and freezing formulation pipelines for 12-18 months.
- Hyaluronic acid commoditization:Fermentation-derived hyaluronic acid from Chinese biotech facilities has collapsed pricing for basic molecular weights, eroding margin pools in mass-market moisturizers.
Strategic Opportunities
- Men's grooming underpenetration:Male-specific anti-aging positioning remains nascent in Germany and France, where pharmacy channel credibility transfers more readily to gender-neutral clinical branding.
- Microbiome-balancing actives:Convergence between dermatology and gut-health research creates white space for prebiotic topical formulations targeting barrier dysfunction in sensitive skin segments.
- Travel retail recovery:Asia-Pacific airport duty-free networks are rebuilding premium beauty floors, offering controlled distribution environments for concentrated serum launches at price points insulating margin structure.
Industry Challenges
- Peptide synthesis expertise scarcity:Solid-phase peptide synthesis requires chemists with GMP biologics experience, a talent pool concentrated among CMOs serving pharmaceutical rather than cosmetic clients.
- Substantiation documentation burden:FDA cosmeceutical claim review demands clinical endpoint data that smaller brands cannot generate without alliance with dermatology research networks.
- Legacy ERP integration:Batch-level ingredient traceability requirements under EU Cosmetics Regulation force reformulation of quality management systems originally designed for commodity chemical tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Products Market |
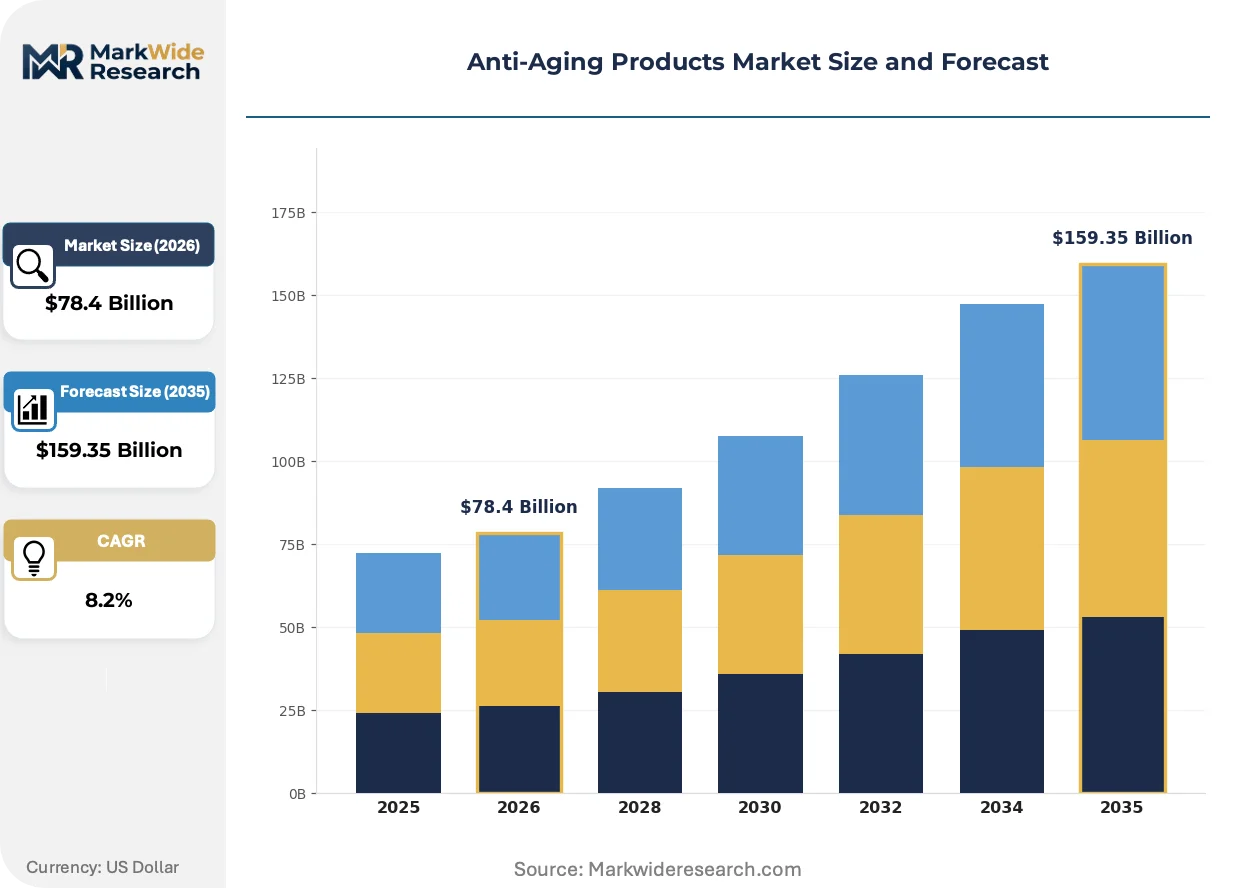
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $159.35 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Oils Application: Skincare, Makeup, Haircare, Eye Care Ingredient: Retinol, Peptides, Hyaluronic Acid, Antioxidants Customer Type: Men, Women, Professionals, Seniors |
| Companies Covered | L'Oréal S.A., Procter & Gamble Company, Unilever PLC, Estée Lauder Companies Inc., Beiersdorf AG, Shiseido Company, Limited, Johnson & Johnson, Avon Products, Inc., Coty Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Products Market Strategic Shifts & Innovations
Biofermentation-derived alternatives are actively displacing petrochemical feedstocks in active ingredient supply chains, while regulatory disclosure mandates and channel restructuring simultaneously reshape competitive positioning.
Bakuchiol extract from Psoralea corylifolia seeds functions as a retinoid-mimetic with reduced photosensitivity and irritation profiles. Premium serum formulators in Seoul's beauty-tech cluster have adopted bakuchiol at 0.5-2% concentrations since 2022. This botanical active is supplanting retinol in pregnancy-safe and sensitive-skin product lines, compressing market share for traditional vitamin A derivatives in dermocosmetic channels.
REACH Annex amendments now mandate disclosure of nanomaterial presence in cosmetic formulations above specific threshold concentrations. European peptide suppliers must submit expanded safety dossiers to ECHA-notified bodies before CE-marked market entry. Professional treatment brands with existing dermatology clinic relationships are absorbing compliance costs more readily than direct-to-consumer entrants lacking institutional credibility.
Subscription-based replenishment models now dominate serum category customer acquisition in North American e-commerce channels. Traditional department store beauty counters lose traffic to tele-dermatology platforms bundling diagnostic imaging with personalized regimen curation. This channel rotation is most visible in California and New York, where telehealth regulatory clarity enabled hybrid medical-aesthetic service integration faster than jurisdictions with restrictive scope-of-practice definitions.
Anti-Aging Products Market Segmentation
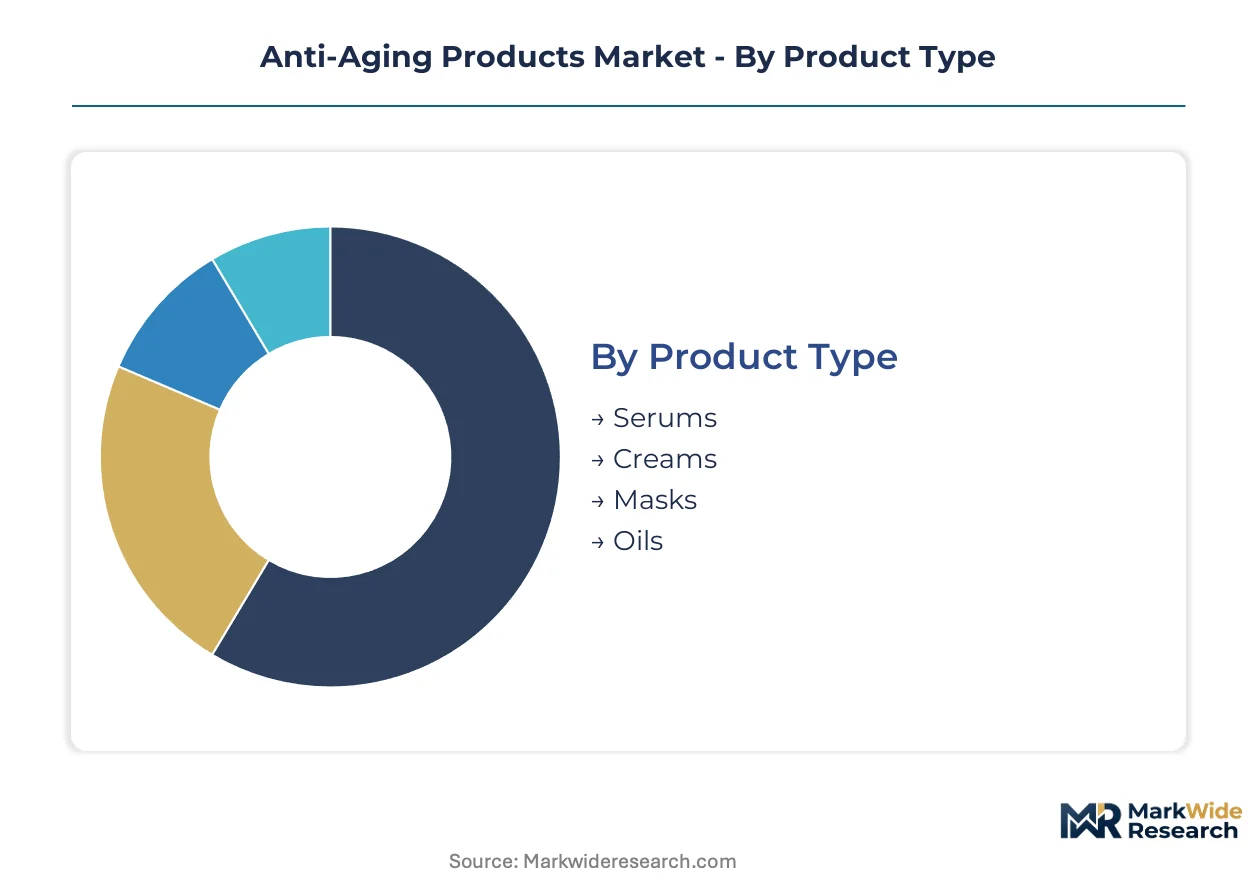
Anti-aging product segmentation reveals distinct channel affinities that shape margin architecture. Concentrated serum formulations command premium pharmacy and clinic placement, while mass-market creams flow through grocery and e-commerce replenishment models.
Product Type:
Channel placement varies sharply across formulation formats, with pharmacy networks filtering for clinical-grade actives and department stores optimizing for sensorial experience.
- Serums:Water-based formulations carrying 0.3-2% retinol or peptide complexes achieve deepest epidermal penetration. Demand clusters in Seoul's beauty-tech cluster and German pharmacy channels where clinical credibility justifies 40-60% price premiums over creams. L'Oréal's dermatological network anchors European distribution.
- Creams:Emulsion-based vehicles dominate volume through daily regimen integration. Mass-market moisturizers face hyaluronic acid commoditization pressure from Chinese fermentation facilities, compressing margins in basic molecular weight tiers.
- Masks:Sheet and wash-off formats concentrate in South Korean e-commerce and travel retail recovery channels.
- Oils:Facial oil serums occupy niche positioning in clean beauty and pregnancy-safe segments.
Creams dominate installed base through daily use frequency. Serums are where expansion concentrates as peptide research accelerates.
Application:
End-use concentration determines regulatory pathway complexity, with dermatology clinic protocols demanding stricter substantiation than cosmetic positioning.
- Skincare:Daily topical regimens incorporating retinol, hyaluronic acid, and emerging bakuchiol alternatives constitute the volume core. FDA cosmeceutical claim oversight and EU Cosmetics Regulation safety assessments shape formulation pipelines.
- Eye Care:Periorbital formulations command specialized clinical testing for tolerability. Peptide-based protocols from dermatology clinics create institutional demand pull for concentrated actives in this sensitive zone.
- Makeup:Anti-aging claims in color cosmetics face heightened substantiation requirements under MFDS fast-track and ECHA disclosure mandates.
- Haircare:Scalp and strand anti-aging remains underdeveloped relative to facial applications.
Skincare dominates installed base across all distribution tiers. Eye Care is climbing the fastest as peptide synthesis expertise migrates from pharmaceutical to cosmetic CMOs.
Ingredient:
Supply chain configuration and biotech R&D intensity create divergent margin profiles across active categories.
- Peptides:Solid-phase synthesis yields collagen-stimulating signal molecules with superior tolerability versus retinol. Biotechnology suppliers in Seoul and Osaka accelerate fermentation-derived alternatives as REACH Annex amendments extend safety assessment timelines.
- Retinol:Pharmaceutical-grade precursor supply concentrates among three specialty chemical producers, exposing formulators to harvest-cycle allocation constraints and input cost volatility.
- Hyaluronic Acid:Fermentation-derived grades from Chinese biotech facilities have collapsed pricing for basic molecular weights.
- Antioxidants:Botanical extracts and synthetic variants compete on origin narratives and stability profiles.
Retinol dominates installed base through decades of clinical documentation. Peptides are gaining share fastest as tolerability concerns reshape dermatologist recommendations.
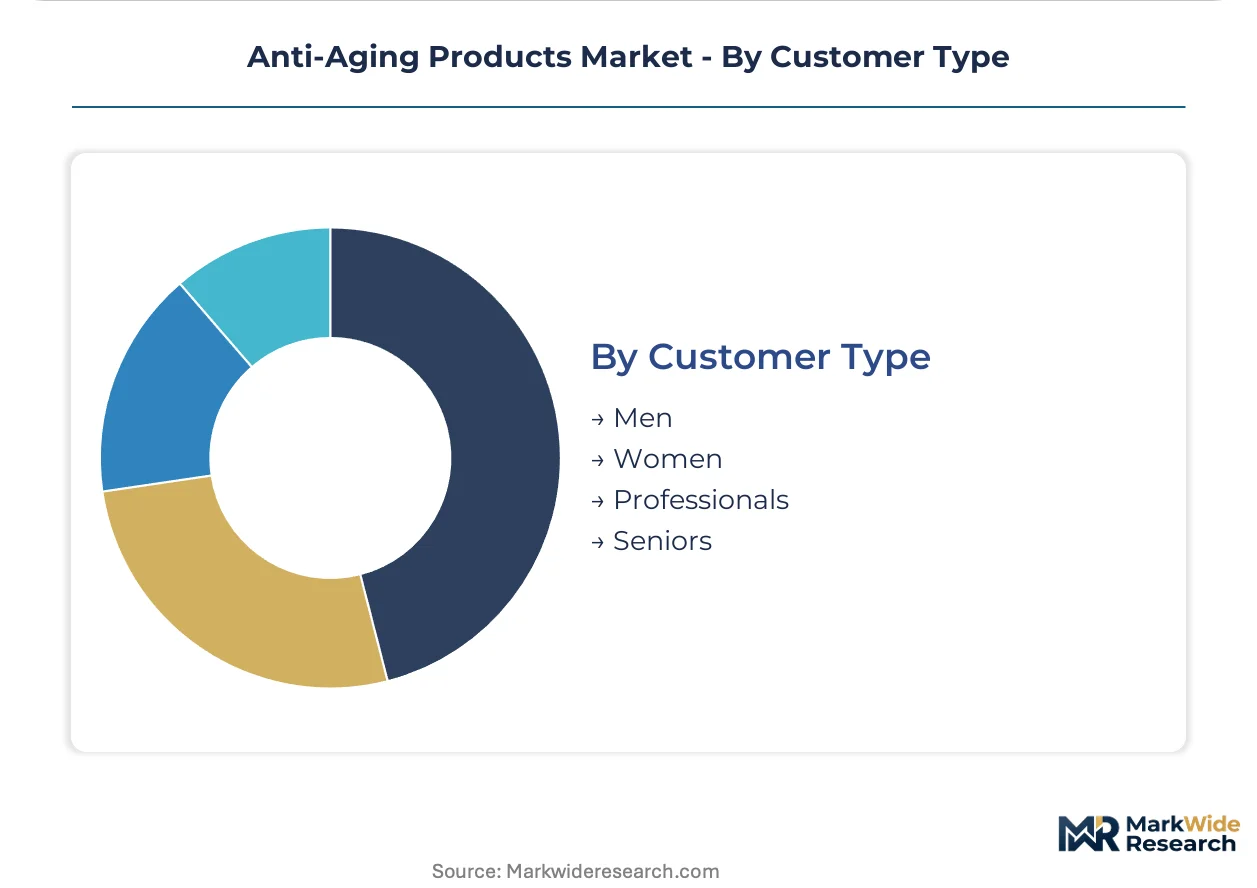
Customer Type:
Demographic targeting precision determines channel efficiency, with gender-specific positioning still nascent in key European markets.
- Women:Core demographic driving serum category premiumization and subscription replenishment model adoption in North American e-commerce.
- Professionals:Time-constrained users favor streamlined clinic-dispensed protocols over multi-step retail regimens.
- Men:Male-specific anti-aging positioning remains underpenetrated in Germany and France where pharmacy credibility transfers to gender-neutral clinical branding.
- Seniors:Mature skin formulations with barrier repair focus concentrate in dermatology clinic and tele-dermatology channels.
Women dominate installed base across all product formats. Men represent the steepest expansion trajectory as grooming category boundaries blur.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three specialty chemical producers control pharmaceutical-grade retinol precursor supply, concentrating upstream input sourcing in specific national territories. Demand formation clusters in jurisdictions with advanced dermatology infrastructure and accelerated regulatory pathways for novel delivery systems.
United States
FDA cosmeceutical claim oversight drives clinical endpoint substantiation requirements for peptide-based formulations. The agency's review timelines shape product launch sequencing for brands seeking premium pharmacy placement. California and New York telehealth regulatory clarity enables hybrid medical-aesthetic service integration faster than restrictive jurisdictions.
Germany
ECHA disclosure mandates under REACH Annex amendments extend safety assessment timelines for peptide suppliers entering CE-marked markets. Pharmacy channel credibility transfers readily to clinical-grade positioning, supporting premium serum distribution. Berlin-Brandenburg hosts dermatology research networks that generate substantiation data for FDA-aligned claim strategies.
South Korea
MFDS fast-track pathways for functional cosmetics accelerate liposome-encapsulated peptide commercialization. Seoul's beauty-tech cluster compresses formulation innovation cycles through proximity between biotechnology suppliers and contract manufacturers. Domestic demand concentrates in concentrated actives with tolerability advantages over traditional retinol matrices.
Japan
METI industrial policy supports fermentation biotechnology infrastructure yielding proprietary postbiotic extracts. Osaka-based microbial cultivation facilities differentiate supply chains through ingredient origin narratives tied to manufacturing heritage. PMDA consultation pathways guide brands navigating between cosmetic and quasi-drug classification boundaries.
France
ANSM oversight of cosmetic safety assessments intersects with CNIL data protection requirements for personalized skincare algorithms. Île-de-France hosts headquarters of multinational dermatological research networks that anchor European premium positioning. Pharmacy regulatory culture favors clinical credibility over mass-market sensorial marketing.
Anti-Aging Products Market Key Industry Players
Concentration sits with multinational conglomerates possessing integrated dermatological research networks and controlled distribution infrastructure. The vendor base spans three tiers: scale-driven mass-market formulators, premium-tier clinical positioning specialists, and biotechnology-derived active suppliers. Strategic moves center on peptide synthesis capability acquisition and travel retail channel reconstruction post-pandemic.
Among French-headquartered conglomerates, L'Oréal S.A. exemplifies the dermatological-network archetype through pharmacy channel anchoring. Estée Lauder Companies Inc. represents premium-tier positioning sustained through controlled travel retail distribution. Shiseido Company, Limited occupies the fermentation-heritage specialization vector, leveraging Japanese microbial cultivation narratives to differentiate peptide and postbiotic supply chains.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble Company |
| Unilever PLC |
| Estée Lauder Companies Inc. |
| Beiersdorf AG |
| Shiseido Company, Limited |
| Johnson & Johnson |
| Avon Products, Inc. |
| Coty Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for pharmaceutical-grade retinol precoders lock in supply access and price visibility for formulators navigating harvest-cycle allocation constraints from the three dominant specialty chemical producers. These contracts insulate premium serum manufacturers from spot-market volatility while compressing margins for mass-market cream producers exposed to hyaluronic acid commoditization from Chinese fermentation facilities.
Pricing Analysis
EU Cosmetics Regulation dictates the pricing tier structure across European pharmacy channels, where REACH Annex compliance costs filter out direct-to-consumer entrants lacking dermatology clinic relationships. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade peptide serums from mass-market retinol creams and basic hyaluronic acid moisturizers. Cost compression in the economy tier is intensifying because Chinese biotech facilities have collapsed pricing for fermentation-derived basic molecular weights. Professional treatment protocols command the least price sensitivity due to institutional demand pull, while grocery-channel replenishment models face the highest buyer price sensitivity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes intermittently disrupt inbound logistics for Seoul-sourced liposome-encapsulated peptide actives. Supply concentrates in South Korea, Japan, and Germany, with fermentation biotechnology infrastructure anchored in Osaka and solid-phase peptide synthesis expertise clustering in Berlin-Brandenburg. Raw material dependencies include Psoralea corylifolia seed extracts for bakuchiol alternatives, retinol precursors from controlled harvest cycles, and microbial cultivation feedstocks for postbiotic development. Single-source vulnerability sits with the three pharmaceutical-grade retinol precursor suppliers. Distribution runs through pharmacy networks for clinical-grade positioning, travel retail for premium serum launches, and e-commerce subscription models for North American replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated dermatology clinic networks and tele-dermatology platforms that now control patient regimen curation, fragmenting traditional retail channel influence.
For Market Incumbents: Secure peptide synthesis capability through alliance with pharmaceutical CMOs possessing GMP biologics expertise, as talent scarcity threatens formulation pipeline continuity. Anchor pharmacy channel positioning through investment in dermatology research network substantiation data that satisfies FDA cosmeceutical claim requirements and insulates against direct-to-consumer entrants lacking clinical credibility. For New Entrants and Emerging Players: Tele-dermatology platform integration gaps where incumbents under-serve create white space for hybrid diagnostic-imaging and personalized regimen curation services in California and New York regulatory environments. Men's grooming segments in Germany and France offer the most penetrable geography due to pharmacy channel credibility transfer to gender-neutral clinical branding. Go-to-market execution should prioritize microbiome-balancing prebiotic formulations targeting barrier dysfunction in sensitive skin segments. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-derived active suppliers with fermentation heritage narratives and existing ECHA-notified body relationships that compress REACH compliance timelines. Long-term viability over the projection horizon rests on acquisition targets possessing solid-phase peptide synthesis infrastructure and dermatology clinic distribution anchors. Watch for MFDS fast-track pathway expansion signals as inflection indicators for novel delivery system commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Capability Acquisition | GMP biologics expertise from pharmaceutical CMOs secures formulation pipeline continuity against talent scarcity. |
| Dermatology Research Network Expansion | Substantiation data generation satisfies FDA cosmeceutical claim requirements and anchors pharmacy channel credibility. |
| Tele-Dermatology Platform Partnership | Hybrid diagnostic-imaging integration captures patient regimen curation control from traditional retail channels. |
| Men's Grooming Line Launch | Gender-neutral clinical branding leverages pharmacy channel credibility in underpenetrated German and French markets. |
| Microbiome-Active Formulation Development | Prebiotic topical development targets barrier dysfunction white space in sensitive skin segments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA cosmeceutical claim filings, ECHA REACH Annex amendments, and MFDS functional cosmetics approval databases to validate market sizing and growth trajectory assumptions. Primary interviews engaged dermatology clinic protocol directors, peptide synthesis CMO technical leads, pharmacy channel category managers, and tele-dermatology platform operators across Seoul, Berlin-Brandenburg, and California clusters. Secondary validation drew from EU Cosmetics Regulation safety assessment disclosures, fermentation biotechnology patent filings, and travel retail duty-free network reconstruction data. Bottom-up product-format volume builds triangulated against top-down regional demand aggregation.
Segmentation dimensions modeled span product type, application, ingredient category, and customer archetype across the analysis window. Analytical framework approach projects value expansion through independent assessment of peptide research acceleration, regulatory pathway complexity, and channel restructuring dynamics. CAGRs were derived from regression analysis of historical approval velocity and substantiation cost trajectories. Industry-specific forecast inputs include MFDS fast-track pathway utilization rates and ECHA safety assessment timeline extensions under REACH Annex amendments.
Underlying assumptions cover sustained dermatology clinic network expansion, stable retinol precursor harvest-cycle allocation, and continued hyaluronic acid fermentation capacity addition in China, with deviation risk concentrated in peptide synthesis chemist talent pool migration and REACH disclosure mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Sodium Methylparaben Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Hair Lightening Product Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Sun Protection Products Market
Cosmetic Chemicals
Anti-Acne Serum Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Asia Pacific Cosmetic Preservatives Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market