
 Cosmetic UV Absorbers Market | 2026-2036
Cosmetic UV Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic UV Absorbers Market Outlook
ISO 24443 sunscreen efficacy testing is redrawing competitive boundaries for cosmetic UV absorber suppliers. BASF SE leverages its integrated photostability labs to sustain leadership in benzotriazole chemistry across European and Asian markets. Clariant AG anchors its position through specialty-grade triazine derivatives that meet Japan's stringent QDMS standards for sensitive-skin formulations.
Cosmetic UV absorbers comprise organic molecules such as avobenzone and octocrylene, inorganic metal oxides like zinc oxide and titanium dioxide in nano-graded dispersions, and hybrid systems combining both mechanisms to achieve broad-spectrum protection with SPF ratings exceeding 50. Organic absorbers dominate current volume due to established formulation compatibility and transparent aesthetic finish, though inorganic filters command premium positioning in reef-safe and pediatric segments where mineral-only claims support higher margin pools. Hybrid solutions represent the fastest-growing structural category as brands seek to balance photostability, sensorial elegance, and regulatory compliance across multiple jurisdictions.
REACH in Europe, FDA sunscreen monograph requirements in the United States, and China's NMPA cosmetic ingredient registration rules collectively determine which UV filter molecules achieve commercial scale and geographic market access. Formulators now face divergent approved-substance lists that fragment global product portfolios and elevate regional compliance costs. Stakeholders must monitor pending FDA monograph updates and NMPA expanded ingredient catalogs to anticipate which filter technologies will unlock or lose major market entry over the next regulatory cycle.
Market Dynamics
Formulators now confront a fundamental tension between photostability mandates from ISO 24443 and the aesthetic demands of dermocosmetic brands seeking transparent, non-whitening mineral protection. This structural pressure is compressing margins for legacy organic filter suppliers while rewarding hybrid system innovators.
Growth Catalysts
- ISO 24443 Compliance:Photostability testing mandates in Europe and Asia are forcing reformulation cycles that favor suppliers with integrated efficacy laboratories and validated filter databases.
- Pediatric and Sensitive-Skin Segments:Mineral-only claims in reef-safe and infant sun care categories are creating premium positioning opportunities for zinc oxide and titanium dioxide nano-dispersion specialists.
- South Korea:K-beauty dermocosmetic exports are accelerating demand for triazine derivatives that satisfy both domestic MFDS standards and destination-market registration requirements.
Market Restraints
- Input Cost Volatility:Benzotriazole precursor chemicals face petrochemical feedstock price swings that compress formulator margins during contract renewal cycles.
- Regulatory Fragmentation:Divergent approved-substance lists between FDA monograph requirements, REACH annexes, and NMPA cosmetic ingredient catalogs force redundant toxicology dossiers and delay geographic expansion.
- Technical Limitation:Avobenzone photodegradation remains unresolved without octocrylene co-formulation, constraining clean-label claims in natural-positioned product lines.
Strategic Opportunities
- India:BIS cosmetic safety standards are expanding to include UV filter concentration limits, creating first-mover advantage for suppliers with pre-validated ingredient portfolios.
- Blue Light Protection:Visible-light filter integration into daily wear skincare represents unclaimed white space between traditional sun care and anti-pollution positioning.
- EU Green Deal:Biobased feedstock incentives are accelerating research into fermentation-derived UV absorber precursors that satisfy renewable content thresholds.
Industry Challenges
- Photostability Chemist Scarcity:Formulation science programs produce insufficient specialists trained in both sunscreen efficacy testing and cosmetic sensorial evaluation.
- Regulatory Dossier Timelines:NMPA expanded ingredient catalog applications require multi-year toxicology investment with uncertain approval outcomes.
- Legacy ERP Integration:Batch record systems designed for commodity chemicals struggle to capture lot-level photostability data demanded by ISO 24443 traceability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic UV Absorbers Market |
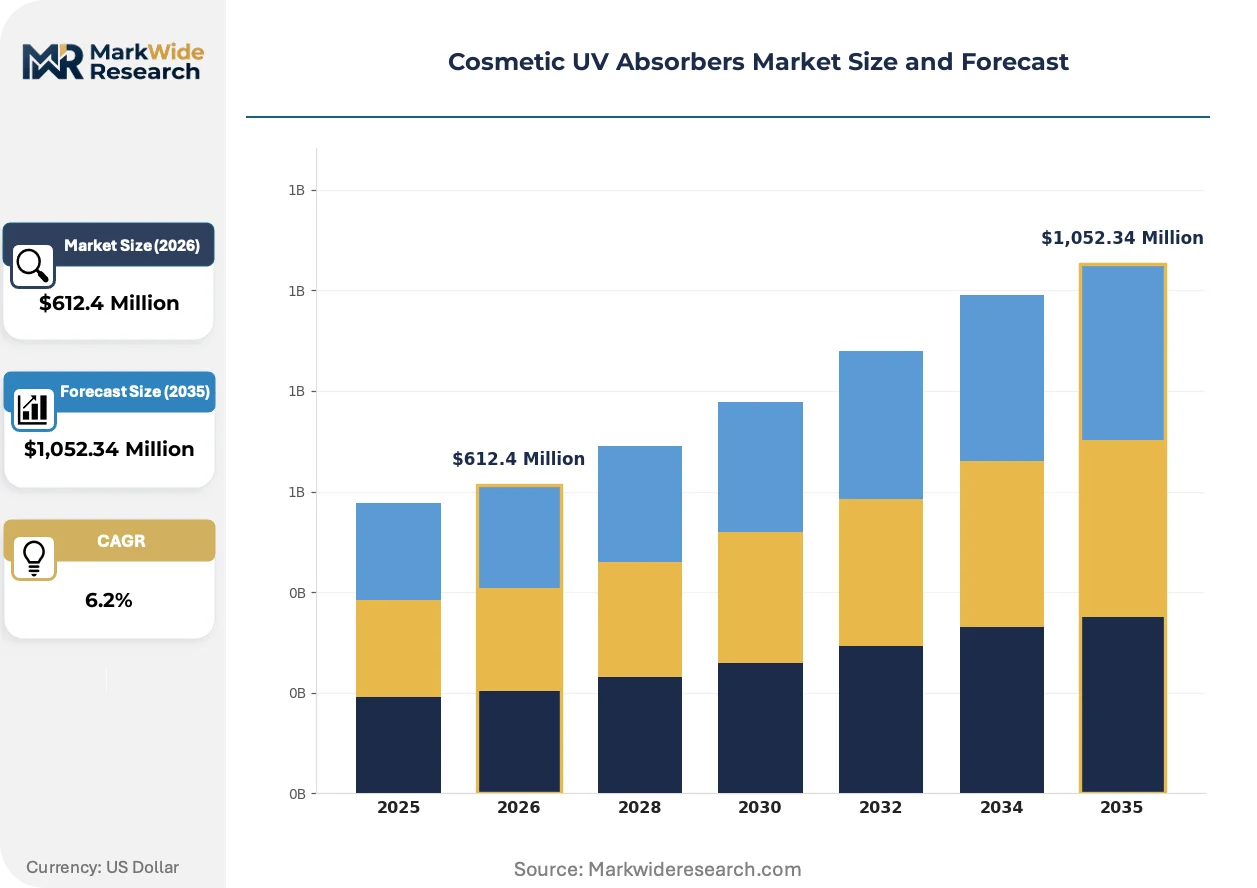
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,052.34 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Absorbers, Inorganic Filters, Hybrid Solutions, Combination Products Formulation Type: Lotions, Creams, Gels, Sprays End User: Consumers, Professionals, Dermatologists, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | BASF SE, Clariant AG, SONGWON Industrial Co., Ltd., ADEKA Corporation, Everlight Chemical Industrial Corporation, Solvay S.A., Milliken Chemical, SABO S.p.A., Addivant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic UV Absorbers Market Strategic Shifts
Active ingredient architecture is splitting into parallel development tracks as mineral-only claims and hybrid performance targets diverge. Formulators must now maintain dual competence in organic photostabilization and nano-mineral dispersion engineering.
Encapsulation technology is bifurcating the UV absorber supply base into two distinct capability tiers. Premium dermocosmetic brands in Germany and South Korea are adopting shell-core microsphere systems that isolate photoreactive organic filters from skin contact. This technology is bifurcating supplier margins, compressing commodity filter prices while creating captive demand for proprietary encapsulation polymers.
REACH authorization procedures are tightening disclosure requirements for benzotriazole derivatives used in rinse-off formulations. ECHA's expanded safety data sheet mandates are forcing suppliers to commission new aquatic toxicity studies. Sun care brands targeting European distribution are responding by accelerating triazine derivative substitution programs.
Clean-label procurement is shortening supplier qualification cycles as brands demand third-party certifications before contract negotiation. Mass-market retailers in the United States are displacing traditional distributor relationships with direct sourcing platforms that audit manufacturing sites for reef-safe claim substantiation. This shift is most visible in California and Florida, where state-level ingredient restrictions exceed federal FDA monograph requirements.
Cosmetic UV Absorbers Market Segmentation
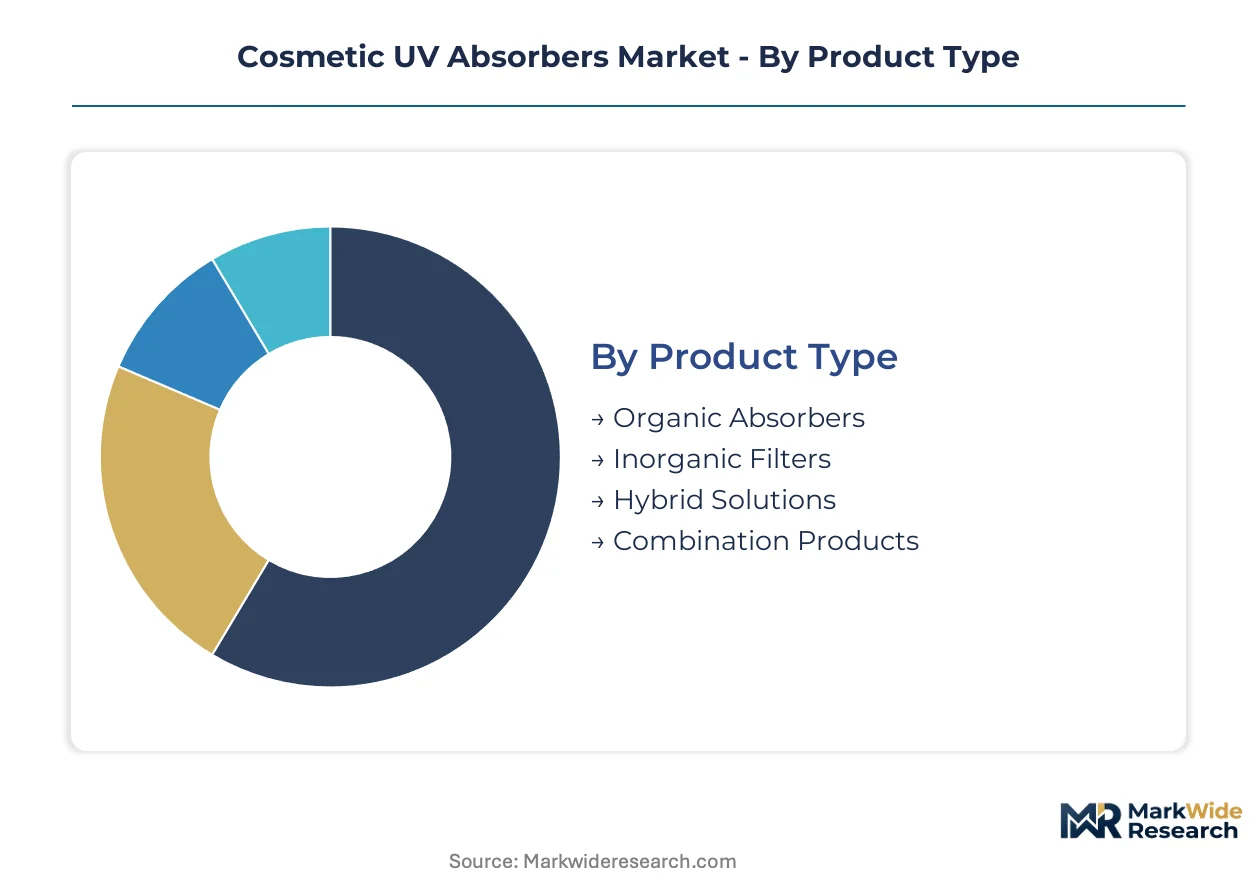
UV absorber procurement patterns diverge sharply between mass-market formulators seeking cost-optimized organic filters and premium dermocosmetic brands demanding validated mineral and hybrid systems. Segmentation clarity determines which suppliers capture volume contracts versus specialty margin pools.
Product Type:
Domestic production concentrates organic absorber supply in Germany and the United States, while inorganic filter manufacturing clusters in South Korea and Japan for export-led dermocosmetic demand.
- Organic Absorbers:Benzotriazole and dibenzoylmethane derivatives dominate current formulation volumes due to established photostabilization protocols and transparent aesthetic finish. European REACH compliance costs are compressing margins for commodity suppliers without integrated efficacy laboratories.
- Inorganic Filters:Nano-graded zinc oxide and titanium dioxide dispersions command premium positioning in reef-safe and pediatric segments where mineral-only claims support higher pricing tiers. South Korean MFDS standards for sensitive-skin formulations are accelerating technical specifications for particle size distribution.
- Hybrid Solutions:Systems combining organic photostability with mineral broad-spectrum protection are gaining share fastest among brands balancing sensorial elegance with regulatory compliance across multiple jurisdictions.
- Combination Products:Pre-blended filter kits reduce formulator R&D cycles for mid-tier brands lacking in-house photostability testing capabilities.
Organic absorbers command the established base. The steepest expansion runs through hybrid solutions.
Formulation Type:
Cost tier differentiation separates premium emulsion engineering from mass-market spray commoditization, with gel formats capturing mid-tier daily wear positioning.
- Lotions:Fluid emulsion systems dominate beach and sport sun care applications where water resistance testing under ISO 24443 protocols determines commercial viability. California and Florida state-level ingredient restrictions are forcing reformulation cycles for mass-market brands.
- Creams:Thicker emulsion bases anchor pediatric and sensitive-skin positioning where barrier function and mineral dispersion stability outweigh spreadability concerns. German dermocosmetic brands are specifying encapsulated organic filters within cream matrices.
- Gels:Silicone and water-based clear systems serve daily wear skincare integration where cosmetic elegance drives repurchase rates.
- Sprays:Aerosol and pump formats face regulatory pressure from EPA volatile organic compound limits and inhalation toxicity scrutiny.
Creams anchor premium positioning. Gels are climbing the fastest as daily wear skincare absorbs UV protection into multi-functional routines.
End User:
Customer type stratification reflects divergent purchasing authority between self-directed consumers and clinically mediated professional channels.
- Consumers:Mass-market purchasing decisions respond to SPF labeling claims and reef-safe certifications, with direct-to-consumer platforms displacing traditional retail relationships in the United States.
- Professionals:Spa and aesthetic clinic channels demand batch-validated photostability documentation that commodity suppliers struggle to provide.
- Dermatologists:Clinical recommendation authority in Germany and South Korea drives mineral-only prescription for post-procedure skin, creating captive demand for validated nano-dispersion suppliers.
- Pharmacies:European pharmacy channel consolidation favors suppliers with centralized distribution and multilingual regulatory dossiers.
Consumer volume dominates unit sales. Dermatologist channel expansion is gaining share fastest in premium mineral segments.
Distribution Channel:
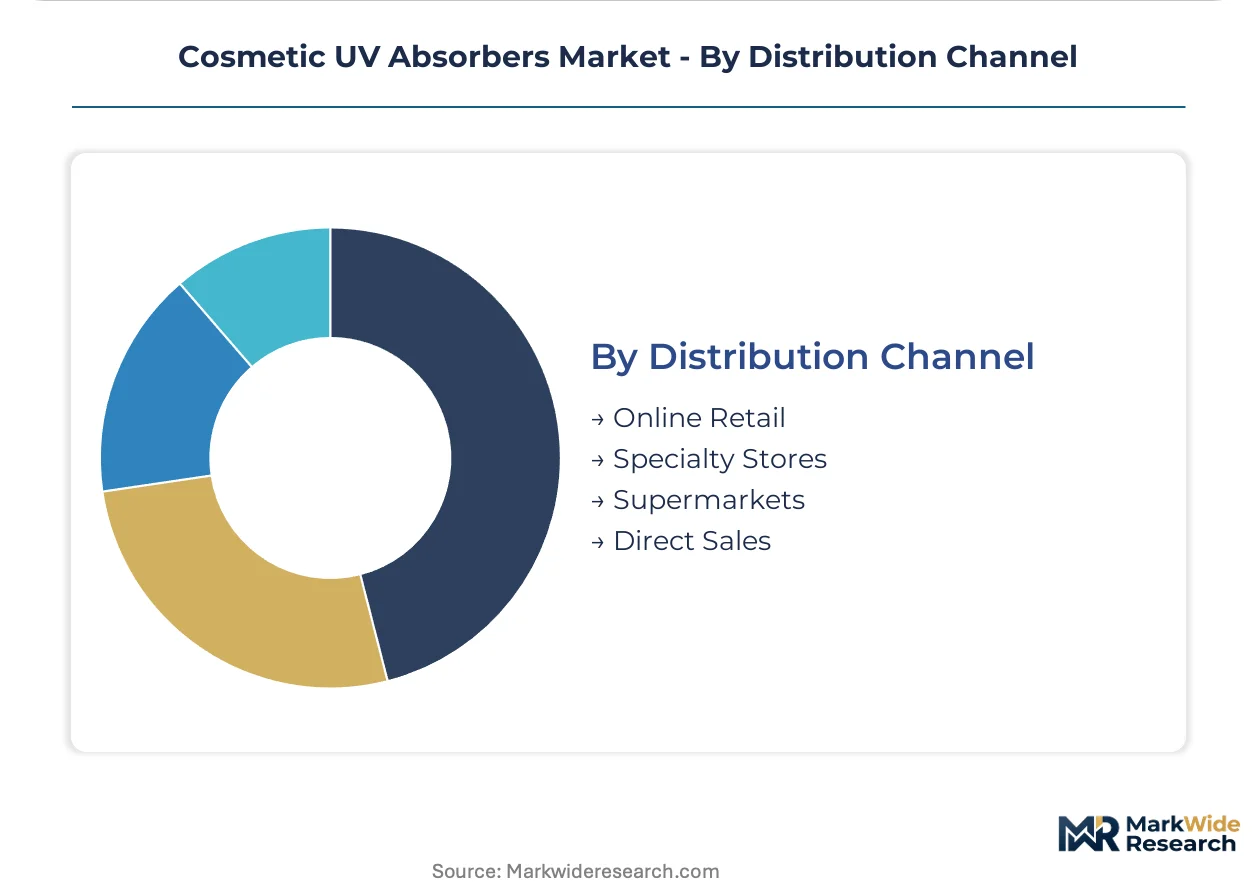
Supply concentration varies between platform-controlled online retail and relationship-dependent specialty store networks.
- Online Retail:Amazon and dedicated dermocosmetic platforms in South Korea are shortening supplier qualification cycles through algorithmic recommendation systems that prioritize third-party certification visibility.
- Specialty Stores:Sephora and Douglas-owned networks in Germany enforce clean-label procurement standards that filter out suppliers lacking EWG or equivalent verification.
- Supermarkets:Mass-market retail concentration in the United States demands price-competitive organic filter supply with minimal technical service requirements.
- Direct Sales:Amway and Rodan + Fields models sustain higher filter specification tolerance through consultant-mediated education.
Supermarkets command the established volume base. Online retail shows the steepest expansion trajectory as platform algorithms reshape discovery patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's dominance in cosmetic UV absorber formulation chemistry, while South Korea's Busan port anchors K-beauty export flows to dermocosmetic markets worldwide.
United States
California and Florida state-level ingredient restrictions exceed FDA monograph requirements, forcing reformulation cycles for mass-market sun care brands. The EPA's volatile organic compound limits on aerosol formats are compressing spray product margins. Miami-Dade and Orange County clusters concentrate contract manufacturing for reef-safe mineral-only lines targeting Caribbean tourism channels.
Germany
Dermocosmetic pharmacy channel consolidation favors suppliers with centralized distribution and multilingual regulatory dossiers. REACH authorization procedures are tightening disclosure requirements for benzotriazole derivatives in rinse-off formulations. The Ludwigshafen chemical complex maintains integrated photostability laboratories serving European formulation houses.
South Korea
K-beauty exports are accelerating demand for triazine derivatives that satisfy both domestic MFDS standards and destination-market registration requirements. Seoul Capital Area formulation houses are specifying encapsulated organic filters within cream matrices for sensitive-skin positioning. Busan-Ulsan industrial corridors concentrate nano-dispersion manufacturing for mineral-only pediatric segments.
China
NMPA cosmetic ingredient registration rules determine which UV filter molecules achieve commercial scale and geographic market access. The Yangtze River Delta formulation clusters are absorbing hybrid system demand from domestic dermocosmetic brands. Shanghai's port infrastructure supports import-dependent supply chains for specialty-grade organic absorbers.
India
BIS cosmetic safety standards are expanding to include UV filter concentration limits, creating first-mover advantage for suppliers with pre-validated ingredient portfolios. Maharashtra and Gujarat industrial zones are attracting toll manufacturing contracts from European brands seeking cost-optimized organic filter supply. Mumbai's financial infrastructure supports direct sourcing platform development displacing traditional distributor relationships.
Cosmetic UV Absorbers Market Competitive Environment
Listed leaders compete with private specialists across regulatory dossier capabilities and photostability testing infrastructure. The supplier base fragments across three capability tiers: integrated chemical conglomerates with in-house efficacy laboratories, mid-scale specialty houses focused on single-filter chemistry, and regional toll manufacturers serving cost-optimized mass-market formulators. Dominant competitive moves include strategic partnerships with encapsulation technology providers and backward integration into petrochemical feedstocks for benzotriazole precursors.
Among European-based chemical conglomerates, BASF SE and Clariant AG exemplify the integrated laboratory archetype, while SONGWON Industrial Co., Ltd. anchors the Asian specialty house tier. These three occupy positions that straddle regulatory compliance infrastructure and regional formulation proximity, representing the structural fault lines between REACH-mandated European supply and MFDS-calibrated Asian production.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| SONGWON Industrial Co., Ltd. |
| ADEKA Corporation |
| Everlight Chemical Industrial Corporation |
| Solvay S.A. |
| Milliken Chemical |
| SABO S.p.A. |
| Addivant |
| Others |
Value Chain & Pricing Dynamics
Triazine derivative substitution for benzotriazole chemistry in European rinse-off formulations is simultaneously relocating production gravity toward South Korean MFDS-certified facilities and compressing legacy supplier margins through redundant toxicology investment. This input transition rewards suppliers with pre-validated REACH dossiers while penalizing commodity producers lacking integrated efficacy laboratories.
Pricing Analysis
Certification level (ISO 24443-grade) creates the primary spread between premium dermocosmetic supply and mass-market commodity tiers. Three-tier pricing structure across premium, standard, and economy levels anchors contract negotiations, with photostability documentation and encapsulated filter systems commanding substantial premiums. Pricing pressure stems from petrochemical feedstock volatility in benzotriazole precursor supply, compressing formulator margins during contract renewal cycles. Mass-market retailers exhibit highest price sensitivity, while German pharmacy channels tolerate premium positioning for validated mineral dispersions.
Supply Chain Analysis
Strategic stockpile preferences dominate UV absorber procurement as formulators buffer against REACH authorization delays and NMPA registration uncertainty. Supply concentrates in Germany for organic filter synthesis, South Korea for nano-dispersion engineering, and Japan for specialty-grade triazine derivatives. Raw material dependencies rest on benzene derivatives, petrochemical feedstocks, and rare-earth mineral processing for titanium dioxide precursors. Single-source vulnerability in photostability chemist talent pools constrains capacity expansion. Distribution runs through Rotterdam's chemical handling infrastructure for European formulation houses and Busan's port complex for K-beauty export flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic UV absorber market sits at an inflection where ISO 24443 photostability mandates and divergent regulatory catalogs are fragmenting global product portfolios and elevating compliance investment thresholds.
For Market Incumbents: Fortify dossier capabilities through backward integration into toxicology testing infrastructure, capturing margin from suppliers lacking REACH-compliant documentation. Expand encapsulation polymer production in Seoul Capital Area clusters to serve K-beauty demand for sensitive-skin formulations. Lock in long-term offtake agreements with benzotriazole precursor suppliers before petrochemical volatility intensifies. For New Entrants and Emerging Players: Differentiate on blue light filter integration for daily wear skincare, an unclaimed positioning space between traditional sun care and anti-pollution claims. Target India's BIS-expanding market with pre-validated ingredient portfolios before concentration limits harden. Pursue direct sourcing platform relationships with Maharashtra toll manufacturers to bypass established distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated laboratory operators over commodity filter suppliers. Long-term viability hinges on regulatory dossier depth rather than scale economics alone. Watch NMPA expanded ingredient catalog approvals as the signal indicating which filter technologies will unlock major market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photostability Testing | Captures margin from REACH-compliant documentation requirements that commodity suppliers cannot meet. |
| Encapsulation Technology Partnership | Secures proprietary shell-core microsphere supply for German dermocosmetic brands demanding skin-contact isolation. |
| Triazine Derivative Capacity Expansion | Positions suppliers to capture substitution demand as ECHA aquatic toxicity mandates displace benzotriazole chemistry. |
| Direct Sourcing Platform Development | Displaces traditional distributor relationships in India and United States mass-market channels. |
| Blue Light Filter R&D Program | Opens white space between sun care and anti-pollution positioning in daily wear skincare integration. |
Study Parameters
Cross-validation between primary interviews with formulation scientists, regulatory affairs directors, and pharmacy procurement managers and secondary validation through REACH registration databases, NMPA cosmetic ingredient catalogs, and MFDS standards documentation anchors the qualitative findings. Bottom-up triangulation from filter-grade production volumes and top-down validation from dermocosmetic brand R&D expenditure disclosures calibrate market sizing. SEC filings from listed chemical conglomerates and customs records from Rotterdam and Busan port authorities provide trade flow verification.
Sensitivity analysis across photostability testing adoption curves, regulatory approval timelines, and petrochemical feedstock price scenarios frames the projection horizon. Segmentation dimensions modeled include organic versus inorganic versus hybrid filter architecture, lotion versus cream versus gel formulation type, and consumer versus dermatologist versus pharmacy channel end-use. CAGRs derive from regression analysis against dermocosmetic sales velocity and ISO 24443 compliance penetration rates. Forecast inputs incorporate K-beauty export growth trajectories and BIS regulatory expansion schedules.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or NMPA catalog expansion would require recalibration. Forecasts reflect assumptions regarding photostability testing adoption and regulatory harmonization progress. Revision becomes warranted when benzotriazole substitution velocity or encapsulation technology cost curves cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Global Cosmetic Peptide Synthesis Market
Cosmetic Chemicals
China Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Anti-Aging Serums Market
Cosmetic Chemicals
Skin Lightening Products Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Anti-Aging and Anti-Wrinkle Products Market
Cosmetic Chemicals
Cosmetic Emulsifier Market
Cosmetic Chemicals
Liposome in Cosmetics Market
Cosmetic Chemicals
Cosmetic Chemicals Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Premium Tattoo Ink Market