
 Anti-Aging and Anti-Wrinkle Products Market | 2026-2036
Anti-Aging and Anti-Wrinkle Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging and Anti-Wrinkle Products Market Analytics
Cosmetic chemist talent shortages in peptide synthesis and encapsulation technology is reorganizing how brands secure formulation pipelines. L'Oréal SA leverages its integrated research network to retain specialized biochemists across France and the United States. Estée Lauder Companies Inc. sustains competitive recruitment through dedicated dermatological science fellowships. Shiseido Company anchors its innovation capacity via long-term partnerships with Japanese university laboratories.
Anti-aging and anti-wrinkle products comprise topical formulations designed to reduce visible skin aging through collagen stimulation, cellular turnover acceleration, or free-radical neutralization, typically containing active concentrations of retinoids, peptides, or hyaluronic acid at pH levels optimized for epidermal penetration. The segment serves both preventive maintenance for younger demographics and corrective treatment for mature skin concerns. Retinol-based serums command premium shelf positioning due to proven efficacy data and dermatologist endorsement, while peptide formulations represent the fastest-expanding ingredient class as consumers seek alternatives with lower irritation profiles. Creams maintain volume leadership across mass retail channels, though eye-specific applications generate disproportionate margin contribution relative to unit volume.
The FDA monitors anti-aging claim substantiation in the United States, while the EU's Cosmetics Regulation enforces ingredient safety assessments through ECHA's REACH framework, and South Korea's MFDS governs functional cosmetics labeling. These bodies collectively elevate barrier costs for new entrants while rewarding documentation-heavy incumbents with sustained market access. Stakeholders must track evolving definitions that distinguish cosmetic from drug classification, as regulatory reclassification would force clinical trial investments or channel restrictions.
Market Dynamics
The convergence of peptide synthesis expertise scarcity with tightening FDA claim substantiation requirements is compressing formulation timelines and forcing brands to restructure R&D partnerships.
Growth Catalysts
- REACH ingredient safety documentation:The EU's ECHA framework rewards incumbent brands with pre-validated dossiers, creating defensive moats against unestablished competitors seeking European market entry.
- Dermatology clinic channel expansion:Professional-grade protocol adoption across outpatient dermatology settings in the United States and Germany is elevating prescription-adjacent positioning for clinical skincare brands.
- Encapsulation technology maturation:Liposome and niosome delivery systems are improving retinol stability and reducing irritation incidence, expanding addressable demographics to sensitive skin populations previously excluded.
Market Restraints
- Peptide raw material concentration:Contract manufacturing for specialized amino acid sequences clusters among South Korean and Swiss suppliers, exposing brands to single-source vulnerability.
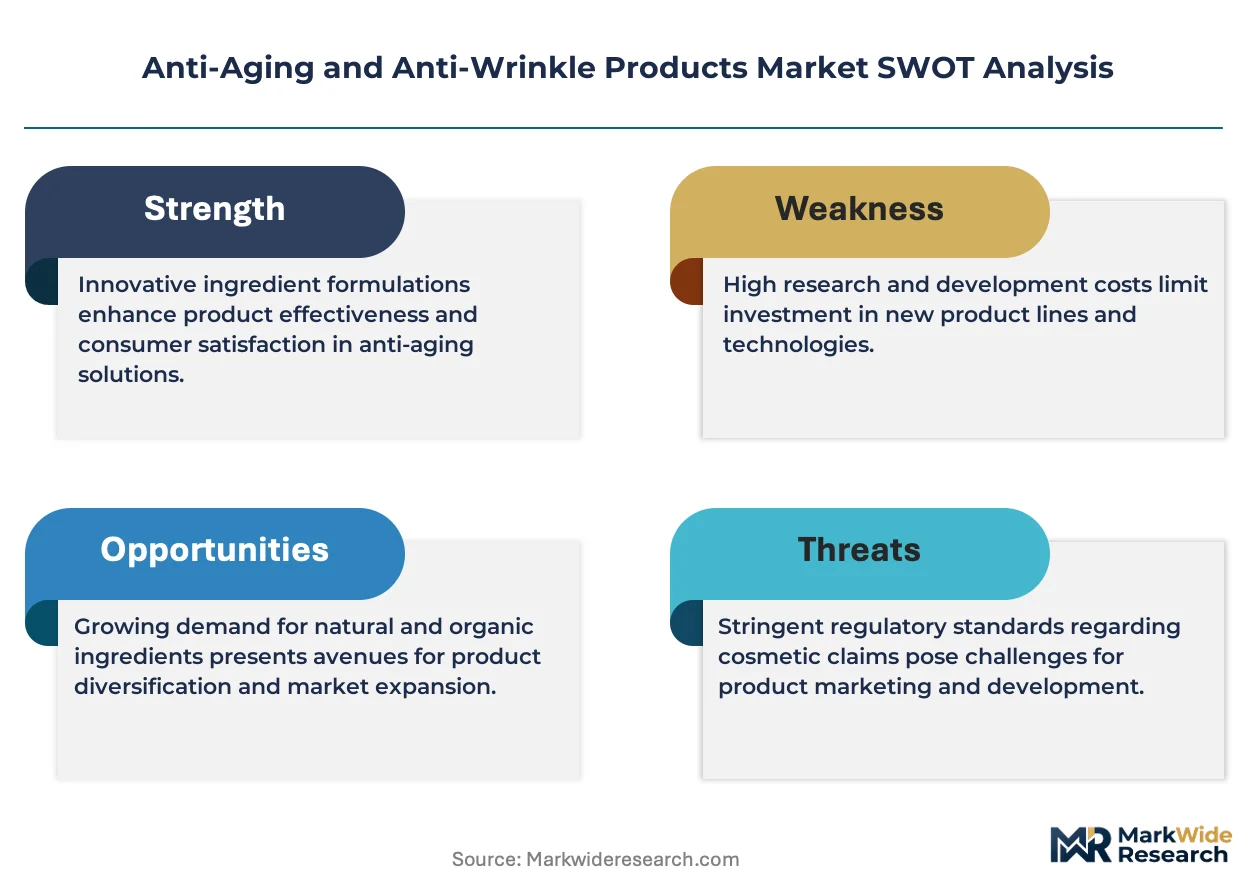
- FDA cosmetic-drug classification ambiguity:Uncertainty around structure-function claim boundaries forces dual-track regulatory preparation, inflating compliance overhead for novel active ingredients.
- Hyaluronic acid price volatility:Fermentation-derived supply chains face agricultural input cost swings that compress margin predictability across mass-market moisturizer lines.
Strategic Opportunities
- Men's grooming category underpenetration:Male-specific anti-aging positioning remains nascent in Germany and Japan, offering first-mover advantage for gender-targeted formulation and packaging.
- MFDS functional cosmetics fast-track:South Korea's abbreviated approval pathway for wrinkle-reduction claims enables accelerated launch velocity versus standard cosmetic registration timelines.
- Biotechnology-pharma convergence:CRISPR-derived cellular senescence research is migrating from therapeutic applications into topical skincare, opening prestige positioning at pharmaceutical credibility levels.
Industry Challenges
- Cosmetic biochemist recruitment bottlenecks:Specialized peptide chemist talent pools in France and the United States are insufficient to match formulation pipeline expansion, forcing compensation inflation.
- Clinical trial infrastructure scaling:Substantiation requirements for anti-wrinkle claims demand dermatological testing capacity that exceeds available investigator site availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging and Anti-Wrinkle Products Market |
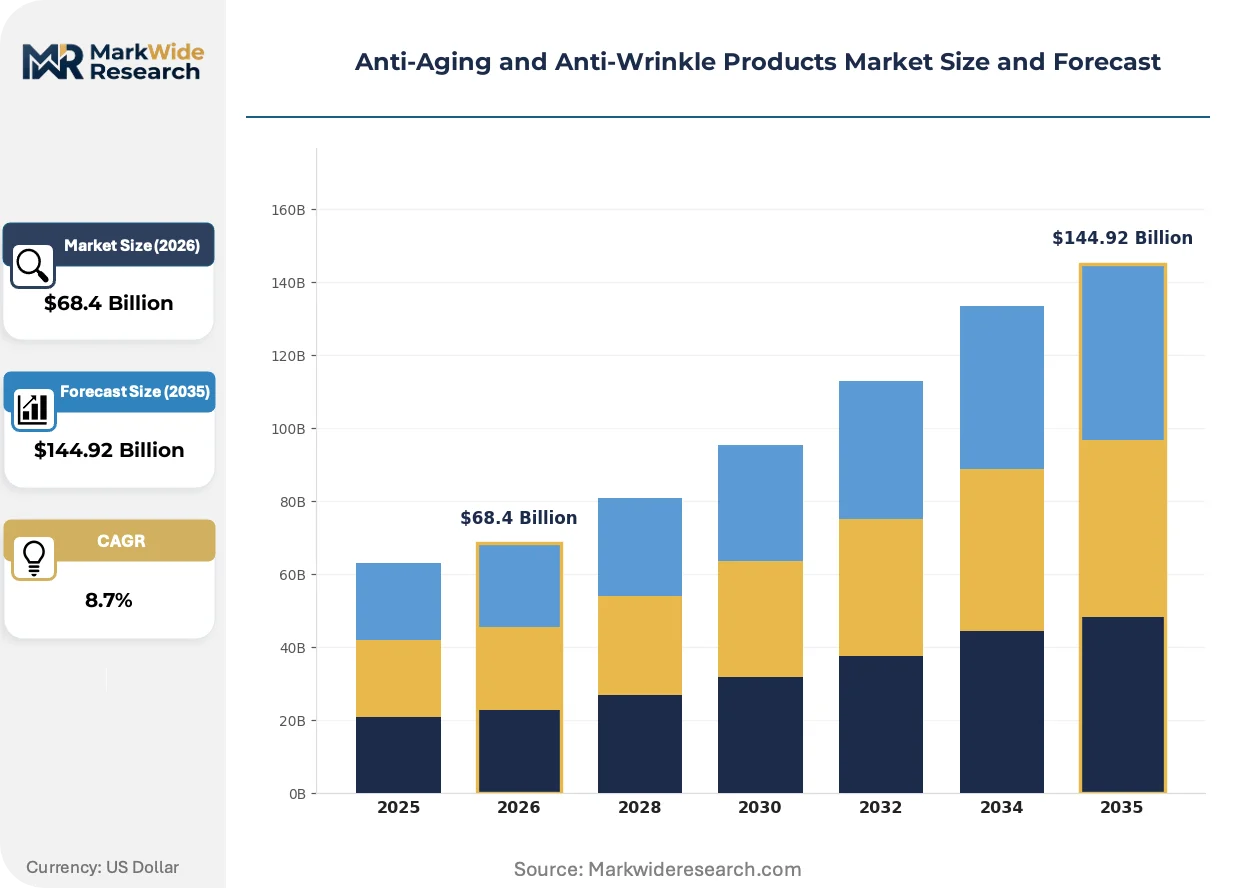
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Masks, Oils Ingredient: Retinol, Peptides, Hyaluronic Acid, Antioxidants Age Group: Teens, 20s, 30s, 40+ Application Area: Face, Neck, Hands, Eyes |
| Companies Covered | L'Oréal SA, Estée Lauder Companies Inc., Procter & Gamble Co., Unilever PLC, Beiersdorf AG, Johnson & Johnson, Shiseido Company, Coty Inc., Avon Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging and Anti-Wrinkle Products Market Evolving Landscape
Biotechnology-derived active delivery systems and regulatory documentation automation are compressing the gap between laboratory discovery and commercial shelf placement.
Microencapsulated retinol is decomposing traditional stability limitations that previously constrained formulation flexibility. Premium skincare brands in Japan and the United States are adopting time-release matrices at accelerated procurement cadences. This technology is decomposing the historical trade-off between efficacy concentration and tolerability, enabling higher active loads without corresponding irritation penalties.
REACH Annex XVII restrictions on preservative systems are forcing reformulation investments across European-exporting manufacturers. The industrial consequence is a shift toward hurdle technology preservation using organic acids and packaging innovations. Brands serving Germany and France are responding with accelerated clean beauty certification timelines to preempt regulatory non-compliance.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for core serum categories. Direct-to-consumer channels in the United States and United Kingdom are capturing repeat purchase loyalty through personalized regimen algorithms. This pattern is most visible among millennial and Generation Z demographics seeking convenience without dermatologist intermediation.
Anti-Aging and Anti-Wrinkle Products Market Segmentation
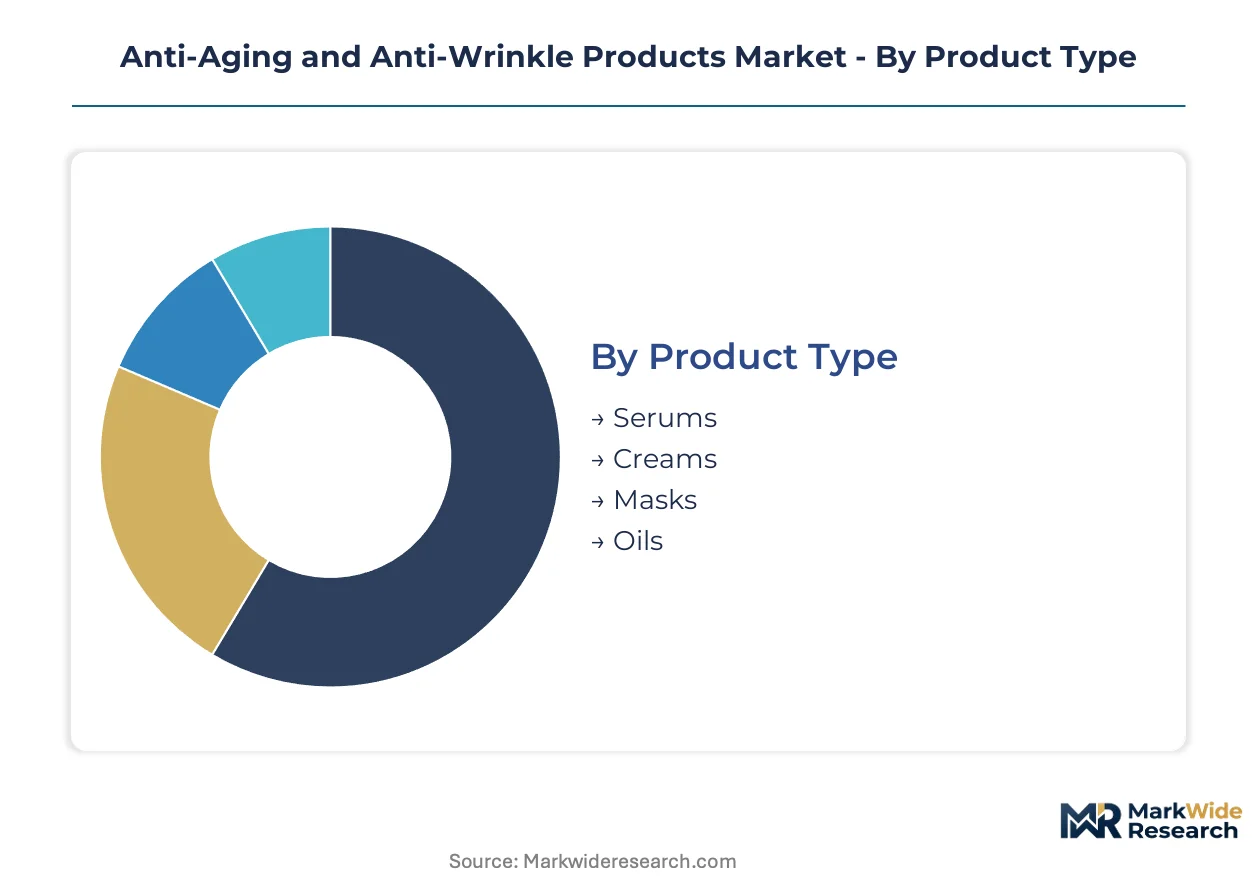
Segmentation in anti-aging and anti-wrinkle products determines channel strategy, pricing architecture, and regulatory pathway selection. Distinct consumer cohorts and application sites demand formulation specificity that reshapes manufacturing priorities and distribution investments.
Product Type:
Channel mix varies sharply by viscosity and usage ritual—serums concentrate in specialty retail and dermatology clinics, while creams dominate mass-market shelf space and subscription replenishment models.
- Serums:Lightweight, high-actives formulations with rapid epidermal penetration profiles. Demand clusters among millennial demographics in the United States and South Korea seeking clinical-grade results without prescription barriers. Dermatology clinic dispensing and direct-to-consumer subscriptions capture the highest-margin transactions.
- Creams:Emulsion-based vehicles delivering sustained hydration with lower irritation potential. Volume leadership persists across German and Japanese mass retail channels where older demographics prioritize tolerability over concentration intensity. Encapsulation technology adoption is expanding efficacy claims in this historically conservative format.
- Masks:Sheet and rinse-off formats for intensive weekly treatment protocols. South Korean beauty innovation corridors drive format experimentation.
- Oils:Lipid-rich occlusive systems targeting barrier repair and mature skin concerns. Prestige positioning in French pharmacy retail commands premium unit economics.
Creams dominate installed base across all measured channels. Serums are where expansion concentrates as encapsulation technology reduces tolerability barriers.
Ingredient:
Cost tier stratification follows active ingredient complexity—biotechnology-derived peptides and stabilized retinoids occupy premium price bands, while commodity hyaluronic acid formulations compete on volume scale.
- Retinol:Vitamin A derivatives with proven collagen stimulation and cellular turnover acceleration. Demand concentrates in prescription-adjacent positioning across United States dermatology clinics where FDA claim substantiation requirements favor established documentation portfolios. Stability challenges drive microencapsulation investment cycles.
- Peptides:Short-chain amino acid sequences signaling collagen synthesis and extracellular matrix repair. Synthesis expertise scarcity in France and Switzerland is reorganizing how brands secure formulation pipelines. South Korean suppliers command strategic leverage in specialized sequence manufacturing.
- Hyaluronic Acid:Fermentation-derived glycosaminoglycan with humectant and volumizing properties. Agricultural input cost volatility compresses margin predictability in mass-market lines.
- Antioxidants:Free-radical neutralizing compounds including vitamin C derivatives and polyphenols. Stability-sensitive formulations require packaging innovation and pH optimization.
Retinol dominates installed base in clinical and prestige channels. Peptides are where expansion concentrates as consumers seek efficacy without irritation penalties.
Age Group:
Application purpose shifts across demographic cohorts—preventive maintenance for younger segments versus corrective intervention for mature consumers, with corresponding differences in active concentration tolerance and price sensitivity.
- Teens:Early intervention focused on photoprotection and antioxidant preloading. Japanese and South Korean markets show concentrated trial behavior in this cohort.
- 20s:Preventive retinol introduction and hydration maintenance. United States direct-to-consumer brands target this demographic with subscription-based regimen building.
- 30s:Corrective-preventive hybrid protocols addressing first visible aging signs. Peptide and retinol combination products gain traction in German pharmacy channels.
- 40+:Intensive correction targeting established wrinkles and elasticity loss. Highest per-capita spending concentration supports premium pricing architecture.
The 40+ cohort dominates installed base value contribution. The 20s segment is where expansion concentrates as preventive positioning penetrates earlier in the consumer lifecycle.
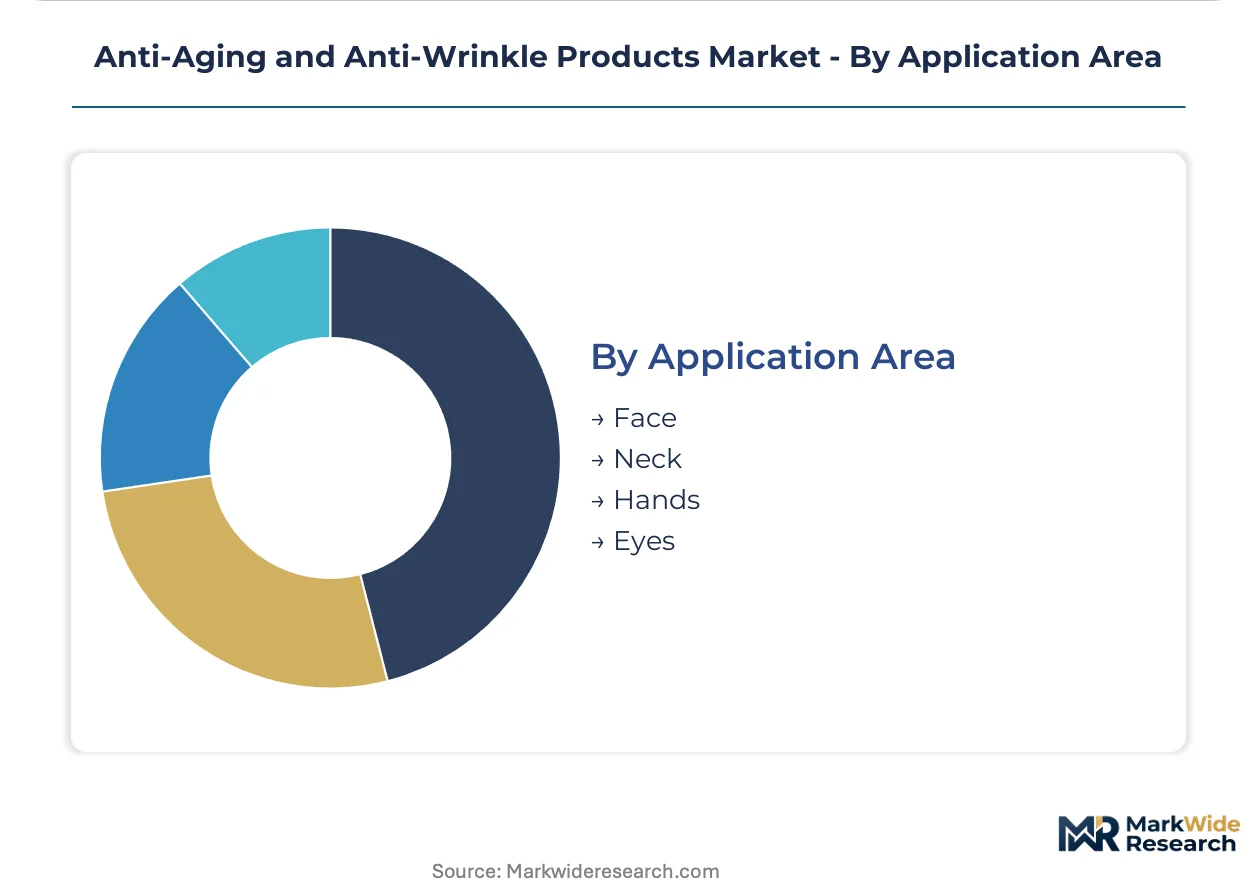
Application Area:
Margin structure varies by anatomical site—eye-specific applications generate disproportionate profit contribution relative to unit volume due to formulation precision requirements and price inelasticity.
- Face:Broad-surface treatment protocols addressing overall aging presentation. Volume concentration across all channels and price tiers.
- Neck:Specialized formulations addressing horizontal line patterns and skin texture differences from facial epidermis. Emerging positioning in prestige lines.
- Hands:Volume replacement and pigmentation correction for exposed extremities. Pharmacy and professional channel concentration in aging demographics.
- Eyes:Delicate periorbital formulations with reduced active concentrations and specialized delivery systems. German and Japanese consumers demonstrate sustained price premium acceptance for this application site.
Face applications dominate installed base across volume metrics. Eye-specific formulations are where expansion concentrates as brands pursue margin optimization through anatomical specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA claim substantiation protocols in the United States establish the regulatory baseline that shapes formulation investments across developed markets. Dermatology clinic dispensing networks concentrate professional-grade demand in specific metropolitan corridors. South Korean MFDS functional cosmetics pathways accelerate commercialization velocity for biotechnology-derived actives.
United States
Dermatology clinic expansion across Texas and Florida drives prescription-adjacent skincare protocol adoption. FDA structure-function claim boundaries force dual-track regulatory preparation for novel peptide ingredients. Greater Boston anchors clinical trial infrastructure serving substantiation requirements for anti-wrinkle efficacy claims.
Germany
Pharmacy retail concentration in Bavaria and North Rhine-Westphalia sustains premium positioning for peptide-based formulations. ECHA REACH Annex XVII preservative restrictions mandate reformulation cycles across European-exporting manufacturers. Frankfurt-Rhine-Main corridor hosts documentation specialists serving EU cosmetics safety dossier preparation.
South Korea
Beauty innovation corridor in Seoul Capital Area generates format experimentation for sheet masks and intensive treatment protocols. MFDS functional cosmetics fast-track enables abbreviated approval timelines for wrinkle-reduction claims. Busan-Ulsan region concentrates contract manufacturing capacity for specialized amino acid sequence synthesis.
Japan
Preventive positioning among Tokyo's millennial demographic expands early-intervention product categories. METI standards govern quasi-drug classification boundaries that influence active ingredient concentration limits. Kansai region pharmaceutical heritage supports dermatological science partnerships for prestige brand R&D.
France
Pharmacy retail tradition in Île-de-France maintains consumer trust in clinician-endorsed skincare protocols. ANSM monitors cosmetic claim substantiation parallel to EU REACH frameworks. Auvergne-Rhône-Alpes biotechnology clusters supply peptide synthesis expertise to formulation pipelines.
Anti-Aging and Anti-Wrinkle Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market's competitive architecture. Multinational conglomerates with captive R&D networks and dermatology clinic relationships command premium shelf positioning and regulatory documentation portfolios. Specialist formulators compete through biotechnology partnerships and regional MFDS fast-track exploitation. Capacity expansion in South Korean contract manufacturing and acquisition of peptide synthesis capabilities represent the dominant competitive vectors reshaping market structure.
Within the integrated multinational tier, L'Oréal SA and Estée Lauder Companies Inc. exemplify archetypes distinguished by research network scale and dermatological science fellowship programs. Shiseido Company occupies a position bridging Japanese pharmaceutical heritage with cosmetics commercialization expertise. These three entities represent distinct geographic anchors—French, American, and Japanese—that shape regional regulatory navigation strategies and formulation pipeline access.
| Leading Market Players |
|---|
| L'Oréal SA |
| Estée Lauder Companies Inc. |
| Procter & Gamble Co. |
| Unilever PLC |
| Beiersdorf AG |
| Johnson & Johnson |
| Shiseido Company |
| Coty Inc. |
| Avon Products Inc. |
| Others |
Value Network & Pricing Analysis
Long-term peptide synthesis offtake agreements with South Korean and Swiss suppliers lock in both supply access and price visibility for prestige skincare brands, insulating them from agricultural input cost swings that compress mass-market hyaluronic acid margins.
Pricing Analysis
United States dermatology clinic channels command 40-60% premiums over German pharmacy retail for identical peptide formulations, reflecting prescription-adjacent positioning and FDA claim substantiation investments. Three-tier pricing structure across premium encapsulated retinol, standard hyaluronic acid moisturizers, and economy antioxidant lines stratifies by active concentration and delivery technology sophistication. Pricing pressure stems from fermentation-derived hyaluronic acid supply cost volatility, forcing mass-market brands toward contract manufacturing consolidation. Generation Z direct-to-consumer subscribers demonstrate highest price sensitivity, while 40+ clinic-channel consumers show lowest elasticity for eye-specific applications.
Supply Chain Analysis
Inventory cycles for specialized amino acid sequences extend 16-24 weeks, constraining formulation pipeline flexibility for brands dependent on South Korean and Swiss contract manufacturers. Peptide synthesis expertise clusters in Busan-Ulsan and Basel regions, while encapsulated retinol stability technology concentrates among Japanese and United States specialty chemical suppliers. Single-source vulnerability in South Korean peptide raw material concentration exposes brands to geopolitical logistics chokepoints. Distribution runs through dermatology clinic dispensing networks in Texas and Florida corridors, pharmacy retail concentration in Bavaria and North Rhine-Westphalia, and direct-to-consumer subscription platforms in United States and United Kingdom metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough driven by post-pandemic clinic-channel normalization and subscription-model retention maturation, positioning stakeholders for recovery-phase positioning gains.
For Market Incumbents: Consolidate peptide synthesis capabilities through captive partnerships with Auvergne-Rhône-Alpes biotechnology clusters, securing formulation pipeline access against cosmetic biochemist recruitment bottlenecks. Acquire South Korean contract manufacturing capacity to defend margin position from raw material concentration risk. Channel control through dermatology clinic relationship deepening in Texas and Florida anchors prescription-adjacent pricing power. For New Entrants and Emerging Players: Differentiate on men's grooming category underpenetration in Germany and Japan, where gender-targeted positioning remains nascent relative to saturated female-skincare channels. Exploit MFDS functional cosmetics fast-track pathways for accelerated wrinkle-reduction claim approval versus standard registration timelines. Direct-to-consumer subscription algorithms targeting United States millennial preventive maintenance protocols offer lowest competitive density entry vector. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale peptide synthesis specialists with validated ECHA REACH dossiers and established South Korean supplier relationships, capturing defensive moat value from regulatory documentation barriers. Five-to-ten year viability hinges on biotechnology-pharma convergence migration from therapeutic senescence research into topical applications. Watch CRISPR-derived cellular senescence clinical trial readouts as inflection signal for prestige positioning credibility thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Partnership | Secures formulation pipeline access against cosmetic chemist talent shortages in France and Switzerland. |
| MFDS Fast-Track Exploitation | Abbreviates wrinkle-reduction claim approval timelines versus standard South Korean cosmetic registration pathways. |
| Dermatology Clinic Network Expansion | Captures prescription-adjacent positioning in Texas and Florida metropolitan corridors with highest per-capita spending. |
| Encapsulation Technology Procurement | Enables higher retinol active loads without irritation penalties, expanding addressable sensitive-skin demographics. |
| Men's Grooming Line Launch | Addresses underpenetration in Germany and Japan where male-specific anti-aging positioning remains nascent. |
Research Methodology
A spread of perspectives from cosmetic chemists at L'Oréal SA and Estée Lauder Companies Inc., dermatology clinic dispensing managers in Texas and Florida, South Korean contract manufacturing procurement leads, and German pharmacy retail category buyers converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) filings, ECHA REACH Annex XVII restriction updates, MFDS functional cosmetics approval databases, and Nielsen retail audit data for United States and German skincare channels. Bottom-up volume modeling by product type, ingredient class, and age cohort triangulated against top-down market sizing from regulatory documentation portfolios.
Segmentation dimensions modeled span product type (serums, creams, masks, oils), ingredient category (retinol, peptides, hyaluronic acid, antioxidants), age demographic (teens through 40+), and application area (face, neck, hands, eyes) across the analysis window. CAGRs were derived from dermatology clinic expansion trajectories, subscription-model penetration curves, and encapsulation technology adoption rates. Forecast inputs incorporated MFDS approval velocity differentials and ECHA preservative restriction implementation timelines.
Material uncertainties — FDA cosmetic-drug classification reclassification, peptide raw material supply disruption, and hyaluronic acid fermentation input cost spikes — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Face Primer Market
Cosmetic Chemicals
Herbal Mascara Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Cosmetic Cetearyl Alcohol Ingredients Market
Cosmetic Chemicals
Facial Essence Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Cosmetic & Toiletry Chemicals Market
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Organic Cosmetic Ingredients Market