
 Ghana Automobile Market | 2026-2036
Ghana Automobile Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Automobile Market Foresight
The Ghana automobile market is recalibrating around a widening split between imported fully-built premium units and locally assembled commodity vehicles serving price-sensitive buyers. Toyota Motor Corporation leverages its established dealer network and hybrid technology portfolio to sustain dominance in the premium tier. Kantanka Automobile anchors the domestic assembly segment with in-house production of SUVs and sedans for government and institutional buyers. Volkswagen AG competes through its Accra assembly partnership, targeting fleet operators with localized hatchback and pickup truck output.
An automobile is a self-propelled road vehicle powered by an internal combustion engine, electric motor, or hybrid drivetrain, typically featuring a chassis, powertrain, and passenger or cargo compartment designed for transportation of people and goods. In Ghana, vehicles must comply with GVIN registration standards and ECOWAS roadworthiness protocols to operate commercially. The pickup truck and SUV categories lead volume due to rural infrastructure demands and commercial utility requirements. The electric and hybrid fuel type segment is expanding fastest as Ghana Grid Company power reliability improves and import duty exemptions for clean vehicles take effect. Authorized dealerships remain the dominant sales channel, though fleet sales generate superior margin pools through volume contracts with mining and logistics enterprises.
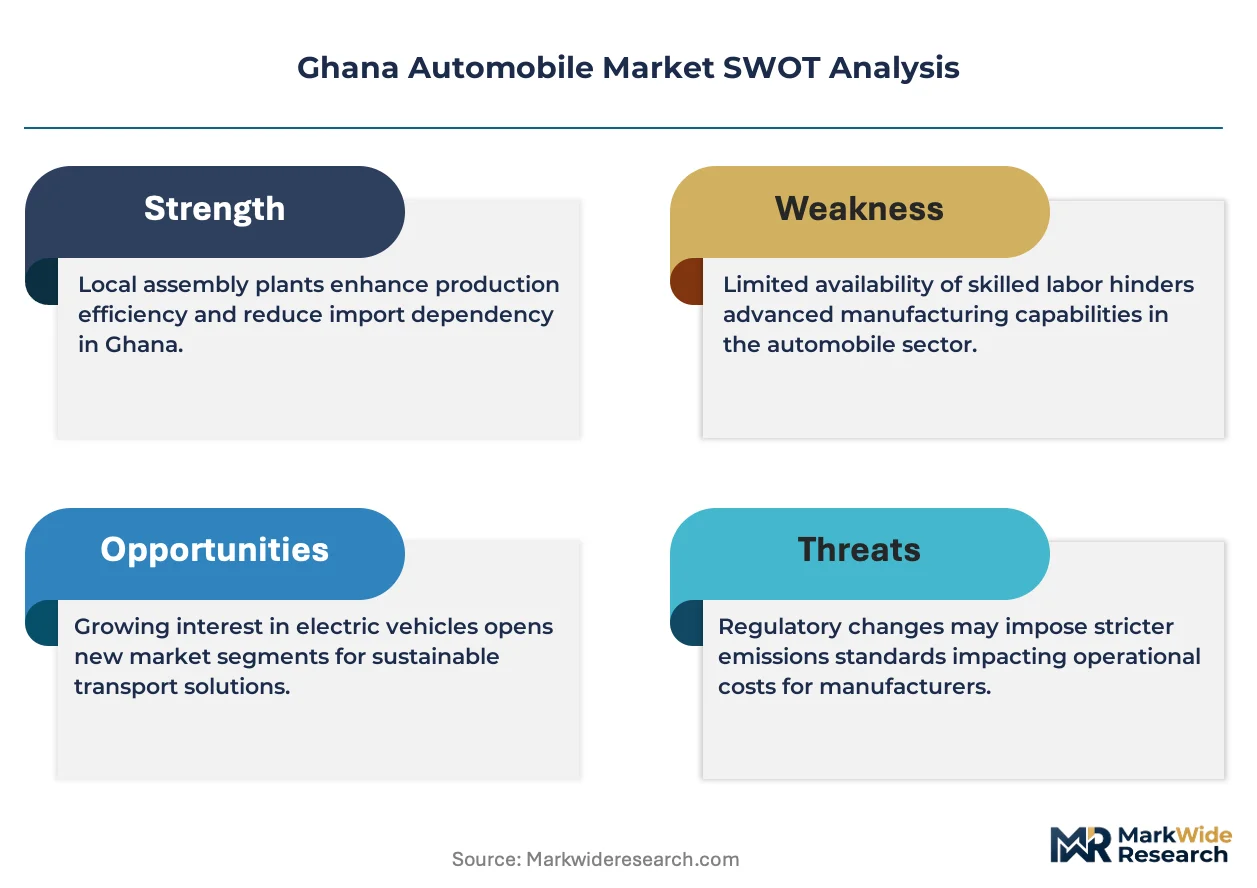
Ghana's Automotive Development Policy, administered by the Ministry of Trade and Industry and the Ghana Standards Authority, mandates local assembly quotas and phased import restrictions to stimulate domestic manufacturing capacity. The Environmental Protection Agency enforces emission benchmarks aligned with Euro 4 standards, shaping engine specifications for vehicles entering the market. Stakeholders must monitor regulatory enforcement consistency and grid infrastructure deployment to determine optimal timing for electric vehicle portfolio commitments.
Market Dynamics
Ghana's automobile market is restructuring around the tension between import dependency and domestic assembly mandates, with the Ghana Standards Authority enforcing local content quotas that redirect procurement flows toward Kantanka and Volkswagen Accra partnerships.
Growth Catalysts
- Ghana Automotive Development Policy:The Ministry of Trade and Industry mandates phased import restrictions and local assembly quotas, redirecting fleet procurement toward domestic production facilities.
- Ride-hailing fleet expansion:Operators across Accra and Kumasi are accelerating vehicle procurement to meet urban mobility demand, creating concentrated bulk purchasing channels.
- Grid reliability improvements:Ghana Grid Company infrastructure investments enable electric vehicle charging networks, supporting hybrid and electric drivetrain adoption in commercial segments.
Market Restraints
- Import duty volatility:Tariff fluctuations on fully-built units create margin compression for premium segment distributors dependent on Japanese and European supply chains.
- Local component scarcity:Limited domestic steel and electronics manufacturing forces assemblers to import sub-assemblies, undermining cost advantages of local production.
- Euro 4 compliance costs:Environmental Protection Agency emission benchmarks require engine retooling that increases unit costs for entry-level vehicle categories.
Strategic Opportunities
- Corporate fleet electrification:Mining and logistics enterprises in Greater Accra are piloting hybrid procurement under clean vehicle duty exemptions, creating premium contract channels.
- Kumasi distribution hub development:Underpenetrated secondary city markets offer first-mover positioning for authorized dealerships beyond Accra concentration.
- After-sales service unbundling:Independent maintenance networks are capturing service revenue from aging vehicle parc, displacing captive dealership models.
Industry Challenges
- Certification timeline compression:GVIN registration and ECOWAS roadworthiness protocols create multi-month approval delays that strain inventory financing for importers.
- Technical workforce scarcity:Local shortage of hybrid drivetrain technicians limits service capacity for electrified vehicle segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Automobile Market |
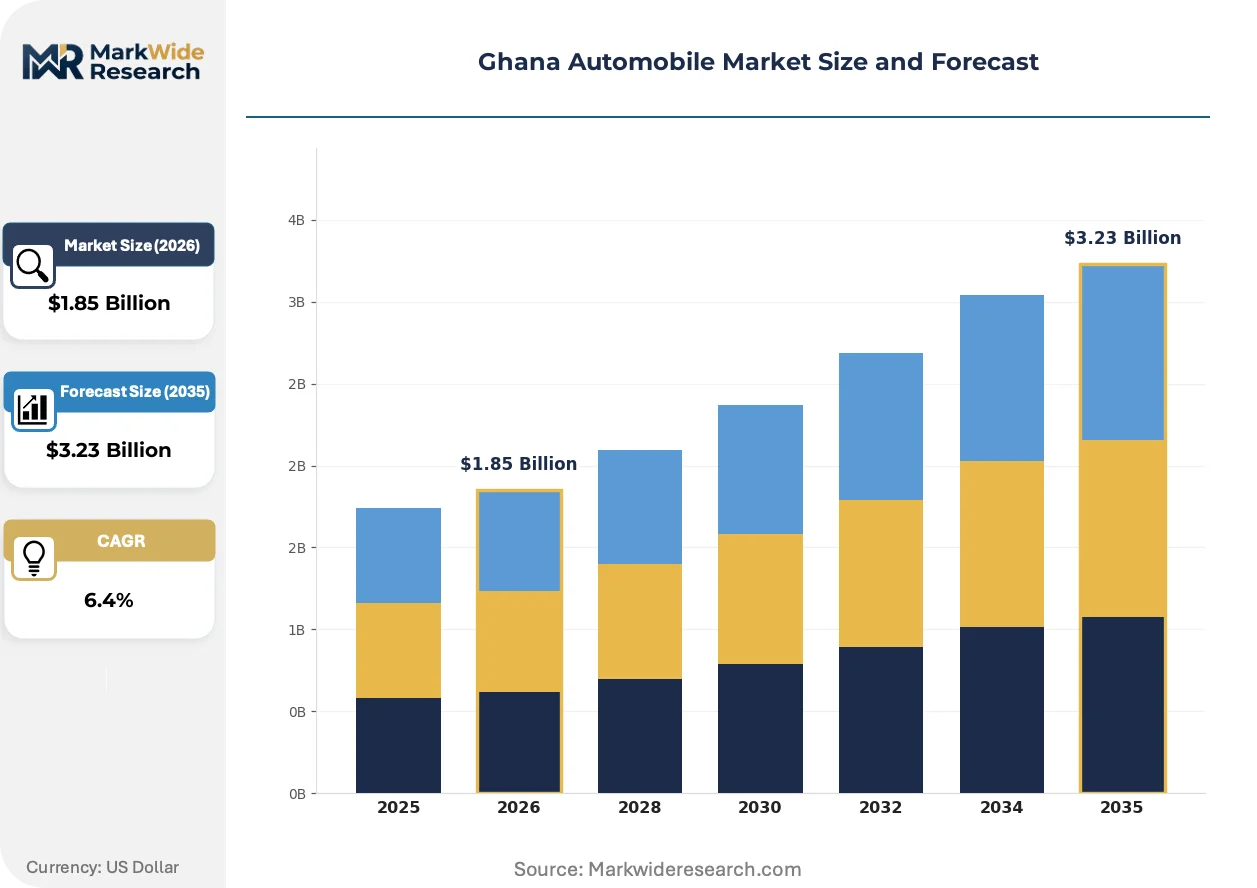
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Truck, Van, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid, Liquefied Petroleum Gas, Compressed Natural Gas Sales Channel: Authorized Dealerships, Online Marketplaces, Used Car Dealers, Fleet Sales, Auction Houses, Direct Purchase End User: Individual Consumers, Ride-Hailing Operators, Government Agencies, Corporate Fleets, Taxi Services, Rental Companies |
| Companies Covered | Toyota Motor Corporation, Volkswagen AG, Nissan Motor Co. Ltd, Hyundai Motor Company, Kantanka Automobile, APL Nissan Ghana, Alliance Motors Ghana Limited, CFAO Ghana PLC, Suzuki, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Automobile Market Shifts & Advancements
Powertrain diversification and regulatory enforcement are compressing traditional market boundaries, with electrification and local assembly mandates forcing portfolio restructuring across import-dependent distributors.
Hybrid drivetrain technology is electrifying commercial fleet procurement in Ghana. Mining operators and logistics enterprises are adopting Toyota hybrid systems to manage fuel cost exposure on long-haul routes. This electrification is compressing payback periods for premium drivetrain investments and redirecting fleet specification away from conventional diesel platforms.
Ghana Standards Authority enforcement of local assembly quotas is restructuring import authorization workflows. The Ministry of Trade and Industry is withholding import permits for vehicle categories with active domestic production equivalents. This regulatory pressure most affects sedan and SUV segments, where Kantanka and Volkswagen Accra output now satisfies government and institutional tender requirements.
Fleet buyers are consolidating procurement authority through centralized tender processes. Mining conglomerates and ride-hailing platforms are bypassing retail dealership networks in favor of direct manufacturer negotiations. This buyer concentration is most visible in Greater Accra, where corporate accounts now dictate specification standards and after-sales service terms across the premium segment.
Ghana Automobile Market Segmentation
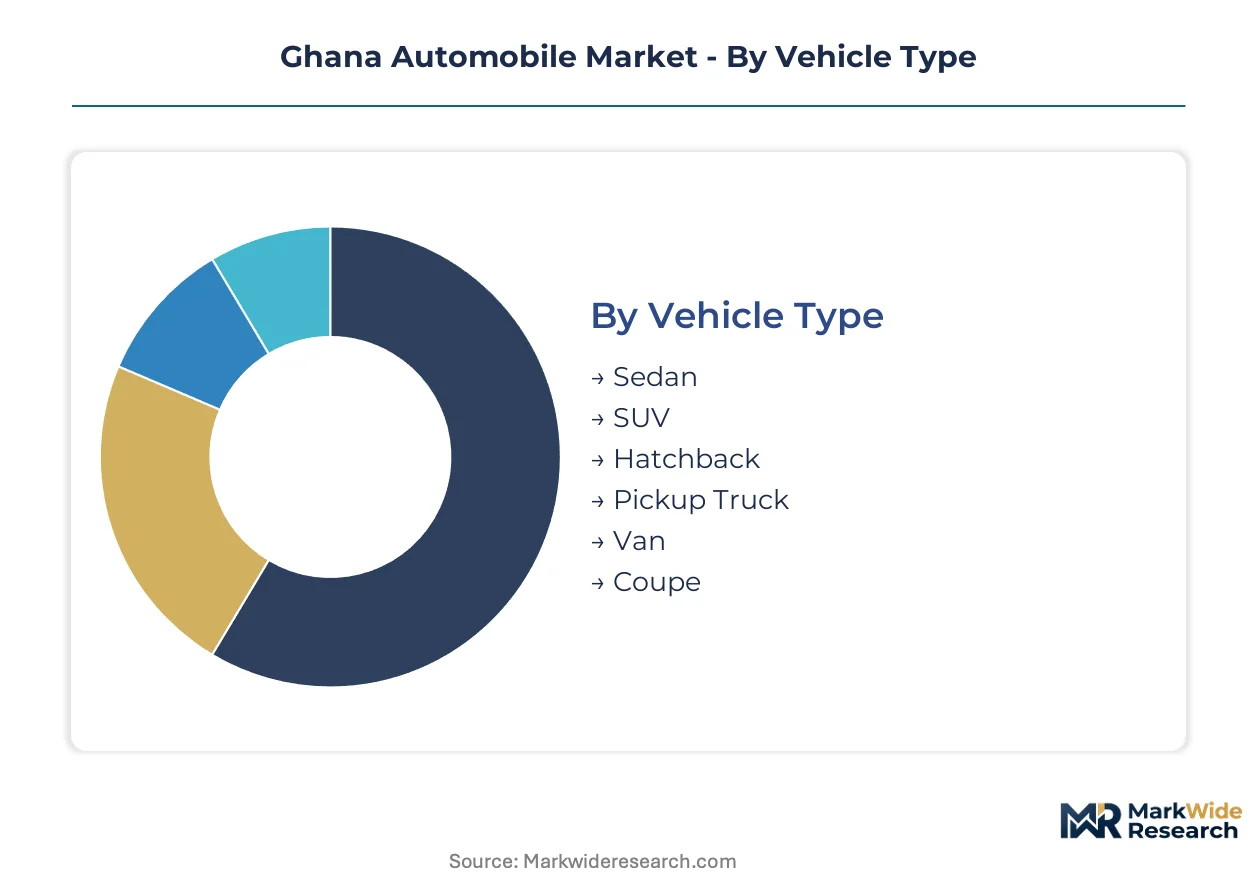
Ghana's automobile segmentation reflects divergent procurement pathways between corporate bulk buyers and individual retail purchasers. Local assembly mandates and fleet electrification priorities are reshaping how volume distributes across vehicle categories and sales channels.
Vehicle Type:
Assembly output concentrates around utility-focused platforms serving commercial and rural infrastructure needs.
- SUV:Body-on-frame and unibody sport utility vehicles dominate Kantanka and Volkswagen Accra production lines. Corporate fleets in Greater Accra specify elevated ground clearance for deteriorated road conditions.
- Pickup Truck:Open-bed commercial vehicles with diesel or petrol powertrains anchor mining and logistics procurement. Rural contractors across Ashanti Region prioritize payload capacity over passenger comfort.
- Sedan:Three-box passenger cars serve government institutional buyers under local content quotas.
- Hatchback:Compact two-box designs target urban commuters through Volkswagen Accra assembly partnerships.
- Van:Panel and passenger van configurations support ride-hailing fleet expansion in Accra and Kumasi.
- Coupe:Two-door performance variants attract premium individual buyers through authorized Toyota dealerships.
Pickup trucks absorb the bulk of installed capacity; electric drivetrain variants are expanding most quickly.
Fuel Type:
Cost tiers separate established internal combustion platforms from emerging electrified alternatives.
- Hybrid:Dual-powertrain systems combining petrol engines with electric motors capture mining fleet procurement. Toyota Motor Corporation dominates this segment through established dealer service networks.
- Electric:Battery-electric vehicles with zero tailpipe emissions qualify for import duty exemptions. Ghana Grid Company infrastructure investments enable charging network deployment across Greater Accra.
- Petrol:Spark-ignition internal combustion engines remain the default for price-sensitive individual buyers.
- Diesel:Compression-ignition powertrains sustain long-haul commercial applications despite Euro 4 compliance cost pressures.
- Liquefied Petroleum Gas:LPG conversions offer fuel cost arbitrage for high-mileage taxi operators.
- Compressed Natural Gas:CNG infrastructure limitations restrict adoption to fleet operators with captive refueling capacity.
Diesel retains the largest share of commercial vehicle parc; hybrid systems are gaining share fastest.
Sales Channel:
Customer type determines channel selection, with volume buyers bypassing retail intermediaries.
- Fleet Sales:Direct manufacturer negotiations for mining conglomerates and ride-hailing platforms. Corporate accounts in Greater Accra dictate specification standards and after-sales service terms.
- Authorized Dealerships:Franchise retail networks dominate individual consumer transactions. Toyota Motor Corporation leverages its established presence to sustain premium segment control.
- Online Marketplaces:Digital platforms aggregate used vehicle inventory for price-transparent comparison.
- Used Car Dealers:Independent traders service entry-level buyers with imported pre-owned units.
- Auction Houses:Bulk disposal channels for institutional fleet rotation and lease terminations.
- Direct Purchase:Manufacturer-to-consumer transactions for specialized commercial configurations.
Authorized dealerships handle the greatest transaction volume; fleet sales generate superior margin pools.
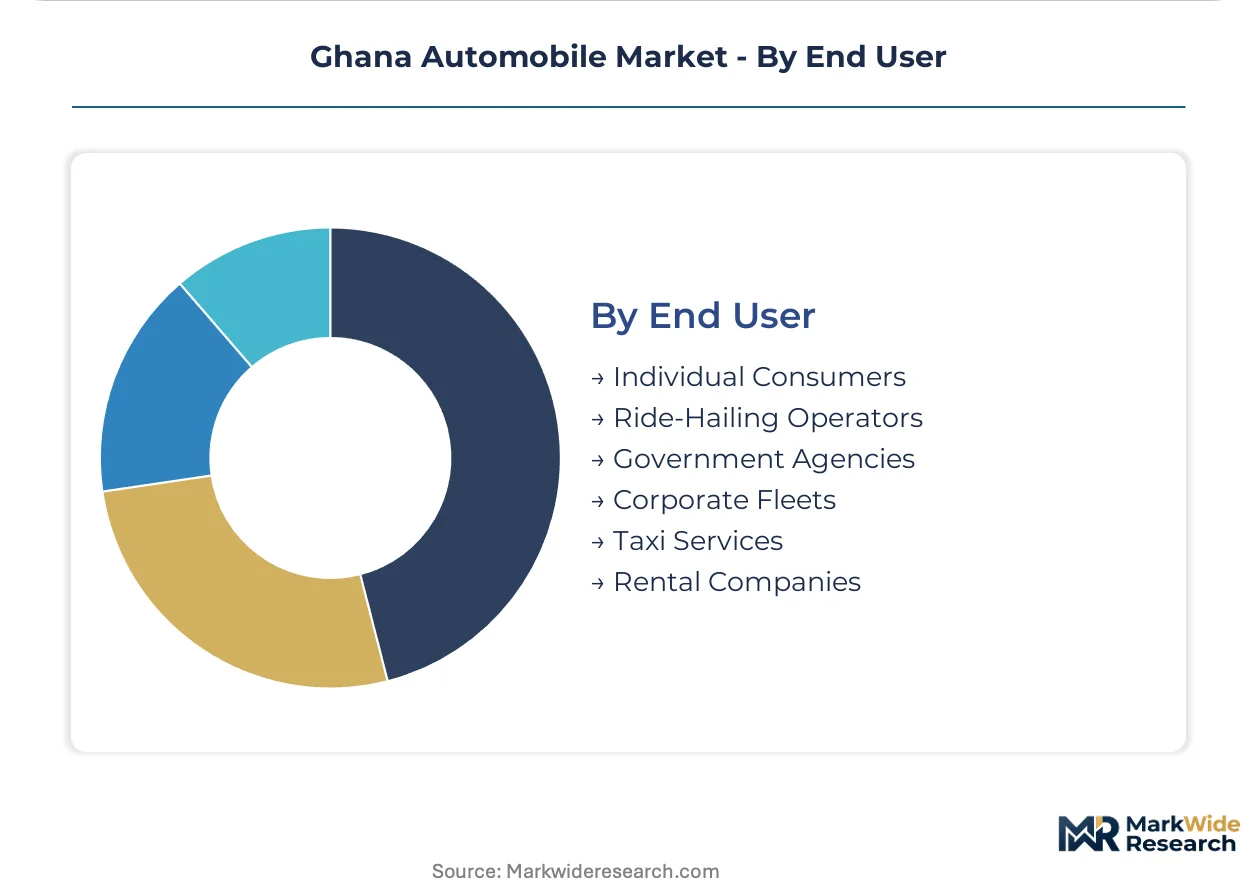
End User:
Application requirements segment buyers between mobility services, resource extraction, and personal transportation.
- Corporate Fleets:Mining and logistics enterprises in Greater Accra pilot hybrid procurement under clean vehicle incentives. Centralized tender processes consolidate specification authority.
- Ride-Hailing Operators:Platform companies across Accra and Kumasi accelerate vehicle procurement to meet urban mobility demand. Bulk purchasing creates concentrated volume channels.
- Government Agencies:Public sector tenders mandate local assembly compliance, redirecting procurement toward Kantanka and Volkswagen Accra output.
- Individual Consumers:Retail buyers split between authorized dealership premium purchases and used import economy options.
- Taxi Services:Owner-operator drivers prioritize fuel efficiency and maintenance accessibility.
- Rental Companies:Short-term vehicle providers focus on depreciation-resistant mainstream segments.
Corporate fleets command the highest per-unit revenue; ride-hailing operators are scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accra dominates Ghana's automobile activity, with the Tema industrial corridor hosting assembly partnerships and the Greater Accra region absorbing the majority of corporate fleet procurement.
Greater Accra
Ride-hailing platforms and mining conglomerates concentrate vehicle procurement in this coastal zone. The Ghana Standards Authority enforces local assembly quotas that redirect government tenders toward Kantanka and Volkswagen Accra output. Tema's free zone infrastructure supports knock-down kit importation for domestic assembly lines.
Ashanti Region
Rural contractors and logistics operators drive pickup truck demand across deteriorated road networks. The Ministry of Trade and Industry administers phased import restrictions that elevate locally assembled utility vehicles in regional procurement. Kumasi's emerging distribution hub attracts dealership expansion beyond Accra concentration.
Western Region
Mining enterprises anchor commercial vehicle demand for payload-intensive operations. Environmental Protection Agency Euro 4 emission benchmarks shape engine specifications for fleet replacements. Takoradi's port facilities handle bulk vehicle imports serving extractive industry logistics.
Northern Region
Cross-border trade corridors generate commercial vehicle demand linking Ghana to Sahel markets. Ghana Grid Company infrastructure investments remain limited, constraining electric vehicle penetration. Tamale functions as a secondary logistics node for northern distribution networks.
Central Region
Tourism and agricultural processing sustain midsize vehicle demand along coastal corridors. The Ghana Automotive Development Policy's local content requirements apply uniformly across all administrative regions. Cape Coast's commercial activity supports authorized dealership satellite operations.
Ghana Automobile Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hybrid technology and local assembly capabilities. The vendor base arranges into three tiers: established Japanese and European manufacturers with dealer networks, domestic assemblers with government relationships, and emerging fleet specialists. Three strategic archetypes dominate: technology licensors leveraging hybrid drivetrain portfolios, local content champions exploiting assembly quotas, and fleet aggregators consolidating ride-hailing procurement. Competitive moves center on strategic partnerships for assembly localization and portfolio diversification into electrified drivetrains.
Within the technology licensor tier, Toyota Motor Corporation and Volkswagen AG exemplify divergent pathways—Toyota leveraging established hybrid systems through dealer networks, Volkswagen exploiting Accra assembly partnerships for fleet penetration. Kantanka Automobile occupies a distinct position as the domestic content anchor, capturing institutional procurement under local assembly mandates. These three entities represent the structural fault lines between import-dependent premium distribution and quota-protected domestic manufacturing.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volkswagen AG |
| Nissan Motor Co. Ltd |
| Hyundai Motor Company |
| Kantanka Automobile |
| APL Nissan Ghana |
| Alliance Motors Ghana Limited |
| CFAO Ghana PLC |
| Suzuki |
| Others |
Supply & Pricing Matrix
Ride-hailing fleet procurement consolidation across Accra and Kumasi is compressing transaction volumes into fewer large-scale contracts, forcing distributors to absorb volume discounts and renegotiate import financing terms with Asian manufacturing partners.
Pricing Analysis
Throughput-based pricing for commercial fleet contracts anchors Ghana's automobile market, with mining operators negotiating total-cost-of-ownership metrics spanning fuel efficiency, maintenance intervals, and residual value guarantees. Three-tier pricing structure across premium, standard, and economy levels separates Toyota hybrid systems from Volkswagen Accra assembly output and imported used-vehicle alternatives. Cost compression in the entry-level segment is intensifying because Euro 4 compliance retooling adds unit cost without perceived buyer value. Individual retail purchasers through authorized dealerships exhibit highest price sensitivity; corporate fleet buyers with centralized tender processes demonstrate lowest sensitivity due to total-cost accounting frameworks.
Supply Chain Analysis
Single-source vulnerability sits with Japanese powertrain component suppliers feeding Toyota's hybrid drivetrain dominance and German engineering licensors supporting Volkswagen Accra assembly partnerships. Knock-down kit imports draw from Thailand, South Africa, and Germany; steel sub-assemblies rest on Turkish and Chinese mill output. Tariff exposure on fully-built units creates inventory financing strain for premium segment distributors dependent on European and Japanese supply chains. Distribution runs through Tema port free zone infrastructure into authorized dealership networks and direct fleet sales channels serving Greater Accra mining and logistics enterprises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's automobile market is consolidating around local assembly quotas and fleet procurement centralization, with Ghana Standards Authority enforcement phasing out import-dependent distributors lacking domestic manufacturing partnerships.
For Market Incumbents: Deploy hybrid drivetrain certification investments to defend corporate fleet contracts against emerging electric vehicle entrants. Secure backward integration into after-sales service networks to capture maintenance revenue from aging vehicle parc and offset margin compression on new unit sales. Deepen Accra assembly partnerships to satisfy government tender requirements under Ghana Automotive Development Policy mandates. For New Entrants and Emerging Players: Capture Kumasi distribution hub development before established Accra dealerships extend satellite operations into Ashanti Region. Target rural contractor segments with payload-optimized pickup configurations underpenetrated by hybrid-focused incumbents. Pursue direct procurement relationships with ride-hailing platforms bypassing traditional retail channels. For Investors and Strategic Acquirers: The window for entry favors domestic assemblers with government relationships and quota-protected market access over import-dependent distribution assets facing phased permit restrictions. Monitor Ghana Grid Company charging infrastructure deployment timelines as the inflection signal for electric vehicle portfolio viability. Long-term positioning rests on manufacturing licensing rather than trading operations.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Volkswagen Accra operations satisfy Ghana Standards Authority import permit restrictions for sedan and SUV categories. |
| Hybrid Drivetrain Investment | Toyota leverages established service networks to capture mining fleet procurement under clean vehicle duty exemptions. |
| Charging Infrastructure Partnership | Grid reliability investments by Ghana Grid Company enable electric vehicle commercialization across Greater Accra. |
| Fleet Sales Channel Development | Direct manufacturer negotiations with ride-hailing operators bypass retail margin structures and accelerate volume capture. |
| After-Sales Service Expansion | Independent maintenance networks capture revenue from aging vehicle parc and displace captive dealership models. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Ghana automobile market assessment. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations managers, and fleet procurement directors at mining and logistics enterprises were cross-validated against Ghana Standards Authority assembly quota records, Ministry of Trade and Industry import permit databases, and vehicle registration flows from Ghana Grid Company infrastructure reports. Bottom-up production volume estimates from Kantanka and Volkswagen Accra facilities were reconciled with top-down fleet procurement surveys across Greater Accra and Ashanti Region.
Data-stream reconciliation combined production capacity utilization rates, import duty exemption utilization for clean vehicles, and corporate tender award patterns across the analysis window. Segmentation modeling incorporated vehicle class, propulsion architecture, OEM tier, and regional production cluster dimensions. CAGRs were derived from production ramp schedules, fleet replacement cycles, and grid infrastructure deployment timelines. Forecast inputs included Ghana Automotive Development Policy phase-in schedules and Environmental Protection Agency emission benchmark enforcement intensity.
The model holds under continued local assembly quota enforcement and grid reliability improvements; deviation in tariff volatility or Euro 4 compliance cost pass-through would shift volume distribution between import and domestic channels. Forecasts reflect documented assumptions regarding policy continuity and infrastructure investment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Lightweight Cars Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Europe Luxury Car Market