
 Density Meter Market | 2026-2036
Density Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Density Meter Market Analysis
Asset-light leasing models for inline process instrumentation is rewriting competitive entry barriers for mid-tier operators. Endress+Hauser Group Services AG leverages its captive service network to sustain long-term calibration contracts. Anton Paar GmbH dominates laboratory-grade precision with Austrian manufacturing depth. Thermo Fisher Scientific extends its life-sciences channel control into pharmaceutical density workflows.
A density meter measures fluid or solid mass per unit volume, typically employing oscillating U-tube, nuclear, or ultrasonic sensing principles with accuracy reaching 0.0001 g/cm³ to govern batch consistency and regulatory compliance. Inline density meters anchor margin pools in continuous process industries where real-time data eliminates offline sampling delays. Laboratory density meters compete on precision certification for pharmaceutical and food safety laboratories. Portable units occupy field-service niches in upstream oil and gas environmental testing.
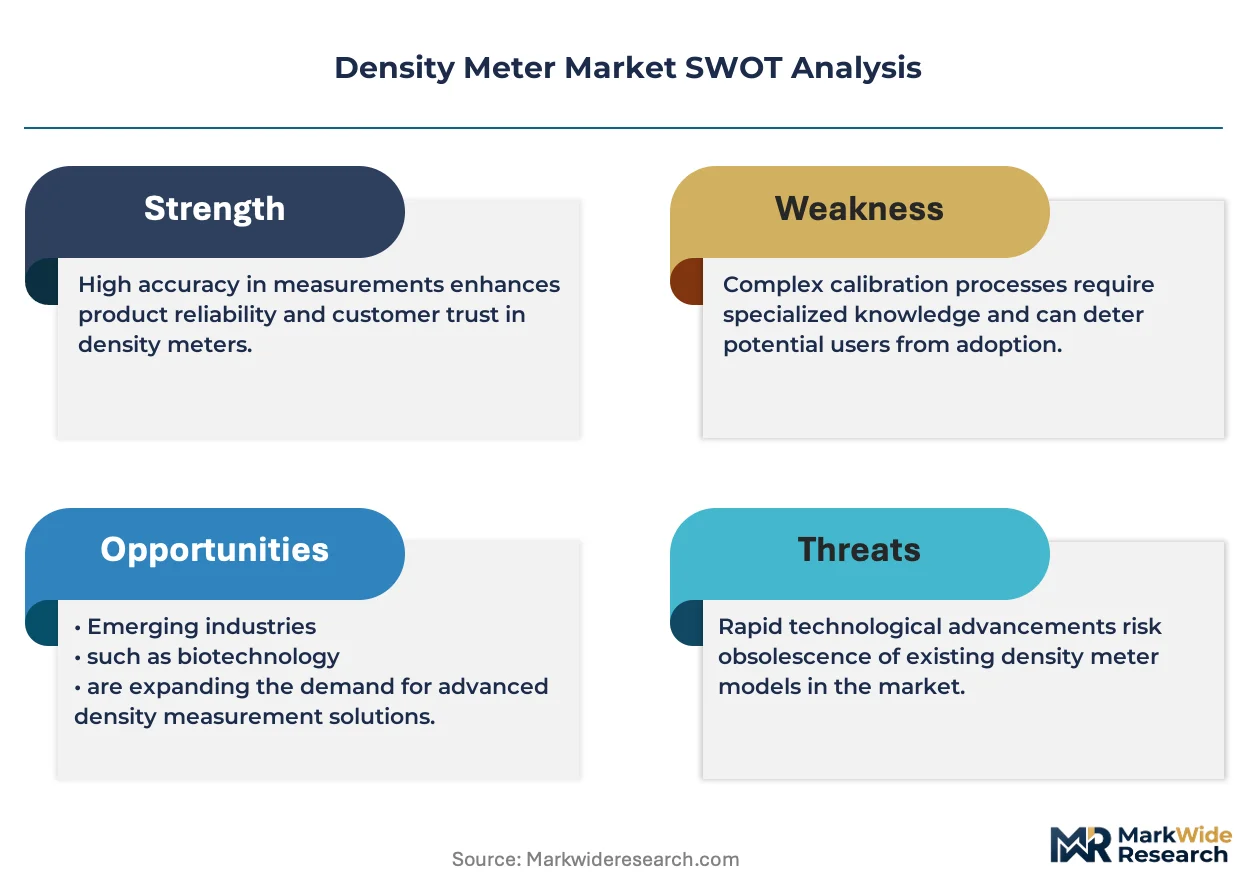
EPA effluent guidelines and FDA process analytical technology standards shape instrument validation protocols in the United States. CE marking under EU MDR and REACH substance restrictions govern European market access and material specifications. Stakeholders must monitor evolving cybersecurity requirements for networked process sensors as digital density meters proliferate on plant-floor Ethernet.
Market Dynamics
Digital density instrumentation is compressing the traditional divide between laboratory precision and inline process control, forcing vendors to recalibrate service architectures around real-time data monetization rather than hardware margins alone.
Growth Catalysts
- Oil and gas process monitoring:Refinery operators deploy inline oscillating U-tube sensors to eliminate offline sampling bottlenecks. Continuous measurement architectures reduce batch cycle times and quality deviation penalties.
- EPA effluent guidelines:Wastewater discharge monitoring mandates tighten calibration frequency requirements. Instrument service contracts extend average customer lifetime value through recurring validation protocols.
- Pharmaceutical PAT standards:FDA process analytical technology frameworks embed density measurement into active process control loops. Real-time release testing reduces quarantine inventory holding costs.
Market Restraints
- High-precision sensor material costs:Corrosion-resistant Hastelloy and titanium alloys for U-tube construction face price volatility from aerospace and chemical sector demand competition.
- Specialized technician scarcity:Nuclear densitometer installation and maintenance require certified radiation safety officers. Training pipeline constraints limit field service expansion velocity.
- Long replacement cycles:Industrial-grade inline meters operate 15-20 year lifespans. Hardware refresh revenue concentrates in greenfield capacity additions rather than installed base turnover.
Strategic Opportunities
- Biopharma single-use integration:Disposable manufacturing trains in mRNA and cell therapy production demand portable density verification at multiple unit operations. Validation-ready handheld units command premium positioning.
- EU Green Deal carbon accounting:Fuel blending accuracy requirements for renewable diesel and sustainable aviation fuel mandate precise density measurement. Inline verification supports mass-balance certification schemes.
- Edge computing convergence:On-sensor analytics packages reduce plant-floor network dependency. Localized diagnostics enable predictive maintenance without centralized SCADA infrastructure.
Industry Challenges
- Cybersecurity certification complexity:IEC 62443 industrial security standards for networked process sensors extend product development timelines. Multi-jurisdiction compliance testing fragments engineering resources.
- Legacy system integration friction:Brownfield facilities operate analog 4-20mA control architectures. Digital density meter retrofit projects require custom signal conditioning and validation protocol redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Density Meter Market |
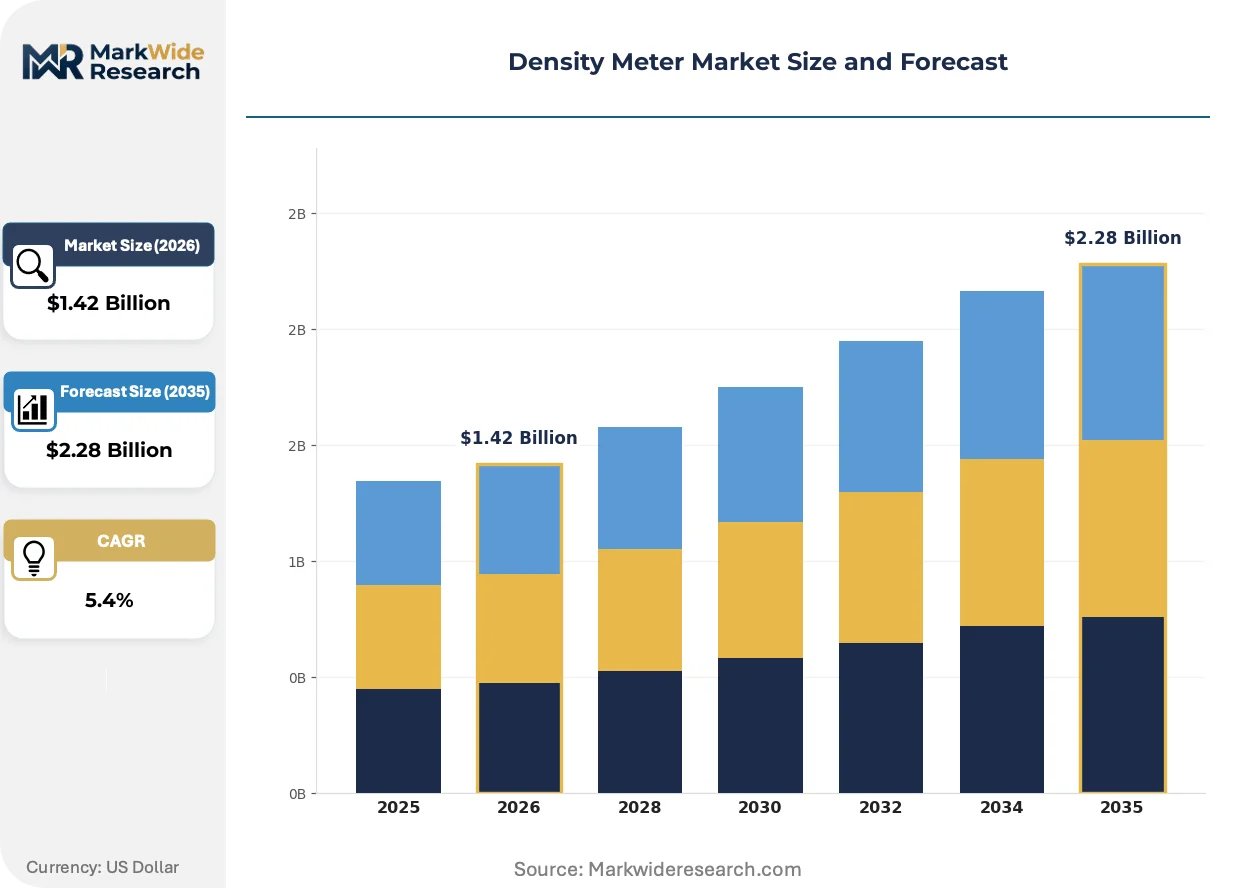
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Density Meters, Laboratory Density Meters, Inline Density Meters, Digital Density Meters End User: Food & Beverage, Chemicals, Oil & Gas, Pharmaceuticals Technology: Hydrometer, Ultrasonic, Vibrating Tube, Nuclear Application: Quality Control, Process Monitoring, Research & Development, Environmental Testing |
| Companies Covered | Endress+Hauser Group Services AG, Thermo Fisher Scientific, Anton Paar GmbH, KROHNE Messtechnik GmbH, Rudolph Research Analytical, Mettler-Toledo International Inc., Yokogawa Electric Corporation, VEGA Grieshaber KG, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Density Meter Market Emerging Trajectories
Sensor miniaturization and embedded analytics are dissolving the hardware-software boundary in density measurement, enabling new commercial models that monetize data continuity rather than instrument shipment.
MEMS-based resonant density sensors are collapsing the cost-performance tradeoff that historically separated laboratory and process-grade instrumentation. Food and beverage manufacturers adopt chip-scale units for in-tank monitoring at price points previously restricted to portable field devices. The technology is collapsing the traditional three-tier product architecture into a continuous capability spectrum.
EU MDR medical device regulation and REACH substance restrictions are tightening material traceability requirements for instruments contacting pharmaceutical and food streams. Manufacturers must document full supply chain provenance for wetted components. Laboratory-grade meter vendors in Germany and Switzerland are restructuring supplier qualification programs to maintain CE marking access.
Service unbundling is fragmenting the traditional instrument-plus-calibration bundle. End-users in upstream oil and gas procure hardware through capital budgets while contracting validation services separately to specialized third-party metrology firms. This purchasing pattern is most pronounced in the US Permian Basin and Gulf Coast refining corridors, where independent service providers compete with manufacturer captive networks.
Density Meter Market Segmentation
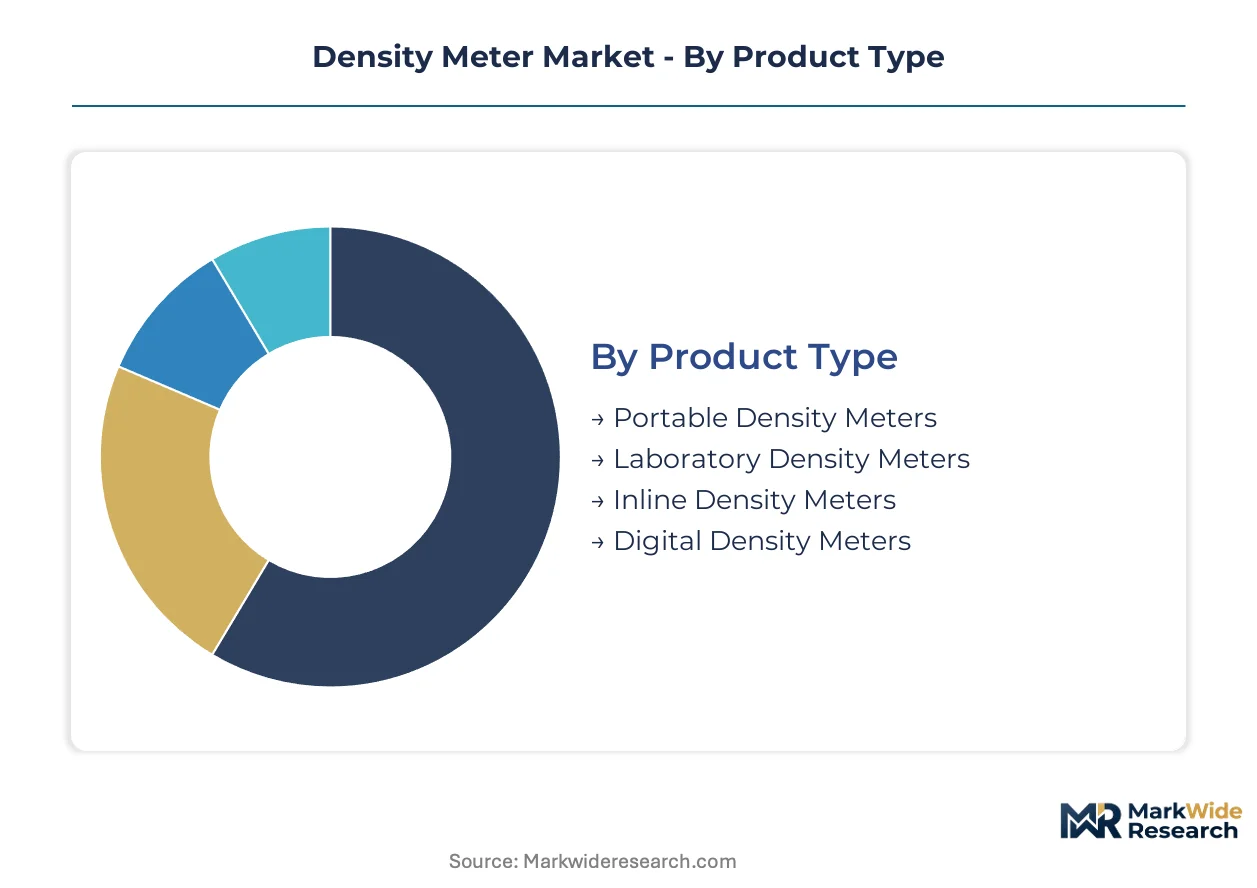
Density meter segmentation reveals how instrument architecture, deployment context, and measurement principle intersect to create distinct value pools. Vendors must align R&D investment with the precision-throughput tradeoffs that dominate each category's purchasing logic.
Product Type:
Mature inline systems anchor industrial process revenue while portable and digital formats reshape accessibility tiers for emerging applications.
- Portable Density Meters:Battery-powered handheld units deploy oscillating U-tube sensors in field environments where laboratory access is impractical. Upstream oil and gas operators in the Permian Basin and Gulf Coast corridors use these for rapid crude characterization at wellhead sampling points, though calibration drift in temperature-variable conditions limits accuracy to 0.001 g/cm³.
- Laboratory Density Meters:Benchtop instruments achieve 0.0001 g/cm³ precision through thermostatted measurement cells and automated sample handling. Pharmaceutical quality control laboratories in Germany and Switzerland dominate demand, driven by FDA process analytical technology validation requirements for drug substance release testing.
- Inline Density Meters:Continuous process integration with 4-20mA or digital Ethernet outputs enables real-time closed-loop control.
- Digital Density Meters:Embedded microprocessors enable on-sensor diagnostics and predictive maintenance algorithms.
Inline density meters handle the majority of throughput; digital density meters are gaining share fastest through edge analytics integration.
End User:
Application-specific regulatory burdens and batch economics create divergent purchasing patterns across verticals.
- Food & Beverage:In-tank monitoring for fermentation control and finished product standardization. Breweries and dairy processors in Belgium and the Netherlands deploy MEMS-based sensors for density-based alcohol and solids content verification.
- Chemicals:Corrosive fluid handling demands Hastelloy or titanium wetted components for acid and caustic concentration measurement. Petrochemical complexes along the US Gulf Coast and in Rotterdam anchor replacement demand for legacy nuclear densitometers facing decommissioning.
- Oil & Gas:Custody transfer and refinery process control applications.
- Pharmaceuticals:Bioprocess monitoring for cell culture density and purification yield optimization.
Oil and gas end users command the largest installed base; pharmaceutical applications are expanding most quickly through single-use manufacturing adoption.
Technology:
Measurement principle selection trades accuracy, maintenance burden, and capital cost against fluid compatibility requirements.
- Hydrometer:Glass float devices remain prevalent in educational settings and routine quality checks where 0.01 g/cm³ precision suffices. Food safety laboratories in India and Brazil retain significant manual hydrometer fleets for density-based Brix measurement in sugar and juice processing.
- Ultrasonic:Non-invasive clamp-on sensors measure acoustic impedance through pipe walls, eliminating wetted component compatibility concerns. Wastewater treatment facilities in China deploy these for sludge density monitoring under MEE effluent discharge enforcement.
- Vibrating Tube:Oscillating U-tube and fork designs dominate precision process applications.
- Nuclear:Gamma attenuation densitometers persist in extreme conditions including high pressure, high temperature, and abrasive slurries.
Vibrating tube technology carries the dominant revenue position; ultrasonic methods are climbing the fastest as non-invasive retrofit demand accelerates.
Application:
Deployment context determines whether instruments operate in episodic verification or continuous control architectures.
- Quality Control:Offline sample testing against specification limits governs batch release decisions. Pharmaceutical manufacturers in Ireland and Singapore run high-throughput density verification for imported active pharmaceutical ingredients under FDA and EMA mutual recognition protocols.
- Process Monitoring:Real-time measurement integration with distributed control systems enables immediate deviation correction. Refinery operators in Germany and the United States deploy inline sensors to minimize off-spec product generation and associated reprocessing costs.
- Research & Development:Method development and formulation characterization in laboratory settings.
- Environmental Testing:Effluent and emissions monitoring for regulatory compliance demonstration.
Process monitoring absorbs the greatest instrument volume; environmental testing is expanding most quickly through tightening effluent standards in China and the European Union.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laboratory-grade manufacturers command premium pricing power against Chinese process instrumentation suppliers, creating a bifurcated procurement landscape where precision certification and volume throughput occupy separate value tiers.
United States
Refinery operators along the Gulf Coast corridor deploy inline oscillating U-tube sensors for real-time crude characterization and custody transfer verification. EPA effluent guidelines under the Clean Water Act tighten calibration frequency mandates for wastewater discharge monitoring. Houston anchors the largest installed base of nuclear densitometers facing decommissioning pressure from radiation safety compliance costs.
Germany
Pharmaceutical quality control laboratories in Baden-Württemberg and Bavaria drive demand for benchtop instruments achieving 0.0001 g/cm³ precision under FDA process analytical technology frameworks. EU MDR medical device regulation and REACH substance restrictions tighten material traceability requirements for wetted components. The Rhine-Main industrial cluster concentrates validation-ready manufacturing for bioprocess monitoring applications.
China
Petrochemical complexes in the Yangtze River Delta and Shandong Peninsula expand inline instrument deployment for continuous process control. MEE effluent discharge enforcement accelerates ultrasonic clamp-on sensor adoption in wastewater treatment facilities. Shenzhen and Shanghai anchor domestic manufacturing capacity for MEMS-based resonant density sensors targeting food and beverage in-tank monitoring.
Switzerland
Precision instrument manufacturers in the Zurich-Basel corridor serve pharmaceutical and food safety laboratories requiring thermostatted measurement cells. Swissmedic and EMA mutual recognition protocols govern validation standards for active pharmaceutical ingredient release testing. The Swiss manufacturing base maintains supplier qualification programs restructuring around full supply chain provenance documentation.
India
Food safety laboratories in Maharashtra and Gujarat retain significant manual hydrometer fleets for density-based Brix measurement in sugar and juice processing. FSSAI standards gradually elevate metrology requirements for finished product standardization. The Mumbai-Pune industrial corridor attracts portable instrument deployment for field-based crude characterization at upstream oil and gas sampling points.
Density Meter Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and calibration protocols. The vendor base organizes around three strategic archetypes: full-stack instrumentation houses with captive service networks, precision-focused laboratory specialists leveraging manufacturing depth, and diversified industrial conglomerates extending process control portfolios. Competitive moves concentrate on strategic partnerships for edge analytics integration and geographic expansion through localized validation certification.
Among Swiss and German precision specialists, Anton Paar GmbH and Mettler-Toledo International Inc. exemplify the laboratory-grade tier where Austrian manufacturing depth and thermostatted measurement cell expertise anchor premium positioning. Endress+Hauser Group Services AG represents the full-stack archetype, leveraging captive service networks to sustain long-term calibration contracts. Thermo Fisher Scientific occupies a position extending life-sciences channel control into pharmaceutical density workflows.
| Leading Market Players |
|---|
| Endress+Hauser Group Services AG |
| Thermo Fisher Scientific |
| Anton Paar GmbH |
| KROHNE Messtechnik GmbH |
| Rudolph Research Analytical |
| Mettler-Toledo International Inc. |
| Yokogawa Electric Corporation |
| VEGA Grieshaber KG |
| Emerson Electric Co. |
| Others |
Supply Flow & Price Mechanics
Titanium and Hastelloy alloy price volatility from aerospace sector demand competition compresses margin structures across precision instrument tiers while simultaneously forcing geographic diversification in raw material sourcing. This input-cost uncertainty widens spreads between laboratory-grade certified units and process-grade alternatives while reshaping supplier qualification protocols in Germany and Switzerland.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA process analytical technology certification tier and volume scale, with pharmaceutical quality control laboratories in Baden-Württemberg showing lowest sensitivity. Cost compression in the portable field-device tier is intensifying because MEMS-based resonant sensors collapse historical cost-performance tradeoffs.
Supply Chain Analysis
Extended payment terms from Austrian and German precision manufacturers to specialty alloy suppliers in Japan and the United States reveal working capital pressures throughout upstream tiers. Corrosion-resistant U-tube materials and thermostatted measurement cell components draw from concentrated metallurgical capacity in Austria, Germany, and Japan. Single-source vulnerability in titanium sponge processing creates exposure to export restriction shifts. Distribution runs through captive service networks for calibration-intensive laboratory units and third-party industrial distributors for process-grade hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS sensor miniaturization and embedded edge analytics constitute a technological inflection compressing the laboratory-process precision divide, creating white-space for platform-native entrants while threatening hardware-margin dependency among incumbents.
For Market Incumbents: Harden calibration service contract retention through predictive maintenance algorithm deployment and captive technician certification programs. Nuclear densitometer decommissioning pressure from radiation safety compliance costs threatens installed base revenue; backward integration into MEMS resonant sensor fabrication secures cost positioning against emerging chip-scale competitors. For New Entrants and Emerging Players: Build out validation-ready handheld units targeting single-use biopharma manufacturing trains in mRNA and cell therapy production. The portable density verification segment at multiple unit operations offers lowest incumbent saturation. Pursue direct partnerships with contract development and manufacturing organizations to bypass established channel control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-specialist acquisition targets with FDA and EMA mutual recognition protocol certifications. Five-to-ten year viability hinges on data monetization capability transition. Watch for edge computing convergence adoption rates in brownfield refinery retrofit projects as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensor Platform Integration | Chip-scale resonant technology collapses cost-performance boundaries between laboratory and process grades. |
| Predictive Maintenance Algorithm Development | On-sensor diagnostics enable recurring service revenue independent of hardware refresh cycles. |
| FDA PAT Certification Investment | Process analytical technology validation opens pharmaceutical quality control laboratory procurement channels. |
| Single-Use Biopharma Partnership | Disposable manufacturing train integration addresses fastest-expanding pharmaceutical application segment. |
| Edge Computing Convergence | Localized diagnostics reduce plant-floor network dependency for brownfield facility retrofit demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery process control engineers, pharmaceutical quality control laboratory managers, calibration service technicians, and MEMS sensor R&D directors. Secondary validation drew from FDA process analytical technology guidance documents, EPA effluent guideline enforcement records, EMA mutual recognition protocol filings, and customs trade data for precision instrument categories. Bottom-up instrumentation shipment estimates and top-down process industry capital expenditure patterns were triangulated against reported vendor revenue disclosures.
Calibration against historical instrument replacement cycles and regulatory compliance spending patterns shaped projections across the analysis window. Segmentation dimensions modeled include product architecture, measurement principle, end-use vertical, and geographic regulatory cluster. CAGRs were derived from regression analysis of correlated process industry output and environmental enforcement intensity metrics. Forecast inputs incorporated petrochemical capacity expansion pipelines and pharmaceutical single-use manufacturing adoption curves.
Stress conditions across titanium alloy price volatility, radiation safety officer training pipeline constraints, and cybersecurity certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and process automation capital allocation priorities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Structure Tester Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Global NVH Testing Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Tribometer Market
Test and Measurement
Ethernet Test Equipment Market