
 India CRNO Steel Lamination Market | 2026-2036
India CRNO Steel Lamination Market Size, Share, and Industry Trends Forecast 2026-2036
India CRNO Steel Lamination Market Outlook
Multi-source procurement for CRNO steel is expanding across India's transformer OEMs as domestic mills scale capacity. Tata Steel Limited leverages integrated blast furnace operations to secure consistent silicon steel output. Jindal Steel & Power Ltd. anchors its position through captive iron ore access and downstream cold-rolling investments. Steel Authority of India Limited (SAIL) competes on volume across public sector electrification tenders.
Cold rolled non-oriented (CRNO) electrical steel contains silicon additions of 1-3% with carefully controlled grain structure to minimize hysteresis and eddy current losses in rotating machinery and static apparatus. The material undergoes continuous annealing after cold reduction to develop isotropic magnetic properties essential for motors operating under varying flux directions. Transformer applications within the Application segment command the deepest specification requirements and longest qualification cycles with utilities. Motor applications are accelerating faster as IE4 and IE5 efficiency regulations propagate through India's industrial base, pulling premium CRNO grades from standard offerings.
BIS mandates core loss limits aligned with IEC 60404-8-4 while CEA distribution standards enforce efficiency thresholds for new transformer installations. The PLI scheme for specialty steel provides production-linked incentives that reshape domestic CRNO capacity economics. Stakeholders must monitor BIS amendment timelines and state utility tender specifications to anticipate grade-mix shifts before capacity commitments crystallize.
Market Dynamics
The PLI scheme for specialty steel is restructuring domestic CRNO capacity economics as integrated mills commit to cold-rolling investments and captive silicon steel output. BIS certification mandates for core loss specifications are tightening qualification cycles, forcing transformer OEMs to consolidate supplier bases around certified domestic sources.
Growth Catalysts
- CEA Distribution Standards:Mandatory efficiency thresholds for new transformer installations are pulling high-grade CRNO laminations into distribution infrastructure upgrades across state utilities.
- Maharashtra-Gujarat Manufacturing Clusters:Concentrated transformer OEM activity in western India generates localized demand density that reduces logistics costs and accelerates order cycles.
- IE4 and IE5 Motor Regulations:Industrial efficiency mandates are displacing standard electrical steel grades with premium CRNO specifications in compressor and pump motor applications.
Market Restraints
- Silicon Metal Price Volatility:Input cost swings for the 1-3% silicon addition in CRNO steel compress margin predictability for cold-rolling operations.
- Domestic Mill Concentration:Three integrated producers control the bulk of qualified CRNO output, creating supply bottleneck risk during tender surge periods.
- Grain-Oriented Steel Substitution:Distribution transformer manufacturers in cost-sensitive segments evaluate GO steel alternatives for lower-loss core designs.
Strategic Opportunities
- Eastern India Grid Expansion:West Bengal and Odisha renewable integration projects require upgraded distribution infrastructure with qualified CRNO cores.
- Amorphous Metal Convergence:Hybrid core designs combining CRNO with amorphous ribbon layers enable next-generation loss performance for premium transformer tiers.
- PLI Scheme Capacity Additions:Production-linked incentives for specialty steel are enabling domestic mills to commission dedicated electrical steel cold-rolling lines.
Industry Challenges
- BIS Amendment Tracking:Evolving core loss specifications require continuous reformulation and requalification, extending product development timelines.
- Continuous Annealing Line Capex:Isotropic magnetic property development demands furnace investments that strain mid-scale mill balance sheets.
- Utility Tender Specification Fragmentation:State-by-state procurement standards complicate national scale production planning for CRNO suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India CRNO Steel Lamination Market |
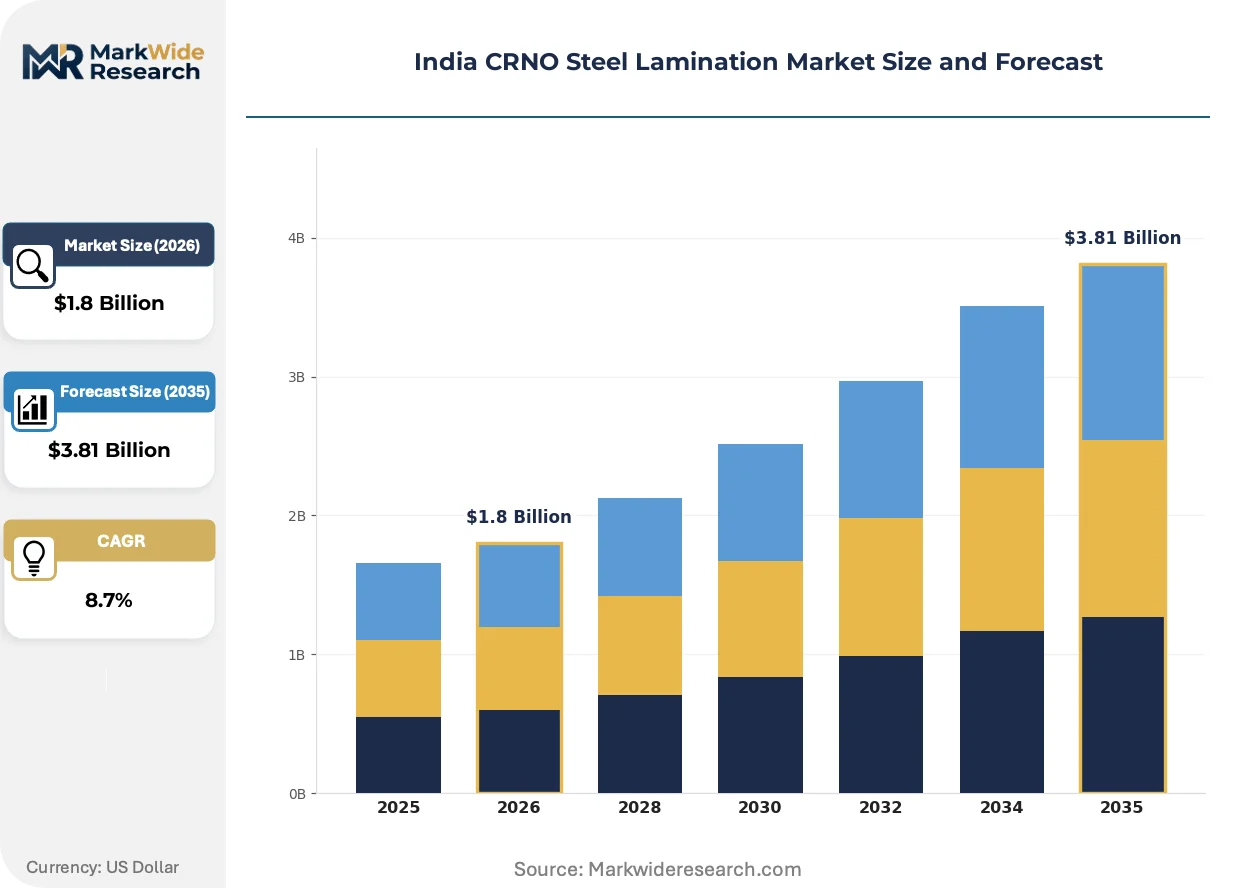
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Steel, Cold Rolled Steel, Hot Rolled Steel, Laminated Steel End User: Automotive, Energy, Industrial, Electronics Application: Transformers, Motors, Generators, Inductors Manufacturing Stage: Raw Material, Processing, Assembly, Quality Control |
| Companies Covered | Electrosteel Steels Ltd., Uttam Galva Steels Ltd., Jindal Steel & Power Ltd., A. P. Steel Processing & Services Pvt. Ltd., Asian Electric Company, Tata Steel Limited, Shyam Ferro Alloys Ltd., Eastern Steel Industries, Steel Authority of India Limited (SAIL), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India CRNO Steel Lamination Market Strategic Shifts
Transformer core design is converging with digital manufacturing and advanced materials to compress loss coefficients while expanding domestic production autonomy. Three developments are restructuring competitive positioning in India's electrical steel value chain.
Thin-gauge CRNO steel is modularizing transformer core construction through precision-slit lamination geometries that reduce eddy current losses. Distribution transformer OEMs in Gujarat are adopting 0.23mm and 0.27mm gauges for new IE3-compliant designs. The technology is modularizing core assembly workflows, enabling smaller fabricators to compete on loss performance without integrated steelmaking.
BIS alignment with IEC 60404-8-4 is tightening maximum core loss limits for CRNO grades used in public sector tenders. The amendment trajectory is disqualifying non-compliant imports and redirecting procurement toward domestic certified mills. Maharashtra utilities are embedding the stricter specifications into 11kV distribution transformer tenders ahead of national mandate timelines.
Multi-year procurement contracts are displacing spot purchasing as transformer OEMs secure silicon steel allocations against tender volatility. State electricity boards are consolidating annual CRNO requirements into single-source agreements with mill-direct supply. The shift is most visible in western India, where Maharashtra and Gujarat utilities anchor demand through centralized purchasing cells.
India CRNO Steel Lamination Market Segmentation
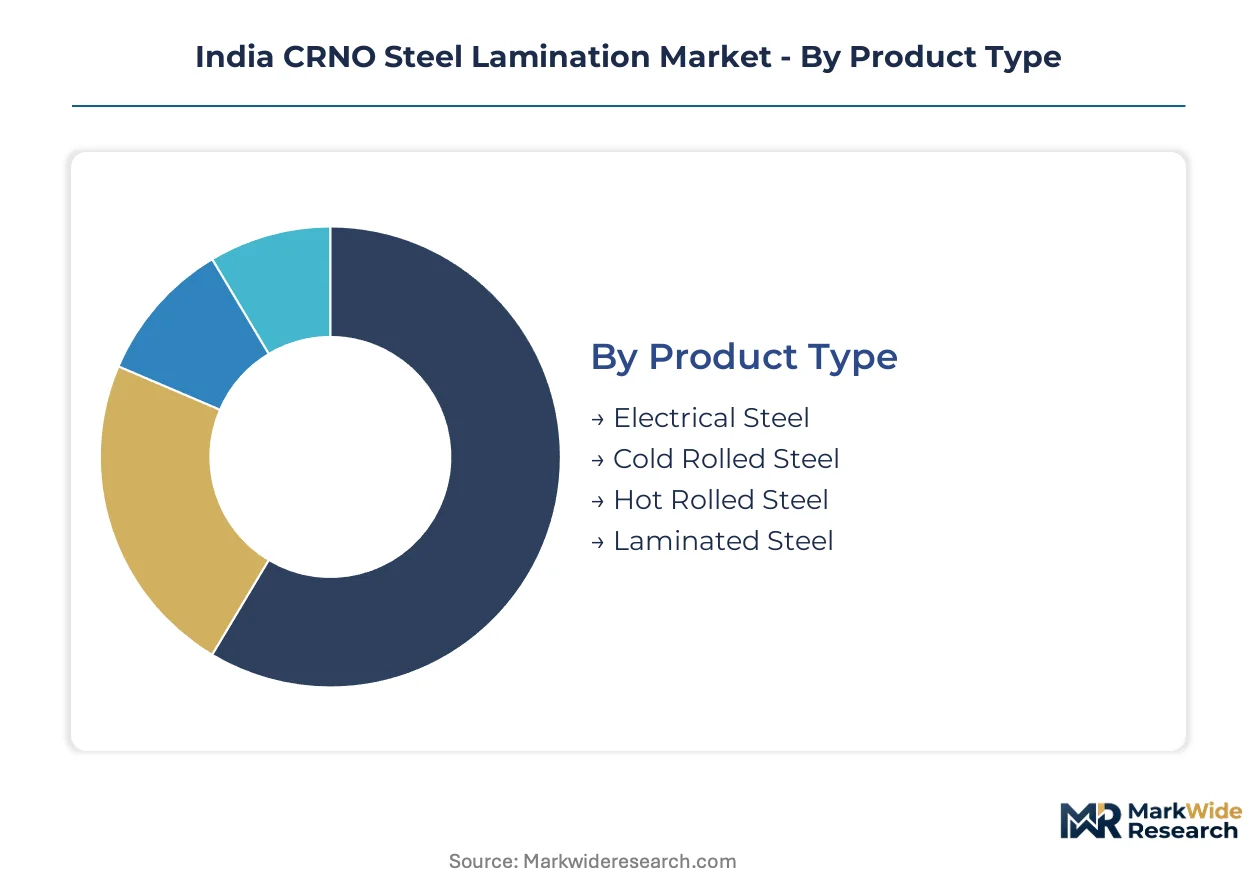
CRNO steel procurement patterns in India diverge sharply across application tiers and manufacturing stages. Each segment exhibits distinct qualification cycles, specification intensity, and supplier consolidation dynamics that reshape competitive positioning.
Product Type:
Domestic mill capacity concentrates around silicon-alloyed grades with tight hysteresis control, leaving commodity flat-rolled products import-dependent.
- Electrical Steel:Silicon-alloyed grades with 1-3% Si content undergo continuous annealing to develop isotropic magnetic properties. Maharashtra transformer OEMs anchor demand for high-permeability specifications as CEA efficiency mandates tighten core loss thresholds.
- Cold Rolled Steel:Precision-thickness strip delivers dimensional tolerances critical for stacked core geometries. Gujarat motor manufacturers are pulling premium CRNO grades for IE4 and IE5 efficiency compliance in compressor and pump applications.
- Laminated Steel:Pre-slit coil formats reduce fabricator processing steps and scrap rates. Demand clusters around tier-2 transformer workshops in western India seeking modular core assembly inputs.
- Hot Rolled Steel:Feedstock for downstream cold-rolling lines with less stringent magnetic property requirements. SAIL and integrated mills control captive supply for internal electrical steel conversion.
Today's leader: Electrical Steel. Tomorrow's challenger: Cold Rolled Steel.
End User:
Cost tier differentiation separates specification-intensive utility procurement from price-sensitive industrial motor sourcing.
- Energy:State electricity boards and renewable developers command the deepest qualification cycles and longest tender horizons. BIS-certified CRNO grades are mandatory for 11kV distribution transformers under CEA distribution standards.
- Industrial:Motor OEMs and compressor manufacturers drive volume throughput with faster order cycles. IE4 efficiency regulations are displacing standard electrical steel with premium CRNO specifications across pump and fan motor lines.
- Automotive:Traction motor laminations for electric mobility applications require ultra-thin gauge CRNO with specialized insulation coatings. The segment is expanding most quickly as domestic EV production scales.
- Electronics:Small-core inductor and choke applications consume narrow-width slit coils. Demand fragments across job-shop fabricators with limited volume concentration.
Energy commands margin premiums. Industrial delivers volume scale.
Application:
Volume concentration tilts toward static apparatus, though rotating machinery is gaining specification intensity.
- Transformers:Distribution and power transformer cores absorb the bulk of qualified CRNO output. Core loss specifications under BIS-IEC alignment are disqualifying non-certified imports from public sector tenders.
- Motors:Industrial efficiency mandates are accelerating premium grade displacement of standard electrical steel. IE5 readiness is pulling 0.23mm and 0.27mm thin-gauge CRNO into next-generation motor designs.
- Generators:Utility-scale and captive power applications require high-permeability laminations with controlled grain structure. Qualification cycles mirror transformer specifications but with lower tender frequency.
- Inductors:Power electronics and renewable integration hardware consume specialized slit-width coils. The segment trails in volume but leads in gauge diversification requirements.
Transformers anchor procurement planning. Motors are climbing the fastest.
Manufacturing Stage:
Backward integration incentives under the PLI scheme are reshaping where value capture concentrates across the CRNO value chain.
- Raw Material:Silicon metal and hot-rolled coil supply concentrate among integrated steel producers. Captive iron ore and blast furnace operations at Tata Steel and JSPL secure input cost predictability.
- Processing:Cold-rolling, annealing, and coating operations constitute the technical bottleneck. Continuous annealing line investments strain mid-scale mill balance sheets despite PLI scheme support.
- Assembly:Core stacking and winding operations fragment across transformer OEMs and job-shop fabricators. Gujarat and Maharashtra clusters exhibit deepest specialization.
- Quality Control:BIS certification and core loss testing create qualification barriers that consolidate supplier bases. State utility tender specifications embed testing protocols that extend product development timelines.
Processing commands technical barriers. Quality Control determines market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat manufacturing clusters concentrate transformer OEM activity, generating localized demand density that reduces logistics costs and accelerates order cycles for CRNO steel laminations. Western India anchors procurement volumes while eastern states expand grid infrastructure.
Maharashtra
State electricity boards command the deepest qualification cycles for distribution transformer cores. CEA distribution standards enforce mandatory efficiency thresholds for new installations. Mumbai-Pune industrial corridor hosts concentrated transformer OEM activity scaling orders for high-efficiency core materials.
Gujarat
Industrial motor manufacturers drive volume throughput with faster order cycles for IE4 and IE5 compliance. BIS certification mandates for core loss specifications tighten material requirements statewide. Ahmedabad-Vadodara belt exhibits deepest specialization in modular core assembly workflows.
West Bengal
Renewable energy integration projects require upgraded distribution infrastructure with qualified CRNO cores. PLI scheme for specialty steel provides production-linked incentives reshaping regional capacity economics. Kolkata-Howrah industrial zone attracts cold-rolling investments from integrated mills.
Karnataka
Electric mobility applications pull ultra-thin gauge CRNO for traction motor laminations. State utility tender specifications embed BIS testing protocols extending product development timelines. Bengaluru-Tumkur corridor expands precision-slit lamination capacity for automotive-grade outputs.
Tamil Nadu
Power electronics and renewable integration hardware consume specialized slit-width coils for inductor applications. Continuous annealing line investments strain mid-scale mill balance sheets despite incentive support. Chennai-Sriperumbudur industrial belt diversifies gauge offerings for electronics fabricators.
India CRNO Steel Lamination Market Competitive Environment
Global majors compete with regional champions across certification tiers, with domestic integrated mills anchoring supply against import-dependent fabricators. Three integrated producers control qualified CRNO output, creating supply bottleneck risk during tender surge periods. Strategic archetypes include blast furnace-integrated steelmakers, cold-rolling specialists with captive silicon supply, and transformer OEMs with backward integration into lamination processing. Capacity expansion and strategic partnerships constitute dominant competitive moves as mills secure silicon metal allocations and OEMs consolidate supplier bases.
Within the integrated steelmaker tier, Tata Steel Limited and Jindal Steel & Power Ltd. exemplify archetypes combining captive iron ore access with downstream electrical steel investments. Steel Authority of India Limited occupies a position representing public sector volume concentration across electrification tenders. These three anchors sit within a structure where BIS certification barriers consolidate procurement around qualified domestic sources, disqualifying non-compliant imports from state utility tenders.
| Leading Market Players |
|---|
| Electrosteel Steels Ltd. |
| Uttam Galva Steels Ltd. |
| Jindal Steel & Power Ltd. |
| A. P. Steel Processing & Services Pvt. Ltd. |
| Asian Electric Company |
| Tata Steel Limited |
| Shyam Ferro Alloys Ltd. |
| Eastern Steel Industries |
| Steel Authority of India Limited (SAIL) |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap transformer fabricators in Gujarat and Maharashtra anchor procurement volumes through multi-year offtake agreements with integrated mills, compressing spot-market liquidity and hardening price discipline for BIS-certified grades. This ownership pattern concentrates bargaining power among three domestic steel producers while fragmenting downstream negotiation leverage.
Pricing Analysis
Silicon metal price pass-through clauses dominate CRNO steel contracts, with quarterly adjustments tethering lamination costs to ferroalloy exchange movements. Contract-based long-term offtake structures prevail across state electricity board tenders, though spot purchasing persists for job-shop fabricators with irregular order cycles. Price differentiation rests on BIS certification tier and volume scale, with certified mills commanding premiums over import alternatives. Cost compression in standard-grade CRNO is intensifying because grain-oriented steel substitutes erode share in distribution transformer tiers. Industrial motor OEMs exhibit highest price sensitivity due to thin margins on IE4 and IE5 compliance, while energy utilities absorb premiums for guaranteed core loss performance.
Supply Chain Analysis
Single-source vulnerability sits with China's dominance in silicon metal refining, where three smelter groups control export pricing for the 1-3% silicon addition essential to CRNO chemistry. Domestic supply draws from captive blast furnace operations at Tata Steel and JSPL, with hot-rolled coil feedstock anchored in Jharkhand and Odisha iron ore basins. Raw material dependencies rest on metallurgical-grade silicon, high-purity iron ore, and specialized rolling mill rolls. Tariff exposure on silicon metal imports constitutes the primary structural risk, compounded by logistics chokepoints at Mumbai and Mundra ports. Distribution runs through mill-direct supply to transformer OEMs, with secondary channels serving tier-2 fabricators via steel service centers in Ahmedabad and Pune.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India CRNO Steel Lamination Market functions as a stable compounder, with CEA distribution standards and renewable integration mandates ensuring sustained procurement velocity regardless of industrial cyclicality.
For Market Incumbents: Anticipate amorphous metal hybrid cores displacing premium CRNO tiers in ultra-high-efficiency transformer segments, and respond by deepening backward integration into continuous annealing capacity in eastern India. Certification investment against forthcoming BIS amendments represents the critical defensive lever, as non-compliant mills face disqualification from public sector tenders. Channel control through exclusive supply agreements with Maharashtra and Gujarat utilities hardens switching costs for challenger mills. For New Entrants and Emerging Players: The price-point gap between BIS-certified premium grades and uncertified import alternatives creates entry space for cold-rolling specialists who secure silicon supply partnerships. Eastern India grid expansion offers the most penetrable geography, with West Bengal and Odisha renewable projects requiring qualified CRNO cores absent established supplier relationships. A go-to-market angle anchored on modular core assembly services for tier-2 transformer workshops bypasses direct mill competition. For Investors and Strategic Acquirers: Integrated transformer OEMs with captive lamination operations are the most active acquirer in this space, seeking to secure silicon steel allocations against tender volatility. The five-to-ten-year viability window favors targets with BIS-certified cold-rolling lines and established utility procurement relationships. The signal to watch is PLI scheme disbursement velocity, as delayed incentive realization would strain balance sheets at mid-scale mills and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Continuous Annealing | Captive annealing capacity at JSPL and Tata Steel insulates core loss consistency from third-party bottlenecks. |
| BIS Certification Pre-Positioning | Early alignment with IEC 60404-8-4 amendments secures qualification for CEA-mandated transformer tenders. |
| Multi-Year Supply Agreement | Maharashtra utilities anchor procurement through centralized purchasing cells, reducing spot price exposure. |
| Thin-Gauge Capacity Addition | 0.23mm and 0.27mm rolling lines enable IE5 motor compliance and premium tier access. |
| Eastern India Geographic Expansion | West Bengal renewable integration projects require qualified CRNO cores with limited incumbent presence. |
Study Parameters
Direct dialogue with transformer OEM procurement heads, steel mill technical directors, state electricity board tender officers, and BIS certification auditors grounded qualitative findings, validated against customs trade data, SAIL and Tata Steel annual disclosures, CEA distribution standard notifications, and PLI scheme administrative records. Bottom-up volume estimates from individual mill capacity announcements triangulated with top-down demand projections derived from state utility capital expenditure plans.
Top-down macro assumptions on renewable integration targets and distribution infrastructure replacement cycles anchored the analytical lens, segmented by application tier, end-user vertical, and regional manufacturing cluster. CAGRs were derived from regression against historical tender volumes and projected equipment procurement schedules, with silicon price elasticity and BIS amendment timelines as key industry-specific inputs across the modeling period.
The model assumes a particular technology adoption path; alternative pathways for amorphous metal core designs would alter the outlook if cost curves compress faster than projected. Forecasts reflect assumptions on PLI scheme continuation and CEA efficiency mandate enforcement, with silicon metal supply disruption or tariff regime shifts as primary revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Beryllium Hydroxide Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Zinc Citrate Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
Chromite Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Lithium Ingots Market