
 Compact Excavator Market | 2026-2036
Compact Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Excavator Market Analytics
Steel-to-composite experimentation in canopy and hood assemblies is broadening the cost-performance envelope for compact excavator OEMs. Caterpillar leverages captive casting capacity and global dealer density to sustain pricing power in the premium crawler segment. Yanmar anchors its position through proprietary engine integration that narrows the power-to-weight gap against larger-class machines.
A compact excavator denotes a tracked or wheeled earthmoving machine with an operating weight below 6 metric tons, typically employing a boom-swing-house configuration with hydraulic auxiliary circuits for attachments such as augers, grapples, or breakers. The equipment serves primarily in confined-space excavation, trenching, and material handling where full-size excavators cannot maneuver or where transport weight limits apply. Mini excavators dominate unit volume across rental fleets and independent contractor garages, while wheeled variants command higher margins in European road-maintenance and urban utility applications where rubber-tired mobility eliminates track wear on paved surfaces. Diesel technology still occupies the majority of installed base, though electric and hybrid architectures are carving share in noise-restricted municipalities and indoor demolition settings.
EPA Tier 4 Final and the EU F-Gas Regulation constrain engine emissions and refrigerant choices, forcing redesign cycles that favor cleaner-burning or electrified powertrains. Japan's METI energy-efficiency benchmarks and the CE marking machinery directive collectively shape which configurations gain market access across North America, Europe, and Asia. Stakeholders must weigh capital allocation between diesel refinement and electric platform development as regulatory thresholds tighten unevenly across jurisdictions.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing diesel engine architectures while forcing OEMs to accelerate hybrid and electric platform development. Steel-to-composite experimentation in canopy assemblies is simultaneously lowering unit costs and expanding the addressable contractor base.
Growth Catalysts
- Urban Utility Infrastructure:Sub-6-ton machines penetrate tighter job sites where full-size excavators cannot maneuver. Municipal contractors in Japan and the United States are expanding compact fleets for trenching and fiber-optic cable installation.
- REACH and F-Gas Regulation:European refrigerant constraints and machinery directives favor cleaner-burning powertrains. OEMs redesign cooling systems to comply, opening certification pathways for electrified variants.
- Steel-to-Composite Substitution:Canopy and hood assemblies employing polymer composites reduce transport weight. This material shift enables trailer-hauling without commercial licensing in several jurisdictions.
Market Restraints
- Engine Cost Inflation:After-treatment systems for Tier 4 Final compliance add substantial cost to diesel powertrains. These input cost pressures compress margins on sub-3-ton units where price sensitivity concentrates.
- Japanese Production Concentration:Kubota and Komatsu anchor domestic manufacturing and export capacity. Supply disruption risk concentrates in earthquake-prone industrial corridors around Osaka and Nagoya.
- Battery Energy Density Limitations:Current lithium-ion configurations cannot match diesel runtime for continuous digging cycles. This technical ceiling restricts electric adoption in heavy-duty demolition and quarry applications.
Strategic Opportunities
- Indoor Demolition Vertical:Zero-emission excavators access noise-restricted municipalities and enclosed structures. Building renovation contractors in Germany and the Netherlands are specifying electric machines for asbestos abatement projects.
- IRA Clean Energy Credits:United States infrastructure incentives subsidize electrified construction equipment procurement. Fleet operators can offset platform development costs through federal tax mechanisms.
- Telematics-Rental Convergence:IoT-enabled hour-metering and predictive maintenance integrate with short-term rental platforms. Equipment-sharing marketplaces in France and the United Kingdom are embedding these tracking systems.
Industry Challenges
- High-Voltage Technician Scarcity:Electric powertrain servicing demands certified electricians with automotive battery experience. OEM service networks face recruitment gaps in rural dealer territories.
- Dual-Certification Timelines:CE marking and EPA compliance require parallel testing protocols. Product launch schedules stretch as engineering teams sequence validation runs for divergent regulatory frameworks.
- Legacy Hydraulic Attachment Compatibility:Electric machines must interface with existing breaker and auger fleets. Proprietary coupler designs fragment the aftermarket and complicate fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Excavator Market |
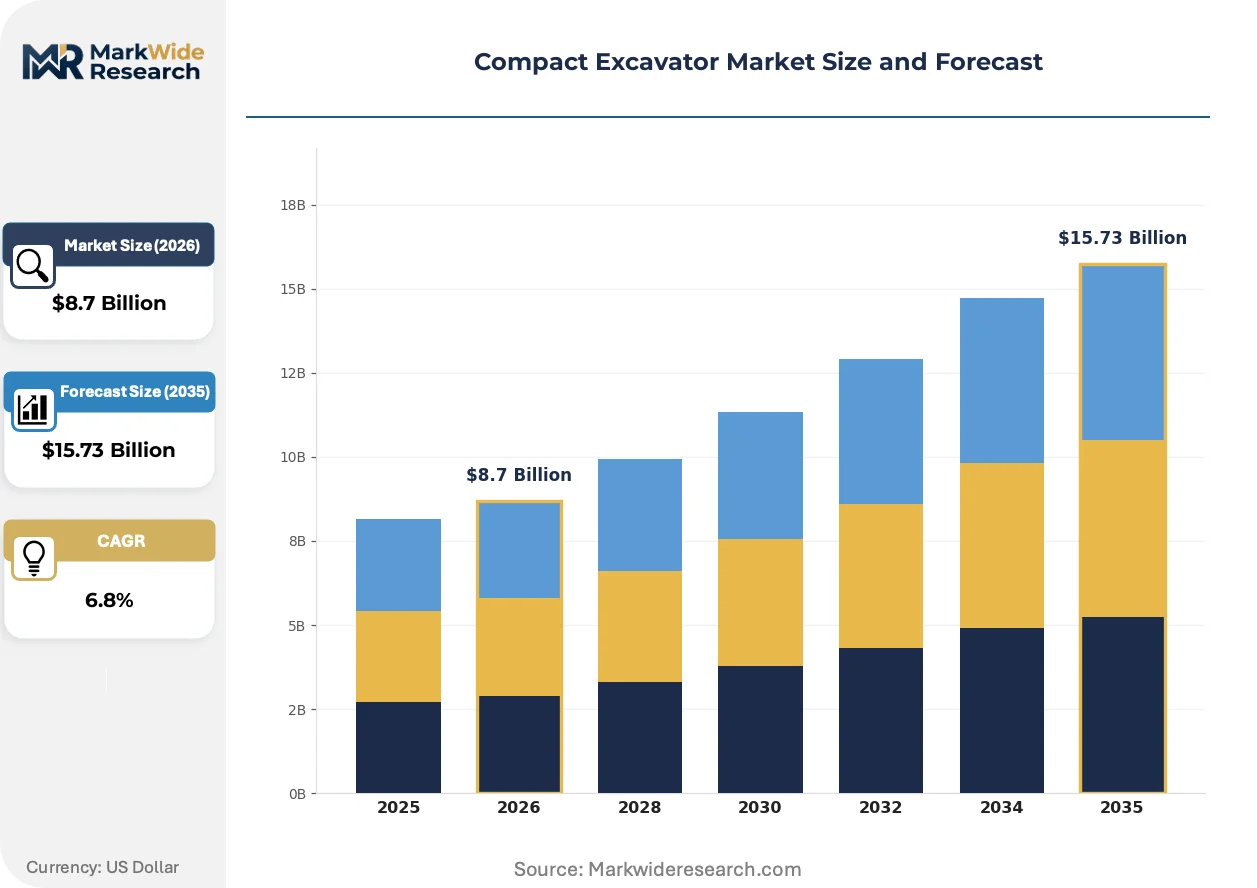
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Micro Excavators, Crawler Excavators, Wheeled Excavators End User: Construction, Landscaping, Agriculture, Demolition Technology: Hydraulic, Electric, Hybrid, Diesel Application: Site Preparation, Utility Installation, Material Handling, Road Maintenance |
| Companies Covered | Kubota Corporation, Caterpillar, Bobcat (Doosan Bobcat), Komatsu Ltd., JCB, John Deere, Takeuchi, Yanmar, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Excavator Market Evolving Landscape
Powertrain electrification is compressing the traditional diesel-hybrid-electric transition timeline. Regulatory thresholds are tightening unevenly across jurisdictions, while procurement behaviors fragment between ownership and subscription models.
Lithium-ion battery packs with thermal management systems are electrifying the sub-3-ton product tier. Indoor demolition contractors in Amsterdam and Tokyo are specifying these configurations for asbestos removal and basement excavation where ventilation is constrained. This technology is electrifying competitive positioning as OEMs without electric platforms face exclusion from municipal procurement lists.
The EU F-Gas Regulation constrains hydrofluorocarbon refrigerants in operator cab climate systems. Equipment manufacturers must redesign HVAC architectures using natural refrigerants or sealed electric compressors. European road-maintenance fleets are absorbing these compliance costs fastest, while North American exporters face retrofit burdens to maintain CE market access.
Rental penetration is accelerating among independent contractors who prioritize fleet flexibility over capital deployment. United States equipment-sharing platforms and European dealer rental pools are displacing traditional ownership models in urban construction verticals. Japan's aging contractor demographic is driving this behavioral shift most visibly, as succession planning favors asset-light operating structures.
Compact Excavator Market Segmentation
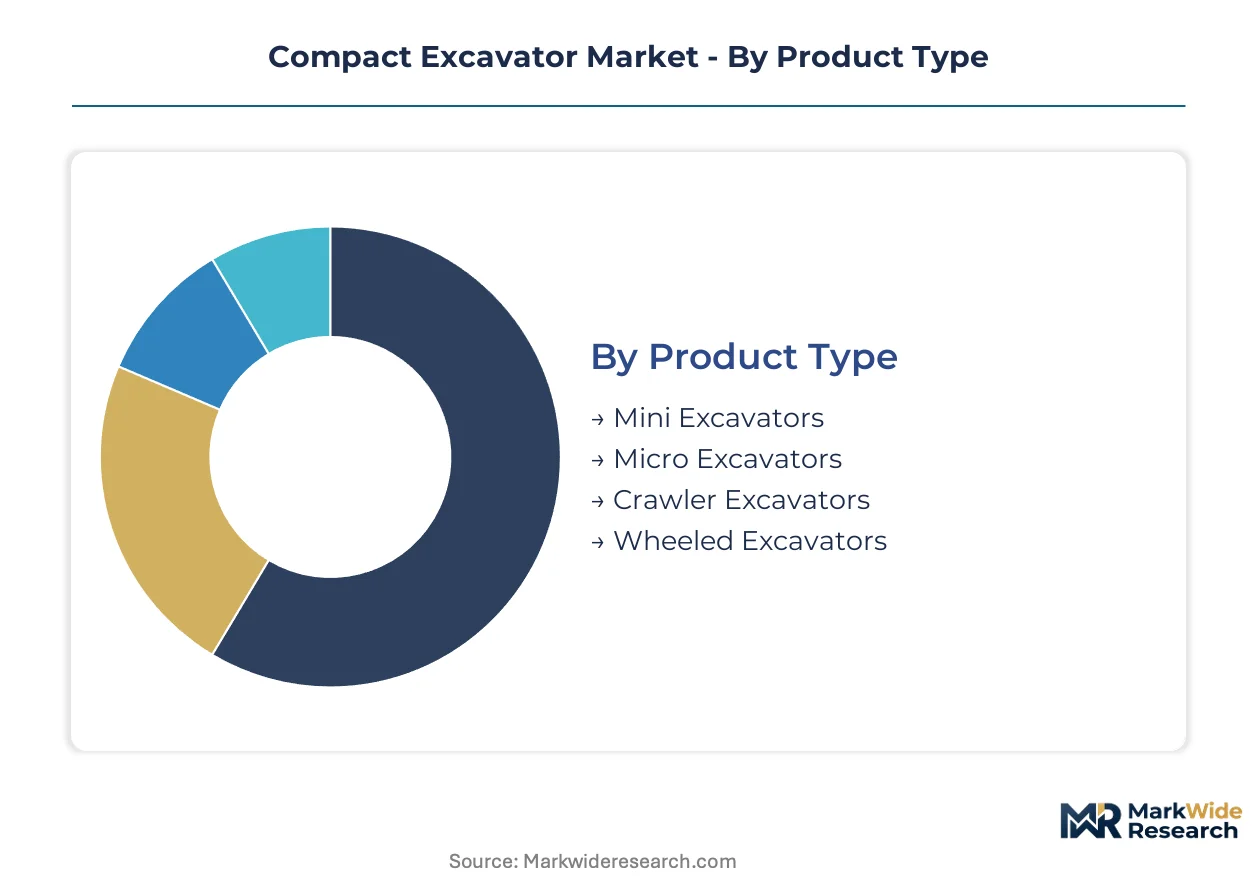
Equipment replacement cycles in compact excavators vary dramatically by segment, with fleet operators timing upgrades to coincide with emissions regulation phases and attachment compatibility refreshes. Segmentation reveals where capital allocation concentrates and which technology transitions command premium pricing.
Product Type:
Upgrade cycles differ sharply across product configurations, with weight-class thresholds triggering trailer licensing requirements that accelerate replacement decisions.
- Mini Excavators:Operating weights between 1.5 and 6 metric tons dominate rental fleet procurement in the United States and Japan. Municipal contractors in Tokyo and Osaka specify these for fiber-optic trenching where transport weight limits apply.
- Micro Excavators:Sub-1.5-ton machines access interior demolition and basement excavation. Amsterdam building renovators deploy these for asbestos abatement where ventilation systems cannot support diesel exhaust.
- Crawler Excavators:Tracked undercarriage configurations deliver stability on uneven terrain. German road-maintenance fleets absorb higher operating costs for traction performance on unpaved surfaces.
- Wheeled Excavators:Rubber-tired mobility eliminates track wear on paved surfaces. European urban utility contractors pay margin premiums for road-speed travel between job sites.
Volume placements concentrate in Mini Excavators; the faster expansion belongs to Micro Excavators.
End User:
Customer-type economics determine attachment specification depth and service contract attachment rates.
- Construction:General contractors drive standardization around quick-coupler systems. United States infrastructure projects specify Tier 4 Final or electric machines for federal compliance.
- Landscaping:Seasonal demand patterns favor rental over ownership. Independent operators in France and the United Kingdom prioritize hour-metering transparency for short-term contracts.
- Agriculture:Farm operators require hydraulic compatibility with existing implement fleets. Japanese rice paddy maintenance creates specialized demand for ultra-lightweight configurations.
- Demolition:Indoor asbestos removal contractors in Germany and the Netherlands mandate zero-emission specifications. Building renovation procurement lists exclude diesel-only machines.
Construction commands the largest fleet deployments; demolition is climbing the fastest on electrification mandates.
Technology:
Powertrain architecture choices fragment procurement committees between total-cost-of-ownership and upfront capital constraints.
- Hydraulic:Open-center and load-sensing circuits remain standard for attachment versatility. Legacy breaker and auger fleets in rural United States dealer territories still specify these configurations.
- Electric:Lithium-ion battery packs with thermal management electrify the sub-3-ton tier. Noise-restricted municipalities in Tokyo and Amsterdam specify these for basement excavation.
- Hybrid:Diesel-electric architectures bridge runtime and emissions requirements. European road-maintenance fleets test these for intermittent duty cycles.
- Diesel:Tier 4 Final after-treatment systems add substantial cost to sub-3-ton units. Price-sensitive independent contractors in Japan delay replacement to amortize compliance investments.
Diesel retains the largest installed base; electric is gaining share fastest on municipal procurement exclusions.
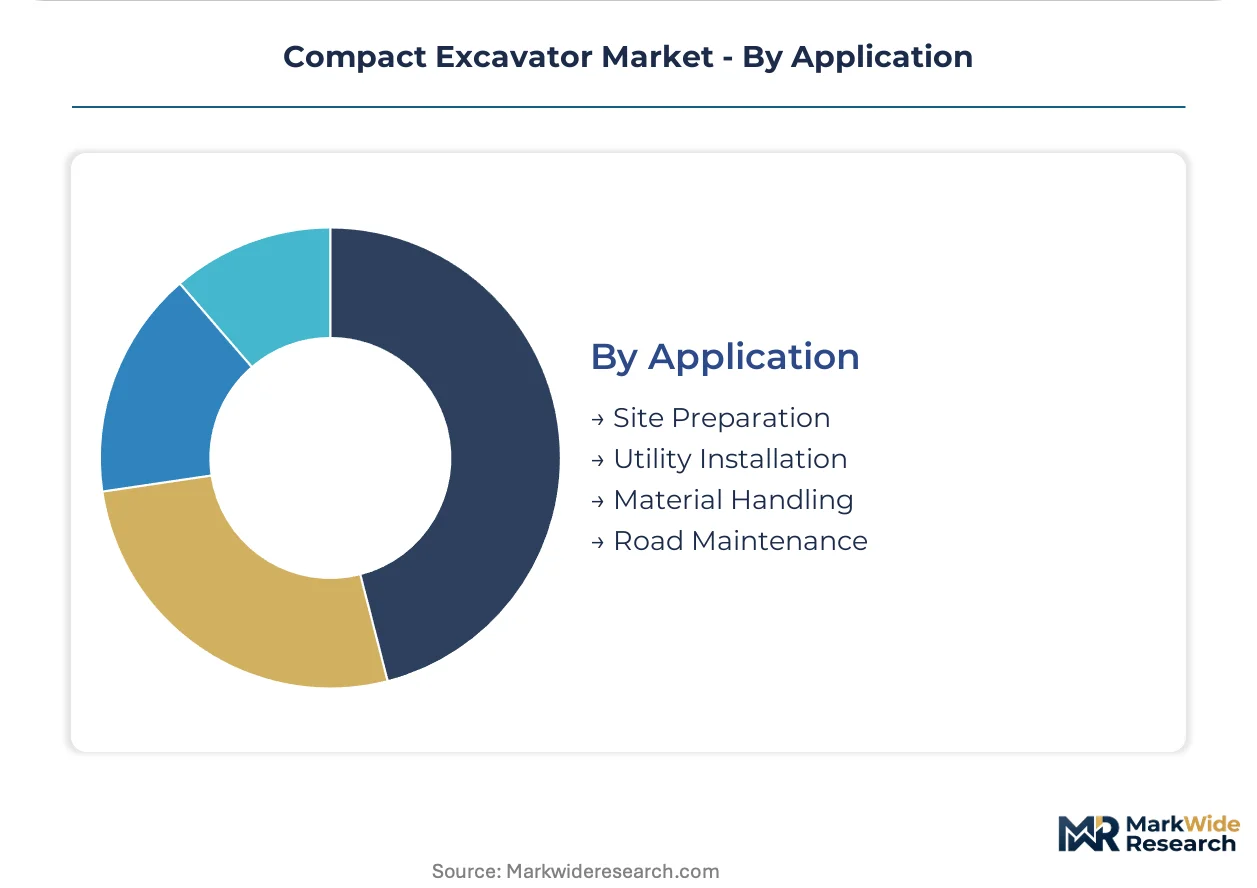
Application:
Task-specific duty cycles determine boom geometry and auxiliary hydraulic flow requirements.
- Site Preparation:Grading and leveling operations demand precise blade control. United States residential developers specify angle-tilt blades for foundation pad preparation.
- Utility Installation:Trenching for fiber-optic and electrical cable drives compact fleet expansion. Japanese municipal contractors navigate congested urban corridors where full-size excavators cannot maneuver.
- Material Handling:Grapple and clamp attachments require dedicated hydraulic circuits. Scrap yards and recycling facilities in Germany prioritize lift capacity over digging force.
- Road Maintenance:Pothole repair and drainage work favors wheeled configurations. French departmental road crews specify rubber-tired machines for rapid inter-site transit.
Utility Installation accounts for the steepest volume trajectory; Road Maintenance shows the strongest margin expansion on wheeled premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese urban utility contractors drive the densest fleet deployment per square kilometer of construction activity. Municipal fiber-optic trenching contracts in Tokyo and Osaka absorb sub-6-ton machines faster than any comparable metropolitan corridor.
United States
EPA Tier 4 Final compliance deadlines compress replacement cycles for diesel-powered rental fleets. The IRA Clean Energy Credits subsidize electric excavator procurement for federal infrastructure contractors. Equipment-sharing platforms in Texas and Florida embed IoT hour-metering to attract independent operators seeking asset-light access.
Germany
Indoor demolition contractors in Berlin and Hamburg mandate zero-emission specifications for asbestos abatement projects. The EU F-Gas Regulation forces HVAC redesigns using natural refrigerants in operator cabs. Bavarian road-maintenance fleets absorb wheeled excavator premiums for rapid transit between municipal job sites.
Japan
METI energy-efficiency benchmarks shape domestic product configurations that subsequently export to Southeast Asian markets. Kubota and Komatsu anchor manufacturing corridors around Osaka and Nagoya. Rice paddy maintenance in rural Chubu creates specialized demand for ultra-lightweight micro excavator variants.
Netherlands
Amsterdam building renovators deploy electric micro excavators for basement excavation where ventilation cannot support diesel exhaust. REACH chemical compliance and machinery directives filter non-conforming imports from Asian suppliers. Rotterdam port logistics clusters handle re-export distribution to Belgian and French contractors.
Australia
Mining services contractors in Western Australia test hybrid powertrains for intermittent duty cycles in remote quarry applications. State-level environmental licensing in Queensland restricts diesel-only equipment in certain heritage-sensitive construction zones. Sydney and Melbourne rental yards concentrate wheeled configurations for urban infrastructure maintenance.
Compact Excavator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line OEMs commanding premium pricing in crawler configurations while regional fabricators capture volume in wheeled variants. The vendor base organizes into three tiers: integrated engine-house manufacturers, hydraulic-system assemblers, and rental-fleet specialists. Dominant competitive moves include captive foundry investments for undercarriage castings and telematics platform development for rental-hour monetization.
Among Japanese integrated manufacturers, Kubota Corporation and Komatsu Ltd. exemplify the engine-house archetype through proprietary powertrain control. Caterpillar occupies a position representing the premium-tier crawler segment with captive casting capacity and global dealer density. These three anchors illustrate how competitive positioning fragments across powertrain integration depth, distribution reach, and material substitution timing.
| Leading Market Players |
|---|
| Kubota Corporation |
| Caterpillar |
| Bobcat (Doosan Bobcat) |
| Komatsu Ltd. |
| JCB |
| John Deere |
| Takeuchi |
| Yanmar |
| Hitachi |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in South Korea and Taiwan dominate undercarriage component supply, translating captive foundry relationships into pricing discipline that resists commoditization in the sub-3-ton tier. Their ownership structure insulates production decisions from quarterly earnings pressure, allowing multi-year tooling amortization that lowers per-unit costs for OEMs with locked-in volume commitments.
Pricing Analysis
Volume placements concentrate in mini excavators where price sensitivity among independent contractors compresses margins; wheeled configurations and electric variants command premium positioning through after-sales service bundling and certification tier differentiation. EPA Tier 4 Final compliance costs intensify pricing pressure in diesel-powered sub-3-ton units, while battery-electric architectures escape this cost compression and capture municipal procurement premiums. Rental fleet operators exhibit lowest price sensitivity due to hour-metering revenue models; independent owner-operators in Japan delay replacement cycles to amortize after-treatment investments.
Supply Chain Analysis
Reverse-logistics networks for hydraulic pump remanufacturing concentrate in Germany and Japan, extending component lifecycles and displacing new-part demand in mature replacement markets. Steel and high-grade cast iron feed from Chinese and Indian mills; hydraulic valve blocks and electronic control modules draw from Japanese and German specialists. Single-source vulnerability concentrates in rare-earth magnet supply for electric powertrain motors, with distribution running through authorized dealer networks that control aftermarket parts access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU F-Gas Regulation construct a cost-of-compliance moat that favors incumbents with parallel certification capabilities, raising effective barriers for unvalidated entrants. This regulatory architecture rewards players who amortized compliance investments across multi-jurisdictional product platforms.
For Market Incumbents: Anticipate margin compression in diesel-only sub-3-ton configurations by accelerating captive battery pack sourcing and thermal management system integration. Defensive consolidation around telematics-enabled rental platforms protects against equipment-sharing marketplace disintermediation. Backward integration into electronic control module production reduces exposure to semiconductor allocation volatility. For New Entrants and Emerging Players: Begin with electric micro excavator specialization for indoor demolition contractors in German and Dutch municipalities where diesel procurement exclusions create addressable white space. Target wheeled configuration gaps in European road-maintenance fleets through rubber-tired mobility patents. Go-to-market leverage rests on hourly rental partnerships with IoT-enabled fleet tracking rather than direct OEM sales channels. For Investors and Strategic Acquirers: Municipal procurement list inclusion for zero-emission specifications is the leading indicator that electric platform development has crossed viability thresholds for sustained returns. Five-to-ten-year viability favors integrated engine-house manufacturers with proprietary powertrain control and captive casting capacity. Acquisition screening should prioritize firms with CE marking and EPA compliance already sequenced; the signal to watch is rental fleet electrification order backlogs from Tier 1 contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Platform Development | Diesel-electric architectures bridge runtime gaps for European road-maintenance intermittent duty cycles. |
| Telematics-Rental Platform Integration | IoT hour-metering embeds OEMs into equipment-sharing marketplaces in France and United Kingdom. |
| Steel-to-Composite Canopy Substitution | Polymer assemblies reduce transport weight below commercial licensing thresholds in multiple jurisdictions. |
| Captive Battery Thermal Management Production | In-house thermal system control secures lithium-ion runtime performance for sub-3-ton electric tiers. |
| Multi-Jurisdiction Certification Sequencing | Parallel CE marking and EPA validation accelerates product launch timelines across Atlantic markets. |
Research Methodology
Independent corroboration across OEM product planning directors, rental fleet procurement managers, and municipal contractor maintenance supervisors underwrites the qualitative findings in this study. Primary interviews with hydraulic systems engineers and aftermarket service heads combined with secondary validation from customs trade data, EPA certification filings, and METI energy-efficiency benchmark disclosures. Bottom-up unit shipment tallies triangulate against top-down equipment replacement cycle modeling.
Rate-of-change decomposition across product type, powertrain architecture, end-use vertical, and regional regulatory cluster structures the forecast framework. CAGRs derive from segmented adoption curve analysis and technology transition timing assumptions across the projection horizon. Industry-specific inputs include lithium-ion battery cost trajectories and municipal procurement electrification mandate propagation patterns.
Underlying measurement precision varies by segment; electric and hybrid technology shares carry tighter precision than diesel replacement timing assumptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and battery energy density improvement trajectories. Practitioners should monitor municipal zero-emission procurement list expansions and rare-earth magnet supply allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Industrial Agitators Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
North America Drilling Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Grout Bags Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Winch Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
CNC Router Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Cold Planers Market