
 Global Tractor Market | 2026-2036
Global Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tractor Market Outlook
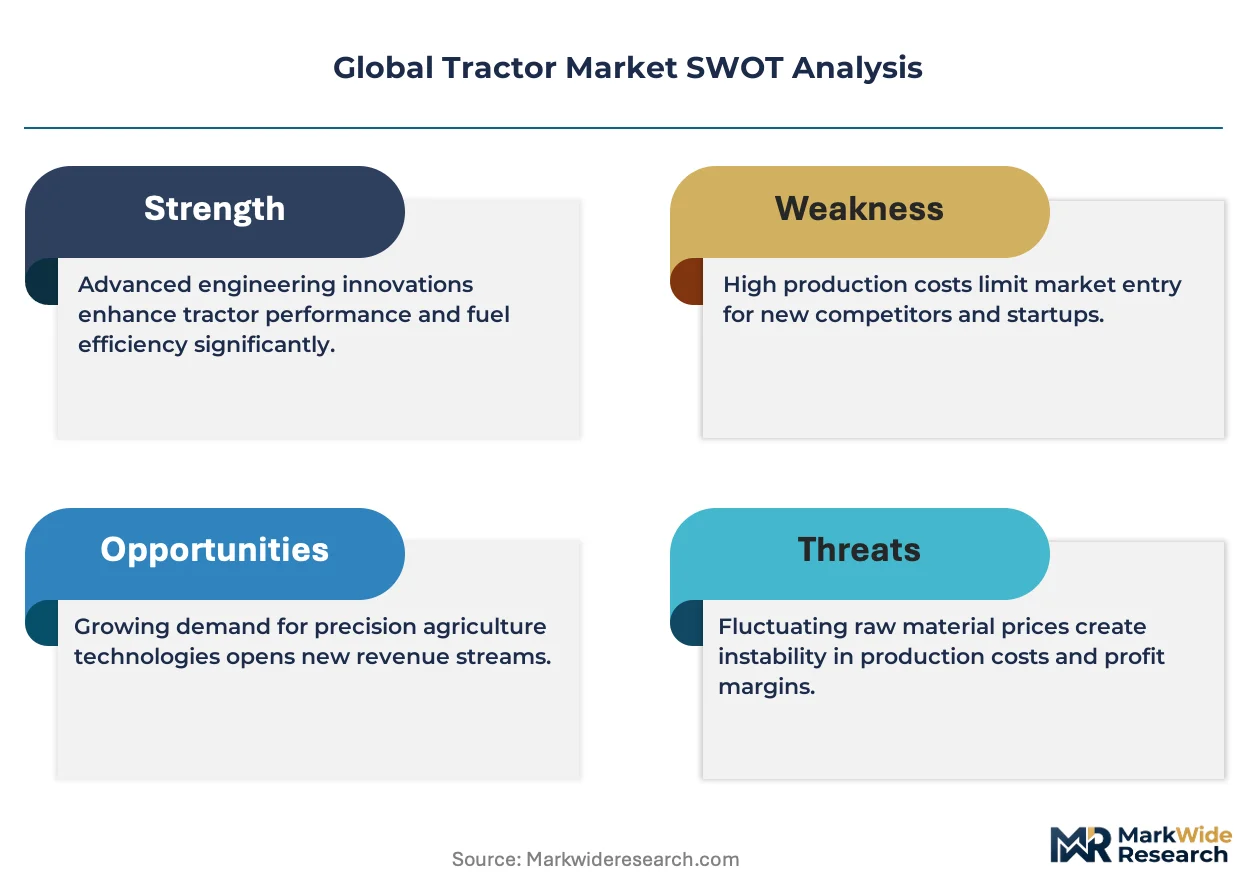
Steel is pivoting toward high-strength alloys and composite-reinforced chassis designs as manufacturers seek weight reduction without sacrificing durability. Deere & Company leverages its precision agriculture software stack to anchor premium positioning in autonomous tractor development. Mahindra & Mahindra sustains dominant share in small-scale and utility segments through dense distribution networks across South Asia. Kubota Corporation specializes in compact tractor architectures for landscaping and specialty crop applications.
A tractor is a self-propelled power unit with an engine typically ranging from 15 to 600 horsepower, designed to pull or power agricultural and industrial implements through a mechanical hitch or power take-off shaft. Diesel engines remain the dominant propulsion technology, though battery-electric and hybrid architectures are penetrating vineyard and municipal applications where noise and emission restrictions apply. Utility tractors and agricultural tractors occupy the largest revenue pools, reflecting sustained replacement cycles among mid-size farms and contractor fleets. Autonomous tractors represent the fastest-growing technology segment, with guidance systems and implement control software capturing disproportionate margin relative to base hardware.
EPA Tier 4 Final and EU Stage V emission standards have forced widespread adoption of selective catalytic reduction and diesel particulate filter systems, adding cost complexity that favors larger manufacturers with integrated engine development capabilities. India's Central Pollution Control Board and Bureau of Indian Standards are tightening domestic emission norms, reshaping competitive access for imported versus locally assembled equipment. Stakeholders must monitor battery energy density trajectories and charging infrastructure rollouts to time electric platform investments against diesel residual value curves.
Market Dynamics
Precision agriculture adoption is compressing replacement cycles as large-scale farming operations in Brazil and the US Midwest demand autonomous guidance systems and implement control software alongside base hardware purchases.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V emission standards:These regulations are accelerating fleet turnover among contractor fleets and commercial agriculture operations seeking compliant equipment, expanding addressable market for newer platforms.
- Mechanization subsidies:India's expanding subsidy programs across agricultural heartland states are pulling smallholder farmers into formal equipment financing, creating first-time tractor ownership demand.
- Autonomous guidance systems:Large-scale farming operations are adopting GPS-based auto-steering and variable-rate application technology, raising equipment specification floors and average transaction values.
Market Restraints
- Steel and high-strength alloy input costs:Volatility in specialty steel pricing compresses manufacturing margins, particularly for mid-size producers lacking long-term supply contracts.
- After-treatment system complexity:Selective catalytic reduction and diesel particulate filter requirements add cost and maintenance burden, extending payback periods for cost-sensitive buyers.
- Battery energy density limitations:Current lithium-ion chemistry constrains runtime for electric platforms in high-draw applications, limiting substitution in row-crop and heavy tillage segments.
Strategic Opportunities
- Vineyard and specialty crop electrification:Noise-sensitive and emission-restricted applications in European viticulture and municipal maintenance are creating early-adopter markets for battery-electric compact tractors.
- Power take-off shaft integration with precision implements:Convergence of mechanical PTO systems with ISOBUS electronic control enables telemetry-based usage billing and predictive maintenance revenue streams.
- Charging infrastructure partnerships:Equipment manufacturers can anchor electric platform rollouts through captive charging networks at dealer locations, reducing buyer adoption friction.
Industry Challenges
- Software-hardware integration timelines:Autonomous tractor development requires simultaneous validation of mechanical systems, sensor fusion algorithms, and safety-critical control software, compressing product launch windows.
- Dealer technician certification gaps:After-treatment diagnostics and electric drivetrain servicing demand training investments that strain rural dealer networks with limited technical labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tractor Market |
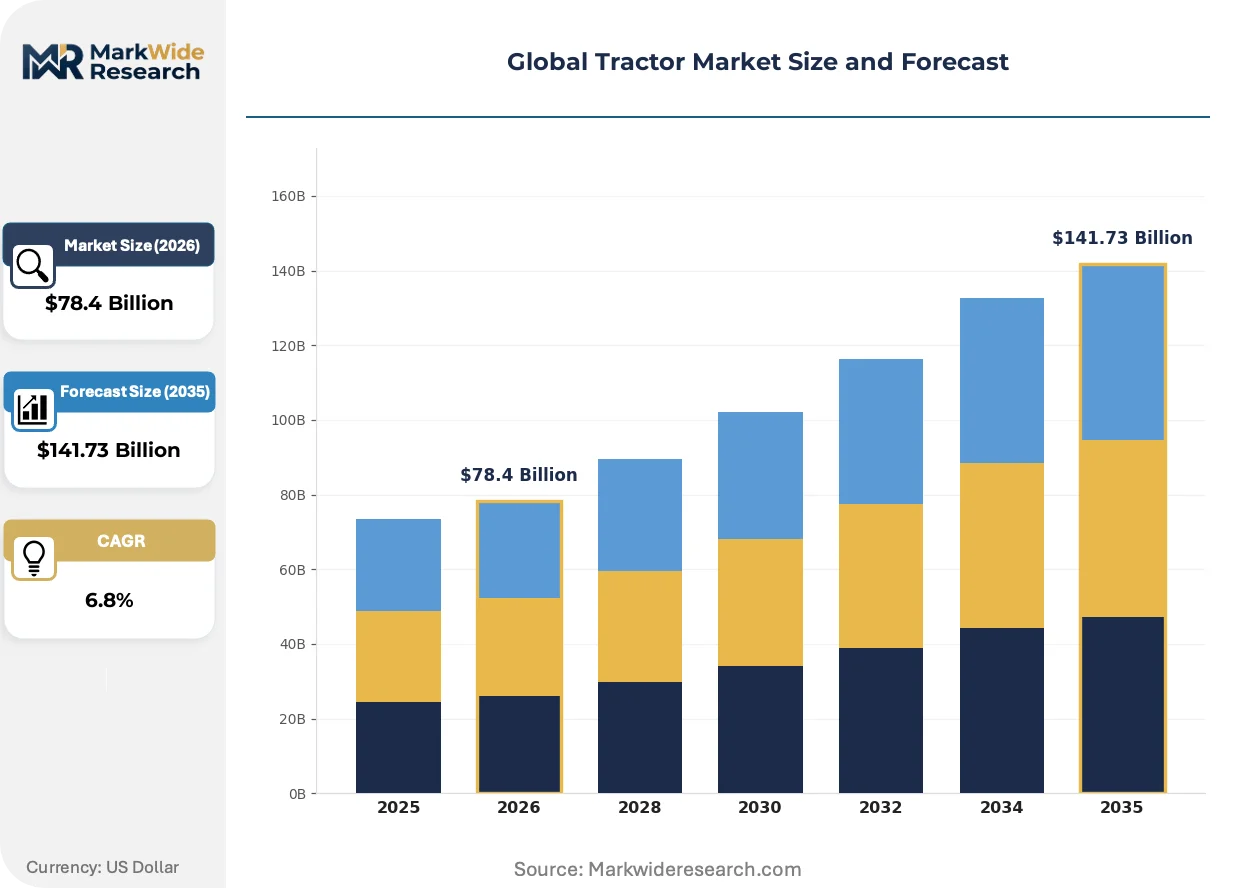
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Tractors, Utility Tractors, Row Crop Tractors, Agricultural Tractors End User: Agriculture, Construction, Landscaping, Forestry Technology: Electric Tractors, Diesel Tractors, Hybrid Tractors, Autonomous Tractors Size: Small-scale, Medium-scale, Large-scale, Commercial |
| Companies Covered | AGCO Corporation, CLAAS, Mahindra & Mahindra, SDF Group, Escorts Kubota, Deere & Company, Kubota Corporation, Yanmar, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tractor Market Strategic Shifts
Autonomous and electric platforms are rewriting equipment specification standards while regulatory emission thresholds force parallel investments in after-treatment and alternative propulsion architectures.
Telematics and ISOBUS connectivity is integrating implement control, fleet management, and predictive maintenance into unified software stacks. Large-scale farming operations in Brazil and the US Corn Belt are specifying these capabilities as baseline requirements. Equipment margins are concentrating in software subscriptions and data services rather than hardware alone.
EU Stage V and EPA Tier 4 Final regulations have mandated selective catalytic reduction and diesel particulate filter installation across all diesel platforms above 25 horsepower. These requirements favor manufacturers with integrated engine development capabilities and captive after-treatment production. Smaller assemblers relying on outsourced powertrains face compliance cost disadvantages and extended homologation timelines.
Equipment-as-service contracting is displacing outright purchase among contractor fleets and large agribusiness operations. Hourly or per-acre usage agreements bundle maintenance, software updates, and seasonal storage, transferring residual value risk to manufacturers. This model is most developed in North American broadacre farming and European contracting sectors where balance sheet efficiency and operational flexibility outweigh ownership preferences.
Global Tractor Market Segmentation
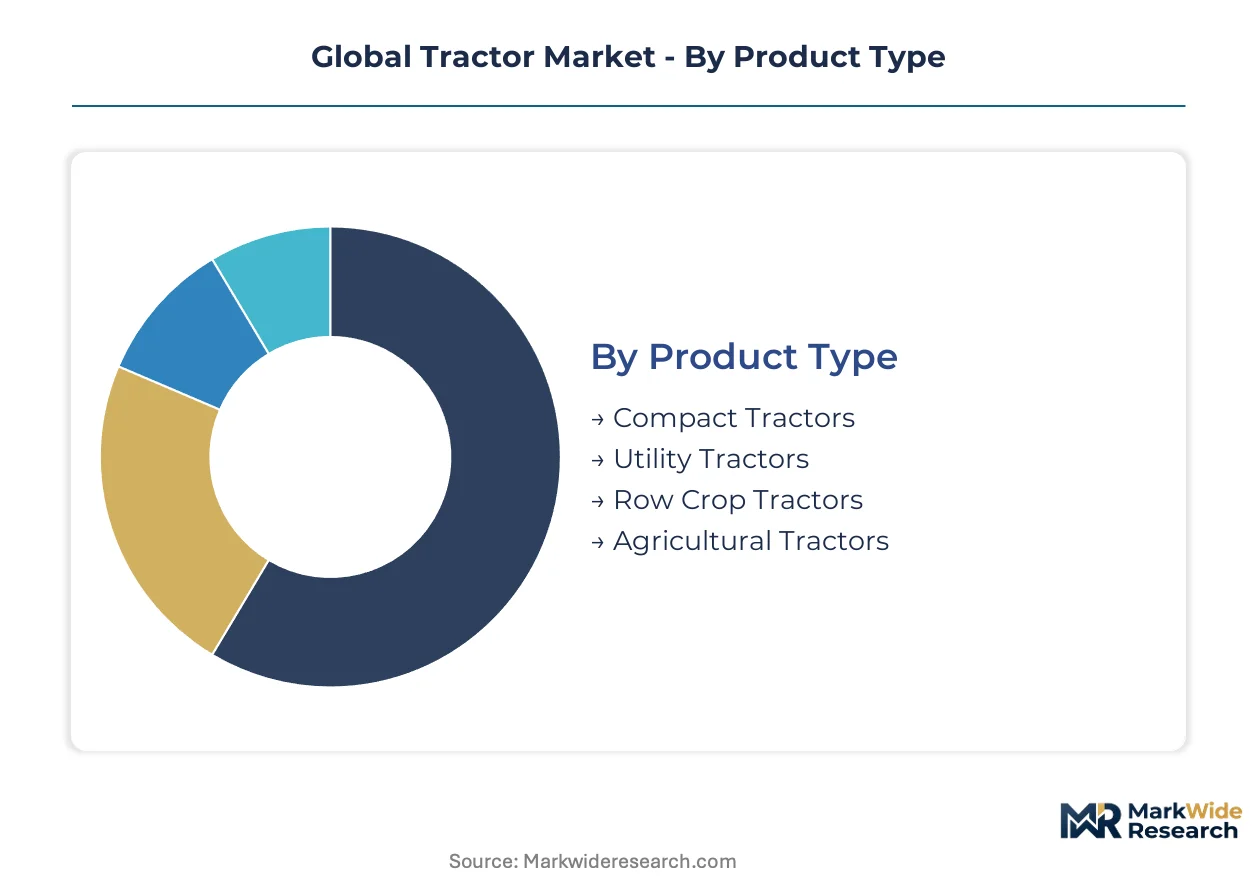
Tractor segmentation reveals divergent margin structures across product architectures and power classes. Equipment manufacturers calibrate platform development to distinct replacement cycles, emission compliance thresholds, and precision agriculture readiness levels.
Product Type:
Compact tractors operate as standalone implements for specialty applications, while row crop and agricultural tractors embed within integrated fleet systems where guidance software and telematics converge.
- Compact Tractors:These machines typically deploy 15-50 horsepower engines in vineyard, orchard, and municipal maintenance settings. European viticulture regions and Japanese specialty crop zones concentrate demand as noise ordinances and emission restrictions tighten.
- Utility Tractors:Versatile 40-100 horsepower platforms dominate mid-size farm and contractor fleets across the US Corn Belt and Brazilian soybean operations. Loader backhoe configurations and three-point hitch flexibility sustain replacement cycles.
- Row Crop Tractors:High-clearance designs with 150-400 horsepower ratings serve precision planting and cultivation in broadacre monoculture systems.
- Agricultural Tractors:Heavy-duty platforms above 300 horsepower pull deep tillage implements and large-scale planting equipment in commercial grain operations.
Volume placements concentrate in Utility Tractors; the faster expansion belongs to Compact Tractors.
End User:
Customer segments stratify by equipment utilization intensity and financing sophistication, with agriculture and construction representing mature procurement channels while landscaping and forestry present fragmented purchasing patterns.
- Agriculture:The dominant demand pool spans commodity crop producers, livestock operators, and diversified farms across India's Punjab-Haryana belt, Brazil's Mato Grosso, and the US Midwest. Mechanization subsidies in India and autonomous guidance adoption in North America reshape specification floors.
- Construction:Loader-equipped utility tractors and backhoe configurations serve residential builders and infrastructure contractors. Rental fleet operators in Germany and Japan concentrate demand for telematics-enabled units with usage-tracking capabilities.
- Landscaping:Compact and sub-compact platforms address golf course maintenance, municipal parks, and residential estate management.
- Forestry:Specialized high-torque tractors with reinforced chassis and winch systems operate in Nordic timber harvesting and Southeast Asian plantation clearing.
Equipment-as-service contracting penetrates deepest in Agriculture; Landscaping shows the steepest expansion trajectory as municipal electrification mandates accelerate.
Technology:
Propulsion architectures diverge between established diesel platforms with after-treatment complexity and emerging electric and autonomous systems where software margins displace hardware value.
- Diesel Tractors:EPA Tier 4 Final and EU Stage V regulations have mandated selective catalytic reduction and diesel particulate filter installation, favoring manufacturers with integrated engine development. Brazil's contractor fleets and India's subsidy-driven smallholders sustain volume demand despite compliance cost burdens.
- Electric Tractors:Battery-electric platforms penetrate vineyard, orchard, and municipal applications where runtime demands remain modest and charging infrastructure can anchor at dealer locations. European viticulture and Japanese urban maintenance operations lead adoption.
- Hybrid Tractors:Parallel architectures blend diesel range extension with electric torque supplementation for variable-load applications.
- Autonomous Tractors:GPS-based auto-steering and implement control systems capture disproportionate margin through software subscriptions and per-acre usage billing.
Hardware shipments dominate in Diesel Tractors; Autonomous Tractors are climbing the fastest as large-scale farming operations mandate guidance capability.
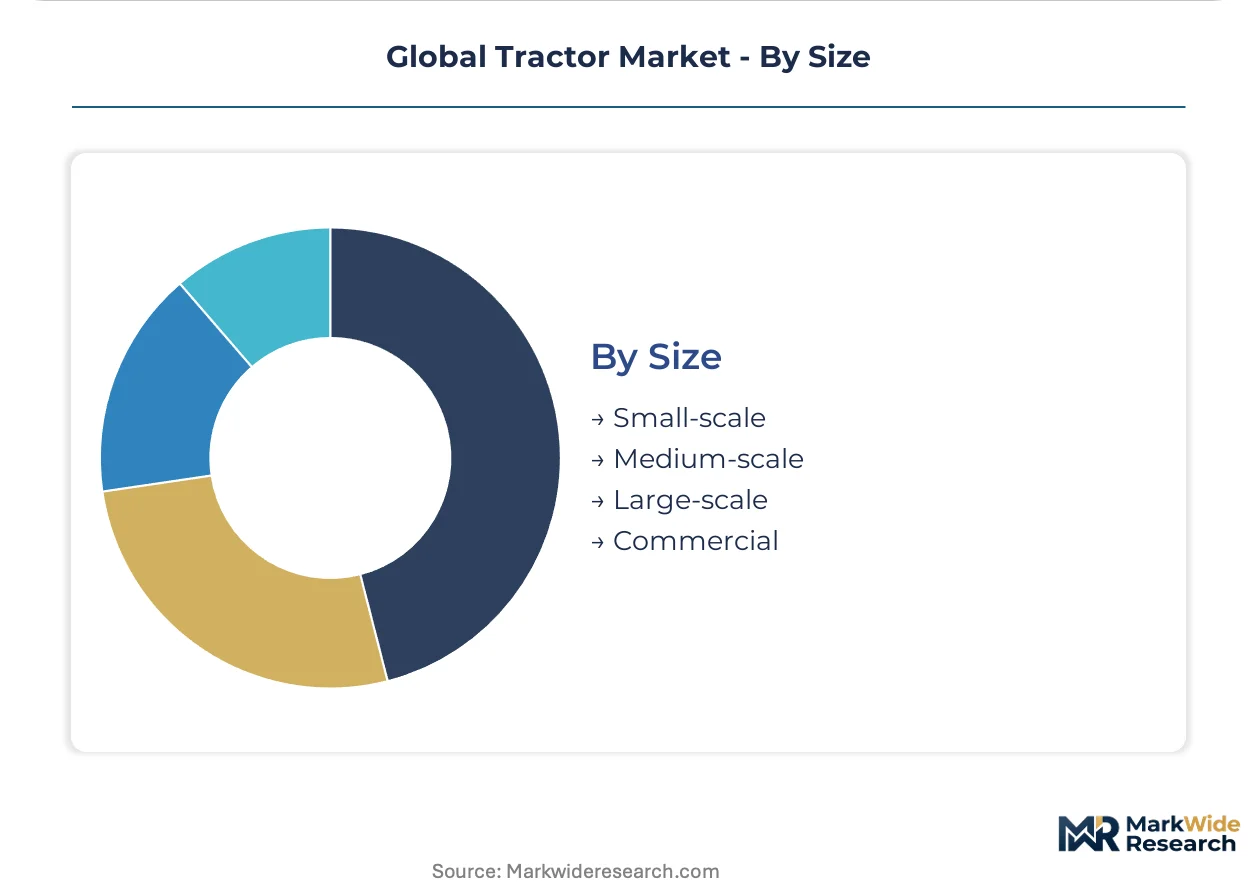
Size:
Scale classifications map to farm structure and financing access, with small-scale equipment serving subsidized first-time buyers and commercial platforms addressing consolidated agribusiness operations.
- Small-scale:Sub-30 horsepower tractors target India's marginal farmers and Southeast Asian smallholders entering mechanized cultivation. India's Central Pollution Control Board emission tightening and state-level subsidy expansion reshape competitive access for imported versus locally assembled equipment.
- Medium-scale:30-75 horsepower platforms balance versatility and capital efficiency for family farms and emerging contractors across Eastern Europe and South America.
- Large-scale:75-200 horsepower tractors serve commercial grain operations and diversified farms with precision agriculture readiness.
- Commercial:200+ horsepower platforms anchor broadacre farming in Brazil, the US, and Russia where fleet standardization and equipment-as-service contracting displace outright purchase.
Shipment value concentrates in Commercial platforms; Small-scale segments gain share fastest as India's subsidy programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in agricultural powerhouses where mechanization subsidies and precision farming investments converge. Brazil's Mato Grosso soybean belt and India's Punjab-Haryana wheat corridor anchor volume shipments. Regulatory tightening across the US, EU, and India reshapes equipment specification floors and compliance timelines.
United States
Large-scale Corn Belt operations mandate GPS auto-steering and variable-rate application technology as baseline specifications. EPA Tier 4 Final emission standards accelerate fleet turnover among contractor fleets seeking compliant platforms. Illinois and Iowa equipment dealerships report rising attachment rates for ISOBUS-enabled implements alongside tractor hardware purchases.
Brazil
Mato Grosso soybean producers drive autonomous guidance adoption across broadacre monoculture systems. ANVISA and national environmental regulators enforce emission protocols that favor integrated engine manufacturers. São Paulo state dealerships expand equipment-as-service contracting to transfer residual value risk from agribusiness operators.
India
Punjab-Haryana smallholders enter formal equipment financing through expanding state-level mechanization subsidies. The Central Pollution Control Board tightens domestic emission norms, reshaping competitive access for imported versus locally assembled equipment. Gujarat and Maharashtra manufacturing clusters scale assembly capacity to meet subsidy-driven demand surges.
Germany
Bavarian and Baden-Württemberg viticulture regions concentrate demand for compact electric platforms under noise ordinances. EU Stage V regulations mandate selective catalytic reduction across diesel platforms above 25 horsepower. Lower Saxony precision agriculture dealerships bundle telemetry subscriptions with hardware transactions.
Japan
Specialty crop zones in Chubu and Kyushu favor compact tractor architectures for orchard and rice paddy applications. METI standards guide domestic emission compliance while supporting electric platform development. Osaka-based equipment distributors anchor charging infrastructure at dealer locations to reduce buyer adoption friction.
Global Tractor Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated engine developers holding structural advantages under tightening emission regimes. The vendor base organizes around three archetypes: diversified agricultural equipment conglomerates with captive powertrain production, regional assemblers leveraging outsourced diesel platforms, and precision agriculture software specialists capturing disproportionate margin through subscription revenue. Consolidation pressures intensify as after-treatment system complexity raises compliance cost barriers. Strategic moves concentrate on captive charging network deployment and equipment-as-service contracting models that transfer residual value risk.
Within the diversified equipment tier, Deere & Company and CNH Industrial occupy positions defined by integrated engine development capabilities and precision agriculture software stacks. Mahindra & Mahindra exemplifies the regional scale archetype through dense distribution networks across South Asian smallholder markets. These three anchors illustrate how compliance cost burdens and software margin capture reshape competitive positioning across diesel, electric, and autonomous platform transitions.
| Leading Market Players |
|---|
| AGCO Corporation |
| CLAAS |
| Mahindra & Mahindra |
| SDF Group |
| Escorts Kubota |
| Deere & Company |
| Kubota Corporation |
| Yanmar |
| CNH Industrial |
| Others |
Value Chain & Pricing Dynamics
Electric platform development and high-strength alloy chassis manufacturing are compressing legacy cost structures while redistributing pricing power toward integrated engine developers and precision agriculture software stacks. Tier 4 Final compliance investments and battery energy density trajectories simultaneously reshape supplier economics and buyer procurement calculus across diesel, hybrid, and autonomous tractor architectures.
Pricing Analysis
Volume shipments concentrate in utility and small-scale diesel tractors where state subsidy programs and contractor fleet turnover sustain transactional pricing; margin capture shifts toward autonomous guidance subscriptions and equipment-as-service contracting. Price differentiation hinges on EPA Tier 4 Final certification tier and precision agriculture software bundling. Pricing pressure runs through mid-size diesel platforms as after-treatment system costs compress manufacturer margins without commensurate buyer willingness to pay. India's smallholder segment exhibits acute price sensitivity; Brazil's agribusiness operators prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Freight cost volatility and chassis component weight reduction requirements are forcing proximity sourcing recalibration across tractor manufacturing networks. Steel and high-strength alloy supply concentrates in China, India, and Germany; selective catalytic reduction systems and diesel particulate filters draw from integrated engine production clusters in the US, Germany, and Japan. Supply chain risk rests on single-source vulnerability for precision guidance sensor arrays and lithium-ion battery cell supply. Distribution runs through captive dealer networks with certified technician pools, particularly dense across India's Punjab-Haryana belt and Brazil's Mato Grosso corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as emission compliance complexity and software-hardware integration timelines force capital-constrained assemblers toward exit or acquisition.
For Market Incumbents: Deploy precision agriculture software stack deepening to anchor subscription revenue and raise switching costs against emerging autonomous platform competitors. Integrate captive after-treatment production to defend margin position under EPA Tier 4 Final and EU Stage V cost pressures. Prioritize technician certification programs across Brazil's São Paulo state and India's Gujarat clusters to lock dealer network loyalty. For New Entrants and Emerging Players: Specialty crop electrification in European viticulture and Japanese urban maintenance presents the most penetrable white-space opportunity. Municipal landscaping fleets under noise ordinance pressure offer near-term volume traction. Partner with charging infrastructure developers at dealer anchor locations to reduce buyer adoption friction without capital-intensive network buildout. For Investors and Strategic Acquirers: Re-rating potential sits with precision agriculture software specialists given autonomous guidance mandate acceleration across Brazil and the US Corn Belt. Long-term viability favors platforms with integrated engine development and ISOBUS telemetry capabilities. Monitor battery energy density trajectories and Indian Central Pollution Control Board enforcement timing as inflection signals for electric platform investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Guidance Stack Acquisition | Captures ISOBUS-enabled subscription revenue from Brazil's Mato Grosso soybean producers. |
| Captive Charging Network Deployment | Anchors electric platform rollout at Osaka and Bavarian dealer locations. |
| After-Treatment System Integration | Defends margin position under EPA Tier 4 Final and EU Stage V mandates. |
| Equipment-as-Service Contracting | Transfers residual value risk from Illinois and Iowa agribusiness operators. |
| High-Strength Alloy Chassis Sourcing | Reduces weight without durability sacrifice for precision agriculture applications. |
Study Parameters
Trade publications, customs filings, and OEM technical documentation formed the secondary backbone, cross-referenced against primary interviews with fleet procurement managers, dealership operations heads, precision agriculture software engineers, and aftermarket service directors. Bottom-up shipment data from India's Punjab-Haryana and Brazil's Mato Grosso corridors triangulated against top-down equipment financing flow analysis.
Historical trendline analysis across diesel, electric, hybrid, and autonomous propulsion architectures informed the projection framework. Segmentation modeling incorporated power class tier, end-use intensity, precision agriculture readiness, and regional subsidy regime. CAGRs derived from equipment replacement cycle compression rates and mechanization subsidy expansion trajectories. Battery energy density curves and charging infrastructure rollout schedules served as electric platform adoption inputs.
Caveats apply where EPA Tier 4 Final enforcement timing or Indian Central Pollution Control Board norm revisions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
North America Agricultural Tractors Machinery Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Crop Sprayers Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market