
 Belt Loader Market | 2026-2036
Belt Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Belt Loader Market Analytics
Multi-source procurement toward hybrid electric-hydraulic platforms is rebalancing supplier relationships across the belt loader supply base. TLD Group leverages its European manufacturing footprint to sustain long-term service contracts with major hub airports. JBT Aerotech anchors its position through in-house production of electric drive systems, reducing dependency on third-party motor suppliers. Weihai Guangtai Airport Equipment competes aggressively on manufacturing scale, occupying cost-sensitive segments in emerging aviation markets.
A belt loader is a self-propelled or towable ground support vehicle equipped with an adjustable conveyor belt mechanism, typically spanning 4 to 10 meters in length and rated for loads between 300 and 700 kilograms per linear meter, designed to transfer luggage and cargo between terminal buildings and aircraft holds. The equipment employs hydraulic lift systems to vary belt elevation across aircraft door sill heights ranging from 1.2 to 4.2 meters, enabling compatibility with narrow-body through wide-body fleets. Automated Loaders now command the strongest margin pools as airports prioritize labor reduction and precise baggage tracking integration. Electric Systems represent the fastest-expanding technology segment, displacing hydraulic alternatives where tarmac electrification infrastructure permits overnight charging cycles.
FAA airworthiness directives for ground support equipment establish minimum braking and stability standards that shape product development priorities for US manufacturers. The EU Green Deal's F-Gas Regulation and national tarmac emission limits enforced by Germany's KBA and France's environmental regulators are accelerating phase-out schedules for diesel-powered units. Stakeholders must monitor battery energy density trajectories and charging infrastructure deployment timelines at hub airports to time capital commitments between incumbent hydraulic platforms and next-generation electric architectures.
Market Dynamics
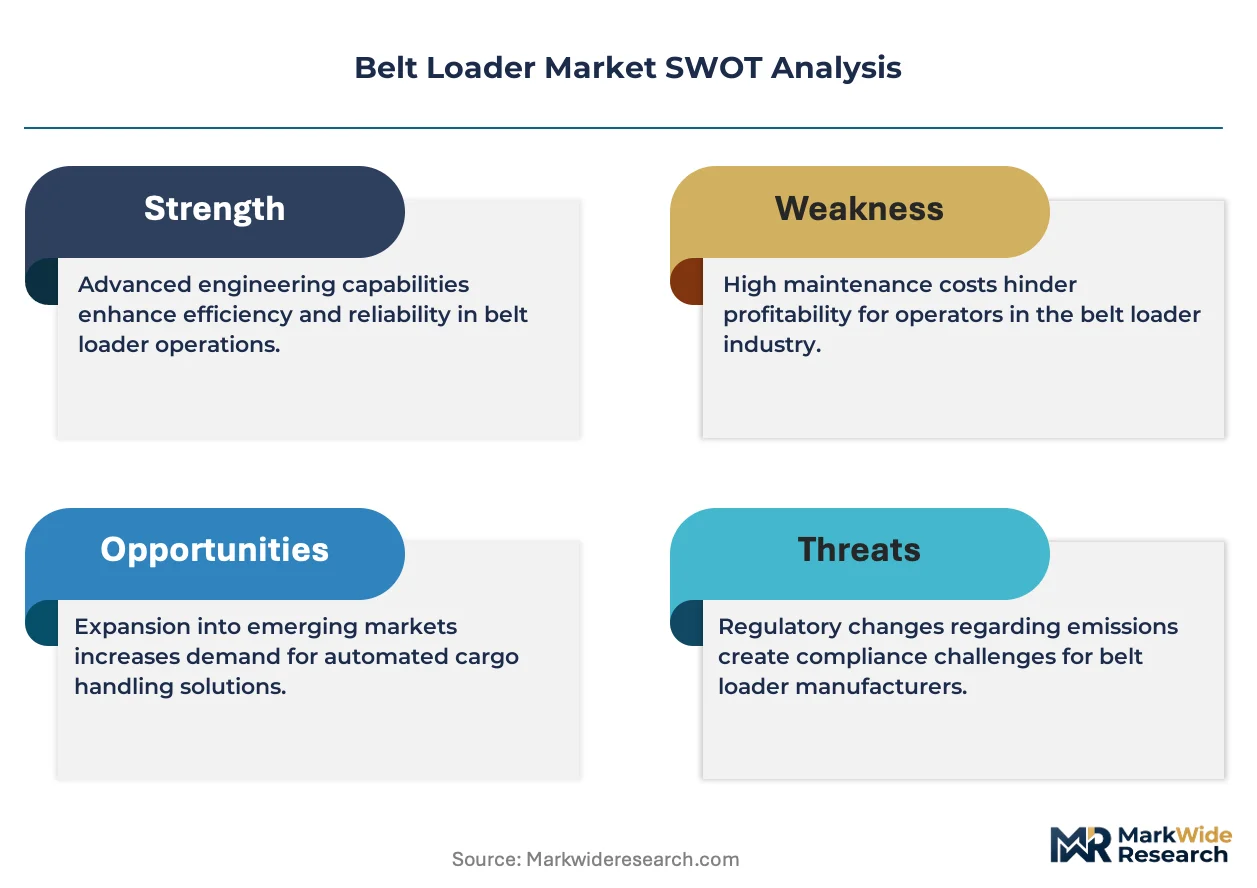
Electrification mandates from the EU Green Deal are compressing replacement cycles for diesel-powered belt loaders while battery energy density improvements enable viable overnight charging protocols at major hub airports.
Growth Catalysts
- EU F-Gas Regulation:Germany's KBA and France's environmental regulators enforce accelerating phase-out schedules for diesel-powered ground support equipment, forcing fleet modernization decisions.
- Aviation infrastructure expansion:Bulk procurement of automated loading systems concentrates in China where new airport construction drives equipment standardization at scale.
- Baggage tracking integration:Airports prioritize labor reduction through precise RFID-enabled cargo monitoring, elevating demand for sensor-equipped belt loader platforms.
Market Restraints
- Battery supply concentration:Lithium-ion cell production concentrates in East Asian manufacturing clusters, exposing procurement to geopolitical friction and input cost volatility.
- Tarmac electrification gaps:Overnight charging infrastructure remains incomplete at secondary airports, limiting electric belt loader deployment to hub facilities with capital-intensive grid upgrades.
- Hydraulic system lock-in:Legacy maintenance expertise and spare parts inventories at ground handling operators create switching friction against electric platform adoption.
Strategic Opportunities
- India aviation infrastructure:PLI scheme incentives for domestic manufacturing create localized assembly opportunities for cost-sensitive emerging market segments.
- Autonomous navigation convergence:Integration of LiDAR positioning with electric drive systems enables unmanned tarmac operations during low-visibility conditions.
- Service contract unbundling:Aftermarket parts and predictive maintenance subscriptions represent margin expansion beyond equipment sales at established hub airports.
Industry Challenges
- FAA airworthiness certification:Ground support equipment braking and stability standards require extensive testing protocols that extend product launch timelines.
- Electromechanical integration complexity:Combining hydraulic lift systems with electric drive architectures demands cross-functional engineering talent scarce in traditional ground handling equipment sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt Loader Market |
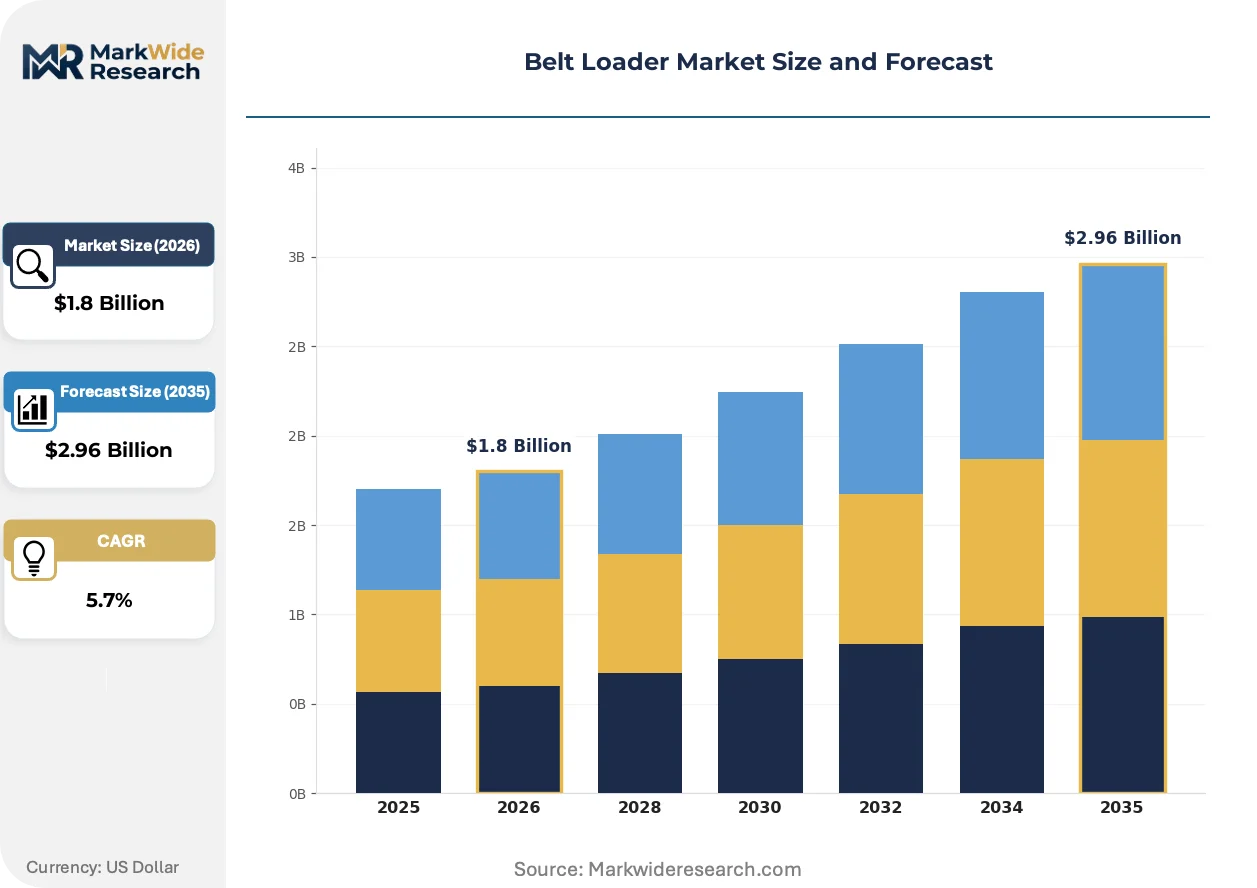
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Loaders, Manual Loaders, Towable Loaders, Mobile Loaders End User: Airports, Shipping Ports, Cargo Handlers, Freight Companies Application: Overhead Loading, Ground Loading, Cargo Transport, Baggage Handling Technology: Hydraulic Systems, Pneumatic Systems, Electric Systems, Mechanical Systems |
| Companies Covered | Textron Ground Support Equipment Inc., TLD Group, JBT Aerotech, CHARLATTE MANUTENTION, Oshkosh Corporation, Weihai Guangtai Airport Equipment, Ersel Group, Sinfonia, TCR Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt Loader Market Evolving Landscape
Automation and electrification are converging to redefine belt loader specifications, with regulatory pressure compressing technology adoption timelines and procurement patterns fragmenting across service models.
Automated Loaders are automating baggage handling through conveyor systems integrated with aircraft hold scanning and weight verification sensors. Major hub airports in Germany and the Netherlands deploy these platforms to reduce manual labor during narrow-body turnarounds. The technology is automating ground crew deployment decisions and compressing aircraft ground time metrics.
EU Green Deal implementation through the F-Gas Regulation and national tarmac emission limits is mandating diesel phase-outs across ground support fleets. Equipment manufacturers must redesign thermal management systems for electric motor cooling under continuous load conditions. Electric belt loader categories face accelerated procurement timelines in France, Germany, and Benelux airports where environmental regulators enforce strictest compliance deadlines.
Hub airports are consolidating vendor relationships toward full-fleet service agreements that bundle equipment, maintenance, and software upgrades under unified contracts. Traditional equipment-only sales channels face displacement from integrated ground handling solution providers. This consolidation pattern concentrates in North American and European hub airports where capital efficiency pressures drive procurement centralization.
Belt Loader Market Segmentation
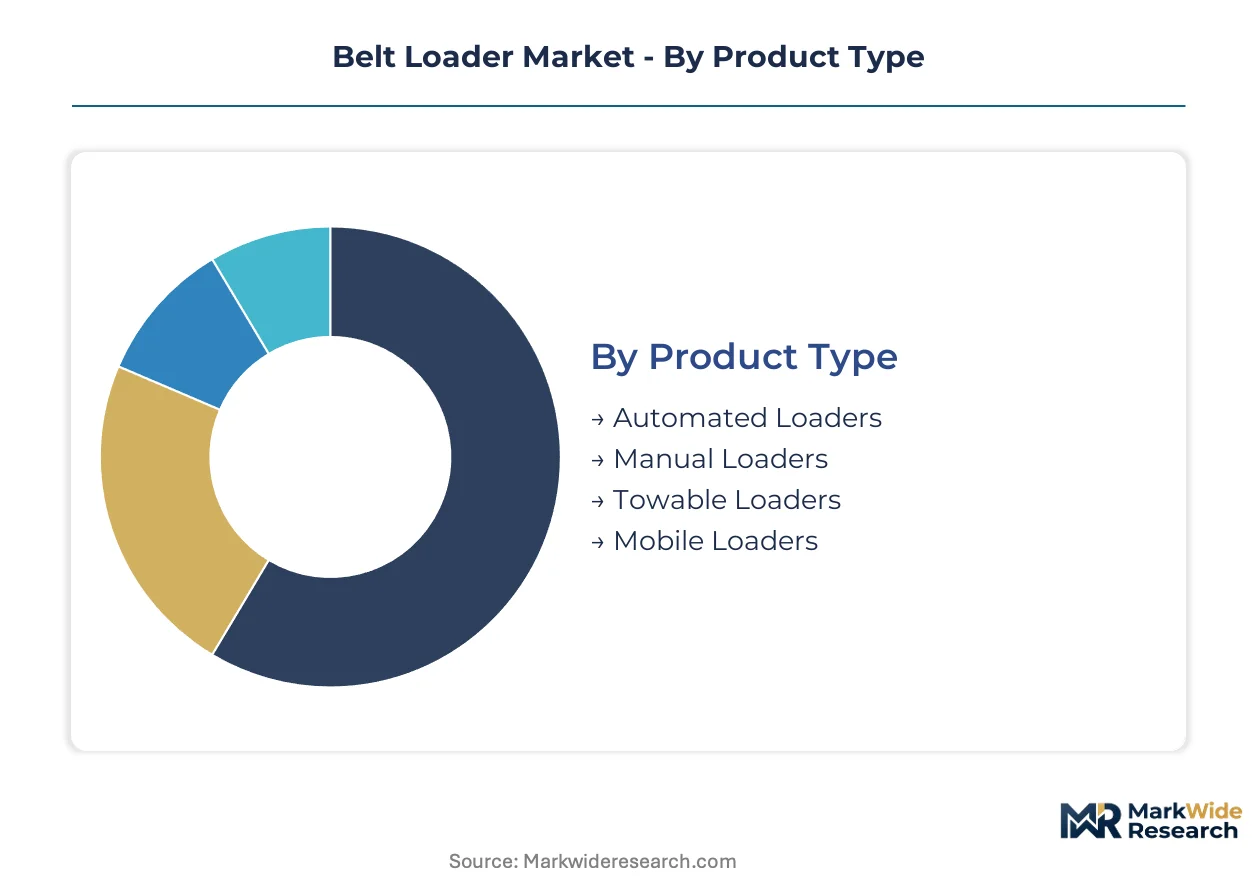
Belt loader procurement patterns fragment sharply across operational scale and regulatory maturity. Equipment specifications diverge between hub airports prioritizing automation and regional facilities optimizing capital efficiency through versatile platforms.
Product Type:
Customization intensity spans from standardized towable units to fully integrated automated systems requiring site-specific conveyor configurations.
- Automated Loaders:Self-propelled platforms integrate LiDAR positioning with RFID baggage tracking and automated hold scanning. Hub airports in Germany and the Netherlands deploy these systems to compress narrow-body turnaround times and reduce ground crew headcount.
- Manual Loaders:Operator-controlled hydraulic lift systems dominate secondary airport fleets where capital constraints limit automation investment. Demand concentrates in India's regional aviation infrastructure expansion under PLI scheme incentives.
- Towable Loaders:Compact units trail behind baggage tractors for flexible deployment across multiple aircraft stands.
- Mobile Loaders:Self-propelled diesel or electric platforms serve high-volume cargo operations at integrated freight terminals.
Most installed capacity flows through Manual Loaders. Expansion is steepest in Automated Loaders.
End User:
Customer sophistication tiers separate integrated hub operators from fragmented ground handling contractors.
- Airports:Direct procurement by airport authorities concentrates at major hubs consolidating vendor relationships under full-fleet service agreements. France's environmental regulators and Germany's KBA enforce EU Green Deal compliance deadlines that accelerate electric platform procurement.
- Cargo Handlers:Third-party ground handling operators balance fleet standardization against contract mobility requirements across multiple airport clients.
- Shipping Ports:Maritime container operations repurpose belt loader mechanics for intermodal cargo transfer at coastal logistics hubs.
- Freight Companies:Integrated logistics providers specify equipment compatibility with existing warehouse automation systems.
Airports command the largest procurement volumes. Cargo Handlers are gaining share fastest as outsourcing expands.
Application:
Operational altitude requirements dictate structural reinforcement and safety system complexity.
- Baggage Handling:Passenger luggage transfer demands precise weight verification sensors and gentle incline angles to prevent damage. Hub airports prioritize this segment for labor reduction and tracking integration.
- Cargo Transport:Heavy freight operations require reinforced belt ratings and extended conveyor spans for containerized goods.
- Overhead Loading:Wide-body aircraft hold access demands maximum elevation range and stabilizing outriggers.
- Ground Loading:Narrow-body compatibility emphasizes rapid elevation adjustment and compact maneuvering footprint.
Ground Loading dominates current fleet composition. Baggage Handling shows the steepest technology upgrade trajectory.
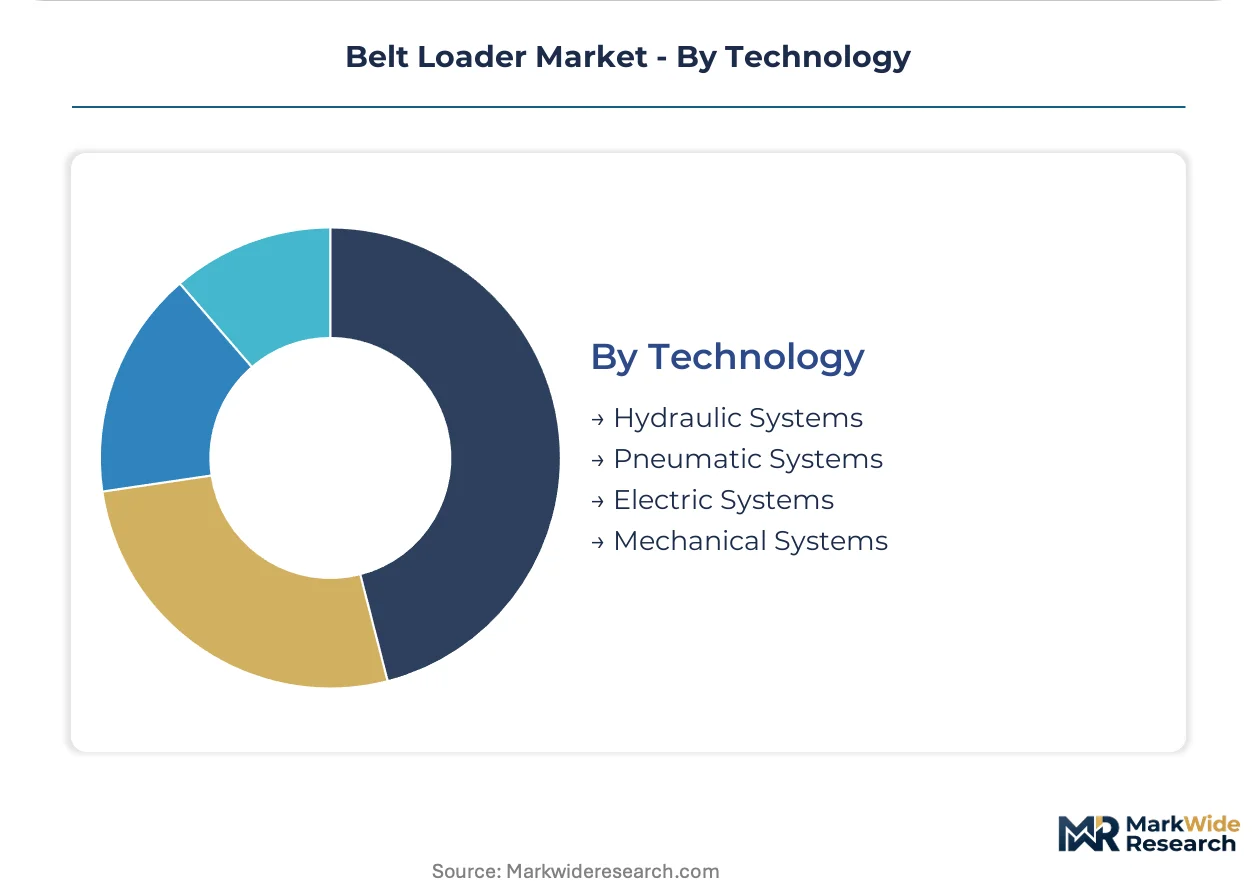
Technology:
Powertrain architecture determines regulatory compliance horizons and total cost of ownership profiles.
- Electric Systems:Battery-electric drive eliminates tarmac emissions and enables overnight charging at electrified hub airports. Thermal management redesigns address motor cooling under continuous load conditions mandated by EU F-Gas Regulation phase-out schedules.
- Hydraulic Systems:Diesel-hydraulic platforms retain installed base dominance where charging infrastructure remains incomplete. Legacy maintenance expertise and spare parts inventories create switching friction against electric adoption.
- Pneumatic Systems:Compressed air actuation serves niche applications requiring explosion-proof operation in hazardous cargo environments.
- Mechanical Systems:Direct drive linkages persist in towable units where simplicity outweighs efficiency optimization.
Hydraulic Systems retain the largest installed base. Electric Systems are climbing the fastest as battery energy density enables viable overnight protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly capacity toward jurisdictions with lower compliance costs for diesel-phase regulations. This arbitrage dynamic concentrates investment in China and India while European producers absorb stricter EU Green Deal enforcement.
United States
FAA airworthiness directives for ground support equipment braking standards drive product redesign cycles at domestic manufacturers. The FAA mandates extensive testing protocols that extend certification timelines for new belt loader platforms. Dallas-Fort Worth and Atlanta hub airports are consolidating vendor relationships under full-fleet service agreements that bundle maintenance with equipment procurement.
Germany
The KBA enforces national tarmac emission limits that accelerate diesel belt loader phase-outs at Frankfurt and Munich airports. Germany's environmental regulators impose strictest EU Green Deal compliance deadlines across ground support fleets. Bavaria's industrial corridor hosts precision engineering clusters supplying electric drive components to regional equipment assemblers.
China
Aviation infrastructure expansion at Chengdu Tianfu and Beijing Daxing airports drives bulk procurement of automated loading systems. The country's dual carbon goals pressure state-owned airlines toward electric ground support equipment adoption. Weihai in Shandong province anchors manufacturing scale for cost-sensitive emerging market segments across Asia-Pacific.
India
PLI scheme incentives for domestic manufacturing create localized assembly opportunities for regional aviation infrastructure. The Directorate General of Civil Aviation is developing ground support equipment standards aligned with international safety protocols. Maharashtra and Karnataka are emerging as assembly hubs for ground handling fleets serving Delhi and Mumbai hub expansion.
France
ANSM environmental regulators enforce F-Gas Regulation compliance that compresses replacement cycles for diesel-powered units at Paris Charles de Gaulle. France's tarmac emission limits exceed EU baseline requirements for ground support equipment. Toulouse-Blagnac's aerospace cluster influences specification standards for automated cargo handling systems.
Belt Loader Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and automation adjacencies. The vendor base stratifies across three tiers: integrated full-fleet service providers, specialized electric drive manufacturers, and scale-driven cost competitors. Strategic archetypes include European incumbents leveraging service contract density, Asian fabricants exploiting manufacturing scale, and technology specialists converging autonomous navigation with electric platforms. Competitive moves center on M&A for charging infrastructure capabilities and strategic partnerships for battery supply security.
Among diversified industrial conglomerates, Textron Ground Support Equipment Inc. and Oshkosh Corporation exemplify the capital-intensive tier with captive distribution networks. TLD Group and JBT Aerotech represent European and North American incumbents respectively, anchoring positions through long-term service relationships with hub airports. Weihai Guangtai Airport Equipment occupies the scale-driven archetype, competing on manufacturing throughput for cost-sensitive procurement in emerging aviation markets.
| Leading Market Players |
|---|
| Textron Ground Support Equipment Inc. |
| TLD Group |
| JBT Aerotech |
| CHARLATTE MANUTENTION |
| Oshkosh Corporation |
| Weihai Guangtai Airport Equipment |
| Ersel Group |
| Sinfonia |
| TCR Group |
| Others |
Value Network & Pricing Analysis
Hub airport procurement consolidation under full-fleet service agreements concentrates pricing power among integrated ground handling solution providers. Electric drive component costs and battery supply security now dominate supplier negotiations more than legacy hydraulic platform economics.
Pricing Analysis
Direct-to-airport vendor relationships compress channel margins versus equipment-only sales through distributor networks. Three-tier pricing structure across premium automated loaders, standard electric platforms, and economy hydraulic units differentiates on certification grade and after-sales bundling. Cost compression in economy tiers intensifies because Chinese manufacturers exploit manufacturing scale advantages. Regional ground handling contractors exhibit highest price sensitivity; hub airports with consolidated procurement tolerate premium pricing for integrated service contracts.
Supply Chain Analysis
Remanufacturing flows for diesel-hydraulic units extend asset life at secondary airports delaying electric platform procurement. Battery cell production concentrates in China, South Korea, and Japan, exposing procurement to geopolitical friction and input cost volatility. Electric motor controllers and lithium-ion cells constitute critical dependencies. Single-source vulnerability in semiconductor-based motor control systems threatens production continuity. Distribution runs through OEM-direct channels for hub airports and regional equipment distributors for fragmented ground handling operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service unbundling and predictive maintenance subscriptions as fleet electrification accelerates replacement part demand. Battery energy density improvements and charging infrastructure deployment timelines determine optimal timing for capital commitment shifts.
For Market Incumbents: Anticipate Chinese manufacturing scale competitors eroding price positions in economy segments by deepening captive supply of electric drive systems. Anchor defensive positioning through long-term service contract density at Frankfurt, Munich, and Paris Charles de Gaulle where EU Green Deal enforcement tightest. Prioritize thermal management engineering talent acquisition for electric motor cooling under continuous load conditions. For New Entrants and Emerging Players: The mid-tier pricing gap between TLD Group premium automated systems and Weihai Guangtai economy platforms offers white-space entry. India's PLI scheme incentives for domestic manufacturing create localized assembly opportunities for cost-sensitive regional aviation infrastructure. Target autonomous navigation convergence with LiDAR positioning as differentiated go-to-market angle for unmanned tarmac operations. For Investors and Strategic Acquirers: Integrated ground handling solution providers are the most active acquirer in this space, consolidating vendor relationships at North American and European hub airports. Acquisition target archetype: electric drive specialists with thermal management IP and established charging infrastructure partnerships. Monitor battery energy density trajectories and hub airport electrification deployment timelines as inflection indicators for electric platform adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electric Drive Systems | JBT Aerotech reduces third-party motor supplier dependency through in-house production capacity. |
| Charging Infrastructure Partnership | Hub airports require capital-intensive grid upgrades to enable overnight electric belt loader protocols. |
| Autonomous Navigation Convergence | LiDAR positioning integration enables unmanned tarmac operations during low-visibility conditions. |
| Full-Fleet Service Agreement Consolidation | Dallas-Fort Worth and Atlanta bundle maintenance with equipment procurement under unified contracts. |
| Localized Assembly Expansion | India's PLI scheme incentives create manufacturing hubs in Maharashtra and Karnataka for regional fleets. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with airport procurement directors, ground handling fleet managers, OEM engineering leads, and aftermarket service heads alongside secondary validation. Trade data from customs authorities, FAA airworthiness directive filings, EU Green Deal regulatory impact assessments, and airport capital expenditure disclosures anchor supply-side analysis. Bottom-up equipment shipment tracking and top-down aviation infrastructure investment flows enable triangulation.
Rate-of-change decomposition separates volume growth from value migration across electric-hydraulic technology transitions. Segmentation dimensions span product type, end user sophistication tier, application altitude requirement, and powertrain architecture across the analysis window. CAGRs derive from installed base replacement modeling against fleet expansion at greenfield airports. Battery energy density trajectories and tarmac electrification deployment schedules constitute industry-specific forecast inputs.
Caveats apply where EU F-Gas Regulation enforcement intensity or lithium-ion supply disruption could materially shift the outlook. Forecasts reflect assumptions on charging infrastructure completion timelines and ground handling operator switching friction from hydraulic maintenance expertise. Practitioners should monitor KBA and ANSM compliance deadline acceleration and East Asian battery cell production concentration for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Smart Card Contactless Ticketing Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Africa 3D Printing Construction Market
Others
Asia-Pacific Social Media Management Market
Others
Italy Feed Additives Market
Others
Idaas Market
Others
Japan Smart Home Market
Others
Nutricosmetics Market
Others
Global Contactless Biometrics Technology Market
Others
Asia-Pacific Road Safety Market
Others
AC Switchgear Market
Others
Short Video Applications Market
Others
Propanil Market
Others
Disposable Non Woven Sponge Market