
 Asia Pacific Contract Packaging Market | 2026-2036
Asia Pacific Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Contract Packaging Market Outlook
Pharmaceutical demand is rebalancing contract packaging capacity across Asia Pacific as biologic therapies and cold-chain requirements expand. MJS Packaging specializes in compliant healthcare packaging formats that meet stringent temperature-control protocols. TricorBraun anchors its regional position through rigid container expertise for high-value drug formulations. Sharp Packaging Services dominates sterile barrier and compliance labeling for regulated medical products.
Contract packaging encompasses outsourced primary, secondary, and tertiary packaging execution performed by third-party providers on behalf of brand owners, typically involving automated filling, sealing, labeling, and kit assembly within ISO-certified cleanroom or controlled environments. Flexible packaging commands expanding share in food and personal care segments due to material efficiency and shelf-life extension properties, while rigid packaging retains margin concentration in pharmaceutical and electronics applications where barrier integrity and dimensional precision are non-negotiable. E-commerce customer channels represent the fastest-growing demand vector, driving investment in right-sized corrugated and automated fulfillment configurations.
India's CDSCO enforces serialization and track-and-trace mandates for pharmaceutical exports, compelling contract packers to upgrade line-level digital infrastructure. Japan's PMDA and METI coordinate on medical device packaging standards that influence specifications across Northeast Asian supply chains. China's SAMR implements evolving food-contact material registrations that affect flexible packaging substrate selection. Stakeholders must weigh regulatory divergence against scale economies when configuring multi-country packaging networks.
Market Dynamics
Biologic cold-chain requirements are redistributing contract packaging capacity toward temperature-certified facilities, while India's PLI scheme and Japan's METI standards fragment compliance architectures across the region.
Growth Catalysts
- CDSCO Serialization Mandates:India's pharmaceutical export track-and-trace requirements compel domestic contract packers to deploy line-level digital infrastructure, creating captive demand for integrated packaging-IT service providers.
- Biologics Expansion:Specialty medicine cold-chain protocols in China and South Korea are pulling investment toward sterile barrier and active temperature-control packaging formats.
- Coastal Manufacturing Clustering:Contract packers concentrated in China's Yangtze River Delta and Pearl River Delta serve simultaneous domestic brand and multinational export demand from single-site footprints.
Market Restraints
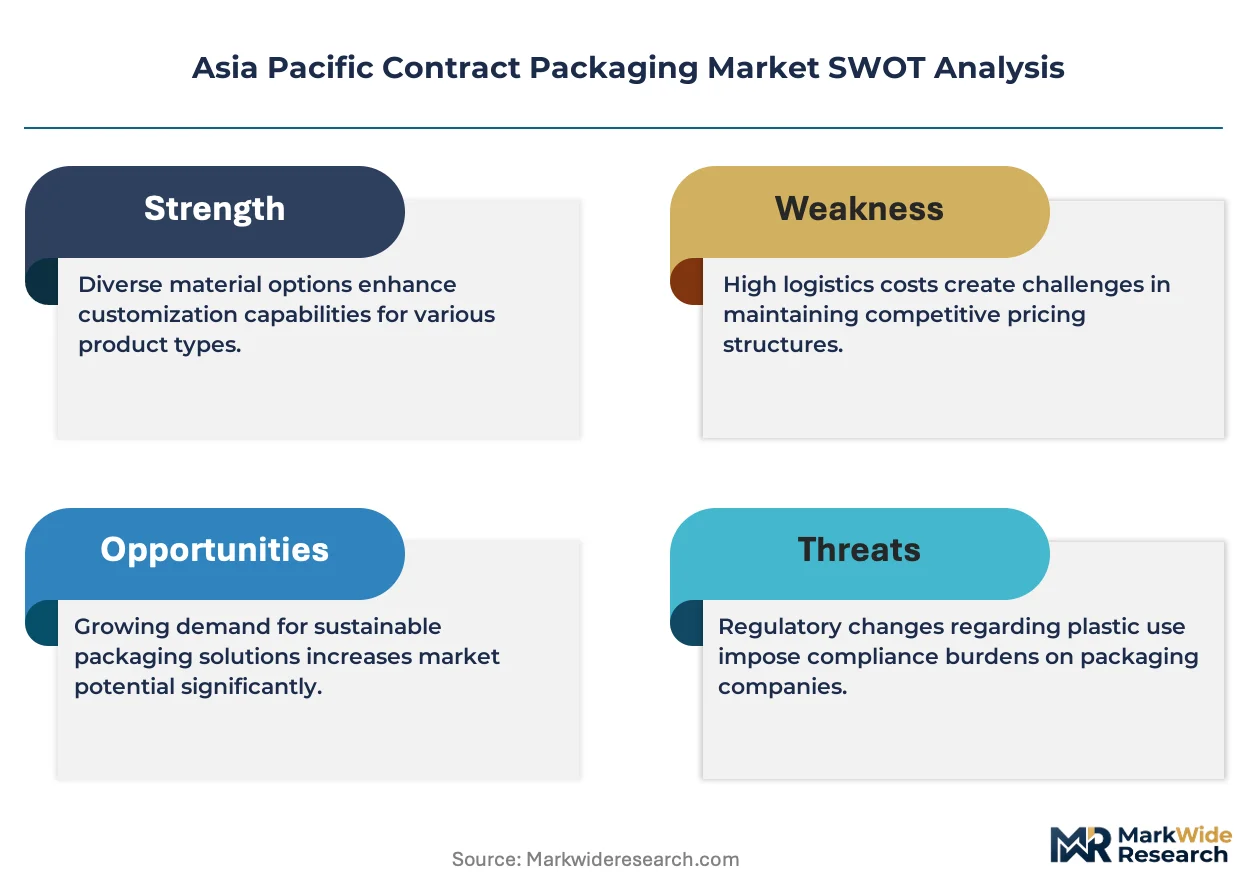
- Polymer Feedstock Volatility:Flexible packaging substrates remain exposed to propylene and ethylene price swings, compressing margin visibility for multi-year contract commitments.
- Equipment Supplier Concentration:High-speed aseptic filling lines source predominantly from German and Swiss OEMs, creating capex bottlenecks and extended lead times for Asia Pacific capacity expansion.
- SAMR Food-Contact Registration:China's evolving substrate approval timelines delay new flexible film introductions by 12-18 months versus comparable EU REACH registrations.
Strategic Opportunities
- Vietnam Manufacturing Migration:Electronics and medical device brands relocating assembly from China create first-mover openings for ISO 13485-certified contract packers in northern industrial zones.
- Indonesia Domestic Consumption:Halal-certified personal care and food packaging demand outpaces local supplier technical capability, inviting regional contract packer facility investment.
- Dual Carbon Policy Alignment:China's MEE carbon intensity targets and Japan's METI circular economy roadmaps reward packers with verified recycled content and renewable energy sourcing.
Industry Challenges
- Cleanroom Technician Scarcity:ISO 14644-1 Class 7-8 operational certification programs lag regional facility buildout, constraining qualified staffing for pharmaceutical and medical device packaging lines.
- Legacy MES Integration:Brownfield contract packaging sites face protracted ERP-to-line automation connectivity projects when retrofitting for CDSCO or PMDA serialization compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Contract Packaging Market |
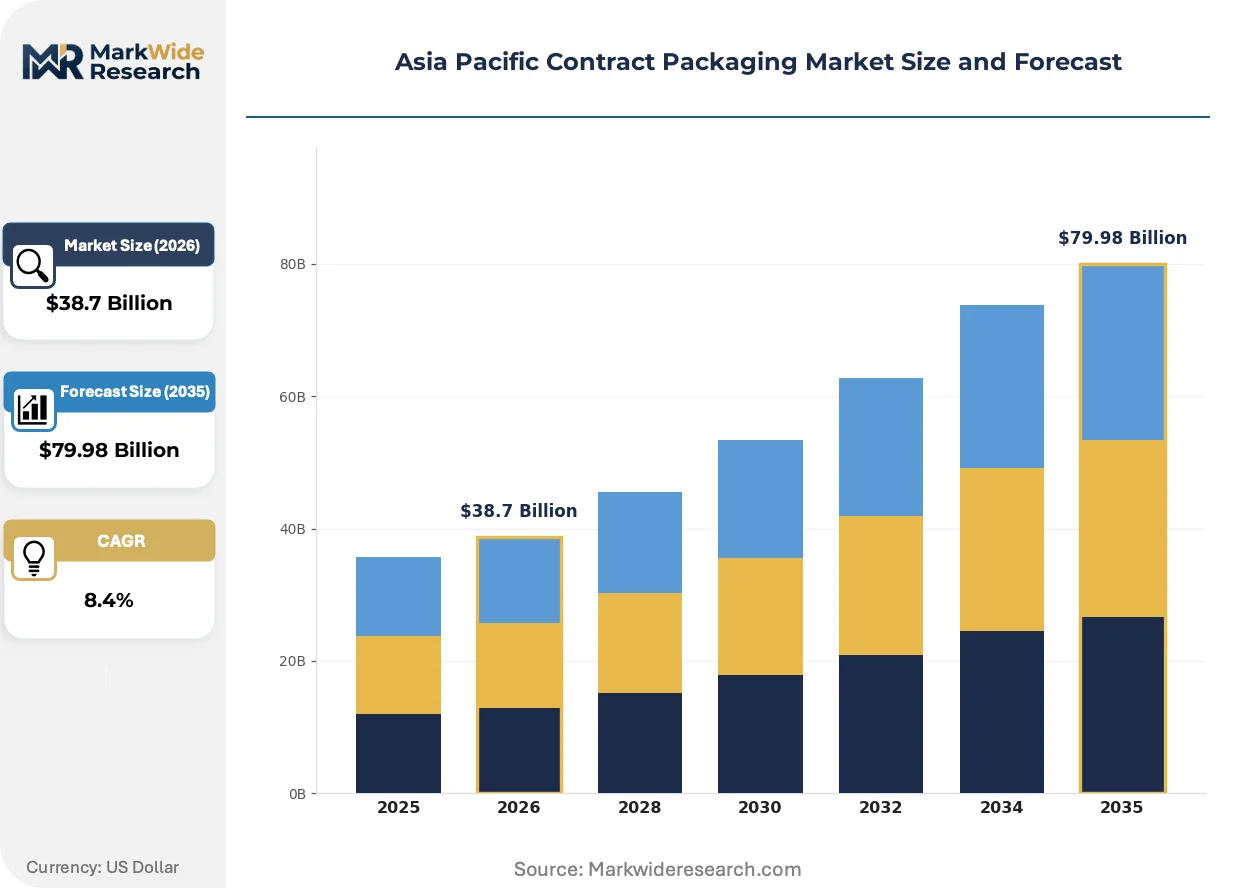
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Packaging, Pharmaceutical Packaging, Electronics Packaging, Consumer Goods Packaging Packaging Type: Flexible Packaging, Rigid Packaging, Semi-Rigid Packaging, Corrugated Packaging Customer Type: Manufacturers, Wholesalers, Retailers, E-commerce End Use Industry: Food & Beverage, Healthcare, Personal Care, Industrial |
| Companies Covered | MJS Packaging, TricorBraun, Berkeley Contract Packaging, Sharp Packaging Services, Premier Packaging, Central Glass, Stamar Packaging, DHL, Unicep, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Contract Packaging Market Strategic Shifts
Automation architectures and substrate chemistry are converging to compress changeover times and expand sustainable format viability across temperature-sensitive and high-volume segments.
Modular robotic workcells are modularizing secondary packaging operations previously locked to dedicated lines. Pharmaceutical and personal care contract packers in Japan and South Korea deploy these units to absorb SKU proliferation without proportional floor space expansion. The technology is modularizing capital deployment models, enabling capacity scaling in 6-month increments rather than 3-year greenfield cycles.
PMDA and METI coordination on medical device sterile barrier standards is harmonizing Northeast Asian specification requirements. The convergence reduces packer qualification burden for multinationals serving Japan, South Korea, and Taiwan from single facilities. Electronics and drug-device combination products face the steepest documentation adjustments as ISO 11607-1 compliance timelines tighten.
Direct-to-patient pharmacy channels are fragmenting order profiles toward micro-lots and individualized kit configurations. Contract packers serving Australian and Singaporean telehealth platforms retrofit lines for lot-size-one flexibility. The shift is most visible in chronic disease management segments where patient-specific dosing compliance packaging replaces standard bulk formats.
Asia Pacific Contract Packaging Market Segmentation
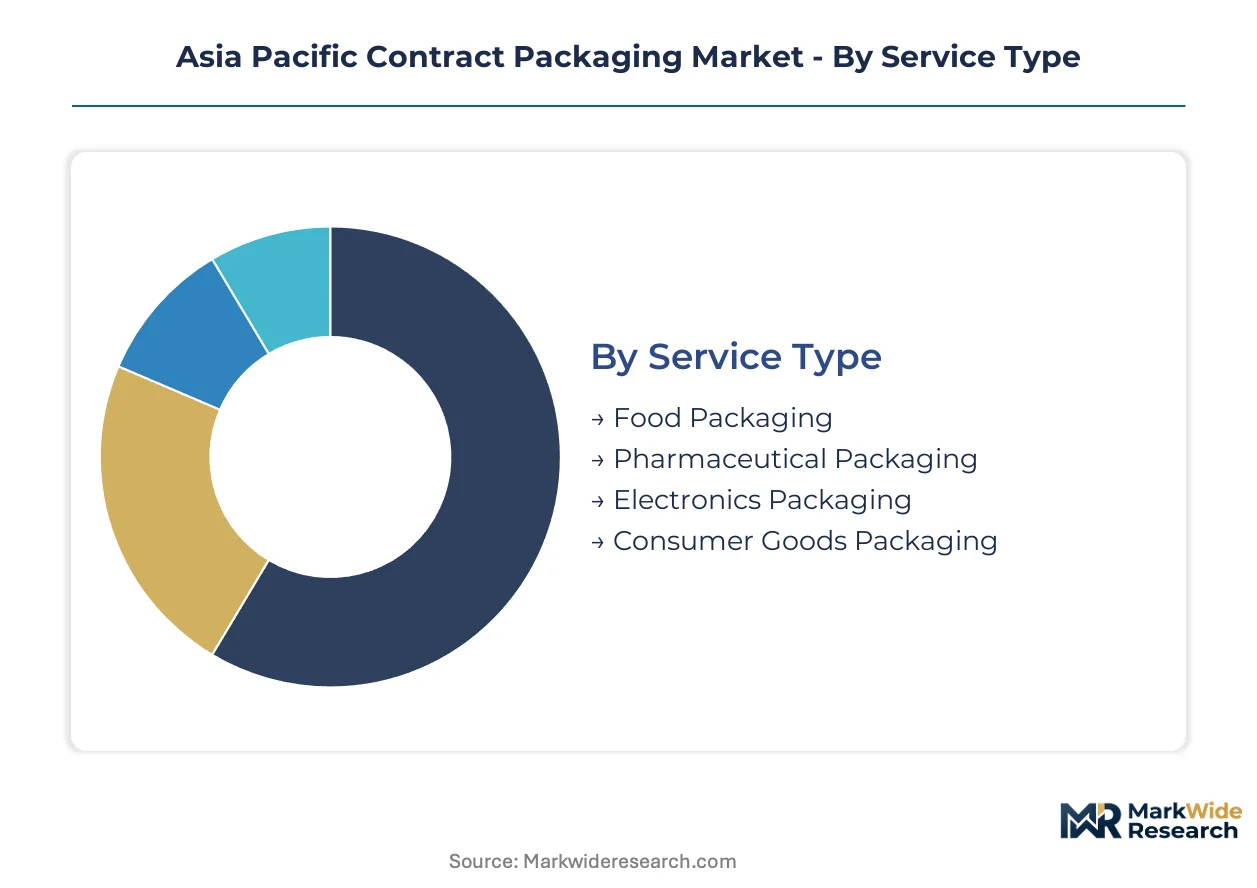
Asia Pacific contract packaging capacity fragments across four distinct segmentation axes, each commanding divergent compliance protocols and automation investments. Service type and packaging format classifications determine facility certification requirements, while customer channel and end-use specifications dictate line configuration and geographic placement strategies.
Service Type:
Standalone service operations dominate high-volume segments, whereas embedded packaging partnerships integrate directly into brand-owner manufacturing campuses.
- Pharmaceutical Packaging:Sterile barrier systems and cold-chain protocols command premium facility investments across China's Yangtze River Delta and India's pharmaceutical clusters. CDSCO serialization mandates and Japan's PMDA sterile barrier standards pull capacity toward temperature-certified cleanrooms with integrated track-and-trace infrastructure.
- Food Packaging:High-output flexible film and modified atmosphere configurations serve both domestic retail and export-oriented processors. China's SAMR food-contact material registrations and Japan's METI circular economy specifications constrain substrate selection timelines, compressing format innovation cycles.
- Electronics Packaging:ESD-safe rigid containers and moisture-barrier formats protect semiconductor and component shipments from Vietnam's northern industrial zones to South Korean assembly hubs.
- Consumer Goods Packaging:SKU-intensive secondary and tertiary configurations absorb modular robotic workcells for rapid changeover across personal care and household product portfolios.
Volume placements concentrate in Food Packaging; the faster expansion belongs to Pharmaceutical Packaging.
Packaging Type:
Cost tier stratification separates commodity substrate formats from precision-engineered barrier systems requiring specialized equipment footprints.
- Flexible Packaging:Multi-layer films and pouches deliver material efficiency for food and personal care applications. Polymer feedstock volatility from propylene and ethylene price swings compresses margin visibility for multi-year contract commitments across Southeast Asian converters.
- Rigid Packaging:Injection-molded and thermoformed containers retain margin concentration in pharmaceutical and electronics segments where dimensional precision and barrier integrity are non-negotiable. TricorBraun anchors regional supply for high-value drug formulations through specialized rigid container expertise.
- Semi-Rigid Packaging:Blister packs and clamshells bridge protection and display requirements for medical device and consumer electronics applications.
- Corrugated Packaging:Right-sized box configurations and automated fulfillment systems capture e-commerce channel expansion across Australian and Singaporean direct-to-patient platforms.
Flexible formats dominate unit economics; rigid systems capture value concentration.
Customer Type:
Channel-specific order profiles fragment lot sizes, with direct-to-consumer channels forcing line retrofits for micro-lot flexibility.
- E-commerce:Direct-to-patient pharmacy and telehealth platforms in Australia and Singapore drive lot-size-one kit configurations for chronic disease management segments. Automated fulfillment architectures compress changeover times from bulk to individualized dosing compliance packaging.
- Manufacturers:Brand-owner outsourcing of primary and secondary packaging execution concentrates demand in China's coastal manufacturing clusters serving simultaneous domestic and export volumes.
- Wholesalers:Intermediate distribution channels require standardized tertiary packaging configurations for palletized logistics across ASEAN trade corridors.
- Retailers:Private-label and shelf-ready packaging specifications demand rapid format switching for seasonal promotional cycles.
Manufacturer relationships anchor capacity utilization; e-commerce channels are gaining share fastest.
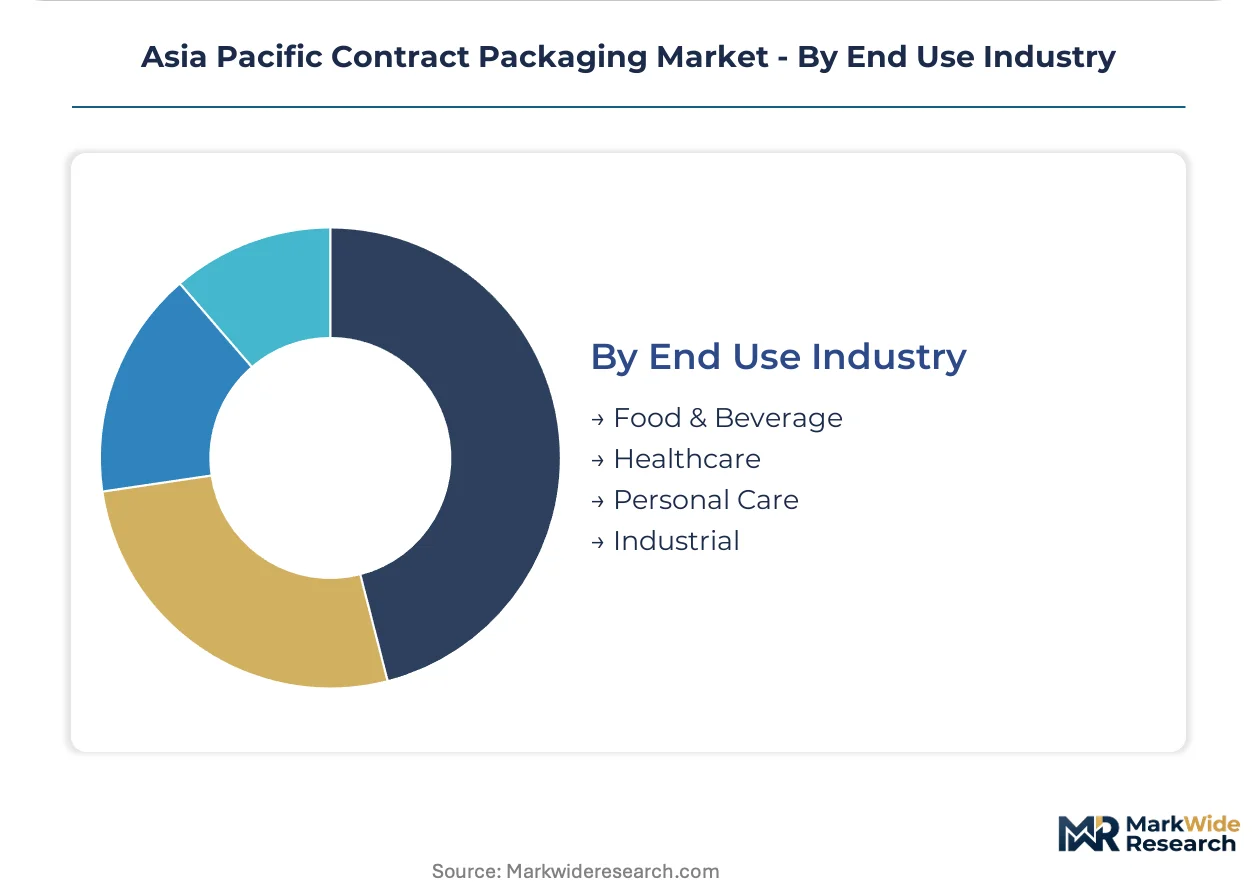
End Use Industry:
Application-specific barrier and compliance requirements partition facility certifications across ISO 14644-1 cleanroom grades and food safety standards.
- Healthcare:Biologic cold-chain protocols and sterile barrier requirements redistribute contract packaging capacity toward temperature-certified facilities. Sharp Packaging Services dominates compliance labeling and sterile barrier systems for regulated medical products across Japan and South Korea.
- Food & Beverage:Extended shelf-life and modified atmosphere specifications drive flexible packaging substrate selection, constrained by China's evolving SAMR food-contact registration timelines.
- Personal Care:Halal-certified packaging demand in Indonesia outpaces local supplier technical capability, inviting regional contract packer facility investment.
- Industrial:Chemical-resistant and bulk container formats serve manufacturing supply chains with lower compliance overhead but higher volume throughput requirements.
Healthcare commands premium pricing; Food & Beverage sustains volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's coastal manufacturing clusters while consumption fragments across emerging ASEAN markets. India's pharmaceutical export engine and Japan's precision medical device demand pull capacity toward divergent compliance architectures. Vietnam and Indonesia absorb manufacturing migration seeking lower-cost sterile barrier and flexible film execution.
China
Yangtze River Delta and Pearl River Delta clusters serve simultaneous domestic brand and multinational export demand from single-site footprints. SAMR food-contact material registrations delay new flexible film introductions by 12-18 months versus comparable EU REACH timelines. Shanghai and Suzhou host temperature-certified facilities capturing biologic cold-chain packaging investment from domestic specialty medicine producers.
India
CDSCO serialization mandates compel domestic contract packers to deploy line-level digital infrastructure for pharmaceutical export compliance. The PLI scheme for pharmaceuticals subsidizes sterile barrier capacity expansion across Maharashtra and Gujarat pharmaceutical corridors. Ahmedabad and Hyderabad clusters anchor integrated packaging-IT service providers serving European and North American export markets.
Japan
PMDA and METI coordination on medical device sterile barrier standards harmonizes Northeast Asian specification requirements for multinationals. Kanto and Kansai regions concentrate ISO 14644-1 Class 7-8 cleanroom operations for high-value drug-device combination products. Tokyo-Osaka industrial corridor facilities reduce packer qualification burden for Taiwan and South Korea market access.
South Korea
MFDS biologic cold-chain protocols pull investment toward active temperature-control packaging formats in Seoul Capital Area and Busan-Ulsan clusters. Electronics packaging demand from semiconductor producers drives ESD-safe rigid container specialization. Daegu-Gyeongbuk medical device assembly hubs contract sterile barrier execution from regional packers meeting tightened ISO 11607-1 compliance timelines.
Vietnam
Electronics and medical device brands relocating assembly from China create first-mover openings for ISO 13485-certified contract packers. Northern industrial zones around Hanoi and Hai Phong absorb capacity investment previously directed toward Pearl River Delta facilities. Japanese and South Korean component suppliers drive demand for moisture-barrier formats protecting semiconductor shipments to regional assembly hubs.
Asia Pacific Contract Packaging Market Competitive Environment
Top-tier vendors anchor multi-country sterile barrier networks, while mid-tier specialists capture single-country flexible film and rigid container segments. The vendor base stratifies across three tiers: integrated healthcare packaging platforms, regional rigid container specialists, and single-site flexible film converters. Two strategic archetypes dominate: compliance-heavy pharmaceutical packers with cleanroom certifications, and volume-driven food and consumer goods operators with rapid changeover capabilities. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for substrate technology access.
Among healthcare-focused specialists, MJS Packaging and Sharp Packaging Services occupy positions exemplifying the sterile barrier and compliance labeling archetype for regulated medical products. TricorBraun anchors the rigid container specialization vector for high-value drug formulations across Northeast Asian markets. These three entities represent distinct competitive positioning: integrated healthcare compliance, rigid container engineering, and pharmaceutical serialization infrastructure respectively.
| Leading Market Players |
|---|
| MJS Packaging |
| TricorBraun |
| Berkeley Contract Packaging |
| Sharp Packaging Services |
| Premier Packaging |
| Central Glass |
| Stamar Packaging |
| DHL |
| Unicep |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon policy and Japan's METI circular economy roadmaps gate qualified supply access and premium-tier pricing power for contract packers demonstrating verified recycled content and renewable energy sourcing. Buyers in pharmaceutical and food segments increasingly require carbon intensity documentation as a threshold for contract eligibility, compressing margins for facilities without certification infrastructure.
Pricing Analysis
Margin tightening in standard-tier flexible packaging reflects propylene and ethylene feedstock volatility compressing multi-year contract visibility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644-1 certified cleanroom operations from commodity converters and unqualified regional suppliers. Pharmaceutical and medical device buyers show lowest price sensitivity due to sterile barrier compliance requirements, while food and consumer goods segments drive aggressive cost-down negotiations. Pricing pressure stems from polymer price swings and extended SAMR registration timelines delaying substrate innovation cycles.
Supply Chain Analysis
Dual-sourcing mandates from multinational brand owners require contract packers to qualify redundant facilities across China's Yangtze River Delta, India's pharmaceutical corridors, and Vietnam's northern industrial zones. Raw material dependencies center on polymer resins, specialized films, and German-Swiss OEM equipment for aseptic filling lines. Single-source vulnerability concentrates in high-speed filling equipment where extended lead times constrain capacity expansion. Distribution runs through coastal manufacturing clusters serving simultaneous domestic and export demand with multimodal logistics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific contract packaging market sits in a technology-transition phase as modular robotic workcells displace dedicated line configurations and digital serialization infrastructure replaces legacy track-and-trace systems.
For Market Incumbents: Anticipate margin compression from polymer feedstock volatility by securing backward integration into recycled content supply chains and renewable energy sourcing. Defend market position through M&A targeting ISO 13485-certified facilities in Vietnam and Indonesia before first-mover capacity saturates. Prioritize CDSCO and PMDA serialization compliance as a competitive moat against regional converters lacking integrated packaging-IT capabilities.
For New Entrants and Emerging Players: Capture white-space opportunity in Halal-certified personal care packaging for Indonesia's domestic consumption growth and ISO 13485 medical device execution in Vietnam's northern industrial zones. Electronics brands relocating assembly from China represent the most penetrable demand segment for new sterile barrier capacity. Lead with sustainability credentials aligned to China's MEE carbon intensity targets as a differentiated go-to-market position.
For Investors and Strategic Acquirers: CDSCO serialization mandate enforcement is the leading indicator that integrated packaging-IT service providers will command premium valuations over commodity converters. Long-term viability favors contract packers with multi-country cleanroom networks spanning pharmaceutical, medical device, and biologic cold-chain segments. Target acquisition archetypes include regional rigid container specialists with TricorBraun-scale technical expertise and pharmaceutical serialization infrastructure providers in India and Japan.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Robotic Workcell Deployment | Absorbs SKU proliferation without proportional floor space expansion in Japan and South Korea facilities. |
| ISO 13485 Certification Investment | Enables first-mover positioning in Vietnam's medical device packaging migration from China. |
| Recycled Content Supply Integration | Aligns with China's MEE carbon targets and Japan's METI circular economy roadmaps for contract eligibility. |
| Serialization Infrastructure Upgrade | Meets CDSCO pharmaceutical export mandates and PMDA medical device track-and-trace requirements. |
| Temperature-Certified Facility Expansion | Captures biologic cold-chain investment from China's specialty medicine producers and South Korean MFDS protocols. |
Study Parameters
Document review covered regulatory filings from CDSCO, PMDA, SAMR, and METI, complemented by interviews with contract packaging operations directors, pharmaceutical supply chain managers, medical device regulatory affairs leads, and flexible film procurement specialists at multinational brand owners. Secondary sources included customs trade data, ISO certification registries, and equipment manufacturer order backlogs. Bottom-up facility capacity assessments and top-down end-use demand estimates were triangulated to validate market sizing.
Historical capacity utilization trends were cross-referenced against panel input from industry stakeholders to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, packaging format, customer channel, and end-use industry with geographic regulatory cluster differentiation. CAGRs were derived from facility investment pipelines and customer contract renewal patterns. Forecast inputs incorporated polymer feedstock price trajectories and SAMR registration timeline assumptions for flexible film substrates.
The model holds under stable regulatory enforcement timelines for serialization mandates and carbon intensity targets; deviation in polymer price volatility or equipment supplier lead times would shift capacity expansion assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global OTA Testing Market
Others
Global Automotive LED Lighting Market
Others
Africa Cotton Market
Others
Software Synthesizers Market
Others
Cellular-Connected Laptops Market
Others
Middle East and Africa Surface Analysis Market
Others
Moveable Water Tap Market
Others
Sports Events Market
Others
Digital Audio Decoders Market
Others
Industrial Personal Computer Market
Others
Paraffin Physical Therapy Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Human Enhancement Technology Market
Others
South Korea Smart Home Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Retail Media Platform Market