
 US Tablet Market | 2026-2036
US Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
US Tablet Market Insights
Subscription-based device management and software-defined security layers are pivoting how vendors monetize tablet deployments beyond hardware margins. Apple Inc. leverages its vertical integration across silicon, operating system, and education app ecosystem to sustain premium positioning in institutional channels. Microsoft Corp. anchors enterprise penetration through Windows tablet continuity with Azure Active Directory and Office 365 workflows. Dell Technologies Inc. competes in ruggedized and healthcare-certified segments where service contracts extend replacement cycles.
A tablet is a portable, slate-form computing device with a touchscreen display, integrated battery, and wireless connectivity, typically measuring 7 to 12 inches diagonally and employing ARM or x86 processors with solid-state storage; its primary purpose is to deliver media consumption, productivity tasks, and specialized vertical applications without integrated physical keyboards. Standard tablets occupy the volume base but face margin compression as replacement cycles lengthen, while 2-in-1 devices and detachable tablets capture higher average selling prices by bridging laptop functionality. The education sector channel concentrates procurement through bulk purchasing cooperatives, whereas healthcare worker demand prioritizes antimicrobial housings and HIPAA-compliant encryption standards.
The FCC governs wireless spectrum allocation and E-Rate subsidy eligibility that directly shapes district-level purchasing timelines and connectivity specifications. FDA oversight of tablet-based medical devices and diagnostic software creates compliance thresholds for healthcare deployments. OSHA ergonomic guidelines influence enterprise fleet decisions for field worker tablet use. Stakeholders must monitor how NHTSA rules on driver-distraction standards affect in-cab logistics tablet specifications and liability exposure.
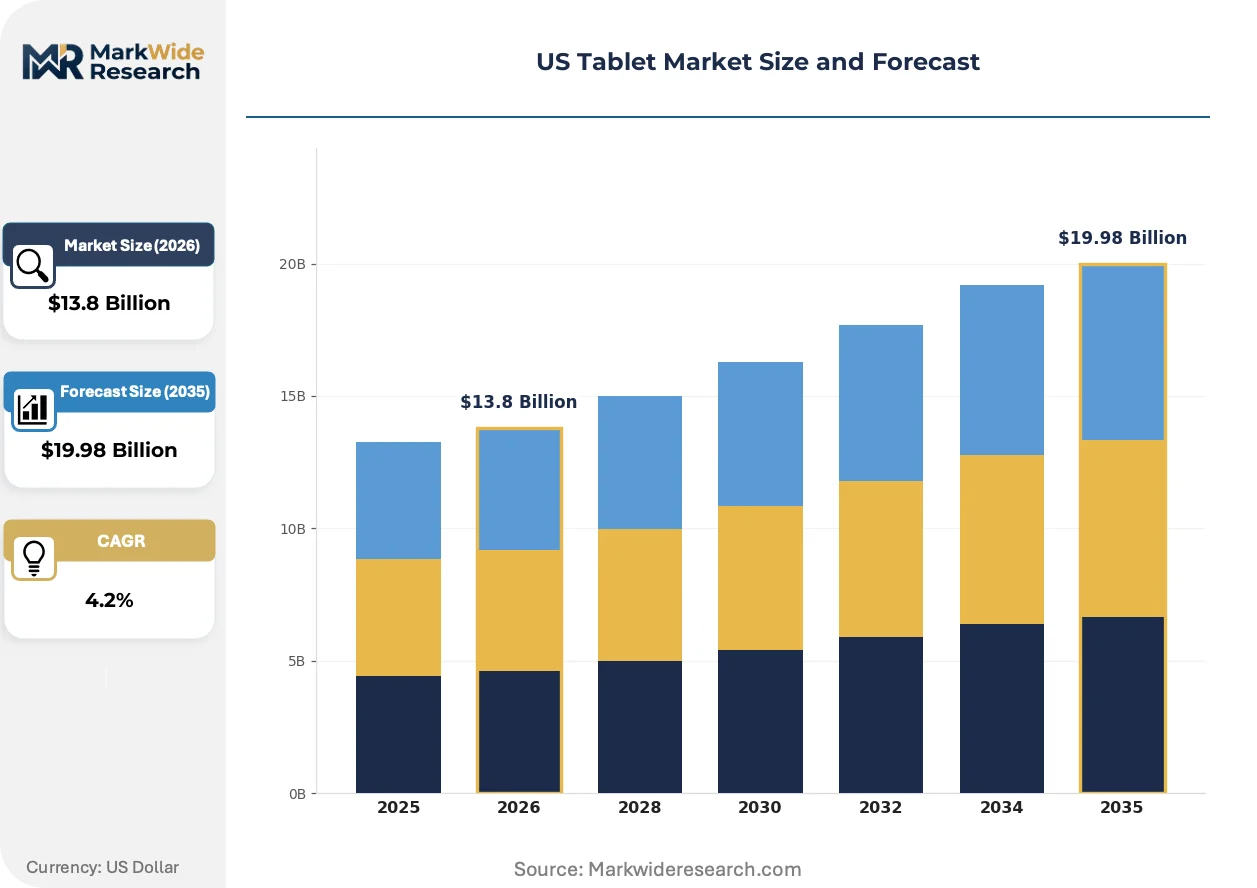
Market Dynamics
FCC E-Rate funding recalibration is compressing procurement timelines for K-12 districts while simultaneously elevating connectivity specifications as a primary vendor selection criterion.
Growth Catalysts
- 1:1 Device Mandates:Texas, California, and Florida school districts are accelerating bulk purchasing cycles through cooperative procurement agreements, creating concentrated demand spikes in Q2 and Q3 budget windows.
- HIPAA-Compliant Form Factors:Healthcare worker tablet demand prioritizes antimicrobial housings and encryption standards that exceed baseline consumer specifications, opening premium pricing tiers.
- OSHA Field Ergonomics:Enterprise fleet managers for logistics and utilities are refreshing device specifications to meet updated ergonomic guidelines for mobile worker safety.
Market Restraints
- Display Panel Concentration:LCD and OLED substrate supply concentrates among East Asian foundries, exposing US assemblers to shipping cost volatility and tariff exposure.
- Silicon Supply Rigidity:ARM-based SoC availability remains constrained by foundry allocation priorities favoring smartphone and automotive volumes over tablet SKUs.
- Replacement Cycle Extension:K-12 asset management software now targets five-year refresh intervals versus three-year norms, compressing annual unit demand.
Strategic Opportunities
- Rural Broadband Gaps:USDA Rural Development grants and FCC Rural Digital Opportunity Fund disbursements are funding tablet-plus-hotspot bundles for unserved counties in Appalachia and the Great Plains.
- Detachable 2-in-1 Convergence:Keyboard-dock accessories and stylus integration are blurring hardware category boundaries, capturing notebook-adjacent budgets from IT procurement officers.
- Subscription Management Layers:Device-as-a-service packaging with embedded MDM and security software is displacing capital expenditure models in mid-sized district contracts.
Industry Challenges
- FCC Compliance Velocity:E-Rate eligibility documentation and competitive bidding requirements extend sales cycles by 90-120 days, straining vendor cash conversion.
- Legacy System Interoperability:District IT departments face integration friction between new tablet fleets and entrenched on-premise student information systems requiring custom API development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tablet Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $19.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tablets, 2-in-1 Devices, Rugged Tablets, Detachable Tablets Operating System: iOS, Android, Windows, Chrome OS Screen Size: 7 inches, 8 inches, 10 inches, 12 inches End User: Education Sector, Business Professionals, Healthcare Workers, Casual Users |
| Companies Covered | Google LLC, Dell Technologies Inc., Apple Inc., Microsoft Corp., HP Inc., Samsung Electronics Co. Ltd., Lenovo Group Ltd., Acer Inc., Amazon.com Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tablet Market Trends and Innovations
Silicon efficiency gains and connectivity protocol evolution are redefining performance benchmarks while procurement digitization reshapes vendor-customer relationships.
ARM-based system-on-chip architectures with dedicated neural processing units are expanding into education and healthcare tablets, enabling on-device inference for accessibility tools and diagnostic imaging. K-12 special education departments and rural health clinics are adopting these configurations fastest. The shift is expanding into mid-tier price bands previously reserved for basic consumption devices.
FCC E-Rate Modernization Order provisions now mandate Wi-Fi 6E compatibility for indoor connectivity subsidies, forcing hardware redesigns ahead of full spectrum availability. District technology coordinators must certify backward compatibility while future-proofing infrastructure investments. California and Texas procurement cooperatives are incorporating these specifications into 2025-2026 bid templates.
Bulk purchasing cooperatives and state-level contract vehicles are consolidating vendor selection authority away from individual districts. Value-added resellers and direct OEM sales teams are losing access to smaller accounts as intermediate aggregators capture commission structures. Florida and North Carolina education purchasing alliances exemplify this concentration most visibly.
US Tablet Market Segmentation
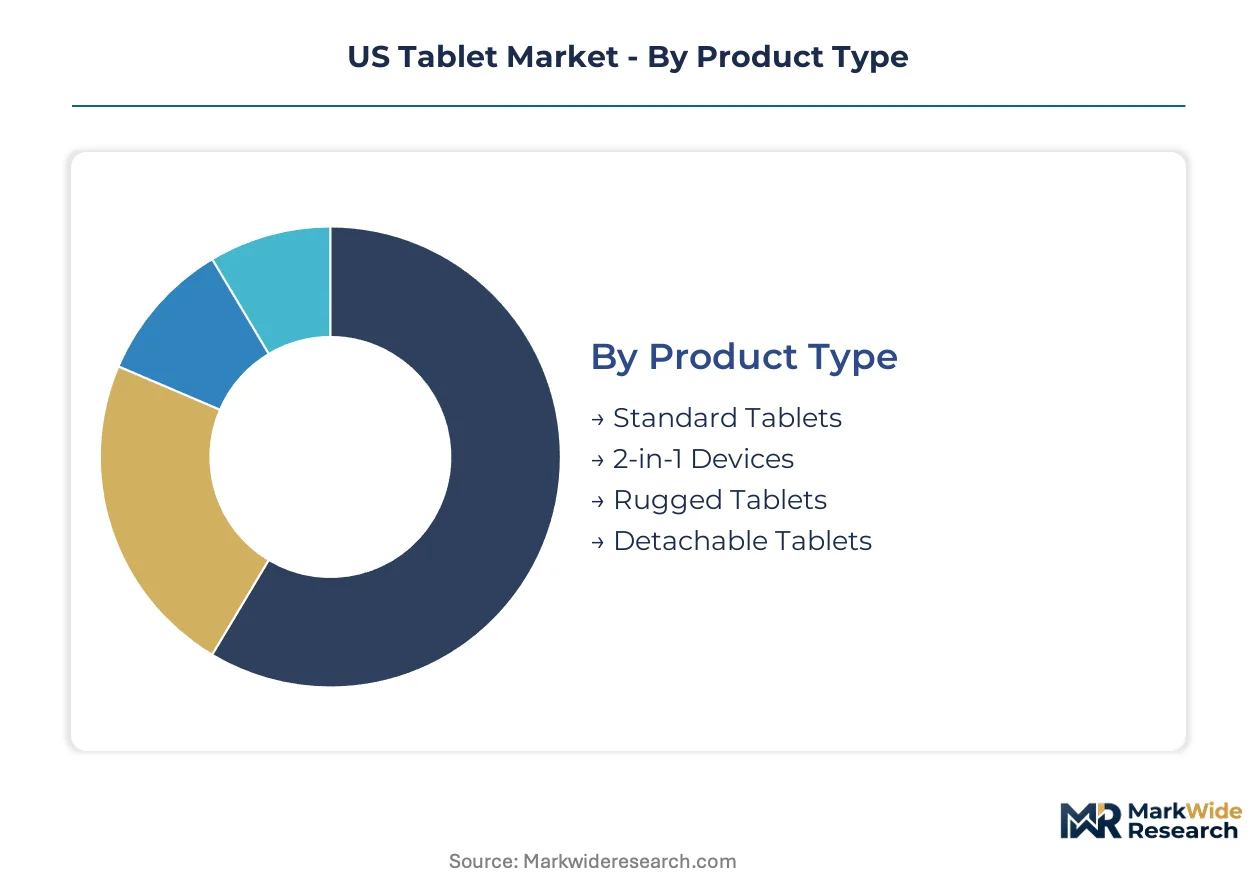
Tablet procurement patterns diverge sharply across use cases, with institutional buyers prioritizing manageability and durability while consumer segments chase display quality and ecosystem continuity. Understanding these segment boundaries reveals where margin pools concentrate and where volume commoditization threatens vendor profitability.
Product Type:
District IT directors and fleet managers weigh total cost of ownership against functional flexibility when selecting form factors for deployment.
- Standard Tablets:Slate-form devices with fixed displays and ARM-based processors dominate K-1 classroom consumption and content delivery. Texas and California procurement cooperatives source these in highest volumes for 1:1 programs, though five-year refresh cycles compress annual unit demand.
- 2-in-1 Devices:Convertible form factors with 360-degree hinges and integrated keyboards bridge laptop replacement budgets in enterprise settings. Healthcare administrators in Florida hospital systems favor these for clinical documentation workflows requiring both tablet portability and keyboard precision.
- Rugged Tablets:MIL-STD-810G certified housings with IP65 ingress protection serve field service technicians and utility workers across OSHA-regulated environments.
- Detachable Tablets:Magnetic keyboard docks and stylus-compatible displays target hybrid workers needing periodic laptop functionality without full notebook weight.
Standard Tablets lead on scale; 2-in-1 Devices lead on momentum.
Operating System:
Enterprise security posture and existing application portfolios lock procurement decisions into specific platform ecosystems.
- iOS:Closed architecture with centralized MDM deployment and App Store curation dominates affluent suburban districts and healthcare institutions requiring HIPAA-aligned encryption standards. Apple silicon efficiency extends battery life for all-day student use.
- Android:Open-source flexibility enables OEM customization for specialized verticals, though fragmentation complicates enterprise security policy enforcement across device generations.
- Windows:Active Directory integration and Office 365 continuity anchor enterprise fleet decisions in Fortune 500 field operations and government agencies.
- Chrome OS:Cloud-native architecture with automatic security updates and aggressive price positioning captures budget-constrained rural districts in Appalachia and the Great Plains.
iOS commands premium pricing; Chrome OS gains share fastest in underfunded districts.
Screen Size:
Display dimension selection reflects portability requirements against content readability trade-offs in specific work environments.
- 7 inches:Pocketable form factors suit logistics workers requiring one-handed operation during warehouse picking and delivery confirmation tasks.
- 8 inches:Compact displays balance portability with readability for elementary students and mobile point-of-sale applications in retail.
- 10 inches:The institutional standard for K-12 1:1 programs, offering sufficient canvas for digital textbooks and standardized testing interfaces. FCC E-Rate procurement templates specify this dimension most frequently.
- 12 inches:Laptop-competitive screen real estate targets creative professionals and healthcare specialists reviewing diagnostic imagery requiring fine detail resolution.
10 inches anchors institutional volume; 12 inches climbs fastest as notebook replacement accelerates.
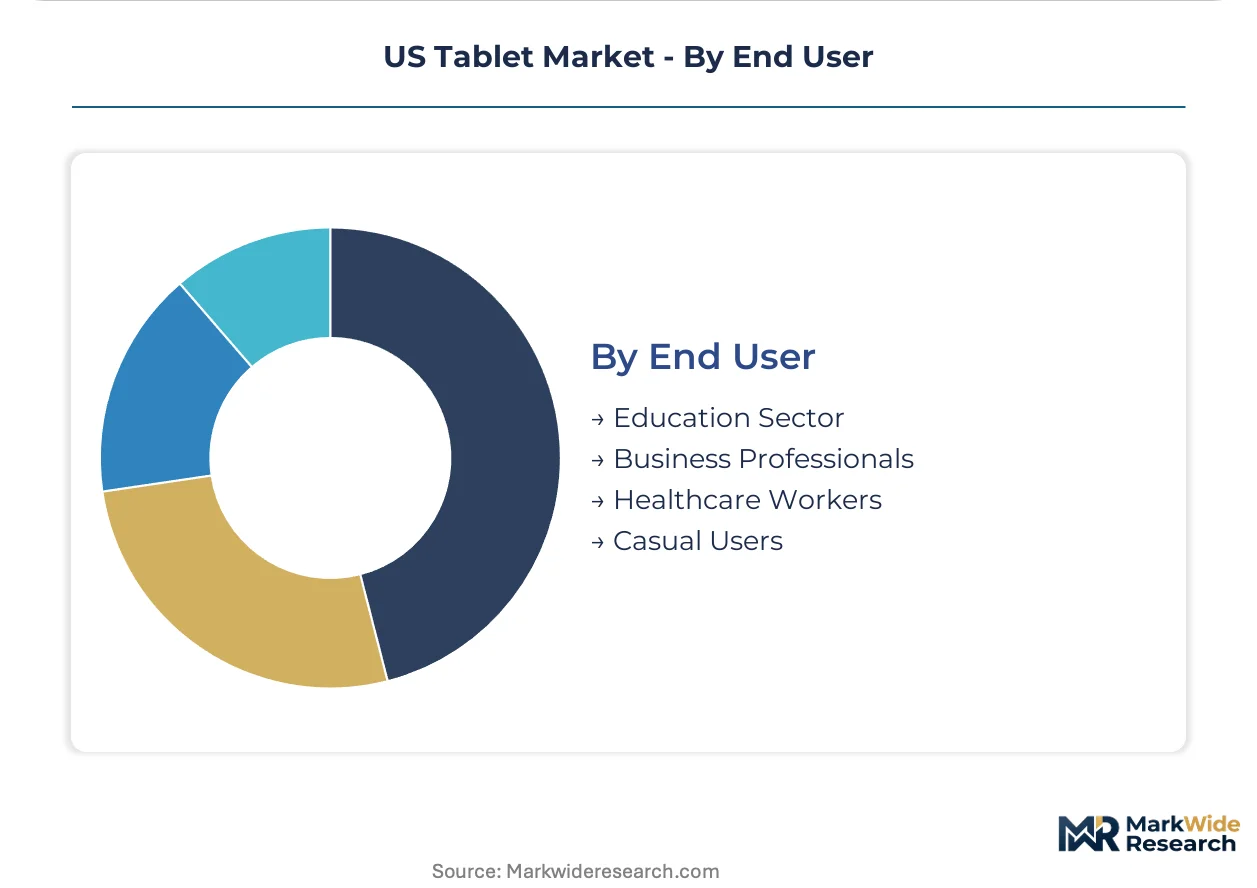
End User:
Budget authority and compliance requirements fragment demand across sectors with diverging technical specifications.
- Education Sector:Bulk purchasing through state cooperatives concentrates volume in Texas, California, and Florida, with FCC E-Rate eligibility dictating connectivity and security specifications. Asset management software now targets extended refresh cycles.
- Business Professionals:Enterprise IT departments prioritize Azure Active Directory integration and zero-trust security architectures for hybrid workforces.
- Healthcare Workers:Antimicrobial housings and HIPAA-compliant encryption standards open premium pricing tiers for hospital and clinic deployments.
- Casual Users:Media consumption and gaming drive replacement demand, though smartphone screen enlargement erodes distinct use cases.
Education Sector leads on unit volume; Healthcare Workers lead on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California procurement volumes exceed Texas deployments by a narrow margin, though both states operate on divergent funding cycles. Florida rounds out the concentrated demand triangle where FCC E-Rate disbursements dictate hardware refresh timing.
California
Los Angeles Unified and San Diego County districts drive bulk purchasing through the California Department of Education's cooperative contracts. State legislation mandates digital equity provisions that extend device lifecycles to five years. Silicon Valley technology clusters supply adjacent districts with direct OEM relationships, bypassing traditional reseller channels.
Texas
Houston Independent School District and Dallas-Fort Worth metroplex systems anchor the nation's largest 1:1 deployment pipeline. Texas Education Agency procurement templates require Wi-Fi 6E compatibility ahead of federal mandates. Austin's technology corridor hosts vendor field offices that coordinate Q2 budget window deliveries.
Florida
Miami-Dade and Broward County districts concentrate southeastern demand for antimicrobial healthcare tablets and education devices alike. State purchasing alliances consolidate formerly fragmented district procurement authority. Orlando's simulation training cluster generates specialized demand for ruggedized tablets in aviation and defense applications.
New York Metro
New York City Department of Education operates the nation's largest municipal tablet fleet with distinct security specifications. State contracts prioritize zero-trust architecture compliance for hybrid workforce deployments. Hudson Valley manufacturing corridors supply assembly and refurbishment services for extended lifecycle programs.
Mountain West
USDA Rural Development grants fund tablet-plus-hotspot bundles across Montana, Wyoming, and Idaho counties with broadband gaps. FCC Rural Digital Opportunity Fund disbursements accelerate deployment timelines in unserved tribal lands. Denver-Boulder technology corridors anchor logistics and field service tablet demand from energy extraction industries.
US Tablet Market Competitive Landscape
Top-tier vendors anchor premium institutional channels, while mid-tier OEMs compete on price positioning in budget-constrained districts. The vendor base stratifies across three functional tiers: silicon-integrated platform owners, enterprise systems integrators, and volume assemblers. Strategic archetypes include ecosystem lock-in specialists, ruggedized vertical players, and cloud-native disruptors. Competitive moves center on MDM subscription bundling and cooperative procurement certification.
Within the ecosystem-integrated tier, Apple Inc. and Microsoft Corp. exemplify divergent platform strategies that shape institutional purchasing criteria. Dell Technologies Inc. anchors enterprise and healthcare-certified segments where service contract extensions displace hardware margin dependence. These three entities occupy positions that reflect the market's segmentation between closed-architecture premium positioning and open-ecosystem flexibility.
| Leading Market Players |
|---|
| Google LLC |
| Dell Technologies Inc. |
| Apple Inc. |
| Microsoft Corp. |
| HP Inc. |
| Samsung Electronics Co. Ltd. |
| Lenovo Group Ltd. |
| Acer Inc. |
| Amazon.com Inc. |
| Others |
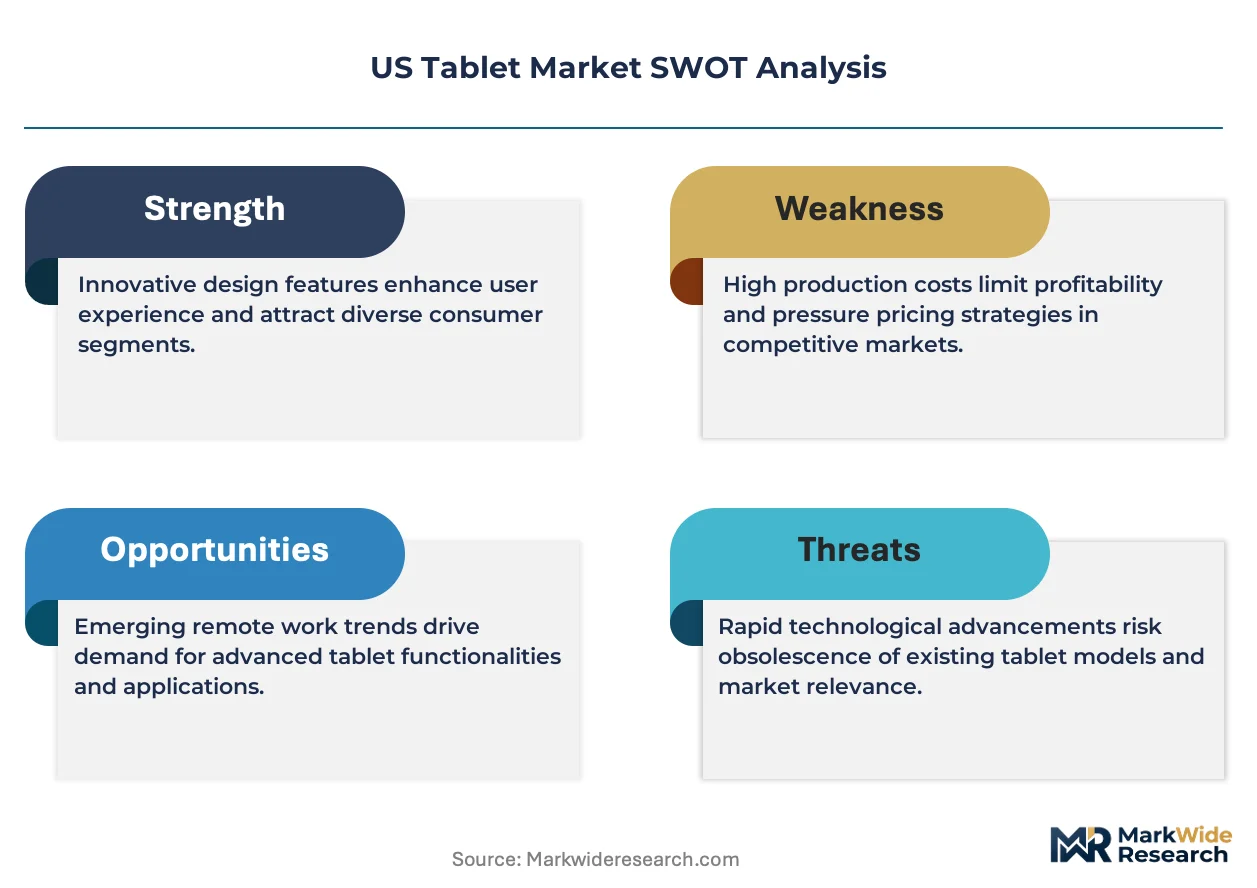
Pricing and Supply Chain Analysis
ARM-based SoC fabrication transitions toward 5nm and 3nm process nodes are simultaneously compressing per-unit silicon costs and concentrating foundry relationships among Taiwan Semiconductor Manufacturing and Samsung Electronics, reshaping how OEMs negotiate component pricing and allocate procurement risk across multi-year district contracts.
Pricing Analysis
Capacity additions in Taiwanese foundries are reshaping price floors for ARM-based tablet processors, enabling mid-tier OEMs to narrow the gap with premium-tier pricing. Three-tier pricing structure across premium, standard, and economy levels separates Apple silicon deployments from Chrome OS volume plays from baseline Android slates. Cost compression in the standard tier is intensifying because K-12 cooperatives now mandate five-year total cost of ownership guarantees. Rural districts in Appalachia exhibit highest price sensitivity; healthcare systems in Florida show lowest sensitivity due to HIPAA compliance premiums.
Supply Chain Analysis
Freight cost volatility from East Asian ports to US distribution centers is forcing OEMs to diversify final assembly locations. Tablet production draws from China, Taiwan, and Vietnam for display substrates, processor wafers, and battery cells respectively. Key inputs include indium tin oxide for touch panels, lithium cobalt oxide for power cells, and rare earth elements for speaker magnets. Tariff exposure on Chinese-assembled finished goods remains the dominant structural risk. Distribution runs through value-added resellers and direct OEM field offices to state procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US tablet market represents a late-cycle quality story where replacement cycle extension and specification inflation favor vendors with service-layer monetization and silicon integration depth.
For Market Incumbents: Anticipate margin compression in standard tablet tiers by accelerating subscription-based device management bundling and securing FCC E-Rate cooperative certification ahead of Wi-Fi 6E mandate expansion. Threat substitution from Chrome OS cloud-native disruptors demands backward integration into education-specific software stacks. Certification investment in FERPA-aligned data governance is the critical defensive lever. For New Entrants and Emerging Players: Direct-to-district digital procurement portals offer the fastest route to bypass incumbent reseller relationships and capture rural broadband gap funding. White-space targets include USDA Rural Development tablet-plus-hotspot bundles in Montana tribal lands and specialized ruggedized deployments for OSHA-regulated field technicians in Denver-Boulder energy corridors. A hardware-as-a-service pricing model with embedded MDM differentiates against capital-expenditure incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Android OEMs lacking service revenue attachment. Long-term viability over the next decade hinges on successful pivot from hardware margin dependence to recurring software revenue. Acquisition target archetype: vertically integrated specialists with captive ARM-based silicon design and existing FCC E-Rate cooperative relationships. The signal to watch is district procurement template consolidation accelerating in Florida and North Carolina purchasing alliances.| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 6E Hardware Redesign | FCC E-Rate subsidy eligibility now mandates backward-compatible connectivity specifications for district contracts. |
| Device-as-a-Service Packaging | Subscription bundling with embedded MDM displaces capital expenditure models in mid-sized K-12 deployments. |
| Rural Broadband Bundle Partnership | USDA Rural Development grants fund tablet-plus-hotspot combinations across unserved Appalachian counties. |
| Healthcare Certification Investment | FDA oversight of diagnostic software creates compliance thresholds opening premium pricing tiers in Florida hospital systems. |
| Cooperative Procurement Certification | Texas Education Agency template approval secures access to the nation's largest 1:1 deployment pipeline. |
Research Methodology
Multiple input streams — district technology coordinator interviews, FCC E-Rate disbursement records, and foundry capacity utilization disclosures — were reconciled to construct bottom-up unit forecasts and top-down value estimates. Primary discussions with K-12 procurement directors, healthcare biomedical engineers, enterprise fleet managers, and value-added reseller executives informed specification trends and pricing dynamics. Secondary validation drew from SEC 10-K filings, USAC E-Rate program data, and hyperscaler education vertical disclosures.
Data-stream reconciliation across shipment tracking, cooperative bid awards, and silicon allocation reports enabled segmentation modeling by product type, operating system, screen size, and end-user vertical throughout the forecast period. CAGRs were derived from replacement cycle elasticity estimates and specification upgrade penetration curves. Key inputs included FCC E-Rate funding trajectory assumptions and ARM-based SoC foundry allocation priorities favoring automotive over tablet volumes.
FCC funding recalibration, foundry allocation shocks, and district procurement consolidation are the dominant revision risks to volume assumptions. Forecasts reflect documented assumptions about E-Rate eligibility continuity and Wi-Fi 6E adoption pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Moonstone Market
Others
Singapore Retail Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Nuclear Power Cables Market
Others
Trusted Platform Module (TPM) Market
Others
Automatic Barriers and Bollards Market
Others
Cat Dry Food Market
Others
Europe Intercom Devices Market
Others
Workbench Tanks Market
Others
Vortexers Market
Others
Convenience Stores Market
Others
Motor Grader Market
Others
Profilometer Market
Others
Europe Indoor LBS Market
Others
Delumper Market
Others
Electrical Calibration Equipment Market