
 Linseed Oil Market | 2026-2036
Linseed Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Linseed Oil Market Analysis
The linseed oil market is recalibrating as cold-pressed artisan grades command widening price premiums over solvent-extracted commodity volumes used in industrial alkyd production. Cargill, Incorporated leverages its North American oilseed crushing infrastructure to anchor supply security for bulk chemical buyers. Henry Lamotte Oils GmbH differentiates through Baltic-origin traceability and food-grade certification pathways that sustain margin capture in specialty segments.
Linseed oil is a drying oil extracted from flaxseed (Linum usitatissimum) containing approximately 50-60% alpha-linolenic acid, which polymerizes upon oxidation to form hard, water-resistant films. Its primary industrial purpose centers on binder applications in paints, coatings, and printing inks where oxidative crosslinking delivers durable surface protection. Boiled linseed oil dominates volume flows into wood finishes and exterior coatings due to faster drying kinetics achieved through metallic drier additives. Raw linseed oil occupies the premium tier serving artists and conservators who reject polymerization catalysts, while stand oil—thermally polymerized to high viscosity—commands specialized niches in glazing mediums and enamel formulations.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain alkyd coating formulations, redirecting demand toward lower-solvent linseed oil derivatives. ECHA REACH restrictions on cobalt-based driers are forcing reformulation investments across European coatings supply chains. China's MEE enforcement of GB standards on architectural coating emissions is tightening import specifications for raw linseed oil destined for domestic paint production. Stakeholders must monitor evolving drier chemistry substitutions and regional certification divergences to preserve formulation compliance and market access across jurisdictions.
Market Dynamics
Alkyd resin reformulation under tightening volatile organic compound limits is forcing coatings manufacturers to rebalance feedstock specifications toward lower-solvent linseed oil derivatives, compressing traditional formulation windows and redrawing procurement priorities.
Growth Catalysts
- REACH Annex XVII cobalt restrictions:ECHA limits on cobalt-based driers are accelerating drier chemistry substitution toward manganese and iron-based alternatives, expanding addressable volume for compliant linseed oil binders in European architectural coatings.
- Artisan wood finish segment:France, Italy, and the United States are witnessing concentrated demand for cold-pressed raw grades among conservators and furniture makers who reject metallic polymerization catalysts.
- China's MEE GB standards:Enforcement of architectural coating emission limits is tightening import specifications for raw linseed oil destined for domestic paint production, pulling higher-grade volumes into the market.
Market Restraints
- Flaxseed supply concentration:Crushing capacity clusters in the Black Sea region and the Canadian prairies, exposing buyers to weather-driven harvest volatility and geopolitical logistics friction.
- Stand oil production bottleneck:Thermal polymerization to high viscosity requires specialized reactor infrastructure with limited installed base, constraining specialty glazing medium supply.
- Soybean oil substitution pressure:Lower-cost drying oil alternatives are capturing share in commodity alkyd formulations where oxidative performance specifications permit flexibility.
Strategic Opportunities
- India's BIS standards alignment:Emerging formaldehyde emission regulations for wood panel products are creating entry pathways for low-VOC natural oil finishes in furniture manufacturing clusters.
- Food-grade certification arbitrage:Cold-pressed volumes meeting FSSAI and EFSA pathways command margin premiums in nutraceutical and culinary applications beyond industrial binders.
- Digital direct-to-artist channels:E-commerce platforms are disintermediating traditional art supply distributors, enabling Baltic-origin traceability storytelling to reach conservators directly.
Industry Challenges
- Drier chemistry requalification:Reaching performance parity with legacy cobalt systems using manganese-iron blends demands extended testing cycles that delay formulation lock.
- Batch consistency for stand oil:Thermal polymerization viscosity targets require precise temperature control that legacy kettle infrastructure struggles to maintain across scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linseed Oil Market |
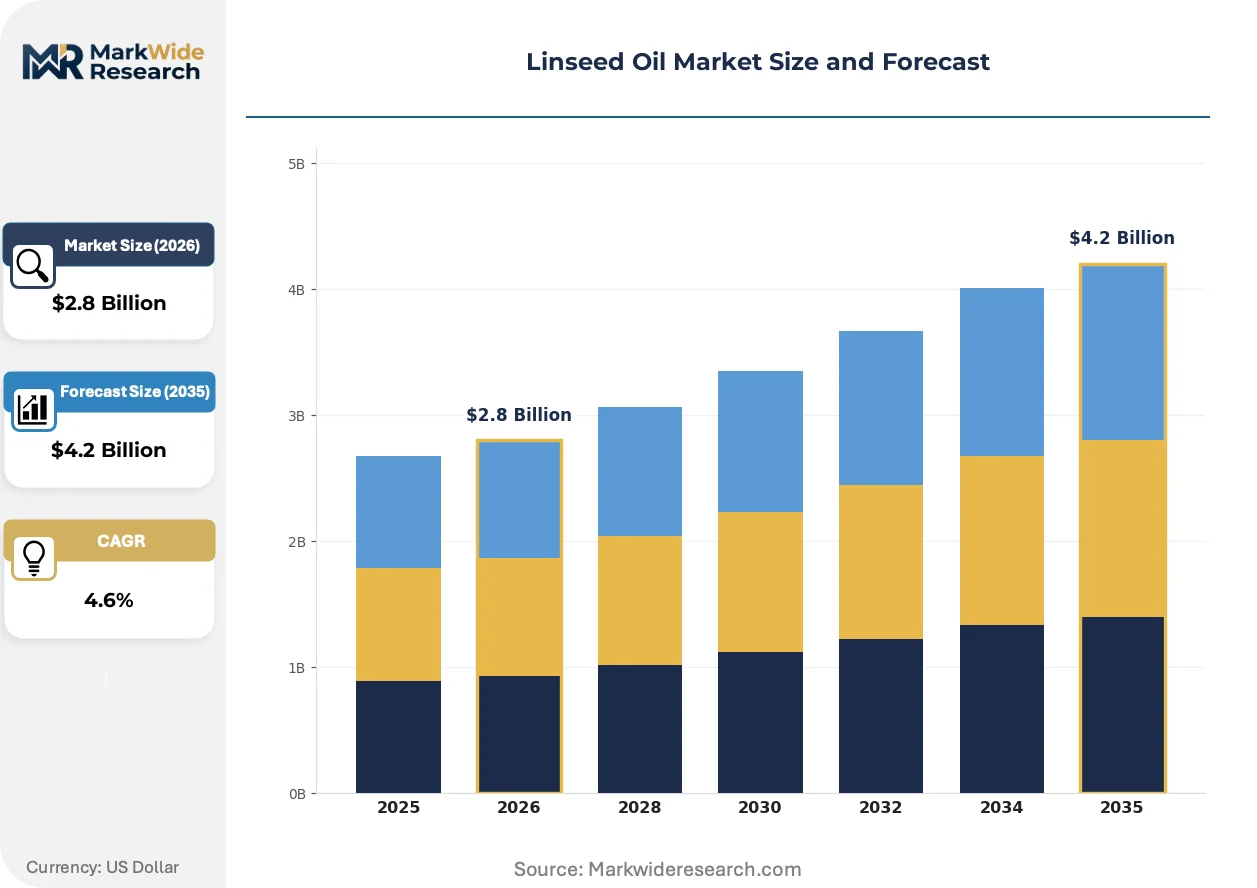
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Linseed Oil, Boiled Linseed Oil, Stand Oil, Flaxseed Oil Application: Paints, Coatings, Inks, Wood Finishes End User: Industrial Users, Craftsmen, Artists, Manufacturers Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Henry Lamotte Oils GmbH, Gustav Heess GmbH, Vandeputte Oleochemicals, Wilmar International Ltd., Krishi Oils Limited, AOS Products Pvt. Ltd., Jamieson Natural Sources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linseed Oil Market Emerging Trajectories
Formulation chemistry and supply chain verification technologies are converging to address compliance pressures while opening premium positioning pathways for traceable, certified grades.
Water-reducible alkyd emulsion technology is integrating surface-active polymer architectures that disperse traditional oil-modified polyester chains in aqueous phases without cosolvent loading. Mid-tier coatings manufacturers in Germany are piloting these systems at commercial scale to preempt EPA NESHAP enforcement actions. The structural consequence is a compression in solvent-borne alkyd volume forecasts as waterborne alternatives capture specification share in architectural maintenance coatings.
China's MEE is tightening GB 18582 enforcement for interior architectural coatings, lowering permissible VOC content thresholds and triggering reformulation investments across domestic paint production. The industrial consequence is a quality bifurcation in import specifications, with higher-grade raw linseed oil separating from commodity solvent-extracted volumes. Waterborne alkyd producers in Guangdong and Jiangsu provinces are responding by qualifying Baltic-origin cold-pressed grades for premium product lines.
Blockchain-enabled provenance verification is reshaping procurement patterns among artisan wood finish buyers who now demand farm-to-barrel traceability documentation. Specialty distributors in France and Italy are replacing traditional spot-market purchasing with contracted Baltic-origin supply chains that embed certification at harvest. This behavioral shift is most visible in the United States conservator segment, where museum-grade specification sheets now require polymerization catalyst disclosure and geographic origin attestation.
Linseed Oil Market Segmentation
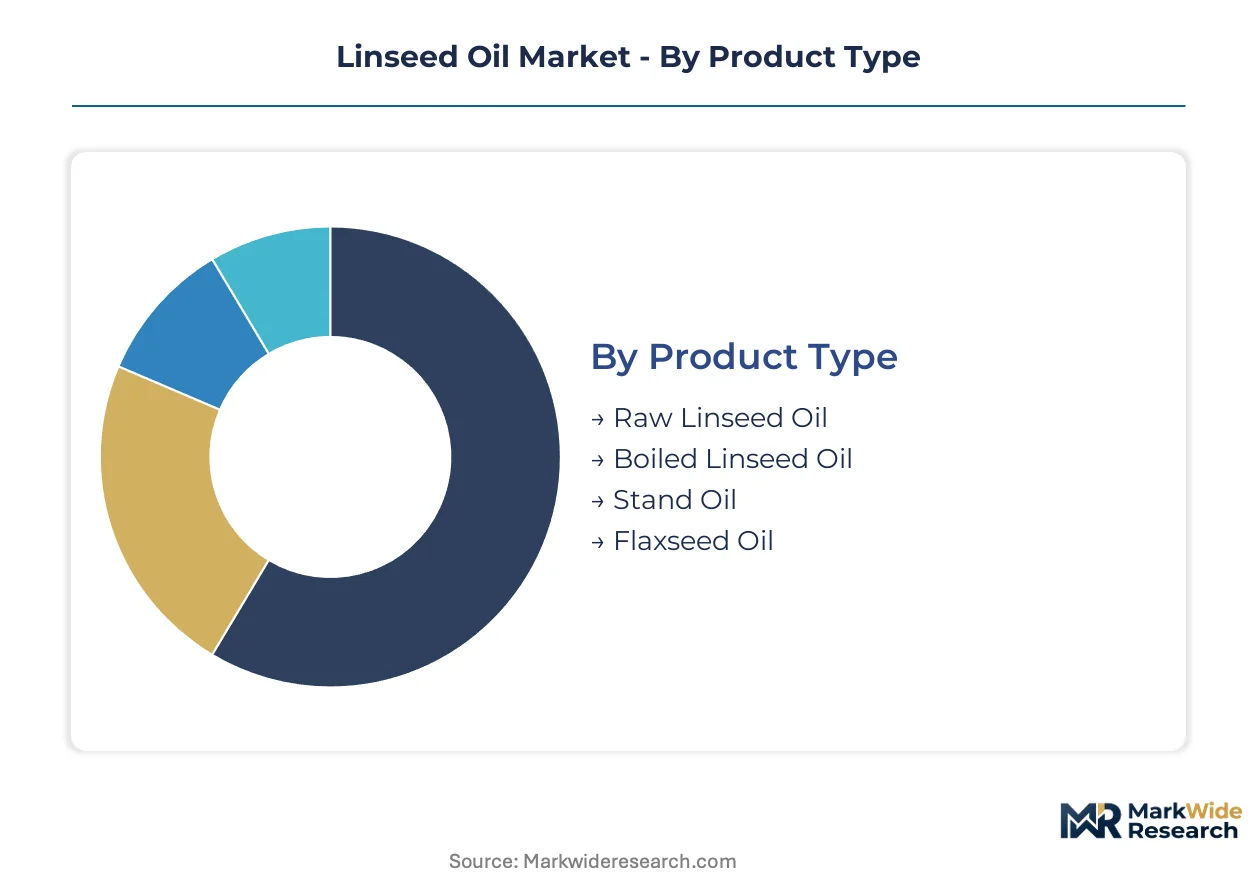
Linseed oil segmentation reflects divergent technical specifications across polymerization states and purity grades. Each category maps to distinct regulatory compliance requirements and margin structures that reshape procurement priorities for coatings formulators and artisan buyers alike.
Product Type:
Integration depth varies sharply across polymerization states, with thermally processed grades embedding directly into industrial alkyd systems while cold-pressed variants serve standalone artisan applications.
- Raw Linseed Oil:Cold-pressed extraction preserves alpha-linolenic acid integrity at 50-60% concentration without metallic drier additives. Museum conservators in France and Italy specify this grade for furniture restoration where polymerization catalyst disclosure is mandatory under emerging provenance documentation standards.
- Boiled Linseed Oil:Metallic drier catalysis accelerates oxidative crosslinking kinetics for wood finish and exterior coating applications. German paint manufacturers are expanding procurement of compliant grades as ECHA REACH cobalt restrictions force reformulation away from legacy drier systems.
- Stand Oil:Thermal polymerization to high viscosity serves specialized glazing medium and enamel formulation niches.
- Flaxseed Oil:Food-grade cold-pressed volumes command nutraceutical and culinary certification premiums beyond industrial binder applications.
Boiled linseed oil leads volumes today; raw linseed oil is gaining share fastest among traceability-focused buyers.
Application:
Cost tier stratification separates commodity alkyd feedstock from premium wood finish specifications, with VOC compliance thresholds acting as the primary sorting mechanism.
- Paints:Alkyd resin formulations consume the largest volume share, with water-reducible emulsion technology now displacing solvent-borne systems under EPA NESHAP and China MEE enforcement.
- Coatings:Architectural maintenance specifications in Germany are piloting aqueous-phase oil-modified polyester dispersions that eliminate cosolvent loading.
- Inks:Oxidative crosslinking binders serve printing applications where drying speed and film durability specifications dominate procurement.
- Wood Finishes:Artisan demand concentrates in cold-pressed raw grades across United States conservator and furniture maker segments.
Paints dominate volume flows; wood finishes are climbing the fastest on artisan premiumization.
End User:
Customer type segmentation tracks divergent specification intensity, from bulk chemical procurement to individual artist-grade certification requirements.
- Industrial Users:Coatings manufacturers in Guangdong and Jiangsu provinces are qualifying Baltic-origin cold-pressed grades for premium waterborne alkyd product lines under tightening GB 18582 enforcement.
- Craftsmen:Furniture makers in France and Italy drive concentrated demand for metallic-drier-free finishes with blockchain-enabled provenance verification.
- Artists:Individual conservators reject polymerization catalysts, requiring geographic origin attestation on specification sheets.
- Manufacturers:Bulk alkyd resin producers face reformulation investment cycles as drier chemistry substitution extends testing timelines.
Industrial users anchor volume demand; craftsmen are expanding most quickly on traceability premiums.
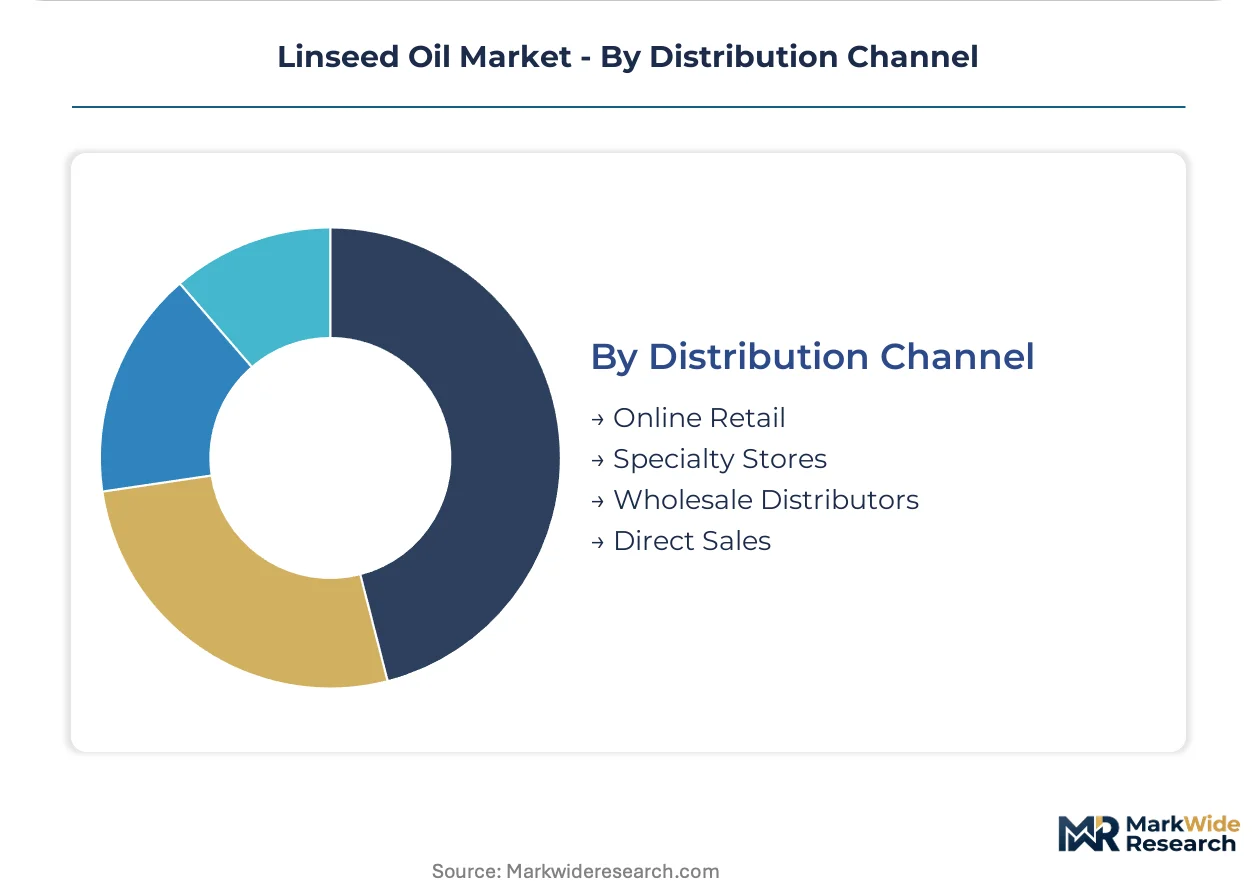
Distribution Channel:
Supply concentration in Black Sea and Canadian prairie crushing regions shapes channel economics, with traceability requirements favoring contracted direct relationships over spot-market purchasing.
- Online Retail:E-commerce platforms are disintermediating traditional art supply distributors, enabling Baltic-origin storytelling to reach United States conservators directly.
- Specialty Stores:Museum-grade specification support and polymerization catalyst disclosure services sustain margin capture in artisan segments.
- Wholesale Distributors:Bulk chemical buyers leverage Cargill's North American oilseed crushing infrastructure for supply security.
- Direct Sales:Contracted supply chains with farm-to-barrel documentation are replacing spot-market purchasing among specialty distributors.
Wholesale distributors handle the largest volumes; online retail is gaining share fastest on digital disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oilseed crushing talent clusters in the Black Sea basin and Canadian prairies anchor global supply security for linseed derivatives. Artisan conservator networks concentrate in Western European heritage centers and select United States metropolitan markets. Regulatory divergence across EPA, ECHA REACH, and China's MEE is fragmenting procurement specifications by destination market.
United States
Conservator demand for polymerization-catalyst-free finishes drives cold-pressed raw grade procurement in New York and Boston museum districts. EPA NESHAP enforcement under hazardous air pollutant standards constrains alkyd coating formulations in industrial Midwest paint production. Chicago-area coatings manufacturers are qualifying water-reducible emulsion systems to preempt regulatory actions.
Germany
Architectural coatings producers in North Rhine-Westphalia are expanding compliant linseed oil procurement as ECHA REACH Annex XVII cobalt restrictions force drier chemistry substitution. The country's national chemical regulator maintains strict enforcement of volatile organic compound limits in industrial formulations. Bavarian paint manufacturers are piloting aqueous-phase oil-modified polyester dispersions at commercial scale.
China
Waterborne alkyd producers in Guangdong and Jiangsu provinces are qualifying higher-grade raw linseed oil under tightening MEE enforcement of GB 18582 architectural coating emission standards. The Ministry of Ecology and Environment is lowering permissible volatile organic compound content thresholds for interior applications. Pearl River Delta manufacturing clusters are driving quality bifurcation between cold-pressed and solvent-extracted import grades.
France
Furniture restoration specialists in Paris and Lyon drive concentrated artisan demand for metallic-drier-free finishes with blockchain-enabled provenance documentation. The national consumer affairs regulator supports emerging provenance disclosure standards for heritage conservation materials. Île-de-France specialty distributors are replacing spot-market purchasing with contracted Baltic-origin supply chains.
India
Furniture manufacturing clusters in Maharashtra and Gujarat are creating entry pathways for low-volatile organic compound natural oil finishes under emerging BIS formaldehyde emission regulations for wood panel products. The Bureau of Indian Standards is aligning wood product certification with international emission protocols. Mumbai-area manufacturers are testing cold-pressed volumes for premium export-oriented furniture lines.
Linseed Oil Market Vendor Landscape
Capital-heavy crushing and refining producers compete with asset-light specialty distributors and certification-focused traders. The supplier base fragments across three operational tiers: multinational agribusinesses with integrated oilseed infrastructure, regional European refiners with Baltic-origin traceability positioning, and Asia-Pacific traders serving bulk chemical procurement. Two strategic archetypes dominate competitive positioning: supply security anchors leveraging crushing scale, and margin capture specialists exploiting certification premiums. Capacity expansion in Black Sea crushing and direct-to-artist digital channel development represent the primary competitive moves reshaping market access.
Among North American agribusinesses, Cargill, Incorporated exemplifies the supply security archetype through its integrated oilseed crushing infrastructure. Henry Lamotte Oils GmbH and Gustav Heess GmbH represent the European traceability-specialist tier, with geographic naming conventions indicating Baltic-origin positioning strategies. These three entities occupy distinct competitive spaces: bulk chemical feedstock security, heritage conservation certification, and industrial alkyd formulation compliance respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Henry Lamotte Oils GmbH |
| Gustav Heess GmbH |
| Vandeputte Oleochemicals |
| Wilmar International Ltd. |
| Krishi Oils Limited |
| AOS Products Pvt. Ltd. |
| Jamieson Natural Sources |
| Others |
Supply Flow & Price Mechanics
ECHA REACH cobalt drier restrictions are forcing German coatings manufacturers to qualify compliant linseed oil grades, compelling Baltic-origin suppliers to expand cold-pressed certification capacity and widening price spreads against commodity solvent-extracted volumes.
Pricing Analysis
Certification-bundled pricing separates cold-pressed food-grade volumes from unbundled industrial alkyd feedstock. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA pathway completion, organic designation, and blockchain traceability documentation. Price differentiation intensifies as manganese-iron drier requalification extends testing cycles for compliant boiled grades. Bulk chemical buyers in Guangdong demonstrate highest price sensitivity; museum conservators in Paris and Boston accept substantial premiums for metallic-drier-free provenance.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg consolidate Baltic-origin cold-pressed volumes for European artisan channels. Crushing capacity clusters in Canada, Kazakhstan, and Russia, drawing from Black Sea and prairie flaxseed harvests. Raw material inputs hinge on weather-driven alpha-linolenic acid yield variability, metallic drier additive chemistry, and thermal polymerization reactor availability. Single-source vulnerability concentrates in stand oil production, where specialized kettle infrastructure limits qualified suppliers. Distribution runs through contracted direct sales relationships replacing spot-market purchasing among traceability-focused buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The linseed oil market reads as a late-cycle quality story, with artisan wood finish specifications in France and Italy demanding farm-to-barrel traceability that commands widening margin premiums over commodity alkyd feedstock.
For Market Incumbents: Anticipate soybean oil substitution pressure in commodity alkyd formulations by deepening backward integration into Black Sea crushing assets and accelerating manganese-iron drier chemistry certification to preempt reformulation lock delays. Cargill-scale suppliers should secure long-term offtake agreements with Guangdong waterborne alkyd producers before GB 18582 enforcement tightens import specifications further.
For New Entrants and Emerging Players: Launch via digital direct-to-artist channels targeting United States conservators in New York and Boston museum districts, where e-commerce disintermediation enables Baltic-origin storytelling without distributor margin capture. India's Maharashtra furniture manufacturing clusters offer penetrable white-space under emerging BIS formaldehyde emission regulations, with low-VOC natural oil finishes qualifying for premium export-oriented product lines.
For Investors and Strategic Acquirers: Asymmetric upside sits with European traceability-specialist refiners possessing EFSA certification pathways and contracted Baltic-origin harvest relationships. Five-to-ten year viability favors suppliers combining food-grade credentialing with industrial alkyd compliance capabilities. Watch MEE enforcement intensity in Jiangsu province as inflection indicator for quality-bifurcated import demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | Black Sea capacity expansion secures alpha-linolenic acid supply for compliant alkyd formulations. |
| Certification Pathway Investment | EFSA and FSSAI food-grade credentials unlock nutraceutical premiums beyond industrial binder margins. |
| Digital Direct-to-Artist Channel Launch | E-commerce platforms disintermediate traditional distributors for United States conservator segments. |
| Long-term Supply Agreement | Contracted Baltic-origin relationships replace spot-market purchasing among traceability-focused buyers. |
| Drier Chemistry R&D Partnership | Manganese-iron blend qualification accelerates reformulation timelines for REACH Annex XVII compliance. |
Methodological Framework
Multiple input streams — coatings formulator interviews, oilseed crusher operational data, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at North American and European crushing facilities, procurement leads at German and Chinese alkyd resin producers, art supply channel partners, and museum conservation specialists. Secondary validation drew from ECHA REACH restriction documentation, China MEE GB standard enforcement records, customs trade data, and SEC filings of integrated agribusinesses.
Data-stream reconciliation anchored volume and value outputs across the analysis window. Segmentation dimensions modeled include polymerization state, certification tier, end-use application, and regional regulatory cluster. CAGRs were derived from production capacity trajectories, import specification evolution, and substitution elasticity estimates for competing drying oils. Stand oil reactor utilization rates and cold-pressed capacity expansion timelines informed specialty grade supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea harvest disruption, cobalt drier ban acceleration, or waterborne alkyd emulsion technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Virtual Keyboard Market
Others
Gym Wipes Market
Others
Military 4D Printing Market
Others
North America Cashew Market
Others
Canada Laser Hair Removal Market
Others
Global Microcontroller Embedded Systems Market
Others
Global Digital Market
Others
United States Printed Signage Market
Others
Europe Aircraft Lighting Systems Market
Others
Metaverse Market
Others
Global Smart Home Installation Service Market
Others
Evidence Management Market
Others
Africa Smart Card Market
Others
Exosome Technologies Market
Others
Industrial PC Market
Others
Safety Critical Software Testing Market