
 Manned Evtol Crafts Market | 2026-2036
Manned Evtol Crafts Market Size, Share, and Industry Trends Forecast 2026-2036
Manned Evtol Crafts Market Insights
California's aerospace manufacturing base is pivoting toward electric vertical takeoff capacity as venture-backed producers scale carbon composite airframe output. Joby Aviation leverages extensive flight-test data from its California operations to sustain FAA certification momentum. Archer Aviation anchors its strategy in proprietary battery-electric propulsion architectures. Beta Technologies competes through an integrated charging and aircraft ecosystem designed for commercial operator workflows.
Manned eVTOL crafts are piloted electric aircraft with distributed propulsion, typically featuring six to twelve rotors and maximum takeoff weights between 1,500 and 6,000 pounds, engineered for short-haul urban and regional transport missions. Passenger vehicle types dominate current development pipelines as air taxi operators pre-order certified platforms for metropolitan deployment. Battery-powered propulsion systems attract the majority of engineering investment, though hybrid-electric configurations retain relevance for extended-range medical evacuation routes where endurance thresholds exceed pure-electric capabilities.
FAA Part 23 and Part 135 frameworks govern US commercial operations while EASA's SC-VTOL standards shape European type certification requirements, with both agencies imposing rigorous battery thermal runaway containment protocols that extend development timelines. China's CAAC has granted operational permits ahead of Western counterparts, creating asymmetric regulatory access that influences fleet deployment sequencing. Stakeholders must monitor certification reciprocity agreements between jurisdictions, as fragmented approval pathways threaten to fragment fleet interoperability and operator business models across operational territories.
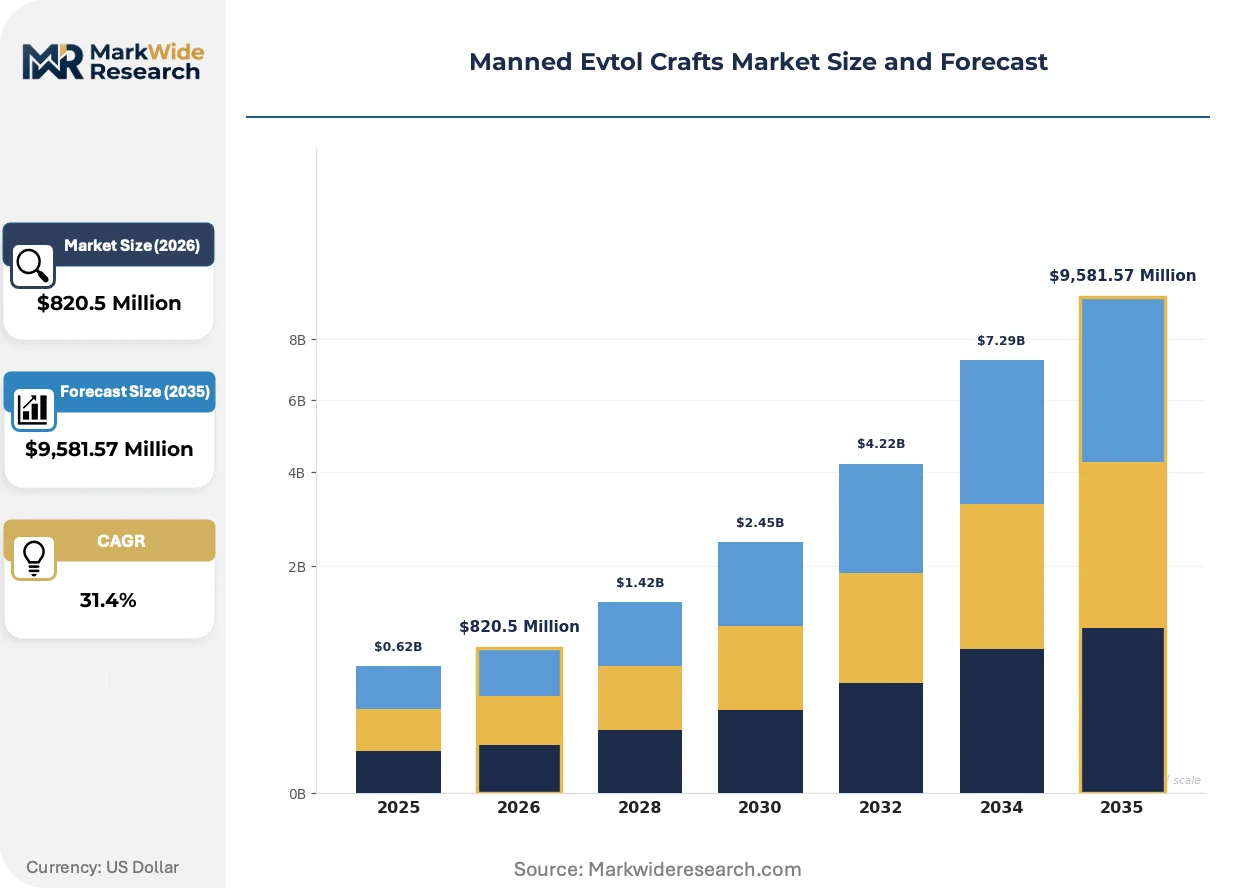
Market Dynamics
Battery thermal runaway containment protocols from FAA and EASA are extending development timelines while CAAC's accelerated certification in China creates competitive asymmetry that reshapes fleet deployment sequencing across jurisdictions.
Growth Catalysts
- CAAC Operational Permits:China's aviation regulator has granted operational certificates ahead of Western counterparts, enabling commercial passenger flights in multiple municipalities and establishing early-mover infrastructure advantages.
- Urban Air Mobility Infrastructure:Dubai and Shenzhen are expanding dedicated vertiport networks and air traffic management systems specifically designed for eVTOL integration into existing metropolitan transport grids.
- Carbon Composite Airframes:Advanced manufacturing techniques for lightweight structural materials are reducing aircraft empty weight ratios and extending effective range per battery charge cycle.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode material processing and cell manufacturing concentrate in East Asian supply chains, creating input vulnerability for Western airframe assemblers.
- FAA Part 23 Certification Friction:Rigorous airworthiness standards for powered-lift aircraft impose multi-year validation timelines that delay revenue service entry for new platform entrants.
- Hybrid-Electric Substitution:Extended-range medical evacuation routes favor hybrid architectures where battery-only endurance falls below mission-critical thresholds.
Strategic Opportunities
- Saudi Giga-Project Integration:NEOM and Red Sea coastal developments are soliciting eVTOL operators for tourist and resident mobility within purpose-built smart city environments.
- Autonomous Flight Convergence:Sensor fusion between LiDAR, radar, and optical systems is enabling reduced-crew operations that lower per-seat operating economics.
- Vertiport Real Estate Arbitrage:Rooftop and parking structure retrofits in dense metropolitan cores offer lower-cost entry points than greenfield heliport construction.
Industry Challenges
- Certified Pilot Scarcity:FAA and EASA have not established standardized type ratings for powered-lift eVTOL operations, forcing operators to train against provisional curricula.
- Battery Swapping Infrastructure:Commercial operators require turnaround times under ten minutes, demanding capital-intensive charging and swap station networks at each operational node.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manned Evtol Crafts Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $9,581.57 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger, Cargo, Emergency Response, Law Enforcement, Recreational Propulsion: Electric, Hybrid Electric, Hydrogen Fuel Cell, Turbine, Battery Powered Application: Urban Air Mobility, Air Taxi, Medical Evacuation, Goods Delivery, Surveillance Customer Type: Private Operators, Government Agencies, Healthcare Providers, Corporate Fleets |
| Companies Covered | Joby Aviation, Archer Aviation, EHang, Eve Holding, Beta Technologies, Lilium, Vertical Aerospace, Volocopter, Wisk Aero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manned Evtol Crafts Market Trends and Innovations
Distributed electric propulsion architectures are fundamentally altering aircraft design paradigms, enabling configurations impossible under conventional turbine or piston powertrains while forcing concurrent evolution in certification methodologies and operator training frameworks.
Solid-state battery chemistries are expanding into eVTOL propulsion systems by replacing liquid electrolytes with ceramic or polymer alternatives that reduce fire risk and enable higher energy density packaging. Archer Aviation and Joby Aviation are flight-testing prototype cells for integration into 2027-2028 platform refreshes. This transition is expanding into airworthiness certification frameworks as regulators develop new thermal testing protocols specific to solid-state failure modes.
EASA's SC-VTOL Special Condition framework is mandating fault-tolerant flight control systems and redundant power distribution architectures that exceed traditional Part 23 requirements. European manufacturers must demonstrate continued safe flight and landing following single-point failures in any propulsion or control channel. Tilt-rotor configurations with mechanical complexity face disproportionate compliance burden compared to multicopter designs with inherent redundancy.
Air taxi operators are consolidating procurement around pre-certified platform commitments rather than developmental partnerships, concentrating order books among three to four airframe producers with visible FAA type certificate progress. This concentration is compressing supplier negotiation leverage and locking in maintenance and training ecosystems years before revenue service begins. The shift is most visible in California and Texas where venture-backed operators are placing binding pre-delivery payments to secure production slots.
Manned Evtol Crafts Market Segmentation
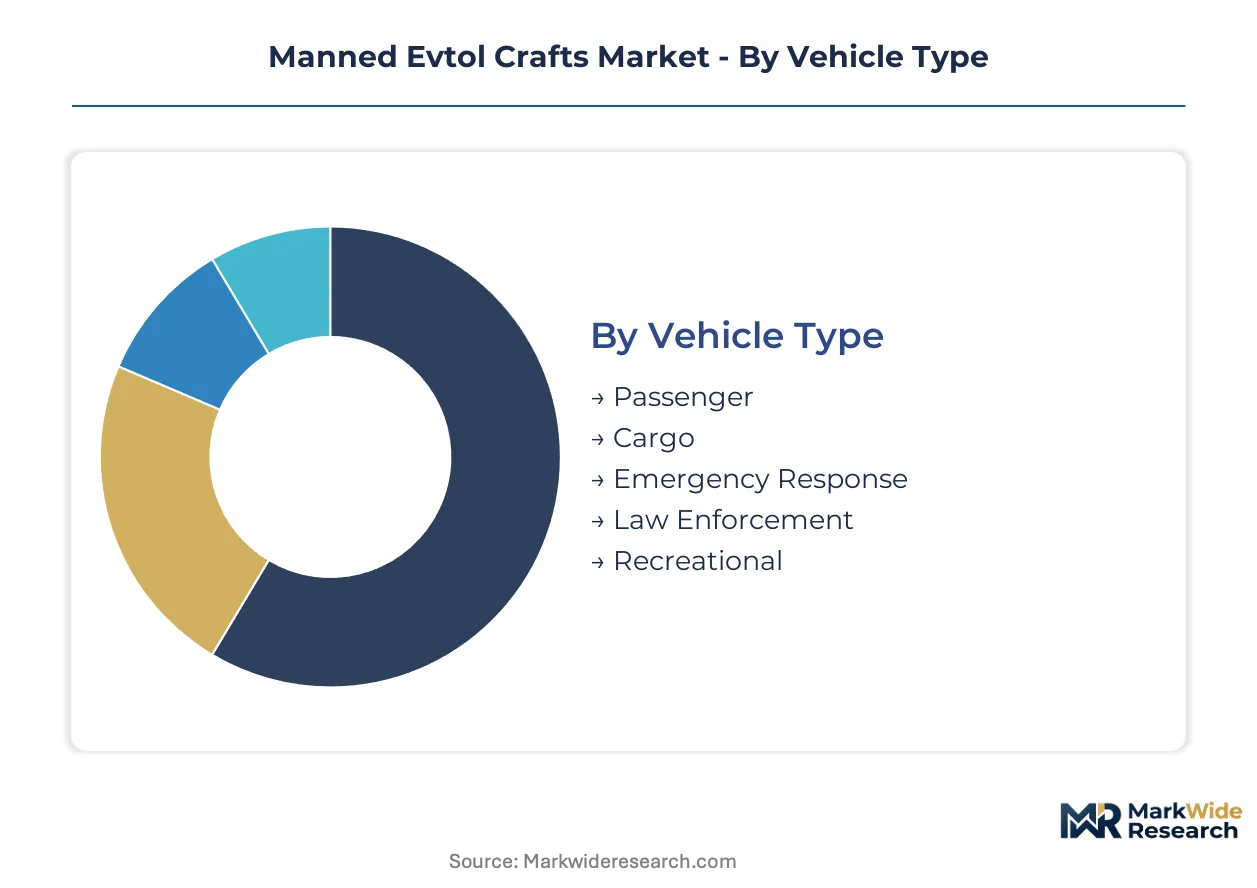
Segmentation in manned eVTOL crafts reveals divergent capital requirements across vehicle configurations and operational models. Battery thermal management systems and distributed propulsion architectures impose asymmetric upfront costs that reshape fleet procurement strategies.
Vehicle Type:
Passenger configurations demand the steepest capital commitments due to FAA Part 23 certification rigor and redundant flight control mandates.
- Passenger:Six to twelve rotor distributed architectures with maximum takeoff weights between 1,500 and 6,000 pounds dominate pre-order backlogs. Dubai and Shenzhen air taxi operators are binding production slots for certified platforms ahead of revenue service.
- Cargo:Payload-optimized designs sacrifice cabin pressurization for battery bay volume, enabling 500-pound lift capacities over 50-mile routes. Goods delivery operators in California are retrofitting vertiports for autonomous cargo loading workflows.
- Emergency Response:Medical evacuation configurations prioritize rapid battery swap compatibility over range.
- Law Enforcement:Surveillance-equipped variants integrate thermal imaging and encrypted communications arrays.
- Recreational:Two-seat sport models face lighter certification burdens under FAA Light-Sport Aircraft pathways.
Most installed capacity flows through Passenger. Expansion is steepest in Emergency Response.
Propulsion:
Powertrain selection determines airworthiness certification complexity and supply chain exposure to lithium-ion concentration.
- Electric:Pure battery architectures attract the majority of engineering investment despite thermal runaway containment protocols that extend FAA validation timelines. Joby Aviation and Archer Aviation are flight-testing solid-state prototypes for 2027-2028 platform refreshes.
- Hybrid Electric:Range-extender configurations retain relevance for medical evacuation routes where battery-only endurance falls below mission-critical thresholds.
- Hydrogen Fuel Cell:Proton exchange membrane stacks enable longer duration flights with faster refueling than battery swap infrastructure.
- Turbine:Conventional turboshaft powertrains persist in heavy-lift military derivatives.
- Battery Powered:This designation overlaps with Electric but emphasizes modular cell architectures for commercial operator swap workflows.
Electric powertrains carry the heaviest certification burden. Hybrid Electric is gaining share fastest in extended-range applications.
Application:
Operational use case dictates vertiport infrastructure requirements and air traffic management integration depth.
- Urban Air Mobility:Metropolitan point-to-point networks require dedicated corridor allocation and rooftop vertiport retrofits. EASA SC-VTOL fault-tolerant flight control mandates impose disproportionate compliance burdens on tilt-rotor configurations.
- Air Taxi:On-demand passenger services concentrate procurement among three to four airframe producers with visible FAA type certificate progress.
- Medical Evacuation:Hybrid-electric endurance thresholds dominate route planning for rural hospital connectivity.
- Goods Delivery:Autonomous cargo variants bypass pilot scarcity constraints.
- Surveillance:Law enforcement and border patrol applications prioritize loiter time over speed.
Urban Air Mobility anchors current infrastructure investment. Medical Evacuation shows the steepest expansion trajectory.
Customer Type:
Buyer category determines financing structure and regulatory reciprocity exposure across operational territories.
- Private Operators:Venture-backed air taxi services in California and Texas are placing binding pre-delivery payments to secure production slots years ahead of revenue service.
- Government Agencies:Military and border patrol procurement favors domestic supply chain content requirements.
- Healthcare Providers:Hospital systems are partnering with eVTOL operators for dedicated medical evacuation fleet access.
- Corporate Fleets:Employee shuttle services and executive transport contracts are emerging in Saudi NEOM and Red Sea coastal developments.
Government Agencies control the largest committed order value. Private Operators are expanding most quickly into binding pre-certification commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's CAAC has granted operational permits ahead of FAA and EASA timelines, while the United States retains the deepest concentration of venture-backed airframe developers. This regulatory asymmetry is reshaping fleet deployment sequencing across jurisdictions.
United States
Venture-backed operators in California and Texas are placing binding pre-delivery payments to secure production slots years ahead of revenue service. FAA Part 23 and Part 135 frameworks govern commercial operations with rigorous battery thermal runaway containment protocols. The California aerospace manufacturing base is pivoting toward electric vertical takeoff capacity as producers scale carbon composite airframe output.
China
EHang holds operational certificates for manned flight in multiple municipalities, establishing early-mover infrastructure advantages. The CAAC's accelerated certification timeline creates competitive asymmetry that influences global fleet deployment sequencing. Shenzhen is expanding dedicated vertiport networks and air traffic management systems specifically designed for eVTOL integration.
Germany
EASA's SC-VTOL Special Condition framework mandates fault-tolerant flight control systems and redundant power distribution architectures. Volocopter anchors European multicopter development from its Stuttgart operations. The country's automotive supply chain concentration provides access to precision manufacturing capabilities for carbon composite structural components.
United Arab Emirates
Dubai's urban air mobility operators are expanding pilot programs for passenger transport with dedicated corridor allocation. The Dubai Roads and Transport Authority is coordinating vertiport real estate development across rooftop and parking structure retrofits. NEOM and Red Sea coastal developments are soliciting eVTOL operators for tourist and resident mobility within purpose-built smart city environments.
United Kingdom
Vertical Aerospace is developing tilt-rotor configurations from its Bristol engineering base under EASA certification pathways. The UK's CAA is aligning with EASA SC-VTOL standards while maintaining national discretion on operational permit timing. London's dense metropolitan core offers lower-cost vertiport entry points through parking structure retrofits rather than greenfield heliport construction.
Manned Evtol Crafts Market Competitive Landscape
United States producers anchor one tier; Chinese and German specialists hold differentiated positions in certification sequencing and operational deployment. The vendor base clusters around three to four airframe producers with visible FAA or EASA type certificate progress, concentrating order books and compressing supplier negotiation leverage. Two strategic archetypes dominate: venture-backed integrated platform developers and established aerospace suppliers pivoting into electric propulsion. Competitive moves center on binding pre-certification procurement commitments and strategic vertiport infrastructure partnerships.
Within the integrated platform tier, Joby Aviation exemplifies the California-based developer archetype leveraging extensive flight-test data to sustain certification momentum. Archer Aviation occupies a position among proprietary battery-electric propulsion architects. EHang represents the regulatory-first mover archetype with operational certificates across multiple Chinese municipalities. These three companies illustrate the geographic and strategic divergence shaping competitive positioning as type approval timelines diverge across jurisdictions.
| Leading Market Players |
|---|
| Joby Aviation |
| Archer Aviation |
| EHang |
| Eve Holding |
| Beta Technologies |
| Lilium |
| Vertical Aerospace |
| Volocopter |
| Wisk Aero |
| Others |
Pricing and Supply Chain Analysis
Air taxi operators binding pre-delivery payments for certified platforms concentrate procurement leverage among three to four airframe producers, compressing supplier margins and establishing tiered pricing stratification across certification grade and volume commitment levels.
Pricing Analysis
Capacity additions in California and Texas are reshaping price floors for carbon composite airframe assemblies. Contract-based long-term offtake agreements dominate, with price differentiation driven by FAA certification progress and battery energy density specifications. Cost compression in the cargo segment intensifies as autonomous variants bypass pilot training economics. Government agencies show least price sensitivity due to domestic content mandates, while private operators face acute pressure to secure production slots.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Stuttgart, and Dubai anchor hub-and-spoke patterns for battery cell and power electronics logistics. Manufacturing draws from China for cathode processing, South Korea for cell assembly, and Germany for precision flight control components. Single-source vulnerability concentrates in solid-state electrolyte ceramic substrates. Distribution runs through vertiport-adjacent micro-fulfillment nodes designed for sub-ten-minute battery swap turnaround.
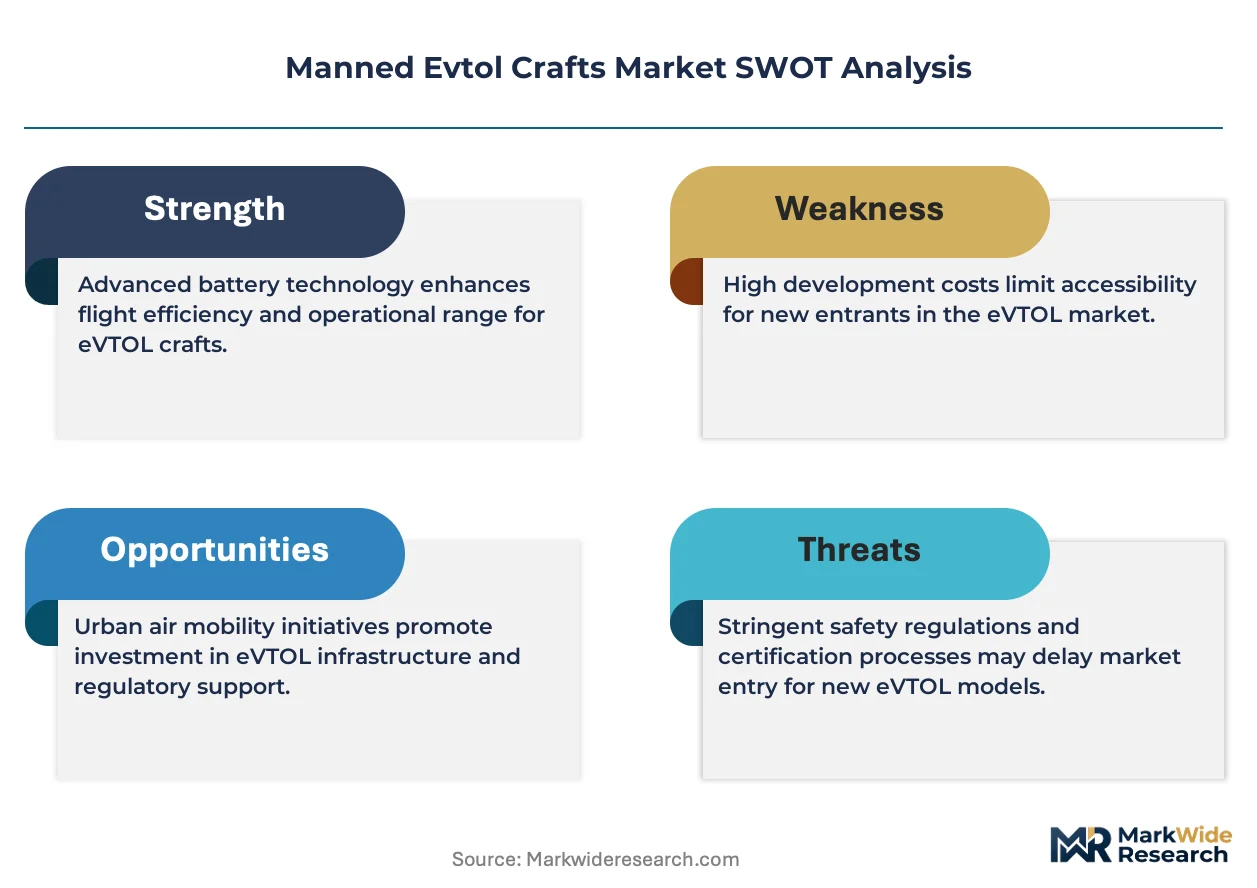
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manned eVTOL procurement is shifting toward fault-tolerant flight control specifications as EASA SC-VTOL mandates harden certification baselines, elevating premium-tier platform valuations.
For Market Incumbents: Acquire vertiport real estate portfolios in metropolitan corridor nodes before regulatory zoning solidifies. Consolidate battery swap infrastructure partnerships to lock in operator switching costs. Hybrid-electric range-extender technology from emerging entrants threatens pure-electric incumbents in medical evacuation segments. For New Entrants and Emerging Players: Launch via purpose-built smart city deployments in Saudi NEOM and Red Sea developments where greenfield infrastructure eliminates retrofit constraints. Target cargo configurations in California goods delivery networks where autonomous loading workflows bypass pilot scarcity. Pursue EASA SC-VTOL certification reciprocity pathways to access European urban air mobility corridors. For Investors and Strategic Acquirers: Aerospace primes with urban air mobility divisions are the most active acquirers in this space, seeking distributed electric propulsion IP and flight-test data repositories. Five-to-ten-year viability hinges on CAAC-FAA-EASA certification reciprocity convergence. Monitor FAA type certificate issuance velocity as the critical inflection signal for production slot value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Vertiport Infrastructure Partnership | Secures corridor allocation rights in Dubai and Shenzhen metropolitan planning frameworks. |
| Solid-State Battery Integration | Reduces thermal runaway containment costs under FAA Part 23 airworthiness protocols. |
| CAAC Certification Reciprocity | Unlocks asymmetric operational permit advantages ahead of Western regulatory timelines. |
| Autonomous Flight Control Development | Enables reduced-crew economics through LiDAR-radar-optical sensor fusion architectures. |
| Carbon Composite Manufacturing Scale-Up | Lowers empty weight ratios and extends effective range per battery charge cycle. |
Research Methodology
Multiple input streams — flight-test data disclosures, regulatory filing repositories, and vertiport development permits — were reconciled against primary interviews with FAA certification leads, EASA airworthiness engineers, CAAC operational permit officers, and air taxi fleet procurement directors. Secondary validation drew from FAA Part 23 amendment dockets, EASA SC-VTOL special condition texts, CAAC operational certificate registries, and carbon composite trade flow data. Bottom-up platform delivery schedules and top-down infrastructure investment flows were triangulated to anchor volume estimates.
Data-stream reconciliation across the projection horizon employed vehicle configuration, propulsion architecture, application use case, and customer type as segmentation dimensions. CAGRs were derived from production slot commitments and regulatory approval velocity curves. Forecast inputs incorporated battery energy density improvement trajectories and pilot training pipeline constraints specific to powered-lift type ratings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CAAC-FAA-EASA certification reciprocity delays or lithium-ion supply chain disruptions. Outputs reflect documented assumptions on regulatory timeline convergence and solid-state battery commercialization schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Helicopters Market
Aircraft
Aircraft Flight Control System Market
Aircraft
India Winglets Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Docking System Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Aircraft Ailerons Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Hybrid Aircraft Market
Aircraft
Aircraft Radome Market
Aircraft
France Aviation Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Military Helicopters Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market