
 United States Household Battery Market | 2026-2036
United States Household Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Household Battery Market Analytics
UL 1973 certification for stationary battery systems is reorganizing competitive access in the United States household battery sector, forcing manufacturers to retool testing protocols before products reach retail channels. Duracell Inc. leverages its brand strength and supermarket shelf dominance to control alkaline segment positioning. Tesla anchors premium residential storage through its integrated Powerwall ecosystem and direct-to-consumer channel. Energizer Holdings Inc. competes across both primary and rechargeable lines while sustaining R&D intensity in lithium-metal formulations.
United States household batteries encompass electrochemical cells and modular packs designed for residential power delivery, typically operating at 1.5V to 48V nominal with capacities from 600mAh to 13.5kWh depending on chemistry and form factor. These devices store and discharge electrical energy through redox reactions involving zinc-manganese dioxide, lithium cobalt oxide, or lead-dioxide systems to power portable electronics, emergency equipment, and grid-tied home energy systems. Alkaline cells dominate unit volume across remote controls and flashlights where low self-discharge and shelf stability preserve margin pools. Lithium-ion packs capture the fastest expansion within smoke detector backup and residential solar storage applications as cycle life requirements intensify. Lead-acid retains niche positioning in rural off-grid households where upfront cost sensitivity outweighs energy density preferences.
The Department of Transportation's hazmat shipping rules and OSHA workplace safety standards govern cell transport and installation labor, while the EPA's Universal Waste Rule shapes end-of-life collection infrastructure that manufacturers must fund. California Energy Commission regulations under Title 20 mandate minimum performance thresholds for rechargeable systems sold into the state, effectively setting a de facto national benchmark. Stakeholders should monitor NHTSA's evolving guidance on home battery fire suppression as thermal runaway incidents trigger local installation moratoriums that could reshape permitting timelines and insurance requirements.
Market Dynamics
California's Title 20 appliance efficiency standards are forcing manufacturers to retool product lines before national rollout, compressing testing timelines and redistributing margin pools toward certified suppliers.
Growth Catalysts
- Residential solar-plus-storage clusters:Texas and Florida utilities are accelerating interconnection approvals for home battery systems paired with rooftop photovoltaic arrays.
- EPA Universal Waste Rule infrastructure:End-of-life collection mandates are creating funded reverse logistics networks that reduce customer acquisition friction for replacement cycles.
- Lithium-ion cycle life improvements:Rechargeable cells now exceed 5000 cycles in stationary applications, matching warranty periods demanded by solar installers.
Market Restraints
- Cobalt and lithium carbonate price volatility:Raw material input swings compress gross margins for pack assemblers unable to pass through costs.
- East Asian cell concentration:Cylindrical and prismatic lithium-ion production clusters in South Korea and Japan create supply vulnerability for US integrators.
- Lead-acid substitution ceiling:Rural off-grid households in Appalachia and the Mountain West retain incumbent chemistry due to upfront capital constraints.
Strategic Opportunities
- IRA residential clean energy credits:The Inflation Reduction Act's standalone storage incentive unlocks retrofit demand in markets without solar penetration.
- Direct-to-installer channel bypass:Manufacturers are building captive distribution to electrical contractors, disintermediating traditional retail markup.
- Solid-state electrolyte convergence:Next-generation separators combined with silicon-anode architectures promise energy density doubling by decade end.
Industry Challenges
- UL 1973 certification timelines:Third-party testing backlogs extend product launch windows by 8-14 months.
- NFPA 855 fire suppression integration:Local fire marshals are imposing non-standard installation requirements that fragment permitting protocols across jurisdictions.
- Electrical contractor training gaps:Shortage of technicians qualified for 48V DC residential integration limits deployment velocity in the Southeast.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Household Battery Market |
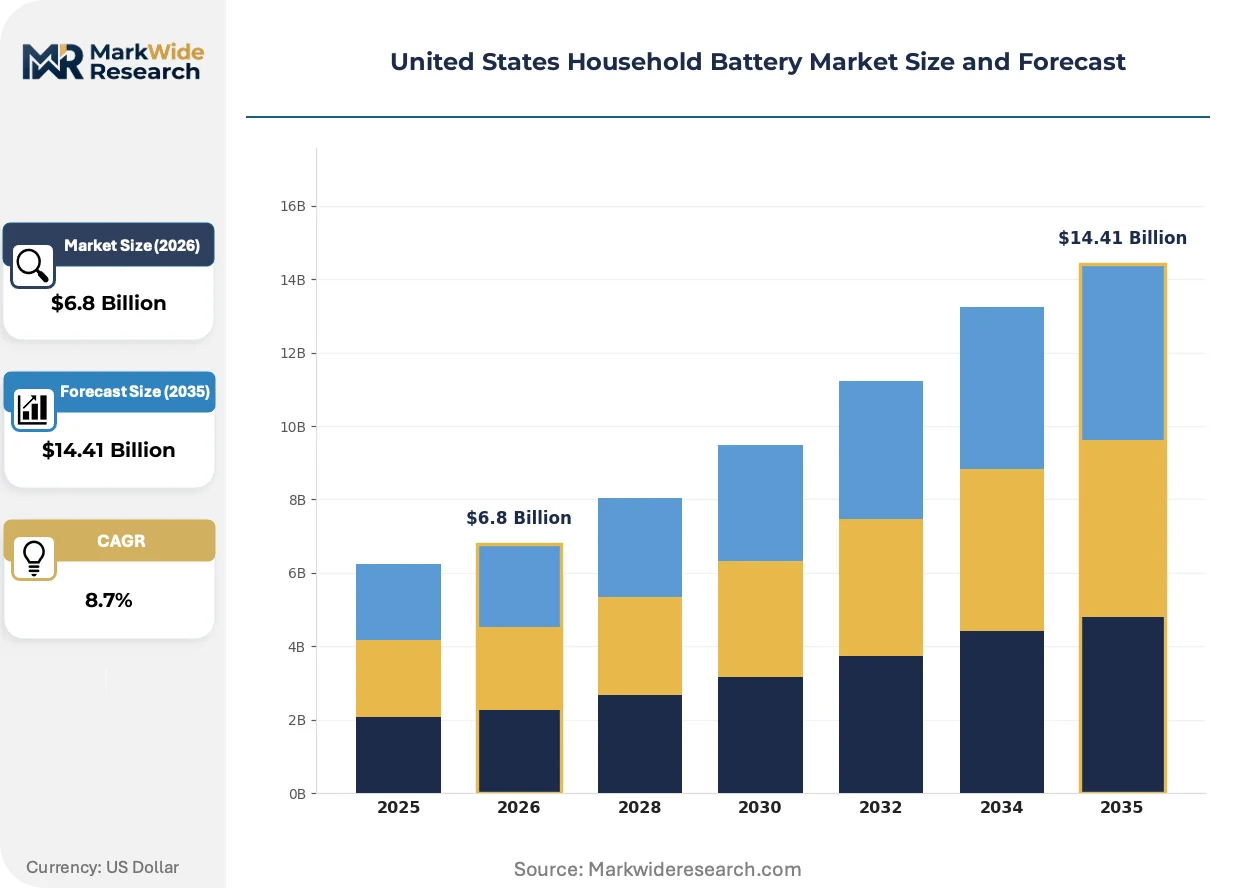
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Alkaline, Lithium-Ion, Nickel-Metal Hydride, Lead-Acid Application: Remote Controls, Flashlights, Smoke Detectors, Wireless Mice End User: Households, Small Businesses, Educational Institutions, NGOs Distribution Channel: Online Retail, Supermarkets, Discount Stores, Hardware Stores |
| Companies Covered | Power Sonic Corporation, Exide Technologies Inc., Duracell Inc., Enphase Energy, Tesla, Energizer Holdings Inc., Zeus Battery Products, Stryten Energy, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Household Battery Market Evolving Landscape
Electrochemical architecture shifts and regulatory tightening are compressing product lifecycles while opening premium positioning for certified systems.
Solid-state lithium-metal cells are supplanting conventional liquid-electrolyte packs in premium residential storage. Solar installers serving the California and Hawaii markets are specifying these systems for fire-prone zones despite 40% cost premiums. The chemistry is compressing warranty risk reserves and enabling 20-year service contracts previously uneconomical.
OSHA workplace safety standards for battery handling are tightening contractor insurance requirements. Installation labor costs are rising 12-18% in states with active enforcement. The Southwest and Gulf Coast markets are responding with prefabricated outdoor enclosure systems that reduce on-site assembly time.
Homeowners are bundling battery procurement with solar origination rather than retrofitting later. The integrated sale is displacing standalone storage marketing through electrical distributors. This pattern concentrates most visibly in Arizona and Nevada where time-of-use rate structures reward simultaneous PV and storage deployment.
United States Household Battery Market Segmentation
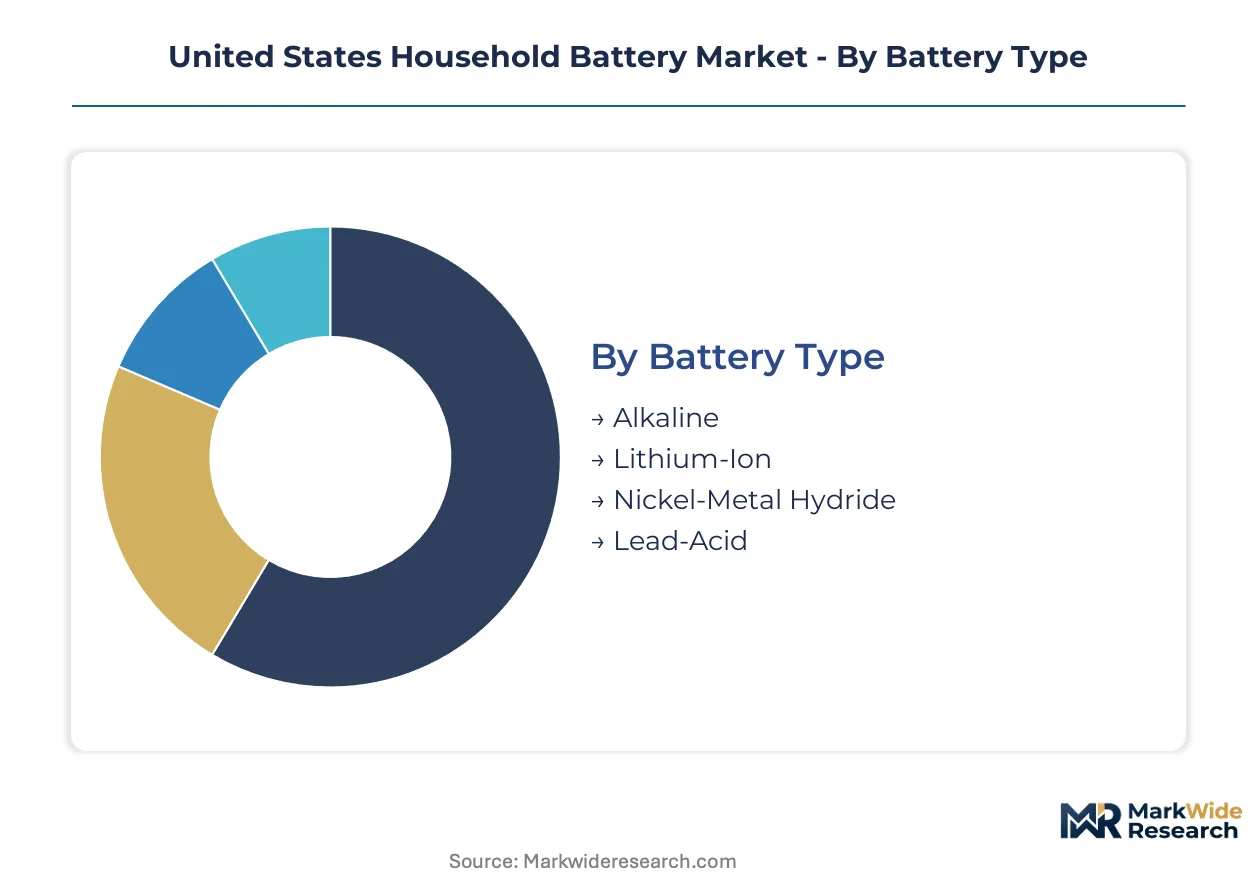
Segmentation in the United States household battery market reveals how regulatory pressure and chemistry-specific performance standards reshape procurement patterns across residential, commercial, and institutional buyers. Distinct compliance pathways for stationary storage versus portable electronics create divergent margin structures that manufacturers must navigate.
Battery Type:
California's Title 20 efficiency mandates and UL 1973 certification requirements create tiered market access based on chemistry-specific thermal stability and cycle life thresholds.
- Lithium-Ion:Rechargeable cells utilizing lithium cobalt oxide or lithium iron phosphate cathodes dominate residential solar-plus-storage installations in Texas and Florida. Cycle life exceeding 5000 cycles matches installer warranty demands while IRA standalone storage credits accelerate retrofit adoption in non-solar markets.
- Alkaline:Zinc-manganese dioxide primary cells with low self-discharge characteristics control unit volume across remote controls and flashlights. Duracell and Energizer shelf positioning in supermarkets preserves margin pools despite commodity chemistry.
- Nickel-Metal Hydride:Rechargeable cells with moderate energy density serve wireless peripherals and backup applications where cost sensitivity tempers lithium-ion specification.
- Lead-Acid:Flooded and sealed lead-acid systems retain rural off-grid positioning in Appalachia and the Mountain West where upfront capital constraints outweigh energy density preferences.
Established volume favors Alkaline; emerging adoption favors Lithium-Ion.
Application:
Installation labor requirements and fire suppression integration costs segment demand between plug-and-play portable devices and permanently installed residential storage systems.
- Smoke Detectors:Backup power mandates in California and New York building codes drive lithium-ion penetration where 10-year sealed battery requirements displace alkaline. NFPA 855 compliance adds installation complexity that fragments permitting timelines.
- Remote Controls:Low-drain infrared and RF devices consume alkaline volume through supermarket impulse placement. Shelf stability and instant readiness preserve primary cell dominance despite rechargeable alternatives.
- Flashlights:Emergency preparedness demand clusters in hurricane-prone Florida and Gulf Coast states. LED efficiency gains extend runtime while reducing current draw requirements.
- Wireless Mice:Peripheral power needs favor alkaline convenience in corporate procurement while rechargeable nickel-metal hydride gains traction in sustainability-focused educational institutions.
Volume concentrates in Remote Controls; steepest expansion trajectory appears in Smoke Detectors.
End User:
Procurement scale and compliance sophistication separate individual household purchasing from institutional tender processes with formal sustainability criteria.
- Households:Individual consumers driving retail volume through supermarkets and online channels. Solar-plus-storage bundling with rooftop photovoltaic arrays concentrates in Arizona and Nevada time-of-use markets.
- Small Businesses:Commercial entities with backup power needs and ESG reporting obligations. OSHA workplace safety standards tighten contractor insurance requirements for installation labor.
- Educational Institutions:K-12 and university procurement with formal e-waste policies and bulk purchasing leverage. EPA Universal Waste Rule compliance shapes reverse logistics requirements.
- NGOs:Non-governmental organizations deploying off-grid power in rural development and disaster relief contexts. Lead-acid retention reflects total cost of ownership constraints in grant-funded programs.
Transaction volume favors Households; contract complexity favors Educational Institutions.
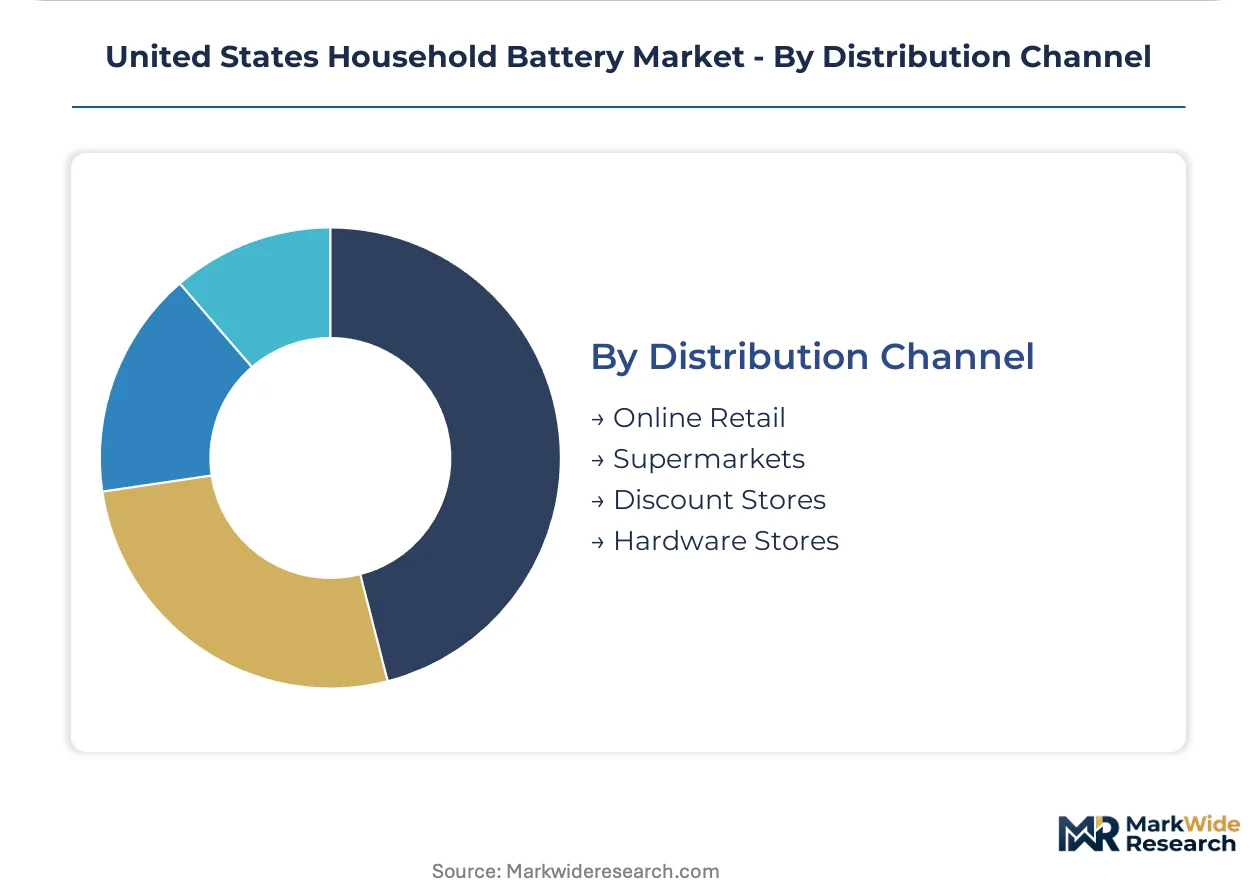
Distribution Channel:
Channel economics and customer acquisition costs determine chemistry access, with direct-to-installer bypass emerging as a structural threat to traditional retail markup.
- Supermarkets:Impulse-driven alkaline volume through checkout lane placement and brand recognition. Duracell and Energizer shelf dominance preserves premium positioning against private label erosion.
- Online Retail:E-commerce platforms capturing rechargeable and specialty battery demand with subscription replenishment models. Direct-to-consumer lithium-ion storage sales bypass electrical distributor markup.
- Hardware Stores:Contractor-facing channels for residential storage and emergency power equipment. Prefabricated outdoor enclosure systems reduce on-site assembly time in Southwest and Gulf Coast markets.
- Discount Stores:Price-sensitive alkaline volume with private label and secondary brand presence. Margin compression limits supplier R&D recovery.
Unit velocity runs through Supermarkets; value capture is climbing the fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's standalone storage credits are redistributing deployment activity across state-level regulatory environments. State-level interconnection standards and building codes create divergent permitting timelines that manufacturers must navigate.
California
Residential solar-plus-storage bundling dominates procurement in time-of-use markets. The California Energy Commission's Title 20 efficiency mandates set de facto national benchmarks for rechargeable system performance. The San Diego-Los Angeles corridor hosts the densest installer network for lithium-ion residential storage.
Texas
Grid instability events accelerate backup power demand among suburban households. ERCOT interconnection protocols streamline approval timelines for home battery systems paired with rooftop arrays. The Austin-Dallas-Houston triangle concentrates solar installer activity and electrical contractor training programs.
Florida
Hurricane preparedness drives emergency power equipment procurement through retail and contractor channels. The state's building code mandates for solar-ready construction create embedded storage opportunities. The Tampa-Orlando-Miami corridor leads residential storage deployment velocity in the Southeast.
New York
Smoke detector backup power mandates in building codes displace alkaline with lithium-ion sealed cells. NYSERDA incentive programs accelerate cold-climate battery deployment for grid-tied residential systems. The New York Metro area hosts the Northeast's largest electrical contractor training infrastructure for 48V DC integration.
Arizona
Peak demand charge structures reward simultaneous photovoltaic and storage deployment. The state's solar access laws prevent homeowner association restrictions on rooftop system installation. The Phoenix-Tucson corridor exhibits the highest per-capita residential storage attachment rates for new solar origination.
United States Household Battery Market Competitive Landscape
Listed leaders compete with private specialists across capital access and channel control dimensions. The vendor base organizes into three tiers: mass-market alkaline producers with supermarket dominance, premium lithium-ion integrators with direct-to-installer channels, and regional lead-acid fabricators serving rural off-grid segments. Consolidation pressure concentrates in the stationary storage tier where UL 1973 certification requirements favor scaled testing investment. Dominant competitive moves include backward integration into cell supply and captive distribution builds to electrical contractors.
Within the premium storage tier, Tesla and Enphase Energy exemplify integrated ecosystem positioning. Duracell Inc. and Energizer Holdings Inc. anchor mass-market alkaline and rechargeable lines through retail channel control. Among diversified energy storage fabricators, Exide Technologies Inc. and Power Sonic Corporation occupy positions spanning industrial and residential applications.
| Leading Market Players |
|---|
| Power Sonic Corporation |
| Exide Technologies Inc. |
| Duracell Inc. |
| Enphase Energy |
| Tesla |
| Energizer Holdings Inc. |
| Zeus Battery Products |
| Stryten Energy |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Cylindrical lithium-ion cell capacity utilization above 85% in South Korean and Japanese manufacturing clusters concentrates bargaining power among tier-one suppliers, compressing margin pools for US pack assemblers while establishing price floors that resist downward pressure from lead-acid substitution. Scale economies in prismatic cell production tether pricing trajectories to East Asian facility utilization rates, with California's Title 20 compliance costs layering additional certification premiums atop base chemistry costs.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with UL 1973-certified stationary systems commanding substantial premiums over portable alkaline alternatives. Three-tier pricing structure across premium lithium-ion storage, mid-grade nickel-metal hydride, and economy alkaline levels reflects brand positioning and warranty duration rather than raw chemistry costs. Pricing pressure stems from cobalt and lithium carbonate volatility that pack assemblers struggle to pass through to cost-sensitive rural households. Institutional buyers in educational procurement exhibit lowest price sensitivity due to ESG compliance mandates, while discount store channels face acute margin compression from private label erosion.
Supply Chain Analysis
Inventory lead times for lithium-ion cylindrical cells stretch 16-24 weeks from South Korean and Japanese cathode manufacturers, creating working capital intensity that favors scaled integrators. Raw material dependencies center on Chilean lithium brine, Indonesian nickel laterite, and Congolese cobalt hydroxide. Single-source vulnerability concentrates in separator membrane supply from Japanese specialty chemical producers. Distribution runs through electrical contractor channels for stationary storage and supermarket impulse placement for alkaline volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installer certification scarcity and qualified technician shortages constrain deployment velocity, creating structural bottlenecks that favor stakeholders with captive training infrastructure or prefabricated system approaches.
For Market Incumbents: Secure UL 1973 certification pipelines ahead of competitor backlog clearance, locking electrical contractor relationships before NFPA 855 fragmentation hardens local permitting requirements. Backward integration into lithium iron phosphate cell supply hedges East Asian concentration risk while preserving margin capture from IRA standalone storage credits. For New Entrants and Emerging Players: Contractor training service gaps in the Southeast and Mountain West present white-space entry points where incumbents under-invest in 48V DC integration support. Prefabricated outdoor enclosure systems reduce on-site labor requirements, enabling direct-to-installer bypass of traditional electrical distributor markups. Target rural off-grid households in Appalachia with lead-acid alternative financing that bridges upfront capital constraints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lithium iron phosphate specialists with proven cycle life data and installer channel relationships over unproven solid-state chemistry ventures. Acquisition targets should demonstrate captive distribution to electrical contractors and California market access through Title 20 compliance. The signal to watch is NHTSA guidance evolution on residential fire suppression standards, which could trigger permitting moratoriums reshaping competitive access.| Strategic Initiative | Industry Significance |
|---|---|
| UL 1973 Certification Investment | California Energy Commission mandates create de facto national compliance barriers for uncertified competitors. |
| Direct-to-Installer Channel Build | Electrical contractor bypass captures margin pools traditional distributors currently extract. |
| Lithium Iron Phosphate Backward Integration | Cobalt-free chemistry reduces raw material volatility exposure while meeting cycle life warranty demands. |
| Prefabricated Outdoor Enclosure Systems | OSHA tightening in Southwest markets favors reduced on-site assembly labor models. |
| Contractor Training Infrastructure | Technician scarcity in Southeast limits deployment velocity for competitors without captive programs. |
Research Methodology
A spread of perspectives from solar installer procurement leads, electrical contractor operations managers, battery pack engineering directors, and utility interconnection planners converged on the working assumptions driving chemistry adoption trajectories. Primary fieldwork combined with secondary validation from EPA Universal Waste Rule implementation reports, California Energy Commission Title 20 compliance databases, and FERC interconnection queue data. Bottom-up cell shipment analysis and top-down residential storage deployment estimates were triangulated to anchor volume assumptions.
Segmentation dimensions modeled span battery chemistry type, application use case, end-user procurement sophistication, and distribution channel structure across the projection horizon. CAGRs were derived from installer survey data on replacement cycle timing and solar-plus-storage attachment rates. IRA credit phase-out schedules and NHTSA fire suppression guidance evolution served as scenario inputs for sensitivity testing.
Underlying assumptions cover lithium carbonate price stabilization, Title 20 compliance cost pass-through feasibility, and electrical contractor training program expansion, with deviation risk concentrated in raw material geopolitical disruptions and local fire marshal NFPA 855 interpretation variance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
India Rechargeable Battery Market
Batteries
Battery Light Towers Market
Batteries
Rear Rack Battery Market
Batteries
VRLA Batteries Market
Batteries
Tubular Batteries Market
Batteries
Custom Battery Pack Market
Batteries
Aluminum Based Battery Market
Batteries
Secondary Battery Market
Batteries
Nimh Battery Market
Batteries
Global Industrial Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Indonesia Battery Market
Batteries
Primary Battery Market
Batteries
Wireless Power Bank Market