
 Hybrid Truck Market | 2026-2036
Hybrid Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Truck Market Intelligence
Heavy-duty hybrid certification standards for long-haul durability is collapsing the competitive gap between traditional diesel platforms and electrified alternatives. Volvo Group leverages its integrated powertrain manufacturing to sustain European market presence. Daimler AG anchors its position through proprietary diesel-electric architecture. BYD Motors Inc. dominates battery-dominant series hybrid configurations for urban delivery routes in Asian megacities.
A hybrid truck combines an internal combustion engine with one or more electric motors through a shared drivetrain, typically employing a 300-800V battery pack and regenerative braking systems to recover kinetic energy during deceleration. These vehicles serve commercial freight operators seeking emission reductions without the range limitations of pure battery-electric platforms. The powertrain dimension shows diesel-electric hybrids retaining the largest installed base while hydrogen-electric variants capture the fastest expansion in heavy long-haul applications. Application segmentation reveals urban delivery as the most mature deployment channel, whereas refrigerated transport commands the highest per-unit margins due to auxiliary power demands for thermal management.
EPA greenhouse gas standards for medium- and heavy-duty vehicles and the EU F-Gas Regulation on mobile air conditioning refrigerants compel manufacturers to redesign thermal systems and powertrain thermal efficiency. China's MIIT new energy vehicle credit system mandates escalating hybrid and electric production quotas for commercial vehicle makers. Fleet operators and logistics providers must monitor regulatory credit trading mechanics and battery second-life valuation to optimize total cost of ownership across multi-year procurement cycles.
Market Dynamics
Powertrain thermal efficiency mandates under EPA greenhouse gas standards and EU F-Gas Regulation are forcing simultaneous redesign of diesel-electric architectures and mobile air conditioning systems, compressing development cycles for commercial vehicle manufacturers.
Growth Catalysts
- EU Green Deal commercial vehicle emission targets:Municipal waste management fleets in Germany are expanding hybrid truck procurement to meet tightening CO2 reduction requirements for heavy-duty vehicles.
- MIIT new energy vehicle credit system:China's escalating production quotas for commercial vehicle makers are concentrating demand in the Pearl River Delta manufacturing corridor.
- Port logistics electrification:NEV mandates for port operators are accelerating hybrid truck deployment in China's densest freight corridors without requiring full battery-electric range.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack cost volatility and cathode material sourcing bottlenecks in concentrated Asian supply chains constrain production scaling for 300-800V hybrid architectures.
- Heavy-duty durability certification:Long-haul hybrid certification standards create technical friction for powertrain validation, extending time-to-market for series hybrid configurations.
- Pure battery-electric substitution:Improving BEV range and charging infrastructure in urban delivery corridors threatens battery-dominant hybrid positioning in last-mile logistics.
Strategic Opportunities
- Refrigerated transport auxiliary power:Thermal management power demands in cold-chain logistics create margin expansion potential for hybrid trucks with dedicated electric refrigeration drives.
- Battery second-life valuation:Fleet operators optimizing total cost of ownership across multi-year procurement cycles can monetize end-of-first-life battery packs through stationary storage arbitrage.
- Hydrogen-electric long-haul convergence:Fuel cell-battery hybrid architectures for heavy long-haul applications represent unpenetrated white space beyond diesel-electric installed bases.
Industry Challenges
- Regulatory credit trading mechanics:Fleet procurement teams lack standardized frameworks for valuing NEV credits across jurisdictions, complicating multi-year vehicle financing structures.
- Thermal system integration complexity:Simultaneous optimization of powertrain cooling and mobile air conditioning under F-Gas refrigerant restrictions demands cross-functional engineering capabilities scarce in traditional truck OEMs.
- Regenerative braking calibration:Kinetic energy recovery system tuning for variable freight loads requires embedded software expertise concentrated in automotive-tier suppliers rather than legacy truck manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Truck Market |
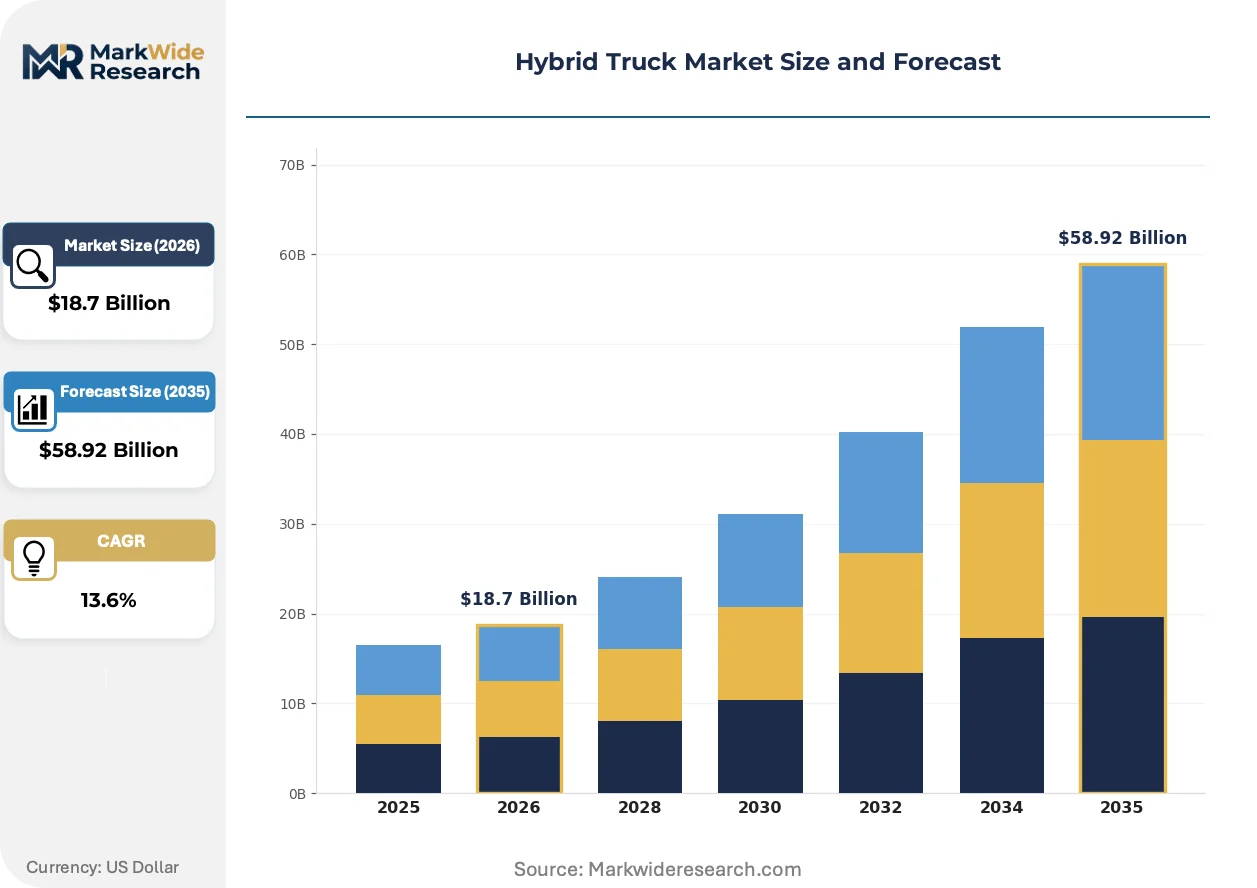
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Series Hybrid, Parallel Hybrid, Mild Hybrid, Plug-in Hybrid, Full Hybrid Powertrain: Diesel-Electric, Gasoline-Electric, Hydrogen-Electric, Compressed Natural Gas-Electric, Biodiesel-Electric Application: Urban Delivery, Long Haul Transport, Construction Logistics, Waste Management, Refrigerated Transport End User: Logistics Providers, Fleet Operators, Municipal Agencies, Private Freight Carriers, Leasing Companies |
| Companies Covered | Ford Motor Company, Toyota Motor Corporation, Volvo Group, BYD Motors Inc., General Motors, Daimler AG, Nissan Motor Corporation, Hino Motors, Ltd., Mercedes Benz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Truck Market Strategic Shifts & Innovations
Modular powertrain architectures are fragmenting the historical integration between engine, transmission, and axle suppliers, enabling new competitive entry points for electrification specialists and battery pack assemblers.
Silicon carbide power electronics are decomposing the traditional voltage and thermal constraints of 300-800V hybrid architectures. Port logistics operators in China's manufacturing corridors are specifying SiC inverters for their next procurement cycles. This technology compression is collapsing the efficiency gap between series and parallel hybrid topologies, forcing incumbent diesel-electric suppliers to accelerate inverter sourcing partnerships.
EPA greenhouse gas standards for medium- and heavy-duty vehicles are tightening fleet-average CO2 limits through model year 2032. Manufacturers must redesign thermal management systems to maintain powertrain efficiency under sustained load conditions. Refrigerated transport operators face the steepest compliance cost escalation due to simultaneous F-Gas refrigerant phase-down requirements.
Fleet procurement teams are unbundling vehicle acquisition from energy sourcing and maintenance contracts, treating hybrid trucks as managed assets rather than capital equipment. Third-party fleet management platforms are displacing direct OEM relationships in urban delivery segments. This channel shift is most advanced in Germany's municipal waste management sector, where public procurement rules favor multi-vendor service aggregation.
Hybrid Truck Market Segmentation
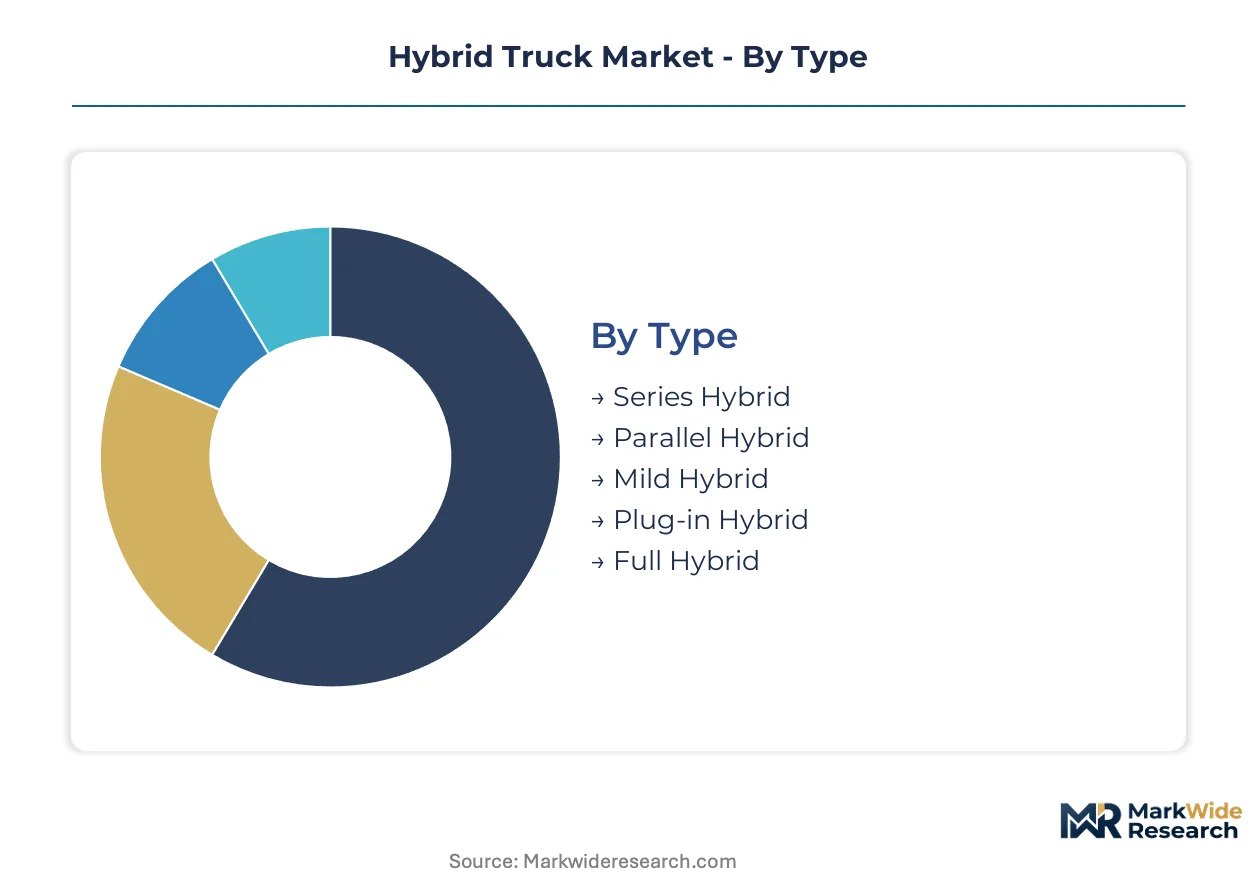
Hybrid truck procurement patterns diverge sharply across powertrain architectures and duty cycles, with regulatory pressure and total cost of ownership calculations driving distinct technology preferences by application. Fleet operators segment their vehicle portfolios based on route predictability, auxiliary power demands, and credit compliance requirements rather than upfront capital cost alone.
Type:
Series hybrid configurations dominate export-led procurement from Asian manufacturing bases, whereas parallel and mild hybrid variants serve mature domestic replacement cycles in European and North American markets.
- Series Hybrid:The electric motor exclusively propels the vehicle while the combustion engine functions as a generator. Port logistics operators in China's Pearl River Delta specify these for drayage routes where stop-and-go duty cycles maximize regenerative braking recovery.
- Parallel Hybrid:Both combustion engine and electric motor can drive the wheels directly through mechanical coupling. German municipal waste fleets favor this architecture for its operational flexibility across variable route topography.
- Mild Hybrid:A 48V belt-driven starter-generator assists the combustion engine without standalone electric propulsion capability. Cost-sensitive private freight carriers in secondary Chinese cities deploy these for incremental emission reductions without infrastructure dependency.
- Plug-in Hybrid:Larger battery packs enable significant all-electric range before combustion engagement. Urban delivery contractors with depot charging access specify these for last-mile zero-emission zone compliance.
- Full Hybrid:Capable of sustained electric-only operation at highway speeds through high-voltage architectures. Long-haul operators testing hydrogen-electric transition pathways use these as interim platforms.
Parallel hybrid holds the largest share; momentum sits with series hybrid configurations.
Powertrain:
Cost tier stratification separates established diesel-electric platforms from emerging hydrogen-electric investments, with fuel price volatility determining regional adoption pacing.
- Diesel-Electric:Mature thermal management and service infrastructure support this dominant installed base. European fleet operators under EU Green Deal compliance timelines represent the core replacement demand.
- Gasoline-Electric:Lighter-duty applications in price-sensitive emerging markets favor this lower first-cost option. Southeast Asian logistics providers specify these for intra-city distribution where diesel sulfur regulations remain permissive.
- Hydrogen-Electric:Fuel cell-battery hybrid architectures eliminate range constraints for heavy long-haul corridors. Chinese state-backed demonstration projects in the Yangtze River Delta are validating durability under sustained load conditions.
- Compressed Natural Gas-Electric:Dual-fuel flexibility addresses regions with pipeline infrastructure but limited hydrogen availability. Indian fleet operators leverage this for compliance with the country's dual carbon goals.
- Biodiesel-Electric:Renewable fuel compatibility supports circular economy procurement mandates. Brazilian agricultural logistics contractors favor this for closed-loop fuel sourcing from soy processing operations.
Diesel-electric retains dominant volume; hydrogen-electric is climbing the fastest as infrastructure commitments materialize.
Application:
Customer type segmentation reveals municipal agencies prioritizing emission visibility while private operators optimize for asset utilization and residual value.
- Urban Delivery:Stop-and-go duty cycles with predictable daily mileage maximize hybrid efficiency gains. Chinese e-commerce fulfillment networks in Shenzhen and Shanghai drive procurement volume for this mature segment.
- Long Haul Transport:Sustained highway operation challenges regenerative braking contribution and battery sizing economics. Australian mining corridor operators test hydrogen-electric variants for 800+ kilometer routes.
- Construction Logistics:Severe duty cycles and off-road terrain demand reinforced powertrain durability. German equipment rental fleets specify these for urban construction emission zones.
- Waste Management:Low-speed refuse collection with frequent stops creates ideal hybrid operating conditions. Municipal procurement in Hamburg and Munich expands under EU Green Deal implementation.
- Refrigerated Transport:Auxiliary power demands for thermal management strain pure battery-electric range. Cold-chain specialists accept premium pricing for dedicated electric refrigeration drives.
Urban delivery commands greatest volume; refrigerated transport generates steepest margin expansion.
End User:
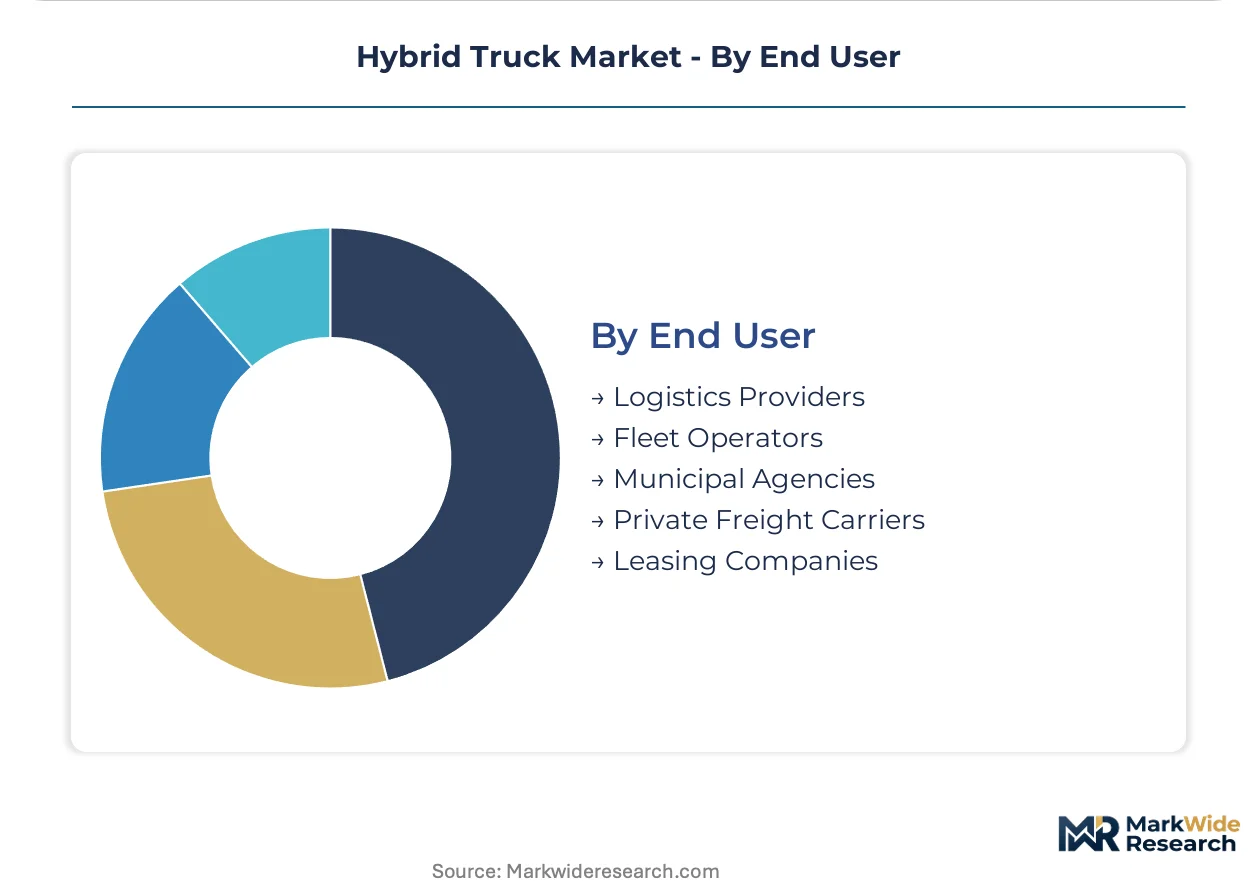
Volume concentration sits with large fleet operators achieving scale economies in maintenance and energy procurement, while leasing companies intermediate technology risk for smaller operators.
- Logistics Providers:Integrated network operators optimize vehicle specifications across heterogeneous route portfolios. DHL Supply Chain and comparable operators standardize on modular powertrain platforms.
- Fleet Operators:Asset-heavy trucking companies manage total cost of ownership across 7-10 year replacement cycles. These stakeholders drive second-life battery valuation methodologies.
- Municipal Agencies:Public procurement rules favor multi-vendor service aggregation over direct OEM relationships. German waste management authorities specify performance-based contracts.
- Private Freight Carriers:Owner-operator and small fleet segments prioritize acquisition cost and financing availability. These users lag in hybrid adoption due to residual value uncertainty.
- Leasing Companies:Asset financiers absorb technology obsolescence risk while offering usage-based pricing. These intermediaries are displacing direct OEM relationships in European urban delivery.
Fleet operators hold the largest share; leasing companies are gaining share fastest as procurement unbundles from vehicle acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in heavy-duty commercial vehicles are redirecting manufacturing investment toward markets with domestic battery supply chains and emission compliance deadlines. Net-importing regions accelerate local assembly partnerships while established production bases defend shipment volumes through technology licensing.
China
MIIT production quotas and port electrification mandates concentrate procurement in the Pearl River Delta manufacturing corridor. The country's dual carbon goals compel state-backed demonstration projects validating hydrogen-electric architectures in the Yangtze River Delta. Shenzhen and Shanghai drive urban delivery volume for series hybrid configurations serving e-commerce fulfillment networks.
Germany
EU Green Deal commercial vehicle emission targets expand municipal waste fleet procurement in Hamburg and Munich. KBA certification requirements for heavy-duty durability create technical friction for powertrain validation. The country's integrated powertrain manufacturing sustains European market presence through proprietary diesel-electric architecture.
United States
EPA greenhouse gas standards for medium- and heavy-duty vehicles tighten fleet-average CO2 limits through model year 2032. The Southeast manufacturing corridor attracts battery pack assembly investment to serve regional freight operators. California's Advanced Clean Trucks regulation accelerates hybrid deployment in port logistics serving Los Angeles-Long Beach.
Japan
METI technology roadmaps prioritize silicon carbide power electronics for next-generation hybrid architectures. Domestic manufacturers leverage embedded software expertise for regenerative braking calibration. The Kansai industrial region hosts validation facilities for series hybrid configurations targeting Asian export markets.
India
PLI scheme incentives for commercial vehicle electrification concentrate procurement in Maharashtra and Gujarat logistics corridors. The country's dual carbon goals drive compressed natural gas-electric hybrid adoption where pipeline infrastructure exists. Fleet operators in Delhi-NCR optimize total cost of ownership across 7-10 year replacement cycles.
Hybrid Truck Market Key Industry Players
Concentration sits with integrated automotive conglomerates possessing captive powertrain manufacturing and established service networks. Tiered competitive positioning separates full-line manufacturers from electrification specialists and battery pack assemblers. Two strategic archetypes dominate: legacy truck OEMs defending installed base relationships, and battery-dominant challengers capturing urban delivery procurement. Dominant competitive moves include strategic partnerships for silicon carbide inverter sourcing and portfolio diversification into hydrogen-electric architectures.
Within the integrated automotive tier, Ford Motor Company, Toyota Motor Corporation, and Volvo Group exemplify established archetypes with multi-continent manufacturing footprints. These entities occupy positions spanning diesel-electric through hydrogen-electric technology portfolios. BYD Motors Inc. anchors the battery-dominant specialist segment, representing the configuration most specified by port logistics operators in China's densest freight corridors. Daimler AG and General Motors sit within the premium-tier vector for long-haul durability certification, while Nissan Motor Corporation and Hino Motors, Ltd. exemplify regional specialists with concentrated Asian market presence. The competitive dynamic hinges on unbundling vehicle acquisition from energy sourcing contracts, with third-party fleet management platforms displacing direct OEM relationships in municipal procurement.
| Leading Market Players |
|---|
| Ford Motor Company |
| Toyota Motor Corporation |
| Volvo Group |
| BYD Motors Inc. |
| General Motors |
| Daimler AG |
| Nissan Motor Corporation |
| Hino Motors, Ltd. |
| Mercedes Benz |
| Others |
Cost & Logistics Intelligence
EPA greenhouse gas standards for medium- and heavy-duty vehicles gate both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb certification costs into tiered vehicle architectures while fleet operators face divergent total cost of ownership calculations across compliance timelines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels based on powertrain voltage architecture and after-sales service bundling. Price differentiation separates 800V series hybrid platforms with dedicated thermal management from 300V parallel configurations and 48V mild hybrid entry points. Cost compression in the standard tier is intensifying because silicon carbide inverter sourcing partnerships command premium supplier allocations. Private freight carriers exhibit the highest price sensitivity due to residual value uncertainty, whereas municipal agencies under EU Green Deal mandates accept premium positioning for emission visibility.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cathode materials and silicon carbide wafers is displacing just-in-time preferences among Tier 1 powertrain suppliers facing MIIT quota volatility. Supply concentrates in China for battery cell manufacturing, South Korea for cathode precursor refining, and Japan for power electronics substrates. The hybrid truck ecosystem draws from cobalt-doped lithium nickel manganese oxide, automotive-grade silicon carbide substrates, and high-temperature thermal interface materials. Single-source vulnerability in 800V inverter module assembly creates chokepoint exposure. Distribution runs through captive OEM service networks in Europe and third-party fleet management platforms in Asian urban delivery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting around unbundled vehicle-as-a-service contracts, with third-party fleet management platforms displacing direct OEM relationships and creating interoperability demands across charging infrastructure and battery second-life valuation systems.
For Market Incumbents: Compound defensive positioning through backward integration into silicon carbide inverter manufacturing and captive battery pack assembly in the Pearl River Delta manufacturing corridor. Certification investment for heavy-duty durability standards under KBA and EPA protocols gates market access against battery-dominant challengers. Channel control through multi-year service contracts with municipal waste management fleets in Germany resists displacement by third-party aggregators. For New Entrants and Emerging Players: Lead with hydrogen-electric fuel cell-battery architectures for Australian mining corridor operators and Chinese state-backed Yangtze River Delta demonstration projects, the most penetrable white space beyond diesel-electric installed bases. Refrigerated transport auxiliary power systems for cold-chain logistics offer margin expansion potential with dedicated electric refrigeration drives. A go-to-market angle through battery second-life valuation partnerships with fleet operators optimizes total cost of ownership messaging. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrogen-electric long-haul architectures as infrastructure commitments materialize. The 5-10 year viability window favors acquisition targets with embedded software expertise for regenerative braking calibration and thermal system integration. Vertically integrated powertrain specialists with captive silicon carbide sourcing represent the priority archetype. The signal to watch is port logistics operator procurement specifications shifting from diesel-electric to fuel cell-battery hybrid configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Sourcing Partnership | EPA thermal efficiency mandates force SiC adoption for 800V architectures in port logistics procurement. |
| Hydrogen-Electric Architecture Validation | Chinese state-backed demonstration projects in the Yangtze River Delta test heavy long-haul durability. |
| Battery Second-Life Valuation Platform | Fleet operators monetize end-of-first-life packs through stationary storage arbitrage under MIIT credit systems. |
| Thermal System Integration Capability | F-Gas refrigerant restrictions demand cross-functional engineering scarce in traditional truck OEMs. |
| Third-Party Fleet Management Aggregation | German municipal procurement rules favor multi-vendor service contracts over direct OEM relationships. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 powertrain procurement leads, municipal fleet managers in Hamburg and Munich, and port logistics operators in Shenzhen, then refined against secondary validation from EPA regulatory filings, MIIT production quota disclosures, EU Green Deal implementation documents, and IHS Markit commercial vehicle registration databases. Bottom-up triangulation across powertrain architecture segmentation converged with top-down market sizing from trade flow analysis.
Variance decomposition across powertrain type, application duty cycle, voltage architecture tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume buildups and value-per-unit trajectories. Forecast inputs incorporated silicon carbide adoption curves in inverter specifications and hydrogen infrastructure commitment timelines in Chinese demonstration corridors.
Forecasts assume regulatory continuity in EPA greenhouse gas standards and EU F-Gas refrigerant phase-down schedules; material policy shifts would require re-modeling. Battery cell supply concentration in Asian cathode material processing and heavy-duty durability certification friction represent specific revision triggers. Revision becomes warranted when hydrogen-electric procurement specifications in port logistics cross threshold penetration levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market