
 Germany Hybrid Electric Vehicle Battery Market | 2026-2036
Germany Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Hybrid Electric Vehicle Battery Market Insights
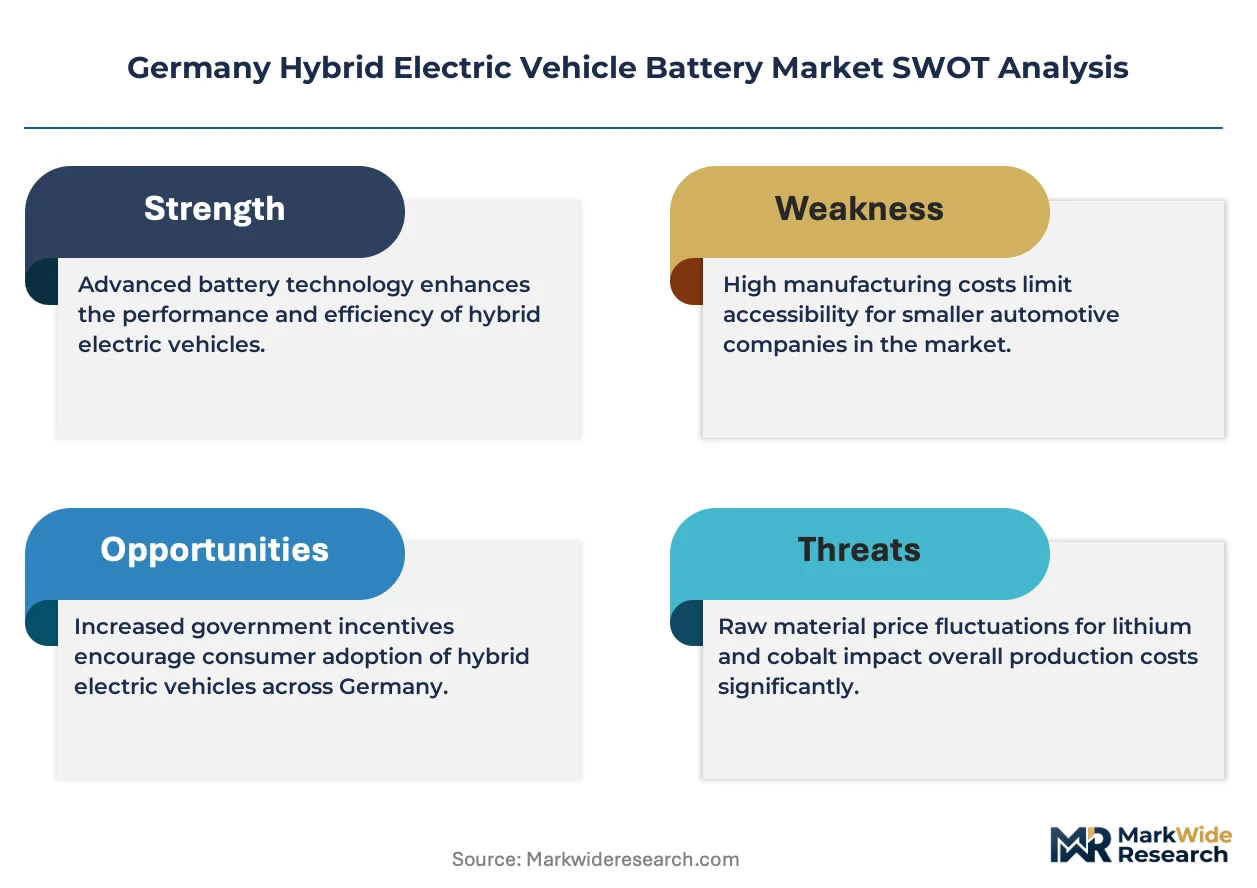
Aftermarket service revenue for legacy nickel-metal hydride refurbishment is narrowing as lithium-ion cell longevity extends replacement cycles. LG Energy Solution leverages its Polish manufacturing footprint to supply German OEM assembly lines with minimal cross-border friction. Samsung SDI sustains premium positioning through high-nickel cathode chemistry tailored to German performance hybrid architectures. Northvolt AB anchors domestic supply security with its planned German gigafactory, reducing import dependency for European automakers.
Germany hybrid electric vehicle batteries store electrical energy for propulsion assistance alongside internal combustion engines, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathodes rated between 200 and 400 volts. These systems enable torque fill, regenerative braking energy recovery, and short-range electric-only operation in passenger and light commercial vehicles. Lithium-ion chemistry dominates installed capacity due to superior energy density and declining cell cost curves, while solid-state formulations attract R&D capital for next-generation thermal stability. Fleet operators represent the fastest-growing end-user channel as German delivery and municipal services electrify under emissions-zone restrictions, whereas private owners still concentrate in premium sedan and SUV segments where hybrid powertrains offset range anxiety.
The KBA enforces type-approval standards for battery safety and electromagnetic compatibility across all hybrid systems sold in Germany, while EU REACH and RoHS frameworks restrict hazardous substance content in cell manufacturing inputs. Germany's national implementation of the EU CO2 fleet targets for automakers effectively mandates hybrid electrification as a compliance bridge technology through the mid-2030s. Stakeholders must monitor how the EU Battery Regulation's recycled-content mandates and carbon-footprint declarations reshape cell supplier qualification criteria for German vehicle programs.
Market Dynamics
The EU Battery Regulation's carbon-footprint declarations and recycled-content mandates are compressing supplier qualification timelines for German OEMs, forcing accelerated supply chain reconfiguration before the 2030 compliance thresholds.
Growth Catalysts
- EU CO2 Fleet Targets:Germany's national implementation mandates hybrid electrification as a compliance bridge technology through the mid-2030s, compelling automakers to expand battery procurement programs.
- Fleet Electrification:German delivery and municipal services operators are accelerating vehicle replacement cycles under emissions-zone restrictions in urban centers.
- Cell Chemistry Advances:High-nickel cathode formulations are extending energy density in performance hybrid architectures, enabling longer electric-only range in premium segments.
Market Restraints
- Raw Material Concentration:Cobalt and refined lithium supply chains concentrate in politically unstable jurisdictions, exposing German pack assemblers to price volatility and export restriction risk.
- Cell Manufacturing Scale-Up Lag:Domestic European cell production capacity remains insufficient to match German OEM demand curves through the late 2020s.
- Legacy Nickel-Metal Hydride Lock-In:Extended service life in existing hybrid fleets delays replacement demand and narrows aftermarket refurbishment revenue windows.
Strategic Opportunities
- Rhine-Ruhr Logistics Corridors:Dense freight networks in North Rhine-Westphalia offer concentrated deployment potential for hybrid commercial vehicle electrification.
- Solid-State Convergence:Interface engineering between ceramic electrolytes and silicon-anode architectures promises next-generation thermal stability for German performance applications.
- Second-Life Stationary Storage:Retired automotive battery packs are finding secondary applications in German grid-balancing installations, extending value extraction from initial cell production.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:German universities produce insufficient specialists in cell characterization and battery management system firmware development to meet OEM hiring targets.
- REACH Compliance Complexity:Substance restriction updates require continuous reformulation of electrolyte additives and separator coatings, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Hybrid Electric Vehicle Battery Market |
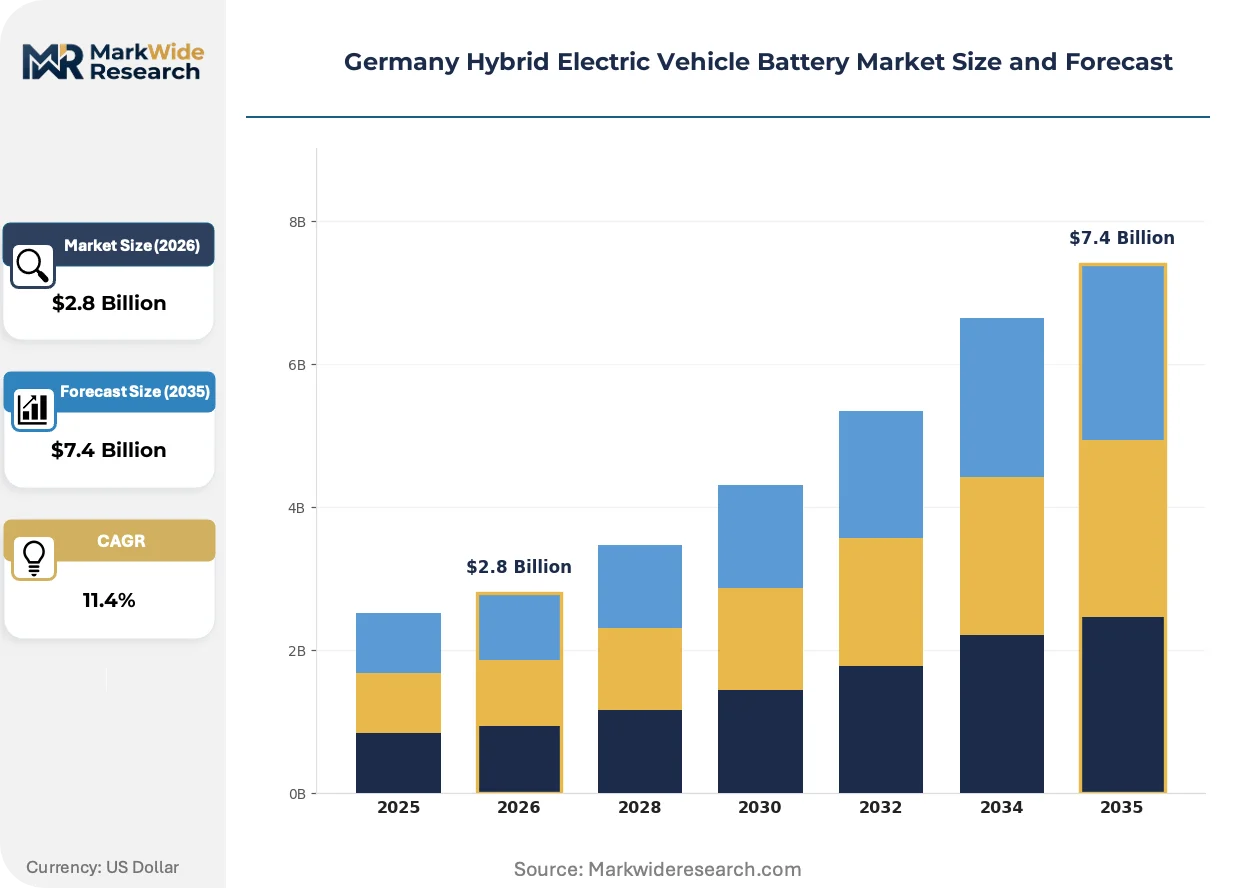
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
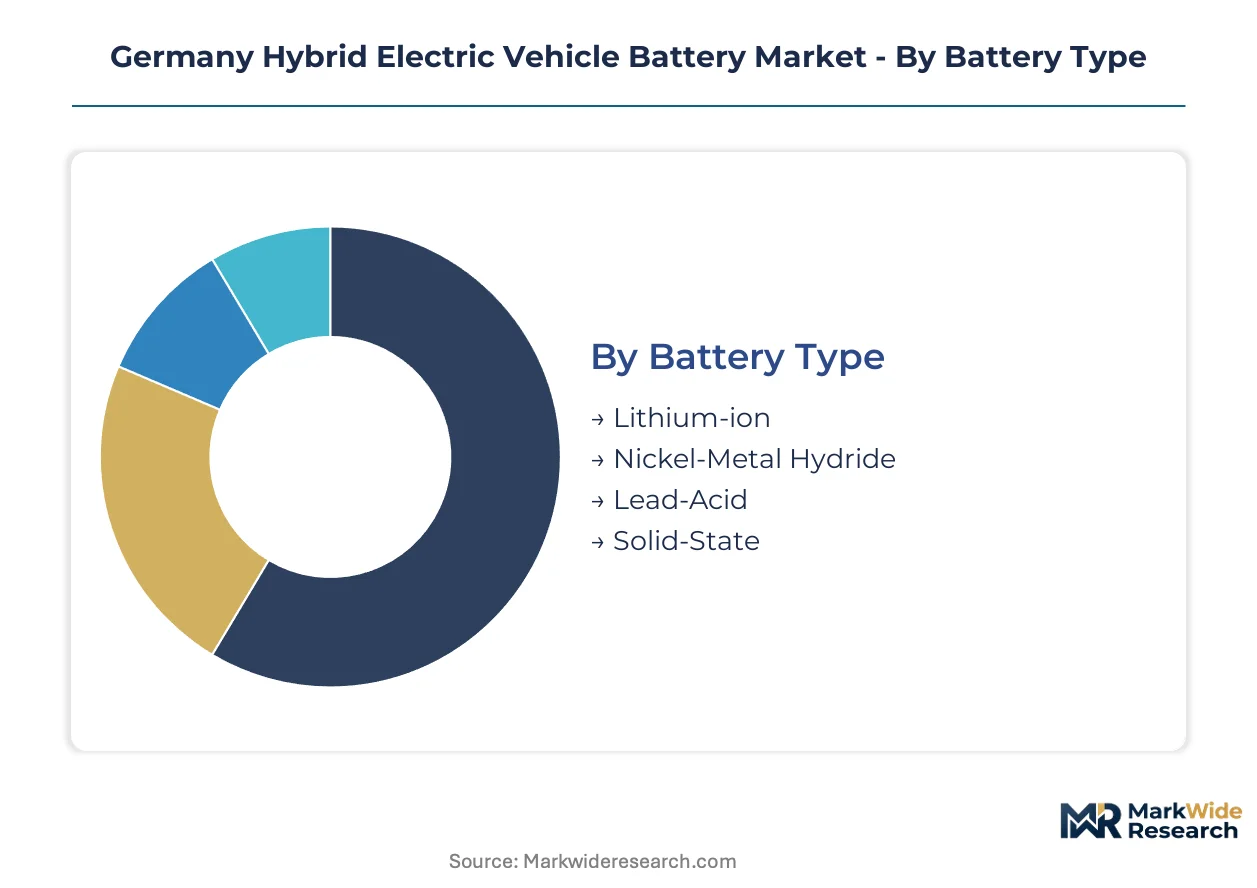
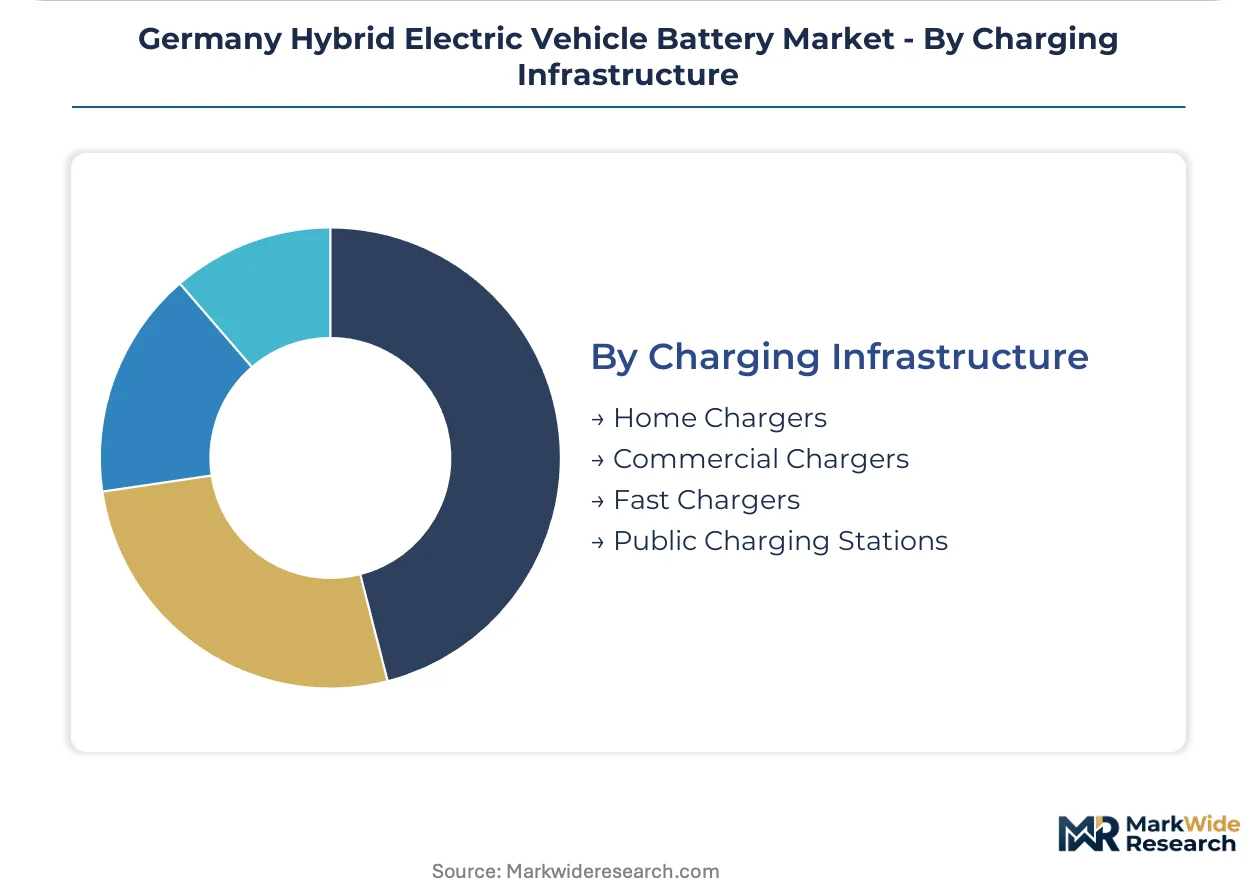
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Vehicle Model: SUV, Sedan, Hatchback, Sports Car End User: Fleet Operators, Private Owners, Car Rentals, Government Agencies Charging Infrastructure: Home Chargers, Commercial Chargers, Fast Chargers, Public Charging Stations |
| Companies Covered | LG Energy Solution, Contemporary Amperex Technology Co Ltd, BYD Company, Northvolt AB, Vehicle Energy Japan Inc, Samsung SDI, Panasonic Corporation, SK On, GS Yuasa Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Hybrid Electric Vehicle Battery Market Trends and Innovations
Active materials and pack architectures are undergoing simultaneous transformation as German OEMs balance performance requirements against emerging regulatory constraints on carbon intensity and material provenance.
Silicon-dominant anode formulations are migrating from laboratory-scale validation to series production programs at German premium manufacturers. BMW and Mercedes-Benz engineering centers have accelerated silicon oxide blending ratios in cylindrical cell designs to push gravimetric energy density past 300 watt-hours per kilogram. This chemistry migration from graphite baselines is compressing cobalt content requirements while introducing new challenges in electrode expansion management during cycling.
Germany's Federal Motor Transport Authority enforces type-approval standards for battery safety and electromagnetic compatibility that exceed baseline EU harmonized requirements. The KBA's extended thermal propagation testing protocols have forced pack designers to incorporate additional ceramic fiber barriers and venting channels. Premium SUV and light commercial vehicle segments absorb the highest compliance costs, passing engineering investments through to fleet procurement contracts.
Leasing structures are displacing direct purchase for hybrid battery systems in German commercial fleets. Municipal operators and logistics providers now favor full-service contracts bundling cell replacement, thermal management maintenance, and end-of-life recycling obligations. This financing rotation concentrates most visible in Berlin and Hamburg metropolitan procurement frameworks, where total-cost-of-ownership calculations dominate capital allocation decisions.
Germany Hybrid Electric Vehicle Battery Market Segmentation
German hybrid battery procurement patterns diverge sharply across vehicle architectures and ownership structures. Fleet operators prioritize total-cost-of-ownership metrics while private owners respond to performance specifications and brand positioning.
Battery Type:
Mature lithium-ion platforms dominate installed base while solid-state formulations occupy emerging qualification pipelines at German OEM engineering centers.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathodes rated between 200-400 volts enable torque fill and regenerative braking recovery. Demand concentrates in Rhine-Ruhr metropolitan assembly corridors where BMW and Mercedes-Benz pack integration facilities cluster under KBA type-approval protocols.
- Solid-State:Ceramic electrolyte architectures with silicon-anode interfaces promise next-generation thermal stability for performance hybrid applications. German premium manufacturers are accelerating laboratory-scale validation toward series production timelines as EU Battery Regulation carbon-footprint mandates compress supplier qualification windows.
- Nickel-Metal Hydride:Legacy chemistry persists in existing hybrid fleets with extended service life delaying replacement cycles.
- Lead-Acid:Auxiliary power applications in light commercial micro-hybrid systems support start-stop functionality at lower voltage thresholds.
Lithium-ion handles the majority of throughput; solid-state is expanding most quickly on share as OEMs position for post-2030 thermal performance requirements.
Vehicle Model:
Cost tier stratification separates premium SUV engineering investments from mass-market hatchback procurement volumes.
- SUV:Premium segment architectures absorb highest KBA thermal propagation compliance costs through ceramic fiber barriers and venting channels. Fleet procurement contracts in North Rhine-Westphalia logistics corridors favor hybrid SUV platforms for combined payload capacity and emissions-zone access.
- Sedan:Mid-size executive configurations balance electric-only range against internal combustion efficiency for private owners in Berlin and Hamburg metropolitan areas.
- Hatchback:Compact urban formats dominate municipal service electrification under German city center restriction schemes.
- Sports Car:Performance hybrid architectures utilize high-nickel cathode chemistry for transient torque delivery in limited-production German specialty vehicles.
SUV configurations command the steepest pricing premium; hatchback platforms are gaining share fastest in fleet renewal cycles.
End User:
Customer type determines financing structure and service bundling requirements across German procurement frameworks.
- Fleet Operators:Delivery and municipal services operators in German urban centers are accelerating replacement cycles under emissions-zone restrictions. Full-service leasing contracts now bundle cell replacement, thermal management maintenance, and end-of-life recycling obligations through Berlin and Hamburg metropolitan procurement frameworks.
- Private Owners:Premium sedan and SUV segments concentrate where hybrid powertrains offset range anxiety through brand positioning and performance specifications.
- Car Rentals:Short-term mobility providers balance acquisition cost against residual value exposure in German airport and city-center locations.
- Government Agencies:Federal and state procurement mandates prioritize domestic supply security under Germany's national hydrogen strategy and EU Green Deal implementation.
Fleet operators represent the steepest expansion trajectory; private owners retain the largest installed base volume.
Charging Infrastructure:
Geography of installation separates residential density from commercial corridor throughput requirements.
- Home Chargers:Residential installations in German suburban and rural municipalities support overnight replenishment for private hybrid owners with dedicated parking infrastructure.
- Commercial Chargers:Workplace and retail location deployments serve fleet depot operations and employee benefit programs across German logistics hubs.
- Fast Chargers:Highway corridor installations enable extended-range hybrid operation for intercity commercial transport along Rhine-Ruhr freight networks.
- Public Charging Stations:Municipal street parking integration supports urban residents without dedicated charging access in Berlin, Hamburg, and Munich metropolitan cores.
Home chargers handle the majority of replenishment events; fast chargers are climbing the fastest on infrastructure investment share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across German sub-regions. Fleet operators in industrial corridors prioritize total-cost-of-ownership metrics, while private buyers in affluent metropolitan cores absorb premium pricing for performance specifications.
North Rhine-Westphalia
Logistics operators along Rhine-Ruhr freight corridors drive concentrated hybrid commercial vehicle procurement. The KBA enforces type-approval standards for battery safety and electromagnetic compatibility that exceed baseline EU requirements. Düsseldorf and Cologne host BMW and Mercedes-Benz pack integration facilities where thermal propagation testing protocols force ceramic fiber barrier incorporation.
Bavaria
Premium automotive engineering centers in Munich anchor high-nickel cathode chemistry development for performance hybrid architectures. Germany's national hydrogen strategy accelerates phase-out timelines for pure internal combustion platforms through the Free State's manufacturing base. Ingolstadt and Munich metropolitan areas concentrate OEM battery management system firmware development teams facing acute talent scarcity.
Baden-Württemberg
Stuttgart's automotive supplier ecosystem supports silicon-anode validation programs migrating toward series production. EU REACH and RoHS frameworks restrict hazardous substance content in cell manufacturing inputs affecting electrolyte additive formulation. The Neckar-Alb region clusters solid-state battery R&D facilities pursuing ceramic electrolyte interface engineering.
Berlin-Brandenburg
Municipal service electrification under city center emissions-zone restrictions accelerates hatchback fleet replacement cycles. Full-service leasing contracts now bundle cell replacement, thermal management maintenance, and end-of-life recycling obligations through metropolitan procurement frameworks. Tesla's Grünheide facility proximity influences regional supplier qualification expectations for carbon-footprint declarations.
Lower Saxony
Volkswagen Group's Wolfsburg headquarters anchors mass-market hybrid platform battery procurement programs. The EU Battery Regulation's recycled-content mandates compress supplier qualification timelines for volume vehicle programs. Hanover's commercial vehicle manufacturing corridor favors hybrid SUV platforms balancing payload capacity against emissions-zone access requirements.
Germany Hybrid Electric Vehicle Battery Market Competitive Landscape
Integrated cell manufacturers and specialist pack assemblers split the market along capability lines. Korean and Chinese producers dominate lithium-ion cell supply through established European distribution infrastructure. Three archetypes define competitive positioning: scale-driven chemistry specialists, vertically integrated automotive suppliers, and emerging European domestic champions. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs secure qualification under tightening carbon-footprint thresholds.
Within the scale-driven tier, LG Energy Solution and Samsung SDI exemplify established supply relationships leveraging Polish manufacturing proximity to German assembly lines. Contemporary Amperex Technology Co Ltd occupies a position among Chinese producers with expanding European qualification pipelines. Northvolt AB anchors the domestic champion archetype through its planned German gigafactory, reducing import dependency for European automakers facing EU Battery Regulation compliance deadlines.
| Leading Market Players |
|---|
| LG Energy Solution |
| Contemporary Amperex Technology Co Ltd |
| BYD Company |
| Northvolt AB |
| Vehicle Energy Japan Inc |
| Samsung SDI |
| Panasonic Corporation |
| SK On |
| GS Yuasa Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European cell manufacturing is compressing supplier pricing power while elevating long-term offtake premiums for German OEMs seeking supply security under EU Battery Regulation deadlines.
Pricing Analysis
Aftermarket service contracts now drive lifetime value extraction as full-service leasing bundles displace direct battery purchases across German commercial fleets. Three-tier pricing structure across premium, standard, and economy levels stratifies by cathode chemistry grade and KBA certification tier, with high-nickel formulations commanding substantial premiums. Cost compression in nickel-metal hydride refurbishment is intensifying because lithium-ion longevity extends replacement cycles. Fleet operators exhibit the highest price sensitivity through total-cost-of-ownership calculations, whereas private owners in premium segments absorb performance-driven premiums with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on advanced cathode manufacturing equipment are constraining technology transfer to emerging European producers and preserving incumbent supplier advantages. Cell production concentrates in China, South Korea, and Japan, with German pack assembly drawing from refined lithium, cobalt, and nickel sulfate feedstocks. Single-source vulnerability around Chinese cathode precursor supply creates structural exposure for European qualification timelines. Distribution runs through just-in-time delivery corridors from Polish manufacturing footholds to Rhine-Ruhr OEM integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German hybrid battery procurement constitutes a defensive-moat market where regulatory entrenchment through KBA type-approval protocols creates substantial switching costs for qualified suppliers.
For Market Incumbents: Harden supply relationships through backward integration into cathode precursor production and captive recycling capacity under EU Battery Regulation recycled-content mandates. Secure engineering talent pipelines in battery management system firmware development to offset electrochemical specialist scarcity threatening OEM hiring targets. For New Entrants and Emerging Players: Establish a beachhead in second-life stationary storage applications for retired automotive packs, where grid-balancing demand in Berlin-Brandenburg offers lower qualification barriers than vehicle programs. Target municipal fleet procurement frameworks with full-service leasing propositions bundling thermal management and end-of-life obligations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state ceramic electrolyte manufacturing as German premium OEMs accelerate laboratory validation toward series production. Acquisition candidates should demonstrate EU Battery Regulation carbon-footprint declaration readiness and established KBA thermal propagation testing compliance. Watch for inflection in silicon-anode electrode expansion management yield rates as the critical viability signal.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Gigafactory Capacity Buildout | Northvolt AB's German facility reduces import dependency under EU Battery Regulation compliance deadlines. |
| Silicon-Anode Chemistry Migration | BMW and Mercedes-Benz engineering centers push gravimetric energy density past 300 watt-hours per kilogram. |
| Full-Service Leasing Contract Expansion | Berlin and Hamburg municipal frameworks bundle cell replacement with end-of-life recycling obligations. |
| Solid-State Interface Engineering Partnership | Baden-Württemberg R&D clusters pursue ceramic electrolyte thermal stability for performance applications. |
| Second-Life Stationary Storage Deployment | Retired automotive packs extend value extraction through German grid-balancing installations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with battery pack procurement leads, OEM platform engineers, Tier 1 supplier technical directors, and fleet operations managers; and secondary validation through KBA type-approval filings, EU REACH substance restriction updates, vehicle production databases, and customs trade records. Bottom-up cell demand modeling triangulated against top-down OEM electrification program announcements across the analysis window.
Forecast inputs incorporated vehicle class segmentation, propulsion architecture differentiation, content per vehicle trajectories, and regional production cluster capacity expansion schedules. CAGRs were derived from regression analysis of historical procurement patterns projected against EU CO2 fleet target compliance curves and national hydrogen strategy phase-out timelines.
Stress conditions across raw material price volatility, export restriction scenarios, and cell manufacturing scale-up delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on cathode chemistry adoption rates and KBA protocol evolution. Material shifts in EU Battery Regulation carbon-footprint threshold stringency or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Vehicle Market