
 Middle Office Outsourcing Market | 2026-2036
Middle Office Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle Office Outsourcing Market Analysis
Back-office reconciliation margin is narrowing as providers push upstream into trade execution support and portfolio analytics. SS&C Technologies leverages its custody-technology stack to anchor multi-asset class servicing. Genpact competes through embedded artificial intelligence in compliance workflows. State Street dominates securities-lending infrastructure, extending its footprint into data aggregation for alternative asset managers.
Middle office outsourcing encompasses the delegation of trade processing, risk management, compliance monitoring, and data aggregation functions that sit between front-office revenue generation and back-office settlement. Providers deliver these services through cloud-native platforms, robotic process automation, and predictive analytics to reduce operational error rates and accelerate regulatory reporting cycles. Trade processing and risk management command the largest share of contracted value, while artificial intelligence-enabled compliance services represent the fastest-expanding margin pool. Cloud computing underpins scalability across asset-manager clients, whereas hybrid solutions—blending managed services with client-retained technology—capture growing preference among hedge funds and private equity firms seeking configurability without full infrastructure replacement.
US SEC oversight of investment-adviser outsourcing, UK FCA operational resilience requirements, and Singapore MAS technology risk-management guidelines collectively elevate vendor due-diligence standards and contractual liability. European EBA outsourcing guidelines and impending DORA compliance deadlines further tighten audit-trail and business-continuity obligations for cross-border providers. Stakeholders must weigh vendor concentration risk against the operational leverage gained from consolidating multiple middle-office functions under single-platform arrangements.
Market Dynamics
Cloud-native infrastructure is compressing the cost curve for trade processing and risk analytics, forcing incumbent providers to re-architect legacy platforms or cede ground to agile challengers deploying containerized microservices and API-first architectures.
Growth Catalysts
- SEC outsourcing oversight:Heightened US investment-adviser due-diligence requirements compel asset managers to professionalize vendor selection, expanding addressable market for qualified providers.
- Private equity fund administration:Surging alternative asset AUM creates demand for portfolio analytics and investor reporting beyond traditional mutual-fund servicing capabilities.
- Robotic process automation:Deployment of software bots for reconciliation and exception handling reduces unit costs and accelerates contract win rates in competitive RFPs.
Market Restraints
- Vendor concentration risk:Heavy reliance on single-platform arrangements for multiple middle-office functions creates systemic exposure if provider operational resilience fails.
- Hybrid cloud complexity:Technical debt from blending client-retained infrastructure with managed services extends implementation timelines and inflates integration costs.
- DORA compliance friction:EU Digital Operational Resilience Act mandates stringent audit trails and business-continuity testing that smaller providers struggle to satisfy.
Strategic Opportunities
- Japan METI fintech sandbox:Regulatory experimentation framework enables pilot deployments of AI-enabled compliance tools for cross-border fund managers.
- Tokenized asset servicing:Convergence of distributed ledger technology with traditional custody systems opens margin pools for digital-asset middle-office functions.
- Wealth management democratization:Retail robo-advisory platforms in Singapore require scalable back-to-middle-office integration previously reserved for institutional clients.
Industry Challenges
- Quantitative risk-modeling talent scarcity:Shortage of professionals fluent in both derivatives pricing and cloud architecture constrains platform development velocity.
- Legacy system entanglement:Core banking and custody platforms from the 1990s resist API modernization, fragmenting data flows across hybrid environments.
- Cross-border data residency:Conflicting jurisdictional requirements for trade data storage complicate multi-entity outsourcing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle Office Outsourcing Market |
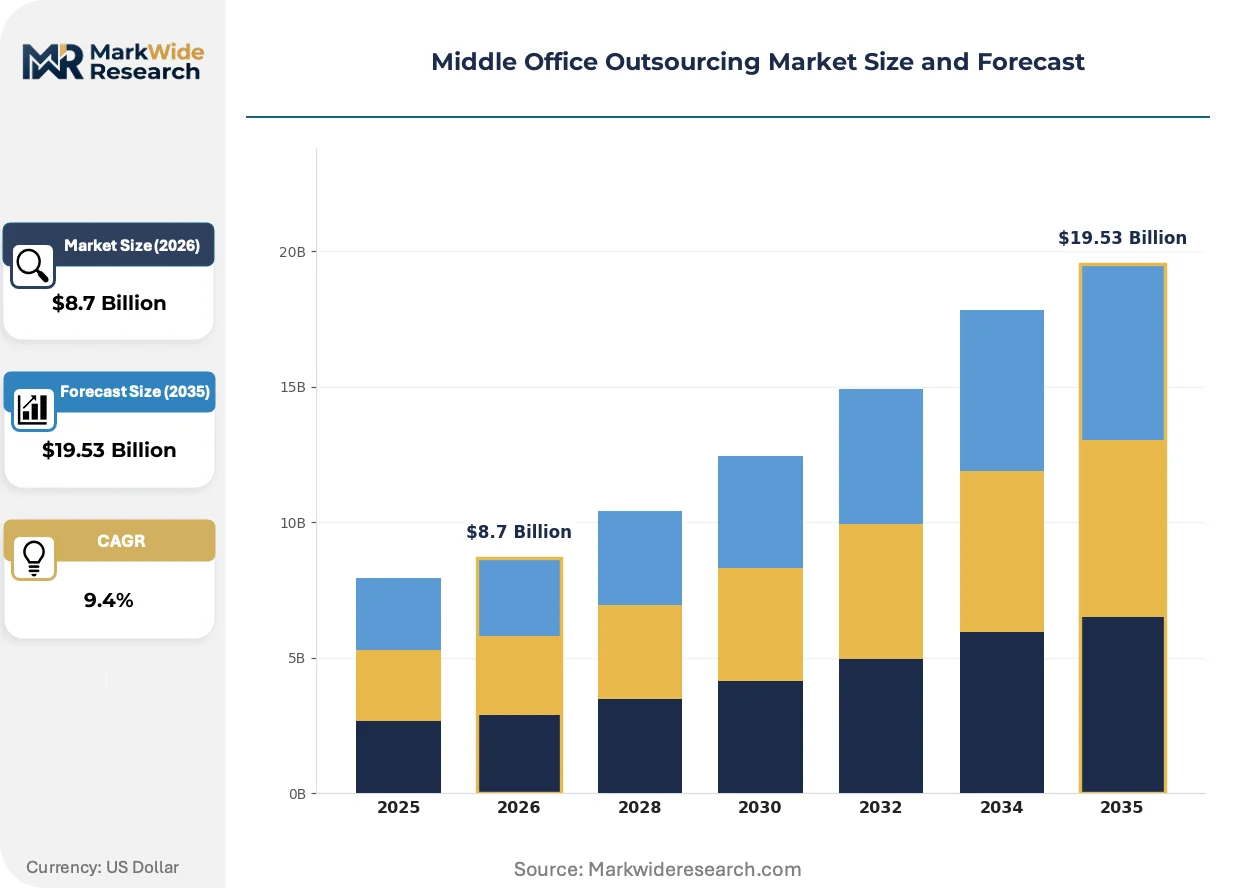
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Trade Processing, Risk Management, Compliance Services, Data Management End User: Investment Banks, Hedge Funds, Asset Managers, Private Equity Firms Technology: Cloud Computing, Robotic Process Automation, Big Data Analytics, Artificial Intelligence Solution: Managed Services, Consulting, Technology Solutions, Hybrid Solutions |
| Companies Covered | SS&C Technologies, Citigroup, Accenture, Apex Group, Genpact, BNY Mellon, Northern Trust, JPMorgan Chase & Co., State Street, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle Office Outsourcing Market Emerging Trajectories
Artificial intelligence is penetrating compliance workflows and predictive risk analytics, while regulatory pressure on operational resilience accelerates platform consolidation and cloud migration across buy-side institutions.
Containerized microservices architecture is virtualizing legacy trade-processing stacks. Hedge funds and boutique asset managers are adopting Kubernetes-orchestrated deployments fastest, bypassing monolithic vendor platforms. This technology is virtualizing the traditional vendor-client boundary, enabling modular service procurement that compresses switching costs and expands competitive entry points.
EU DORA implementation deadlines are forcing cross-border providers to harden incident-response protocols and third-party risk-management frameworks. Asset servicers must now maintain redundant processing sites and real-time regulatory reporting pipelines. European UCITS and AIFM fund structures face the steepest compliance burden, driving consolidation toward providers with pre-certified operational resilience infrastructure.
Subscription-based service models are displacing traditional fixed-fee outsourcing contracts. Mid-market asset managers are negotiating usage-linked pricing tied to trade volumes and portfolio complexity rather than asset-under-management baselines. This shift is most pronounced in the United Kingdom, where regulatory cost-disclosure rules sharpen price transparency and accelerate vendor switching cycles.
Middle Office Outsourcing Market Segmentation
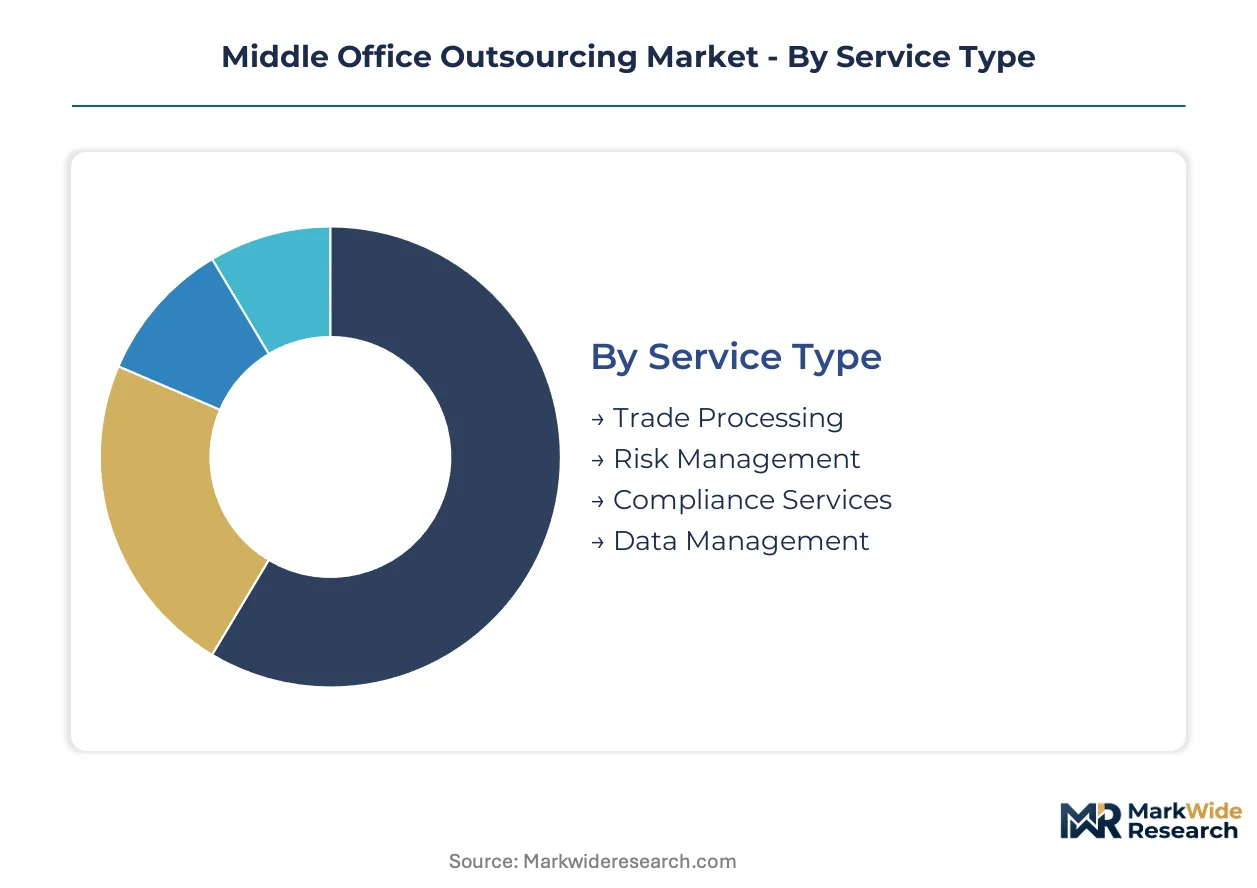
Segmentation in middle office outsourcing reveals how service providers align capabilities with distinct operational pain points across asset classes and technology maturity levels. Each dimension exposes different margin structures, implementation complexity, and vendor selection criteria that shape competitive positioning.
Service Type:
After-sales service intensity varies sharply across service types, with trade processing demanding 24/7 exception-handling support while compliance services require periodic regulatory updates and audit trail maintenance.
- Trade Processing:Encompasses order routing, trade confirmation, and settlement instruction generation across equities, fixed income, and derivatives. Investment banks in the United States and United Kingdom drive contract value, pressured by SEC and FCA requirements for T+1 settlement acceleration and real-time trade reporting.
- Risk Management:Delivers portfolio analytics, stress testing, and counterparty exposure monitoring through cloud-native calculation engines. Hedge funds seeking VAR model outsourcing and private equity firms managing illiquid asset valuation represent concentrated demand, constrained by quantitative talent scarcity and model validation burdens.
- Compliance Services:Regulatory reporting, surveillance, and policy management functions.
- Data Management:Aggregation, normalization, and distribution of investment data across internal systems and external counterparties.
By volume, trade processing leads. By growth pace, compliance services is ahead.
End User:
Cost tier differentiation separates institutional clients willing to pay premium fees for bespoke integration from mid-market buyers seeking standardized platforms with faster deployment.
- Investment Banks:Multi-asset class trading operations with complex cross-border regulatory footprints. FCA operational resilience mandates and SEC outsourcing oversight drive vendor consolidation toward providers with pre-certified infrastructure and redundant processing sites.
- Asset Managers:Mutual fund and ETF sponsors requiring scalable middle-office support across expanding product ranges. Singapore-based managers are deepening reliance on third-party infrastructure as MAS technology risk-management guidelines elevate vendor due-diligence standards.
- Hedge Funds:Boutique and multi-strategy firms prioritizing agility and rapid onboarding.
- Private Equity Firms:Alternative asset managers with specialized portfolio analytics and investor reporting requirements.
Asset managers dominate current contract value. Private equity firms are expanding most quickly as surging AUM creates demand beyond traditional mutual-fund servicing capabilities.
Technology:
Application maturity determines implementation risk, with cloud computing now baseline while artificial intelligence deployments remain experimental and talent-constrained.
- Cloud Computing:Foundational infrastructure for scalable trade processing and data aggregation. Containerized microservices and Kubernetes-orchestrated deployments are displacing monolithic legacy platforms, particularly among agile challengers and mid-market asset managers seeking configurability without full infrastructure replacement.
- Artificial Intelligence:Machine learning models for predictive risk analytics, compliance surveillance, and exception prediction. Genpact and similar providers embed AI in regulatory workflows, though model explainability requirements under EU AI Act and similar frameworks constrain deployment velocity.
- Robotic Process Automation:Software bots for reconciliation, data validation, and routine reporting tasks.
- Big Data Analytics:Large-scale portfolio and market data processing for investment decision support.
Cloud computing commands the largest installed base. Artificial intelligence represents the steepest expansion trajectory as regulatory pressure accelerates automation investment.
Solution:
Customer type preferences split between fully outsourced managed services and hybrid arrangements retaining client-side technology control.
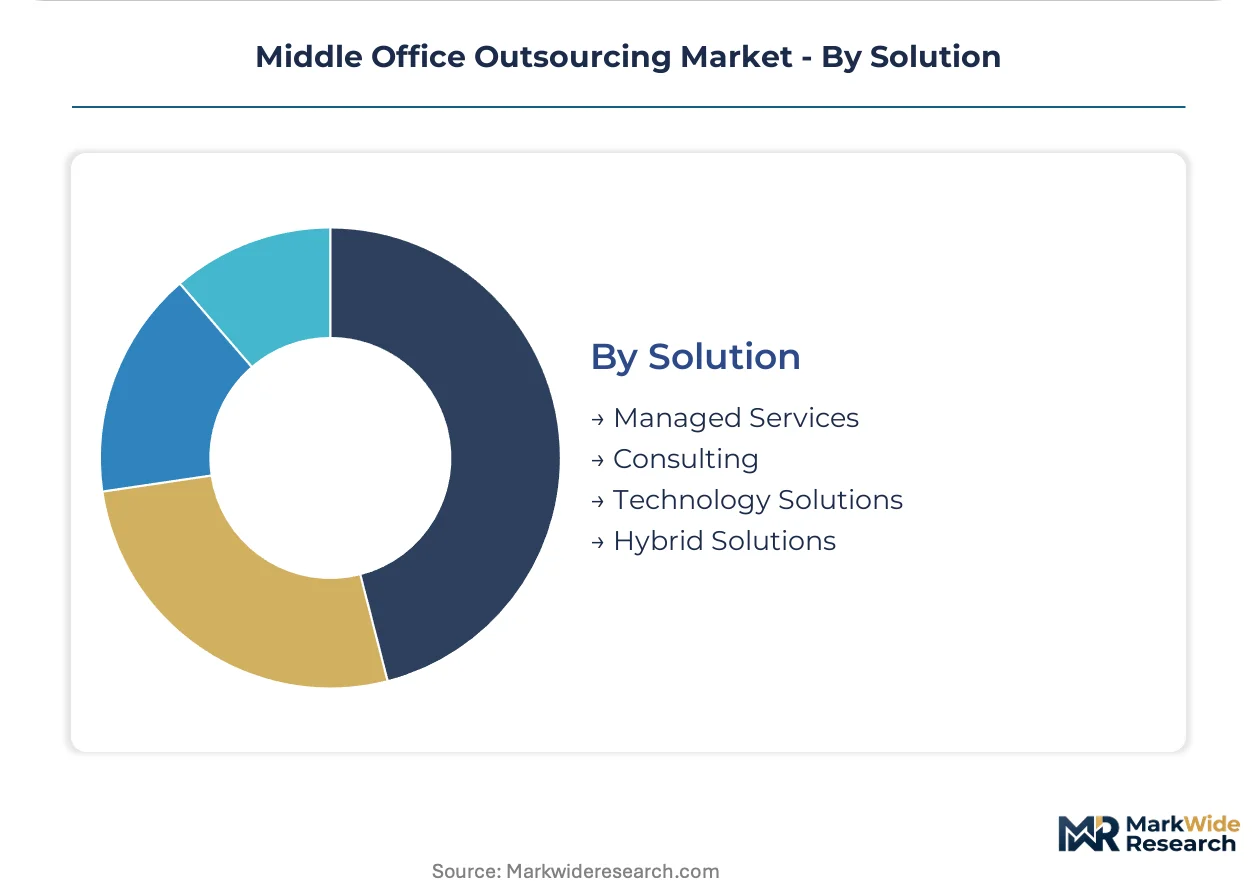
- Managed Services:Comprehensive outsourcing of middle-office functions with provider-owned technology and staff. SS&C Technologies anchors multi-asset class servicing through custody-technology stacks, capturing hedge funds and private equity firms seeking to offload operational complexity without capital expenditure.
- Hybrid Solutions:Blending client-retained infrastructure with provider-managed components. This model captures growing preference among alternative asset managers requiring configurability, though technical debt from integration extends implementation timelines and inflates upfront costs.
- Consulting:Advisory engagements for vendor selection, process redesign, and regulatory readiness.
- Technology Solutions:Licensed software platforms deployed on client infrastructure.
Managed services retains the largest revenue share. Hybrid solutions are gaining share fastest as regulatory complexity drives demand for customized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes middle office outsourcing as a regulatory compliance necessity, while Singapore and the United Kingdom treat it as a competitive infrastructure investment, and Germany approaches it through operational resilience standardization.
United States
Asset managers in New York and Boston are consolidating vendor relationships under SEC outsourcing oversight mandates for investment advisers. The regulator's heightened due-diligence requirements compel institutional investors to professionalize vendor selection processes. Chicago's derivatives trading community drives specialized demand for risk analytics and portfolio stress-testing capabilities.
United Kingdom
London-based investment banks face FCA operational resilience requirements that mandate redundant processing sites and real-time regulatory reporting pipelines. The regulator's deadlines for business-continuity testing accelerate consolidation toward providers with pre-certified infrastructure. Edinburgh's fund administration cluster deepens reliance on third-party trade processing as UCITS and AIFM structures face steep compliance burdens.
Singapore
Wealth management platforms and family offices in the city-state expand middle office partnerships under MAS technology risk-management guidelines. The regulator's vendor due-diligence standards elevate contractual liability thresholds for cross-border providers. The Raffles Place financial district hosts concentrated demand for cloud-native portfolio analytics serving Southeast Asian fund distribution.
Germany
Frankfurt's asset servicers prepare for EU Digital Operational Resilience Act implementation with stringent audit-trail and incident-response protocol investments. The EBA outsourcing guidelines tighten cross-border provider obligations ahead of DORA deadlines. Munich's private banking sector experiments with hybrid cloud deployments blending client-retained infrastructure with managed service components.
Japan
Tokyo-based fund managers pilot AI-enabled compliance tools through METI's fintech sandbox regulatory experimentation framework. The program enables cross-border asset managers to test automated surveillance and exception prediction workflows. Osaka's regional banking trusts explore robotic process automation for reconciliation tasks previously handled through manual back-office operations.
Middle Office Outsourcing Market Vendor Landscape
Capability concentration sits with technology-anchored specialists; scale advantage sits with custody-bank incumbents. The market structures around three tiers: global custodians extending into data aggregation, pure-play outsourcers deploying cloud-native platforms, and consulting firms embedding artificial intelligence in compliance workflows. Consolidation pressure favors providers with redundant processing sites and pre-certified operational resilience infrastructure. Strategic moves center on custody-technology stack integration and containerized microservices architecture deployment.
Within the custody-bank tier, State Street and BNY Mellon occupy positions built on securities-lending infrastructure and multi-asset class servicing heritage. SS&C Technologies exemplifies the technology-anchored specialist archetype through its custody-technology stack approach to hedge fund and private equity client acquisition. Genpact represents the AI-embedded workflow specialist, competing through machine learning deployment in regulatory compliance and surveillance functions.
| Leading Market Players |
|---|
| SS&C Technologies |
| Citigroup |
| Accenture |
| Apex Group |
| Genpact |
| BNY Mellon |
| Northern Trust |
| JPMorgan Chase & Co. |
| State Street |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on cloud infrastructure hyperscalers determines both pricing tier spreads and supply chain shape across middle office outsourcing. US SEC outsourcing oversight and EU DORA compliance deadlines compress margins for providers lacking redundant processing sites while amplifying premium pricing power for certified operational resilience infrastructure.
Pricing Analysis
Long-term managed service contracts anchor the pricing structure, though subscription-based SaaS tiers are displacing fixed-fee arrangements. Pricing stratifies across premium certified-resilience tiers, standard cloud-native deployments, and economy RPA-augmented offerings, with differentiation driven by operational resilience certification level and trade volume scale. Cost compression in the economy tier intensifies because containerized microservices lower competitive entry barriers. Mid-market asset managers exhibit highest price sensitivity, while hedge funds and private equity firms prioritize configurability over unit cost.
Supply Chain Analysis
Upstream feedstock of quantitative risk-modeling talent and cloud compute capacity concentrates in the United States, the United Kingdom, and India. Provider technology stacks draw from Kubernetes-orchestrated container platforms, legacy custody system APIs, and AI/ML compliance surveillance engines. Single-source vulnerability in securities-lending infrastructure creates systemic exposure if State Street or BNY Mellon operational resilience fails. Distribution runs through direct enterprise sales to asset managers and embedded partnerships with custody banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from containerized microservices challengers bypassing monolithic platforms, requiring defensive consolidation around operational resilience certification and custody-technology stack integration.
For Market Incumbents: Harden operational resilience infrastructure through redundant processing site investments in Singapore and Frankfurt to pre-empt DORA compliance failures. Deepen vertical integration into AI-enabled compliance workflows to neutralize Genpact's machine learning threat in regulatory surveillance. Anchor multi-asset class servicing through custody-technology stack consolidation that raises switching costs for hedge fund and private equity clients.
For New Entrants and Emerging Players: Build out Kubernetes-native trade processing platforms targeting mid-market asset managers in the United Kingdom where regulatory cost-disclosure rules accelerate vendor switching cycles. Target Japan's METI fintech sandbox for pilot deployments of AI-enabled compliance tools serving cross-border fund managers. Pursue direct-to-fund-manager SaaS sales bypassing incumbent custody bank channel control.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors providers with pre-certified operational resilience infrastructure and redundant processing sites. Long-term viability hinges on cloud-native platform architecture and regulatory compliance automation capabilities across the projection horizon. Monitor DORA implementation deadlines as inflection indicator for accelerated vendor consolidation toward compliant providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Operational Resilience Certification | SEC and FCA mandates elevate contractual liability thresholds for cross-border providers lacking redundant infrastructure. |
| Containerized Microservices Deployment | Kubernetes-orchestrated platforms compress switching costs and expand competitive entry points against legacy vendors. |
| AI-Enabled Compliance Integration | Machine learning surveillance addresses EU AI Act model explainability requirements while accelerating regulatory reporting cycles. |
| Hybrid Cloud Architecture Expansion | Blended client-retained and managed service configurations capture hedge fund demand for configurability without full replacement. |
| Tokenized Asset Servicing Capability | Distributed ledger convergence with custody systems opens margin pools for digital-asset middle-office functions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with asset manager operations heads, hedge fund CFOs, private equity fund administrators, custody bank technology executives, and regulatory compliance officers. Secondary validation incorporated SEC investment adviser filings, FCA operational resilience guidance documents, MAS technology risk-management circulars, EBA outsourcing guidelines, and cloud infrastructure hyperscaler capex disclosures. Bottom-up contract value analysis and top-down market sizing triangulation anchored the analytical framework.
Calibration against historical vendor consolidation patterns and regulatory implementation timelines shaped the projection methodology across the analysis window. Segmentation dimensions modeled encompass service type, end user archetype, technology deployment model, and solution configuration. CAGRs were derived from trade volume elasticity assumptions and regulatory compliance spending intensity curves. AI penetration rates in compliance workflows and containerized platform adoption velocity served as industry-specific forecast inputs.
Stress conditions across cloud infrastructure pricing volatility, quantitative talent scarcity escalation, and cross-border data residency friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory deadline adherence and operational resilience certification diffusion. Cross-checking against custody bank earnings disclosures and asset manager vendor concentration metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Commodity Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Check Cashing Services Market
Financial Services
Global Automated Algo Trading Market
Financial Services
India Legal Services Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Foreign Exchange Services Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Trade Finance Market
Financial Services
Benefits Consulting Service Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
E-Brokerage Market
Financial Services
Germany E-Brokerage Market