
 Benefits Consulting Service Market | 2026-2036
Benefits Consulting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Benefits Consulting Service Market Insights
Mid-sized companies is bifurcating demand away from traditional large-corporation advisory relationships as these employers grapple with regulatory complexity without internal benefits expertise. Mercer leverages its actuarial depth and global broker network to anchor multi-country benefits harmonization programs. Willis Towers Watson competes through proprietary health analytics platforms that sustain pricing leverage in self-funded medical plan design. Aon dominates captive insurance consulting for employers seeking alternative risk financing for employee benefits.
Benefits consulting services encompass advisory engagements that design, administer, and optimize employer-sponsored health insurance, retirement savings vehicles, and ancillary welfare programs through actuarial modeling, regulatory compliance mapping, and vendor procurement management. These services functionally reduce employer cost exposure while ensuring statutory adherence across federal, state, and local benefit mandates. Health Benefits commands the largest revenue pool among service types due to persistent medical inflation and pharmacy benefit complexity, while Self-service Platforms represents the fastest-expanding delivery model as employers digitize enrollment and employee communications. Large Corporations remains the most mature client segment with saturated penetration, whereas Small Enterprises harbors underdeveloped advisory access and emerging insurtech partnership potential.
The US Department of Labor enforces ERISA fiduciary standards that mandate documented investment prudence for retirement plan sponsors, directly elevating demand for qualified plan consultant engagement. HIPAA privacy rules and IRS cafeteria plan regulations further compel employer investment in compliance-oriented advisory retainers. Stakeholders must monitor the convergence of artificial intelligence in benefits administration with evolving fiduciary liability frameworks to anticipate where advisory value shifts from transactional compliance to predictive workforce risk management.
Market Dynamics
Mid-sized employers are fragmenting advisory relationships across specialized boutiques rather than consolidating with full-service brokers, forcing incumbents to unbundle actuarial, compliance, and technology capabilities into modular service tiers.
Growth Catalysts
- ACA Employer Mandate Complexity:The US Affordable Care Act's reporting requirements for firms with 50-99 full-time equivalent employees generate retainer demand for Section 6056 compliance documentation and penalty risk assessment.
- Pharmacy Benefit Carve-Outs:Self-funded plan sponsors are disaggregating PBM contracts from medical carriers, creating procurement advisory work for specialty drug cost containment and rebate transparency negotiations.
- 401(k) Auto-Enrollment Thresholds:State-level retirement savings mandates in Illinois, California, and Oregon compel small employers without ERISA-exempt plans to seek fiduciary outsourcing and investment policy statement drafting.
Market Restraints
- Actuarial Talent Scarcity:Fellowship-track credentialed professionals command compensation premiums exceeding 40% above general consulting wages, compressing firm margins on fixed-fee compliance engagements.
- Carrier Consolidation:Horizontal mergers among national health insurers reduce the viable vendor panel for broker-mediated RFP processes, limiting price discovery leverage in fully insured markets.
- Fee Compression from Robo-Advisors:Automated 401(k) investment management platforms substitute algorithmic fund selection for human advisor relationships in retirement plan segments below $10 million in assets.
Strategic Opportunities
- Private Exchange Penetration:Active enrollment marketplaces for defined contribution health benefits remain underdeveloped among employers with 100-500 lives, offering first-mover positioning for technology-enabled advisory hybrids.
- Mental Health Parity Audits:The US Mental Health Parity and Addiction Equity Act's 2024 technical release creates forensic claims analysis demand to demonstrate quantitative treatment limitation compliance.
- Captive Insurance Structuring:Alternative risk financing for stop-loss layers and prescription drug liabilities attracts mid-market employers seeking premium stability outside conventional fully insured arrangements.
Industry Challenges
- Legacy System Integration:Employer HRIS platforms with decade-old data architectures resist API connectivity for real-time enrollment synchronization, forcing costly middleware development or manual reconciliation workflows.
- Fiduciary Litigation Exposure:ERISA class actions targeting excessive recordkeeping fees and underperforming target-date fund lineups expose consulting firms to co-fiduciary liability claims when investment monitoring protocols fail documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benefits Consulting Service Market |
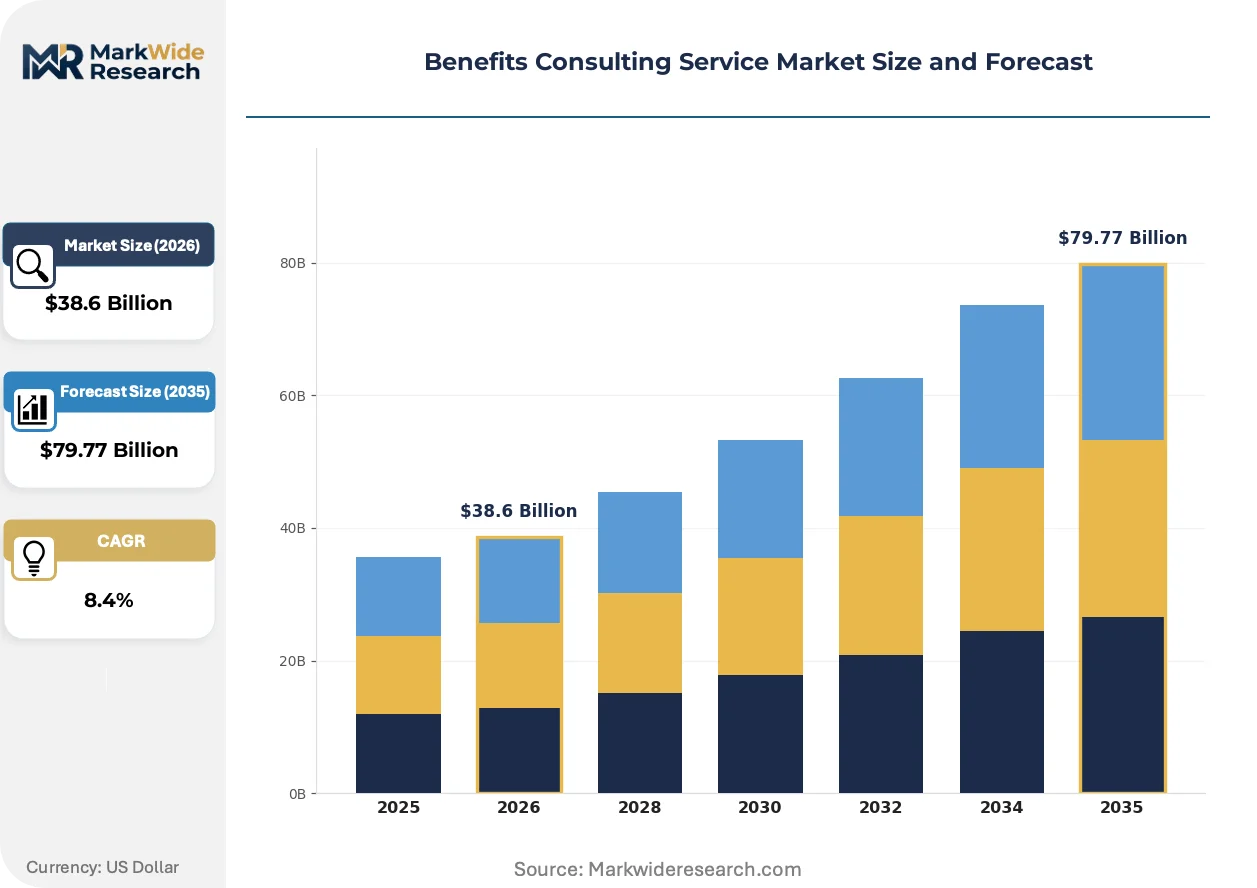
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Health Benefits, Retirement Planning, Wellness Programs, Disability Management, Employee Assistance Industry Vertical: Information Technology, Manufacturing, Education, Financial Services, Hospitality Client Type: Small Enterprises, Mid-sized Companies, Large Corporations, Nonprofit Organizations, Government Agencies Delivery Model: Onsite Consulting, Remote Advisory, Hybrid Service, Self-service Platforms, Third-party Partnerships |
| Companies Covered | Mercer, Willis Towers Watson, Aon, ADP, Arthur J. Gallagher & Co., Insperity, PwC, Deloitte, Lockton Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benefits Consulting Service Market Trends and Innovations
Artificial intelligence is compressing the advisory value chain from retrospective compliance reporting toward predictive workforce risk modeling, reallocating consultant hours from data aggregation to strategic intervention design.
Predictive analytics engines for medical cost forecasting is miniaturizing the historical reliance on annual actuarial valuation cycles into continuous claims monitoring dashboards. Self-funded employers with 500-2,000 covered lives are adopting these tools fastest, compressing the feedback loop between utilization pattern detection and plan design intervention from quarters to weeks.
The US Department of Labor's 2024 fiduciary investment advice regulation reinstates the five-part test for ERISA prohibited transaction exemptions, compelling broker-dealers to document fee reasonableness through independent benchmarking. Retirement plan consultants serving small-market 401(k) sponsors face the steepest compliance burden, with many restructuring compensation from commission-based to level-fee advisory models to avoid conflict-of-interest scrutiny.
Employer procurement of benefits advisory services is fragmenting across point solutions rather than bundled retainers. Mid-sized companies in the manufacturing vertical increasingly separate health benefits consulting from retirement plan advisory, engaging specialized boutiques for pharmacy benefit management while retaining generalist firms for ERISA compliance. Texas and Florida exhibit this unbundling pattern most acutely, where regional broker dominance has historically resisted national firm penetration.
Benefits Consulting Service Market Segmentation
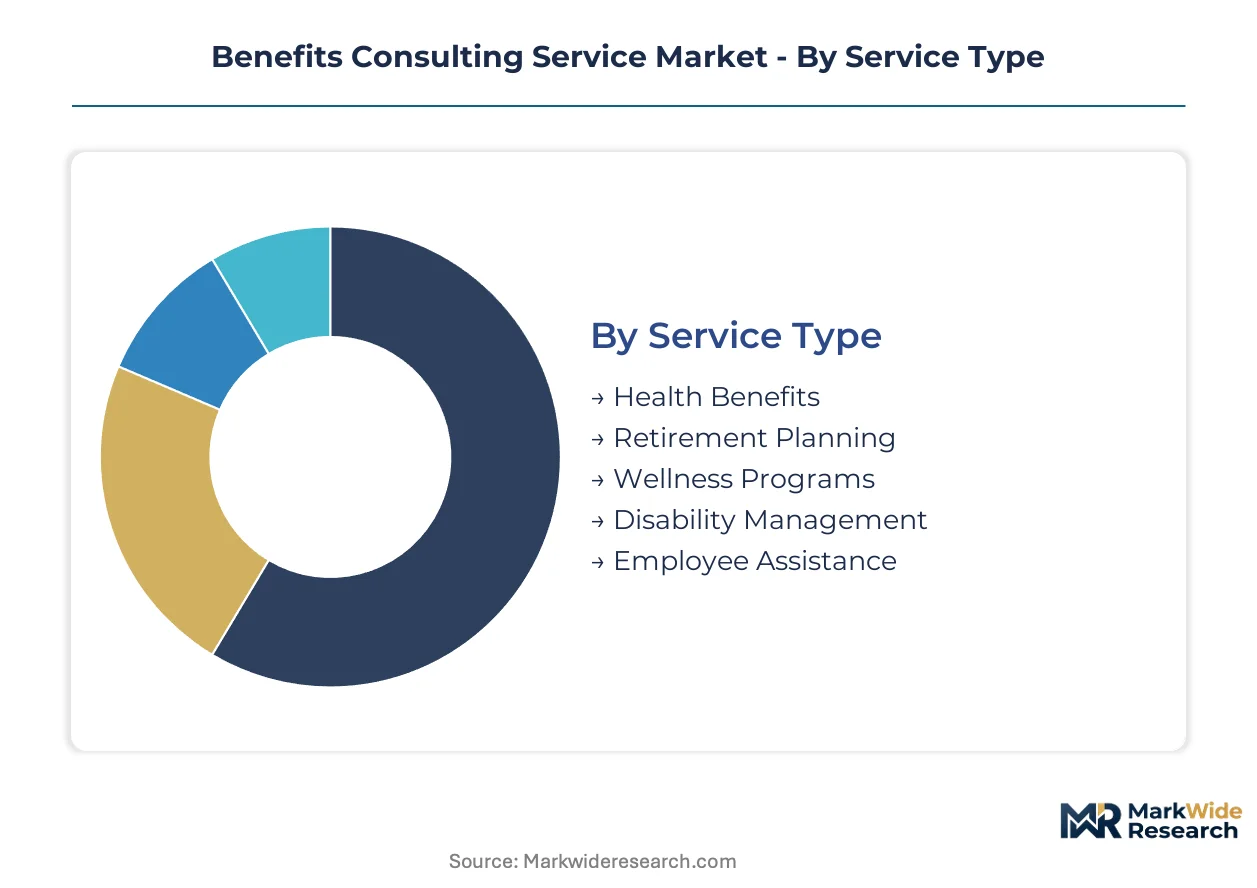
Benefits consulting services fragment across four distinct dimensions that shape how advisory firms structure pricing, deploy talent, and build technology platforms. Each segmentation axis reveals divergent margin profiles and competitive dynamics.
Service Type:
Advisory engagements flow through distinct channel architectures: actuarial-heavy services retain high-touch consulting relationships, while compliance-oriented offerings increasingly route through technology-enabled delivery.
- Health Benefits:Comprehensive medical, dental, and vision plan design supported by actuarial modeling and pharmacy benefit procurement. Demand concentrates among self-funded employers in the United States grappling with persistent medical inflation and specialty drug cost escalation.
- Retirement Planning:ERISA fiduciary advisory, investment policy statement drafting, and qualified plan design for defined contribution and defined benefit vehicles. State-level retirement mandates in Illinois, California, and Oregon are accelerating small-employer adoption of outsourced fiduciary services.
- Wellness Programs:Biometric screening, health risk assessment, and incentive design for population health management.
- Disability Management:Short-term and long-term disability plan structuring, claims advocacy, and return-to-work program design.
- Employee Assistance:Mental health counseling access, work-life balance resources, and crisis intervention hotlines.
By volume, Health Benefits leads. By growth pace, Retirement Planning is ahead.
Industry Vertical:
Cost tier differentiation separates technology-intensive advisory from labor-intensive compliance work across employer categories.
- Information Technology:Equity compensation integration, global mobility benefits, and competitive benchmarking for talent acquisition. Silicon Valley and Seattle tech clusters drive premium advisory spend on executive benefits and international assignment services.
- Manufacturing:Union negotiation support, multi-site benefits harmonization, and captive insurance feasibility for self-funded medical plans. Rust Belt and Gulf Coast manufacturing corridors exhibit acute demand for pharmacy benefit carve-out advisory.
- Education:Public sector retirement system navigation, TIAA-CREF plan optimization, and student loan repayment benefit design.
- Financial Services:Regulatory compliance for broker-dealer compensation, deferred compensation structuring, and fiduciary governance for bank-owned life insurance arrangements.
- Hospitality:High-turnover enrollment administration, tipped-employee benefit eligibility, and seasonal workforce coverage strategies.
By advisory spend per employee, Information Technology leads. By expansion trajectory, Manufacturing is accelerating fastest.
Client Type:
Customer maturity determines service packaging: sophisticated buyers unbundle capabilities while emerging segments require integrated solutions.
- Small Enterprises:Employers with fewer than 50 full-time equivalents seeking ACA compliance documentation and state-mandated retirement plan facilitation. Texas and Florida small businesses increasingly fragment advisory relationships across specialized boutiques rather than consolidating with full-service brokers.
- Mid-sized Companies:Firms with 50-999 employees representing the fastest-expanding client archetype as regulatory complexity outpaces internal HR capacity. These employers generate concentrated demand for Section 6056 reporting and pharmacy benefit management advisory.
- Large Corporations:Mature buyers with saturated advisory penetration and established multi-year broker relationships.
- Nonprofit Organizations:Mission-driven employers navigating unrelated business income tax implications and religious exemption considerations for contraceptive coverage.
- Government Agencies:Public sector entities managing civil service retirement systems and multi-jurisdictional employee benefit harmonization.
By revenue concentration, Large Corporations leads. By growth velocity, Mid-sized Companies is expanding most quickly.
Delivery Model:
Supply concentration among technology platforms is reshaping how advisory services reach end employers.
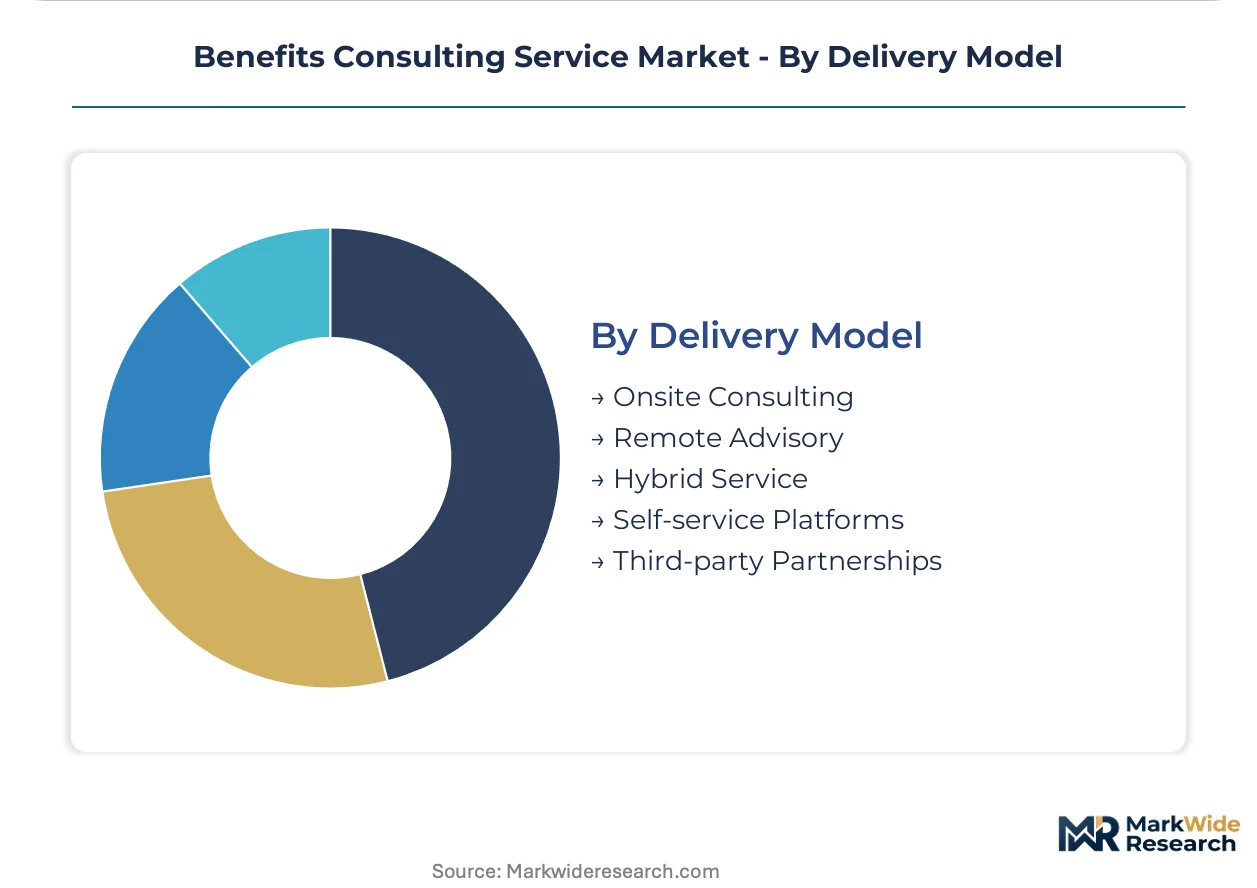
- Onsite Consulting:Embedded advisor presence for open enrollment administration, employee education sessions, and claims dispute resolution. Unionized manufacturing and public sector employers in the Midwest and Northeast retain this high-touch model for collective bargaining support.
- Remote Advisory:Virtual consultant engagement for plan design, vendor RFP management, and compliance documentation. Geographic dispersion of remote workforces post-pandemic has normalized this delivery mode for technology and professional services employers.
- Hybrid Service:Blended in-person and digital delivery combining quarterly onsite reviews with continuous remote support.
- Self-service Platforms:Technology-enabled enrollment, decision support tools, and employee communication portals. This delivery mode is gaining share fastest among mid-sized employers digitizing benefits administration.
- Third-party Partnerships:White-label advisory embedded within payroll platforms, PEO arrangements, and industry association purchasing cooperatives.
By deployment scale, Hybrid Service leads. By adoption velocity, Self-service Platforms is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border advisory flows from United States-based firms into Canadian and Mexican employer markets intensify as NAFTA-era benefits harmonization gives way to USMCA-mandated compliance documentation for multinational workforces.
United States
Employers with 50-99 full-time equivalent employees drive retainer demand for Section 6056 ACA reporting compliance. The US Department of Labor enforces ERISA fiduciary standards that mandate documented investment prudence for retirement plan sponsors. Silicon Valley and Seattle tech clusters generate premium advisory spend on executive benefits and international assignment services.
Canada
Provincial health system gaps create private supplementary benefits procurement demand among mid-sized employers. Health Canada regulates drug pricing through the Patented Medicine Prices Review Board, influencing pharmacy benefit management advisory scope. Toronto and Vancouver financial services corridors exhibit concentrated demand for pension plan de-risking and liability-driven investment strategies.
Germany
Works council consultation requirements for benefit changes sustain high-touch advisory relationships in industrial sectors. The German Federal Financial Supervisory Authority oversees occupational pension vehicles under the Occupational Pensions Act. Bavaria and Baden-Württemberg manufacturing clusters generate captive insurance feasibility studies for employee benefit risk financing.
United Kingdom
Defined benefit pension scheme buyout activity accelerates demand for liability-driven investment advisory and longevity risk transfer. The Pensions Regulator enforces funding standards and employer covenant assessments for occupational schemes. London and Southeast England financial services employers drive spend on global mobility benefits and equity compensation integration.
Japan
Aging workforce demographics elevate demand for retirement plan design and phased retirement program structuring. The Ministry of Health, Labour and Welfare administers Employees' Pension Insurance and health insurance society regulations. Tokyo and Osaka metropolitan employers invest in defined contribution plan advisory as corporate pension fund deficits persist.
Benefits Consulting Service Market Competitive Landscape
Player mix skews toward diversified professional services networks with actuarial depth and global broker infrastructure. Market structure concentrates among three global brokers commanding multi-country benefits harmonization relationships, with mid-tier boutiques fragmenting share in specialized niches. Strategic archetypes include actuarial-heavy full-service brokers, technology-enabled advisory hybrids, and compliance-focused boutique specialists. Competitive moves center on unbundling service tiers for mid-sized employers and embedding predictive analytics platforms into traditional consulting relationships.
Within the full-service broker tier, Mercer and Willis Towers Watson occupy positions anchored by proprietary health analytics and global network infrastructure. Aon exemplifies the alternative risk financing specialist archetype through captive insurance consulting capabilities. Among technology-enabled providers, ADP represents the payroll-platform-embedded advisory model that automates enrollment administration and compliance documentation for small and mid-sized employer segments.
| Leading Market Players |
|---|
| Mercer |
| Willis Towers Watson |
| Aon |
| ADP |
| Arthur J. Gallagher & Co. |
| Insperity |
| PwC |
| Deloitte |
| Lockton Companies |
| Others |
Pricing and Supply Chain Analysis
Platform substitution of legacy broker networks with API-enabled advisory tools redraws supply geography toward cloud infrastructure hubs while compressing per-engagement pricing economics. This displacement simultaneously elevates talent costs for actuarial-heavy services and deflates commoditized compliance documentation fees.
Pricing Analysis
Legacy actuarial consulting commands premium retainers against emerging self-service platform tiers and nascent AI-augmented advisory hybrids. Price differentiation rests on credential density and proprietary data asset access, with fellowship-track actuaries justifying substantial fee premiums over generalist consultants. Cost compression in compliance documentation intensifies as automated enrollment tools substitute algorithmic workflows for hourly advisory labor. Small enterprises exhibit acute price sensitivity, while large corporations with captive risk financing needs demonstrate inelastic demand for specialized captive insurance structuring.
Supply Chain Analysis
Inbound logistics costs for technology infrastructure components—server hardware, cybersecurity middleware, and API connectivity modules—fluctuate with container availability across Pacific trade lanes. Supply concentrates in the United States for actuarial talent and proprietary health analytics platforms, in India for back-office compliance processing, and in Ireland for EU data residency requirements. Raw material dependencies include cloud compute capacity, cybersecurity certification frameworks, and regulatory compliance databases. Single-source vulnerability permeates the actuarial fellowship pipeline, where credential production limits service expansion velocity. Distribution runs through direct enterprise sales forces for large accounts and embedded payroll platform partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The benefits consulting service market sits at an AI disruption inflection where predictive analytics engines compress traditional actuarial valuation cycles from quarters to weeks. This technological shift fragments incumbent pricing power while opening white-space for technology-native entrants.
For Market Incumbents: Consolidate proprietary health analytics capabilities through targeted capability acquisition in pharmacy benefit management forecasting. Deepen vertical integration into cloud-based enrollment infrastructure to defend margin position against payroll-platform-embedded competitors. The threat of robo-advisor substitution in sub-$10 million retirement plan segments demands immediate compensation model restructuring from commission-based to level-fee advisory frameworks.
For New Entrants and Emerging Players: ERISA fiduciary certification fast-tracks unlock immediate advisory legitimacy for technology-enabled hybrids targeting small-enterprise state-mandated retirement plan compliance. The most penetrable segment comprises Texas and Florida small businesses with fragmented boutique relationships and unmet ACA Section 6056 documentation needs. A direct digital acquisition model bypassing traditional broker channels captures price-sensitive employers seeking modular compliance services.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-embedded advisory hybrids with scalable technology infrastructure. Long-term viability across a five-to-ten-year window hinges on predictive analytics integration and regulatory technology automation. Acquisition targets should demonstrate captive insurance structuring expertise or pharmacy benefit carve-out advisory depth. The signal to watch is Department of Labor enforcement intensity around ERISA fiduciary investment advice regulations, which accelerates outsourcing demand when penalty exposure escalates.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Predictive Analytics Deployment | Compresses actuarial valuation cycles from quarterly to continuous monitoring for self-funded employers. |
| Pharmacy Benefit Management Specialization | Captures carve-out advisory demand as employers disaggregate PBM contracts from medical carriers. |
| ERISA Fiduciary Compliance Technology | Automates documentation standards for Section 6056 reporting and investment policy statement drafting. |
| Captive Insurance Structuring Capability | Enables alternative risk financing for mid-market employers seeking premium stability outside conventional markets. |
| Payroll Platform Partnership Integration | Embeds advisory services within ADP and similar workflows for automated small-enterprise enrollment administration. |
Research Methodology
A spread of perspectives from benefits consulting partners, ERISA compliance officers, pharmacy benefit managers, and HR technology procurement leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings of publicly traded advisory firms, Department of Labor enforcement action databases, and state insurance commissioner regulatory filings. Bottom-up employer spend estimates triangulated against top-down service provider revenue segmentation across the analysis window.
Segmentation dimensions modeled include service type taxonomy, client size archetype, delivery model infrastructure, and industry vertical specialization. CAGRs were derived from historical trajectory analysis and regulatory inflection impact assessment. Forecast inputs incorporated ACA employer mandate phase-in schedules, state-level retirement savings mandate adoption curves, and actuarial talent pipeline constraints.
Underlying assumptions cover steady regulatory enforcement intensity and moderate healthcare cost inflation, with deviation risk concentrated in ERISA litigation volume spikes and carrier consolidation acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Commercial Debt Collection Software Market
Financial Services
South Korea Financial Services Software Market
Financial Services
Reconciliation Software Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Online Lottery Market
Financial Services
Spain E-Brokerage Market
Financial Services
Source to Pay Market
Financial Services
India Security Brokerage Market
Financial Services
Direct Selling Market
Financial Services
North America B2C Legal Services Market
Financial Services
North America B2B Legal Services Market
Financial Services
Canada Credit Cards Market
Financial Services
Online Investment Platform Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Global Temporary Labor Market
Financial Services
Banking Cloud Services Market