
 Qatar Analysis of Key Sectors and Investment Opportunities Market | 2026-2036
Qatar Analysis of Key Sectors and Investment Opportunities Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Analysis of Key Sectors and Investment Opportunities Market Insights
Digital twin infrastructure is reconfiguring how investors model risk and returns across Qatar's project pipeline. QatarEnergy leverages upstream hydrocarbon revenues to anchor downstream industrial investments. Qatari Diar Real Estate Investment Company specializes in master-planned communities that integrate residential, retail, and transit access.
The Qatar Analysis of Key Sectors and Investment Opportunities encompasses structured capital allocation across energy, construction, healthcare, and tourism verticals, governed by project finance frameworks, concession agreements, and sovereign development mandates that prioritize long-dated yield stability over speculative returns. Investment type segmentation reveals foreign direct investment dominating hydrocarbon-linked industrial projects, while public-private partnerships control transport and utility infrastructure where government retains strategic oversight. Market segment analysis shows renewable energy and infrastructure development commanding the deepest capital pools, with medical services and hospitality positioned as secondary growth corridors tied to population expansion and visitor economy targets.
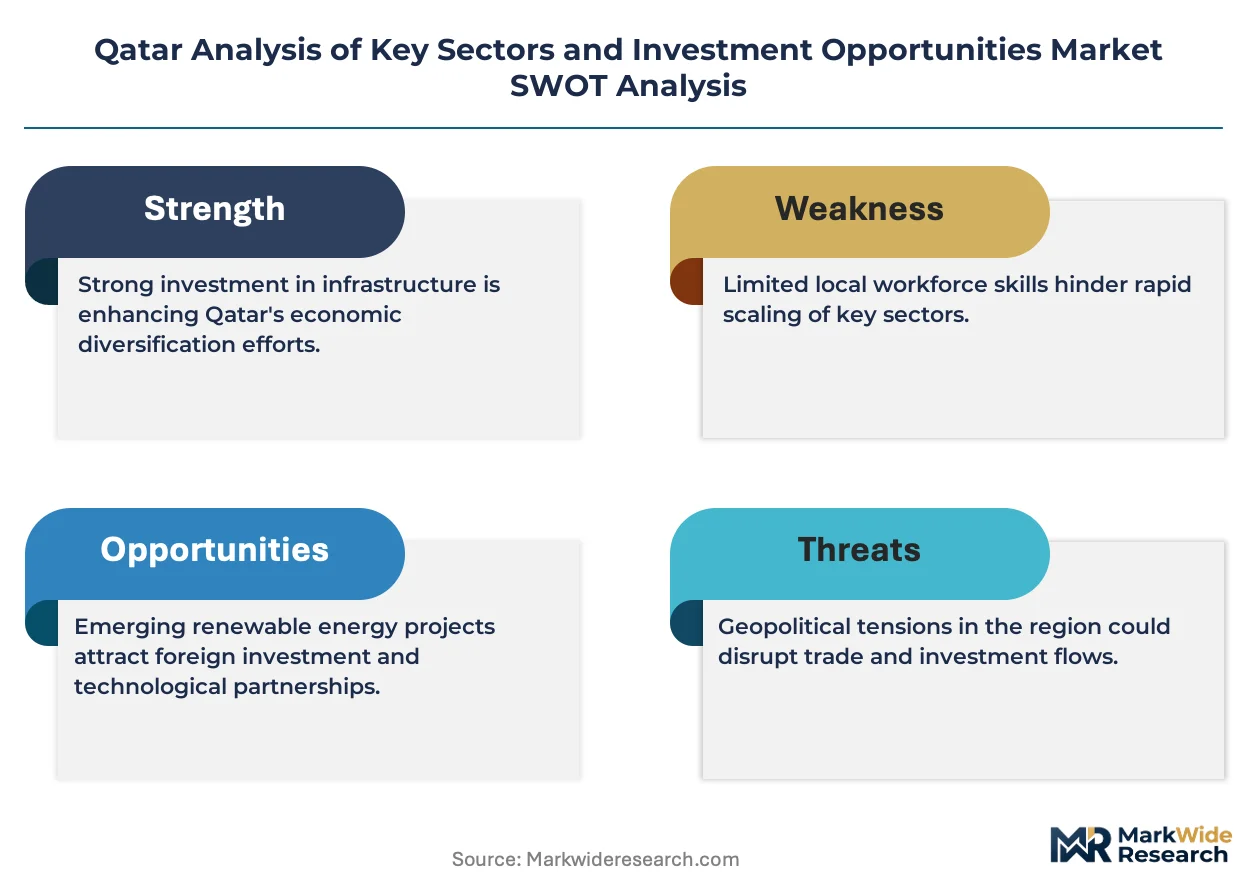
Qatar Central Bank prudential regulations and Qatar Financial Centre Authority governance standards shape fund structuring and cross-border capital mobility for institutional investors. The Qatar Stock Exchange disclosure requirements and Ministry of Commerce and Industry foreign ownership rules determine market access thresholds for non-GCC participants. Stakeholders must monitor how QatarEnergy's LNG expansion capex schedule and Qatar Rail network completion timelines alter sectoral priority rankings in sovereign planning documents.
Market Dynamics
Qatar National Vision 2030 is compressing project timelines across energy, transport, and healthcare assets, forcing capital allocators to synchronize sovereign mandates with institutional yield requirements.
Growth Catalysts
- Digital twin platforms:Real-time infrastructure modeling reduces due diligence cycles for rail-linked commercial zones in Lusail. Asset managers deploy these tools to stress-test concession cash flows before commitment.
- Qatar Central Bank prudential regulations:Fund structuring rules attract long-tenor institutional capital into project finance vehicles. Sovereign credit enhancement lowers hurdle rates for foreign participants.
- Downstream industrialization:QatarEnergy anchors petrochemical and LNG-linked manufacturing clusters. Hydrocarbon revenues feed captive demand for specialized construction and logistics services.
Market Restraints
- Specialized contractor scarcity:Limited local capacity for smart city integration creates bottleneck risk. Doha and Lusail compete for the same engineering pools.
- Foreign ownership thresholds:Ministry of Commerce and Industry caps constrain non-GCC control in strategic sectors. Joint venture structures add governance complexity.
- Steel and cement input volatility:Regional supply disruptions transmit directly to project economics. Fixed-price EPC contracts carry margin erosion exposure.
Strategic Opportunities
- Healthcare infrastructure gap:Medical services capacity lags population expansion targets. Greenfield hospital developments attract concession-based investment.
- Qatar Financial Centre Authority governance standards:Regulatory clarity enables Sharia-compliant fund domiciliation. Islamic finance structures unlock GCC and Malaysian capital sources.
- AI-enabled asset management:Machine learning converges with IoT sensor networks in commercial real estate. Predictive maintenance contracts create recurring revenue streams.
Industry Challenges
- Digital engineering talent deficit:BIM and digital twin expertise concentrates with international contractors. Knowledge transfer requirements strain local training capacity.
- Multi-stakeholder coordination complexity:Qatar Rail network completion dependencies cascade through mixed-use development schedules. Misaligned timelines trigger penalty clauses.
- Qatar Stock Exchange disclosure compliance:Listed vehicle reporting standards extend fundraising timelines. Private placement structures bypass this friction but limit liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Analysis of Key Sectors and Investment Opportunities Market |
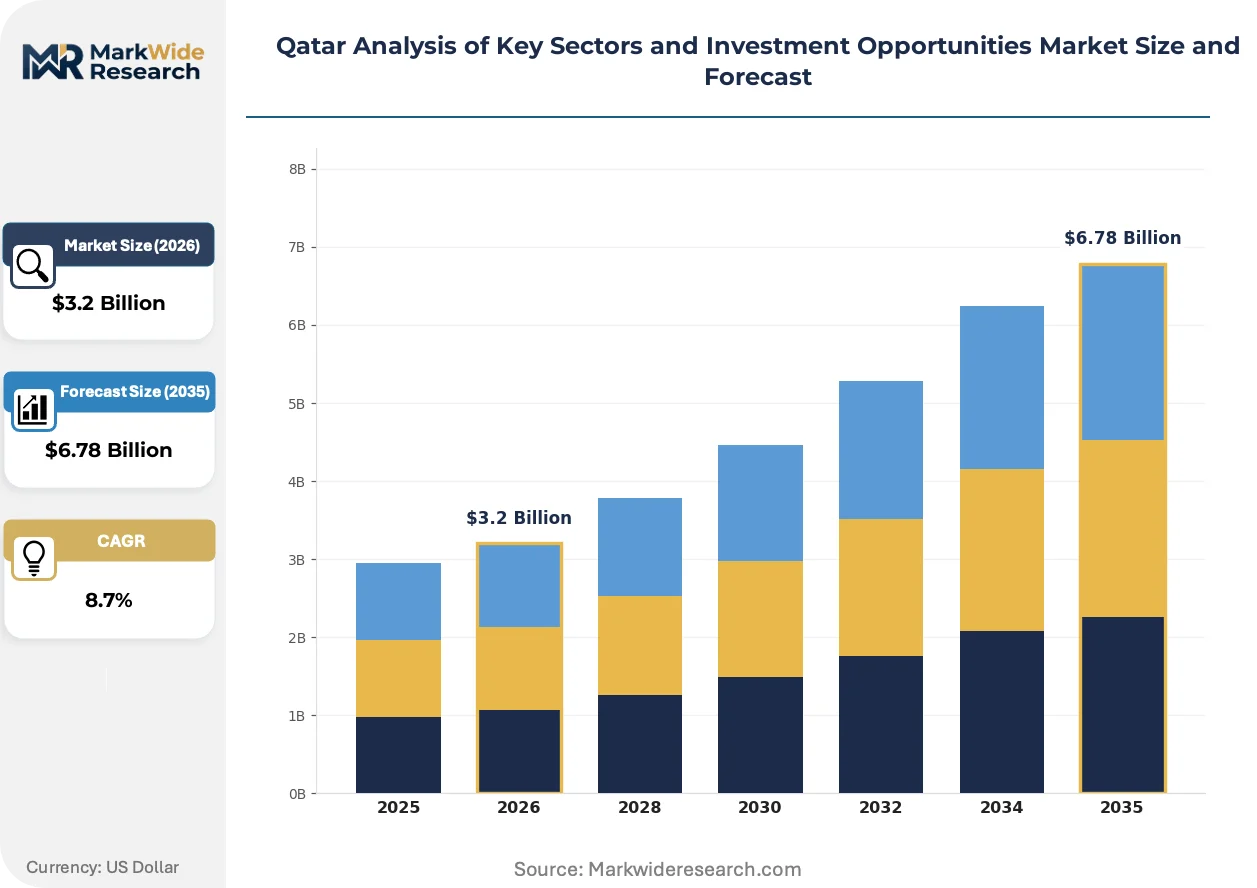
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Energy, Construction, Healthcare, Tourism Investment Type: Foreign Direct Investment, Public-Private Partnership, Venture Capital, Real Estate Market Segment: Renewable Energy, Infrastructure Development, Medical Services, Hospitality Funding Stage: Seed, Growth, Expansion, Mature |
| Companies Covered | Qatar Investment Authority, QatarEnergy, Qatar National Bank, Qatar Airways Group, Ooredoo Q.P.S.C., Qatari Diar Real Estate Investment Company, Qatar Rail, Barwa Real Estate Group, Qatar Development Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Analysis of Key Sectors and Investment Opportunities Market Trends and Innovations
Capital deployment patterns in Qatar are reorganizing around data-centric due diligence tools and sovereign-mandated sustainability criteria that reshape how investors evaluate long-dated infrastructure positions.
Digital twin infrastructure is collapsing traditional risk assessment timelines across Qatar's project pipeline. Sovereign wealth funds and institutional allocators now simulate construction delays, revenue shortfalls, and regulatory changes before final investment decisions. Lusail's mixed-use developments serve as the primary testing ground for these platforms.
Qatar Financial Centre Authority governance standards are tightening disclosure requirements for cross-border fund structures. Asset managers must document beneficial ownership and environmental compliance before market access approval. Foreign participants are restructuring as Qatar-domiciled vehicles to satisfy these mandates.
Institutional procurement of infrastructure exposure is fragmenting away from concentrated sovereign mandates toward specialized sector funds. Pension allocators and family offices now bypass generalist development vehicles in favor of healthcare or renewable energy-specific pools. Doha-based fund administrators report accelerating subscription timelines for these targeted structures.
Qatar Analysis of Key Sectors and Investment Opportunities Market Segmentation
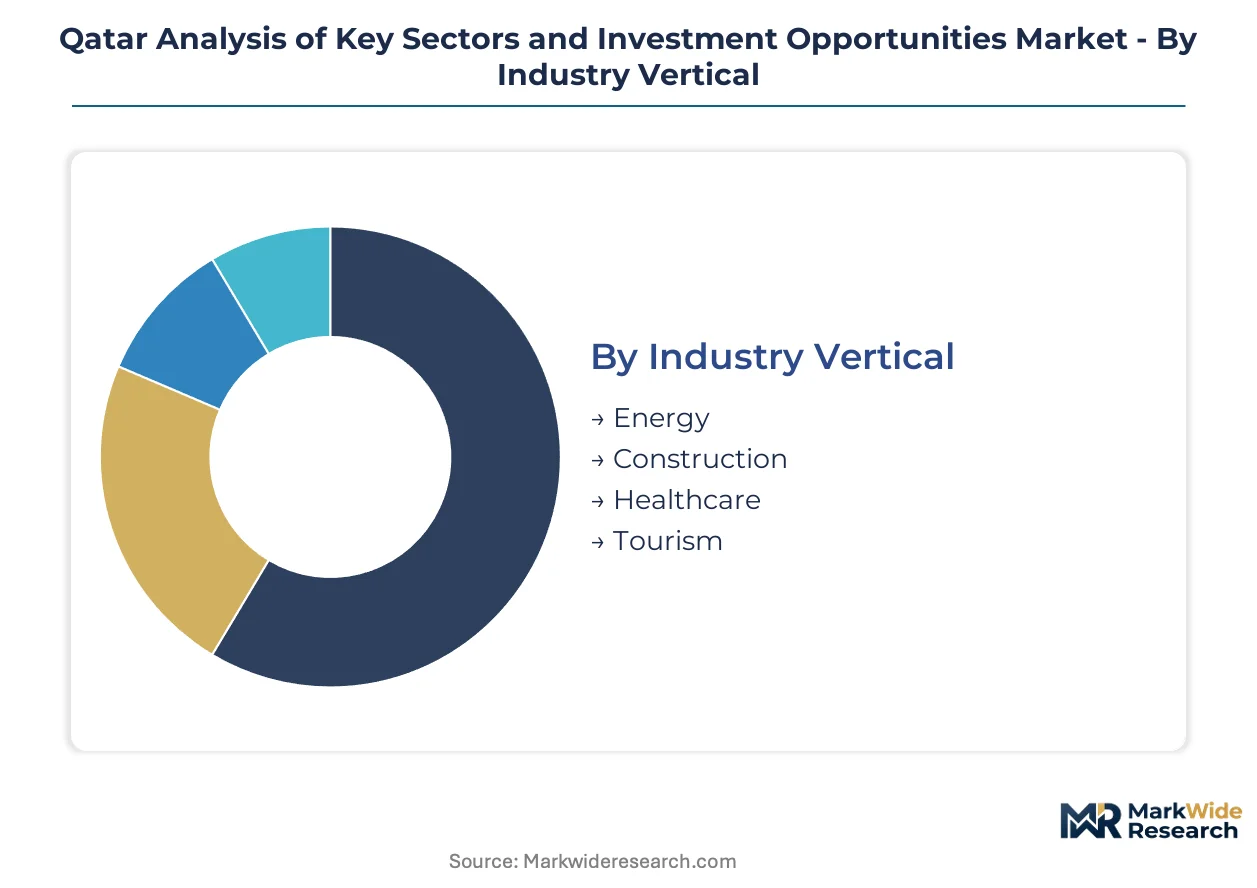
Segmentation in Qatar's investment landscape reveals how sovereign mandates, capital source constraints, and project maturity requirements partition deployable capital across discrete risk-return profiles. Investors must align vehicle structures with Qatar National Vision 2030 priority sequencing to secure allocation.
Industry Vertical:
After-sales service intensity varies sharply across verticals, with construction and healthcare demanding sustained operational support while energy investments front-load technical commissioning.
- Energy:QatarEnergy anchors LNG expansion and downstream petrochemical clusters. Hydrocarbon-linked industrial projects attract foreign direct investment through concession frameworks with sovereign credit enhancement.
- Construction:Smart city integration and digital twin deployment dominate Doha and Lusail developments. Specialized contractor scarcity creates bottleneck risk for rail-linked commercial zones.
- Healthcare:Greenfield hospital developments address capacity gaps against population expansion targets. Medical services attract concession-based investment with long-dated yield stability.
- Tourism:Hospitality assets tie to visitor economy targets under sovereign development mandates. Mixed-use developments integrate retail and transit access to capture institutional commitment.
Energy holds the largest share; momentum sits with healthcare infrastructure.
Investment Type:
Capital source determines governance complexity and return horizon, with sovereign-mandated vehicles favoring stability over speculative upside.
- Foreign Direct Investment:Hydrocarbon-linked industrial projects dominate FDI flows. QatarEnergy's LNG expansion capex schedule synchronizes with foreign capital deployment timelines.
- Public-Private Partnership:Transport and utility infrastructure retain government strategic oversight. Qatar Rail network completion dependencies cascade through mixed-use development schedules.
- Venture Capital:AI-enabled asset management and digital twin platforms attract early-stage capital. Machine learning converges with IoT sensor networks in commercial real estate applications.
- Real Estate:Master-planned communities integrate residential, retail, and transit access. Qatari Diar specializes in developments that concentrate institutional commitment in Doha and Lusail.
Public-private partnerships command the deepest capital pools; venture capital is expanding most quickly in proptech applications.
Market Segment:
Project pipeline priority rankings in sovereign planning documents concentrate capital deployment toward infrastructure and energy transition assets.
- Renewable Energy:Solar and hydrogen-linked manufacturing clusters feed captive demand from QatarEnergy's industrialization strategy. Downstream investments anchor specialized construction and logistics services procurement.
- Infrastructure Development:Digital twin platforms compress risk assessment timelines across transport and utility assets. Lusail serves as the primary testing ground for real-time infrastructure modeling.
- Medical Services:Hospital capacity expansion lags population growth targets. Greenfield developments attract concession-based structures with recurring revenue streams.
- Hospitality:Visitor economy targets drive mixed-use asset integration. Rail-linked commercial zones in Doha compete for the same engineering pools as Lusail developments.
Infrastructure development holds the largest share; renewable energy is gaining share fastest on QatarEnergy's decarbonization timeline.
Funding Stage:
Project maturity requirements in sovereign mandates compress timelines, forcing capital allocators to synchronize seed and growth commitments with institutional yield hurdles.
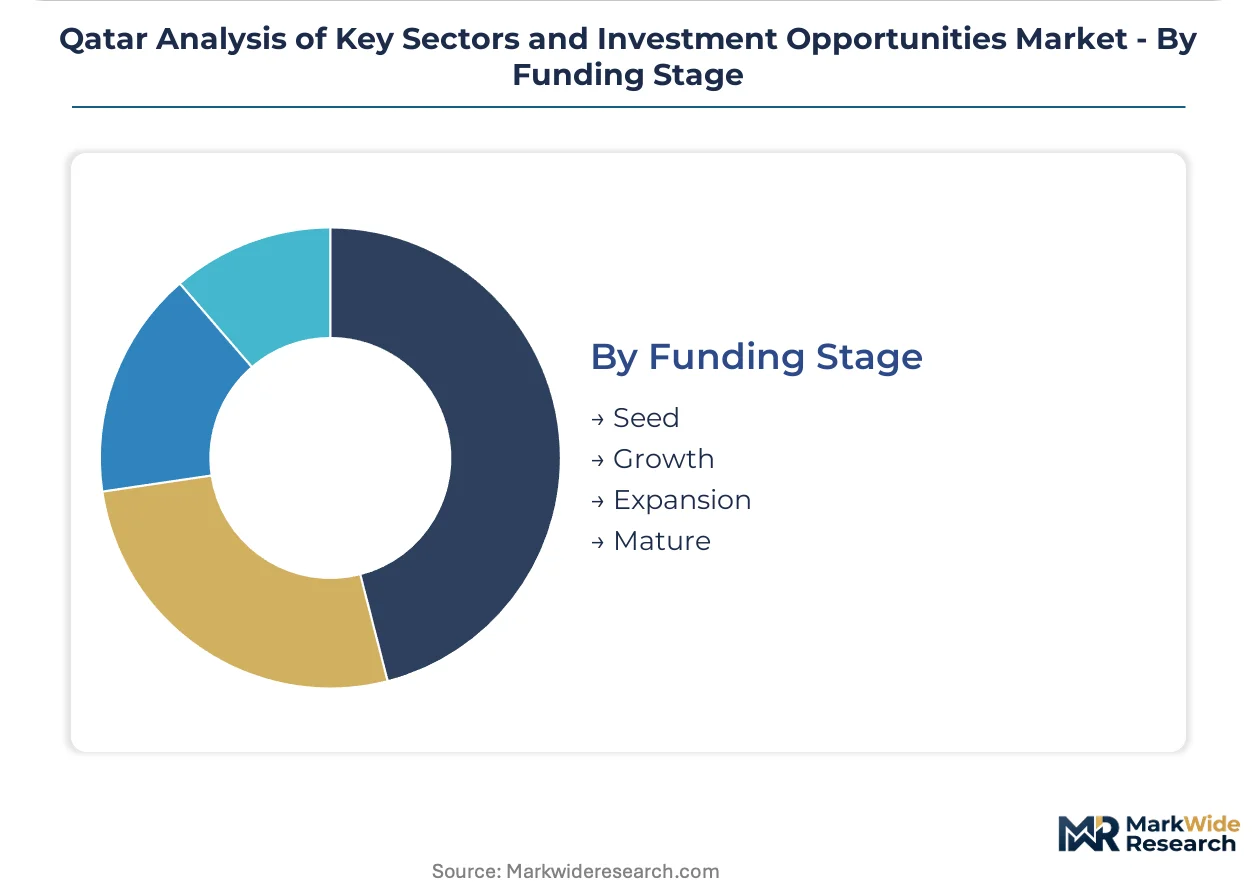
- Seed:Digital twin and AI-enabled asset management platforms attract early capital. Qatar Financial Centre Authority governance standards enable Sharia-compliant fund domiciliation for GCC and Malaysian sources.
- Growth:Smart city technologies and IoT sensor networks scale through predictive maintenance contracts. Recurring revenue streams appeal to pension allocators and family offices.
- Expansion:Healthcare infrastructure and renewable energy assets reach operational scale. Concession agreements with long-dated yield stability attract institutional commitment.
- Mature:Hydrocarbon-linked industrial and hospitality assets generate stabilized cash flows. Qatar Stock Exchange disclosure requirements extend fundraising timelines for listed vehicles.
Expansion-stage assets hold the largest share; seed-stage proptech ventures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's investment landscape operates as a net capital exporter, with sovereign wealth deployment exceeding inbound foreign direct investment flows. Hydrocarbon revenues generate surplus liquidity that Qatar Investment Authority channels into overseas acquisitions while domestic project finance attracts Gulf and Asian institutional capital.
Doha Metropolitan Area
Commercial real estate and financial services concentrate in the capital district. Qatar Central Bank prudential regulations govern fund structuring for cross-border capital mobility. The Qatar Financial Centre hosts asset managers deploying digital twin platforms for infrastructure risk modeling across Lusail-linked developments.
Lusail City
Mixed-use developments and rail-linked commercial zones anchor institutional commitment here. Qatar Rail network completion timelines cascade through project schedules with penalty clause exposure. Smart city integration creates specialized contractor scarcity as developments compete for engineering pools.
Al Wakrah and Industrial Corridor
Downstream petrochemical clusters feed QatarEnergy's LNG-linked manufacturing strategy. The Ministry of Commerce and Industry foreign ownership caps shape joint venture structures in strategic sectors. Captive demand for construction and logistics services anchors procurement from Doha-based contractors.
Education City and Healthcare Zone
Medical services capacity expansion lags population growth targets in this corridor. Greenfield hospital developments attract concession-based investment with long-dated yield stability. Qatar Development Bank credit enhancement lowers hurdle rates for foreign participants in healthcare infrastructure.
Pearl-Qatar and Hospitality Cluster
Visitor economy targets drive mixed-use asset integration along the waterfront. Qatari Diar Real Estate Investment Company master-planned communities concentrate institutional commitment. Hospitality assets compete with Lusail developments for the same engineering and project management capacity.
Qatar Analysis of Key Sectors and Investment Opportunities Market Competitive Landscape
On the supply side, the industry is bifurcated between sovereign-mandated development vehicles and specialized private operators. Qatar Investment Authority and QatarEnergy anchor the sovereign tier with hydrocarbon-linked capital deployment. Three archetypes dominate: state-owned enterprises controlling strategic infrastructure, real estate investment companies executing master-planned communities, and financial institutions structuring project finance vehicles. Competitive moves center on concession agreement positioning and cross-border partnership formation for technology transfer.
Among state-owned development vehicles, QatarEnergy exemplifies upstream-to-downstream integration archetypes, while Qatari Diar Real Estate Investment Company occupies a position within master-planned community specialists. Qatar National Bank represents the financial structuring tier that channels institutional capital into sovereign-mandated projects.
| Leading Market Players |
|---|
| Qatar Investment Authority |
| QatarEnergy |
| Qatar National Bank |
| Qatar Airways Group |
| Ooredoo Q.P.S.C. |
| Qatari Diar Real Estate Investment Company |
| Qatar Rail |
| Barwa Real Estate Group |
| Qatar Development Bank |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in specialized digital engineering talent across Doha and Lusail compresses contractor availability while simultaneously elevating pricing power for international firms with BIM and digital twin expertise. Qatar Central Bank prudential regulations and Qatar Financial Centre Authority governance standards layer compliance costs onto fund structuring, transmitting fee pressure to institutional investors seeking project finance exposure.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across Qatar's infrastructure development pipeline. Three-tier pricing stratification separates premium concession agreements with sovereign credit enhancement from standard joint venture structures and economy-tier fixed-price EPC contracts exposed to steel and cement input volatility. Price differentiation rests on certification level—Qatar Stock Exchange disclosure compliance versus private placement exemptions—and volume scale of QatarEnergy-linked industrial clusters. Cost compression in fixed-price EPC tiers is intensifying because regional supply disruptions for construction inputs transmit directly to margin erosion. State-owned enterprises and sovereign wealth funds exhibit lowest price sensitivity due to long-dated yield mandates, while mid-sized foreign contractors face acute pressure on hurdle rates.
Supply Chain Analysis
Upstream hydrocarbon feedstock from QatarEnergy's LNG expansion anchors captive demand for specialized construction and logistics services procurement. Geographic supply concentration draws engineering talent from India, the Philippines, and South Korea, while steel and cement inputs source from regional producers in Saudi Arabia, the UAE, and Oman. Single-source vulnerability concentrates in digital twin platform providers and BIM software licensors concentrated with international contractors. Distribution runs through Qatar-domiciled fund administrators and project finance vehicles structured under Qatar Financial Centre Authority standards, with Qatar Development Bank credit enhancement lowering access friction for foreign participants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware deployment across Qatar's investment landscape, with predictive maintenance contracts and AI-enabled asset management platforms generating recurring revenue streams that outpace traditional construction and energy asset yields.
For Market Incumbents: Build regulatory moats through Qatar Financial Centre Authority governance certification and Qatar Central Bank fund structuring licensure to defend against emerging fintech entrants and regional fund administrators. Deepen backward integration into digital twin platform development to reduce reliance on international contractors with concentrated BIM expertise. Prioritize capacity addition in Lusail's rail-linked commercial zones before Qatar Rail network completion triggers penalty clause exposure across competing developments.
For New Entrants and Emerging Players: Build out white-space presence in healthcare infrastructure concession agreements where medical services capacity lags population expansion targets. Target seed-stage proptech ventures deploying AI-enabled asset management and IoT sensor networks for commercial real estate applications. Penetrate through Qatar Development Bank credit-enhanced structures that lower hurdle rates for foreign participants in greenfield hospital developments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across renewable energy and downstream industrialization sub-segments as QatarEnergy's decarbonization timeline accelerates solar and hydrogen-linked manufacturing cluster deployment. Long-term viability across the analysis window favors expansion-stage assets with operational scale and concession-based yield stability over mature hydrocarbon-linked industrial positions. Acquisition targets should exhibit Qatar-domiciled fund structures with Sharia-compliant domiciliation for GCC and Malaysian capital access. Monitor QatarEnergy's LNG expansion capex schedule as the primary inflection signal for sectoral priority rebalancing in sovereign planning documents.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Agreement Positioning | Secures long-dated yield stability with sovereign credit enhancement from Qatar Development Bank. |
| Digital Twin Platform Deployment | Compresses due diligence cycles for Lusail mixed-use developments and rail-linked commercial zones. |
| Sharia-Compliant Fund Domiciliation | Unlocks GCC and Malaysian capital sources through Qatar Financial Centre Authority governance standards. |
| Backward Integration into Construction Inputs | Mitigates steel and cement price volatility exposure in fixed-price EPC contracts. |
| Healthcare Infrastructure Concession | Captures recurring revenue streams from greenfield hospital developments serving population expansion targets. |
Research Methodology
Initial hypotheses were tested against primary input from sovereign wealth fund allocators, project finance vehicle managers, EPC contractors, and Qatar Financial Centre Authority compliance officers and refined through secondary validation. Primary fieldwork combined structured interviews with QatarEnergy procurement leads, Qatar Rail network planners, and healthcare infrastructure developers with documentary analysis of Qatar Central Bank prudential regulations and Qatar Stock Exchange disclosure requirements. Secondary sources encompassed sovereign development mandate documents, concession agreement frameworks, and Qatar National Vision 2030 priority sequencing publications. Bottom-up project pipeline assessment and top-down capital flow analysis were triangulated to reconcile deployment timelines with institutional yield requirements.
Demand-supply balance modeling anchored forecast construction across the projection horizon. Segmentation dimensions encompassed industry vertical, investment type, market segment, and funding stage, with additional granularity applied to QatarEnergy capex schedule synchronization and Qatar Rail network completion dependencies. CAGRs were derived through slope analysis of capital deployment trajectories against sovereign mandate timelines. Industry-specific forecast inputs included hydrocarbon revenue allocation patterns and digital twin platform adoption curves in Lusail development schedules.
Sensitivities concentrate around QatarEnergy's LNG expansion timeline revisions, Qatar Rail network completion delays cascading through mixed-use development schedules, and Qatar Central Bank prudential regulation modifications affecting fund structuring costs. Forecasts embed assumptions regarding sovereign credit enhancement continuity and foreign ownership threshold stability under Ministry of Commerce and Industry oversight. Cross-checking against Qatar Investment Authority overseas deployment disclosures and Qatar Stock Exchange listed vehicle filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Virtual Account Management Software Market
Financial Services
India Payroll Services Market
Financial Services
India Legal Services Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Australia Online Gambling Market
Financial Services
Digital Transformation in BFSI Market
Financial Services
E-Invoicing Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Liquidation Service Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Multivendor ATM Software Market
Financial Services
Global Treasury Software Market
Financial Services
Europe Factoring Services Market
Financial Services
ATM Software Market
Financial Services
North America B2C Legal Services Market
Financial Services
India Trade Finance Market