
 Middle East and Africa Private Equity Fund Market | 2026-2036
Middle East and Africa Private Equity Fund Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Private Equity Fund Market Insights
Gulf sovereign capital deployment into African technology corridors is realigning LP-GP dynamics across the Middle East and Africa Private Equity Fund Market. Investcorp leverages its Bahrain headquarters to anchor cross-border buyout flows between the Gulf and North Africa. Actis sustains competitive positioning through specialized energy transition mandates in Egypt and Kenya. Helios Investment Partners dominates sub-Saharan growth capital allocation with dedicated local presence in Lagos and Nairobi.
A private equity fund constitutes a pooled investment vehicle structured as a limited partnership, collecting capital commitments from institutional and accredited investors to acquire equity stakes in privately held companies across specified geographies and sectors, with capital deployment typically occurring over a defined investment period and returns realized through controlled exits. The fund's commercial purpose centers on generating absolute returns through operational value creation, financial engineering, and multiple expansion in target portfolio companies. Buyout strategies currently command the deepest LP commitment pools across the Middle East and Africa region, while venture capital segments register the fastest deployment velocity into fintech and health-tech verticals. Mid-sized funds between two hundred and five hundred million dollars capture disproportionate attention from regional family offices seeking concentrated manager relationships without mega-fund fee drag.
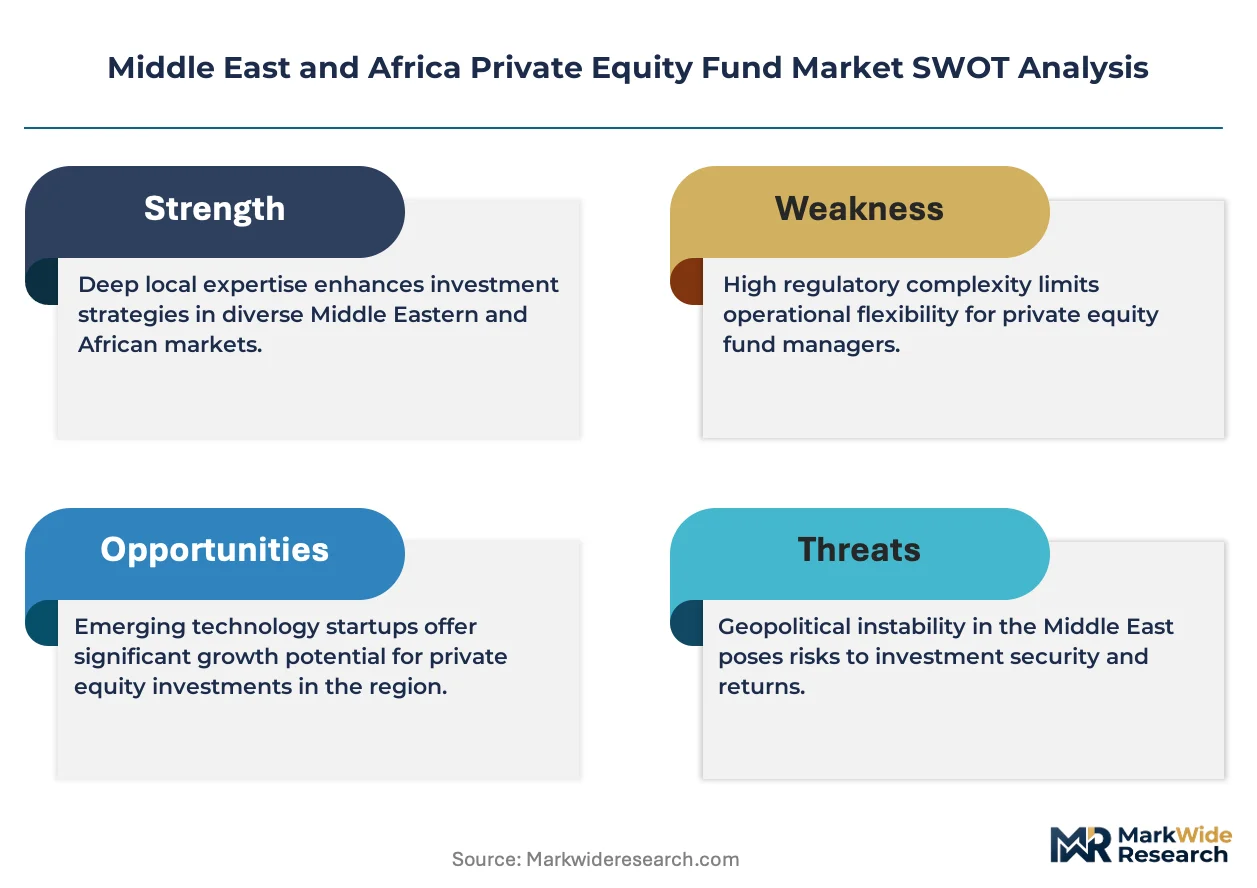
The Dubai Financial Services Authority and the Financial Sector Conduct Authority of South Africa impose divergent disclosure and investor protection standards that shape fund domiciliation decisions across the region. The UAE's Securities and Commodities Authority has introduced qualified investor frameworks that reduce retail exposure while streamlining institutional capital formation. Nigeria's Securities and Exchange Commission continues refining private fund registration requirements to attract offshore LP capital. Stakeholders must monitor how regulatory arbitrage between Dubai International Financial Centre and Casablanca Finance City evolves as competing fund domiciliation hubs.
Market Dynamics
Sovereign wealth funds from the Gulf Cooperation Council are redirecting capital deployment toward African technology corridors, compressing traditional LP-GP timelines and forcing fund managers to establish localized operational infrastructure ahead of capital calls.
Growth Catalysts
- UAE Regulatory Sandbox:The Securities and Commodities Authority's qualified investor framework accelerates fund registration timelines while reducing retail exposure, streamlining institutional capital formation for alternative investment vehicles.
- Healthcare Infrastructure Privatization:South African provincial governments are tendering hospital management concessions, concentrating demand for mid-sized buyout funds with specialized operational capabilities.
- Fintech Penetration:Mobile money interoperability protocols across East Africa are creating venture-scale exit pathways for payment infrastructure investments, pulling growth capital into Nigeria and Kenya.
Market Restraints
- Currency Convertibility Risk:Egyptian pound volatility and Nigerian naira liquidity constraints impose hedging costs that erode IRR targets for USD-denominated fund structures.
- Local Banking Concentration:Syndicated acquisition financing depends on a narrow consortium of pan-African lenders, amplifying refinancing risk during credit cycle contractions.
- Valuation Methodology Fragmentation:Absence of standardized comparable transaction databases across the region complicates LP reporting and secondary market pricing.
Strategic Opportunities
- Morocco Fund Domiciliation:Casablanca Finance City's emerging regulatory framework offers an alternative hub to Dubai International Financial Centre, with preferential double-taxation treaties across Francophone West Africa.
- Energy Transition Mandates:Egypt's feed-in tariff revisions and Kenya's geothermal expansion programs create dedicated allocation pools for climate-focused private equity strategies.
- Secondaries Market Development:Limited partner liquidity needs are generating transaction flow for NAV-based continuation vehicles, particularly among Gulf family office portfolios seeking duration management.
Industry Challenges
- Local Operating Partner Scarcity:Experienced C-suite executives with cross-border M&A integration expertise command premium compensation packages that strain management fee economics.
- Sharia Compliance Complexity:Structuring musharaka and mudaraba arrangements for Islamic LP capital requires specialized legal documentation that extends closing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Private Equity Fund Market |
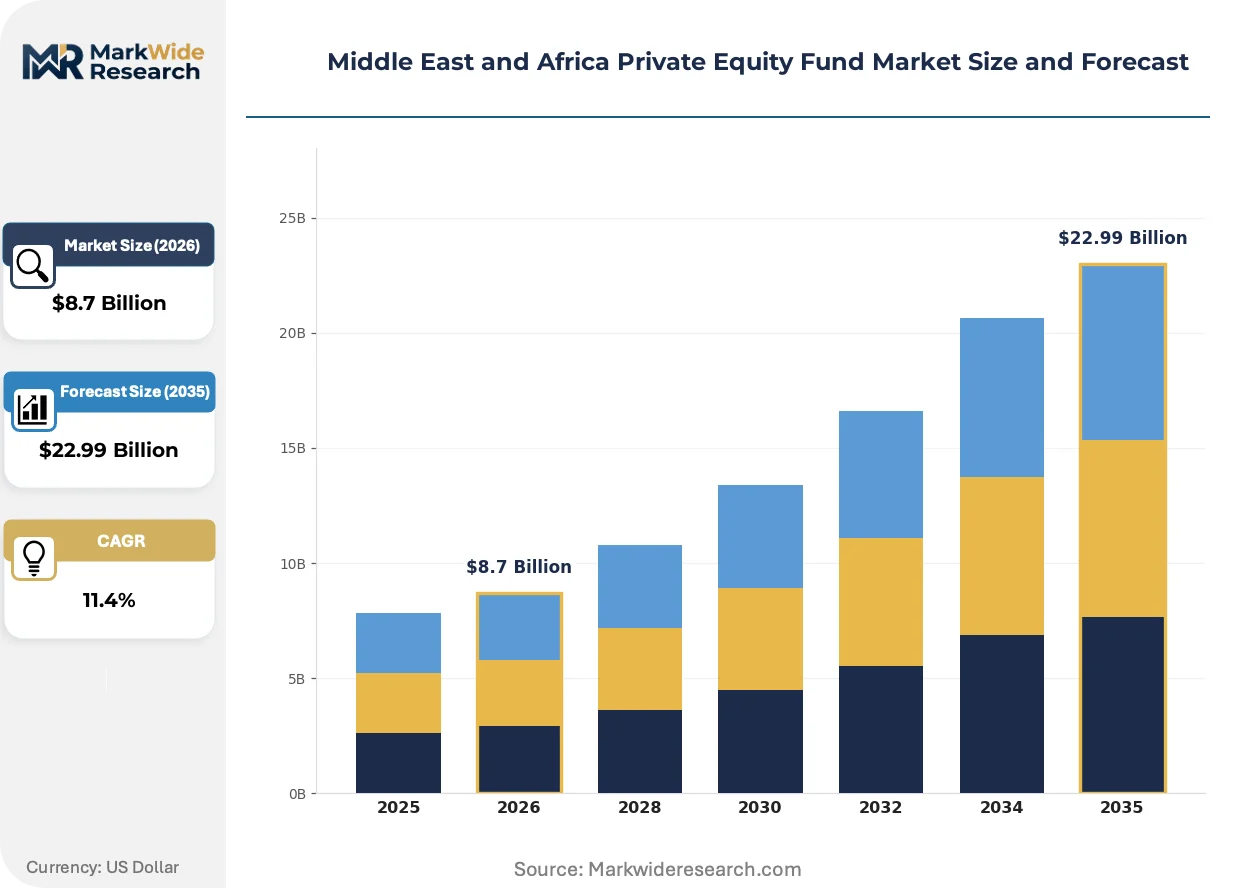
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Buyout, Growth Capital, Venture Capital, Mezzanine Fund Size: Small Fund, Mid-sized Fund, Large Fund, Mega Fund Asset Class: Equity, Debt, Mixed Assets, Real Estate Investor Type: Institutional Investors, High Net Worth Individuals, Family Offices, Corporates |
| Companies Covered | Investcorp, Actis, AfricInvest, Gulf Capital, EFG Hermes PE, Helios Investment Partners, Development Partners International, Qalaa Holdings, Amethis Finance, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Private Equity Fund Market Trends and Innovations
Digital infrastructure is compressing due diligence cycles and enabling direct sourcing models that bypass traditional intermediary networks across the Middle East and Africa private equity landscape.
Artificial intelligence-driven portfolio monitoring platforms are automating operational KPI tracking and early warning detection for value erosion. Mid-market buyout funds with Egyptian and Nigerian manufacturing exposures are deploying these systems to reduce on-site management bandwidth requirements. The technology is automating routine variance analysis and freeing operating partners to focus on strategic intervention design.
South Africa's Financial Sector Conduct Authority has introduced enhanced disclosure requirements for alternative investment funds marketing to retirement schemes, elevating transparency standards for fee reporting and co-investment rights. The regulation is forcing fund administrators to upgrade data infrastructure and renegotiate prime brokerage arrangements. Private equity vehicles with significant pension fund LP bases are restructuring side letter provisions to preempt compliance friction.
Family offices across the Gulf are consolidating manager relationships and shifting from fund-of-funds structures toward direct co-investment platforms with preferred economic terms. This concentration is displacing traditional fund placement agents and compressing fundraising timelines for established GPs with track records in the region. The behavior shift is most visible in Abu Dhabi and Riyadh, where single-family investment vehicles now represent the fastest-growing LP category for growth equity strategies.
Middle East and Africa Private Equity Fund Market Segmentation
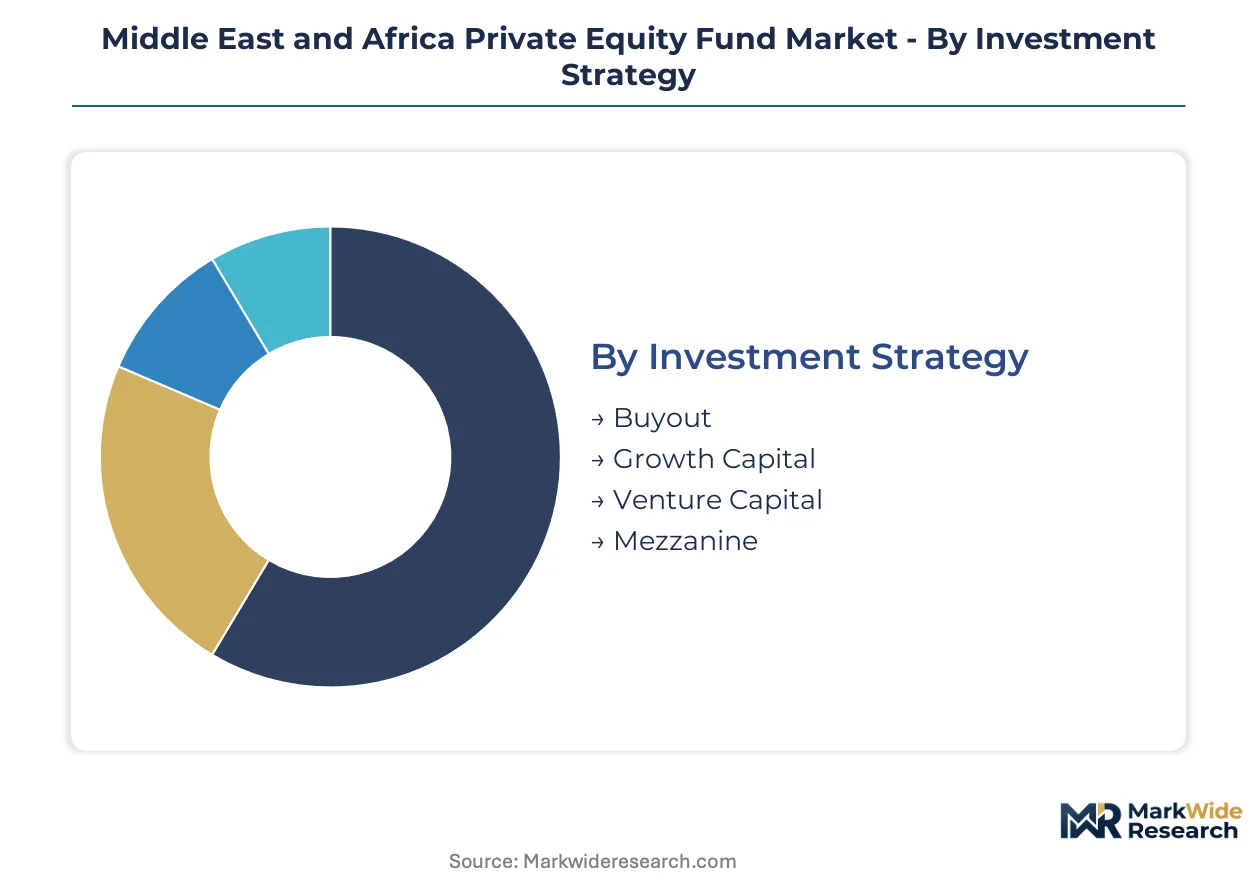
Investment strategy and fund size configurations determine capital access and fee structures across Middle East and Africa private equity. Institutional LP mandates and regulatory thresholds further constrain manager positioning within each segment category.
Investment Strategy:
LP risk-return preferences and liquidity horizons drive strategy selection, with sovereign wealth funds prioritizing control-oriented approaches while development finance institutions favor earlier-stage exposure.
- Buyout:Majority-stake acquisitions of established enterprises with proven cash flows. South African healthcare infrastructure privatizations and Egyptian manufacturing consolidation are concentrating capital deployment here, though currency hedging costs compress net returns.
- Growth Capital:Minority investments in expansion-stage companies requiring operational scaling without full ownership transfer. Nigerian fintech and Kenyan agribusiness ventures are pulling regional family office allocations toward this segment as exit timelines shorten.
- Venture Capital:Seed through Series C financing for technology-enabled business models. Mobile money interoperability across East Africa is creating viable exit pathways for payment infrastructure bets.
- Mezzanine:Subordinated debt with equity participation rights, filling capital structure gaps in leveraged transactions. South African syndicated lending concentration limits deployment scale.
Volume sits with Buyout; growth tilts toward Venture Capital.
Fund Size:
Management fee economics and investment team bandwidth dictate optimal fund scale, with regional family offices avoiding mega-fund fee drag while demanding sufficient diversification.
- Small Fund:Vehicles below two hundred million dollars targeting niche sector or geographic specializations. Lagos and Nairobi-based managers dominate sub-Saharan growth capital with localized sourcing networks.
- Mid-sized Fund:Two hundred to five hundred million dollar structures balancing concentration risk with operational flexibility. South African healthcare buyouts and Egyptian energy transition mandates are concentrating LP demand here.
- Large Fund:Five hundred million to one billion dollar vehicles requiring multi-country deployment to absorb capital. Casablanca Finance City and Dubai International Financial Centre registrations are competing for this category.
- Mega Fund:Structures exceeding one billion dollars, predominantly Gulf sovereign-backed vehicles with cross-regional mandates. Actis and Investcorp anchor this tier with dedicated Africa strategies.
Capital formation clusters at Mid-sized Fund; expansion is steepest among Small Fund specialists.
Asset Class:
Sharia compliance requirements and local banking market depth influence asset class mix, with Islamic LP capital demanding specialized structuring expertise.
- Equity:Common and preferred shareholdings with full upside participation. Egyptian pound volatility and Nigerian naira liquidity constraints impose hedging costs on USD-denominated structures.
- Debt:Senior and subordinated lending with fixed income characteristics. Pan-African lender concentration amplifies refinancing risk during credit contractions.
- Mixed Assets:Hybrid structures combining equity upside with debt downside protection. UAE regulatory sandbox frameworks are streamlining registration for these vehicles.
- Real Estate:Direct property ownership and development platforms. Saudi sovereign wealth deployment into logistics and data center infrastructure is expanding this segment.
Deployment weight rests with Equity; Real Estate is gaining share fastest on infrastructure privatization.
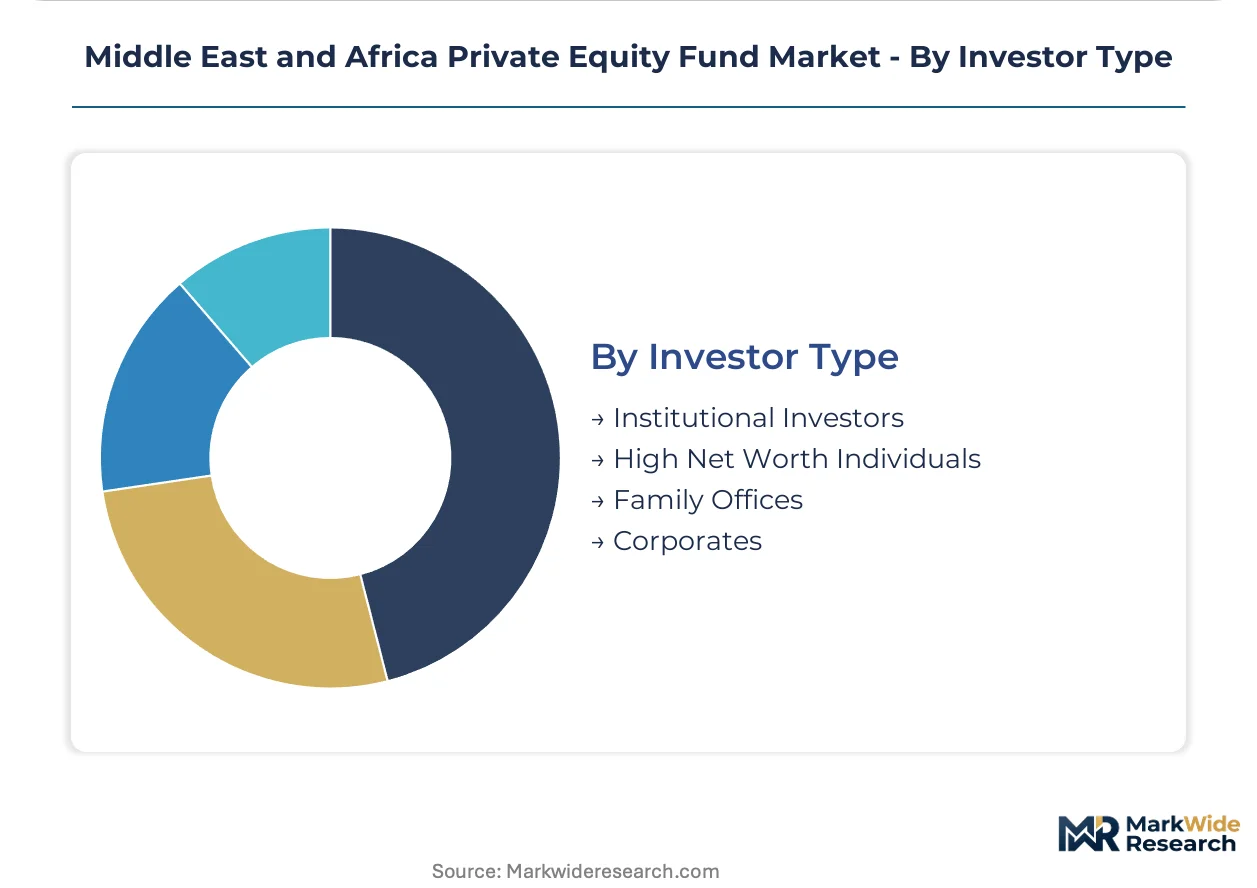
Investor Type:
LP governance structures and liquidity requirements shape fund terms, with direct co-investment rights becoming standard for concentrated relationships.
- Institutional Investors:Pension funds, insurance companies, and endowments with stringent fiduciary standards. South Africa's Financial Sector Conduct Authority disclosure requirements are elevating fee transparency mandates.
- High Net Worth Individuals:Accredited private investors seeking diversification through fund commitments. UAE qualified investor frameworks restrict retail access while streamlining institutional pathways.
- Family Offices:Single and multi-family investment vehicles with flexible mandates and long duration preferences. Abu Dhabi and Riyadh-based offices are displacing traditional fund-of-funds structures with direct platforms.
- Corporates:Strategic balance sheet deployment for sector-specific exposure and ecosystem development. Gulf sovereign wealth funds are increasingly channeling capital through captive corporate vehicles.
Commitment volume concentrates with Institutional Investors; Family Offices are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign capital pools anchored in Abu Dhabi and Riyadh supply the foundational liquidity for private equity deployment across the Middle East and Africa corridor. Fund domiciliation decisions increasingly hinge on regulatory arbitrage between Dubai International Financial Centre and Casablanca Finance City.
United Arab Emirates
Dubai's healthcare infrastructure privatization and fintech licensing reforms are concentrating LP demand for mid-sized buyout vehicles. The Dubai Financial Services Authority's qualified investor framework accelerates fund registration timelines while restricting retail participation. Abu Dhabi Global Market anchors the region's largest sovereign wealth deployment platforms.
Saudi Arabia
Vision 2030 diversification mandates are channeling Public Investment Fund capital into Egyptian manufacturing and Nigerian technology corridors. The Capital Market Authority's alternative investment fund regulations streamline foreign GP market access. Riyadh-based family offices are displacing traditional fund-of-funds structures with direct co-investment platforms.
South Africa
Provincial hospital management concessions and renewable energy procurement programs are concentrating demand for operational buyout specialists. The Financial Sector Conduct Authority's enhanced disclosure requirements for retirement scheme investments elevate fee transparency mandates. Johannesburg anchors sub-Saharan Africa's deepest syndicated lending markets.
Egypt
Feed-in tariff revisions for solar and wind projects are creating dedicated allocation pools for climate-focused strategies. The Financial Regulatory Authority's private fund registration refinements aim to attract offshore LP capital. Cairo's manufacturing consolidation opportunities are pulling Gulf sovereign capital into control-oriented transactions.
Nigeria
Mobile money interoperability protocols and health-tech platform scaling are shortening venture capital exit timelines. The Securities and Exchange Commission continues refining private fund registration to reduce offshore capital friction. Lagos anchors West Africa's densest growth capital sourcing networks.
Middle East and Africa Private Equity Fund Market Competitive Landscape
Global majors compete with regional champions across fund size categories and sector specialization dimensions. The market structure concentrates around three tiers: Gulf sovereign-backed mega-funds with cross-regional mandates, mid-sized specialists with localized operational infrastructure, and niche players targeting single-country deployment. Dominant competitive moves include regulatory arbitrage between domiciliation hubs and direct co-investment platform construction to bypass traditional LP-GP fee structures.
Within the cross-regional buyout tier, Investcorp leverages its Bahrain headquarters to anchor Gulf-North Africa transaction flows, while Actis sustains positioning through specialized energy transition mandates. Helios Investment Partners occupies a dominant position in sub-Saharan growth capital through dedicated Lagos and Nairobi presence. These three exemplify the archetype of scale-driven regional specialists competing against global emerging market platforms.
| Leading Market Players |
|---|
| Investcorp |
| Actis |
| AfricInvest |
| Gulf Capital |
| EFG Hermes PE |
| Helios Investment Partners |
| Development Partners International |
| Qalaa Holdings |
| Amethis Finance |
| Others |
Pricing and Supply Chain Analysis
LP commitment fee benchmarks and carried-interest hurdle rates cascade through fund economics, compressing management fee margins for sub-scale managers while amplifying pricing power for established GPs with proven Africa track records. This cost structure differentiation stratifies the market into premium, standard, and emerging manager tiers based on fund size thresholds and operational infrastructure depth.
Pricing Analysis
Management fee unbundling from operational overlay services is reshaping LP-GP negotiations across the Middle East and Africa corridor. Three-tier pricing structure across premium, standard, and economy levels reflects fund size segmentation, with mega-funds commanding two-percent management fees and twenty-percent carried interest against mid-sized vehicles at one-point-five percent and fifteen percent. Pricing pressure stems from Gulf family office consolidation into direct co-investment platforms that bypass traditional fund-of-funds fee layers. Emerging managers with sub-two-hundred-million-dollar vehicles face acute price sensitivity as institutional LPs demand fee discounts for first-time relationships.
Supply Chain Analysis
DFSA and FSCA regulatory certifications gate access to fund domiciliation infrastructure, with only qualified administrators and prime brokers cleared to service institutional capital pools. Supply concentration centers on the United Arab Emirates, South Africa, and Morocco as competing hub jurisdictions, each drawing from specialized legal, audit, and custody service ecosystems. Raw material dependencies include Sharia advisory capacity, local operating partner networks, and syndicated lending consortium relationships. Single-source vulnerability runs through pan-African lender concentration for acquisition financing. Distribution runs through placement agent networks, direct sovereign relationships, and emerging secondaries market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa private equity fund market is consolidating around scale-driven specialists, with currency hedging cost compression forcing sub-scale managers toward subordination or exit. Regulatory arbitrage between Dubai and Casablanca is accelerating this Darwinian selection.
For Market Incumbents: Cement dominance through captive Sharia structuring capabilities and dedicated local operating partner platforms in Lagos and Nairobi. Threat vectors include Gulf sovereign direct-deployment models that disintermediate traditional GP relationships. Priority levers center on vertical integration into portfolio company value-creation functions and regulatory sandbox pre-approval in multiple domiciliation hubs. For New Entrants and Emerging Players: The UAE Securities and Commodities Authority qualified investor framework opens a window for specialized fintech and health-tech growth capital vehicles targeting Egyptian and Nigerian technology corridors. Most penetrable white-space sits in sub-two-hundred-million-dollar funds with dedicated sector theses and localized sourcing networks. Go-to-market positioning should anchor on co-investment rights and preferential fee structures for concentrated family office relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor operational turnaround specialists with Egyptian manufacturing or South African healthcare infrastructure exposure. Long-term viability across the analysis window hinges on demonstrated value-creation track records rather than financial engineering alone. Acquisition target archetype combines mid-sized fund scale with dedicated local presence and sector specialization depth. Signal to watch is secondary market transaction flow for NAV-based continuation vehicles as Gulf family offices seek duration management.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Pre-Approval | DFSCA and FSCA clearances accelerate capital formation timelines for alternative investment vehicles. |
| Local Operating Partner Platform Buildout | Dedicated Lagos and Nairobi infrastructure compresses due diligence cycles and sourcing bandwidth. |
| Sharia Structuring Capability Integration | Captive musharaka and mudaraba expertise unlocks Gulf sovereign wealth deployment pools. |
| Secondaries Market Vehicle Construction | NAV-based continuation funds address Gulf family office liquidity management requirements. |
| Direct Co-Investment Platform Launch | Abu Dhabi and Riyadh single-family vehicles displace traditional fund-of-funds intermediation. |
Research Methodology
Independent corroboration across fund administrator filings, regulatory disclosure databases, and LP commitment records underwrites the qualitative findings in this study. Primary interviews with fund general partners, limited partner advisory committees, regulatory affairs officers at DFSA and FSCA, and prime brokerage relationship managers combined with secondary validation from securities filings, fund performance databases, and sovereign wealth disclosure reports. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical fundraising cycles and deployment velocity patterns shaped the projection framework across the analysis window. Segmentation dimensions modeled include investment strategy, fund size tier, asset class configuration, and investor type governance structure. CAGRs were derived from regression analysis against macroeconomic indicators, regulatory policy trajectories, and capital formation pipeline visibility. Forecast inputs incorporate currency convertibility risk premiums, local banking market depth indices, and exit pathway maturity assessments for fintech and health-tech verticals.
The model assumes a particular technology adoption path; alternative pathways for AI-driven portfolio monitoring platforms would alter the outlook for operating partner bandwidth requirements and management fee economics. Forecasts reflect assumptions regarding regulatory sandbox expansion, sovereign wealth mandate continuity, and mobile money interoperability protocol standardization. A model refresh is warranted upon material change in Egyptian pound or Nigerian naira convertibility regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
US Hedge Fund Market
Investment Analysis and Financial Strategies
United Kingdom Parametric Insurance Market
Investment Analysis and Financial Strategies
Asia-Pacific Fintech Market
Investment Analysis and Financial Strategies
Europe BFSI Biometrics Market
Investment Analysis and Financial Strategies
Canada Accounting Software Market
Investment Analysis and Financial Strategies
North America Fintech Cloud Market
Investment Analysis and Financial Strategies
Transaction Monitoring Software Market
Investment Analysis and Financial Strategies
Internet of Things (IoT) in Banking Market
Investment Analysis and Financial Strategies
Revenue Assurance Market
Investment Analysis and Financial Strategies
Spain Online Trading Platform Market
Investment Analysis and Financial Strategies
Canada Mortgage/Loan Brokers Market
Investment Analysis and Financial Strategies
Family Office Services Market
Investment Analysis and Financial Strategies
Remittance Market
Investment Analysis and Financial Strategies
Factoring Market
Investment Analysis and Financial Strategies
Global Regulatory Reporting and Compliance Market
Investment Analysis and Financial Strategies
Financial Services Cloud Market