
 Global Medical Equipment Financing Market | 2026-2036
Global Medical Equipment Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Equipment Financing Market Foresight
Hospital procurement channels is tilting away from direct purchase toward vendor-managed financing arrangements. JPMorgan Chase & Co. leverages its wholesale banking infrastructure to anchor large health system credit facilities across North America. Bajaj Finserv competes in India's densely fragmented clinic market through localized underwriting and rapid equipment deployment timelines. Macquarie Group Limited specializes in structured operating leases for high-value imaging modalities, giving it durable positions in Australian and European hospital networks.
Medical equipment financing denotes the provision of capital or lease structures enabling healthcare providers to acquire diagnostic, therapeutic, and monitoring devices without immediate full payment, typically involving collateralized obligations with equipment serving as security and terms calibrated to clinical revenue cycles. The primary purpose centers on preserving provider liquidity while accelerating technology access. Equipment category segmentation shows imaging devices commanding the largest financing volume due to six-figure unit costs and rapid obsolescence cycles, while surgical instruments financing grows fastest in ambulatory settings where outpatient migration compresses payback timelines. End user type dynamics reveal hospitals dominating absolute transaction value, though diagnostic centers extract superior margin pools through shorter-term, higher-frequency refinancing needs.
FDA equipment classification rules, EU MDR post-market surveillance obligations, and India's CDSCO import licensing framework collectively shape lender collateral valuation and residual risk models across jurisdictions. HIPAA data security provisions in the US and GDPR patient information standards in Europe further constrain connected device financing structures, embedding compliance costs into lease rate calculations. Stakeholders must monitor how central bank rate trajectories and sovereign healthcare budget revisions recalibrate provider creditworthiness and equipment refresh cadences.
Market Dynamics
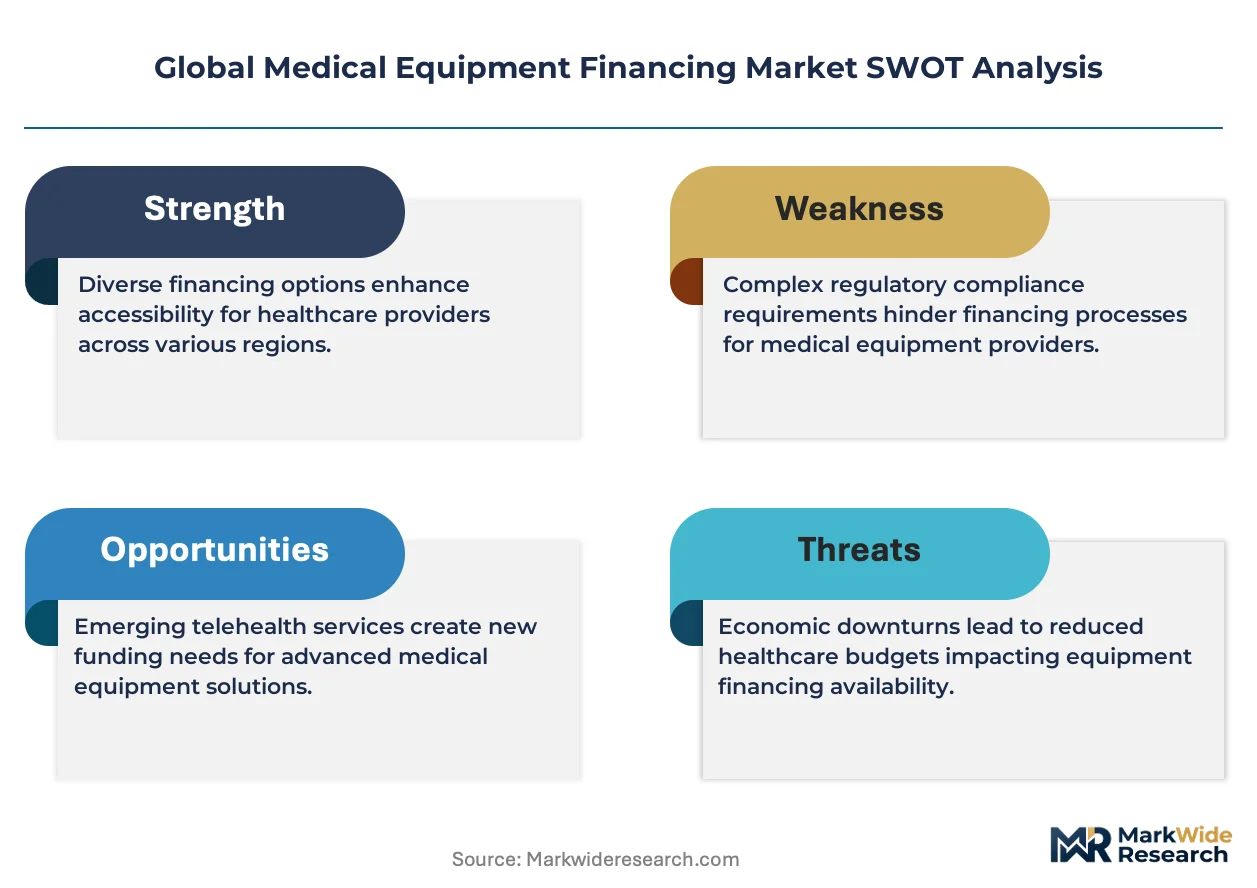
Hospital liquidity constraints are accelerating vendor-managed financing structures as the dominant procurement channel for high-value diagnostic equipment. The FDA's UDI tracking mandates and EU MDR classification upgrades are forcing providers into accelerated equipment refresh cycles that favor lease-based acquisition over capital purchase.
Growth Catalysts
- Regulatory Compliance Pressure:The EU MDR's stricter post-market surveillance obligations and India's CDSCO import licensing framework are compelling hospitals to upgrade to compliant devices, with financing structures absorbing the capital shock of mandatory replacements.
- Imaging Technology Obsolescence:CT and MRI systems face compressed innovation cycles, with mid-sized hospitals in Brazil and Germany leveraging operating leases to access current-generation modalities without full ownership risk.
- Ambulatory Surgical Migration:Outpatient procedure volume is concentrating in specialized clinics across India, where rapid equipment deployment timelines and shorter payback periods favor surgical instrument financing products.
Market Restraints
- Central Bank Rate Volatility:Sovereign monetary tightening in North American and European markets is elevating benchmark rates, directly inflating lease rate calculations and compressing provider creditworthiness assessments.
- Residual Value Uncertainty:Connected devices with embedded data processing capabilities face accelerated functional obsolescence, complicating lender collateral valuation models for second-hand equipment remarketing.
- Regulatory Fragmentation:Divergent data security requirements between HIPAA in the US and GDPR in Europe are embedding compliance premiums into cross-border financing structures, raising transaction costs for multinational health systems.
Strategic Opportunities
- Diagnostic Center Penetration:India's densely fragmented clinic market presents white space for localized underwriting models that compress approval timelines and match equipment deployment to regional patient flow patterns.
- Technology Convergence:AI-enabled diagnostic imaging systems are hybridizing hardware and software value propositions, creating subscription-embedded financing structures that bundle equipment access with algorithm updates.
- Green Equipment Incentives:The EU Green Deal's medical device energy efficiency standards are generating regulatory tailwinds for financing products that prioritize low-consumption imaging modalities with preferential lease terms.
Industry Challenges
- Connected Device Cybersecurity:HIPAA and GDPR compliance requirements for patient data protection are extending financing due diligence timelines, as lenders verify security architecture before collateralizing networked diagnostic equipment.
- Integration Complexity:New imaging systems must interface with legacy hospital information infrastructure, creating implementation delays that strain lease commencement schedules and revenue recognition timelines for financing providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Equipment Financing Market |
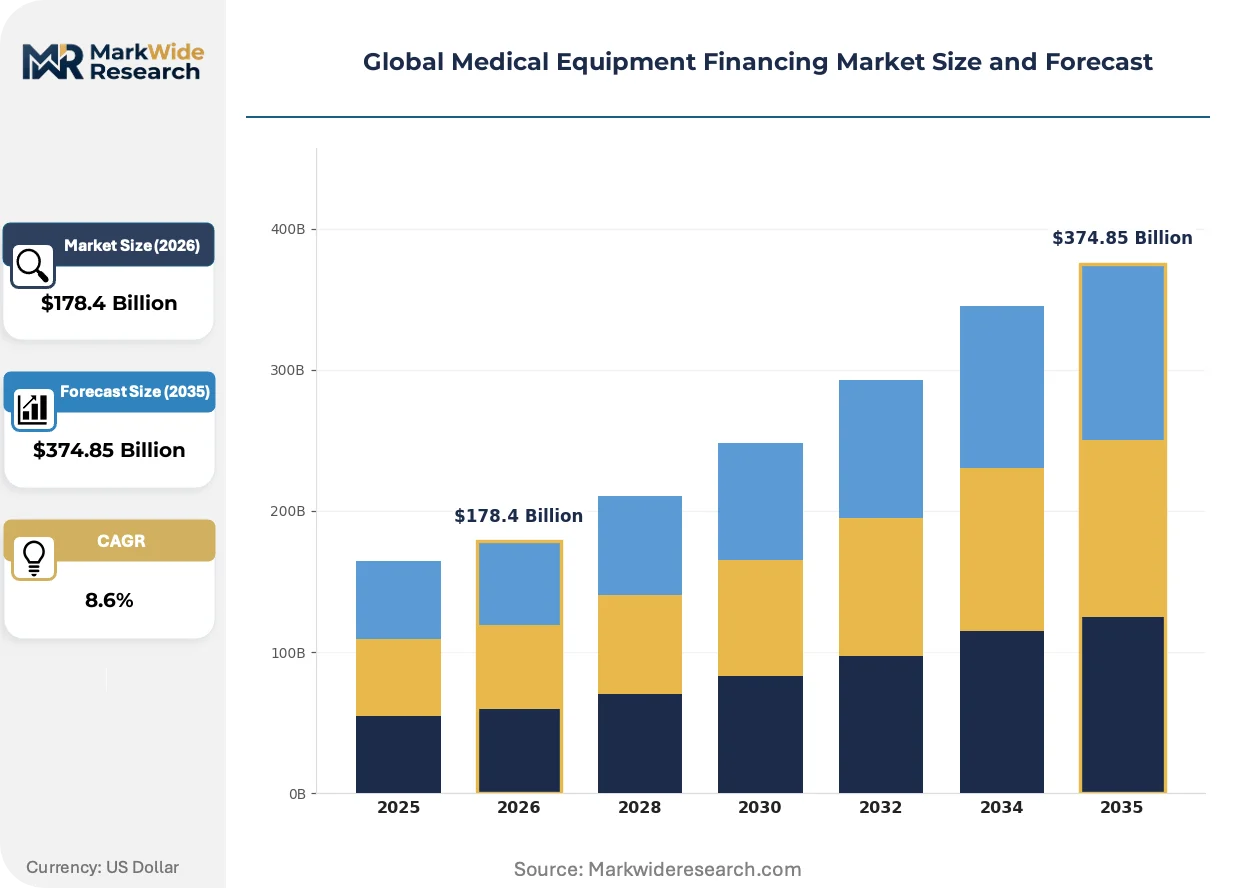
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $374.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Model: Leasing, Direct Lending, Vendor Financing, Equipment Loans, Operating Lease Equipment Category: Imaging Devices, Surgical Instruments, Patient Monitoring, Diagnostic Tools, Laboratory Equipment End User Type: Hospitals, Diagnostic Centers, Ambulatory Care Facilities, Specialized Clinics, Research Institutes Payment Structure: Installment Plans, Balloon Payment, Deferred Payment, Full Settlement, Rent-to-Own |
| Companies Covered | Hero FinCorp, National Funding, Blue Bridge Financial, First American Equipment Finance, SMC Finance, TIAA Bank, Bajaj Finserv, JPMorgan Chase & Co., Macquarie Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Equipment Financing Market Shifts & Advancements
Financing structures are evolving from simple equipment leases toward integrated service contracts that bundle maintenance, software updates, and compliance support. This shift reflects provider demand for predictable operational expenditures and vendor incentives to capture long-term revenue streams beyond hardware margins.
AI-augmented imaging platforms are hybridizing diagnostic hardware with real-time analytics capabilities, enabling radiology departments to generate interpretive reports without separate IT infrastructure investments. Academic medical centers in Germany and the United States are piloting these bundled arrangements most aggressively, compressing the traditional separation between capital equipment and service contracts into unified subscription models.
The EU MDR's enhanced clinical evidence requirements are extending pre-market certification timelines for Class III devices, forcing financing providers to structure longer grace periods before lease payments commence. Manufacturers targeting European hospital networks are absorbing these delays through deferred-payment instruments, while lenders adjust residual risk models to account for postponed revenue recognition.
Consolidation among US health systems is concentrating purchasing power into centralized procurement functions that negotiate enterprise-wide equipment financing facilities. These structures displace individual hospital lease arrangements, with JPMorgan Chase and specialized healthcare lenders competing to anchor multi-year credit facilities spanning dozens of affiliated facilities across state lines.
Global Medical Equipment Financing Market Segmentation
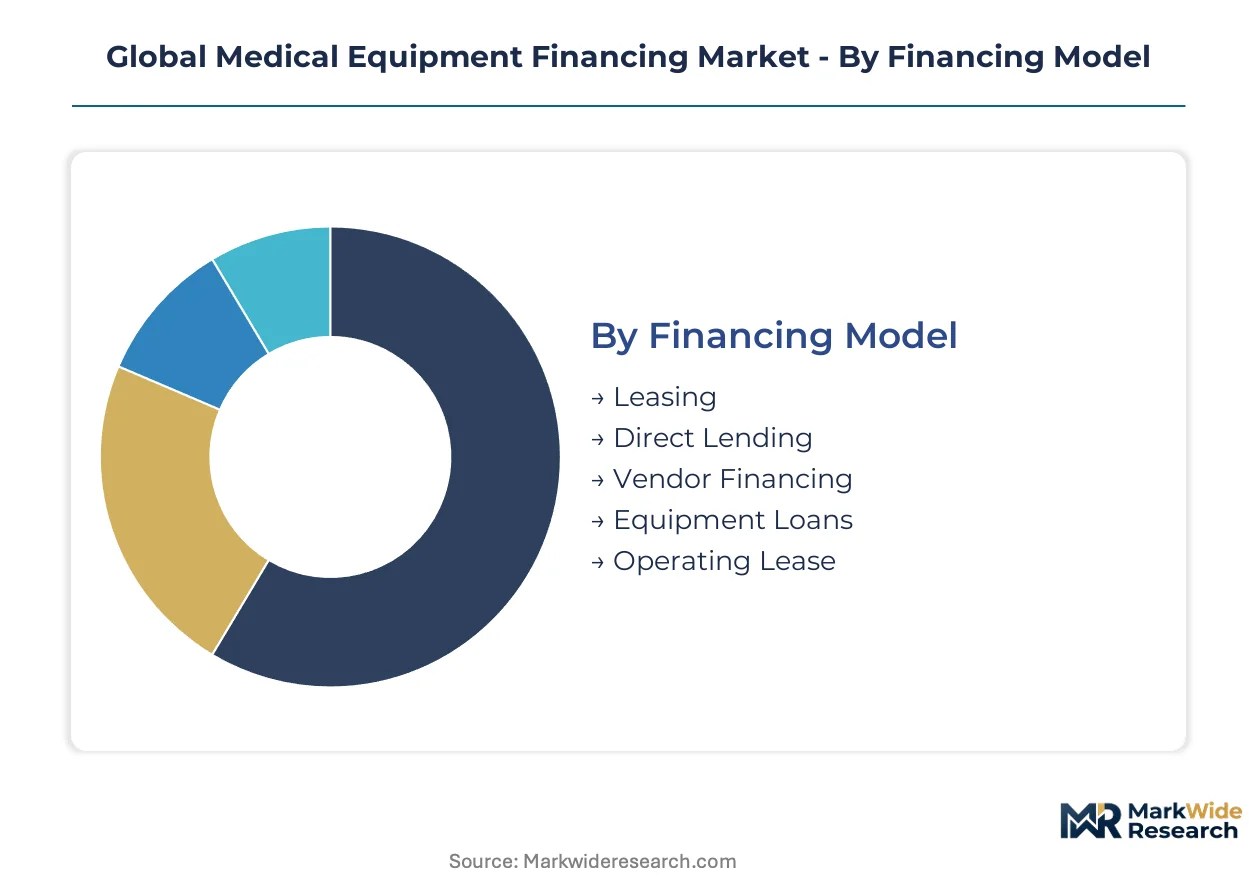
Medical equipment financing structures vary dramatically across procurement channels, with each segment demanding distinct collateral frameworks, residual risk models, and compliance integration. Lenders calibrate terms to equipment obsolescence cycles and end-user revenue stability, creating tiered product architectures that match capital deployment to clinical utility.
Financing Model:
After-sales service intensity varies sharply across financing structures, with bundled maintenance contracts reshaping lender risk profiles and provider cash flow predictability.
- Leasing:Operating lease structures dominate high-value imaging modalities, transferring residual value risk to lessors while preserving hospital liquidity for operational priorities. German hospital networks favor these arrangements for MRI and CT systems given compressed technology refresh cycles.
- Direct Lending:Balance-sheet loans from institutional creditors anchor large health system credit facilities, with JPMorgan Chase deploying wholesale banking infrastructure across North American provider networks. Collateral valuation depends heavily on FDA UDI tracking compliance and equipment remarketability.
- Vendor Financing:Manufacturer-captive finance arms compress approval timelines through pre-negotiated residual values and streamlined deployment logistics.
- Equipment Loans:Term debt structures with equipment-as-collateral suit mid-sized diagnostic centers seeking ownership pathways.
- Operating Lease:Pure rental arrangements without purchase options minimize capital commitment for ambulatory facilities testing new service lines.
By volume, Leasing leads. By growth pace, Vendor Financing is ahead.
Equipment Category:
Unit cost stratification drives financing structure selection, with six-figure imaging systems demanding sophisticated residual value engineering versus lower-ticket device categories.
- Imaging Devices:CT, MRI, and PET systems command the largest absolute financing volumes due to rapid obsolescence and prohibitive capital outlay. Brazilian hospital networks leverage these structures to expand diagnostic capacity without sovereign budget dependence.
- Surgical Instruments:Robotic surgical systems and specialized toolsets generate fastest-expanding financing demand as outpatient migration concentrates procedure volume in ambulatory settings. Shorter payback timelines attract specialized lenders.
- Patient Monitoring:Connected bedside and wearable systems face GDPR and HIPAA compliance premiums embedded in lease rate calculations.
- Diagnostic Tools:Point-of-care testing equipment suits fragmented clinic markets with rapid deployment needs.
- Laboratory Equipment:Analytical and pathology systems carry extended useful lives, favoring term loan structures over operating leases.
Imaging Devices dominates transaction value. Surgical Instruments shows steepest expansion trajectory.
End User Type:
Customer creditworthiness dispersion creates tiered pricing architectures, with consolidated health systems extracting preferential terms versus fragmented independent providers.
- Hospitals:Consolidated US health systems negotiate enterprise-wide credit facilities spanning dozens of affiliated facilities, displacing individual hospital lease arrangements. Centralized procurement functions concentrate purchasing power.
- Diagnostic Centers:India's densely fragmented clinic market rewards localized underwriting models that compress approval timelines. Higher-frequency refinancing needs generate superior margin pools for specialized lenders.
- Ambulatory Care Facilities:Outpatient surgical centers favor shorter-term structures matching equipment depreciation to procedure revenue cycles.
- Specialized Clinics:Single-specialty providers concentrate demand for targeted modalities like ophthalmic or dental imaging systems.
- Research Institutes:Academic medical centers in Germany pilot AI-augmented imaging bundles, merging hardware and algorithm subscription costs.
Hospitals anchor absolute financing volume. Diagnostic Centers gain share fastest.
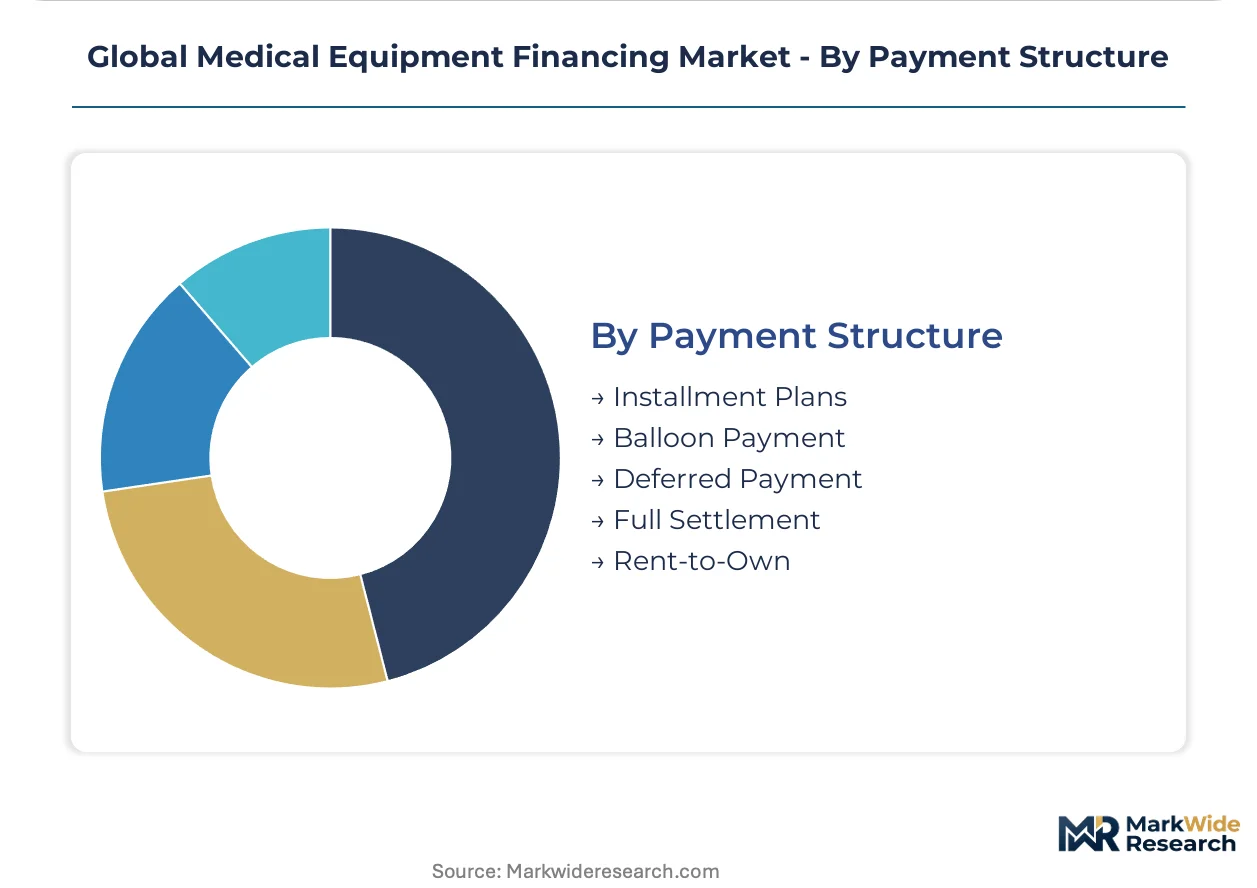
Payment Structure:
Cash flow timing flexibility separates competitive offerings, with deferred and balloon structures addressing provider revenue cycle mismatches.
- Installment Plans:Level payment schedules dominate hospital procurement, matching lease obligations to predictable operational expenditure budgets. EU MDR compliance-driven refresh cycles favor these predictable structures.
- Balloon Payment:Low initial outlays with terminal lump sums suit diagnostic centers expecting equipment trade-in or technology upgrade paths.
- Deferred Payment:Grace periods before first payment accommodate EU MDR-extended certification timelines, with manufacturers absorbing delays through customized instruments.
- Full Settlement:Upfront purchase with subsequent reimbursement suits sovereign-funded health systems with budget certainty.
- Rent-to-Own:Conversion pathways from rental to ownership attract ambulatory facilities testing market demand before capital commitment.
Installment Plans lead by transaction count. Deferred Payment expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks command superior lease terms compared to Brazilian providers, reflecting divergent sovereign credit profiles and equipment refresh cadences across financing markets.
United States
Consolidated health systems in Texas and Florida negotiate enterprise-wide credit facilities spanning dozens of affiliated facilities. HIPAA data security provisions extend financing due diligence timelines for connected diagnostic equipment. The Cleveland Clinic and Mayo Clinic networks anchor multi-billion-dollar imaging procurement programs.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pilot AI-augmented imaging bundles that merge hardware and algorithm subscriptions. EU MDR post-market surveillance obligations compress equipment replacement cycles. Siemens Healthineers maintains dense financing relationships with university hospitals across Baden-Württemberg.
India
Densely fragmented diagnostic centers in Maharashtra and Karnataka drive demand for rapid-deployment surgical instrument financing. CDSCO import licensing frameworks embed compliance premiums into cross-border lease structures. Apollo Hospitals and Narayana Health anchor imaging capacity expansion in Chennai and Bengaluru.
Brazil
Mid-sized hospital networks in São Paulo and Minas Gerais leverage operating leases to access CT and MRI systems without full capital outlay. ANVISA device registration timelines shape lender collateral valuation models. Hospital Israelita Albert Einstein and Hospital Sírio-Libanês concentrate high-value financing activity in São Paulo's metropolitan corridor.
Australia
Macquarie Group structures operating leases for high-value imaging modalities across New South Wales and Victoria. TGA compliance requirements for connected devices extend security architecture verification periods. Royal Melbourne Hospital and Royal Prince Alfred Hospital anchor structured financing for diagnostic infrastructure renewal.
Global Medical Equipment Financing Market Competitive Landscape
Wholesale banking conglomerates and specialized healthcare lenders split the market between balance-sheet depth and sector-specific underwriting velocity. The vendor base concentrates around three strategic archetypes: universal banks deploying wholesale infrastructure, captive finance arms of equipment manufacturers, and independent specialty lenders with localized risk models. Consolidation pressures favor scale-driven players with multi-jurisdictional regulatory expertise. Competitive positioning hinges on residual value engineering capabilities and compliance integration speed.
Within the universal banking tier, JPMorgan Chase & Co. anchors large health system credit facilities across North American provider networks. Bajaj Finserv occupies a position among India-based specialists competing in densely fragmented clinic markets through rapid underwriting timelines. Macquarie Group Limited exemplifies the structured operating lease archetype for high-value imaging modalities across Australian and European hospital networks.
| Leading Market Players |
|---|
| Hero FinCorp |
| National Funding |
| Blue Bridge Financial |
| First American Equipment Finance |
| SMC Finance |
| TIAA Bank |
| Bajaj Finserv |
| JPMorgan Chase & Co. |
| Macquarie Group Limited |
| Others |
Supply & Pricing Matrix
Undercapacity in German MRI manufacturing is compressing supplier margins while elevating lease rate premiums for hospital networks seeking rapid equipment deployment. This utilization squeeze feeds directly into financing provider pricing posture, as lenders embed extended delivery timelines and residual value uncertainty into contracted terms.
Pricing Analysis
The customization-premium spread between configured-to-order imaging systems and standard lease configurations runs wide in this market. Subscription-embedded financing structures dominate AI-augmented modalities, bundling hardware access with algorithm update fees. Price differentiation centers on FDA UDI compliance tier and after-sales service intensity. Pricing pressure stems from central bank rate trajectories elevating benchmark costs across North American and European credit facilities. Diagnostic centers in fragmented markets exhibit highest price sensitivity, while consolidated US health systems extract volume-scale concessions.
Supply Chain Analysis
Export-control regimes restricting semiconductor and precision imaging component flows are reshaping equipment availability timelines across financing markets. Manufacturing concentrates in Germany, the United States, and Japan for high-value diagnostic modalities. Supply chains draw from specialized rare-earth magnet suppliers, cryogenic cooling system fabricators, and AI processor foundries. Single-source vulnerability in superconducting wire supply creates delivery risk for MRI lessors. Distribution runs through manufacturer-captive finance arms and wholesale banking channels with direct hospital network relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residual value engineering capabilities separate viable financing providers from commodity lenders in this market, yet talent scarcity in healthcare asset valuation constrains expansion velocity for mid-tier players seeking scale.
For Market Incumbents: Build regulatory compliance moats through preemptive EU MDR and FDA UDI certification investments that compress rival approval timelines. Anchor enterprise-wide credit facilities with consolidated health systems to displace fragmented single-hospital arrangements. Defend against fintech entrants by embedding cybersecurity verification into standard due diligence protocols for connected diagnostic equipment. For New Entrants and Emerging Players: India's Maharashtra and Karnataka diagnostic center clusters offer underpenetrated white space for localized underwriting models with sub-48-hour approval velocities. Target ambulatory surgical migration in Brazilian outpatient settings where shorter payback timelines attract specialized capital. Pursue vendor financing partnerships with emerging-market equipment distributors lacking captive finance capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-integrated imaging platforms as software development costs merge with hardware deployment. Long-term viability favors acquirers of specialty lenders with proven residual value track records in second-hand equipment remarketing. Monitor central bank rate trajectories as the primary inflection signal for provider creditworthiness compression and equipment refresh cadence shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Accelerated certification timelines force financing structures with extended grace periods. |
| Hospital System Partnership | Enterprise-wide credit facilities displace fragmented single-facility lease arrangements. |
| AI Algorithm Subscription Bundle | Hardware-software convergence creates recurring revenue streams beyond equipment margins. |
| Cybersecurity Architecture Verification | HIPAA and GDPR compliance extends due diligence for connected diagnostic collateral. |
| Green Equipment Certification Program | EU Green Deal energy standards generate preferential lease terms for low-consumption modalities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and equipment financing underwriters; and secondary validation through FDA UDI registration databases, EU MDR notified body certifications, hospital procurement contract filings, and central bank policy disclosures. Bottom-up equipment deployment tracking triangulated against top-down credit facility origination data.
Forecast inputs incorporated financing model penetration curves, equipment obsolescence cycles, and regulatory compliance refresh timelines across the projection horizon. Segmentation dimensions spanned financing structure, equipment category, end-user type, payment structure, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to historical origination volumes and sovereign healthcare budget trajectories. Industry-specific inputs included EU MDR implementation pace and AI-enabled imaging adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-integrated fintech lenders would shift outcomes. Material shifts in central bank rate trajectories or sovereign healthcare austerity measures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Investment Trading Software Market
Financial Services
Online Investment Platform Market
Financial Services
Online Lottery Market
Financial Services
UK Islamic Finance Market
Financial Services
ATM Managed Services Market
Financial Services
Credit Rating Software Market
Financial Services
Contract for Difference Broker Market
Financial Services
Digital Account Opening Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Smart Finance Services Market
Financial Services
Account Aggregators Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Latin America Factoring Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
United Kingdom E-Brokerage Market