
 Foreign Exchange Services Market | 2026-2036
Foreign Exchange Services Market Size, Share, and Industry Trends Forecast 2026-2036
Foreign Exchange Services Market Analysis
ISO 20022 messaging certification is collapsing the barrier between tier-one banks and algorithmic market makers. JPMorgan Chase & Co leverages its proprietary COiN platform to automate post-trade reconciliation across spot and forward workflows. XTX Markets Ltd competes through machine-learning pricing engines that dominate electronic spot matching in London and Singapore. Deutsche Bank AG anchors its franchise on corporate FX hedging advisory spanning forward contracts and currency swaps.
Foreign exchange services encompass the conversion, hedging, and settlement of currencies between counterparties, typically executed over-the-counter with settlement cycles ranging from T+0 for spot transactions to multi-year tenors for structured swaps. These services enable international trade finance, portfolio rebalancing, and corporate treasury risk management across volatile currency pairs. Spot transactions absorb the highest transaction velocity among service types, while forward contracts and currency swaps capture the deepest margin pools from corporate hedging demand. Automated trading systems and API integration are displacing voice-brokered workflows, particularly among hedge funds and quantitative asset managers seeking microsecond latency.
The US SEC and CFTC jointly enforce registration standards for swap dealers under Dodd-Frank, while the EU's ESMA applies MiFID II best-execution rules to electronic FX platforms operating within member states. Japan's FSA mandates segregation of client funds for retail margin FX providers, tightening capital buffers against counterparty default. Stakeholders must monitor how central bank digital currency pilots reshape correspondent banking relationships and settlement infrastructure.
Market Dynamics
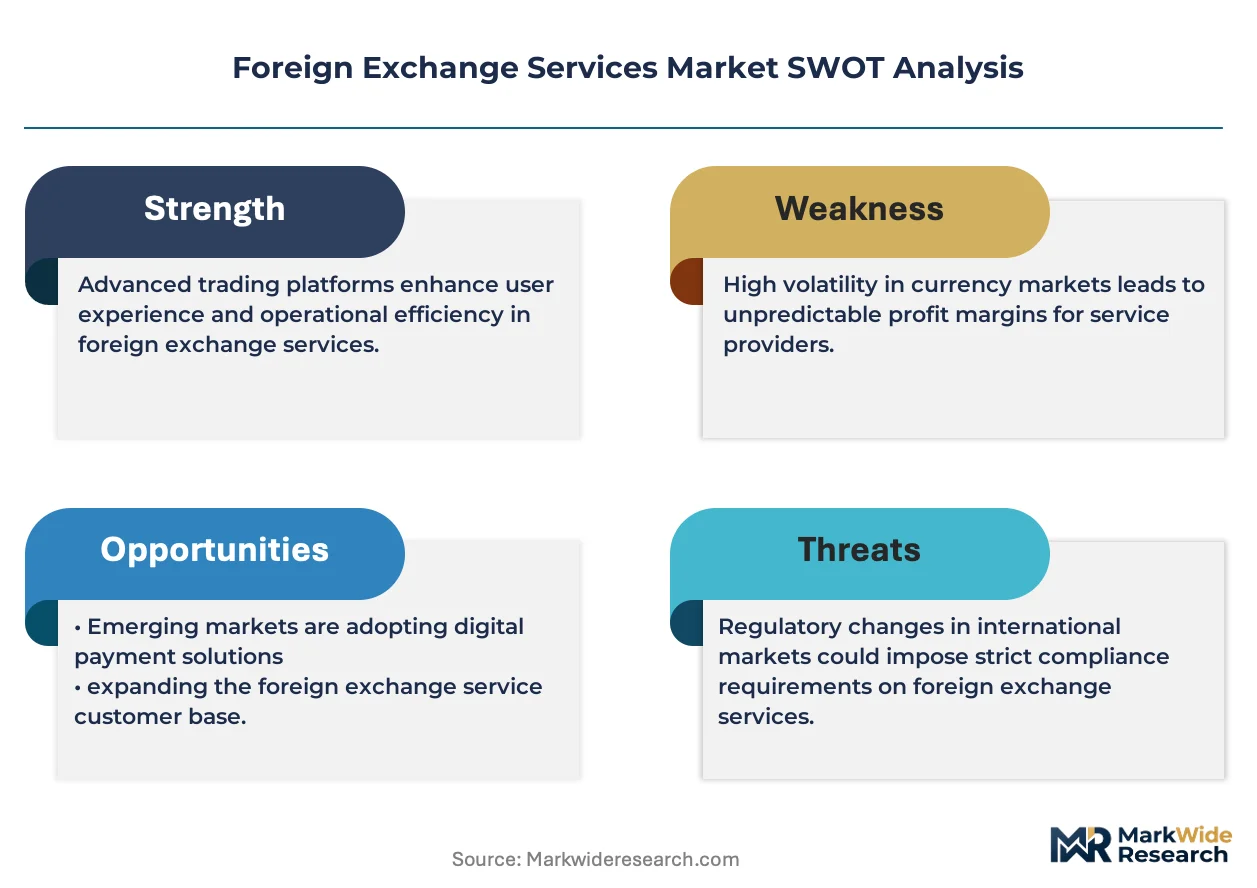
ISO 20022 messaging standardization is collapsing interoperability barriers between legacy correspondent banking networks and algorithmic liquidity providers, forcing infrastructure reinvestment across spot, forward, and swap workflows.
Growth Catalysts
- Cross-border e-commerce expansion:Merchant treasury departments in Singapore and London are scaling automated hedging programs to manage multi-currency receivables volatility.
- MiFID III best-execution mandates:The EU's tightening standards for electronic trading venues are accelerating platform consolidation and transparency tooling adoption.
- API-first integration:Corporate ERP systems are embedding real-time rate feeds and execution capabilities directly into treasury management workflows.
Market Restraints
- Concentrated liquidity provision:Tier-one banks and select non-bank market makers in London and Singapore control pricing formation in major currency pairs.
- Settlement risk in T+2 forwards:Herstatt risk exposure persists in emerging market currency corridors lacking CLS Bank coverage.
- Capital intensity of prime brokerage:Basel III leverage ratio requirements constrain balance sheet deployment for FX swap market-making.
Strategic Opportunities
- Central bank digital currency pilots:Wholesale CBDC infrastructure in Singapore and the EU is testing atomic settlement that could displace correspondent banking layers.
- Carbon accounting integration:Corporate treasuries are layering emissions data into currency hedging decisions to meet CSRD disclosure requirements.
- Embedded FX in B2B payments:Fintech platforms are capturing SME hedging demand that traditional banks underserve.
Industry Challenges
- Legacy system interoperability:Post-trade reconciliation between SWIFT MT and ISO 20022 formats is creating operational friction during the multi-year migration window.
- Quantitative talent scarcity:Pricing engine development and machine-learning model governance require specialized skill sets concentrated among a limited pool of practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foreign Exchange Services Market |
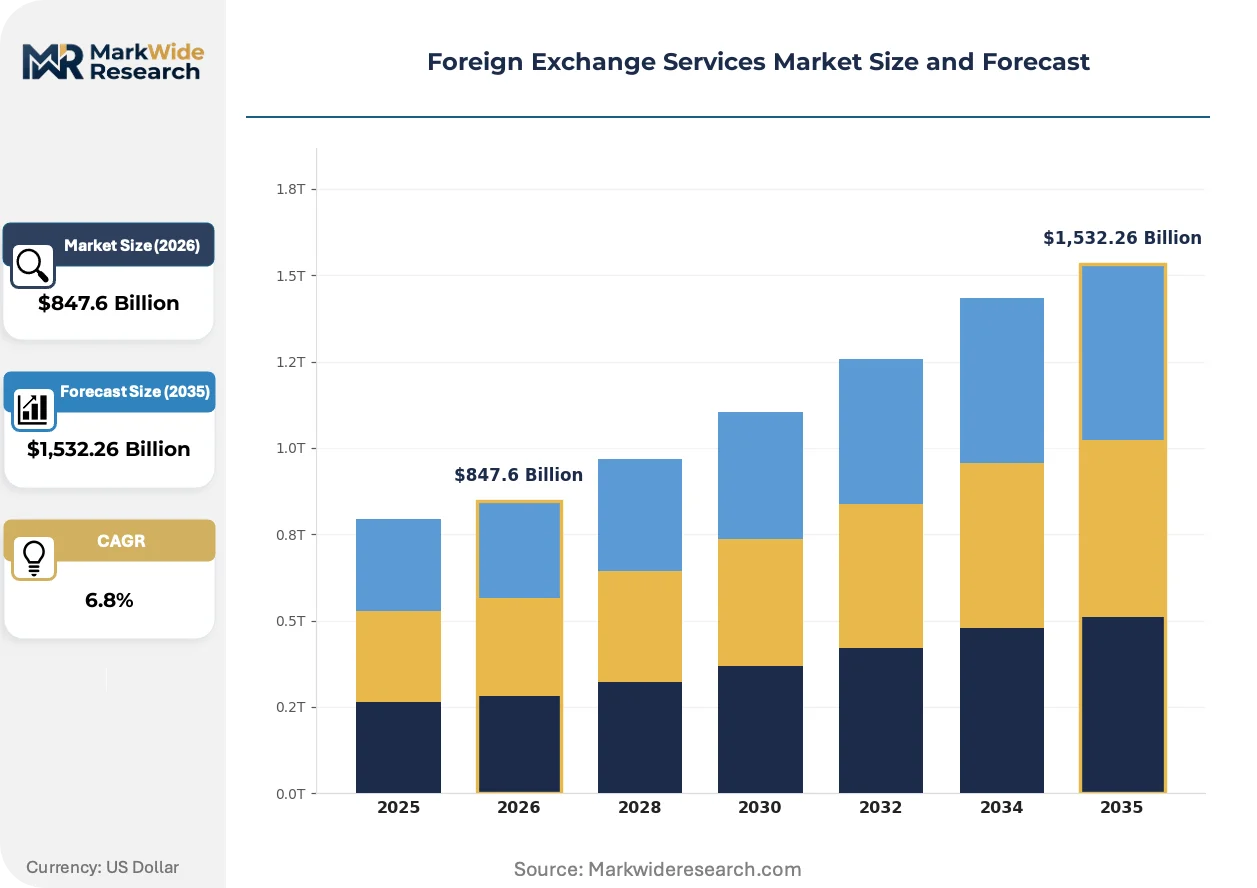
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,532.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spot Transactions, Forward Contracts, Currency Swaps, Options Client Type: Banks, Corporates, Hedge Funds, Retail Investors Transaction Size: Small, Medium, Large, Institutional Technology: Automated Trading Systems, API Integration, Web Platforms, Mobile Applications |
| Companies Covered | JPMorgan Chase & Co, UBS Group AG, Deutsche Bank AG, Citigroup Inc, HSBC Holdings PLC, Goldman Sachs Group Inc, Bank of America Corp, Barclays PLC, XTX Markets Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foreign Exchange Services Market Emerging Trajectories
Algorithmic execution infrastructure is compressing latency thresholds while regulatory fragmentation across jurisdictions is forcing multi-venue compliance architectures. These shifts are redrawing competitive boundaries between bank and non-bank liquidity providers.
Machine-learning pricing engines deployed by quantitative market makers are miniaturizing the bid-ask spreads available in electronic spot markets. Hedge funds and systematic asset managers are capturing these tighter rates through direct market access APIs. The compression is eroding voice-brokered revenue pools while concentrating flow toxicity risk with the fastest analytical systems.
ESMA's MiFID III framework is extending best-execution documentation requirements to FX forwards and swaps previously exempt from systematic reporting. Electronic trading venues operating across EU member states must now demonstrate transaction cost analysis and venue selection rationale. Corporate treasury platforms are responding by embedding compliance audit trails directly into execution algorithms.
Corporate hedging behavior is rotating from static calendar-based forward programs toward dynamic, exposure-linked execution triggered by ERP-integrated risk thresholds. Multinational manufacturers with operations across Germany, Japan, and the United States are adopting this approach to reduce carry costs and basis risk. The shift is compressing traditional bank advisory relationships in favor of automated, self-service platforms.
Foreign Exchange Services Market Segmentation
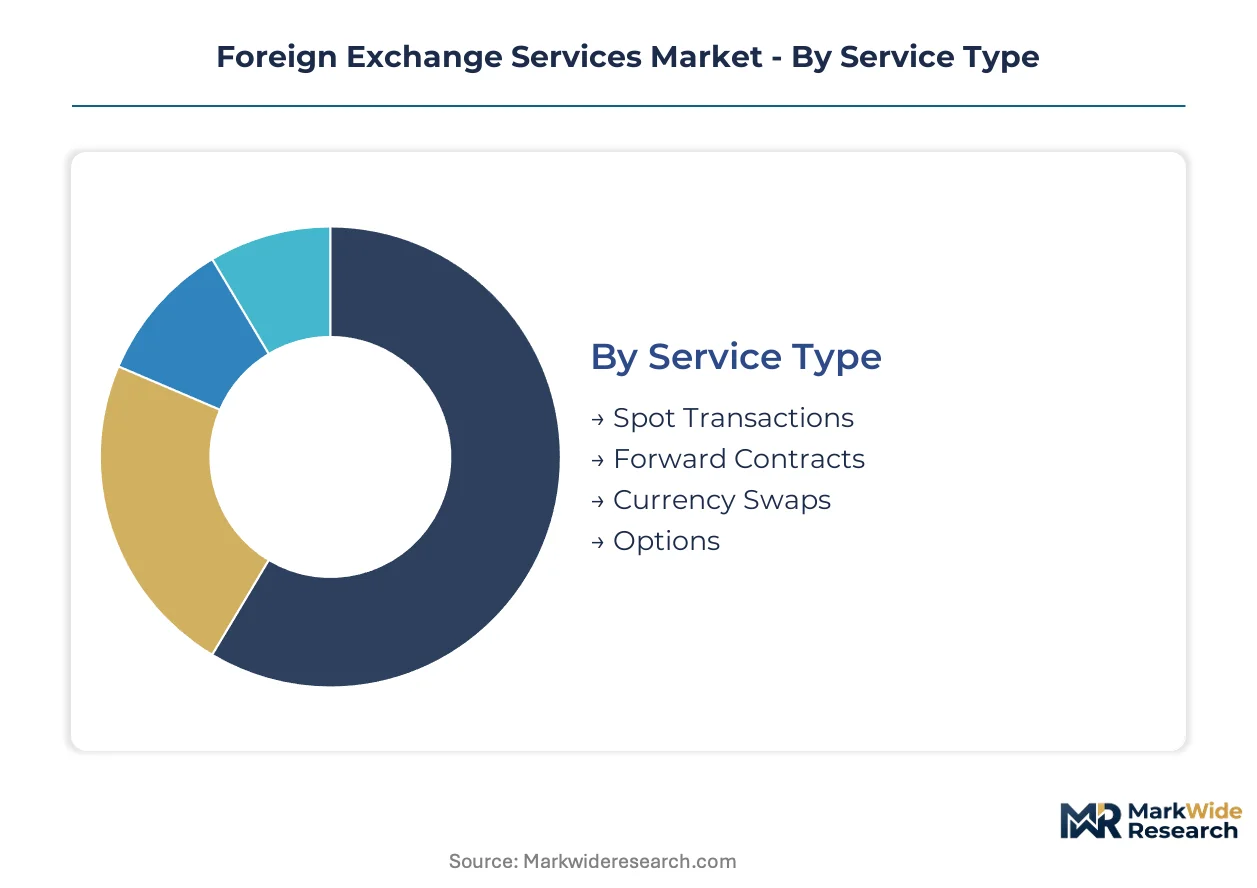
Segmentation in foreign exchange services determines execution infrastructure, margin capture, and regulatory treatment. Service type dictates settlement cycles and capital requirements. Client type shapes pricing models and relationship intensity.
Service Type:
Channel mix varies sharply by tenor and complexity, with voice execution persisting in long-dated structures while electronic platforms dominate high-velocity spot flows.
- Spot Transactions:Immediate settlement instruments executed at current market rates with T+0 or T+2 delivery cycles. Demand concentrates among high-frequency trading firms and e-commerce treasury desks in Singapore and London, driven by real-time liquidity needs and API-accessible pricing feeds.
- Forward Contracts:Customized agreements locking exchange rates for future delivery dates ranging from one week to twelve months. Corporate treasury departments across Germany, Japan, and the United States deploy these instruments to hedge receivables volatility, constrained by Herstatt risk in emerging market corridors lacking CLS Bank coverage.
- Currency Swaps:Simultaneous spot and forward transactions exchanging principal and interest flows across currencies. Basel III leverage ratio requirements constrain balance sheet deployment for market-making in this segment.
- Options:Derivative contracts providing the right but not obligation to exchange currency at predetermined rates. Premium pricing reflects implied volatility surfaces calibrated by quantitative trading desks.
Spot transactions dominate installed base. Forward contracts and currency swaps are where expansion concentrates.
Client Type:
Margin architecture inverts across the client hierarchy, with retail and SME segments commanding wider spreads than institutional flows despite lower absolute ticket sizes.
- Banks:Interdealer market participants providing liquidity to other financial institutions and large corporate clients. Tier-one institutions in London and Singapore control pricing formation in major currency pairs through proprietary electronic platforms.
- Corporates:Non-financial enterprises managing multi-currency exposures from international trade and cross-border operations. Manufacturing conglomerates with supply chains spanning multiple jurisdictions are rotating from static calendar-based hedging toward dynamic, ERP-integrated execution triggered by risk thresholds.
- Hedge Funds:Systematic and discretionary asset managers deploying leveraged currency positions as alpha generation or portfolio diversification tools. Quantitative strategies demand microsecond latency through direct market access APIs.
- Retail Investors:Individual speculators and small business owners accessing FX markets through margin trading platforms. Japan's FSA mandates segregation of client funds for providers serving this segment, tightening capital buffers against counterparty default.
Banks and corporates anchor revenue volume. Hedge funds are expanding most quickly through algorithmic execution adoption.
Transaction Size:
Cost tier stratification determines whether clients access interbank pricing or absorb marked-up retail spreads, with threshold effects at standard lot boundaries.
- Small:Transactions below standard institutional lot sizes, typically accessed through retail brokers or fintech platforms with embedded markup structures. SME hedging demand in this tier is migrating toward embedded FX in B2B payment platforms that traditional banks underserve.
- Medium:Ticket sizes qualifying for prime brokerage relationships but below direct interbank access thresholds. Regional banks and specialized non-bank market makers compete for flow in this tier through relationship pricing.
- Large:Institutional-scale transactions executed directly with tier-one liquidity providers or through anonymous electronic matching platforms. MiFID III best-execution mandates now require documentation of venue selection rationale for trades in this category.
- Institutional:Block-sized flows from central banks, sovereign wealth funds, and large asset managers moving markets upon execution. Voice-brokered workflows persist here for illiquid currency pairs and complex structured tenors.
Large transactions dominate institutional infrastructure deployment. Small and medium tiers are gaining share fastest through API-first platform proliferation.
Technology:
Maturity gradients separate legacy infrastructure from cloud-native architectures, with migration timelines compressed by ISO 20022 standardization mandates.
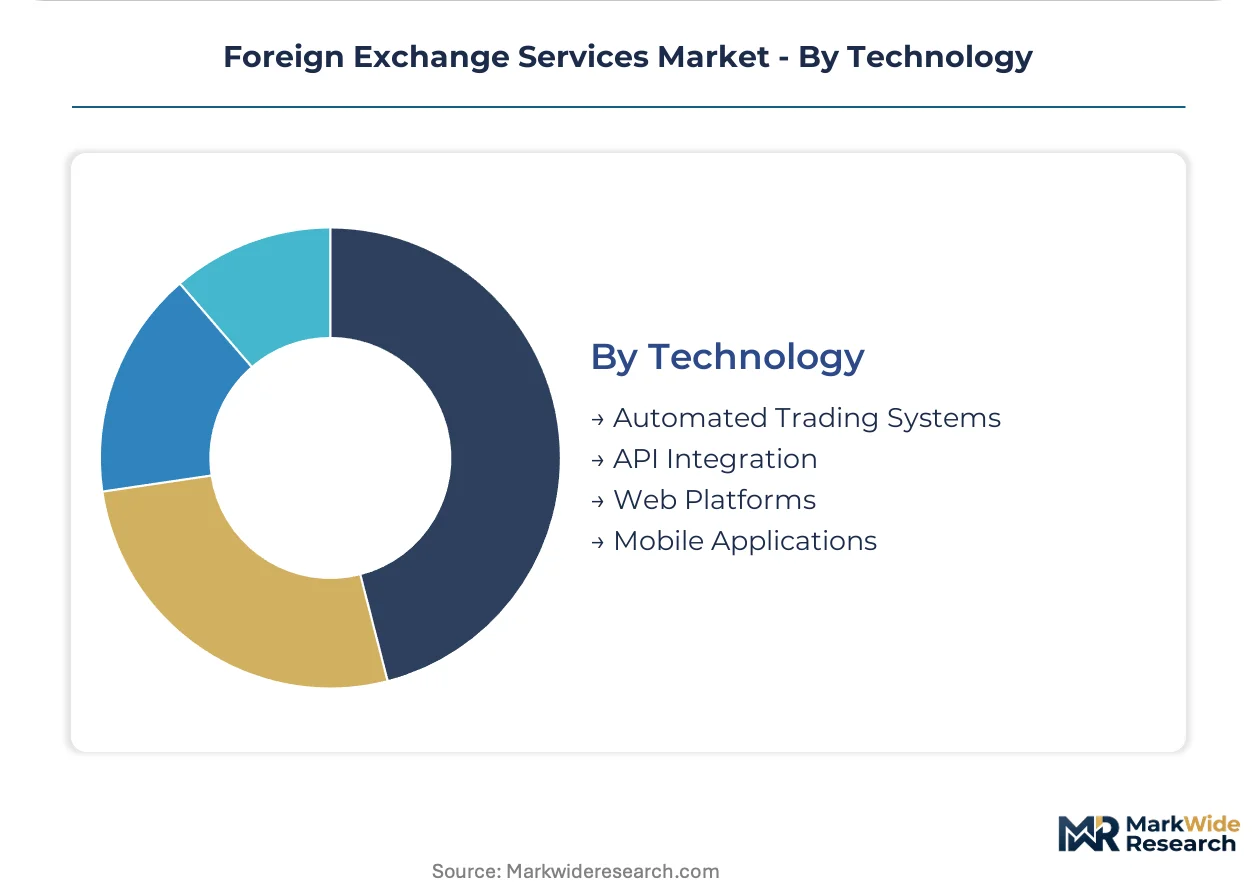
- Automated Trading Systems:Algorithmic execution infrastructure deploying pre-programmed strategies across multiple liquidity venues. Machine-learning pricing engines deployed by quantitative market makers in London and Singapore miniaturize bid-ask spreads available in electronic spot markets.
- API Integration:Direct connectivity between client ERP or treasury management systems and execution venues. Corporate platforms in Singapore and London are embedding real-time rate feeds and execution capabilities directly into workflow automation.
- Web Platforms:Browser-based interfaces serving retail and small corporate clients with standardized product menus. ESMA's MiFID III framework is extending best-execution documentation requirements to trades executed through these channels.
- Mobile Applications:Smartphone-native interfaces for position monitoring and execution on compressed timelines. Post-trade reconciliation between SWIFT MT and ISO 20022 formats creates operational friction during the multi-year migration window affecting these newer channels.
Automated trading systems anchor institutional market structure. API integration represents the steepest expansion trajectory as corporate treasury departments modernize infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MiFID III implementation across EU member states is redistributing FX trading volumes toward jurisdictions with lighter post-trade reporting burdens. Singapore's wholesale liquidity hub and London's electronic matching infrastructure capture the displaced flow.
United States
The SEC and CFTC jointly enforce Dodd-Frank registration standards for swap dealers, compressing balance sheet deployment for currency swap market-making. Regional banks in New York and Chicago are retreating from prime brokerage services under Basel III leverage constraints. Chicago's derivatives exchanges anchor institutional options flow.
United Kingdom
ESMA's best-execution mandates now cover FX forwards and swaps previously exempt from systematic reporting. XTX Markets Ltd exemplifies the machine-learning pricing engines dominating electronic spot matching in London. The City's correspondent banking layers face displacement from wholesale CBDC pilots.
Germany
Corporate treasury departments across Bavaria and Baden-Württemberg rotate from static calendar-based hedging toward ERP-integrated dynamic execution. Deutsche Bank AG anchors its franchise on forward contract advisory for manufacturing exporters. Frankfurt's ECB proximity shapes euro liquidity formation.
Singapore
Cross-border e-commerce merchant treasuries scale automated hedging programs to manage multi-currency receivables volatility. The Monetary Authority of Singapore pilots wholesale CBDC infrastructure testing atomic settlement. The city-state's wholesale FX liquidity hub concentrates pricing formation for Asia-Pacific currency pairs.
Japan
The FSA mandates segregation of client funds for retail margin FX providers, tightening capital buffers against counterparty default. Tokyo's institutional investors drive demand for long-dated currency swaps. Osaka's commodity exchanges experiment with FX-linked derivatives.
Foreign Exchange Services Market Vendor Landscape
Listed leaders compete with private specialists across electronic execution infrastructure, creating a tiered structure where scale-driven banks and algorithmic market makers split liquidity provision. Tier-one institutions control pricing formation in major currency pairs through proprietary platforms. Three archetypes dominate: universal banks with balance sheet depth, quantitative specialists with machine-learning engines, and advisory-focused relationship banks. Consolidation concentrates among electronic venue operators, while technology licensing agreements proliferate between legacy institutions and fintech infrastructure providers.
Within the universal bank tier, JPMorgan Chase & Co and Deutsche Bank AG exemplify divergent strategic positioning—one automating post-trade reconciliation through proprietary platforms, the other anchoring on corporate hedging advisory spanning forward contracts and currency swaps. XTX Markets Ltd occupies a position among quantitative specialists, representing the non-bank market makers compressing bid-ask spreads through machine-learning pricing engines in London and Singapore.
| Leading Market Players |
|---|
| JPMorgan Chase & Co |
| UBS Group AG |
| Deutsche Bank AG |
| Citigroup Inc |
| HSBC Holdings PLC |
| Goldman Sachs Group Inc |
| Bank of America Corp |
| Barclays PLC |
| XTX Markets Ltd |
| Others |
Supply Flow & Price Mechanics
ISO 20022 messaging certification gates both liquidity provider qualification and price differentiation in electronic FX markets. Tier-one banks and algorithmic market makers with certified infrastructure capture tighter spreads while uncertified participants absorb markup penalties.
Pricing Analysis
Certification level creates the primary spread stratification across electronic venues. Tier-one banks with proprietary matching engines command premium pricing for spot transactions, while API-integrated non-bank market makers undercut through machine-learning pricing engines. Cost compression in retail-facing spot markets is intensifying because embedded FX fintech platforms disintermediate traditional bank markups. Corporate treasury departments show lowest price sensitivity for forward contract advisory, while retail margin traders drive hardest bargain hunting.
Supply Chain Analysis
CLS Bank settlement infrastructure in London, New York, and Tokyo underwrites counterparty risk mitigation across T+2 forward workflows. Liquidity provision draws from tier-one banks in Singapore and London, plus quantitative specialists with co-located matching engines. Single-source vulnerability concentrates in emerging market currency corridors lacking CLS coverage. Distribution runs through prime brokerage relationships for institutional clients and mobile APIs for retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine-learning pricing engine development and quantitative model governance represent scarce capabilities concentrated among limited practitioner pools. Firms lacking these assets face structural disadvantage in electronic spot markets.
For Market Incumbents: Compound defensive positioning through ISO 20022 infrastructure completion ahead of regulatory deadlines. Acquire API-first fintech platforms serving SME hedging demand that traditional advisory relationships underserve. Vertical integration into cloud-native treasury management systems locks corporate clients before embedded FX competitors scale. For New Entrants and Emerging Players: Lead with carbon-accounting-integrated hedging tools targeting CSRD-disclosure-driven corporate treasuries in Germany and the EU. Capture SME segments through B2B payment platform partnerships that bypass bank prime brokerage minimums. Position as compliance-native alternatives for MiFID III documentation requirements. For Investors and Strategic Acquirers: MiFID III implementation reshapes the acquisition landscape by concentrating venue operators with systematic reporting infrastructure. Five-to-ten year viability favors quantitative specialists with machine-learning pricing engines and cloud-native post-trade platforms. Monitor wholesale CBDC pilot outcomes in Singapore and the EU as atomic settlement adoption signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Infrastructure Migration | Certification separates tier-one liquidity providers from algorithmic market makers in electronic spot markets. |
| API-First Treasury Platform Integration | Corporate ERP embedding captures hedging workflows previously managed through voice-brokered bank relationships. |
| Machine-Learning Pricing Engine Deployment | XTX Markets Ltd exemplifies spread compression dominance in London and Singapore electronic matching. |
| Wholesale CBDC Settlement Infrastructure | Monetary Authority of Singapore pilots test atomic settlement displacing correspondent banking layers. |
| Carbon Accounting Hedging Integration | CSRD disclosure requirements create compliance-driven demand for emissions-linked currency risk management. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation workflows. Treasury technology officers at multinational manufacturers, electronic trading venue operators, quantitative market maker risk managers, and corporate FX advisory heads at tier-one banks provided qualitative grounding. Secondary sources encompassed CLS Bank settlement volume disclosures, ESMA MiFID III consultation papers, Monetary Authority of Singapore CBDC pilot documentation, and SWIFT ISO 20022 migration reports. Bottom-up transaction flow estimates and top-down market sizing triangulated across these inputs.
Across the analysis window, the forecasting framework modeled service type segmentation by settlement cycle and capital intensity, client type by relationship depth and pricing model, and technology tier by infrastructure maturity and regulatory compliance status. CAGRs derived from historical volume trajectories in spot, forward, and swap instruments, adjusted for API adoption curves and MiFID III implementation timelines. Forward contract advisory revenue pools and algorithmic spot matching volume served as industry-specific calibration inputs.
Underlying assumptions cover stable CLS Bank coverage expansion, ISO 20022 migration timelines, and central bank digital currency pilot progression, with deviation risk concentrated in emerging market settlement infrastructure gaps and quantitative talent scarcity. Practitioners should keep alternative scenarios live as regulatory fragmentation and wholesale CBDC adoption patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Australia Online Gambling Market
Financial Services
Europe E-Invoicing Market
Financial Services
Contract for Difference Broker Market
Financial Services
Benefits Consulting Service Market
Financial Services
China Trade Finance Market
Financial Services
Europe B2B Legal Services Market
Financial Services
ATM Software Market
Financial Services
Latin America Factoring Services Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Global Product Cost Management Market
Financial Services
China Factoring Services Market
Financial Services
South Korea Trade Finance Market
Financial Services
Online Investment Platform Market
Financial Services
Africa Lottery Market
Financial Services
Cash Logistics Market