
 Europe E-Invoicing Market | 2026-2036
Europe E-Invoicing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Invoicing Market Intelligence
Cloud-native architecture is consolidating around API-first platforms that displace legacy PDF-to-XML conversion workflows. SAP SE leverages its S/4HANA installed base to anchor enterprise e-invoicing rollouts across German automotive supply chains. Pagero competes through PEPPOL access point density across Nordic public procurement networks. Basware Corporation specializes in accounts-payable automation that extends beyond invoice receipt into payment reconciliation workflows.
Europe e-invoicing denotes the electronic exchange of structured invoice data between trading parties using standardized formats such as EN 16931, UBL 2.1, or CII syntax, transmitted through certified service providers or direct ERP integration for VAT reporting and payment settlement. Cloud-based deployment leads solution uptake as SMEs abandon on-premise maintenance burdens, while compliance management tools capture expanding margin pools from real-time VAT reporting obligations. The BFSI end-user segment sustains premium pricing for multi-jurisdiction audit trail capabilities, whereas manufacturing buyers prioritize purchase-order matching embedded within e-invoice software.
EU ViDA reforms, ECHA-aligned data-integrity standards, and country-level VAT digitization mandates from Germany's BMF and Italy's Agenzia delle Entrate are reshaping product requirements and market access conditions across the continent. The EU AI Act introduces algorithmic transparency obligations for automated invoice-processing systems that classify transactions or flag anomalies. Stakeholders must monitor how national tax authorities sequence mandatory B2B e-invoicing deadlines and whether PEPPOL network governance evolves toward centralized EU oversight or remains member-state fragmented.
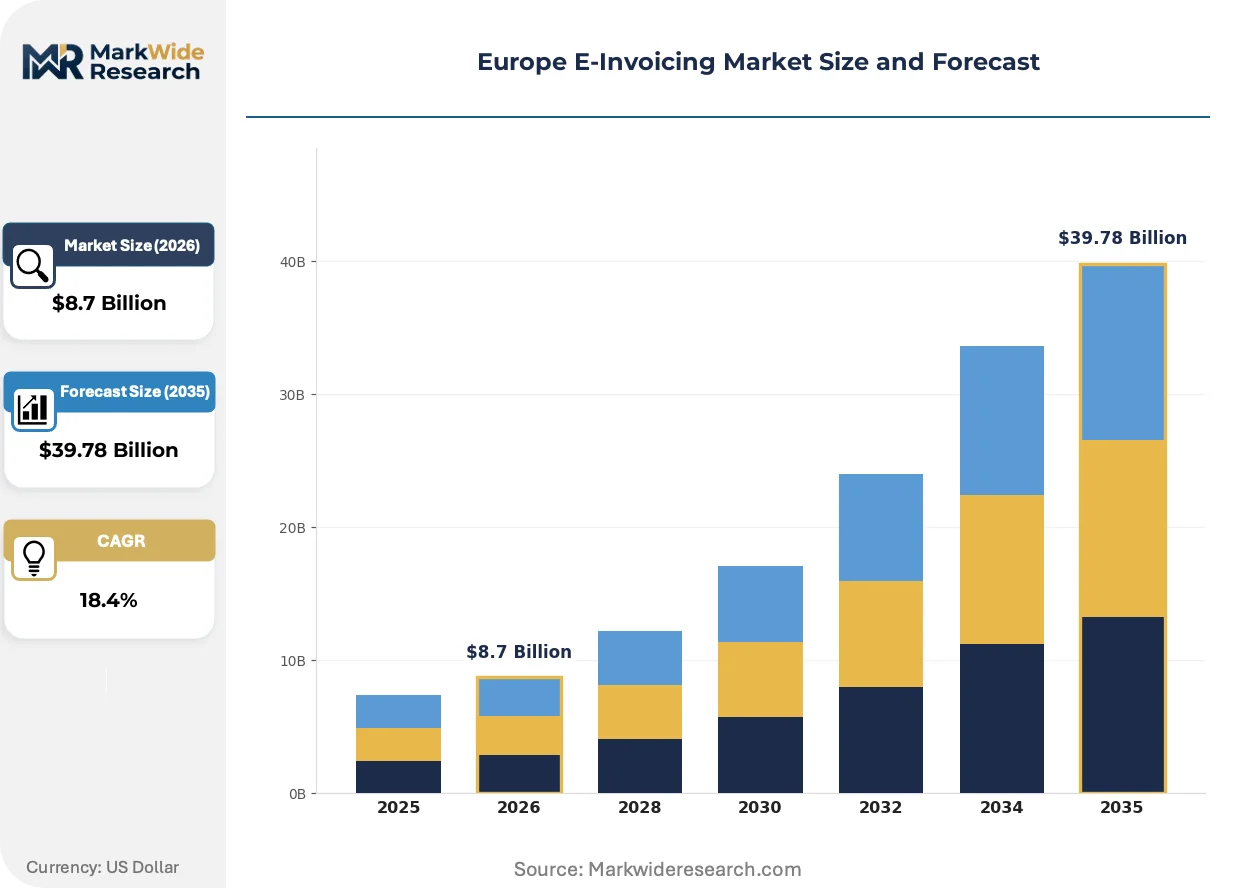
Market Dynamics
EU ViDA reforms and the PEPPOL network expansion are compressing implementation timelines across member states, forcing ERP vendors and service providers to accelerate API-first platform development ahead of national mandate deadlines.
Growth Catalysts
- EN 16931 Standardization:The EU-wide adoption of this semantic data model eliminates format fragmentation, reducing integration costs for cross-border B2B transactions and enabling seamless PEPPOL network interoperability.
- Germany BMF Mandates:The Federal Ministry of Finance's phased B2B e-invoicing requirements are compelling mid-market enterprises to abandon paper-based workflows, creating concentrated demand for cloud-native compliance platforms.
- Real-Time VAT Reporting:Italy's Agenzia delle Entrate clearance model and similar schemes across France and Poland are converting invoice transmission into a continuous data stream, expanding addressable market for automated tax engines.
Market Restraints
- Legacy ERP Lock-In:Deep SAP and Oracle installations in German automotive supply chains create switching friction, slowing cloud-native platform penetration despite regulatory pressure.
- Member-State Fragmentation:Divergent national implementation timelines and PEPPOL authority governance structures force vendors to maintain jurisdiction-specific compliance modules, elevating R&D overhead.
- XML-to-API Transition Costs:SMEs face capital intensity in migrating from established PDF-to-XML conversion workflows to structured data exchange, particularly in Southern and Eastern European markets with limited IT staffing.
Strategic Opportunities
- Romania and Bulgaria:These markets exhibit minimal e-invoicing penetration among domestic SMEs, presenting first-mover advantage for PEPPOL access point providers willing to localize pricing and support.
- AI-Act Compliance Layer:Algorithmic transparency requirements for automated invoice classification systems create premium service tiers around explainable anomaly detection and audit trail documentation.
- Embedded Finance Convergence:The integration of e-invoicing data with supply chain finance and dynamic discounting platforms opens recurring revenue streams beyond transaction processing fees.
Industry Challenges
- PEPPOL Authority Coordination:Vendors must navigate 27 national access point certification regimes with varying technical specifications and update cadences, straining operational scalability.
- Hybrid Cloud Architecture:Enterprises demand seamless on-premise-to-cloud orchestration for sensitive invoice data, complicating product roadmaps and support infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Invoicing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile End User: Retail, Healthcare, BFSI, Manufacturing Solution: E-Invoice Software, Payment Processing, Compliance Management, Reporting Tools Customer Type: SMEs, Large Enterprises, Government Agencies, Non-Profit Organizations |
| Companies Covered | Coupa Software Inc., Comarch SA, SAP SE, Pagero, Cegedim SA, Basware Corporation, International Business Machines Corporation, Esker SA, Tradeshift, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Invoicing Market Strategic Shifts & Innovations
API-first architectures are displacing batch-file exchange protocols, enabling real-time invoice validation and payment reconciliation that compresses working capital cycles for European enterprises.
Cloud-native e-invoicing platforms are modularizing around microservices that separate compliance validation, data transformation, and network transmission functions. German automotive suppliers and French retail chains are adopting these composable stacks to isolate regulatory changes without full platform overhauls. This modularization is reducing implementation timelines from quarters to weeks.
The EU AI Act introduces mandatory documentation requirements for machine-learning systems that flag suspicious transactions or classify invoice anomalies. Vendors must now maintain algorithmic audit trails and human-in-the-loop review protocols, particularly affecting BFSI deployments where automated decisioning faces heightened scrutiny. Compliance tooling around explainability is emerging as a distinct product category.
Buyer concentration among large European procurement consortia is shifting vendor engagement models from per-transaction pricing toward outcome-based contracts tied to working capital optimization. Nordic public sector frameworks and German automotive purchasing cooperatives now demand guaranteed days-payable-outstanding improvements, forcing providers to embed supply chain finance capabilities directly within invoice workflows.
Europe E-Invoicing Market Segmentation
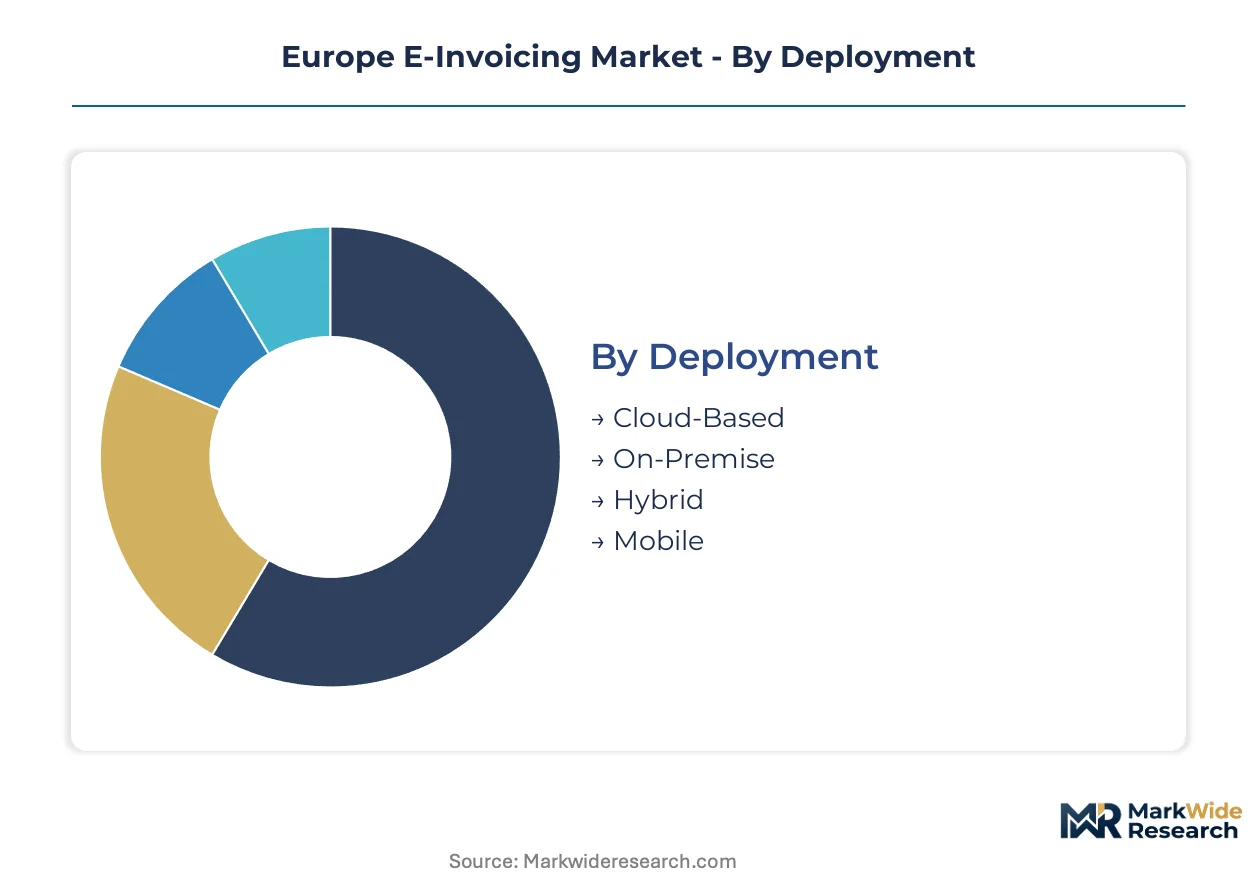
E-invoicing vendors architect product portfolios around deployment flexibility and compliance intensity. Segmentation reveals where platform investments concentrate and which buyer archetypes command premium pricing.
Deployment:
Cloud-native buyers prioritize zero-maintenance infrastructure and automatic regulatory updates; on-premise holdouts demand data sovereignty for sensitive invoice repositories.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance burdens while embedding real-time EN 16931 validation engines. German mid-market manufacturers and French retail chains are migrating here to satisfy BMF and DGFiP mandate deadlines without capital expenditure.
- On-Premise:Dedicated installations within enterprise data centers preserve complete audit trail custody. Italian banking consortia and German automotive suppliers with legacy SAP landscapes maintain this model for high-volume transaction processing where latency sensitivity exceeds cloud convenience.
- Hybrid:Orchestrated workloads split sensitive master data on-premise while routing transactional validation through cloud PEPPOL access points.
- Mobile:Native iOS and Android applications enabling field-based invoice approval workflows for distributed procurement teams.
Cloud-Based leads volumes today; Hybrid is gaining share fastest as enterprises sequence cloud migration without full displacement.
End User:
Sector-specific compliance regimes and transaction velocity requirements shape solution configuration and pricing tiers.
- BFSI:Multi-jurisdiction audit trails and algorithmic anomaly detection satisfy EU AI Act documentation obligations for automated transaction classification. Real-time VAT reporting integration with Agenzia delle Entrate and Polish tax authorities drives concentrated demand among Italian and Polish banking networks.
- Manufacturing:Purchase-order matching embedded within invoice workflows compresses three-way reconciliation cycles. German automotive supply chains prioritize this capability to synchronize with S/4HANA procurement modules.
- Retail:High-volume supplier onboarding with automated PEPPOL network discovery reduces procurement administrative overhead.
- Healthcare:Patient data isolation requirements and public procurement framework compliance dominate vendor selection criteria.
BFSI commands premium pricing today; Manufacturing is expanding most quickly as B2B mandates penetrate supplier networks.
Solution:
Modular architecture separates infrastructure, compliance, and analytics into composable service layers.
- E-Invoice Software:Core platforms handling EN 16931, UBL 2.1, and CII syntax generation with embedded PEPPOL transmission protocols. German automotive suppliers anchor demand here for ERP-integrated document exchange.
- Compliance Management:Automated tax engine updates responding to ViDA reforms and country-specific mandate sequencing. Italian real-time reporting requirements and France's upcoming B2B obligations sustain concentrated investment.
- Payment Processing:Embedded settlement rails connecting invoice approval to treasury execution.
- Reporting Tools:Dashboard analytics for days-payable-outstanding optimization and supplier performance scoring.
E-Invoice Software anchors revenue today; Compliance Management is climbing the fastest as mandate timelines compress.
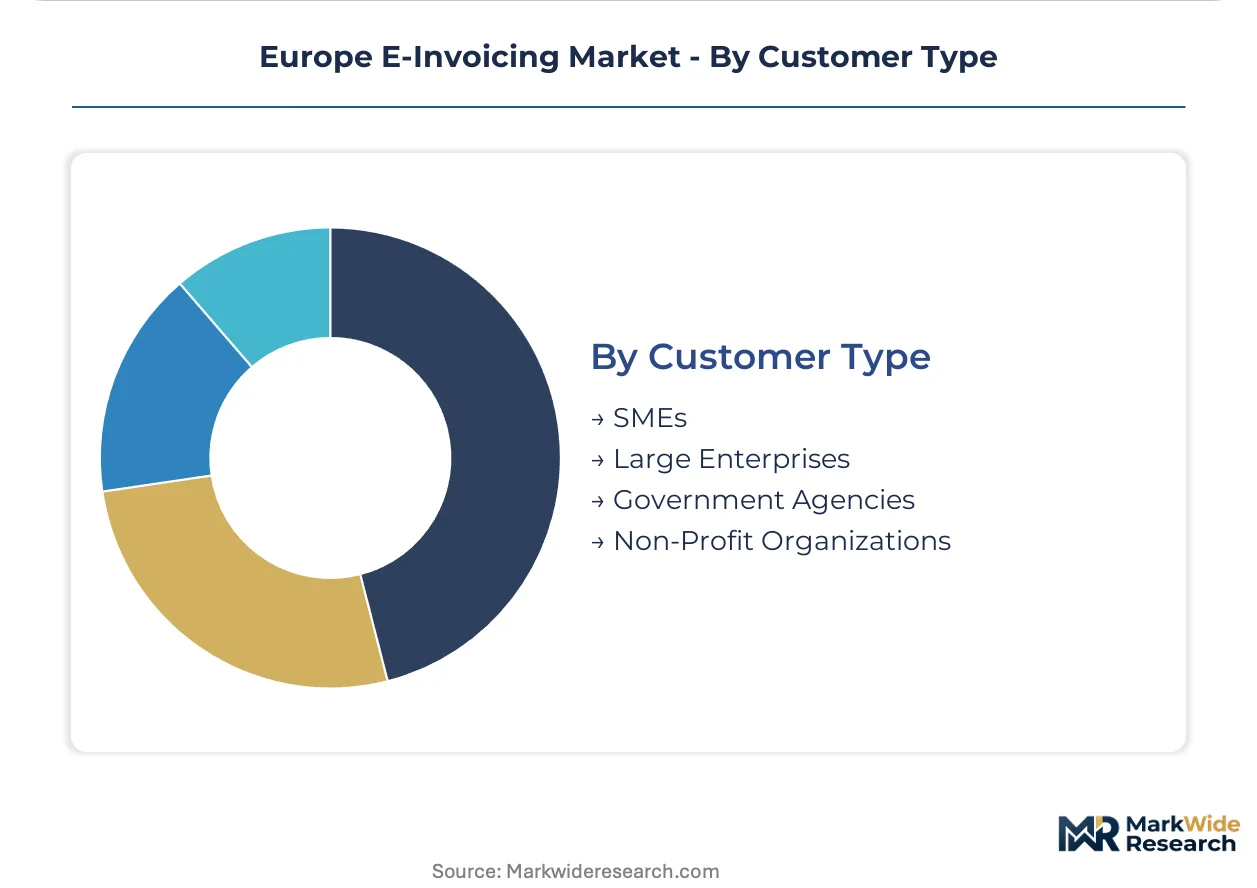
Customer Type:
Scale determines integration complexity and willingness to absorb implementation consulting costs.
- Large Enterprises:Global template deployments with multi-entity consolidation and intercompany netting capabilities. German automotive purchasing cooperatives and Nordic public procurement frameworks demand outcome-based contracting tied to working capital metrics.
- SMEs:Standardized PEPPOL access point subscriptions with pre-configured ERP connectors. France's phased B2B mandate and Germany's mid-market rollout create concentrated demand for low-touch onboarding.
- Government Agencies:Framework-compliant procurement with mandatory open standards and local data residency.
- Non-Profit Organizations:Grant-funded implementations prioritizing donor reporting transparency over transaction velocity.
Large Enterprises dominate spending today; SMEs are expanding most quickly as national mandates broaden addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive supply chains anchor regional demand as BMF mandate deadlines compress implementation timelines for mid-market enterprises. France and Italy follow with concentrated public sector procurement modernization and real-time VAT reporting requirements. Nordic markets exhibit mature PEPPOL network density, while Eastern European jurisdictions present underpenetrated SME segments.
Germany
Federal Ministry of Finance phased B2B mandates and automotive supplier compliance requirements drive platform adoption. The BMF's 2025-2027 rollout timeline compels S/4HANA-integrated document exchange across Baden-Württemberg and Bavaria manufacturing clusters. Stuttgart's supplier networks prioritize purchase-order matching embedded within invoice workflows to synchronize procurement modules.
France
DGFiP mandate sequencing and retail chain supplier onboarding requirements concentrate demand in cloud-native solutions. France's phased B2B obligation timeline creates urgency for standardized PEPPOL access point subscriptions among Île-de-France mid-market enterprises. Paris-based procurement consortia now demand outcome-based contracting tied to working capital optimization metrics.
Italy
Agenzia delle Entrate clearance model and real-time VAT reporting obligations sustain premium demand for automated tax engines. Italian banking networks require multi-jurisdiction audit trail capabilities compliant with EU AI Act documentation standards. Milan's financial services cluster anchors concentrated investment in algorithmic anomaly detection systems.
Poland
National tax authority digitization timelines and manufacturing supplier network expansion create implementation windows for compliance management tools. Polish real-time reporting schemes mirror Italian clearance architecture, elevating demand for continuous data stream capabilities. Warsaw's emerging procurement hubs attract PEPPOL access point providers seeking Central European anchor positions.
Sweden
Nordic public procurement framework compliance and mature PEPPOL network density sustain platform competition through access point differentiation. Swedish government agencies mandate open standards and local data residency for framework-compliant procurement. Stockholm's public sector digitization programs exhibit highest regional penetration of API-first invoice validation architectures.
Europe E-Invoicing Market Key Industry Players
Global majors compete with regional champions across compliance intensity and ERP integration depth. The vendor base stratifies between ERP-anchored platforms, PEPPOL-specialized access point providers, and accounts-payable automation specialists. Three archetypes dominate: enterprise resource planning extenders, network infrastructure operators, and financial workflow optimizers. Competitive moves concentrate on API-first platform development and jurisdiction-specific compliance module expansion.
Among ERP-anchored platforms, SAP SE exemplifies the enterprise extender archetype through S/4HANA installed base leverage. Pagero occupies a position within the network infrastructure tier, representing PEPPOL access point density strategies. Basware Corporation anchors the financial workflow optimizer segment, exemplifying specialization beyond invoice receipt into payment reconciliation capabilities.
| Leading Market Players |
|---|
| Coupa Software Inc. |
| Comarch SA |
| SAP SE |
| Pagero |
| Cegedim SA |
| Basware Corporation |
| International Business Machines Corporation |
| Esker SA |
| Tradeshift |
| Others |
Cost & Logistics Intelligence
German automotive purchasing cooperatives and Nordic public procurement frameworks concentrate demand for e-invoicing platforms, anchoring value-based pricing models tied to working capital outcomes rather than per-transaction fees. This buyer concentration shifts vendor engagement toward outcome-based contracts with guaranteed days-payable-outstanding improvements.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and PEPPOL access point certification fees shapes SaaS-tiered subscription models across the European market. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade compliance management with AI-Act documentation from mid-market PEPPOL connectivity bundles. Cost compression in the SME tier intensifies because of standardized onboarding automation and competing access point density. Manufacturing buyers exhibit highest price sensitivity due to margin pressure from automotive OEMs, while BFSI institutions absorb premium tiers for multi-jurisdiction audit capabilities.
Supply Chain Analysis
Reverse-logistics flows for data migration and legacy ERP decommissioning create secondary service revenue streams as enterprises transition from on-premise installations to cloud-native architectures. Platform development concentrates in Germany, Sweden, and Finland, with PEPPOL governance expertise clustering in Nordic markets and compliance engineering anchoring in German technology hubs. Raw material dependencies center on cloud compute capacity, API gateway infrastructure, and cryptographic certificate services. Single-source vulnerability runs through PEPPOL authority certification bottlenecks where national regulators control access point accreditation. Distribution runs through direct enterprise sales for large accounts and partner-channel networks for SME penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU ViDA reforms and country-level mandate sequencing generate recurring demand waves for compliance platform upgrades. Germany's BMF phased rollout anchors near-term demand concentration.
For Market Incumbents: To counter cloud-native entrants with API-first architectures, SAP SE and established ERP extenders should deepen S/4HANA integration moats while acquiring PEPPOL access point density in underpenetrated Eastern European markets. Certification investment in EU AI Act algorithmic transparency tooling creates defensive differentiation against modular compliance specialists. For New Entrants and Emerging Players: Capture first-mover positions in Romanian and Bulgarian SME segments where PEPPOL penetration remains minimal and localization barriers deter incumbent expansion. Romania's delayed mandate timeline presents the most penetrable geography for low-touch, pre-configured ERP connectors priced below German mid-market tiers. For Investors and Strategic Acquirers: Private equity firms with vertical software portfolios are the most active acquirer in this space, targeting compliance management specialists with recurring revenue anchored to real-time VAT reporting mandates. Acquisition candidates should demonstrate EN 16931 validation engine IP and jurisdiction-specific tax authority integrations. Monitor German BMF deadline enforcement rigor as the primary inflection signal for demand acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| PEPPOL Access Point Expansion | Certification in Poland and Romania captures Central European mandate windows ahead of competitors. |
| AI-Act Compliance Layer Development | Explainable anomaly detection tooling commands BFSI premium pricing under EU algorithmic transparency rules. |
| Embedded Finance Integration | Supply chain finance convergence transforms transaction processing into recurring working capital revenue streams. |
| Hybrid Cloud Architecture Investment | On-premise-to-cloud orchestration satisfies German automotive data sovereignty requirements without full displacement. |
| SME Onboarding Automation | Pre-configured ERP connectors reduce implementation timelines from quarters to weeks for France's mid-market rollout. |
Research Approach
Coverage spans Western Europe, Nordic markets, and Central Eastern Europe, with primary inputs from each regional cluster. The analysis combines structured interviews with ERP integration specialists, tax technology consultants, PEPPOL access point operators, and procurement directors at automotive purchasing cooperatives with secondary validation from EU ViDA regulatory filings, national tax authority mandate publications, and EN 16931 standardization committee documentation. Bottom-up platform deployment estimates triangulate against top-down addressable market calculations across cloud-native and on-premise segments.
Rate-of-change decomposition separates mandate-driven replacement demand from organic digital transformation across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, customer scale tier, and country-specific regulatory adoption phase. CAGRs derive from installed base erosion curves, mandate deadline sequencing, and PEPPOL network penetration trajectories. Industry-specific forecast inputs incorporate BMF implementation timeline adherence and Agenzia delle Entrate clearance model adoption rates.
Underlying measurement precision varies by segment; German and Italian markets carry tighter precision than Romanian and Bulgarian estimates due to regulatory transparency differences. Forecasts reflect assumptions around mandate enforcement consistency and PEPPOL governance centralization. Practitioners should monitor German BMF deadline delays, French DGFiP sequencing changes, and EU AI Act enforcement intensity for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Capital Restructuring Services Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Check Cashing Services Market
Financial Services
Germany Factoring Services Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Financial Advisory Services Market
Financial Services
Financial Services Software Market
Financial Services
Contract for Difference Broker Market
Financial Services
Global Alternative Data Market
Financial Services
Banking Cloud Services Market
Financial Services
E-KYC Market
Financial Services
Africa Factoring Services Market
Financial Services
China Financial Services Software Market
Financial Services
Germany E-Brokerage Market
Financial Services
South Korea Factoring Services Market