
 Global Process Equipment Market | 2026-2036
Global Process Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Process Equipment Market Outlook
Multi-source procurement for critical rotating machinery is pivoting toward consolidated vendor partnerships with engineering accountability. Emerson Electric leverages its automation-embedded valve portfolios to anchor long-term service contracts. Siemens competes through digital twin integration across pump and compressor fleets. GE sustains aftermarket dominance via predictive analytics tied to heavy-duty gas turbine auxiliaries.
Process equipment encompasses engineered machinery designed to transform, transport, or separate raw materials and intermediates through controlled physical or chemical operations, typically operating at pressures from vacuum to 10,000 psi and temperatures spanning cryogenic to 1,100°C. Heat exchangers represent the most mature product category with established margin pools in refurbishment cycles, while pumps command the largest installed base across upstream oil and gas. Mechanical technology still occupies the majority of capital expenditure, though thermal processing systems are gaining share in pharmaceutical sterilization and food pasteurization applications.
The EPA enforces emissions limits on compressor stations and process heaters under Clean Air Act New Source Performance Standards, while REACH in Europe mandates material disclosure for sealing compounds and gasket materials in valve assemblies. China's MEE implements dual carbon goals that force retrofits of thermal oxidizers and waste-heat recovery units. Stakeholders must monitor how carbon border adjustment mechanisms reshape equipment specification standards for export-bound manufacturing facilities.
Market Dynamics
Carbon border adjustment mechanisms are forcing export-oriented manufacturers to specify low-emission process equipment, compressing procurement cycles and elevating lifecycle assessment documentation above first-cost bidding.
Growth Catalysts
- EU F-Gas Regulation:Compressor emissions standards across member states are accelerating retrofit demand for hermetic and semi-hermetic systems in cold chain infrastructure.
- India's chemical corridor:Automated separation systems are scaling procurement around Dahej and Mundra as specialty chemical capacity expands.
- Waste-heat recovery:Thermal oxidizer retrofits tied to China's MEE dual carbon goals are displacing conventional combustion systems in steel and cement auxiliaries.
Market Restraints
- Specialty alloy concentration:Superalloy supply for high-pressure vessels concentrates in a limited supplier base, exposing procurement to nickel and cobalt price volatility.
- REACH material disclosure:Sealing compound and gasket documentation requirements add 12-18 months to valve assembly qualification timelines for European projects.
- Mechanical technology lock-in:Thermal processing systems face substitution pressure from microwave and radio-frequency sterilization in pharmaceutical applications.
Strategic Opportunities
- Saudi Arabia's giga-projects:Neom and Red Sea developments specify modular process skids with 40-year design life, opening premium fabrication contracts.
- Digital twin convergence:Physics-based simulation married to IoT sensor streams enables predictive maintenance contracts for rotating machinery fleets.
- US IRA clean manufacturing:Section 45X credits for domestic content are reshoring heat exchanger and pressure vessel fabrication to Gulf Coast ports.
Industry Challenges
- ASME Section VIII certification backlog:Inspector availability constraints are extending pressure vessel delivery schedules by 6-9 months.
- Legacy DCS integration:Brownfield automation retrofits require protocol translation layers that inflate commissioning costs and erode margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Process Equipment Market |
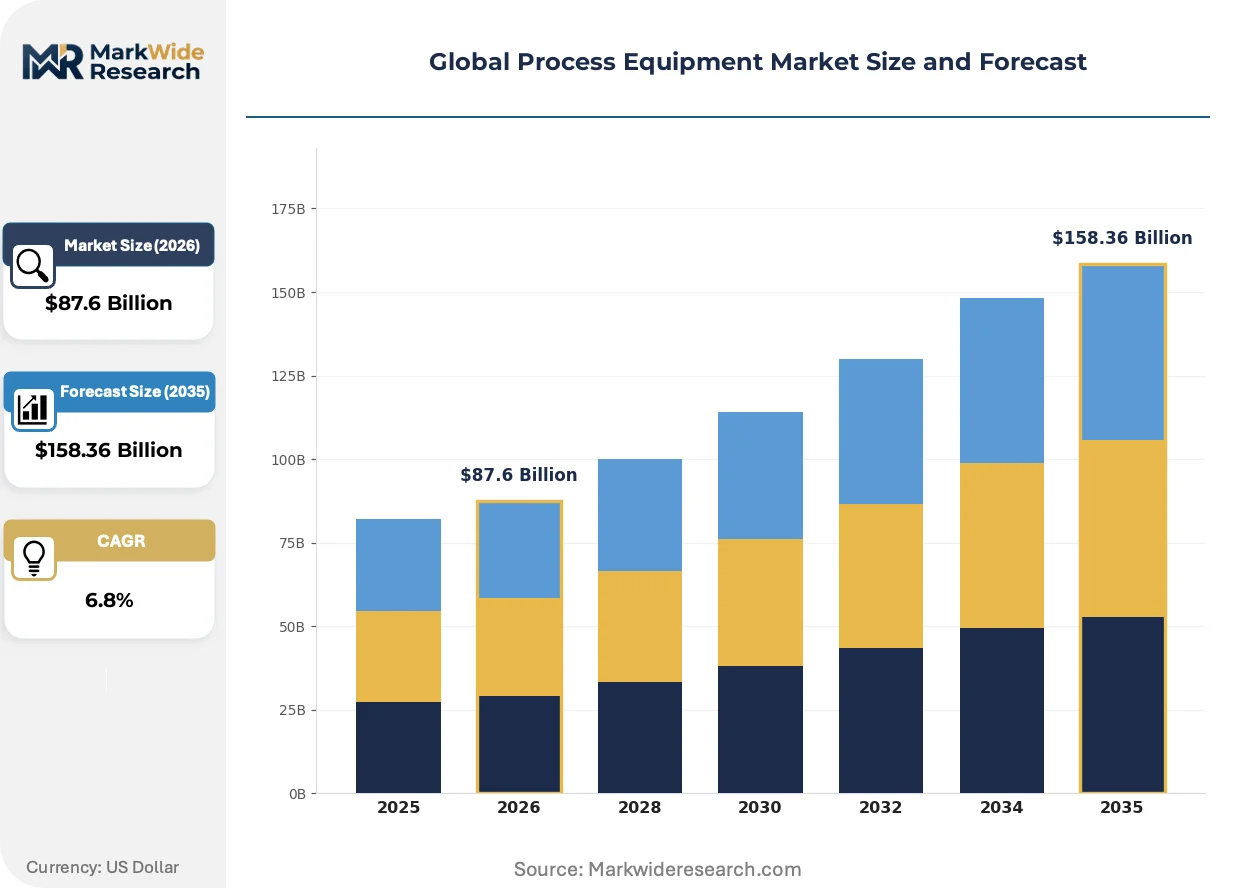
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Valves, Compressors, Heat Exchangers Technology: Mechanical, Electrical, Chemical, Thermal End User: Oil & Gas, Pharmaceuticals, Food & Beverage, Water Treatment Application: Material Handling, Mixing, Separation, Processing |
| Companies Covered | ANSYS, GE, Emerson Electric, FEECO International, Isgec Heavy Engineering, Gardner Denver, Caterpillar, Godrej & Boyce Manufacturing, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Process Equipment Market Strategic Shifts
Equipment intelligence is migrating from centralized control rooms to edge-embedded sensors, compressing response loops and unbundling traditional service contracts into performance-guaranteed subscriptions.
Magnetic bearing technology for centrifugal compressors is electrifying oil-free operation in petrochemical and LNG applications. Basell and QatarEnergy are specifying magnetic bearing trains for ethylene cracker charge gas compression. The elimination of lubrication systems is electrifying maintenance intervals from quarterly to biennial, collapsing aftermarket lubricant revenue pools.
REACH authorization requirements for chromium trioxide in hard chrome plating are forcing valve manufacturers to shift toward thermal spray coatings and laser cladding. The restriction affects ball valve stem and seat surfaces most acutely. German pump and valve specialists are responding with in-house coating facilities to preserve wear resistance without import dependency.
Lifecycle contracting is displacing capital purchase in water treatment and power generation auxiliaries. Veolia and Suez now procure membrane bioreactor skids on throughput-guaranteed terms rather than CAPEX. This compression is most visible in Australia's municipal desalination expansion, where state water authorities demand 20-year availability commitments bundled into single-vendor responsibility.
Global Process Equipment Market Segmentation
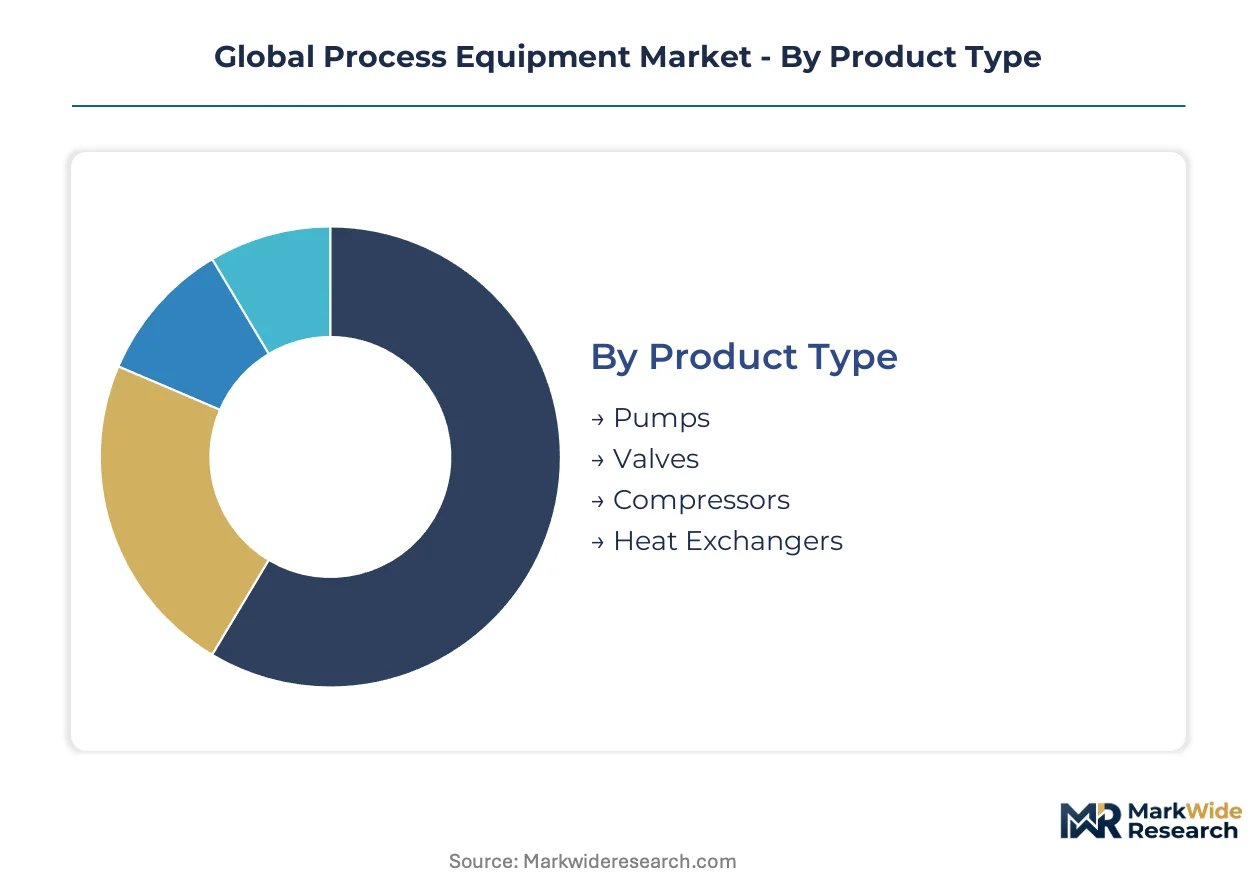
Process equipment procurement diverges sharply between standardized commodity units and engineered-to-order systems requiring ASME certification. Specification complexity cascades through technology choices, end-use requirements, and application intensity, fragmenting vendor strategies across margin tiers.
Product Type:
Standardization ranges from catalog pumps to fully custom pressure vessels with project-specific metallurgy.
- Pumps:Centrifugal and positive displacement designs dominate upstream oil and gas installations across the Permian Basin and North Sea. Procurement concentrates in API 610 and API 674 specification grades for reliability-critical services.
- Valves:Control, isolation, and safety relief configurations span cryogenic LNG terminals to supercritical steam conditions. REACH authorization pressures on chromium trioxide plating are accelerating thermal spray coating adoption for ball valve stems.
- Compressors:Reciprocating and centrifugal trains handle process gases from ethylene crackers to hydrogen pipelines. Magnetic bearing electrification is displacing oil-lubricated systems in Basell and QatarEnergy ethylene facilities.
- Heat Exchangers:Shell-and-tube, plate, and printed circuit architectures recover thermal energy across refining and chemical complexes. Refurbishment cycles sustain aftermarket margin pools in mature installed bases.
Most installed capacity flows through Pumps. Expansion is steepest in Compressors.
Technology:
Capital allocation tilts toward electrification and precision thermal control as carbon intensity disclosure tightens.
- Mechanical:Rotating machinery and pressure-boundary equipment still commands the majority of capital expenditure through established reliability engineering. India's chemical corridor at Dahej and Mundra scales automated separation systems using mechanical drive trains.
- Electrical:Variable frequency drives, magnetic bearings, and edge-embedded sensors compress response loops and enable predictive maintenance subscriptions. Electrification of compressor auxiliaries eliminates lubrication systems and collapses quarterly maintenance to biennial intervals.
- Chemical:Catalytic reactors, electrochemical cells, and membrane systems transform feedstocks through controlled molecular conversion. Pharmaceutical API manufacturing specifies electrochemical flow reactors for continuous processing.
- Thermal:Thermal oxidizers, waste-heat recovery units, and sterilization systems face substitution pressure from microwave and radio-frequency alternatives. China's MEE dual carbon goals force retrofits in steel and cement auxiliaries.
Mechanical technology anchors current installed value. Thermal systems are gaining share fastest in pharmaceutical sterilization and food pasteurization.
End User:
End-use intensity varies from continuous-process refining to batch-mode pharmaceutical manufacturing with validation requirements.
- Oil & Gas:Upstream production, midstream transport, and downstream refining demand pressure-rated equipment for hydrocarbon containment. Saudi Arabia's Neom and Red Sea giga-projects specify modular process skids with 40-year design life.
- Pharmaceuticals:Aseptic processing, containment, and sterilization systems require FDA and EMA validation documentation. Microwave sterilization is displacing conventional thermal processing in parenteral drug manufacturing.
- Food & Beverage:Pasteurization, mixing, and clean-in-place systems balance hygienic design against energy efficiency. High-pressure processing equipment extends shelf life without thermal degradation.
- Water Treatment:Membrane bioreactors, disinfection systems, and desalination trains shift toward lifecycle contracting. Australian state water authorities demand 20-year availability commitments bundled into single-vendor responsibility.
Oil & Gas retains the largest equipment installed base. Water Treatment is shifting procurement fastest toward throughput-guaranteed performance contracts.
Application:
Application complexity scales from bulk solids handling to precision separation with purity specifications.
- Material Handling:Pneumatic conveying, pumping, and solids transport systems move raw materials and intermediates through continuous processes. Dense-phase conveying reduces attrition in catalyst and polymer pellet systems.
- Mixing:Static, dynamic, and multiphase blending equipment achieves compositional uniformity for reaction kinetics. High-shear mixers disperse nanomaterials in battery electrolyte production.
- Separation:Distillation, filtration, centrifugation, and membrane systems isolate product streams from complex mixtures. Automated separation systems scale procurement around India's Dahej specialty chemical expansion.
- Processing:Reaction, crystallization, and thermal treatment units execute the core chemical and physical transformations. Continuous processing equipment displaces batch systems in pharmaceutical active ingredient manufacturing.
Material Handling commands the broadest cross-industry deployment. Separation is climbing the fastest as specialty chemical and bioprocessing purity requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen and Leverkusen anchor the densest concentration of process equipment procurement in Europe, with chemical conglomerates driving demand for high-pressure vessels and automated separation systems. The regional distribution reflects regulatory stringency, feedstock access, and export manufacturing intensity across major industrial economies.
Germany
Specialty chemical expansion around Ludwigshafen and Leverkusen sustains demand for ASME-certified pressure vessels and magnetic bearing compressor trains. The EU F-Gas Regulation tightens emissions standards for hermetic systems in cold chain infrastructure. REACH authorization pressures on chromium trioxide plating force valve manufacturers toward thermal spray coating in-house production.
United States
Permian Basin upstream operations and Gulf Coast refinery expansions concentrate procurement of API 610 centrifugal pumps and heavy-duty gas turbine auxiliaries. EPA Clean Air Act New Source Performance Standards enforce emissions limits on compressor stations and process heaters. Section 45X domestic content credits under the IRA reshore heat exchanger fabrication to Texas and Louisiana port facilities.
China
Steel and cement auxiliary retrofits dominate demand for waste-heat recovery units and thermal oxidizers as MEE dual carbon goals tighten enforcement. GB standards and SAMR certification requirements extend equipment qualification timelines. The Yangtze River Delta chemical corridor scales procurement of automated separation systems for specialty polymer production.
India
Dahej and Mundra specialty chemical capacity expansion drives procurement of mechanical drive separation systems and modular process skids. BIS certification and PLI scheme incentives accelerate localization of pump and valve manufacturing. Gujarat's industrial corridor concentrates fabrication contracts for export-oriented pharmaceutical API processing equipment.
Saudi Arabia
Neom and Red Sea giga-projects specify modular process skids with 40-year design life, opening premium fabrication contracts for pressure-boundary equipment. SFDA pharmaceutical regulations and dual carbon commitments shape equipment specification standards. The Eastern Province petrochemical complex sustains demand for ethylene cracker charge gas compression systems.
Global Process Equipment Market Competitive Environment
Global majors compete with regional champions across engineering accountability and lifecycle service contracting. The vendor base stratifies into three tiers: integrated automation-electrical conglomerates with digital twin capabilities, mid-scale fabrication specialists with ASME certification depth, and regional champions serving protected domestic procurement. Competitive moves center on consolidated vendor partnerships replacing multi-source procurement, and predictive maintenance subscriptions displacing traditional service contracts.
Within the integrated automation tier, Emerson Electric and Siemens exemplify the convergence of control systems with rotating machinery portfolios. GE occupies a position anchoring aftermarket dominance through predictive analytics tied to heavy-duty gas turbine auxiliaries. Among India-based fabricators, Isgec Heavy Engineering and Godrej & Boyce Manufacturing represent regional champions with captive ASME Section VIII certification capabilities serving domestic chemical and pharmaceutical demand.
| Leading Market Players |
|---|
| ANSYS |
| GE |
| Emerson Electric |
| FEECO International |
| Isgec Heavy Engineering |
| Gardner Denver |
| Caterpillar |
| Godrej & Boyce Manufacturing |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation mandates on hermetic compressor retrofits are compressing procurement cycles and forcing supply chains toward low-leakage component certification, elevating lifecycle documentation above first-cost bidding and redistributing margin toward qualified fabricators.
Pricing Analysis
Input-cost pass-through from nickel and cobalt superalloy volatility anchors pricing dynamics for ASME-certified pressure vessels. Three-tier pricing structure across premium, standard, and economy levels separates long-life modular skids from catalog pumps and refurbished heat exchangers. Cost compression in standard-grade mechanical equipment is intensifying because Indian and Chinese fabricators are scaling BIS and GB-certified production. Municipal water authorities exhibit the highest price sensitivity due to lifecycle contracting mandates, while Saudi giga-project developers absorb premium pricing for 40-year design-life specifications.
Supply Chain Analysis
Refurbishment flows for heat exchanger tube bundles and compressor seal cartridges are creating reverse-logistics value pools that captive service networks now capture. Manufacturing concentrates in Germany, the United States, and China, with Ludwigshafen and Gulf Coast port facilities anchoring high-pressure vessel fabrication. Supply chains draw from specialty alloy feedstock tied to Australian and Indonesian nickel mining. Single-source vulnerability concentrates in magnetic bearing and precision coating equipment. Distribution runs through EPC contractors and OEM aftermarket service organizations rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Section 45X domestic content credits in the United States offset REACH-driven cost inflation in European fabrication, redirecting capital toward Gulf Coast port facilities.
For Market Incumbents: Deepen captive ASME Section VIII certification capabilities to defend against Indian and Chinese regional champions capturing mid-tier procurement. Anchor long-term service contracts through predictive analytics integration. Prioritize in-house thermal spray coating facilities to eliminate chromium trioxide import dependency under REACH authorization pressures. For New Entrants and Emerging Players: Australian state water authorities represent an underserved buyer archetype demanding throughput-guaranteed membrane bioreactor contracts with 20-year availability commitments. Target pharmaceutical API processing equipment in Gujarat's industrial corridor where BIS certification and PLI incentives accelerate localization. Enter through modular skid partnerships with established EPC contractors rather than direct OEM competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale fabricators possessing captive ASME certification and magnetic bearing integration capabilities. Long-term viability hinges on digital twin convergence and lifecycle contracting displacement of capital purchase. Monitor ASME Section VIII inspector availability constraints as an inflection indicator for delivery schedule premiums and pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Captive nickel and cobalt supply hedges price volatility for ASME-certified pressure vessel production. |
| Digital Twin Platform Development | Physics-based simulation married to IoT sensor streams enables predictive maintenance subscription revenue. |
| Magnetic Bearing Technology Adoption | Oil-free compressor operation collapses maintenance intervals and eliminates lubricant aftermarket revenue pools. |
| Lifecycle Contracting Transition | Throughput-guaranteed terms displace capital purchase in water treatment and power generation auxiliaries. |
| Regional Certification Investment | BIS, GB, and SAMR qualification accelerates localization in India and China chemical corridors. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads were validated against secondary sources including customs and trade data, SEC 10-K filings, and ACC and Cefic industry reports. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Historical trendline analysis of installed base refurbishment cycles and capacity expansion announcements informed projection frameworks across the analysis window. Segmentation dimensions include product type, technology class, end-use intensity, and regional regulatory cluster. CAGRs were derived from elasticity modeling of capital expenditure patterns and substitution dynamics between mechanical and thermal processing systems. Forecast inputs incorporate ASME certification backlog data and magnetic bearing adoption curves in ethylene cracker applications.
Underlying measurement precision varies by segment; standardized pumps and catalog valves carry tighter precision than engineered-to-order pressure vessels with project-specific metallurgy. Forecasts reflect assumptions around carbon border adjustment mechanism enforcement and dual carbon goal implementation timelines. Practitioners should monitor nickel and cobalt price volatility, ASME inspector availability, and REACH authorization timelines for chromium trioxide alternatives as early signals requiring forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Heavy Duty Vacuum Bottle Market
Others
Printed Leather Market
Others
Global Phablets and Superphones Market
Others
Mini Pcs Market
Others
Industrial Personal Computer Market
Others
Infant Fever Stickers Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Global Solder Balls Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Paper Shredder Market
Others
Duty Free Retail Market
Others
Global Virtual Keyboard Market
Others
Hotel Wardrobe Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Lined Tank Market
Others
Embedded Computer Market