
 Magnesium Lactate Market | 2026-2036
Magnesium Lactate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Lactate Market Analytics
Chinese specialty chemical producers are expanding magnesium lactate capacity to serve pharmaceutical and food additive buyers across Asia and Europe. Corbion N.V. leverages its fermentation expertise to sustain consistent supply of high-purity grades for nutraceutical applications. Jost Chemical Company anchors North American supply through its FDA-registered specialty mineral compounds. Jungbunzlauer Suisse AG competes on citrate and lactate salt technology leadership, extending its organic acid platform into magnesium nutrition.
Magnesium lactate is the magnesium salt of lactic acid, typically supplied as a white crystalline powder with a magnesium content of approximately 8-10 percent by weight, produced through neutralization of lactic acid with magnesium carbonate or hydroxide. It functions primarily as a highly bioavailable mineral fortifier in dietary supplements, a pH buffer in pharmaceutical formulations, and a skin-conditioning agent in cosmetic preparations. Pharmaceutical-grade material commands premium positioning due to USP and EP compliance requirements, while food-grade volumes dominate tonnage through bakery and beverage fortification. Nutritional supplements represent the fastest-expanding application as consumers shift toward chelated mineral formats over inorganic salts.
The FDA's food additive regulations and USP monographs govern magnesium lactate purity thresholds for ingestible and injectable uses, while REACH registration requirements in Europe restrict non-compliant industrial imports. EFSA health claim authorization processes shape how dietary supplement companies position magnesium lactate in consumer marketing. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as diverging specifications threaten to fragment batch certification costs and complicate multi-regional supply strategies.
Market Dynamics
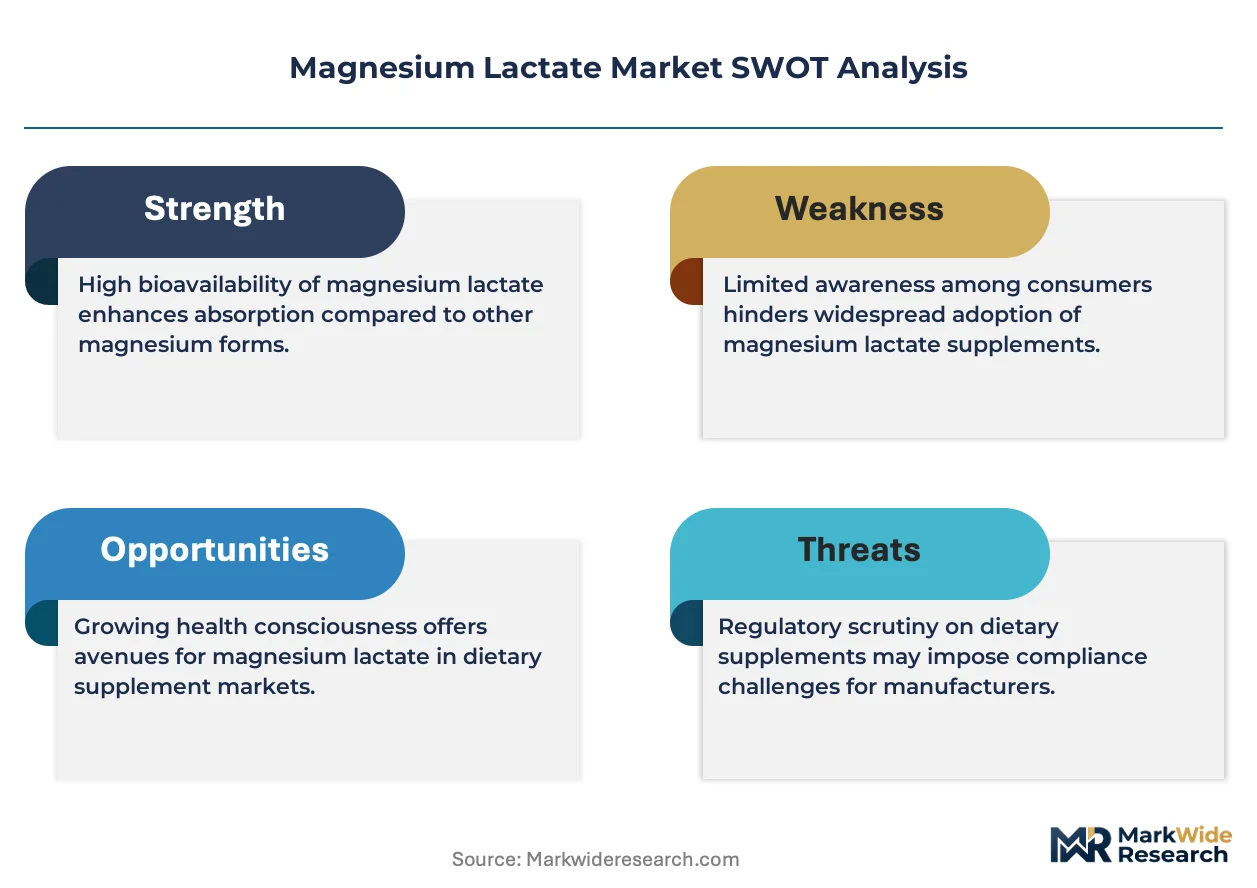
Pharmaceutical-grade certification requirements are fragmenting supplier economics as USP, EP, and JP monographs diverge on heavy metal limits and microbial specifications, forcing multi-regional producers to maintain parallel quality systems.
Growth Catalysts
- EFSA Health Claim Pathways:The EU's novel food authorization framework is accelerating magnesium lactate inclusion in fortified beverages and infant nutrition, expanding addressable food-grade volume.
- Chelated Mineral Preference Shift:Nutraceutical formulators are substituting magnesium oxide and sulfate with magnesium lactate to improve gastrointestinal tolerability and absorption kinetics in aging populations.
- German Pharmaceutical Cluster Density:Concentrated specialty chemical infrastructure around Ludwigshafen and Leverkusen reduces logistics costs for pharmaceutical-grade lactate salts serving European compounding pharmacies.
Market Restraints
- Lactic Acid Feedstock Volatility:Fermentation-derived lactic acid prices fluctuate with corn starch and sugar beet availability, compressing magnesium lactate margins during agricultural commodity spikes.
- Chinese Capacity Concentration:Over 60 percent of food-grade magnesium lactate fermentation capacity sits in Shandong and Jiangsu provinces, creating single-geography supply vulnerability for Asian and European buyers.
- Magnesium Citrate Substitution:Jungbunzlauer and other organic acid specialists promote magnesium citrate as a direct competitor with comparable bioavailability and superior solubility in effervescent formats.
Strategic Opportunities
- Indian Dietary Supplement Formalization:FSSAI's tightening standards for mineral fortification are displacing unorganized magnesium oxide suppliers, creating structured demand for USP-grade magnesium lactate in Mumbai and Hyderabad formulation hubs.
- Cosmeceutical Skin Barrier Applications:Magnesium lactate's humectant and keratolytic properties are penetrating dermatological skincare lines as an alternative to urea and lactic acid alone in atopic dermatitis formulations.
- Japan's Specified Health Food System:PMDA and Consumer Affairs Agency pathways for mineral-functional claims favor documented bioavailability data, advantaging chelated magnesium salts over inorganic competitors in aging-care product development.
Industry Challenges
- Pharmacopeial Harmonization Delays:Diverging USP-NF and EP heavy metal testing methodologies force redundant laboratory validation, extending batch release timelines for multi-regional suppliers.
- Continuous Fermentation Scale-Up:Transitioning from batch to continuous lactic acid fermentation requires capital-intensive bioreactor retrofitting that mid-cap magnesium lactate producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Lactate Market |
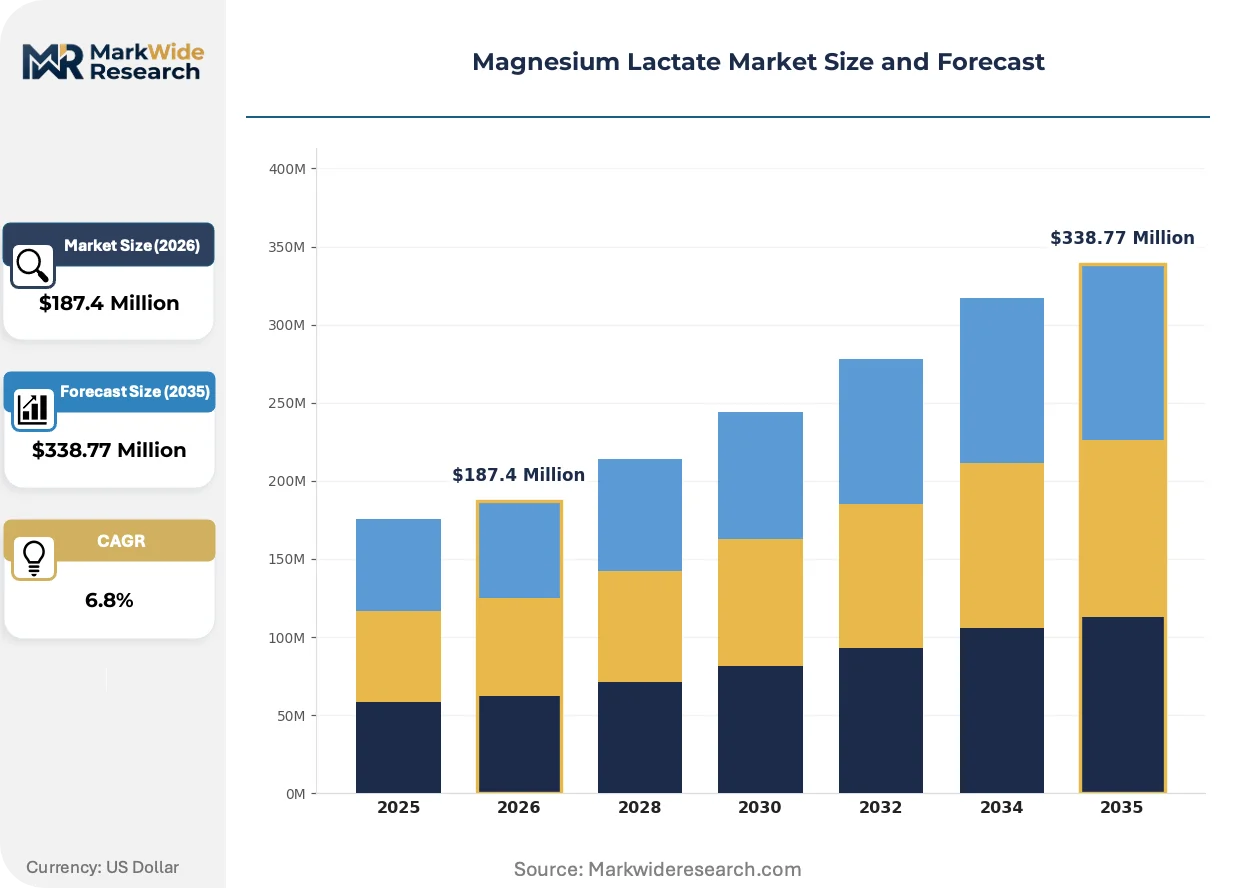
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Nutritional Supplements, Food Additives, Pharmaceuticals, Personal Care Products End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Dietary Supplement Companies Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wholesale Distributors |
| Companies Covered | Merck KGaA, Corbion N.V., Jost Chemical Company, Gadot Biochemical Industries Ltd., Dr. Paul Lohmann GmbH KG, Hawkins, Inc., Jungbunzlauer Suisse AG, Shijiazhuang Donghua Jinlong Chemical Co., Ltd., Nutraceutical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Lactate Market Evolving Landscape
Process intensification and regulatory data requirements are reshaping how magnesium lactate manufacturers compete on purity documentation and supply chain transparency rather than commodity scale alone.
Continuous chromatographic purification is modularizing pharmaceutical-grade magnesium lactate production by enabling smaller-batch, higher-purity output without dedicated crystallization infrastructure. Specialty chemical producers in Switzerland and Germany are adopting this to serve orphan drug formulators requiring sub-ppm heavy metal specifications. The technology is compressing minimum efficient scale thresholds, allowing regional players to contest premium segments previously captured by integrated fermentation giants.
REACH registration dossier updates under ECHA's 2023 substance evaluation work program are tightening reproductive toxicity data requirements for magnesium salts used in food contact materials. This regulatory pressure is accelerating toxicology investment among European suppliers while excluding non-registered importers from pharmaceutical excipient qualification. German and Dutch compounders now demand extended safety data packages that Chinese exporters struggle to assemble.
Direct-to-brand mineral sourcing is disrupting traditional distributor-mediated procurement in North American nutraceuticals. Supplement brands in Utah and California are establishing direct quality agreements with Jost Chemical and Corbion, bypassing chemical distributors to secure lot-specific certificates of analysis and audit rights. This channel compression is most visible in the sports nutrition vertical, where formulation speed and traceability claims outweigh distributor inventory convenience.
Magnesium Lactate Market Segmentation
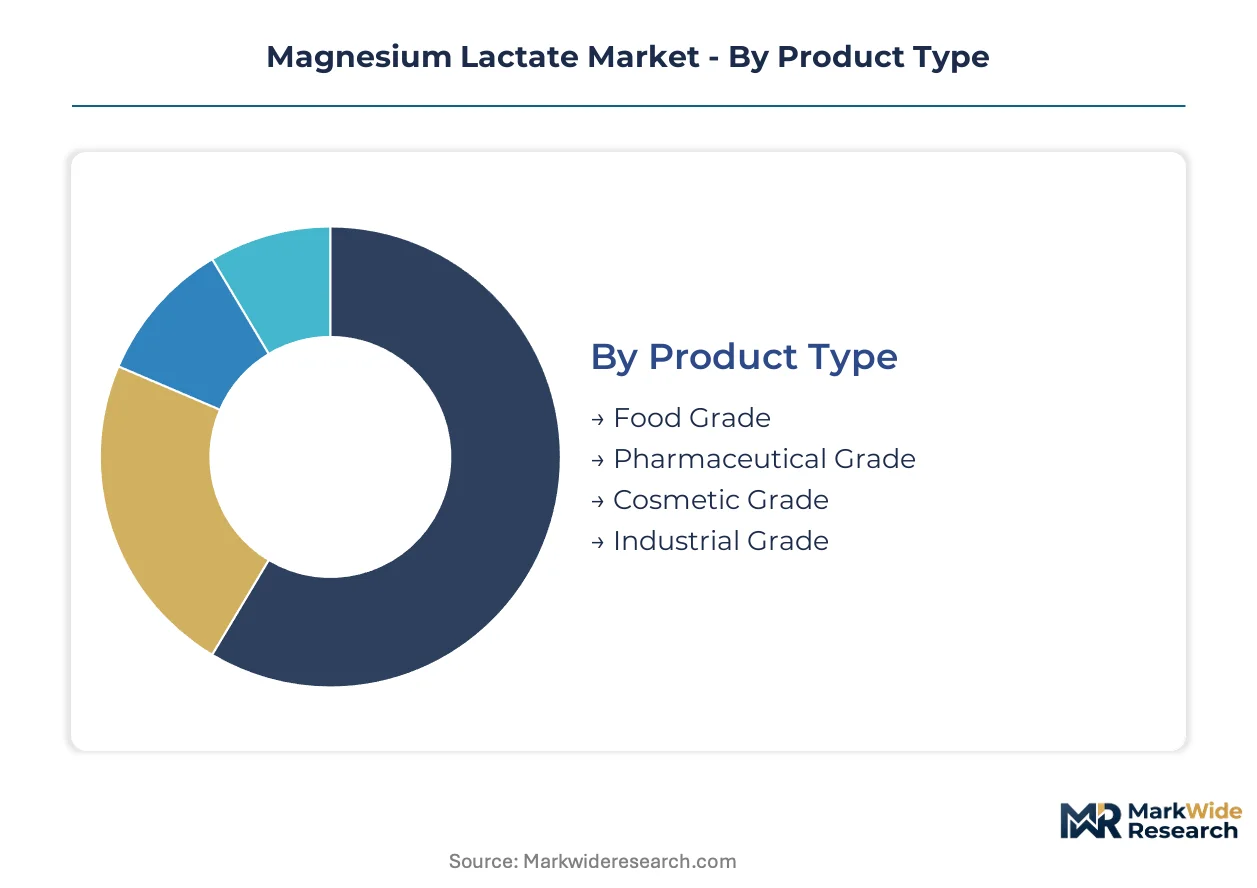
Magnesium lactate procurement splits sharply across certification tiers, with pharmaceutical and food-grade specifications commanding divergent supply chains and pricing structures. Buyers segment suppliers by monograph compliance rather than commodity chemistry, creating distinct competitive arenas within what appears chemically homogeneous.
Product Type:
Purity thresholds and regulatory documentation requirements determine supplier selection and margin capture across grades.
- Food Grade:Complies with FCC and JECFA specifications for heavy metals and microbial limits, typically supplied in bulk crystalline form for bakery and beverage fortification. Demand concentrates in German and Dutch food compounders seeking EFSA-compliant mineral fortification for infant nutrition and functional beverages, constrained by REACH registration requirements that exclude non-European suppliers from pharmaceutical-adjacent food contact applications.
- Pharmaceutical Grade:Meets USP-NF, EP, and JP monographs with sub-ppm heavy metal certification and validated microbial specifications, produced through dedicated fermentation trains with chromatographic finishing. German compounding pharmacies and US FDA-registered facilities in St. Louis drive specification intensity as injectable and high-dosage oral formulations demand batch-specific certificates of analysis.
- Cosmetic Grade:Satisfies EC 1223/2009 cosmetic safety standards with documented dermal irritation profiles, supplied to Swiss and French dermatological skincare formulators.
- Industrial Grade:Serves non-ingestible applications including polymer stabilization and metal surface treatment with relaxed purity specifications.
Food Grade leads on scale; Pharmaceutical Grade leads on momentum.
Application:
End-use functionality determines formulation compatibility and bioavailability positioning in finished goods.
- Nutritional Supplements:Chelated mineral formats displace magnesium oxide in aging-population formulations seeking gastrointestinal tolerability, with Utah and California sports nutrition brands establishing direct supplier relationships for lot traceability.
- Food Additives:pH buffering and mineral fortification in bakery, beverages, and infant formula governed by EFSA health claim authorization processes in Europe and FDA food additive regulations in the US.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient uses in antacid, laxative, and mineral replacement therapies requiring multi-pharmacopeia compliance.
- Personal Care Products:Humectant and keratolytic applications in atopic dermatitis formulations competing with urea and lactic acid alternatives.
Nutritional Supplements climb the fastest; Food Additives anchor volume.
End User:
Procurement sophistication and quality system requirements separate buyer tiers.
- Healthcare Providers:Hospital systems and specialty pharmacies in Germany and the US demanding validated supply chains for parenteral nutrition and electrolyte replacement therapies.
- Food Manufacturers:Multinational fortification programs in Mumbai and Hyderabad formulation hubs displacing unorganized mineral suppliers under tightening FSSAI standards.
- Cosmetic Companies:Dermatological skincare lines in Switzerland and France incorporating magnesium lactate as alternative to urea in barrier repair formulations.
- Dietary Supplement Companies:Direct-to-brand sourcing by Utah and California sports nutrition brands compressing distributor margins in favor of supplier audit rights.
Food Manufacturers dominate tonnage; Dietary Supplement Companies reshape procurement patterns.
Distribution Channel:
Channel selection reflects urgency, lot size, and documentation requirements.
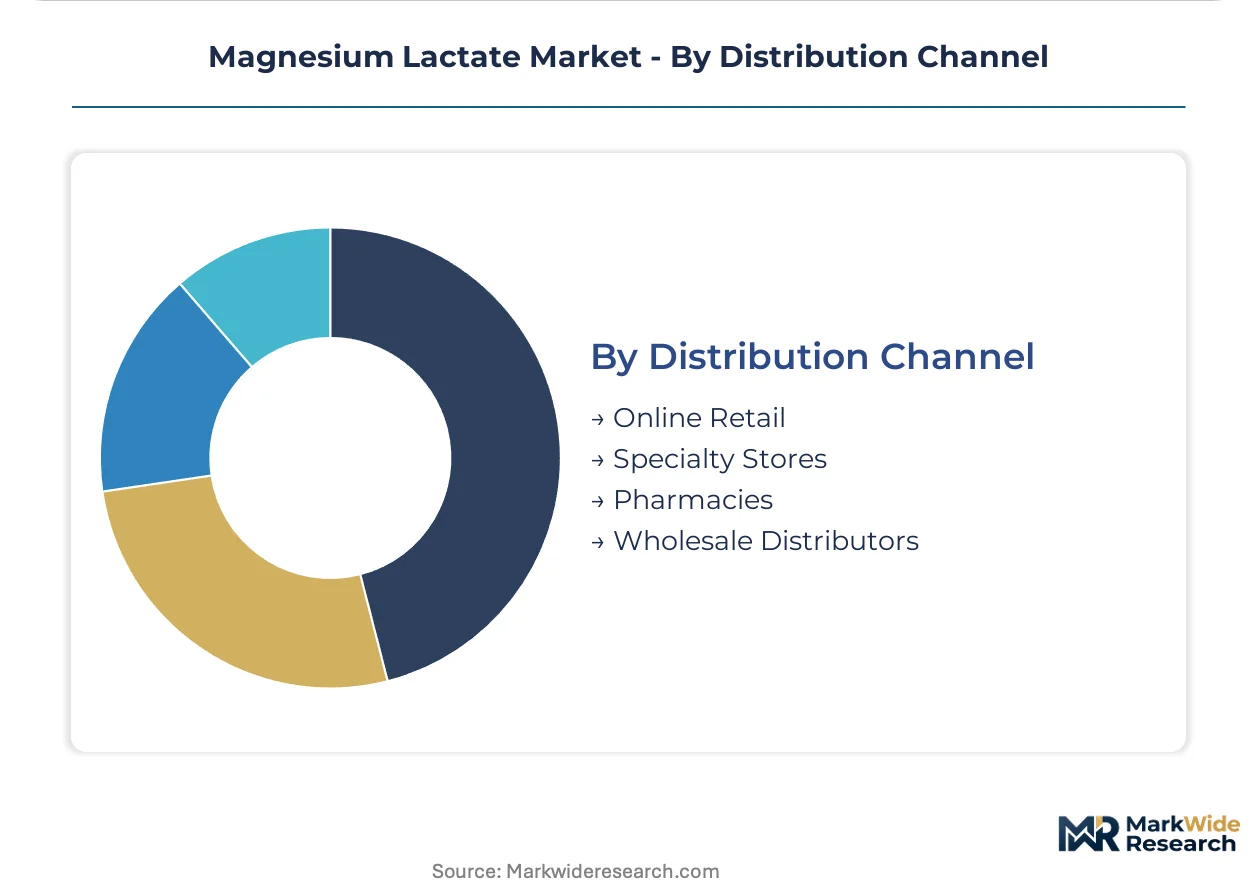
- Online Retail:E-commerce platforms serving small-scale nutraceutical formulators and research institutions with rapid fulfillment and certificate of analysis access.
- Specialty Stores:Regional chemical distributors in Leverkusen and Ludwigshafen serving German pharmaceutical compounders with just-in-time delivery.
- Pharmacies:Hospital and retail pharmacy procurement for prescription mineral supplements and electrolyte therapies.
- Wholesale Distributors:Traditional bulk chemical distribution facing margin compression as direct supplier relationships proliferate.
Wholesale Distributors retain volume; Online Retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration follows divergent compliance costs. Chinese fermentation capacity serves price-sensitive food-grade buyers while European facilities absorb REACH toxicology investments to retain pharmaceutical access.
China
Shandong and Jiangsu provinces concentrate over sixty percent of food-grade fermentation capacity. SAMR's tightening food additive standards are displacing unorganized producers. Qingdao specialty chemical clusters are upgrading USP-grade lines to capture Indian and Southeast Asian pharmaceutical demand.
Germany
Ludwigshafen and Leverkusen specialty chemical infrastructure anchors European pharmaceutical-grade supply. ECHA's 2023 substance evaluation work program is forcing reproductive toxicity data investments. Bavarian compounding pharmacies are consolidating procurement around multi-pharmacopeia certified suppliers.
United States
Utah and California sports nutrition brands are compressing distribution channels through direct supplier relationships. FDA food additive regulations and USP-NF monographs govern ingestible purity thresholds. St. Louis FDA-registered facilities are expanding chromatographic finishing capacity for injectable-grade output.
India
Mumbai and Hyderabad formulation hubs are displacing unorganized magnesium oxide suppliers under tightening FSSAI standards. FSSAI's mineral fortification rules are creating structured demand for USP-grade material. Gujarat specialty chemical producers are retrofitting fermentation trains to serve domestic dietary supplement formalization.
Switzerland
Swiss dermatological skincare formulators are incorporating magnesium lactate for atopic dermatitis applications. Swissmedic cosmetic safety requirements exceed EC 1223/2009 baselines. Basel-area organic acid technology clusters are extending citrate and lactate salt platforms into mineral nutrition.
Magnesium Lactate Market Competitive Landscape
Chinese producers anchor the volume tier; European and North American specialists hold the premium certification tier. The vendor base splits between fermentation-integrated giants and regional compounders with chromatographic finishing capabilities. Three archetypes dominate: integrated fermentation platforms, specialty mineral compounders with pharmacopeia expertise, and regional chemical distributors upgrading quality systems. Capacity expansion and direct-to-brand procurement compression represent the dominant competitive vectors.
Within the integrated fermentation tier, Corbion N.V. and Jungbunzlauer Suisse AG exemplify organic acid platform extension into magnesium nutrition. Jost Chemical Company occupies a position among North American specialty mineral compounders with FDA-registered infrastructure. These three anchors illustrate how geographic specialization and certification depth determine tier placement.
| Leading Market Players |
|---|
| Merck KGaA |
| Corbion N.V. |
| Jost Chemical Company |
| Gadot Biochemical Industries Ltd. |
| Dr. Paul Lohmann GmbH KG |
| Hawkins, Inc. |
| Jungbunzlauer Suisse AG |
| Shijiazhuang Donghua Jinlong Chemical Co., Ltd. |
| Nutraceutical Corporation |
| Others |
Value Network & Pricing Analysis
Captive fermentation integration across Shandong and Jiangsu provinces anchors Chinese producers' cost position in food-grade magnesium lactate while simultaneously constraining their pricing power in pharmaceutical segments where REACH registration and USP certification investments create European and North American margin premiums.
Pricing Analysis
Distributor margin compression in North American nutraceutical procurement is accelerating direct-to-brand contracting as Utah and California sports nutrition companies bypass wholesale channels for lot-specific certificates of analysis. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates USP-certified material commanding audit-premiums from FCC-compliant bulk crystalline facing agricultural commodity pass-through. Cost compression in food-grade runs through lactic acid feedstock volatility tied to corn starch and sugar beet harvests. Healthcare providers exhibit lowest price sensitivity due to validated supply chain requirements for parenteral nutrition, while commodity food compounders negotiate aggressively on volume.
Supply Chain Analysis
Specialized fermentation workforce availability in Ludwigshafen and Leverkusen underpins German pharmaceutical-grade production quality, while comparable technical labor pools in Gujarat and Maharashtra feed Indian capacity expansion. Supply concentrates in China for food-grade fermentation, Germany for pharmaceutical finishing, and India for emerging dietary supplement formalization. Raw material dependencies center on fermentation-derived lactic acid, magnesium carbonate or hydroxide neutralizing agents, and chromatographic purification resins. Single-geography concentration in Shandong and Jiangsu provinces creates vulnerability for Asian and European buyers. Distribution runs through direct quality agreements for premium grades and wholesale chemical distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnesium lactate procurement functions as a geographic-arbitrage play between REACH-registered European pharmaceutical-grade premiums and Chinese food-grade scale economics, with regulatory compliance cost differentials exceeding manufacturing cost differentials across the Atlantic.
For Market Incumbents: Deepen chromatographic finishing capabilities in FDA-registered St. Louis and Ludwigshafen facilities to defend pharmaceutical-grade positioning against Chinese USP-line upgrades. Prioritize multi-pharmacopeia certification investments as USP-NF and EP divergence threatens batch release economics. Secure captive lactic acid supply through backward integration into fermentation or long-term offtake agreements with Corbion and Jungbunzlauer to buffer agricultural commodity volatility. For New Entrants and Emerging Players: Direct-to-brand e-commerce channels offer the lowest friction entry path for small-batch pharmaceutical-grade magnesium lactate serving orphan drug formulators and research institutions. Target cosmeceutical skin barrier applications in Swiss and French dermatological markets where magnesium lactate displaces urea in atopic dermatitis formulations. Penetrate Indian dietary supplement formalization under tightening FSSAI standards by offering USP-grade material with documented bioavailability data against incumbent magnesium oxide suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional specialty mineral compounders with pharmacopeia expertise because certification depth and audit relationships constitute transferable intangible assets across magnesium, calcium, and zinc salt portfolios. Mid-cap targets with existing USP-NF and EP compliance infrastructure offer superior long-term viability than greenfield capacity in an environment of tightening ECHA reproductive toxicity requirements. Monitor EFSA health claim authorization velocity for magnesium-functional positioning as the signal indicating premium-grade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive supply of fermentation-derived lactic acid insulates margins from agricultural commodity spikes in corn starch markets. |
| Multi-Pharmacopeia Certification Investment | Parallel USP-NF, EP, and JP compliance enables single-batch release across German, US, and Japanese pharmaceutical customers. |
| Direct-to-Brand Quality Agreements | Bypassing wholesale distributors secures lot traceability premiums from Utah and California sports nutrition formulators. |
| Continuous Chromatographic Purification Scale-Up | Modular finishing technology compresses minimum efficient scale thresholds for orphan drug-grade production. |
| REACH Registration Dossier Enhancement | Extended reproductive toxicity data packages exclude non-registered Chinese competitors from European pharmaceutical excipient qualification. |
Research Methodology
Multiple input streams — executive interviews with specialty chemical plant managers, procurement leads at dietary supplement formulators, and distribution channel partners; secondary validation through customs/trade data, SEC 10-K filings, and ECHA registration databases; and technical R&D director surveys — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates and supply-side capacity assessments.
Historical volume trajectories were cross-referenced against panel input from fermentation technology specialists and pharmaceutical excipient procurement officers to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated grade tier, end-use application, and regional production hub dimensions with CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs included lactic acid feedstock pricing dynamics, pharmacopeial harmonization progress, and regulatory authorization timelines for mineral-functional health claims.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation scale-up would alter the outlook if capital constraints delay bioreactor retrofitting among mid-cap producers. Forecasts reflect assumptions regarding REACH enforcement intensity, EFSA authorization velocity, and Chinese environmental regulatory tightening. Material deviation in lactic acid feedstock pricing, pharmacopeial divergence, or ECHA substance evaluation outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Sodium Ferrocyanide Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Banlangen Granules Market
Bulk Chemicals
Dithiocarbamates Market