
 Amblyopia Treatment Softwares Market | 2026-2036
Amblyopia Treatment Softwares Market Size, Share, and Industry Trends Forecast 2026-2036
Amblyopia Treatment Softwares Market Insights
The amblyopia treatment software sector is rebalancing between premium immersive systems and commodity screening tools. Vivid Vision, Inc. leverages virtual reality hardware integration to anchor its position in high-end therapeutic delivery. NovaSight competes through proprietary eye-tracking algorithms that sustain clinical validation standards across European and Asian markets.
Amblyopia treatment software comprises digital therapeutic programs designed to correct visual acuity deficits through repetitive, targeted visual stimulation exercises delivered via screens, headsets, or cloud-connected devices. These platforms employ dichoptic presentation protocols, contrast manipulation, and real-time performance analytics to retrain cortical visual processing in patients with lazy eye conditions. Home-Based Therapy solutions currently lead volume deployment while Virtual Reality technology captures the fastest expansion trajectory due to superior engagement metrics and measurable outcome differentiation. Ophthalmology Practices represent the most concentrated margin pool as gatekeepers of clinical validation and reimbursement authorization.
The FDA's Software as a Medical Device framework shapes product classification pathways and clinical evidence requirements for therapeutic visual software in the United States. HIPAA compliance obligations and state-level telehealth licensing regulations further constrain deployment architecture and data handling protocols for platforms serving pediatric populations. Stakeholders must monitor evolving payer coverage determinations for digital therapeutics as these decisions will determine whether home-based subscription models achieve sustainable reimbursement parity with clinic-administered interventions.
Market Dynamics
The FDA's Software as a Medical Device framework is compressing product development timelines while elevating clinical evidence thresholds for therapeutic visual platforms. This regulatory recalibration is forcing developers to front-load validation investments before commercial deployment.
Growth Catalysts
- Telehealth Licensing Expansion:State-level telehealth regulations in the United States are enabling remote prescription of home-based amblyopia therapy. Pediatric ophthalmology practices leverage these frameworks to extend patient reach beyond metropolitan corridors.
- Eye-Tracking Algorithm Maturation:Proprietary gaze-monitoring technologies are improving treatment fidelity through real-time performance adjustment. Clinical validation protocols now incorporate these biometric feedback loops as standard-of-care components.
- China:The NMPA's digital therapeutics pathway is accelerating market entry for software-based vision correction tools. Domestic developers align product architectures with these streamlined approval mechanisms.
Market Restraints
- Reimbursement Authorization Bottlenecks:Payer coverage determinations for digital therapeutics lag behind clinical validation cycles. Ophthalmology practices absorb upfront costs while awaiting coding recognition from major insurers.
- VR Hardware Supply Concentration:Headset component sourcing concentrates among Asian contract manufacturers. Tariff exposure and logistics fragility create margin pressure for immersive therapy platforms.
- Contrast Sensitivity Ceiling:Current dichoptic presentation protocols hit physiological limits in severe amblyopia cases. Software-only interventions fail patients below threshold visual acuity levels.
Strategic Opportunities
- India:The CDSCO's emerging digital health framework presents first-mover positioning for cloud-native vision training platforms. Urban pediatric ophthalmology networks in Mumbai and Delhi seek validated home-based alternatives.
- Artificial Intelligence Convergence:Machine learning models trained on treatment response datasets enable personalized exercise progression. Adaptive difficulty algorithms differentiate outcomes against static protocol competitors.
- Direct-to-Consumer Subscription Channels:Parental demand for at-home solutions is bypassing traditional clinic gatekeepers. Platforms with standalone FDA clearance are testing bypass reimbursement models through employer wellness programs.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system implementation for Software as a Medical Device classification extends 18-24 months. Small developers face capital depletion before revenue recognition.
- Integration Friction with Electronic Health Records:HL7 FHIR interoperability standards remain inconsistently implemented across hospital systems. Therapy platforms require manual data bridges, degrading workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amblyopia Treatment Softwares Market |
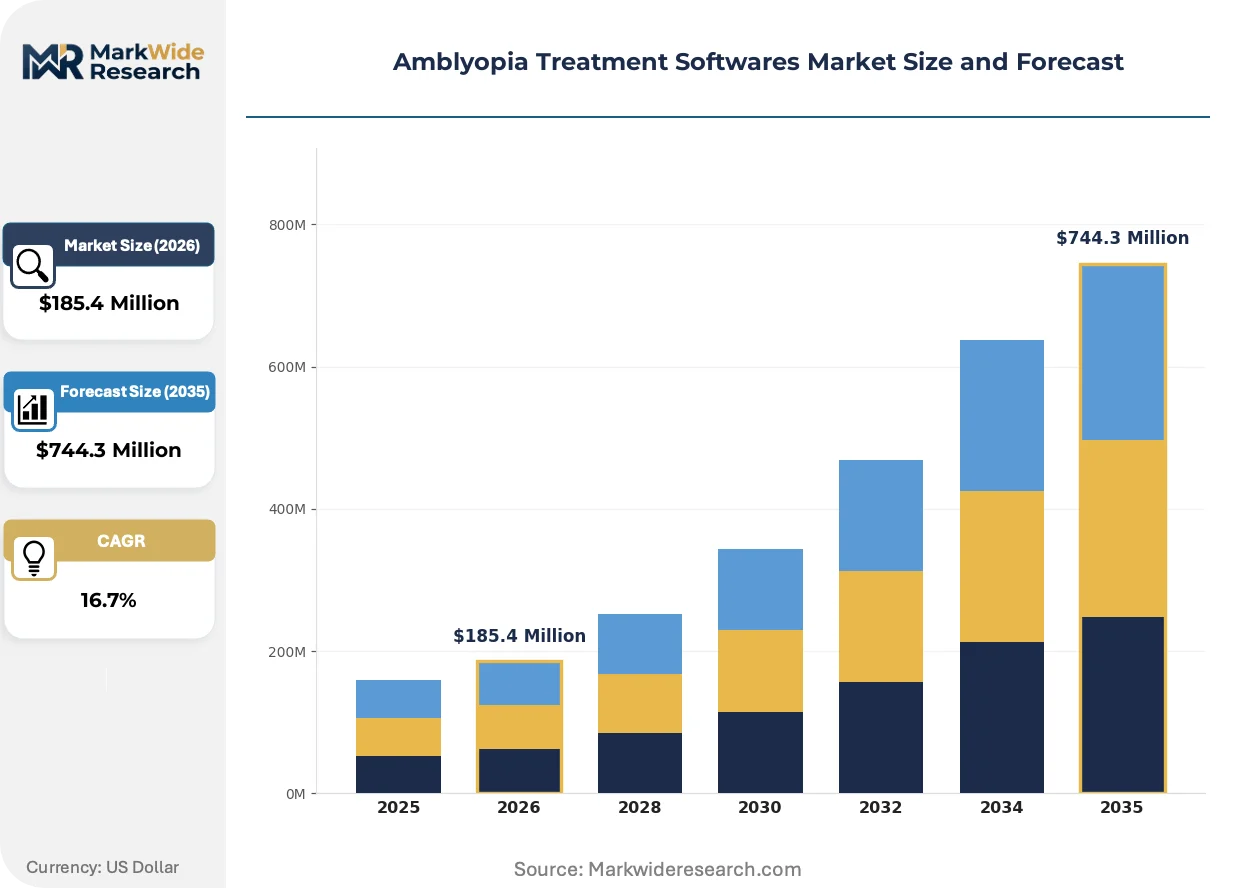
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $744.3 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home-Based Therapy, Screening Software, Vision Training, Telehealth Solutions Technology: Mobile Applications, Virtual Reality, Cloud-Based Platforms, Software as a Service End User: Pediatric Clinics, Ophthalmology Practices, Hospitals, Home Users Delivery Mode: Online, Offline, Subscription Model, One-Time Purchase |
| Companies Covered | Vivid Vision, Inc., NovaSight, RevitalVision, CureSee, Bynocs, Smart Optometry, AmblyoCare, Wow Vision Therapy, Optics Trainer, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amblyopia Treatment Softwares Market Trends and Innovations
Machine learning is penetrating amblyopia treatment protocols at the point of patient interaction. Three developments are compressing the gap between diagnostic assessment and therapeutic adjustment.
Adaptive difficulty algorithms are automating exercise calibration based on real-time performance degradation. Pediatric ophthalmology practices in Boston and San Francisco deploy these systems to maintain engagement without clinician oversight. The technology is automating the labor-intensive protocol tuning that previously required weekly in-person visits.
The EU Medical Device Regulation's classification guidance for therapeutic software is elevating post-market surveillance obligations. European developers must maintain clinical follow-up registries that track pediatric outcomes across multi-year treatment windows. Small platforms without pharmacovigilance infrastructure are exiting the market rather than absorbing compliance costs.
Parental purchasing committees are displacing sole clinician authority in therapy selection for school-age children. Online review ecosystems and peer recommendation networks now filter platform consideration sets before ophthalmology consultation. This behavioral shift concentrates adoption in platforms with consumer-grade user experience design, particularly in United States suburban markets with high digital literacy.
Amblyopia Treatment Softwares Market Segmentation
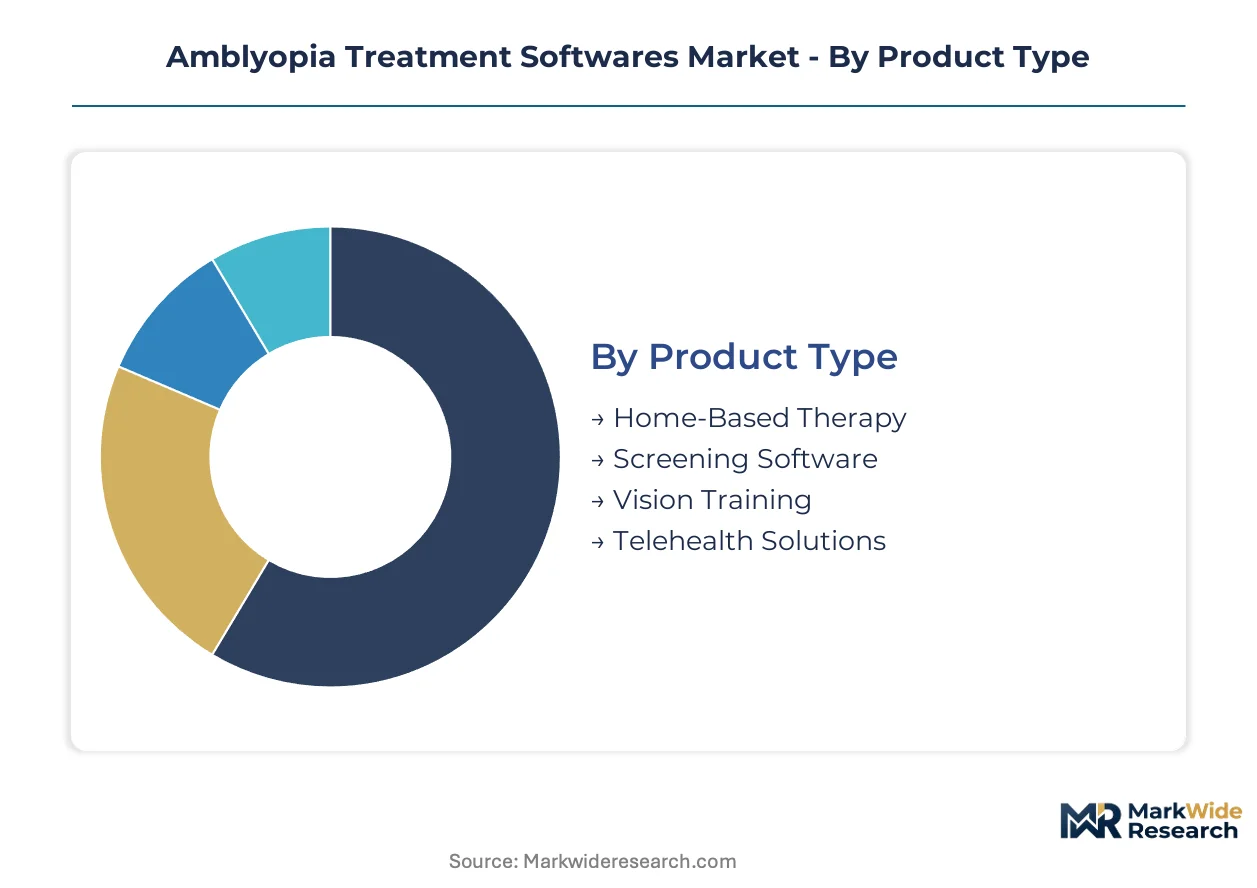
Segmentation in amblyopia treatment softwares reveals divergent investment profiles across deployment architectures. Product type splits between capital-intensive immersive systems and lightweight screening tools, while technology choices determine regulatory pathway complexity and reimbursement eligibility.
Product Type:
Supply concentration favors platforms with integrated hardware-software stacks over standalone applications.
- Home-Based Therapy:Cloud-connected exercise protocols enable remote monitoring by pediatric ophthalmologists. Demand clusters in United States suburban markets where working parents prioritize schedule flexibility over clinic visits. FDA Software as a Medical Device classification requirements elevate compliance costs for new entrants.
- Vision Training:Adaptive algorithms adjust contrast and dichoptic presentation in real-time based on patient response. Boston and San Francisco pediatric practices deploy these systems to reduce manual protocol calibration labor. Machine learning integration differentiates premium offerings from static exercise libraries.
- Screening Software:Lightweight diagnostic tools for early detection in school and primary care settings.
- Telehealth Solutions:Integrated platforms combining remote consultation with prescribed exercise delivery.
Today's leader: Home-Based Therapy. Tomorrow's challenger: Vision Training.
Technology:
Cost tier stratification separates enterprise-grade immersive systems from consumer-accessible mobile applications.
- Virtual Reality:Headset-based dichoptic presentation achieves superior engagement metrics through immersive environments. Hardware sourcing concentrates among Asian contract manufacturers, exposing margin pressure from tariff and logistics volatility. European Union Medical Device Regulation post-market surveillance obligations extend compliance timelines for VR therapeutic platforms.
- Cloud-Based Platforms:Browser-delivered exercises minimize patient-side hardware requirements and enable rapid protocol updates. HIPAA-compliant data architectures dominate United States deployments. Subscription revenue models align platform incentives with long-term patient adherence.
- Mobile Applications:Smartphone-native solutions for basic screening and compliance tracking.
- Software as a Service:Enterprise licensing for multi-clinic ophthalmology networks.
Virtual Reality commands premium pricing. Cloud-Based Platforms scale fastest across mid-market practices.
End User:
Customer type determines purchasing authority structure and reimbursement pathway complexity.
- Ophthalmology Practices:Gatekeepers of clinical validation and prior authorization for insurance coverage. These practices concentrate in metropolitan United States healthcare corridors with established referral networks. Revenue per patient exceeds other channels due to professional supervision billing codes.
- Pediatric Clinics:Early intervention access points with high patient volume but lower per-case revenue. State-level telehealth licensing expansions enable remote therapy prescription beyond traditional geographic constraints. Parental demand for at-home solutions is reshaping procurement criteria toward consumer-grade user experience.
- Hospitals:Academic medical centers driving clinical trial recruitment and validation studies.
- Home Users:Direct-to-consumer segment bypassing traditional clinical gatekeepers through employer wellness programs.
Ophthalmology Practices control margin capture. Pediatric Clinics drive volume expansion.
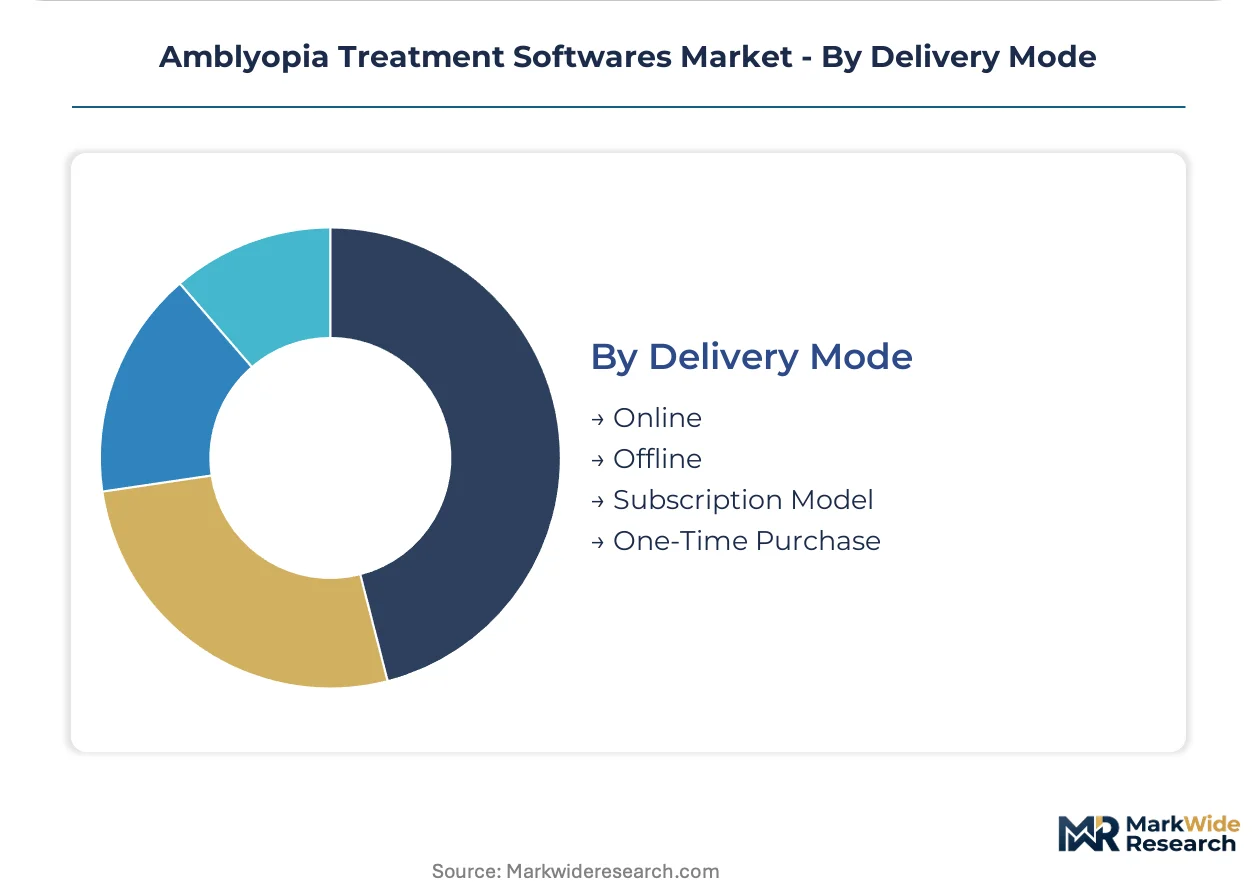
Delivery Mode:
Application context separates acute intervention platforms from longitudinal maintenance tools.
- Subscription Model:Recurring revenue aligns platform development with sustained patient engagement. United States payers are evaluating coverage determinations for home-based digital therapeutics against clinic-administered intervention parity. Churn management becomes critical as parental purchasing committees displace sole clinician authority.
- Online:Immediate deployment without physical distribution infrastructure. HL7 FHIR interoperability gaps create manual data bridge requirements that degrade workflow adoption in hospital systems.
- Offline:Air-gapped installations for security-sensitive institutional environments.
- One-Time Purchase:Perpetual licensing for enterprise ophthalmology networks with internal IT support capacity.
Subscription Model dominates new customer acquisition. One-Time Purchase persists in legacy enterprise accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric ophthalmology specialists cluster in metropolitan healthcare corridors where academic medical centers anchor clinical validation networks. These talent concentrations determine software adoption velocity and reimbursement pathway development.
United States
Boston and San Francisco pediatric practices deploy machine learning-integrated vision training systems to reduce manual protocol calibration. FDA Software as a Medical Device framework compresses development timelines while elevating clinical evidence thresholds. Suburban markets with high digital literacy drive parental purchasing committee formation, displacing sole clinician authority in platform selection.
China
Domestic developers align product architectures with NMPA digital therapeutics pathway streamlining market entry. Urban pediatric ophthalmology networks in Shanghai and Beijing seek validated home-based alternatives to clinic-dependent care. Asian contract manufacturers concentrate VR headset component sourcing, exposing immersive therapy platforms to tariff and logistics volatility.
Germany
EU Medical Device Regulation post-market surveillance obligations extend compliance timelines for therapeutic software developers. Small platforms without pharmacovigilance infrastructure exit rather than absorb multi-year pediatric outcome tracking costs. Munich and Heidelberg academic medical centers drive clinical trial recruitment for dichoptic presentation protocols.
India
CDSCO emerging digital health framework presents first-mover positioning for cloud-native vision training platforms. Mumbai and Delhi urban pediatric ophthalmology networks seek validated home-based alternatives to address specialist shortage. State-level telehealth licensing expansions enable remote therapy prescription beyond traditional metropolitan corridors.
United Kingdom
NHS digital therapeutics evaluation programs shape coverage determinations for home-based amblyopia interventions. London and Oxford academic clusters drive adaptive algorithm development for real-time exercise calibration. Parental demand for at-home solutions reshapes procurement criteria toward consumer-grade user experience design in suburban markets.
Amblyopia Treatment Softwares Market Competitive Landscape
Top-tier vendors anchor premium immersive systems, while mid-market competitors populate cloud-based screening and training tools. The vendor base stratifies across hardware-integrated stacks and lightweight software applications. Three archetypes dominate: VR hardware-software integrators, proprietary algorithm developers, and cloud-native platform operators. Geographic expansion through regulatory pathway optimization and strategic partnerships with academic medical centers constitute the dominant competitive moves.
Within the immersive therapy tier, Vivid Vision, Inc. and NovaSight occupy positions exemplifying divergent technical approaches to dichoptic treatment delivery. Vivid Vision, Inc. anchors hardware-software integration archetypes through its virtual reality platform architecture. NovaSight represents proprietary eye-tracking algorithm specialization competing across European and Asian validation frameworks. RevitalVision sits within the adaptive software tier, demonstrating cloud-native platform positioning for metropolitan ophthalmology networks.
| Leading Market Players |
|---|
| Vivid Vision, Inc. |
| NovaSight |
| RevitalVision |
| CureSee |
| Bynocs |
| Smart Optometry |
| AmblyoCare |
| Wow Vision Therapy |
| Optics Trainer, LLC |
| Others |
Pricing and Supply Chain Analysis
VR headset manufacturing consolidation in East Asia simultaneously compresses hardware procurement economics and concentrates bargaining power among contract manufacturers serving immersive therapy developers. This dual effect reshapes margin structures across the amblyopia software stack, forcing platform vendors to recalibrate bundled service pricing against unbundled software licensing.
Pricing Analysis
Bundled hardware-software service packages command premium positioning against unbundled SaaS licensing for cloud-native exercise platforms. Three-tier pricing structure across premium immersive, standard adaptive, and economy screening tiers reflects FDA Software as a Medical Device certification levels and accompanying clinical validation depth. Price differentiation stems from eye-tracking algorithm sophistication and geographic delivery cost variance for VR hardware. Pricing pressure intensifies in the screening tier as lightweight diagnostic tools proliferate without comparable compliance investment. Pediatric clinics exhibit highest price sensitivity due to volume-driven procurement, while ophthalmology practices absorb premium positioning for clinically validated immersive systems.
Supply Chain Analysis
ISO 13485 quality management certification gates upstream component qualification for Software as a Medical Device classification, extending vendor onboarding timelines. Hardware sourcing concentrates in China, Taiwan, and South Korea for VR headset displays, sensors, and assembly. Software development draws from specialized machine learning talent pools in the United States, Israel, and the United Kingdom. Supply chain risk centers on single-source vulnerability for high-resolution OLED microdisplays used in dichoptic presentation systems. Distribution runs through ophthalmology practice procurement committees and direct-to-consumer subscription channels for cleared home-based platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amblyopia treatment software market has entered late-cycle quality differentiation as parental purchasing committees prioritize clinically validated immersive systems over commodity screening alternatives. This demand shift toward premium specifications rewards vendors with completed FDA SaMD pathways and published pediatric outcome data.
For Market Incumbents: Cement market position through exclusive partnerships with academic medical centers for multi-year pediatric outcome registries required under EU MDR post-market surveillance. Deepen backward integration into proprietary eye-tracking sensor development to reduce hardware cost exposure from Asian contract manufacturers. Lock in ophthalmology practice channel control through integrated EHR interoperability investments that raise switching costs for competitor platforms.
For New Entrants and Emerging Players: CDSCO's emerging digital health framework in India opens a window for cloud-native platform entry before multinational incumbents complete regulatory localization. Target Mumbai and Delhi pediatric ophthalmology networks seeking validated home-based alternatives to address specialist concentration bottlenecks. Pursue employer wellness program distribution partnerships as a bypass channel circumventing traditional reimbursement authorization delays.
For Investors and Strategic Acquirers: Valuations sit cheapest among adaptive algorithm developers without captive hardware integration, presenting acquisition targets for vertical completion. Long-term viability over the coming decade hinges on machine learning differentiation and regulatory pathway completion rather than hardware volume scale. Monitor NMPA digital therapeutics pathway acceleration in China as the inflection signal for Asia-Pacific market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Submission Completion | Unlocks reimbursement authorization pathways and pediatric clinic procurement eligibility. |
| CE Marking Pathway Execution | Enables EU MDR-compliant deployment across German and UK academic medical center networks. |
| Hospital System Partnership | Secures preferred vendor status within metropolitan ophthalmology referral corridors. |
| Software Companion Development | Extends platform utility through EHR-integrated remote monitoring dashboards for clinicians. |
| Reimbursement Strategy Execution | Positions home-based subscription models for payer parity with clinic-administered interventions. |
Research Methodology
Direct dialogue with pediatric ophthalmologists, FDA regulatory consultants, digital health reimbursement specialists, and VR hardware procurement officers grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) and De Novo filings, NMPA digital therapeutics guidance documents, EU MDR classification guidance, and hospital GPO contract databases. Bottom-up patient volume modeling and top-down healthcare IT spending allocation triangulated market sizing across the analysis window.
Segment-level outputs reflect deployment architecture splits between immersive VR systems and cloud-native platforms, technology tiers distinguishing proprietary algorithm from static protocol offerings, and end-user concentration across ophthalmology practices versus pediatric clinic networks. CAGRs were derived from treatment penetration curves calibrated against telehealth licensing expansion trajectories and payer coverage determination timelines. Forecast inputs incorporated eye-tracking hardware cost decline curves and machine learning talent availability by geography.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA digital therapeutics pathway expansion or protracted reimbursement authorization delays. Model outputs reflect documented assumptions regarding telehealth regulatory permanence and VR hardware supply chain stability. A model refresh is warranted upon material change in CMS national coverage determination for digital therapeutics or NMPA pathway implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market