
 North America Eclinical Solutions Market | 2026-2036
North America Eclinical Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
North America Eclinical Solutions Market Analytics
The direct sales channel is narrowing as cloud-native platforms displace legacy on-premises installations across pharmaceutical IT procurement. Oracle Corporation leverages its Cerner acquisition to anchor hospital-integrated trial workflows, while Veeva Systems competes through vertical specialization in life sciences CRM and vault platforms. Medidata Solutions dominates the electronic data capture segment with sensor-cloud integration for decentralized trials.
Eclinical solutions encompass software and services that digitize clinical trial operations, encompassing electronic data capture systems with audit trail capabilities, remote patient monitoring infrastructure, and regulatory submission management tools designed to ensure data integrity across multi-site studies. The deployment dimension shows cloud-based architectures leading new installations while hybrid configurations capture organizations transitioning from validated on-premises servers. Electronic data capture and remote monitoring represent the fastest-expanding service types as sponsors pursue decentralized trial models that reduce site burden and accelerate enrollment timelines.
The FDA enforces 21 CFR Part 11 standards for electronic records and signatures, while Health Canada applies ICH E6(R2) Good Clinical Practice guidelines that mandate audit-ready data trails for market authorization submissions. These frameworks compel vendors to maintain validated software environments and generate substantial recurring demand for compliance consulting and system validation services. Stakeholders must monitor evolving FDA guidance on artificial intelligence in clinical decision support as algorithmic tools penetrate trial endpoints and safety surveillance workflows.
Market Dynamics
Cloud-native architectures are collapsing the traditional enterprise sales cycle for clinical trial software, compressing validation timelines from months to weeks and forcing vendors to restructure implementation and support models around self-service onboarding rather than heavy professional services.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates compel sponsors to replace paper-based processes with validated digital systems, creating replacement demand across mid-sized CROs upgrading legacy infrastructure.
- Decentralized trial models:Patient recruitment constraints are accelerating adoption of remote monitoring technologies that reduce site dependency and expand geographic enrollment pools.
- Boston-Cambridge biotech corridor:Venture-funded biotechnology firms are prioritizing cloud-first procurement for speed-to-first-patient, bypassing traditional on-premises validation cycles.
Market Restraints
- Validation cost structure:FDA computer system validation requirements impose fixed compliance burdens that disproportionately burden smaller sponsors with limited quality assurance staffing.
- AWS-Google-Azure concentration:Cloud infrastructure dependency creates single-point-of-failure risk for multi-tenant clinical platforms operating under strict data residency requirements.
- Legacy system entrenchment:Large pharmaceutical sponsors face switching costs from decades of customized on-premises EDC deployments with embedded business process logic.
Strategic Opportunities
- Canada's underpenetrated mid-market:Health Canada ICH E6(R2) alignment creates regulatory familiarity for US vendors, yet Canadian biotechnology firms lag in cloud adoption versus American peers.
- AI-enabled safety surveillance:FDA draft guidance on machine learning in clinical decision support opens pathways for algorithmic adverse event detection integrated with EDC workflows.
- Direct-to-patient channels:Telehealth platform partnerships bypass traditional site-based distribution, enabling sponsors to capture real-world data streams outside conventional CRO networks.
Industry Challenges
- Clinical data science talent scarcity:Hybrid skill requirements combining biostatistics, cloud architecture, and regulatory knowledge outpace university program output.
- Interoperability friction:EHR-to-EDC integration complexity delays study startup, particularly when hospital IT departments lack resources for custom API development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Eclinical Solutions Market |
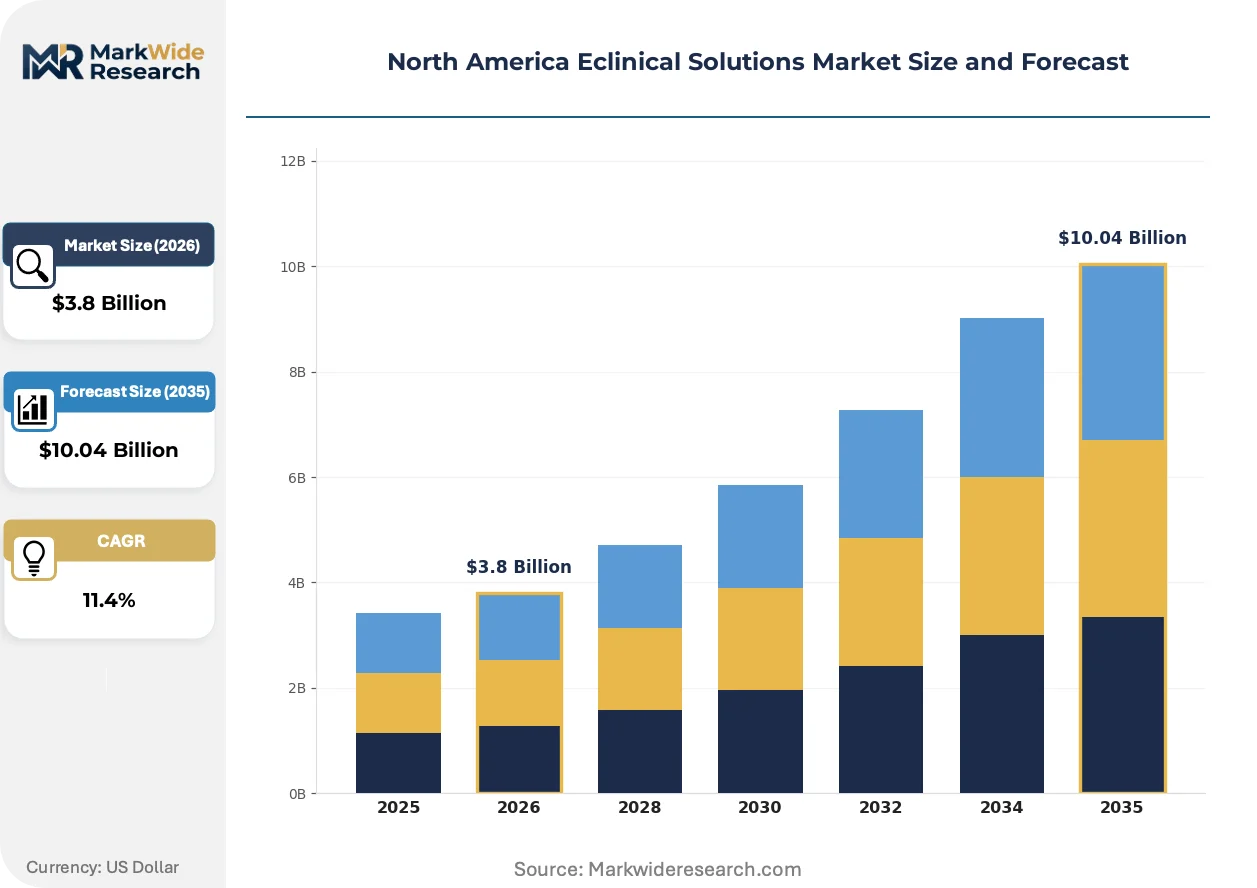
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Management, Electronic Data Capture, Remote Monitoring, Trial Management End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Application: Clinical Trials, Regulatory Compliance, Patient Engagement, Data Analysis |
| Companies Covered | Oracle Corporation, Medidata Solutions, Veeva Systems, Parexel International Corporation, IQVIA, eClinical Solutions, ICON plc, Dassault Systemes, Clario, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Eclinical Solutions Market Evolving Landscape
Sensor-cloud integration is collapsing traditional boundaries between data collection and analysis, enabling continuous biomarker streams that replace scheduled site visits with ambient monitoring.
Edge computing architectures for wearable devices are collapsing the latency between patient physiological signals and investigator dashboard alerts. Mid-sized biotechnology sponsors in the San Francisco Bay Area are deploying these systems for cardiovascular and metabolic studies. The compression of data transmission intervals is collapsing the distinction between synchronous and asynchronous safety monitoring, forcing protocol amendments to accommodate real-time endpoint detection.
FDA guidance on decentralized clinical trials is formalizing remote source data verification as an acceptable alternative to on-site monitoring. The policy shift reduces travel-intensive monitoring costs while requiring sponsors to demonstrate equivalent data integrity through technology controls. Oncology and rare disease trials in the United States are responding fastest, restructuring monitoring plans around risk-based approaches that prioritize centralized data review.
Subscription pricing for platform access is displacing perpetual license models across sponsor procurement functions. Large pharmaceutical buyers are consolidating vendor relationships around enterprise agreements that bundle EDC, eCOA, and imaging capabilities. This concentration is most visible in the United States, where procurement teams are extracting volume commitments in exchange for reduced implementation fees and dedicated customer success resources.
North America Eclinical Solutions Market Segmentation
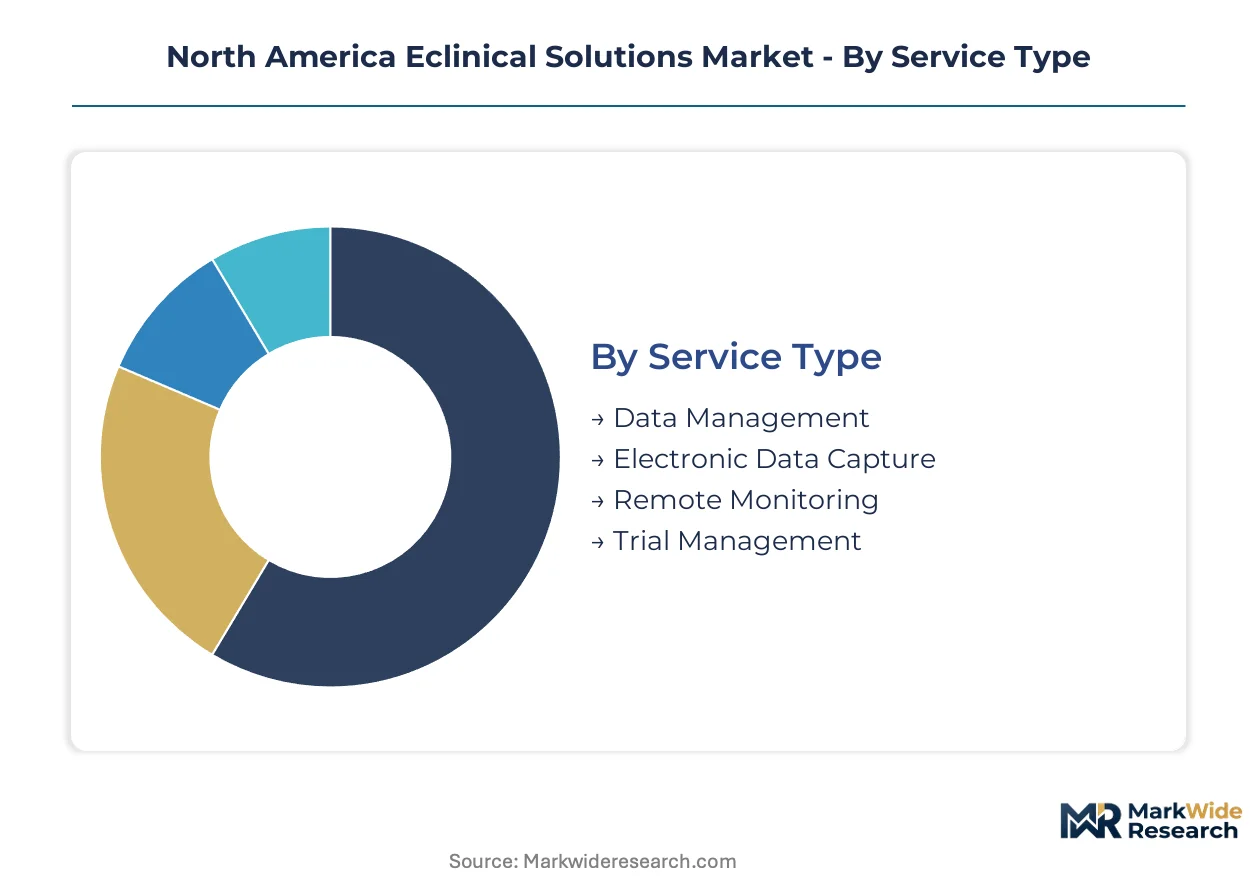
Eclinical solutions vendors structure their portfolios around distinct operational workflows, procurement preferences, and regulatory readiness levels across North American sponsors. Segment boundaries reflect how biotechnology firms prioritize speed-to-deployment while pharmaceutical incumbents emphasize validated infrastructure and multi-study scalability.
Service Type:
Use-case spectrum spans centralized data repositories through decentralized patient monitoring infrastructure, with each service tier demanding differentiated validation protocols and integration architectures.
- Electronic Data Capture:Web-based case report form systems with built-in audit trails and query management workflows. FDA 21 CFR Part 11 compliance requirements drive replacement cycles among mid-sized CROs upgrading from paper-based processes in the Boston-Cambridge corridor.
- Remote Monitoring:Wearable-integrated platforms streaming continuous biomarker data to investigator dashboards. San Francisco Bay Area cardiovascular and metabolic trials deploy these systems to collapse latency between physiological signals and safety alerts.
- Data Management:Centralized repositories with statistical programming interfaces for interim analyses and regulatory submissions.
- Trial Management:Study startup, site activation, and milestone tracking modules with budget forecasting capabilities.
The dominant share belongs to Electronic Data Capture, while Remote Monitoring is closing the gap fastest.
End User:
Customer archetypes range from venture-funded startups seeking cloud-first procurement to established sponsors with decades of customized legacy infrastructure.
- Biotechnology Firms:Venture-backed sponsors prioritizing speed-to-first-patient through cloud-native platforms that bypass traditional validation cycles. The Boston-Cambridge biotech corridor concentrates procurement for Phase I and II oncology studies.
- Pharmaceutical Companies:Large sponsors with embedded business process logic in legacy on-premises EDC deployments facing substantial switching costs. These buyers consolidate vendor relationships through enterprise agreements bundling multiple service types.
- Contract Research Organizations:Mid-sized CROs upgrading infrastructure to meet sponsor demands for decentralized trial capabilities and real-time data access.
- Academic Institutions:University medical centers with limited quality assurance staffing navigating FDA computer system validation requirements for investigator-initiated studies.
Biotechnology Firms command the steepest expansion trajectory, though Pharmaceutical Companies retain the largest committed spend base.
Deployment:
Infrastructure choices reflect organizational maturity, data residency constraints, and integration complexity with existing hospital IT ecosystems.
- Cloud-Based:Multi-tenant architectures with self-service onboarding compressing implementation timelines from months to weeks. AWS-Google-Azure concentration creates single-point-of-failure risk for platforms operating under strict data residency requirements.
- Hybrid:Configurations capturing organizations transitioning from validated on-premises servers, balancing legacy system continuity with remote monitoring scalability.
- On-Premises:Validated servers maintained within sponsor or site-controlled data centers for studies with heightened data sovereignty requirements.
- Mobile:Native applications for patient-reported outcomes and electronic clinical outcome assessments with offline-sync capabilities.
Cloud-Based deployments absorb the majority of new installations, while Hybrid configurations serve the largest backlog of migration demand.
Application:
Functional priorities align with study phase, therapeutic area complexity, and regulatory submission timelines.
- Clinical Trials:Core workflow digitization encompassing site activation, enrollment tracking, and endpoint adjudication across Phase I-IV studies.
- Regulatory Compliance:Submission-ready document management and audit trail maintenance for Health Canada ICH E6(R2) and FDA 21 CFR Part 11 adherence.
- Patient Engagement:Direct-to-patient portals and telehealth integrations bypassing traditional site-based distribution for real-world data capture.
- Data Analysis:Biostatistical programming environments and safety surveillance dashboards with algorithmic adverse event detection capabilities.
Clinical Trials applications anchor vendor revenue, though Patient Engagement is gaining share fastest as decentralized models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 enforcement and Health Canada ICH E6(R2) alignment are accelerating cloud migration across North American sponsors, compressing validation timelines and expanding procurement budgets for decentralized trial infrastructure.
United States
The Boston-Cambridge biotech corridor concentrates venture-funded Phase I and II oncology studies demanding cloud-first EDC platforms. FDA computer system validation requirements compel mid-sized CROs to replace paper-based processes with audit-ready digital systems. San Francisco Bay Area cardiovascular trials deploy sensor-cloud integration for continuous biomarker streaming.
Canada
Health Canada ICH E6(R2) guidelines create regulatory familiarity for US vendors entering the mid-market biotechnology segment. Canadian sponsors lag American peers in cloud adoption, presenting whitespace for platform providers offering hybrid deployment options. Ontario and Quebec medical centers navigate investigator-initiated study validation with limited quality assurance staffing.
Mexico
The national pharmaceutical regulator's alignment with ICH Good Clinical Practice standards enables multi-site trial participation for North American sponsors. Mexico City and Monterrey hospital networks attract Phase III enrollment expansion seeking geographic diversification. Local CROs upgrade electronic data capture capabilities to meet sponsor demands for real-time data access.
North America Eclinical Solutions Market Competitive Landscape
On the supply side, the industry is consolidating around enterprise platform bundling as large pharmaceutical buyers extract volume commitments through multi-year agreements. Three strategic archetypes dominate: cloud-native specialists with vertical life sciences focus, horizontal technology conglomerates leveraging hospital IT footprints, and CRO-integrated service providers embedding software within full-service contracts. M&A activity concentrates on sensor-cloud integration capabilities and telehealth platform partnerships.
Within the enterprise software tier, Oracle Corporation exemplifies horizontal platform leverage through hospital system integration, while Veeva Systems occupies a position as vertical specialist anchoring life sciences CRM and vault deployments. Medidata Solutions represents the sensor-cloud archetype with decentralized trial infrastructure. These three entities collectively illustrate the competitive tension between breadth and depth strategies reshaping vendor procurement.
| Leading Market Players |
|---|
| Oracle Corporation |
| Medidata Solutions |
| Veeva Systems |
| Parexel International Corporation |
| IQVIA |
| eClinical Solutions |
| ICON plc |
| Dassault Systemes |
| Clario |
| Others |
Value Network & Pricing Analysis
The Boston-Cambridge biotech corridor concentrates cloud-native platform development capacity, where vendor density among FDA-validated software providers creates localized pricing power that propagates downstream to sponsor procurement budgets across North America.
Pricing Analysis
Certification level (FDA 21 CFR Part 11-validated versus non-validated tiers) creates the primary spread between premium and standard platform offerings. Subscription SaaS models dominate new procurement, with enterprise agreements bundling EDC, eCOA, and imaging capabilities extracting volume discounts from large pharmaceutical buyers. Cost compression in the mid-market CRO segment is intensifying because venture-funded biotech sponsors demand accelerated deployment timelines with reduced implementation fees. Biotechnology firms exhibit highest price sensitivity due to limited quality assurance staffing, while pharmaceutical incumbents prioritize validated infrastructure over cost minimization.
Supply Chain Analysis
Export-control regimes restricting AI-enabled clinical decision support algorithms limit technology flows between US and Chinese software development centers, fragmenting sensor-cloud integration capabilities across vendor ecosystems. Supply concentrates in the United States for FDA-validated platform development, with secondary development hubs in Canada and Ireland supporting Health Canada and EMA-aligned deployments. Raw material dependencies include AWS-Google-Azure cloud infrastructure, wearable sensor hardware from Taiwan and South Korea, and specialized biostatistical programming talent pools. Single-source vulnerability in hyperscaler concentration creates systemic risk for multi-tenant clinical platforms. Distribution runs through direct enterprise sales teams for large pharmaceutical accounts, with self-service onboarding channels capturing mid-market biotechnology procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as large pharmaceutical sponsors consolidate vendor relationships through multi-year enterprise agreements, compressing margins for undifferentiated platform providers across the competitive landscape.
For Market Incumbents: Entrench position through backward integration into sensor hardware partnerships that lock in wearable-integrated platform capabilities, while expanding dedicated customer success resources for enterprise accounts facing Oracle and Veeva competitive pressure. Prioritize FDA guidance alignment on AI-enabled safety surveillance to preempt regulatory displacement by algorithmic-native entrants. For New Entrants and Emerging Players: Build out hybrid deployment expertise targeting Canada's underpenetrated mid-market biotechnology segment, where Health Canada ICH E6(R2) familiarity meets lagging cloud adoption versus American peers. Capture investigator-initiated study demand at Ontario and Quebec academic medical centers with limited quality assurance staffing. Lead with telehealth platform partnerships enabling direct-to-patient data capture outside established CRO networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-cloud integration specialists with validated FDA infrastructure and established pharmaceutical sponsor relationships. Long-term viability hinges on algorithmic differentiation in decentralized trial workflows rather than legacy EDC feature parity. Target acquisition archetypes combining wearable hardware partnerships with validated software environments. The signal to watch is FDA final guidance on machine learning in clinical decision support, which would accelerate algorithmic-native vendor displacement of incumbent platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Cloud Platform Integration | Collapses latency between patient physiological signals and investigator safety alerts for cardiovascular trials. |
| AI-Enabled Safety Surveillance Development | Positions vendors ahead of FDA final guidance on machine learning in clinical decision support workflows. |
| Hybrid Deployment Capability Buildout | Captures Canadian mid-market biotechnology demand where cloud adoption lags American peer migration. |
| Telehealth Platform Partnership | Enables direct-to-patient data capture bypassing traditional site-based CRO distribution networks. |
| Enterprise Agreement Consolidation | Extracts volume commitments from pharmaceutical buyers bundling EDC, eCOA, and imaging capabilities. |
Research Methodology
A standing panel of clinical operations executives, regulatory affairs leads at biotechnology firms, hospital procurement managers, and CRO technology directors provided ongoing calibration across primary fieldwork. This study combined structured interviews with these stakeholders against secondary validation from FDA 21 CFR Part 11 guidance documents, Health Canada ICH E6(R2) submissions, ClinicalTrials.gov protocol registrations, and hyperscaler cloud infrastructure disclosures. Bottom-up sponsor spending estimates triangulated against top-down vendor revenue segmentation across deployment models and service types.
Scenario bracketing anchored projections across base, upside, and downside regulatory adoption pathways throughout the forecast period. The analytical framework modeled segmentation dimensions spanning deployment architecture, end-user archetype, service type, and therapeutic area adoption intensity. CAGRs derived from sponsor budget allocation surveys cross-referenced against vendor booking disclosures. Forecast inputs incorporated FDA guidance evolution timelines and Health Canada regulatory alignment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by Oracle or vertical specialization pushes by Veeva would shift competitive outcomes materially. Material shifts in FDA final guidance on decentralized trial requirements or AI-enabled clinical decision support would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market